
 Injectable Anti-Wrinkle Treatment Market | 2026-2036
Injectable Anti-Wrinkle Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Injectable Anti-Wrinkle Treatment Market Foresight
Multi-source procurement for active pharmaceutical ingredients is restructuring supply dynamics across the injectable anti-wrinkle sector. AbbVie leverages captive biologics manufacturing to secure consistent botulinum toxin supply for its aesthetic portfolio. Galderma anchors its position through integrated hyaluronic acid filler production and direct clinic channel partnerships. Merz Pharma differentiates via specialized neurotoxin formulations targeting precise facial musculature applications.
Injectable anti-wrinkle treatments comprise purified biologic or synthetic substances administered intradermally or intramuscularly to reduce dynamic or static rhytides, with botulinum toxin type A functioning as a 150 kDa polypeptide that cleaves SNAP-25 to inhibit acetylcholine release at neuromuscular junctions. These products serve the commercial purpose of non-surgical facial rejuvenation in outpatient aesthetic settings. Botulinum toxin commands the largest revenue pool among product types due to repeat treatment cycles and established clinician familiarity, while hyaluronic acid fillers capture expanding margin pools in combination protocols addressing multiple facial zones. Medical spas represent the fastest-growing end user channel as they convert retail consumers into recurring aesthetic patients through membership pricing structures.
The FDA Center for Biologics Evaluation and Research oversees botulinum toxin approval pathways, while the EMA and national European competent authorities enforce the Medical Device Regulation for dermal filler classification and post-market surveillance. These frameworks shape demand by mandating clinical efficacy thresholds and pharmacovigilance systems that elevate compliance costs for market entrants. Stakeholders must monitor evolving biosimilar guidance and emerging state-level scope-of-practice regulations that determine which provider types may administer injectable treatments.
Market Dynamics
Multi-source procurement for active pharmaceutical ingredients is restructuring supply dynamics across the injectable anti-wrinkle sector, with captive biologics manufacturing emerging as the decisive competitive differentiator among established manufacturers.
Growth Catalysts
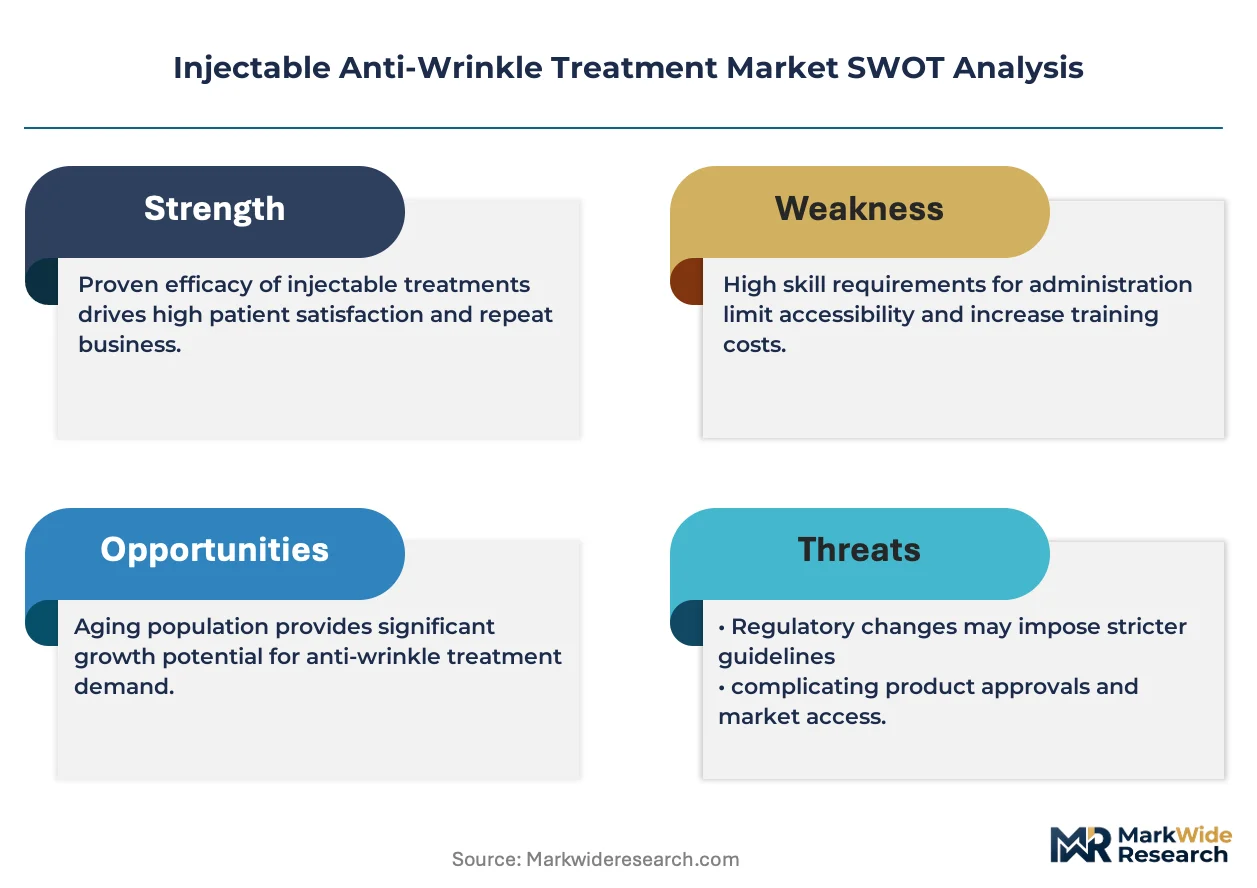
- EMA Medical Device Regulation:Harmonized classification standards for hyaluronic acid fillers accelerate cross-border clinic network expansion and reduce compliance duplication costs across European aesthetic practices.
- Medical spa channel maturation:Membership pricing structures convert retail consumers into recurring aesthetic patients, compressing treatment intervals and stabilizing revenue predictability for injectable providers.
- South Korean manufacturing cluster:Domestic botulinum toxin producers supply both local clinic networks and export markets across Asia, creating supply security and cost advantages for regional distributors.
Market Restraints
- Clostridium botulinum culture media costs:Fermentation-grade raw material price volatility constrains margin expansion for toxin manufacturers dependent on external bioprocessing suppliers.
- Single-source bioreactor dependency:Concentrated sterile manufacturing capacity in select European and North American facilities creates vulnerability to contamination events or capacity constraints.
- FDA pharmacovigilance mandates:Post-market adverse event reporting requirements for botulinum toxin products elevate ongoing compliance burdens and legal exposure for market entrants.
Strategic Opportunities
- Brazilian aesthetic market penetration:Underdeveloped clinic infrastructure in secondary Brazilian cities offers first-mover positioning for neurotoxin-filler combination protocols before local manufacturer consolidation.
- Combination treatment protocols:Simultaneous botulinum toxin and hyaluronic acid administration addressing multiple facial zones commands premium positioning and extends per-patient lifetime value.
- Telehealth consultation integration:Remote pre-screening and treatment planning workflows reduce clinic overhead while expanding geographic catchment areas for medical spa operators.
Industry Challenges
- Injection technique certification bottlenecks:Limited accredited training slots for advanced facial anatomy courses delay provider onboarding and constrain treatment capacity expansion at high-volume clinics.
- Cold chain integrity maintenance:Temperature excursion risks during last-mile distribution to medical spas necessitate redundant monitoring infrastructure and inflate logistics costs for biologic products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injectable Anti-Wrinkle Treatment Market |
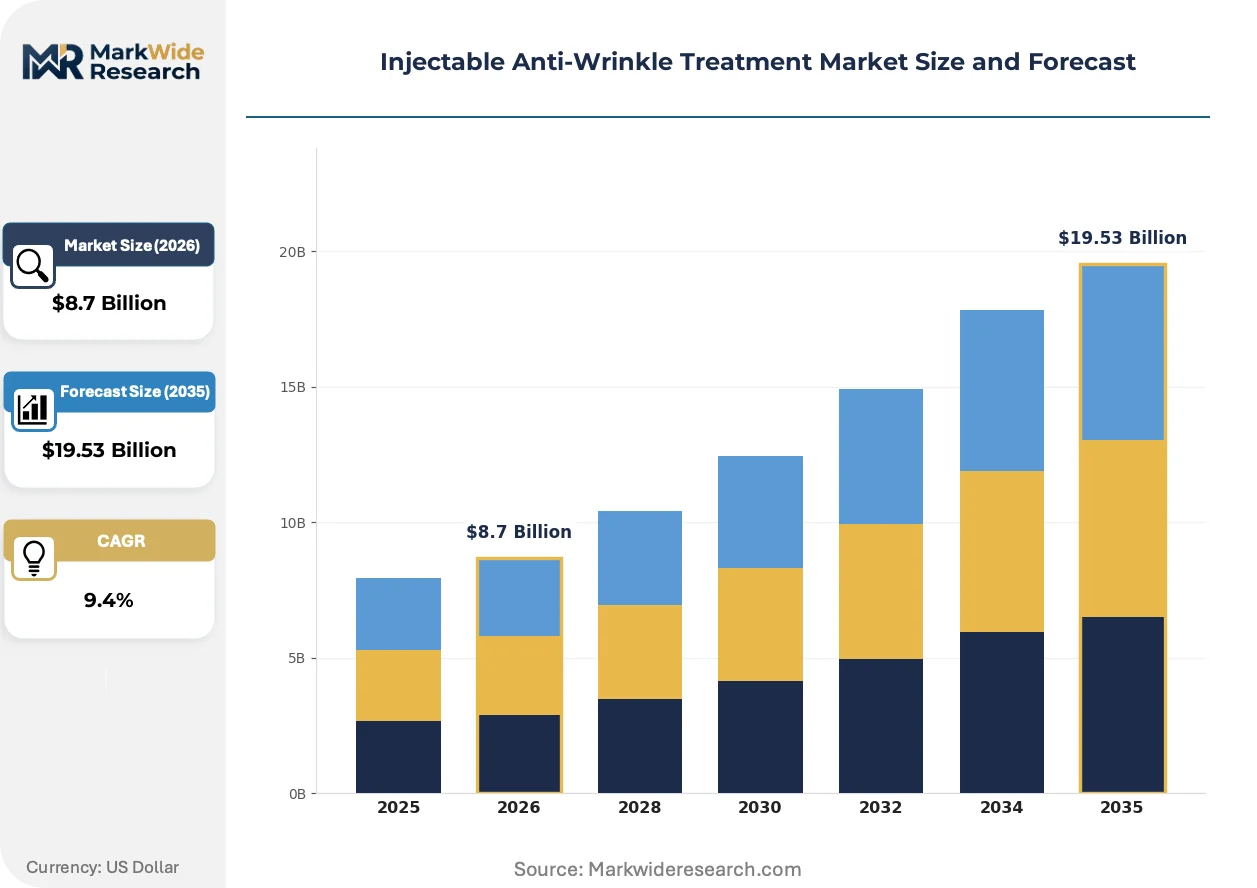
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Botulinum Toxin, Hyaluronic Acid, Poly-L-lactic Acid, Calcium Hydroxylapatite Application: Forehead Lines, Crow's Feet, Frown Lines, Laugh Lines End User: Clinics, Dermatology Practices, Medical Spas, Hospitals Delivery Method: Injectable, Topical, Laser-Assisted, Combination Therapy |
| Companies Covered | AbbVie, Galderma, Merz Pharma, Revance Therapeutics, Sinclair Pharma, Medytox, Ipsen, Suneva Medical, Bloomage BioTechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injectable Anti-Wrinkle Treatment Market Shifts & Advancements
Novel neurotoxin formulations with modified diffusion profiles are reshaping treatment precision standards, while regulatory convergence and channel consolidation simultaneously compress competitive timelines across the aesthetic injectables sector.
Micro-dosing protocols for botulinum toxin type A are expanding into forehead and periorbital applications previously dominated by standard-unit administration. Aesthetic practitioners in high-volume medical spas adopt these techniques to achieve natural movement preservation and differentiate service offerings. The approach is expanding into premium pricing tiers as patients prioritize subtle outcomes over complete paralysis.
The FDA Center for Biologics Evaluation and Research continues refining biosimilar guidance for botulinum toxin products, creating pathway clarity for follow-on entrants. This regulatory development compresses approval timelines for manufacturers with established biologics platforms while elevating clinical evidence requirements. European competitors leveraging EMA centralized procedures gain parallel market access advantages through mutual recognition agreements.
Direct clinic channel partnerships are displacing traditional distributor intermediaries in major metropolitan markets. Aesthetic product manufacturers now deploy dedicated account managers to medical spa chains, unbundling procurement from legacy wholesale relationships. This pattern concentrates most visibly in South Korea and the United States, where multi-location clinic groups command volume-based contracting leverage.
Injectable Anti-Wrinkle Treatment Market Segmentation
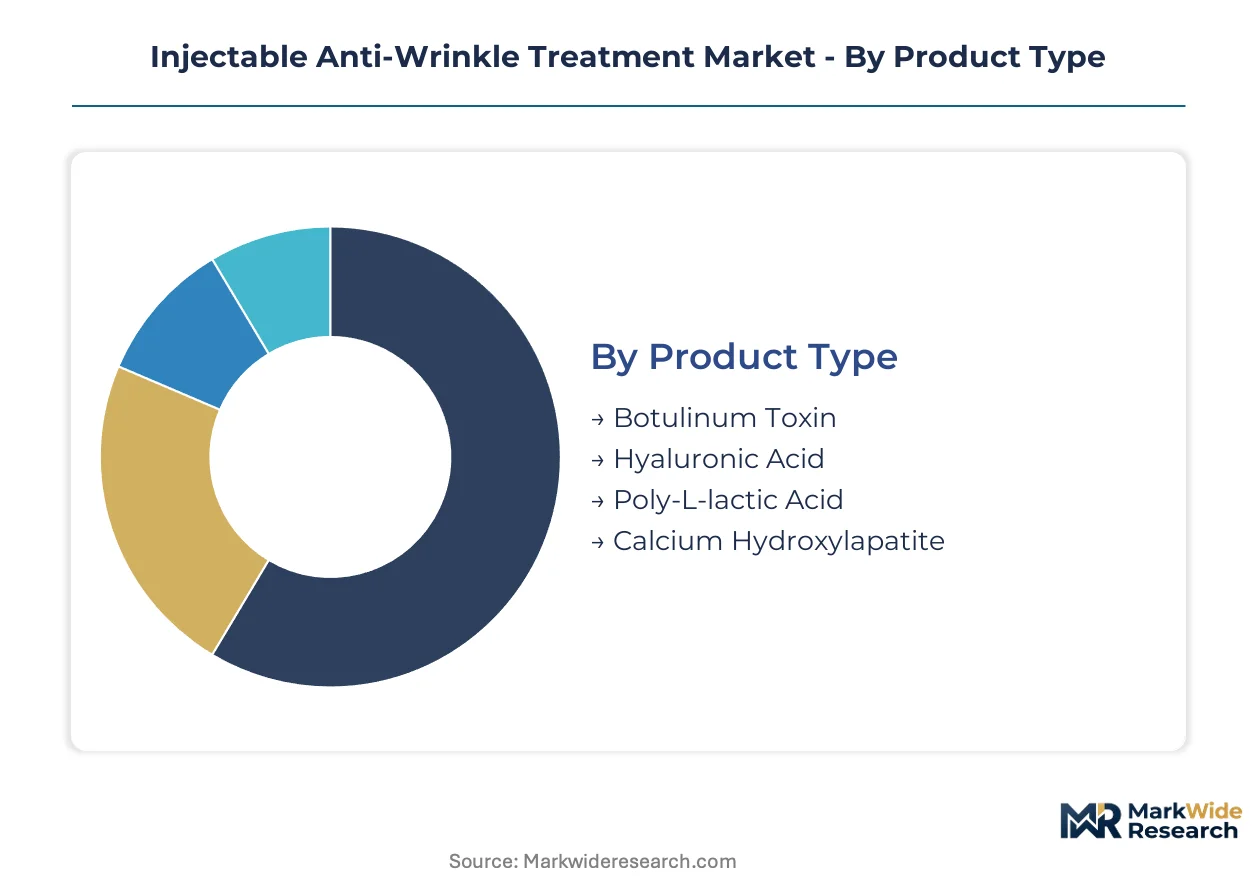
Segmentation in injectable anti-wrinkle treatments reveals how supply chain configuration and clinical workflow requirements reshape competitive positioning across product categories. Manufacturers align R&D investment and distribution infrastructure around distinct technical specifications and end-user operational models.
Product Type:
Supply concentration in active pharmaceutical ingredient sourcing directly determines margin structures and regulatory pathway complexity across biologic and synthetic formulations.
- Botulinum Toxin:A 150 kDa polypeptide derived from Clostridium botulinum fermentation that cleaves SNAP-25 to inhibit acetylcholine release. Demand clusters in South Korean manufacturing facilities serving domestic clinic networks and Asian export markets, with repeat treatment cycles stabilizing revenue predictability for high-volume providers.
- Hyaluronic Acid:Cross-linked glycosaminoglycan formulations manufactured through bacterial fermentation or avian extraction processes. Medical spas in the United States drive volume through combination protocols addressing multiple facial zones, commanding premium positioning when paired with membership pricing structures.
- Poly-L-lactic Acid:Biodegradable synthetic polymer stimulating collagen neogenesis through foreign body response mechanisms.
- Calcium Hydroxylapatite:Mineral-based filler with higher elastic modulus suited for deeper tissue planes and structural volume restoration.
Botulinum toxin absorbs the bulk of installed capacity; hyaluronic acid is expanding most quickly.
Application:
Cost tier differentiation separates premium periorbital treatments from standardized forehead applications based on injection technique complexity and adverse event risk profiles.
- Forehead Lines:Horizontal rhytides across the frontalis muscle requiring precise unit dosing to preserve brow elevation function. Micro-dosing protocols in United States medical spas achieve natural movement preservation, expanding into premium pricing tiers as patients prioritize subtle outcomes.
- Crow's Feet:Lateral periorbital rhytides involving orbicularis oculi muscle modulation with elevated vascular complication risk. South Korean clinic networks emphasize this application for export market differentiation, leveraging domestic toxin manufacturing cost advantages.
- Frown Lines:Glabellar complex targeting corrugator and procerus muscles with established FDA approval pathways.
- Laugh Lines:Nasolabial fold and perioral region addressing static volume loss combined with dynamic muscle activity.
Forehead applications command the greatest treatment volume; crow's feet protocols show the steepest expansion trajectory.
End User:
Customer type segmentation tracks how procurement authority and clinical credentialing requirements fragment channel access for manufacturers.
- Clinics:Multi-specialty outpatient facilities with physician ownership structures and direct purchasing relationships. United States clinic chains negotiate volume-based contracting with dedicated account managers, displacing traditional distributor intermediaries in major metropolitan markets.
- Medical Spas:Retail-converted aesthetic practices employing membership pricing to compress treatment intervals. This channel shows the steepest patient volume growth as telehealth pre-screening expands geographic catchment areas beyond traditional clinic boundaries.
- Dermatology Practices:Specialist-led settings with advanced facial anatomy training and higher adverse event management capacity.
- Hospitals:Institutional settings with centralized procurement and formal pharmacy oversight constraining product selection flexibility.
Medical spas absorb the bulk of new patient acquisition investment; dermatology practices are climbing the fastest in per-patient lifetime value metrics.
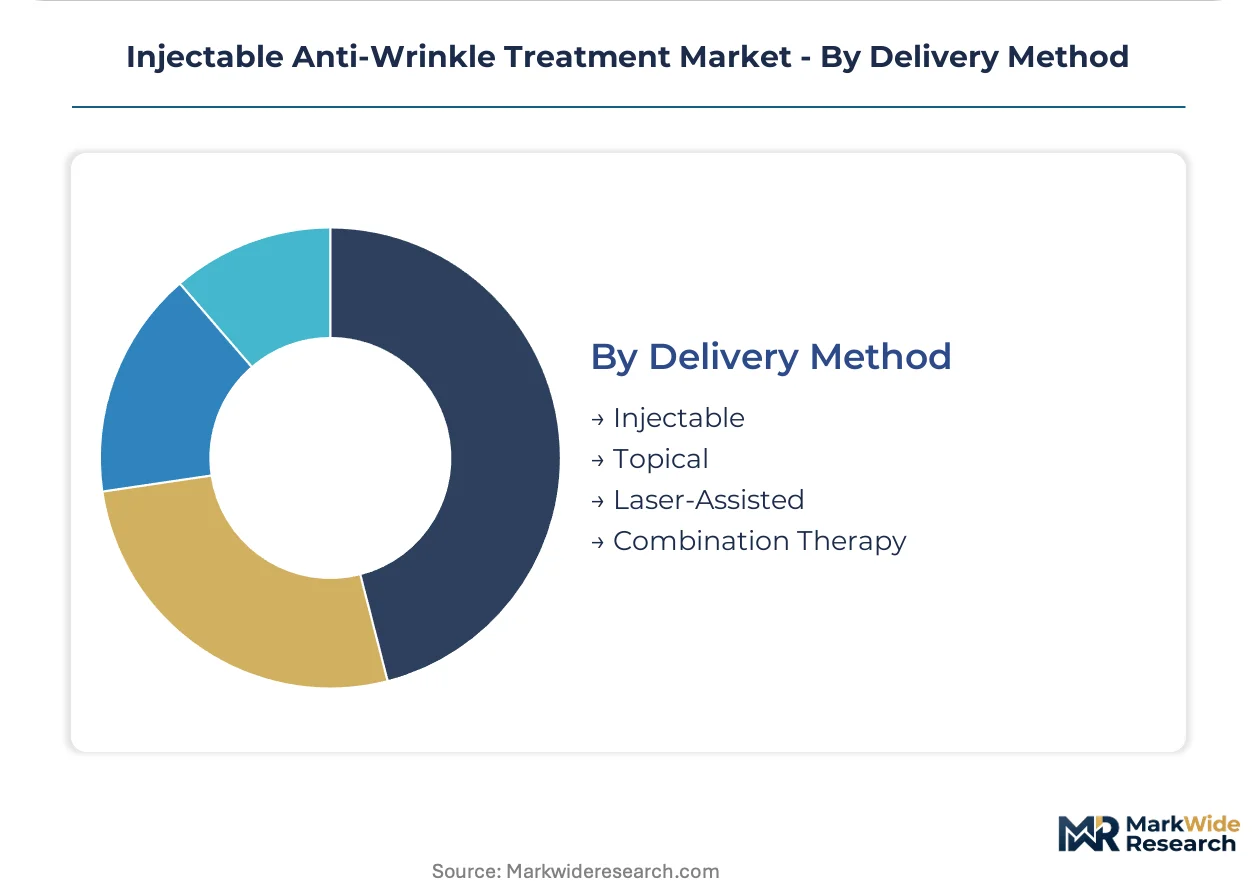
Delivery Method:
Volume concentration in injectable administration reflects regulatory clarity and reimbursement alignment that alternative modalities have not yet achieved.
- Injectable:Intradermal or intramuscular administration via needle or cannula with established FDA Center for Biologics Evaluation and Research oversight. Cold chain integrity requirements during last-mile distribution to South Korean and United States medical spas necessitate redundant monitoring infrastructure.
- Combination Therapy:Simultaneous botulinum toxin and hyaluronic acid administration addressing dynamic and static rhytides in single sessions. Brazilian secondary cities offer first-mover positioning before local manufacturer consolidation catches up to this protocol standard.
- Topical:Transdermal peptide formulations with limited penetration depth and unproven efficacy equivalence.
- Laser-Assisted:Energy-based pre-treatment to enhance product distribution or stimulate parallel collagen remodeling pathways.
Injectable methods absorb the bulk of clinical training investment; combination therapy is gaining share fastest among premium service tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient demand concentrates in South Korea, where domestic manufacturers supply both local clinic networks and export markets across Asia. The United States absorbs significant treatment volume through expanding medical spa channels. European markets operate under harmonized regulatory frameworks that accelerate cross-border clinic network expansion.
United States
Medical spas in metropolitan areas convert retail consumers into recurring aesthetic patients through membership pricing structures. The FDA Center for Biologics Evaluation and Research oversees botulinum toxin approval pathways, mandating clinical efficacy thresholds that elevate compliance costs. Los Angeles and Miami clinic chains negotiate volume-based contracting with dedicated account managers, displacing traditional distributor intermediaries.
South Korea
Domestic botulinum toxin producers supply local clinic networks and export markets across Asia, creating supply security and cost advantages. The MFDS regulates biologics manufacturing and post-market surveillance for aesthetic injectables. Seoul-based manufacturing clusters emphasize periorbital applications for export market differentiation, leveraging domestic toxin production cost advantages.
Germany
Dermatology practices with advanced facial anatomy training drive premium per-patient lifetime value in aesthetic injectables. The EMA enforces Medical Device Regulation for dermal filler classification and post-market surveillance across member states. Frankfurt and Munich serve as distribution hubs for hyaluronic acid filler supply to Central European clinic networks.
Brazil
Underdeveloped clinic infrastructure in secondary cities offers first-mover positioning for neurotoxin-filler combination protocols. ANVISA regulates biologics importation and clinical trial requirements for aesthetic products. São Paulo anchors demand concentration while regional distributors build cold chain infrastructure for last-mile delivery to emerging medical spa locations.
Japan
PMDA oversight of biologics approval creates structured pathways for botulinum toxin formulations entering the aesthetic market. Tokyo and Osaka clinic networks emphasize micro-dosing protocols for natural movement preservation. Domestic demand prioritizes subtle outcomes over complete paralysis, supporting premium pricing tiers for specialized injection techniques.
Injectable Anti-Wrinkle Treatment Market Competitive Landscape
Captive biologics manufacturing dominates the current landscape as established players secure consistent active pharmaceutical ingredient supply. The sector exhibits consolidated structure among fermentation-capable toxin producers alongside fragmented filler specialists. Three archetypes define competitive positioning: integrated biologics manufacturers with captive supply chains, hyaluronic acid specialists with direct clinic channel partnerships, and emerging biosimilar entrants leveraging regulatory pathway clarity. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers defend margin positions against supply cost volatility.
Within the integrated biologics tier, AbbVie and Galderma exemplify archetypes of captive manufacturing and direct channel control. Merz Pharma occupies a specialized position targeting precise facial musculature applications. These three entities anchor the competitive structure through differentiated supply chain configurations and end-user access strategies.
| Leading Market Players |
|---|
| AbbVie |
| Galderma |
| Merz Pharma |
| Revance Therapeutics |
| Sinclair Pharma |
| Medytox |
| Ipsen |
| Suneva Medical |
| Bloomage BioTechnology |
| Others |
Supply & Pricing Matrix
Fermentation-grade raw material price volatility cascades through sterile manufacturing networks into tiered product positioning, where South Korean captive producers extract margin advantages over contract-dependent competitors serving United States medical spa channels.
Pricing Analysis
Volume concentration in standard-unit botulinum toxin compresses margins, while premium micro-dosing protocols and combination therapy bundles preserve pricing power. Price differentiation separates FDA-approved biologics from emerging biosimilar entrants, with brand heritage and clinician training certification commanding sustained premiums. Pricing pressure stems from membership pricing structures at high-volume medical spa chains, though cold chain logistics costs partially offset erosion. Hospital procurement committees exhibit highest price sensitivity; boutique dermatology practices with advanced injection technique credentials show lowest.
Supply Chain Analysis
South Korean domestic-content mandates for biologics manufacturing reshape sourcing patterns, compelling foreign entrants to establish local fermentation partnerships or cede public tender access. Active pharmaceutical ingredient production concentrates in South Korea, Germany, and United States facilities, with Clostridium botulinum culture media and cross-linked hyaluronic acid precursor chemicals anchoring cost structures. Single-source bioreactor dependency in select European and North American sites creates contamination event vulnerability. Distribution runs through dedicated account managers at multi-location clinic groups, displacing traditional wholesale intermediaries in metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterile fermentation capacity scarcity props pricing across botulinum toxin categories, with qualified bioreactor slots constraining supply expansion faster than medical spa channel demand growth.
For Market Incumbents: Deepen captive biologics manufacturing to secure consistent active pharmaceutical ingredient supply against emerging biosimilar entrants leveraging FDA pathway clarity. Expand dedicated account manager coverage at United States medical spa chains before competitor consolidation locks in volume-based contracting. Prioritize cold chain infrastructure redundancy to defend service-level guarantees as last-mile logistics costs escalate. For New Entrants and Emerging Players: Medical spa chains in Brazilian secondary cities offer white-space positioning before local manufacturer consolidation matches neurotoxin-filler combination protocols. Target telehealth-integrated aesthetic practices seeking remote pre-screening workflows to reduce clinic overhead. Pursue regulatory approval pathway efficiency through EMA centralized procedures with parallel MFDS submissions for Asian market access. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap hyaluronic acid specialists with direct clinic channel partnerships in European markets undergoing distributor displacement. Long-term viability centers on manufacturing scale sufficient to absorb fermentation raw material volatility without margin compression. Watch FDA biosimilar guidance refinement as inflection signal for follow-on entrant valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Biologics Manufacturing Expansion | AbbVie and Galderma anchor competitive positioning through in-house fermentation capacity securing supply predictability. |
| Direct Clinic Channel Partnership | Dedicated account managers at United States medical spa chains displace legacy distributors and compress procurement cycles. |
| Micro-Dosing Protocol Certification | Advanced facial anatomy training programs differentiate premium service tiers commanding sustained pricing power. |
| Cold Chain Infrastructure Investment | Temperature excursion monitoring systems defend product integrity during last-mile delivery to high-volume clinics. |
| Regulatory Pathway Parallelization | EMA centralized procedures with mutual recognition agreements accelerate cross-border market access for toxin formulations. |
Research Methodology
Independent corroboration across aesthetic clinic operators, biologics manufacturing executives, and medical spa procurement managers underwrites the qualitative findings, with secondary validation drawing from FDA Center for Biologics Evaluation and Research filings, EMA Medical Device Regulation guidance documents, and MFDS biologics approval databases. Bottom-up treatment volume estimates from clinic network expansion plans triangulate against top-down manufacturer shipment data to anchor market sizing.
Rate-of-change decomposition across product type, application, end user, and delivery method segments structures the analytical framework over the projection horizon. CAGRs derive from segmented volume trajectories weighted by pricing tier evolution, with inputs including medical spa membership pricing penetration rates and biosimilar approval pathway timelines. Modeling incorporates cold chain logistics cost inflation and fermentation raw material price indices as supply-side variables.
Caveats apply where FDA pharmacovigilance mandate intensification or single-source bioreactor contamination events could materially shift the outlook. Forecasts reflect assumptions regarding clinician training certification expansion and medical spa regulatory scope-of-practice stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
North America Dermal Fillers Market
Medical Aesthetics
Breast Reconstruction and Augmentation Market
Medical Aesthetics
China Laser Hair Removal Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Facial Injector Market
Medical Aesthetics
Cosmetic Threads Market
Medical Aesthetics
Hair Transplant Market
Medical Aesthetics
India Hair Transplant Market
Medical Aesthetics
Facial Injectables Market
Medical Aesthetics
Tattoo Removal Patch Market
Medical Aesthetics
Non-Hyaluronic Acid Dermal Filler Market
Medical Aesthetics
France Hair Transplant Market
Medical Aesthetics
Europe Facial Injectable Market
Medical Aesthetics
Korea Medical Aesthetics Market
Medical Aesthetics
Lip Augmentation Market
Medical Aesthetics
Tattoo Removal Market