
 Chemotherapy Induced Pain Market | 2026-2036
Chemotherapy Induced Pain Market Size, Share, and Industry Trends Forecast 2026-2036
Chemotherapy Induced Pain Market Outlook
Extended-release formulation tiers is collapsing the distinction between hospital-administered and take-home pain regimens. Pfizer leverages its manufacturing scale to supply institutional channels across North America and Europe. Eli Lilly and Company anchors its position through R&D intensity in neuropathic pain mechanisms. Teva Pharmaceutical Industries Ltd specializes in generic analgesic portfolios that compete aggressively on price in outpatient settings.
Chemotherapy induced pain encompasses peripheral neuropathy, mucositis, and bone pain syndromes triggered by cytotoxic agents including taxanes, platinum compounds, and vinca alkaloids; management protocols integrate sodium channel blockers, calcium channel modulators, and corticosteroid co-therapies to preserve treatment adherence and dose intensity. The analgesics segment dominates current prescribing volumes, while transdermal delivery modes capture expanding share among home care patients seeking to avoid repeated clinic visits. Cancer treatment centers represent the most concentrated margin pool, though outpatient clinics are growing fastest as same-day chemotherapy protocols proliferate.
The FDA's REMS requirements for extended-release opioids and the EMA's pharmacovigilance obligations for neuropathic agents shape formulation development priorities and label expansion strategies. Health Canada's PMRA standards for abuse-deterrent packaging and the EU MDR's clinical evidence requirements for combination pain devices further constrain market access timelines. Stakeholders must monitor evolving payer criteria for non-opioid first-line protocols and the integration of digital biomarkers into pain assessment workflows.
Market Dynamics
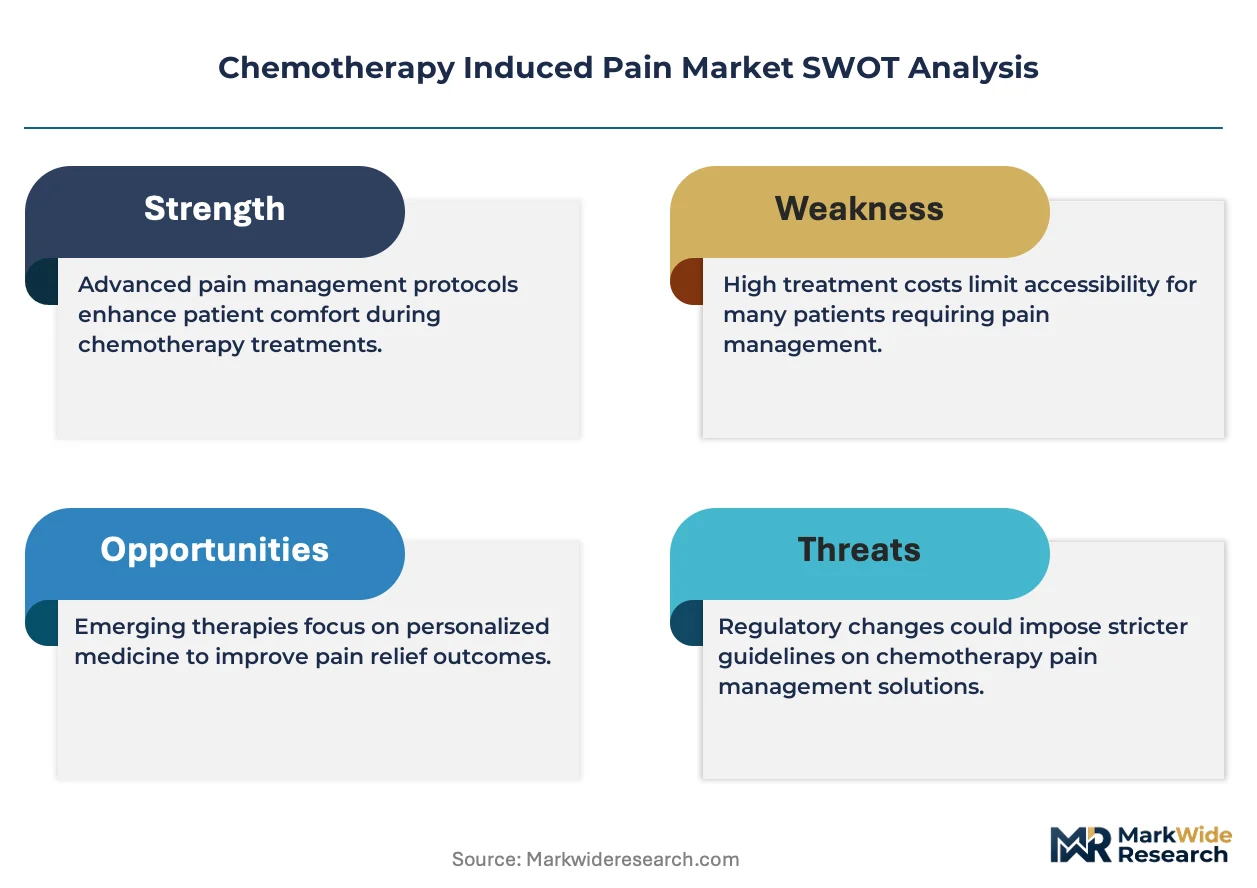
The FDA's REMS expansion for extended-release opioids is forcing pharmaceutical developers to pivot investment toward non-narcotic analgesic pathways, collapsing the traditional hospital-take-home pricing distinction and redrawing competitive boundaries across formulation tiers.
Growth Catalysts
- Platinum-based regimen expansion:Oncology protocols increasingly incorporate carboplatin and oxaliplatin combinations, amplifying peripheral neuropathy incidence and driving demand for sodium channel blockers and calcium channel modulators in cancer treatment centers.
- Medicare reimbursement realignment:United States outpatient administration models now receive preferential reimbursement rates, accelerating same-day chemotherapy protocols and expanding addressable patient populations for home-based pain management.
- EMA pharmacovigilance integration:European neuropathic agent oversight requirements are standardizing clinical evidence thresholds, elevating barriers for marginal competitors and consolidating prescribing authority around validated formulations.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for gabapentinoids concentrates in Indian and Chinese contract manufacturers, exposing formulators to geopolitical friction and customs delays.
- Abuse-deterrent packaging mandates:Health Canada's PMRA standards impose capital-intensive retrofit requirements on extended-release opioid portfolios, compressing margins for legacy products.
- Generic price erosion:Teva Pharmaceutical Industries and Mylan (Viatris) have saturated outpatient channels with commoditized analgesics, constraining branded pricing power in volume-heavy segments.
Strategic Opportunities
- Transdermal delivery white space:Home care patients seeking to avoid repeated clinic visits are driving demand for patch-based formulations, creating expansion opportunities for companies with proprietary permeation technologies.
- Digital biomarker integration:Wearable pain assessment tools are converging with electronic health record systems, enabling outcome-based contracting models with United States payers.
- EU MDR combination device pathway:The European Union's Medical Device Regulation creates accelerated review channels for analgesic-device combinations, rewarding firms with integrated R&D capabilities.
Industry Challenges
- Neuropathic mechanism expertise scarcity:Formulation scientists with specialized knowledge of ion channel pharmacology command premium compensation, constraining mid-tier developers' hiring pipelines.
- Legacy system integration friction:Cancer treatment centers require seamless connectivity between pain management platforms and chemotherapy ordering systems, extending sales cycles for standalone digital health vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemotherapy Induced Pain Market |
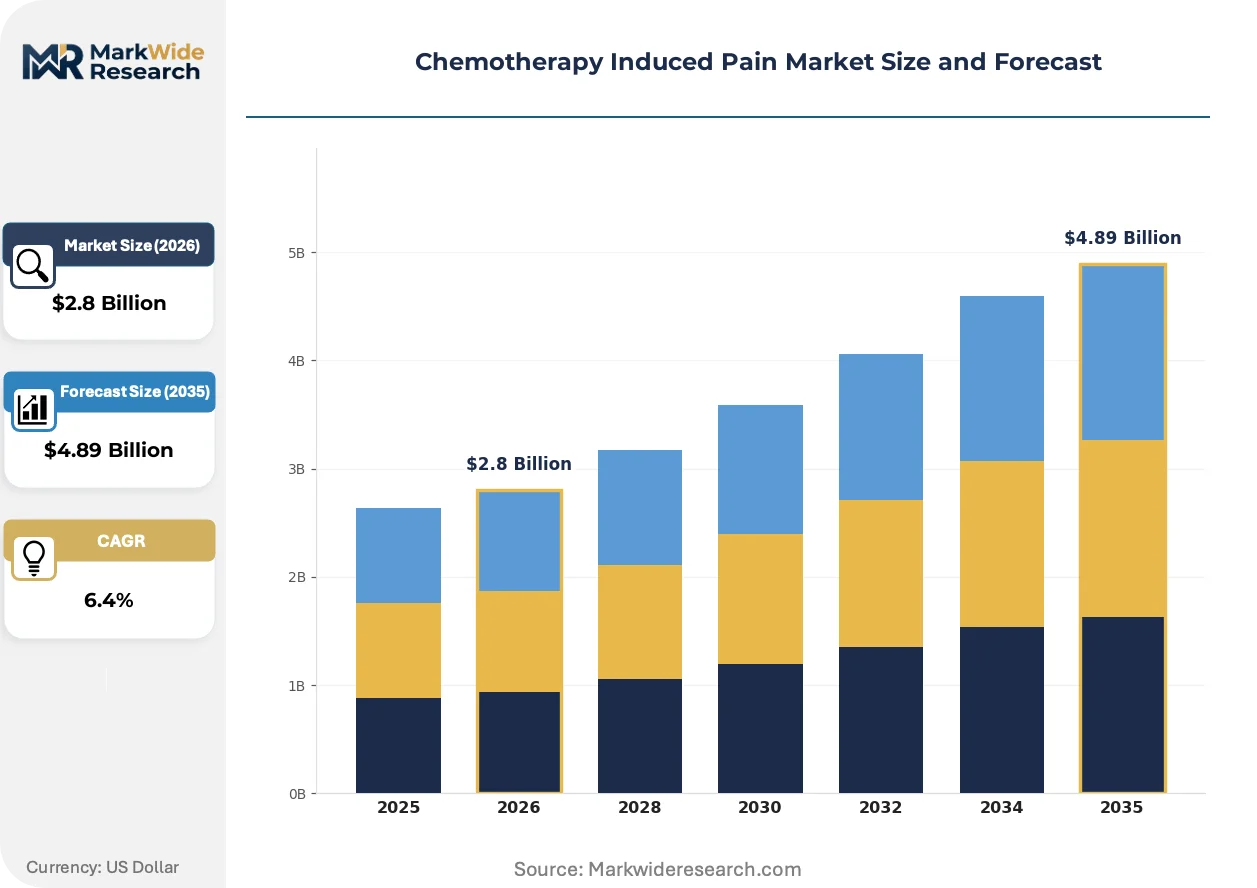
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Antidepressants, Anticonvulsants, Steroids Delivery Mode: Oral, Intravenous, Topical, Transdermal End User: Hospitals, Outpatient Clinics, Home Care, Cancer Treatment Centers Administration Route: Oral Administration, Injection, Infusion, Patch |
| Companies Covered | Teva Pharmaceutical Industries Ltd, Eli Lilly and Company, Pfizer, Viatris Inc, Sun Pharmaceutical Industries Ltd, Aurobindo Pharma Limited, Lupin Limited, Zydus Lifesciences Limited, WEX Pharmaceuticals Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemotherapy Induced Pain Market Strategic Shifts
Formulation science and regulatory architecture are actively reshaping competitive positioning in chemotherapy induced pain management, with three distinct vectors redefining how value is created and captured across the care continuum.
Extended-release depot injectables are bifurcating the market between institutional and ambulatory administration models. Cancer treatment centers in the United States are adopting these formulations to reduce nursing burden during infusion sessions. The technology is compressing reimbursement arbitrage between hospital and outpatient settings.
REACH authorization requirements for novel excipients are elevating toxicology documentation burdens for European formulation developers. Manufacturers must now submit extended safety dossiers for polymer-based delivery vehicles. Small and mid-sized developers are responding by partnering with established excipient suppliers rather than pursuing independent regulatory pathways.
Patient-reported outcome integration into payer contracts is restructuring procurement criteria for United States health systems. Pharmacy benefit managers are unbundling pain management from bundled oncology payments, creating direct purchasing relationships with specialty pharmacies. This shift is most visible in Medicare Advantage plans operating in Florida and Arizona retirement corridors.
Chemotherapy Induced Pain Market Segmentation
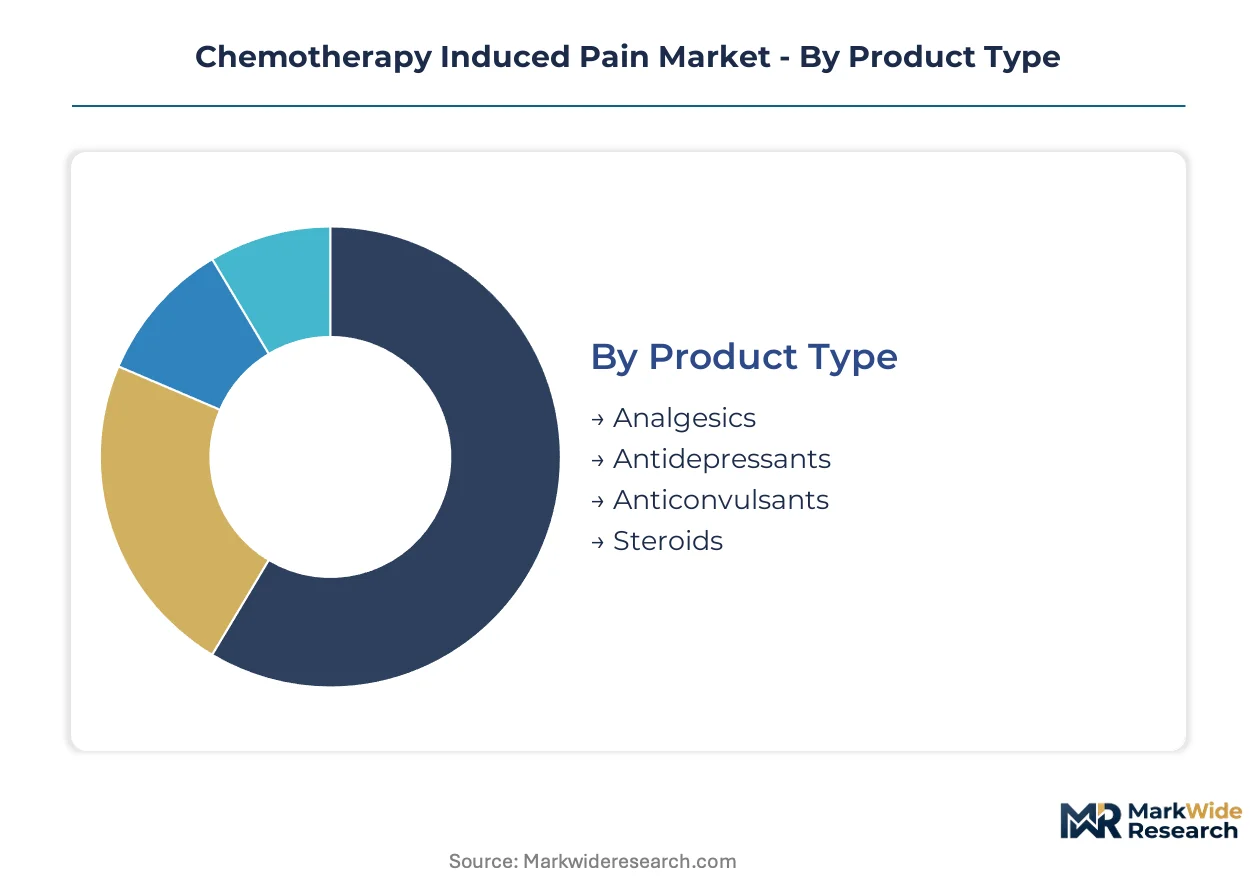
Segmentation in chemotherapy induced pain management reveals how formulation choices and care settings interact to determine commercial access. Channel economics and reimbursement flows differ materially across each dimension, shaping where manufacturers concentrate development resources.
Product Type:
Analgesics dominate hospital formularies through institutional purchasing contracts, while antidepressants and anticonvulsants flow increasingly through specialty pharmacy channels serving outpatient oncology.
- Analgesics:Non-opioid and opioid formulations constitute the foundational prescribing tier across cancer treatment centers. Demand concentrates in United States Medicare Advantage networks where prior authorization protocols favor first-line non-narcotic protocols.
- Anticonvulsants:Gabapentinoids target peripheral neuropathy from platinum-based regimens through calcium channel modulation. Prescribing authority is consolidating around neurologists affiliated with National Cancer Institute-designated centers.
- Antidepressants:Serotonin-norepinephrine reuptake inhibitors address neuropathic pain comorbid with cancer-related depression. Duloxetine and venlafaxine formulations compete on formulary placement in integrated delivery networks.
- Steroids:Dexamethasone co-therapies manage bone pain and mucositis through anti-inflammatory mechanisms. Procurement runs through group purchasing organizations serving academic medical centers.
By volume, analgesics lead. By growth pace, anticonvulsants are expanding most quickly as neuropathy incidence rises with expanded platinum-based protocol adoption.
Delivery Mode:
Cost tier differentiation separates premium infusion-based administration from economy oral generics, with transdermal formats capturing mid-tier positioning through convenience premiums.
- Oral:Immediate-release and extended-release tablets dominate outpatient prescribing through retail pharmacy distribution. Medicare Part D coverage tiers determine patient out-of-pocket exposure for branded versus generic alternatives.
- Intravenous:Infusion-suite administration captures higher reimbursement rates under hospital outpatient prospective payment systems. Cancer treatment centers in the United States deploy IV formulations to maintain dose intensity during curative-intent protocols.
- Topical:Cream and gel formulations address localized mucositis and dermatologic toxicity from radiation-chemotherapy combinations. Compounding pharmacies in Florida and Arizona retirement corridors service demand from geriatric oncology populations.
- Transdermal:Patch technologies eliminate clinic visit requirements for stable chronic pain patients. Proprietary permeation enhancers differentiate premium offerings from commodity lidocaine patches in home care settings.
By patient volume, oral formats dominate. By value concentration, intravenous administration captures the highest per-dose revenue.
End User:
Customer type determines procurement authority structure, with hospitals maintaining centralized pharmacy committees while home care routes through specialty pharmacy benefit managers.
- Cancer Treatment Centers:National Cancer Institute-designated comprehensive cancer centers concentrate prescribing authority for novel neuropathic agents. Formulary decisions integrate pain management protocols with chemotherapy ordering systems.
- Hospitals:General acute care facilities manage chemotherapy induced pain through oncology service lines with embedded palliative care consultation. Group purchasing organization contracts standardize analgesic selection across health system affiliates.
- Outpatient Clinics:Same-day chemotherapy infusion centers proliferate under Medicare reimbursement models favoring ambulatory administration. Community oncology practices in Texas and California retirement corridors drive demand for take-home pain regimens.
- Home Care:Hospice and home health agencies manage terminal cancer pain through nurse-administered protocols. Family caregiver training requirements influence formulation selection toward simpler administration modes.
By revenue concentration, cancer treatment centers lead. By expansion trajectory, outpatient clinics are gaining share fastest as same-day protocols displace inpatient admissions.
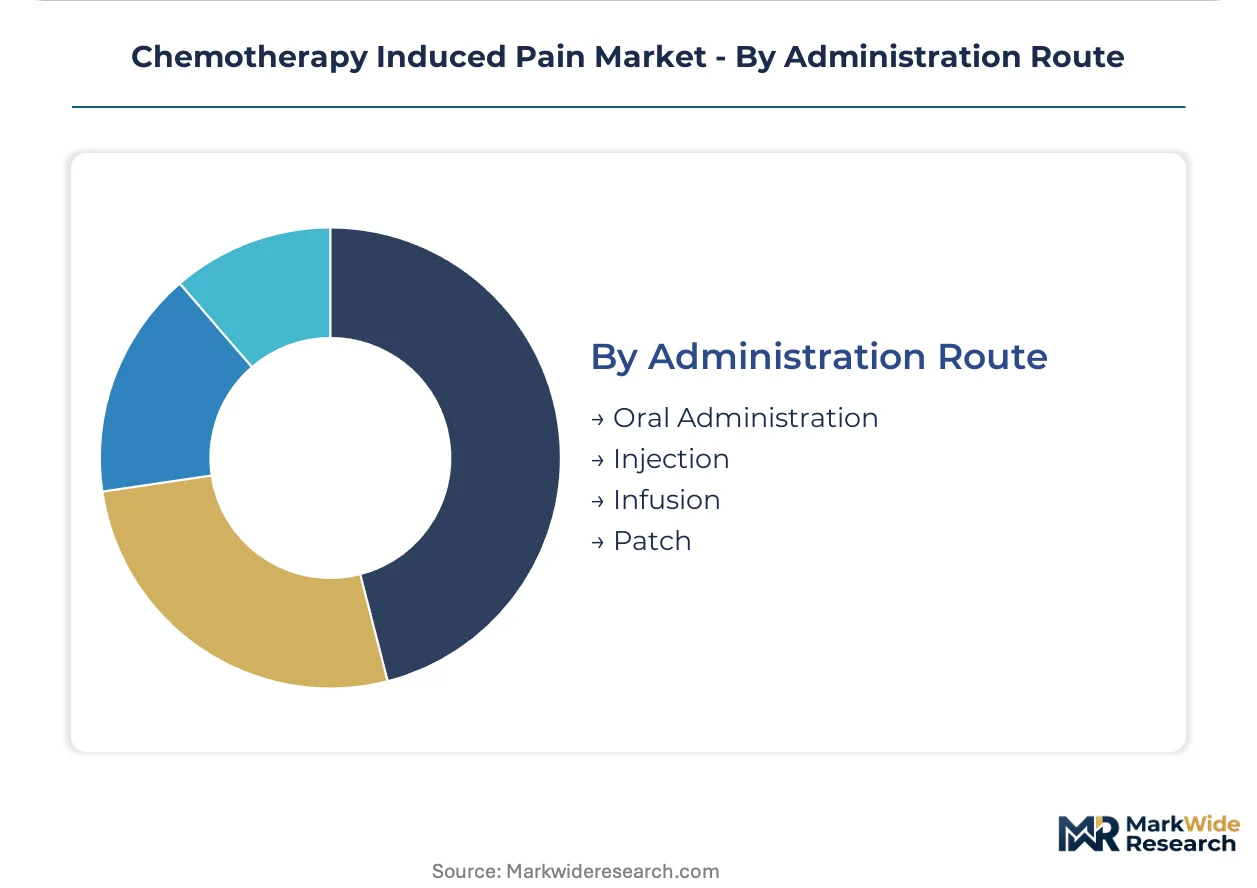
Administration Route:
Supply concentration varies by mechanical complexity, with injection and infusion formats requiring specialized manufacturing capabilities that oral and patch formats do not.
- Injection:Subcutaneous and intramuscular depot formulations extend dosing intervals for patients with compromised gastrointestinal function. Manufacturing concentrates among sterile injectable specialists with FDA-compliant aseptic processing lines.
- Oral Administration:Tablet and capsule formats enable patient self-management outside clinical supervision. Bioequivalence standards from the FDA's Office of Generic Drugs govern substitutability across therapeutic categories.
- Infusion:Pump-administered continuous delivery maintains steady-state plasma concentrations for severe neuropathic pain. Ambulatory infusion center expansion in United States suburban markets drives demand for portable pump-compatible formulations.
- Patch:Reservoir and matrix designs control release kinetics over 72-hour to 7-day wear periods. Adhesive formulation expertise distinguishes commercial winners from products with high discontinuation rates due to skin irritation.
By prescription volume, oral administration dominates. By technical differentiation potential, patch formats are climbing the fastest as permeation science advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pharmaceutical exports supply chemotherapy induced pain formulations to Canadian cancer treatment centers and European hospital networks, establishing transatlantic trade corridors that shape regional market access strategies.
United States
Medicare Advantage plans in Florida and Arizona retirement corridors drive outpatient pain management adoption. FDA REMS requirements for extended-release opioids redirect investment toward non-narcotic pathways. The National Cancer Institute-designated comprehensive cancer centers in Houston and New York concentrate prescribing authority for novel neuropathic agents.
Germany
Oncology service lines in university hospitals expand same-day chemotherapy protocols requiring take-home pain regimens. EMA pharmacovigilance obligations for neuropathic agents standardize clinical evidence thresholds. The Rhine-Ruhr metropolitan region hosts concentrated manufacturing capabilities for sterile injectable analgesics serving Central European distribution networks.
India
Contract manufacturing organizations in Hyderabad and Ahmedabad supply active pharmaceutical ingredients for gabapentinoids to North American and European formulators. CDSCO approval pathways for novel excipients extend development timelines for polymer-based delivery vehicles. The Mumbai-Pune pharmaceutical cluster specializes in generic analgesic production competing on price in outpatient channels.
Japan
Aging demographics amplify demand for bone pain management in platinum-based ovarian and lung cancer protocols. PMDA consultation procedures for combination pain devices accelerate review timelines for integrated analgesic-delivery systems. The Kanto region around Tokyo concentrates hospital pharmacy procurement authority for premium formulation tiers.
United Kingdom
NHS England integrated care systems unbundle pain management from bundled oncology payments, creating direct purchasing relationships with specialty pharmacies. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for abuse-deterrent packaging innovations. The Greater Manchester and London cancer alliances pilot digital biomarker integration into pain assessment workflows.
Chemotherapy Induced Pain Market Competitive Environment
Listed leaders compete with private specialists across formulation tiers and channel access, producing a bifurcated structure where scale-driven pharmaceutical conglomerates dominate institutional procurement while regional specialists capture outpatient niches. The market stratifies into three archetypes: vertically integrated innovators controlling proprietary delivery technologies, generic manufacturers competing on manufacturing scale and regulatory filing speed, and specialty developers concentrating on mechanism-specific neuropathic agents. Competitive moves center on portfolio diversification into transdermal formats and strategic partnerships with digital health platforms for outcome-based contracting.
Among Israel-based specialists, Teva Pharmaceutical Industries Ltd exemplifies the generic-scale archetype through aggressive price positioning in commoditized outpatient segments. Eli Lilly and Company anchors the innovation tier with R&D intensity in neuropathic pain mechanisms. Pfizer occupies a position leveraging manufacturing scale to supply institutional channels across North America and Europe.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd |
| Eli Lilly and Company |
| Pfizer |
| Viatris Inc |
| Sun Pharmaceutical Industries Ltd |
| Aurobindo Pharma Limited |
| Lupin Limited |
| Zydus Lifesciences Limited |
| WEX Pharmaceuticals Inc |
| Others |
Value Chain & Pricing Dynamics
FDA REMS certification tiers gate both API supplier qualification and branded-generic price differentiation simultaneously, concentrating margin capture among manufacturers with institutional formulary access while compressing returns for undifferentiated outpatient competitors.
Pricing Analysis
Hospital pharmacy committees anchor pricing power through group purchasing organization contracts that standardize analgesic selection across health system affiliates. Three-tier pricing structure across premium extended-release, standard immediate-release, and economy generic tiers separates infusion-suite formulations from retail pharmacy alternatives. Cost compression in generic gabapentinoid segments intensifies because Teva and Viatris have saturated outpatient channels with commoditized portfolios. Community oncology practices exhibit highest price sensitivity; NCI-designated cancer centers demonstrate lowest sensitivity due to bundled reimbursement protocols.
Supply Chain Analysis
Active pharmaceutical ingredient manufacturing concentrates in India and China, exposing formulators to customs friction and geopolitical disruption. Sterile injectable capacity draws from the Rhine-Ruhr metropolitan region and the Mumbai-Pune pharmaceutical cluster. Gabapentinoid precursors, polymer-based delivery vehicles, and abuse-deterrent packaging materials constitute critical input dependencies. Single-source vulnerability runs through Indian contract manufacturers supplying North American formulators. Distribution runs through specialty pharmacy benefit managers serving Medicare Advantage networks and group purchasing organizations anchoring hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-opioid analgesic substitution threatens incumbent opioid portfolios as FDA REMS requirements redirect prescribing toward sodium channel blockers and calcium channel modulators.
For Market Incumbents: Consolidate formulation expertise in neuropathic pain mechanisms through selective acquisition of ion channel pharmacology specialists. Deepen backward integration into active pharmaceutical ingredient supply by securing long-term contracts with Hyderabad and Ahmedabad manufacturers. Defend against generic erosion by accelerating transdermal delivery platform development. For New Entrants and Emerging Players: Digital biomarker integration gaps in pain assessment workflows create service-layer entry points for outcome-based contracting models. Target Medicare Advantage plans in Florida and Arizona retirement corridors where prior authorization protocols favor non-narcotic first-line protocols. Pursue hospital system partnerships that embed pain management platforms within chemotherapy ordering systems. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sterile injectable manufacturing as EU MDR clinical evidence requirements elevate facility compliance costs. Long-term viability favors vertically integrated developers controlling proprietary permeation technologies alongside regulatory filing capabilities. Acquisition targets should demonstrate integrated R&D capabilities with validated neuropathic agent pipelines. Monitor FDA label expansion timelines for novel excipient categories as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Transdermal Delivery Platform Development | Proprietary permeation technologies capture home care patients avoiding clinic visits under Medicare reimbursement models. |
| Digital Biomarker Integration | Wearable pain assessment tools enable outcome-based contracting with United States pharmacy benefit managers. |
| EU MDR Combination Device Pathway | Accelerated review channels reward firms with integrated analgesic-delivery system capabilities in European markets. |
| API Supply Contract Securement | Long-term agreements with Indian manufacturers mitigate geopolitical exposure in gabapentinoid precursor sourcing. |
| Non-Opioid Formulation Pipeline Expansion | EMA pharmacovigilance obligations elevate barriers for marginal competitors in neuropathic agent categories. |
Study Parameters
Operator-level perspectives from formulary directors, hospital procurement managers, regulatory affairs leads, and payer access specialists anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation cross-checked segmentation outputs across product type, delivery mode, end user, and administration route dimensions.
Sensitivity analysis framed analytical approach across the projection horizon without specifying discrete year markers. Segmentation dimensions modeled included analgesic category tier, formulation technology, care setting, patient population severity, and regional regulatory cluster. CAGRs derived from historical prescription volume trajectories, reimbursement rate evolution, and protocol adoption curves in platinum-based and taxane regimens. Forecast inputs incorporated neuropathy incidence projections from expanded chemotherapy combinations and Medicare Advantage penetration rates in retirement corridors.
Forecasts assume regulatory continuity in FDA REMS, EMA pharmacovigilance, and Health Canada PMRA regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as opioid risk evaluation protocols, API trade policy, and digital health reimbursement criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Provoked Vestibulodynia Treatment Market
Pain Management
Cancer Pain Market
Pain Management
Migraine Management Market
Pain Management
Global Morphine Market
Pain Management
Chronic Pain Market
Pain Management
Postoperative Pain Market
Pain Management
Lumbosacral Radicular Pain Management Market
Pain Management
Central Pain Syndrome Management Market
Pain Management
Chronic Pain Treatment Market
Pain Management
Chinese Fibromyalgia Market
Pain Management
OTC Painkiller Market
Pain Management
Medicated Pain Relieving Plasters Market
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
Advanced Cancer Pain Management Market
Pain Management
Non Opioid Pain Treatment Market
Pain Management
Tattoo Numbing Cream Market