
 Ice Packs for Pain Market | 2026-2036
Ice Packs for Pain Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Packs for Pain Market Insights
The premium segment is repositioning around clinical-grade temperature consistency and extended duration control, while commodity tiers compete on unit cost and retail shelf turnover. Cardinal Health leverages its hospital distribution network to sustain volume contracts across acute care settings. DJO differentiates through specialized cold wraps that anchor its position in orthopedic recovery protocols. Kobayashi Pharmaceutical dominates consumer pharmacy channels in East Asia with instant cold pack formats.
Ice packs for pain are sealed thermal reservoirs containing gel, liquid, or phase-change materials designed to deliver controlled cold therapy to soft tissue injuries, surgical sites, or chronic pain loci, typically maintaining therapeutic temperatures between 10°C and 15°C for 15–30 minutes. Their primary purpose is to reduce inflammation, numb nerve response, and limit edema formation without pharmaceutical intervention. Reusable gel packs command the widest margin pools due to durability premiums and healthcare procurement cycles, while instant cold packs lead growth in emergency and athletic sidelines where refrigeration access is absent. Cold wraps represent the fastest-expanding structural category as they integrate compression with thermal delivery, addressing post-surgery recovery protocols that demand immobilization alongside cooling.
FDA 510(k) clearance pathways for therapeutic cold devices and CE marking under the EU Medical Device Regulation shape product design requirements, testing documentation, and market access timelines for manufacturers serving regulated channels. ISO 13485 quality management standards further govern production consistency for suppliers targeting institutional buyers. Stakeholders must monitor how reimbursement coding for at-home cold therapy evolves against institutional procurement budgets, as this balance will determine whether premium clinical formats penetrate residential care or retreat to hospital-only deployment.
Market Dynamics
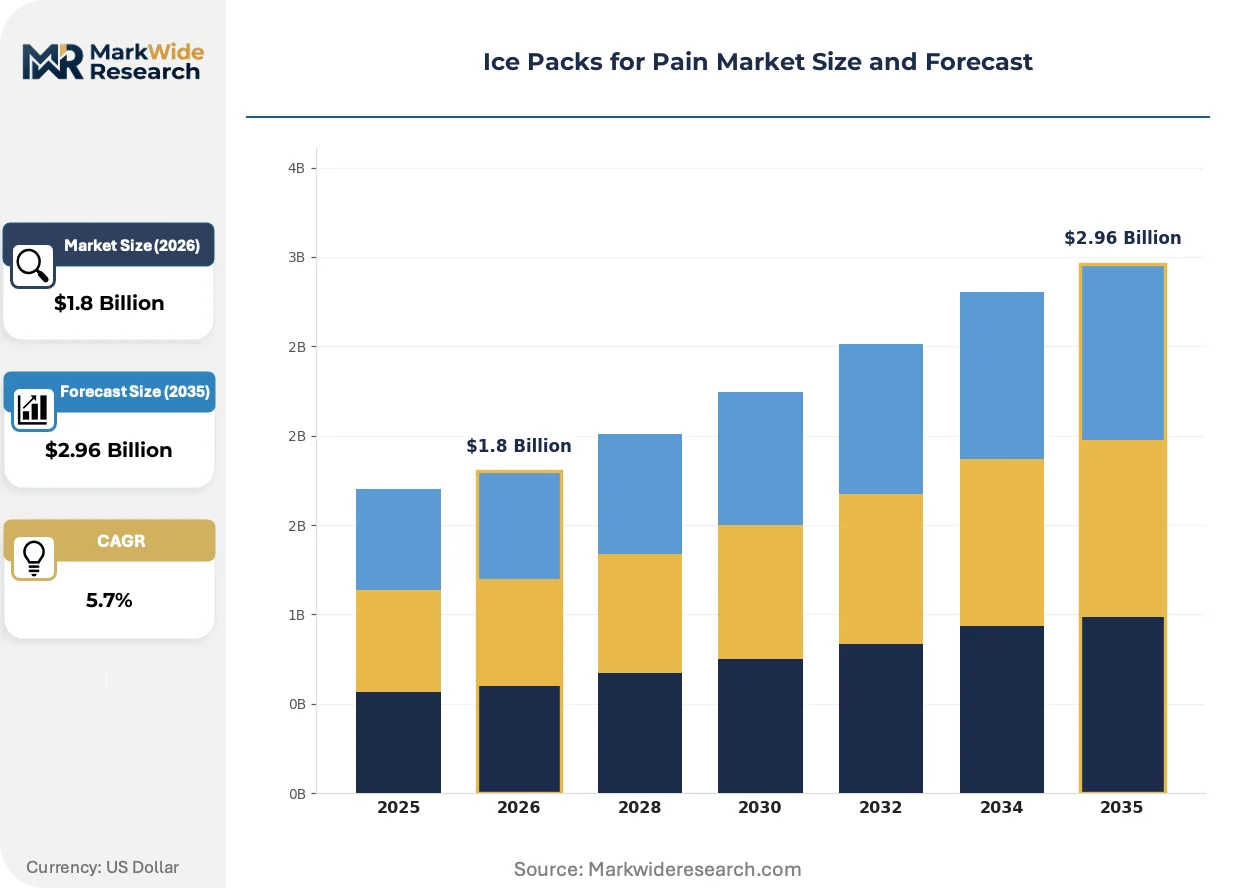
Reimbursement coding divergence between institutional and at-home cold therapy is compressing margin pools and forcing manufacturers to choose between premium clinical-grade positioning and high-volume retail distribution.
Growth Catalysts
- Physiotherapy Reimbursement:Germany's statutory health insurance framework favors professional-grade cold therapy devices, channeling procurement toward reusable gel-based systems in outpatient rehabilitation centers.
- Phase-Change Materials:Advanced thermal compounds extending therapeutic duration beyond 30 minutes are displacing conventional gel formulations in post-surgical recovery protocols.
- Athletic Sideline Demand:Emergency medicine and sports training facilities without refrigeration access are driving procurement of instant cold packs for acute injury response.
Market Restraints
- Input Cost Volatility:Polymer resin prices for pack housings fluctuate with petrochemical feedstock markets, squeezing margins on commodity-tier disposable products.
- Regulatory Friction:FDA 510(k) clearance timelines for therapeutic cold devices extend market entry cycles by 12-18 months for novel temperature-control mechanisms.
- Substitution Threat:Cryotherapy chambers and cold compression therapy systems are capturing orthopedic recovery budgets previously allocated to portable ice packs.
Strategic Opportunities
- Home Recovery Expansion:Post-operative patients in the United States seeking at-home rehabilitation tools represent underpenetrated demand for prescription-grade cold wraps with insurance coding.
- Technology Convergence:Integration of temperature sensors with mobile health platforms is creating connected cold therapy devices for remote patient monitoring.
- Channel Innovation:Direct-to-consumer subscription models for reusable gel pack replacement cycles are bypassing traditional pharmacy and medical supply distributors.
Industry Challenges
- Certification Timeline Compression:ISO 13485 quality management audits and EU MDR technical documentation requirements strain mid-tier manufacturers with limited regulatory affairs capacity.
- Supply Chain Reconfiguration:Reliance on single-source polymer suppliers in East Asia creates vulnerability to logistics disruptions and tariff exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Packs for Pain Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: F gel packs, Reusable ice packs, Instant cold packs, Cold wraps Application: Sports injuries, Post-surgery recovery, Chronic pain management, Home care End User: Athletes, Healthcare providers, Patients, Home users Material: Plastic, Gel, Cloth, Rubber |
| Companies Covered | 3M, Cardinal Health, DJO, Breg, Medline Industries, Performance Health, Kobayashi Pharmaceutical, Rapid Aid, Beurer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Packs for Pain Market Trends and Innovations
Product development is pivoting toward temperature precision and connectivity, with manufacturers embedding sensor technology and pursuing stricter medical device certifications to capture institutional procurement budgets.
Phase-change material formulations with engineered melting points are automating temperature maintenance within the 10°C-15°C therapeutic window without user intervention. Orthopedic surgery centers and sports medicine clinics are adopting these systems for standardized post-operative protocols. The technology is automating compliance with duration-sensitive icing regimens, reducing nursing labor and liability exposure from tissue damage caused by over-cooling.
EU Medical Device Regulation (MDR) Class IIa classification requirements for cold therapy devices with therapeutic claims are tightening technical documentation and clinical evidence standards. Manufacturers must now submit biocompatibility testing and risk management files that exceed previous Medical Device Directive thresholds. Reusable gel pack suppliers targeting European hospital procurement are responding by restructuring quality systems and engaging notified bodies earlier in product development cycles.
Hospital procurement departments are consolidating vendor lists and demanding outcome guarantees for thermal therapy devices, displacing transactional purchasing with multi-year performance contracts. Group purchasing organizations are centralizing cold therapy sourcing decisions, marginalizing smaller suppliers lacking national distribution scale. This concentration is most visible in United States acute care networks, where standardized cold wrap protocols are replacing heterogeneous product mixes across facility footprints.
Ice Packs for Pain Market Segmentation
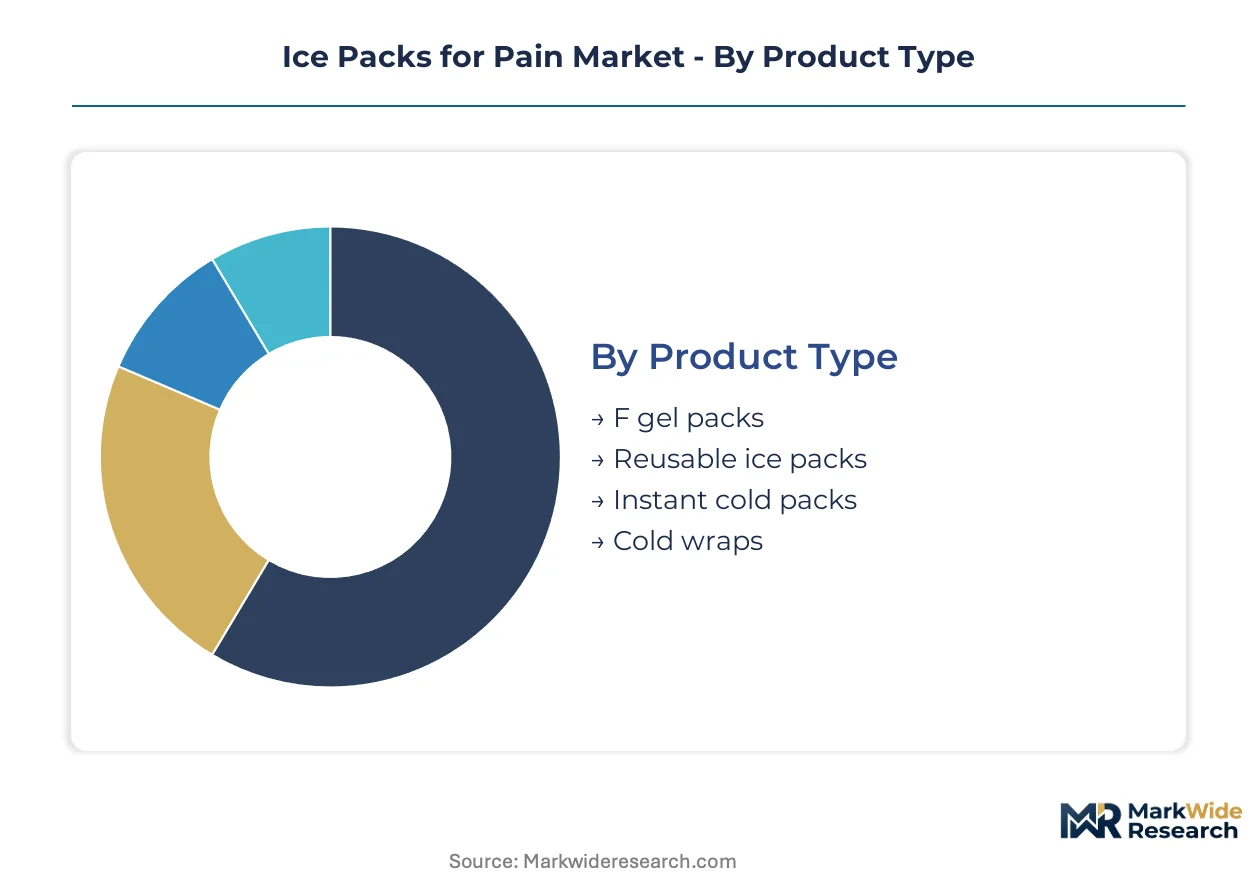
Ice pack manufacturers configure product portfolios across four distinct axes to capture divergent margin pools. Material specifications determine thermal performance ceilings, while end-user targeting shapes channel strategy and regulatory compliance burdens.
Product Type:
Phase-change mechanics and reusability cycles define competitive positioning within thermal delivery systems.
- Reusable gel packs:Polymer-encased aqueous gel formulations withstand hundreds of freeze-thaw cycles without thermal degradation. Germany's outpatient rehabilitation centers favor these systems due to statutory insurance reimbursement for durable medical equipment.
- Cold wraps:Integrated compression garments with embedded gel chambers immobilize joints while delivering targeted cooling. Post-surgical recovery protocols in US orthopedic surgery centers are standardizing these formats to reduce nursing labor.
- Instant cold packs:Ammonium nitrate or urea-based endothermic reactions activate without refrigeration. Athletic trainers and emergency medical technicians stock these for sideline injury response where power access is absent.
- F gel packs:Flexible low-temperature formulations conform to anatomical contours. Physical therapy clinics deploy these for facial and pediatric applications requiring pliable cold sources.
Reusable gel packs lead on scale; cold wraps lead on momentum.
Application:
Clinical setting determines performance thresholds, from acute trauma response to long-term home maintenance regimens.
- Post-surgery recovery:Hospital discharge protocols now mandate cold therapy for orthopedic procedures, creating institutional procurement pipelines for prescription-grade wraps. US insurance coding variations between inpatient and at-home use compress manufacturer margins.
- Sports injuries:Professional athletic organizations and collegiate programs maintain centralized cold therapy inventories. Phase-change material systems with 30-plus minute duration are displacing conventional gel in training facilities.
- Chronic pain management:Rheumatology and pain clinic patients require daily thermal intervention. Reusable formats dominate this segment due to cost sensitivity and environmental disposal concerns.
- Home care:Post-operative patients and aging populations self-administer cold therapy without clinical supervision. Retail pharmacy channels and direct-to-consumer subscriptions are expanding access to clinical-grade formats.
Post-surgery recovery commands procurement volume; home care is climbing the fastest.
End User:
Purchasing authority and reimbursement access create divergent customer archetypes with distinct service requirements.
- Healthcare providers:Hospitals, surgery centers, and physiotherapy clinics negotiate multi-year performance contracts through group purchasing organizations. FDA 510(k) clearance and ISO 13485 certification are mandatory for vendor qualification.
- Athletes:Professional sports franchises, collegiate programs, and individual competitors prioritize rapid deployment and portability. Instant cold packs satisfy refrigeration-free requirements of competitive venues.
- Patients:Individuals recovering from surgery or managing chronic conditions purchase through prescription channels or retail. Insurance reimbursement eligibility determines format selection between clinical and consumer tiers.
- Home users:General consumers address minor injuries and wellness applications without clinical diagnosis. Pharmacy retail and e-commerce platforms serve this price-sensitive segment.
Healthcare providers anchor institutional revenue; home users are gaining share fastest.
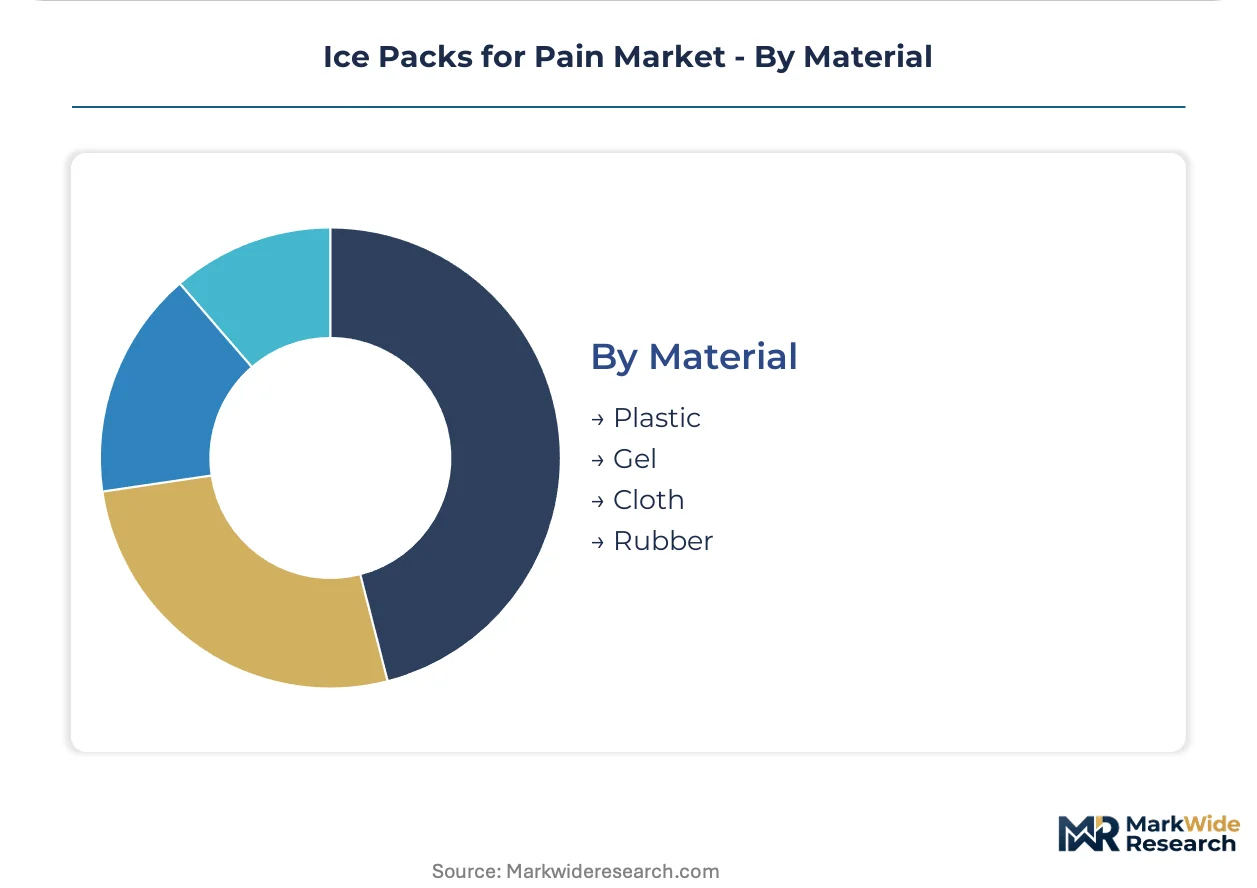
Material:
Housing composition and thermal medium selection govern durability, biocompatibility, and disposal pathways.
- Gel:Cross-linked polymer aqueous solutions store latent heat for controlled release. Medical-grade formulations meeting ISO 10993 biocompatibility standards command premium positioning in regulated channels.
- Plastic:Polyethylene and PVC housings provide barrier protection and puncture resistance. Polymer resin price volatility tied to petrochemical feedstocks squeezes margins on high-volume disposable formats.
- Cloth:Fabric sleeves and wraps enable skin-contact comfort and moisture wicking. Consumer preference for washable, reusable formats drives adoption in home care segments.
- Rubber:Elastomeric bladders withstand extreme temperature differentials and mechanical stress. Industrial and institutional applications favor these for extended service life.
Plastic leads on manufacturing scale; gel leads on clinical specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled physiotherapy professionals concentrate in Germany, where statutory insurance frameworks channel procurement toward clinical-grade cold therapy systems. This workforce density shapes regional demand patterns across rehabilitation networks.
United States
Orthopedic surgery centers in Texas and Florida drive institutional procurement of prescription-grade cold wraps for post-operative protocols. FDA 510(k) clearance timelines extend market entry cycles for novel temperature-control mechanisms. Hospital procurement consolidation across the Southeast is displacing heterogeneous product mixes with standardized vendor contracts.
Germany
Outpatient rehabilitation centers favor reusable gel-based systems under statutory health insurance reimbursement rules. EU MDR Class IIa classification requirements tighten technical documentation standards for therapeutic claims. Manufacturing clusters in Baden-Württemberg supply polymer-encased formulations to physiotherapy networks across Bavaria and North Rhine-Westphalia.
Japan
Aging demographics expand home care demand for daily thermal intervention in chronic pain management. PMDA medical device regulations govern biocompatibility testing for skin-contact cold therapy products. Tokyo-based distributors serve pharmacy retail channels while Osaka manufacturers specialize in flexible low-temperature formulations for pediatric applications.
China
Sports medicine clinics in Shanghai and Beijing procure phase-change material systems for standardized athletic recovery protocols. NMPA medical device registration requirements shape product design documentation for institutional buyers. Manufacturing capacity in Guangdong Province supplies both domestic hospital networks and export markets for instant cold pack formats.
United Kingdom
NHS procurement frameworks prioritize cost-effective reusable formats for outpatient physiotherapy services. MHRA compliance with EU-UK trade agreement technical standards affects cross-border supply continuity. London-based group purchasing organizations centralize cold therapy sourcing decisions for acute care networks across England.
Ice Packs for Pain Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered supply structures. The vendor base organizes around three strategic archetypes: diversified health conglomerates with hospital distribution scale, specialized orthopedic device manufacturers with surgical protocol integration, and consumer health specialists with pharmacy channel dominance. Consolidation pressure from group purchasing organizations favors national distribution scale, while mid-tier suppliers defend position through ISO 13485 certification and regional regulatory expertise.
Among diversified health conglomerates, 3M and Cardinal Health exemplify scale-driven archetypes with institutional procurement leverage. DJO occupies a position within the orthopedic specialization tier, anchoring its presence through surgical protocol integration. Kobayashi Pharmaceutical represents the consumer pharmacy channel dominance model in East Asian markets. These three patterns illustrate how competitive positioning fragments across reimbursement access points rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| 3M |
| Cardinal Health |
| DJO |
| Breg |
| Medline Industries |
| Performance Health |
| Kobayashi Pharmaceutical |
| Rapid Aid |
| Beurer |
| Others |
Pricing and Supply Chain Analysis
Polymer resin costs for pack housings transmit directly from petrochemical feedstock markets through three distinct pricing tiers downstream, with medical-grade gel formulations commanding premiums that commodity disposable formats cannot absorb.
Pricing Analysis
Bundled cold wrap systems with compression garments and unbundled standalone gel packs split the pricing architecture across institutional procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical devices from retail pharmacy formats and bulk athletic sideline packs. Price differentiation stems from ISO 13485 certification status and volume procurement scale through group purchasing organizations. Pricing pressure intensifies in commodity disposable segments as polymer input volatility squeezes manufacturer margins. Home users exhibit highest price sensitivity, while orthopedic surgery centers prioritize outcome guarantees over unit cost.
Supply Chain Analysis
Polymer resin supply rests on petrochemical production clusters in China, South Korea, and Germany, with specialty gel formulation expertise concentrated in Japanese and German chemical processors. Raw material dependencies span polyethylene and PVC housings, cross-linked aqueous gel polymers, and phase-change thermal compounds. Single-source vulnerability in East Asian polymer suppliers creates exposure to logistics disruptions and tariff friction. Distribution runs through hospital group purchasing organizations, medical supply distributors, and direct-to-consumer subscription platforms serving divergent end-user archetypes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Class IIa classification requirements for therapeutic cold devices operate as a regulatory compounder, elevating compliance burdens that favor scaled manufacturers with dedicated regulatory affairs capacity.
For Market Incumbents: Anchor market position through ISO 13485 certification maintenance and backward integration into gel polymer formulation to defend against phase-change material substitution threats. Secure multi-year performance contracts with consolidating hospital procurement departments to lock out mid-tier competitors lacking national distribution scale. Prioritize R&D investment in temperature sensor integration for connected cold therapy platforms. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting post-operative home recovery segments where insurance reimbursement gaps create white-space opportunity. Penetrate the chronic pain management application tier through flexible gel formats priced below clinical-grade cold wraps. Establish channel presence through e-commerce platforms before attempting hospital procurement qualification. For Investors and Strategic Acquirers: Consolidation pressure builds where group purchasing organization vendor list compression marginalizes regional suppliers lacking FDA 510(k) clearance portfolios. Long-term viability favors acquisition targets with established reimbursement coding relationships and EU MDR technical documentation already filed. Watch phase-change material patent expirations as inflection indicators for commoditization risk in premium thermal delivery segments.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates hospital procurement qualification for novel temperature-control mechanisms in US acute care networks. |
| CE Marking Under EU MDR | Unlocks statutory reimbursement access in German outpatient rehabilitation centers favoring reusable gel systems. |
| Hospital System Partnership | Secures standardized cold wrap protocol adoption across orthopedic surgery center networks in Texas and Florida. |
| Software Companion Development | Enables remote patient monitoring integration for connected cold therapy devices with mobile health platforms. |
| Reimbursement Strategy | Captures prescription-grade cold wrap demand from post-operative patients seeking at-home rehabilitation tools. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory filings and trade databases. Primary interviews engaged hospital procurement managers, physiotherapy clinic directors, biomedical engineers, and group purchasing organization contract specialists. Secondary sources encompassed FDA 510(k) clearances, EU MDR technical documentation, hospital procurement databases, and customs trade records. Bottom-up product-type segmentation triangulated against top-down regional demand modeling.
Granularity-level framing applied product type, application, end user, and material dimensions at the country level, with reimbursement policy variation captured as a cross-cutting modifier. CAGRs derived from logistic growth curve fitting anchored to statutory insurance policy changes and surgical volume projections. Phase-change material adoption curves and polymer resin price indices fed industry-specific forecast adjustments throughout the modeling period.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR audit timeline delays and polymer supply disruptions. Forecasts reflect assumptions regarding reimbursement coding stability and orthopedic procedure volume trajectories. Reimbursement policy reversals, cryotherapy chamber substitution acceleration, and notified body capacity constraints warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
Reusable Nursing Pads Market
Patient Care Supplies
Stoma Care Market
Patient Care Supplies
Patient Identification Wristbands Market
Patient Care Supplies
US Pressure Ulcer Prevention Market
Patient Care Supplies
Physical Therapy Supplies Market
Patient Care Supplies
Global Incontinence and Ostomy Care Product Market
Patient Care Supplies
Therapy Pillow Market
Patient Care Supplies
Incontinence Care Products Market
Patient Care Supplies
Stretcher Accessories Market
Patient Care Supplies
External Urine Management Products Market
Patient Care Supplies
Asia-Pacific Hospital Supplies Market
Patient Care Supplies
Global Stoma Care/Ostomy Care and Accessories Market
Patient Care Supplies
Global Perineal Care Market
Patient Care Supplies
Air-Assisted Patient Transfer Systems Market
Patient Care Supplies
Shoe Cover Market
Patient Care Supplies
Disposable Incontinence Products (Dips) Market