
 Central Pain Syndrome Management Market | 2026-2036
Central Pain Syndrome Management Market Size, Share, and Industry Trends Forecast 2026-2036
Central Pain Syndrome Management Market Outlook
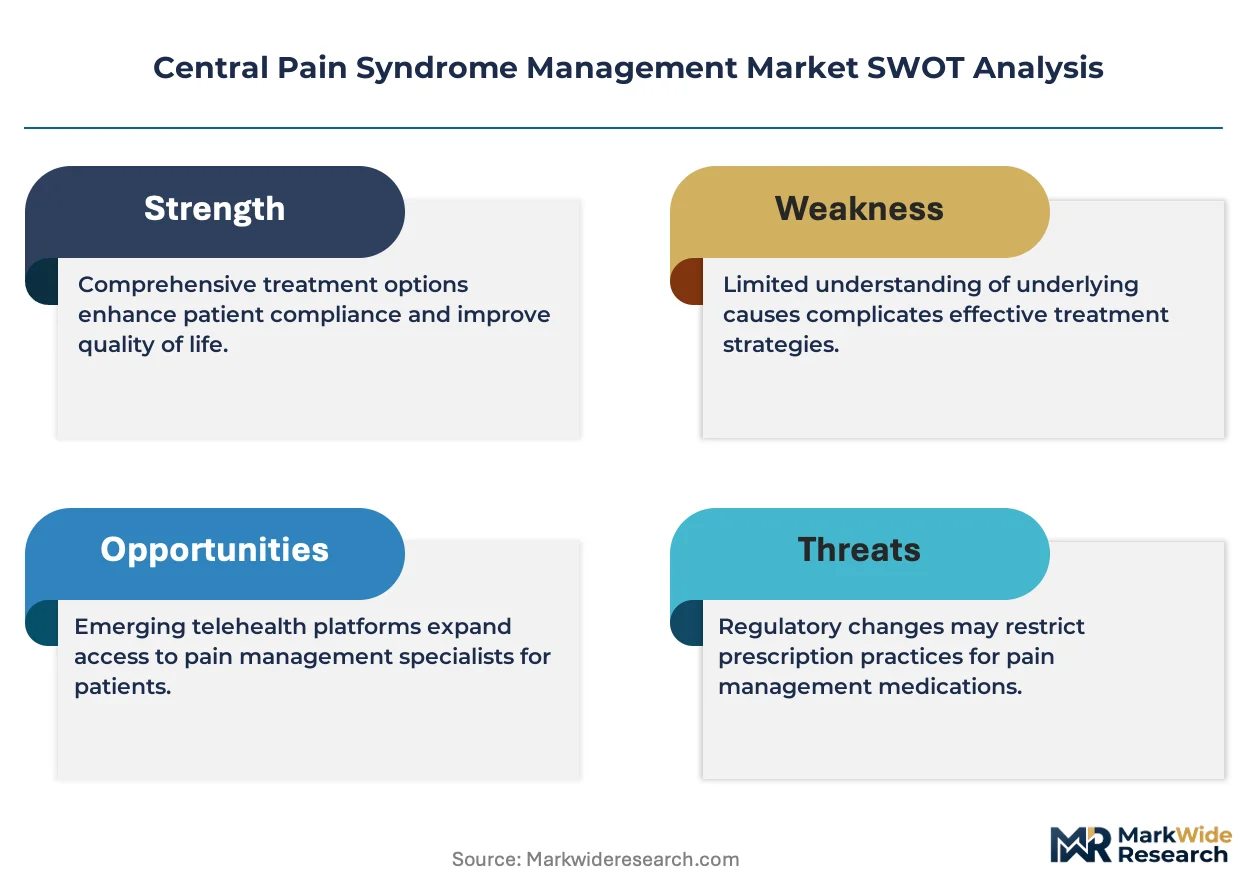
ISO 14155 for clinical investigation of medical devices is reorganizing competitive entry into central pain syndrome management. Medtronic plc leverages decades of spinal cord stimulation expertise to anchor its position in interventional procedures. Boston Scientific Corporation competes through differentiated waveforms and proprietary programming platforms for neuropathic pain.
Central pain syndrome management encompasses pharmacological, interventional, and rehabilitative interventions targeting pathological pain signaling originating from central nervous system lesions or dysfunction, typically involving neurostimulation parameters such as frequency ranges from 2 Hz to 10 kHz and drug delivery concentrations calibrated to blood-brain barrier permeability. Medication retains the largest patient volume but faces margin compression from generic analgesics, while interventional procedures capture premium pricing through device-implant combinations. Neurologic care settings concentrate the most complex case referrals, whereas home healthcare expands fastest as remote programming and wireless monitoring reduce clinic dependency.
The FDA breakthrough therapy designation and EMA's priority medicines scheme create divergent access timelines across the Atlantic, with FDA pathways typically accelerating neuromodulation device reviews by twelve to eighteen months relative to European centralized procedures. The EU Medical Device Regulation imposes stricter clinical evidence requirements on legacy pain devices, forcing manufacturers to retrofit post-market surveillance infrastructure. Stakeholders must monitor reimbursement parity between pharmacologic and interventional modalities as health technology assessments increasingly condition coverage on comparative effectiveness against standard-of-care opioids.
Market Dynamics
ISO 14155 reorganization of clinical investigation standards is compressing competitive entry timelines for neuromodulation devices, forcing manufacturers to restructure trial protocols before market access. This regulatory recalibration favors established players with existing post-market surveillance infrastructure while raising barriers for new entrants.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The pathway accelerates neuromodulation device reviews by twelve to eighteen months relative to European centralized procedures, compressing time-to-revenue for spinal cord stimulation systems.
- Medicare Coverage Determinations:United States reimbursement parity shifts for spinal cord stimulation reshape patient access patterns and expand addressable volumes for interventional procedures.
- Neurology Department Expansion:Tertiary hospitals are establishing dedicated pain management protocols, concentrating complex case referrals and driving demand for implantable neurostimulation systems.
Market Restraints
- EU Medical Device Regulation Strictures:Stricter clinical evidence requirements on legacy pain devices force manufacturers to retrofit post-market surveillance infrastructure, extending compliance timelines.
- Generic Analgesic Compression:Pharmacological segments face margin erosion from commoditized pain medications, constraining R&D reinvestment capacity across oral therapy portfolios.
- Blood-Brain Barrier Permeability Limits:Drug delivery concentration calibration remains technically constrained, restricting efficacy ceilings for central nervous system-targeting pharmacologics.
Strategic Opportunities
- Home Healthcare Expansion:Remote programming and wireless monitoring capabilities reduce clinic dependency, opening ambulatory and residential care channels previously inaccessible to implantable device providers.
- EMA Priority Medicines Scheme Convergence:European accelerated access pathways create parallel regulatory arbitrage opportunities for manufacturers with dual-continent trial strategies.
- Rehabilitative Intervention Integration:Convergence of neurostimulation parameters with physical therapy protocols creates bundled service models spanning 2 Hz to 10 kHz frequency ranges.
Industry Challenges
- Comparative Effectiveness Documentation:Health technology assessments increasingly condition coverage on evidence against standard-of-care opioids, requiring costly head-to-head trial investments.
- Legacy Device Retrofit Burden:Post-market surveillance infrastructure upgrades for existing implantable systems divert engineering resources from next-generation platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central Pain Syndrome Management Market |
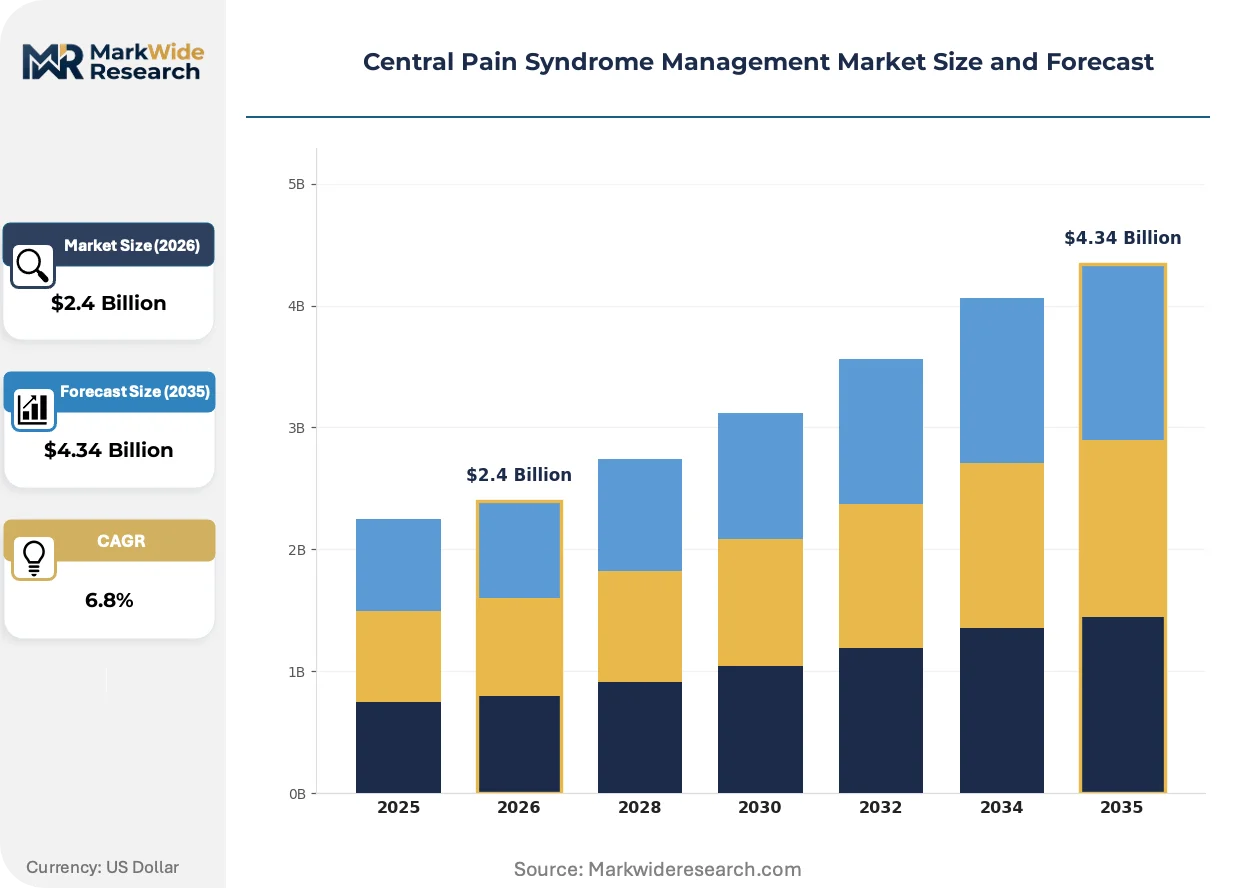
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Medication, Physical Therapy, Psychological Therapy, Interventional Procedures Patient Type: Chronic Pain Patients, Acute Pain Patients, Neuropathic Pain Patients, Post-Surgical Pain Patients Therapeutic Area: Neurology, Pain Management, Rehabilitation, Psychiatry Care Setting: Outpatient Clinics, Hospitals, Home Healthcare, Rehabilitation Centers |
| Companies Covered | Boston Scientific Corporation, Johnson & Johnson, Pfizer Inc., Nevro Corporation, Novartis AG, Eli Lilly and Company, Medtronic plc, Stryker Corporation, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central Pain Syndrome Management Market Strategic Shifts
Neuromodulation parameter customization is fragmenting standardized treatment protocols, with frequency modulation and waveform differentiation emerging as primary vectors of clinical and commercial competition. This shift demands new programming platforms and remote calibration capabilities.
Closed-loop adaptive stimulation systems are decomposing fixed-parameter spinal cord stimulation paradigms. Pain management centers in tertiary hospitals are piloting these responsive platforms for neuropathic pain cohorts. The technology is decomposing the historical distinction between implantation surgery and ongoing clinical management, compressing follow-up revenue cycles while raising upfront device costs.
EMA's priority medicines scheme and FDA breakthrough designation are creating divergent transatlantic access timelines. European centralized procedures lag their American counterparts by twelve to eighteen months for novel neuromodulation therapies. Manufacturers with dual-continent regulatory strategies are sequencing launches to exploit this arbitrage, prioritizing United States commercialization before European market entry.
Service unbundling is disrupting traditional device-implant revenue bundling. Pain management clinics are separating hardware procurement from programming services and remote monitoring subscriptions. United States Medicare reimbursement patterns increasingly recognize these discrete service components, enabling specialized remote monitoring providers to capture value previously retained by device manufacturers.
Central Pain Syndrome Management Market Segmentation
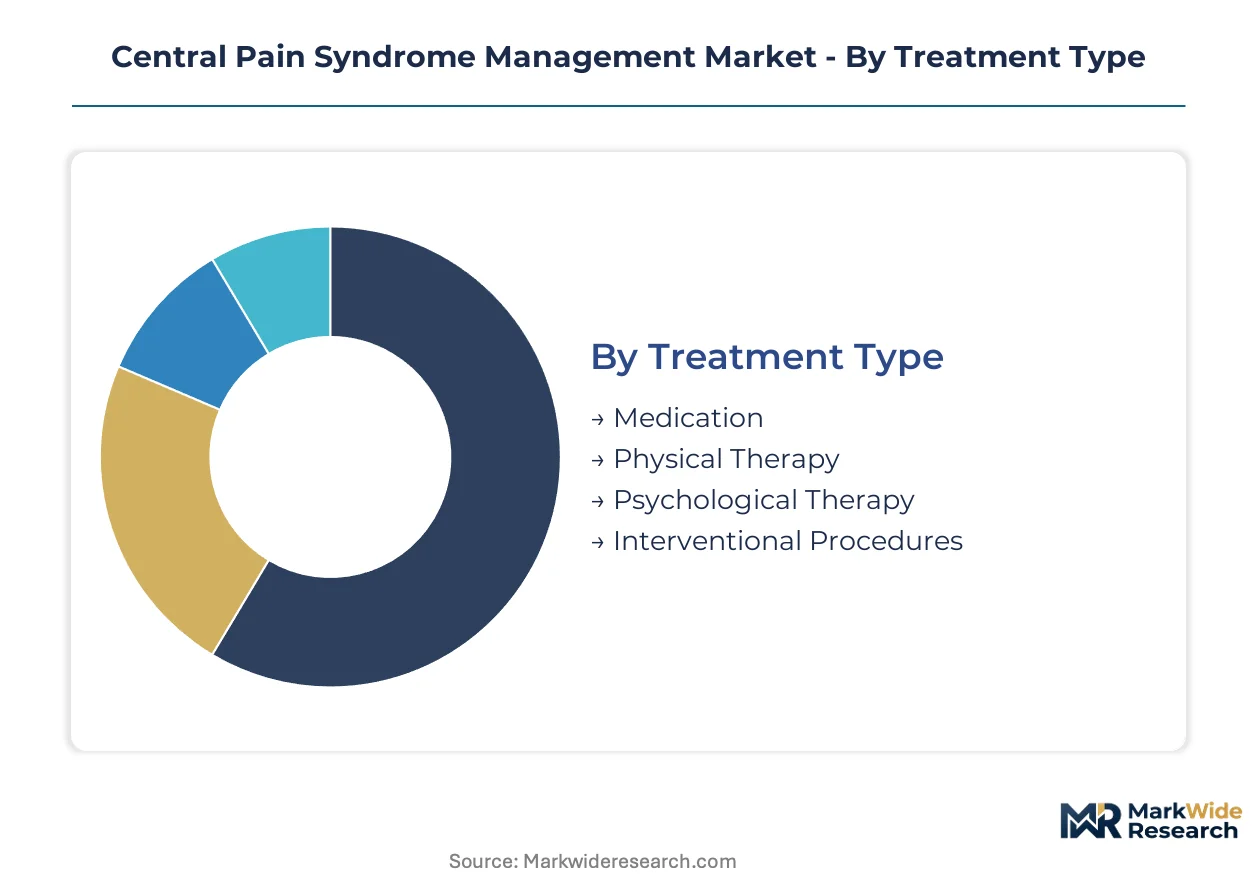
Central pain syndrome management segments fragment across treatment modality, patient acuity, and care delivery site. Substitution pressures from generic pharmacologics and advancing neuromodulation technologies reshape competitive boundaries between categories.
Treatment Type:
Substitution pressure from generic analgesics and device-based alternatives fragments competitive positioning across therapeutic modalities.
- Medication:Oral and parenteral formulations targeting neuropathic pain pathways through sodium channel blockade and GABA modulation. Tertiary hospital formularies concentrate demand for branded anticonvulsants as first-line central pain protocols, though generic gabapentinoids erode pricing power.
- Interventional Procedures:Implantable neurostimulation systems and intrathecal drug delivery requiring surgical placement and parameter programming. United States Medicare coverage determinations for spinal cord stimulation reshape patient access patterns and expand addressable volumes for device-implant combinations.
- Physical Therapy:Neuromuscular re-education and desensitization protocols delivered through specialized rehabilitation protocols.
- Psychological Therapy:Cognitive-behavioral interventions and biofeedback targeting pain catastrophization and central sensitization mechanisms.
Medication anchors the volume base while interventional procedures gain share at the steepest rate.
Patient Type:
Cost tier stratification separates acute episodic management from chronic longitudinal care with divergent reimbursement structures.
- Chronic Pain Patients:Individuals with persistent central pain exceeding three months duration, often following stroke, multiple sclerosis, or spinal cord injury. Neurology departments in tertiary hospitals concentrate the most complex case referrals and drive demand for implantable neurostimulation systems.
- Neuropathic Pain Patients:Cohorts with pain arising from central nervous system lesion or dysfunction, characterized by allodynia and hyperalgesia. FDA breakthrough therapy designation pathways accelerate access to novel neuromodulation therapies for this refractory population.
- Acute Pain Patients:Short-duration central pain presentations requiring immediate intervention and rapid titration protocols.
- Post-Surgical Pain Patients:Central pain syndromes emerging following neurosurgical or orthopedic procedures with iatrogenic nervous system involvement.
Chronic pain patients dominate service utilization while neuropathic pain patients command the highest per-capita expenditure.
Therapeutic Area:
Application concentration in neurological versus rehabilitative settings determines technology adoption speed and device procurement authority.
- Neurology:Specialized practice managing central pain originating from stroke, multiple sclerosis, Parkinson's disease, and other primary neurological conditions. EMA priority medicines scheme and FDA breakthrough designation create divergent transatlantic access timelines for novel therapies.
- Pain Management:Dedicated specialty services integrating pharmacological, interventional, and multimodal approaches for refractory cases. ISO 14155 reorganization of clinical investigation standards compresses competitive entry timelines for neuromodulation devices in these settings.
- Rehabilitation:Functional restoration programs combining physical modalities with adaptive neurostimulation parameter customization.
- Psychiatry:Pain-focused psychiatric services addressing comorbid depression, anxiety, and central sensitization syndromes.
Pain management services capture the highest procedure volume while neurology claims the most complex device placements.
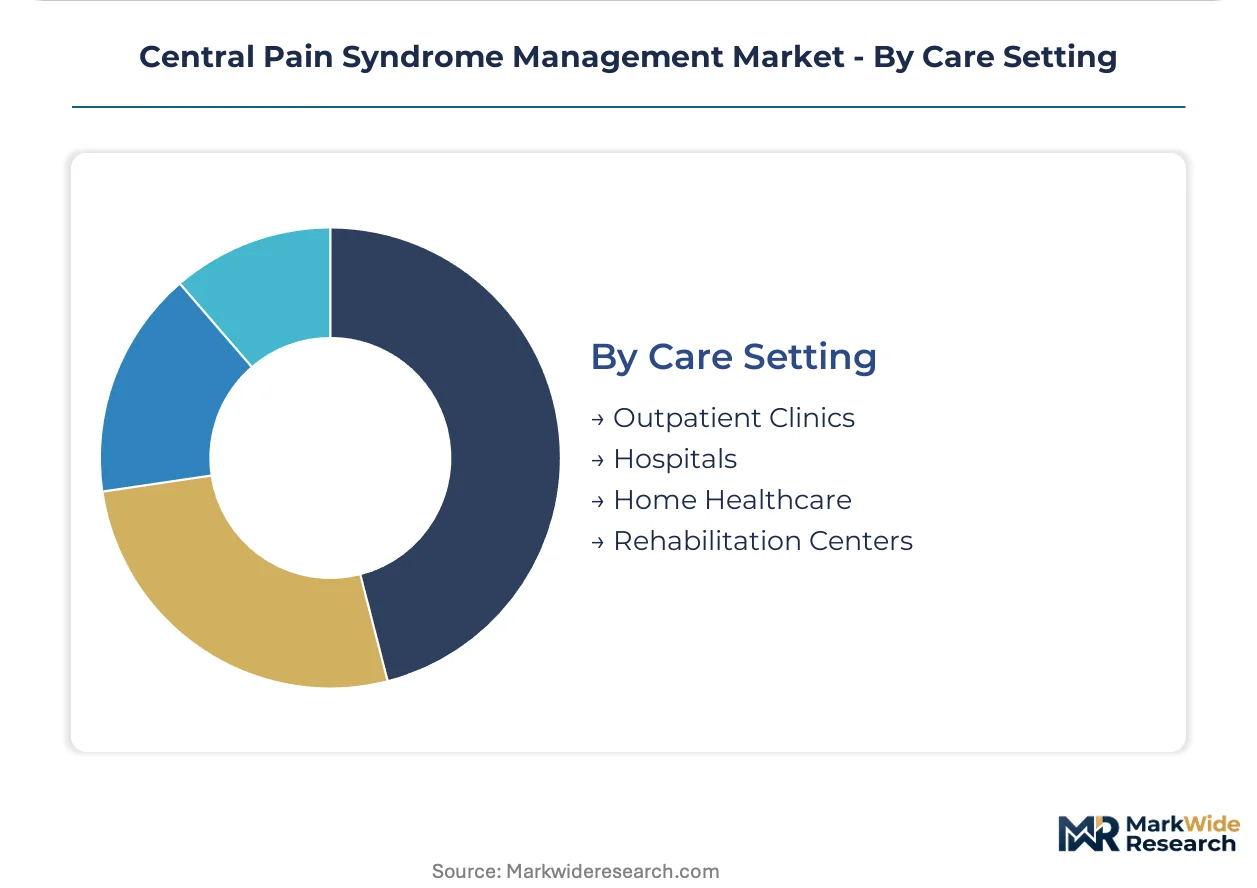
Care Setting:
Customer type stratification separates institutional purchasers from ambulatory and residential channels with distinct procurement workflows.
- Hospitals:Inpatient and outpatient departments performing implantation surgeries, complex medication titration, and acute exacerbation management. Tertiary hospitals are establishing dedicated pain management protocols and expanding dedicated neuromodulation service lines.
- Home Healthcare:Residential delivery of remote programming, wireless monitoring, and nursing support for implanted device patients. Remote programming and wireless monitoring capabilities reduce clinic dependency and open ambulatory channels previously inaccessible to implantable device providers.
- Outpatient Clinics:Ambulatory facilities providing medication management, injection therapies, and non-invasive neuromodulation.
- Rehabilitation Centers:Specialized facilities integrating neurostimulation with physical and occupational therapy protocols.
Hospitals retain the highest absolute revenue while home healthcare expands most quickly as remote capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare coverage determinations for spinal cord stimulation in the United States are reshaping patient access patterns, while EMA's priority medicines scheme and FDA breakthrough designation create twelve-to-eighteen-month divergences in neuromodulation device commercialization timelines across major markets.
United States
Neurology departments in tertiary hospitals are expanding dedicated pain management protocols, concentrating complex central pain case referrals. FDA breakthrough therapy designation accelerates neuromodulation device reviews relative to European procedures. The Cleveland Clinic and Mayo Clinic anchor advanced spinal cord stimulation service lines in Ohio and Minnesota.
Germany
Stricter clinical evidence requirements under EU Medical Device Regulation force manufacturers to retrofit post-market surveillance infrastructure for legacy pain devices. EMA centralized procedures lag FDA pathways for novel neuromodulation therapies. Berlin and Munich host concentration of pain management research centers advancing adaptive stimulation protocols.
Japan
PMDA regulatory frameworks govern spinal cord stimulation device approvals with distinct clinical trial requirements from Western markets. METI industrial policy supports domestic neuromodulation manufacturing capabilities. Tokyo and Osaka medical centers concentrate implantable neurostimulation procedures for refractory neuropathic pain cohorts.
United Kingdom
NICE health technology assessments condition coverage on comparative effectiveness evidence against standard-of-care opioids for interventional pain procedures. MHRA post-Brexit regulatory pathways diverge from EU MDR harmonization timelines. London teaching hospitals and the Oxford-Cambridge corridor concentrate specialized central pain management services.
Switzerland
Swissmedic maintains independent medical device authorization pathways parallel to EU MDR with accelerated review options for breakthrough neuromodulation technologies. Pricing and reimbursement negotiations occur at cantonal level, creating regional access variation. Zurich and Geneva academic medical centers anchor complex pain intervention referral networks.
Central Pain Syndrome Management Market Competitive Environment
Player mix skews toward diversified medical technology conglomerates with neuromodulation divisions alongside specialized neurostimulation pure-plays. Market structure concentrates around established spinal cord stimulation platforms with decades of clinical data accumulation. Three archetypes dominate: integrated device-implant service providers, waveform differentiation specialists, and pharmaceutical-neuromodulation hybrid portfolios. Competitive dynamics center on M&A activity targeting closed-loop adaptive stimulation capabilities and strategic partnerships bundling hardware procurement with remote monitoring subscriptions.
Within the integrated medical technology tier, Medtronic plc and Boston Scientific Corporation anchor positions through spinal cord stimulation expertise and differentiated waveform platforms respectively. Abbott Laboratories occupies a position spanning both neuromodulation devices and pharmaceutical pain management portfolios. Nevro Corporation exemplifies the specialized neurostimulation pure-play archetype with concentrated focus on high-frequency spinal cord stimulation parameters.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Johnson & Johnson |
| Pfizer Inc. |
| Nevro Corporation |
| Novartis AG |
| Eli Lilly and Company |
| Medtronic plc |
| Stryker Corporation |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Generic gabapentinoid substitution for branded anticonvulsants is compressing pharmacological margins while simultaneously shifting procurement geography toward Indian and Chinese API manufacturers, creating divergent cost structures across the Atlantic. This substitution dynamic forces device manufacturers to recalibrate implantable system pricing against commoditized oral therapy benchmarks.
Pricing Analysis
Certification level (FDA breakthrough versus CE-marked standard) creates the primary spread between premium neuromodulation systems and economy-tier alternatives. Three-tier pricing structure across premium, standard, and economy levels anchors implantable device portfolios, with waveform customization and closed-loop capabilities commanding substantial uplifts. Cost compression in the medication tier stems from patent cliff erosion of branded anticonvulsants. Hospital purchasing committees exhibit acute price sensitivity for oral therapies, while tertiary neurology departments prioritize clinical outcomes over device acquisition costs.
Supply Chain Analysis
Port congestion on trans-Pacific lanes elevates inbound logistics costs for electrode arrays and pulse generators sourced from Asian contract manufacturers. Component manufacturing concentrates in Malaysia, Costa Rica, and Ireland, with sterile packaging operations tethered to final assembly sites. Raw material dependencies span platinum-iridium alloys for electrodes, medical-grade silicone for insulation, and lithium-ion cells for implantable power sources. Single-source vulnerability in high-frequency waveform chipsets threatens production continuity. Distribution runs through specialized medical device distributors with GPO contracts to hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Central pain syndrome management demands substitution defense against non-invasive neuromodulation alternatives and digital therapeutics that threaten to displace implantable hardware. Incumbents must fortify positions before these substitutes achieve clinical validation.
For Market Incumbents: Compound defensive moats through backward integration into electrode manufacturing and captive supply of proprietary waveform chipsets. Secure GPO contract exclusivity with tertiary hospital systems before non-invasive alternatives gain FDA clearance. The threat of transcutaneous electrical nerve stimulation systems with closed-loop capabilities demands preemptive channel control. For New Entrants and Emerging Players: Anchor in home healthcare channels where remote programming capabilities reduce incumbent field service advantages. Target neuropathic pain patients with refractory symptoms who have exhausted pharmacological options. The white space in wireless monitoring subscriptions offers recurring revenue models detached from capital-intensive implant manufacturing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed neuromodulation pure-plays that have plateaued at sub-scale revenue and require platform expansion capital. The five-to-ten-year viability window hinges on adaptive stimulation algorithm differentiation. Watch FDA breakthrough therapy designations for closed-loop systems as the inflection signal for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Pathway | Accelerates review timelines for closed-loop adaptive stimulation systems by twelve to eighteen months. |
| CE Marking Pathway | EU MDR compliance demands retrofitted post-market surveillance infrastructure for legacy device portfolios. |
| Hospital System Partnership | Tertiary neurology departments concentrate complex referrals and anchor high-volume implantation service lines. |
| Software Companion Development | Remote programming platforms reduce clinic dependency and open ambulatory revenue channels. |
| Reimbursement Strategy | Medicare coverage determinations for spinal cord stimulation reshape patient access patterns and addressable volumes. |
Study Parameters
Desk research of FDA 510(k) filings, CMS Medicare coverage determinations, and ClinicalTrials.gov registries preceded structured interviews with spinal cord stimulation program directors, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from EMA centralized procedure databases and ISO 14155 guidance documents. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Variance decomposition across treatment modality, patient acuity tier, and care delivery site structured the analytical framework over the projection horizon. Segmentation dimensions modeled encompass medication class, device parameter range, implantation site, and regional regulatory cluster. CAGRs derived from logistic diffusion curves for neuromodulation adoption spliced with pricing elasticity assumptions for generic substitution. Forecast inputs incorporated Medicare coverage expansion scenarios and EU MDR compliance cost pass-through estimates.
Material uncertainties — regulatory delays for adaptive stimulation systems, reimbursement denials for expanded indications, and supply chain disruptions in semiconductor components — sit outside the modeled envelope. Forecasts reflect documented assumptions about clinician adoption rates and payer acceptance thresholds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Opioid Withdrawal Management Market
Pain Management
Chronic Pain Treatment Market
Pain Management
Global Visceral Pain Treatment Market
Pain Management
Muscle Tension Dysphonia Treatment Market
Pain Management
Cancer Pain Market
Pain Management
Pain Management Software Market
Pain Management
Global Pain Management Market
Pain Management
Intravenous (IV) Ibuprofen Market
Pain Management
Cancer Pain Management Market
Pain Management
Global Non-Opioid Pain Patch Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Pain Management Therapeutics Market
Pain Management
Bone Pain Treatment Market
Pain Management
Visceral Pain Market
Pain Management
Pain Patches Market
Pain Management
Global Analgesic Infusion Pumps Market