
 Pain Therapeutic Injectables Market | 2026-2036
Pain Therapeutic Injectables Market Size, Share, and Industry Trends Forecast 2026-2036
Pain Therapeutic Injectables Market Analytics
Home care settings are realigning the end-use mix for pain therapeutic injectables as post-acute pathways shift away from institutional recovery. Pfizer Inc. leverages its manufacturing scale to supply prefilled syringe formats for ambulatory environments. Johnson & Johnson anchors its position through R&D intensity in non-opioid analgesic platforms. Teva Pharmaceutical Industries Ltd. competes on cost-engineered generic injectables for hospital formularies.
Pain therapeutic injectables comprise sterile parenteral formulations—encompassing small-molecule analgesics, corticosteroid suspensions, local anesthetic solutions, and biologic protein preparations—delivered via intravenous, subcutaneous, intramuscular, or intra-articular routes to achieve rapid, dose-precise pain control in acute and chronic settings. Biologics command expanding margin pools as monoclonal antibody therapies for neuropathic and cancer pain indications gain prescriber acceptance. Subcutaneous delivery modes are growing fastest among delivery modes, driven by patient-administered auto-injector designs that reduce nursing dependency.
FDA bioequivalence standards and EMA Good Manufacturing Practice guidelines shape product approval timelines and facility certification requirements for sterile injectable production. The EPA regulates pharmaceutical wastewater discharge from active pharmaceutical ingredient synthesis, raising compliance costs for corticosteroid and anesthetic compound manufacturers. Stakeholders must monitor evolving pharmacovigilance reporting obligations for biologic agents while calibrating capacity investments across prefilled and vial-presented formats.
Market Dynamics
Hospital systems are dismantling their reliance on opioid-based protocols under intensifying FDA scrutiny, redirecting capital toward interventional pain management suites and same-day surgical recovery infrastructure. This structural pivot is compressing formulary windows for traditional analgesics while expanding procurement bandwidth for sterile injectable alternatives.
Growth Catalysts
- Opioid-sparing mandates:The FDA's tightened post-market surveillance of extended-release opioid formulations is compelling health systems to prioritize non-opioid parenteral alternatives in perioperative pathways.
- Auto-injector platforms:Patient-administered subcutaneous delivery systems are reducing nursing dependency in ambulatory settings and expanding addressable care sites beyond traditional infusion centers.
- Biologic acceptance:Monoclonal antibody therapies for neuropathic and cancer pain indications are gaining prescriber confidence, opening margin pools previously captured by small-molecule analgesics.
Market Restraints
- Sterile manufacturing concentration:Aseptic fill-finish capacity for complex biologic injectables concentrates among a limited supplier base in the United States and Western Europe, creating bottleneck risk.
- API cost volatility:Corticosteroid active pharmaceutical ingredient synthesis faces feedstock price instability tied to petroleum-derived precursor markets.
- Bioequivalence barriers:FDA requirements for complex generic injectables extend approval timelines for follow-on products, preserving incumbent pricing power.
Strategic Opportunities
- Home care penetration:Post-acute pathways shifting away from institutional recovery create whitespace for prefilled syringe formats designed for patient self-administration outside clinical settings.
- EMA regulatory alignment:Convergence between FDA and EMA Good Manufacturing Practice guidelines for sterile injectables enables synchronized facility certification across dual jurisdictions.
- Combination therapy convergence:Fixed-dose local anesthetic-corticosteroid suspensions paired with sustained-release platforms are opening new indication categories in chronic joint pain management.
Industry Challenges
- Aseptic technician scarcity:Qualified personnel for sterile fill-finish operations remain concentrated among legacy pharmaceutical manufacturing hubs, constraining greenfield facility ramp rates.
- Legacy system integration:Enterprise resource planning platforms at mid-sized hospital systems require costly retrofitting to accommodate auto-injector inventory tracking and cold-chain monitoring protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pain Therapeutic Injectables Market |
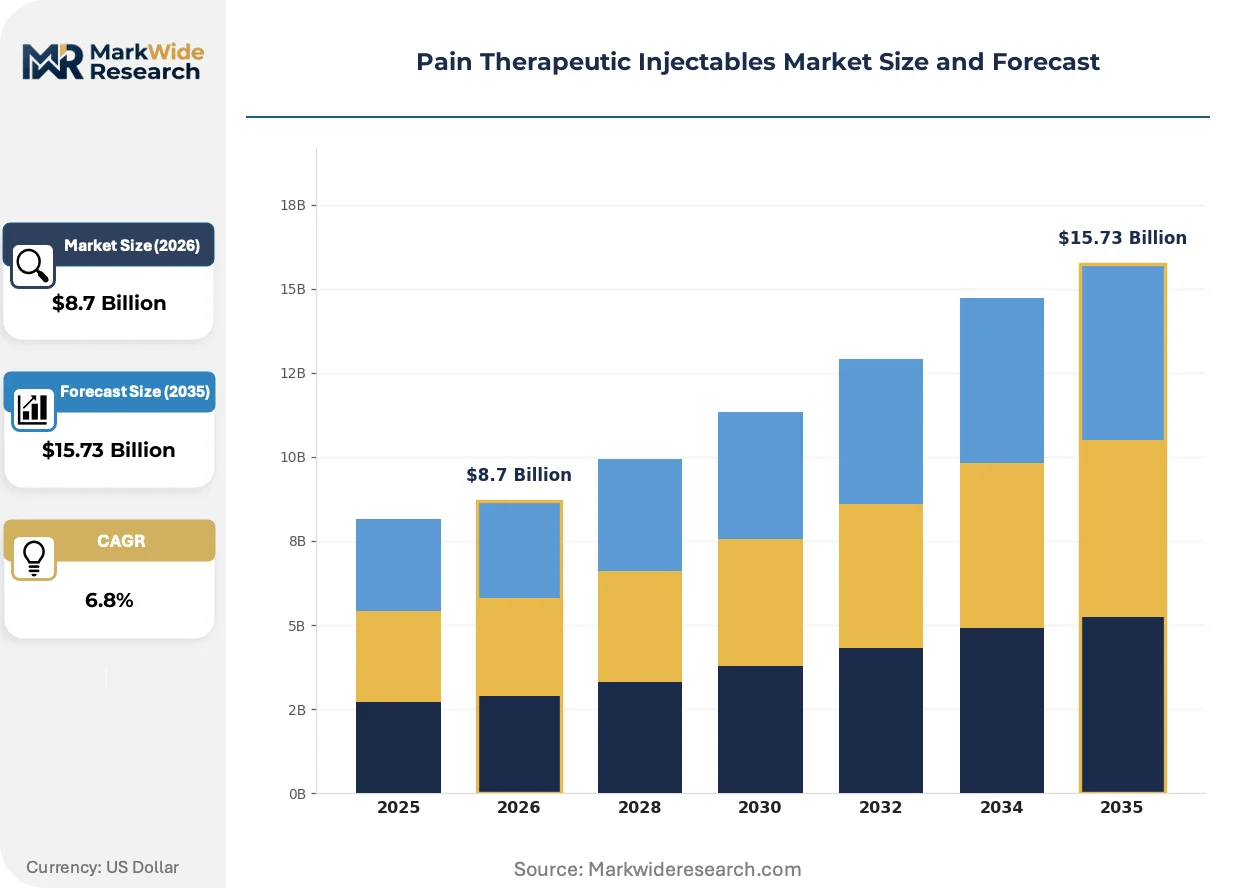
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Corticosteroids, Local Anesthetics, Biologics Therapy Area: Chronic Pain, Acute Pain, Neuropathic Pain, Cancer Pain Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Intra-articular End User: Hospitals, Clinics, Home Care, Pain Management Centers |
| Companies Covered | Pfizer Inc., Johnson & Johnson, Novartis AG, GSK plc, Abbott Laboratories, Inc., Teva Pharmaceutical Industries Ltd., Sanofi S.A., Bayer AG, Endo Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pain Therapeutic Injectables Market Evolving Landscape
Injectable pain therapeutics are undergoing platform-level redesign as delivery technology, regulatory frameworks, and care site economics converge. Three distinct vectors are compressing development cycles and redrawing competitive boundaries.
Prefilled syringe and auto-injector systems are modularizing the traditional infusion center model into distributed, patient-managed administration. Ambulatory surgery centers and home health agencies are adopting these platforms fastest, collapsing the geographic radius between dispensing and dosing. This modularization is enabling same-day discharge protocols that were previously constrained by nursing supervision requirements.
EMA's evolving pharmacovigilance reporting obligations for biologic agents are extending post-approval surveillance burdens onto manufacturers. Companies must now maintain active risk management systems across multiple member state jurisdictions. Biologic protein preparations for neuropathic pain are absorbing the greatest compliance cost increases, with sponsors consolidating regulatory affairs functions in Dublin and Amsterdam to maintain proximity to agency headquarters.
Hospital procurement committees are unbundling analgesic purchasing from bundled surgical payment contracts, creating direct contracting opportunities for injectable manufacturers. Group purchasing organizations are losing leverage as individual health systems negotiate preference-based tiering for opioid-sparing protocols. This behavioral shift is most visible in United States integrated delivery networks, where pharmacy and therapeutics committees now hold independent capital allocation authority previously centralized in supply chain executives.
Pain Therapeutic Injectables Market Segmentation
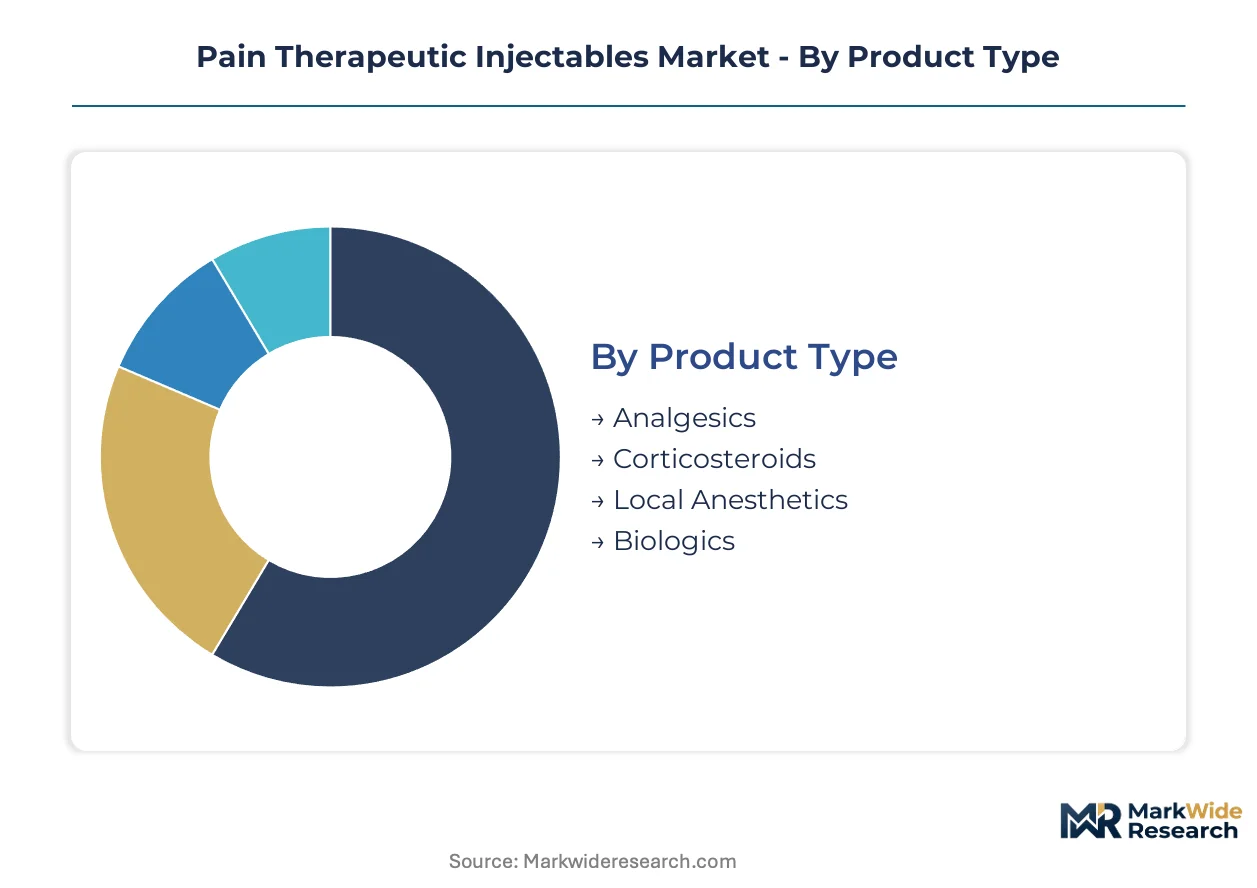
Pain therapeutic injectables fragment across four distinct category axes, each reshaping procurement logic and margin capture. Product type determines manufacturing complexity and regulatory pathway. Therapy area dictates reimbursement intensity and prescriber specialty. Delivery mode controls site-of-care economics. End user concentration shifts capital allocation across institutional and ambulatory channels.
Product Type:
Formulation chemistry and manufacturing sophistication separate winners from margin-erosion zones.
- Analgesics:Small-molecule opioid and non-opioid parenteral formulations dominate hospital formularies through rapid onset and established billing codes. United States health systems prioritize these for same-day surgical recovery protocols under FDA opioid-sparing mandates.
- Biologics:Monoclonal antibody and protein preparations command premium positioning for refractory neuropathic and cancer pain. EMA pharmacovigilance obligations extend post-approval surveillance burdens, consolidating regulatory affairs functions in Dublin and Amsterdam.
- Corticosteroids:Suspension formulations for intra-articular and periarticular injection address chronic joint pain flares.
- Local Anesthetics:Injectable solutions and liposomal preparations enable regional anesthesia and postoperative pain blocks.
Biologics leads on scale; subcutaneous auto-injector formats lead on momentum.
Therapy Area:
Clinical endpoint severity and reimbursement tiering concentrate R&D investment and commercial deployment.
- Acute Pain:Perioperative and trauma-related indications drive volume through hospital procurement committees. United States integrated delivery networks unbundle analgesic purchasing from bundled surgical payments, creating direct contracting opportunities for sterile injectable manufacturers.
- Neuropathic Pain:Complex regional pain syndrome and diabetic neuropathy indications absorb the greatest biologic compliance cost increases. EMA evolving reporting obligations for biologic agents concentrate sponsor investment in risk management systems.
- Chronic Pain:Long-duration management protocols favor depot formulations and sustained-release platforms.
- Cancer Pain:Palliative care pathways and breakthrough pain episodes require rapid-onset parenteral options.
Acute Pain commands procurement volume; Neuropathic Pain climbs the fastest on biologic acceptance.
Delivery Mode:
Route of administration determines site-of-care flexibility and nursing dependency.
- Subcutaneous:Patient-administered auto-injector designs collapse the geographic radius between dispensing and dosing. Ambulatory surgery centers and home health agencies adopt these platforms fastest, enabling same-day discharge protocols previously constrained by nursing supervision.
- Intravenous:Hospital infusion center administration retains dominance for acute perioperative control and patient-controlled analgesia pumps. Legacy enterprise resource planning platforms at mid-sized hospital systems require costly retrofitting to accommodate inventory tracking and cold-chain monitoring.
- Intramuscular:Depot formulations and emergency analgesia rely on this established route.
- Intra-articular:Direct joint space delivery of corticosteroid suspensions addresses localized inflammatory pain.
Intravenous retains installed base dominance; Subcutaneous gains share fastest on home care penetration.
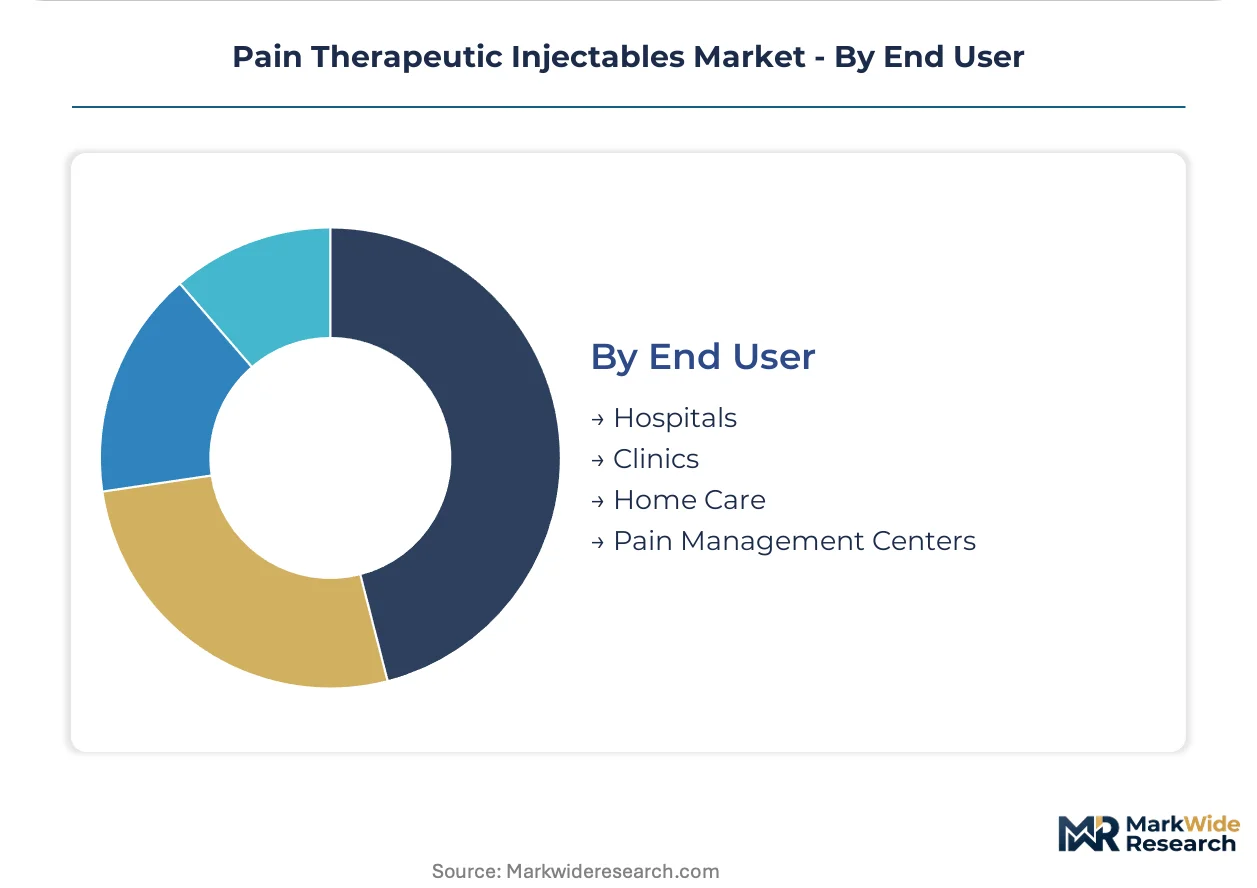
End User:
Capital intensity and care site economics fragment demand across institutional and distributed settings.
- Hospitals:Interventional pain management suites and same-day surgical recovery infrastructure absorb the bulk of capital redirection from opioid-based protocols. FDA tightened post-market surveillance of extended-release opioids compresses formulary windows for traditional analgesics.
- Home Care:Post-acute pathways shifting away from institutional recovery create whitespace for prefilled syringe formats designed for patient self-administration. Pfizer leverages manufacturing scale to supply these ambulatory environments.
- Clinics:Outpatient procedural sites favor rapid-turnover injectable formats.
- Pain Management Centers:Specialty interventional practices concentrate advanced delivery technique and combination therapy protocols.
Hospitals anchor procurement volume; Home Care shows steepest expansion trajectory on pathway redesign.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting sterile injectable manufacturing toward jurisdictions with streamlined aseptic certification pathways, as FDA and EMA compliance costs widen the cost-of-production gap between established and emerging production hubs.
United States
Hospital systems in the United States are dismantling opioid-dependent protocols under intensified FDA post-market surveillance, redirecting capital toward interventional pain management suites. The FDA's tightened scrutiny of extended-release opioid formulations compresses formulary windows for traditional analgesics. Manufacturing clusters in New Jersey and North Carolina concentrate prefilled syringe capacity for ambulatory surgery center supply.
Germany
German hospital procurement committees are unbundling analgesic purchasing from bundled surgical payment contracts, creating direct contracting opportunities for sterile injectable manufacturers. EMA Good Manufacturing Practice guidelines for sterile injectables shape facility certification requirements across the Rhineland industrial corridor. The Frankfurt-Darmstadt biopharma cluster anchors regulatory affairs functions serving dual FDA-EMA jurisdictions.
Switzerland
Swissmedic oversight of biologic protein preparations concentrates high-value manufacturing in the Basel-Zurich corridor amid EMA pharmacovigilance convergence. Swiss facilities absorb compliance cost increases for monoclonal antibody therapies through proximity to European regulatory headquarters. The Lake Geneva region hosts specialized aseptic fill-finish operations for neuropathic pain indications.
India
CDSCO approval pathways for complex generic injectables attract cost-engineered production for hospital formularies serving price-sensitive acute pain segments. Indian manufacturers leverage API synthesis capabilities in Hyderabad and Ahmedabad to supply corticosteroid suspension feedstocks. The Mumbai-Pune pharmaceutical belt concentrates sterile injectable export capacity targeting Middle East and African markets.
Japan
PMDA quality standards for biologic agents sustain premium positioning for monoclonal antibody therapies in cancer pain palliation. Japanese health technology assessment protocols favor patient-administered subcutaneous auto-injectors reducing nursing dependency. The Kansai region around Osaka anchors legacy sterile manufacturing infrastructure serving domestic and Asia-Pacific export demand.
Pain Therapeutic Injectables Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers race to secure aseptic fill-finish capabilities for biologic injectables. The market structure concentrates among multinational pharmaceutical conglomerates with integrated sterile manufacturing footprints, mid-sized generic specialists competing on cost-engineered hospital formularies, and emerging biotech platforms developing monoclonal antibody therapies. Strategic archetypes include scale-driven prefilled syringe suppliers, regulatory-affairs-heavy biologic sponsors, and API-backward-integrated generic houses. M&A activity and geographic diversification into dual-jurisdiction certification facilities represent the dominant competitive vectors.
Among scale-driven pharmaceutical conglomerates, Pfizer Inc. and Johnson & Johnson occupy positions exemplifying manufacturing breadth and R&D intensity respectively, while Teva Pharmaceutical Industries Ltd. represents the cost-engineered generic archetype serving hospital formulary procurement.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| Novartis AG |
| GSK plc |
| Abbott Laboratories, Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi S.A. |
| Bayer AG |
| Endo Pharmaceuticals Inc. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up sterile manufacturing specialists have consolidated aseptic fill-finish capacity across the New Jersey and North Carolina corridors, tightening pricing discipline on biologic injectables while feeding cost compression into generic analgesic tiers.
Pricing Analysis
Distributor margins on prefilled syringe formats absorb the greatest compression as hospital procurement committees unbundle analgesic purchasing from bundled surgical contracts. Three-tier pricing structure across premium biologics, standard small-molecule injectables, and economy generic vials stratifies according to FDA bioequivalence certification tier and manufacturing complexity. Pricing pressure stems from CDSCO-approved complex generic entrants serving price-sensitive acute pain segments. Group purchasing organizations exhibit highest price sensitivity; integrated delivery networks with independent pharmacy and therapeutics committees demonstrate lowest.
Supply Chain Analysis
API synthesis for corticosteroid suspensions rests on petroleum-derived precursor markets concentrated in the United States, India, and China. Hyderabad and Ahmedabad facilities supply corticosteroid feedstocks; the Mumbai-Pune belt concentrates sterile injectable export capacity. Single-source vulnerability concentrates in legacy aseptic technician pools across legacy pharmaceutical manufacturing hubs. Distribution runs through hospital procurement committees, ambulatory surgery center direct contracts, and home health agency channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pain therapeutic injectables rests on two structural levers: patient-administered auto-injector formats capturing premium ambulatory pricing, and cost-engineered generic production rationalizing hospital formulary procurement.
For Market Incumbents: Hedge against CDSCO-sourced generic erosion by securing dual-jurisdiction FDA-EMA facility certification and consolidating regulatory affairs functions in Dublin or Amsterdam. Deepen backward integration into API synthesis for corticosteroid precursors to buffer petroleum feedstock volatility. Prioritize aseptic fill-finish capacity additions in the Rhineland corridor to maintain proximity to EMA headquarters. For New Entrants and Emerging Players: Launch via direct-to-hospital contracting models targeting United States integrated delivery networks that have unbundled analgesic purchasing from supply chain executives. Penetrate home care settings fastest through patient-administered subcutaneous auto-injector designs reducing nursing dependency. Target neuropathic pain biologics where EMA pharmacovigilance obligations have consolidated sponsor investment and created whitespace for nimble regulatory affairs platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized generic sterile injectable houses with API-backward integration and CDSCO approval pathways serving price-sensitive acute pain segments. Long-term viability centers on facilities capable of dual-jurisdiction certification and biologic protein preparation capacity. Watch FDA post-market surveillance intensity on extended-release opioids as the inflection signal for non-opioid parenteral alternative demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Jurisdiction Facility Certification | Synchronized FDA-EMA Good Manufacturing Practice compliance enables margin capture across United States and European hospital procurement. |
| Auto-Injector Platform Development | Patient-administered subcutaneous designs collapse nursing dependency and expand addressable care sites beyond infusion centers. |
| API Backward Integration | In-house corticosteroid precursor synthesis buffers petroleum feedstock price volatility constraining generic manufacturers. |
| Regulatory Affairs Consolidation | Proximity to EMA headquarters in Dublin or Amsterdam reduces pharmacovigilance compliance burdens for biologic protein preparations. |
| Direct Hospital Contracting | Unbundled analgesic purchasing at United States integrated delivery networks creates preference-based tiering opportunities outside group purchasing organization leverage. |
Research Methodology
Multiple input streams — formulary director interviews, hospital procurement manager surveys, and regulatory affairs lead consultations — were reconciled against FDA filings, EMA submission databases, ClinicalTrials.gov records, and hospital procurement contract repositories. Secondary validation drew from SEC 10-K disclosures of sterile injectable manufacturers and customs trade data on API precursor flows. Bottom-up patient-volume modeling and top-down pharmaceutical spending allocation were triangulated to constrain estimate variance.
Historical volume trajectories were cross-referenced against expert panel inputs on opioid-sparing mandate implementation timing and biologic acceptance curves. Segmentation dimensions across the modeling period included product type, therapy area, delivery mode, end-user channel, and regional regulatory cluster. CAGRs were derived from slope-consistency checks against acute pain procedure volumes and ambulatory surgery center expansion rates. Forecast inputs incorporated aseptic fill-finish capacity utilization rates and EMA pharmacovigilance cost absorption assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt FDA opioid policy reversals or sustained petroleum feedstock price spikes. Forecasts reflect documented assumptions on auto-injector adoption velocity and hospital unbundling progression. A small set of triggers — CDSCO generic approval acceleration, Swissmedic biologic manufacturing guidance shifts, and United States integrated delivery network consolidation waves — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Pain Therapeutic Solutions Market
Pain Management
Global Pain Management Market
Pain Management
Opioid Induced Side Effects Treatment Market
Pain Management
Bone Pain Treatment Market
Pain Management
Topical Pain Relief Market
Pain Management
Pain Management Devices Market
Pain Management
Global Morphine Market
Pain Management
Plantar Fasciitis Treatment Market
Pain Management
Intravenous (IV) Ibuprofen Market
Pain Management
Postoperative Pain Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Axial Spondyloarthritis Management Market
Pain Management
Cluster Headache Market
Pain Management
Global Non-Opioid Pain Patch Market
Pain Management
Medical Morphine Market
Pain Management
Erythromelalgia Treatment Market