
 Chronic Pain Treatment Market | 2026-2036
Chronic Pain Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Pain Treatment Market Analysis
Buyer concentration among hospital systems is decoupling from traditional outpatient clinic procurement as homecare and rehabilitation centers fragment demand across decentralized settings. Pfizer Inc. leverages its neuromodulation portfolio to sustain leadership in implantable pain devices. Abbott Laboratories anchors its position through spinal cord stimulation systems that compete directly with Medtronic PLC's neuromodulation franchise. Eli Lilly and Company differentiates via biologic pain pathways while Novartis AG specializes in antiepileptic pain management compounds.
Chronic pain treatment encompasses pharmacological, interventional, and neuromodulatory therapies targeting persistent nociceptive and neuropathic pain lasting beyond normal tissue healing time, typically three to six months. The field employs opioid and non-opioid analgesics, antidepressants with noradrenergic reuptake inhibition, voltage-gated calcium channel modulators, and implantable electrical stimulation devices designed to interrupt pain signal transmission. Analgesics occupy the largest revenue pool among product types though antiepileptics demonstrate the fastest structural growth as prescribers shift from opioid dependency. Neuropathic pain leads therapy area demand while transdermal delivery modes capture expanding homecare share due to patient compliance advantages over injection and intrathecal routes.
The FDA enforces REMS protocols for extended-release opioids while the EMA monitors abuse-deterrent formulation standards through centralized marketing authorization procedures. Japan's PMDA evaluates novel neuromodulation devices under accelerated review pathways for unmet pain indications. Stakeholders must monitor evolving reimbursement thresholds for non-opioid alternatives across Medicare, national health systems, and private payers as clinical evidence requirements tighten for interventional therapies.
Market Dynamics
The FDA's Risk Evaluation and Mitigation Strategy for extended-release opioids has triggered a wholesale reallocation of prescribing authority toward non-opioid alternatives, fragmenting historical revenue concentration among analgesic categories and implantable device manufacturers.
Growth Catalysts
- Japan's PMDA accelerated review pathways:Neuromodulation devices for unmet pain indications gain market access timelines compressed versus standard PMA routes, incentivizing device sponsors to prioritize Japanese submissions.
- Homecare settings:Transdermal delivery systems capture patient compliance advantages over intrathecal and injection routes, expanding addressable populations beyond hospital-bound cohorts.
- Medicare reimbursement thresholds:Expanded coverage for spinal cord stimulation and peripheral nerve field stimulation procedures reduces out-of-pocket burdens for Medicare-eligible chronic pain patients.
Market Restraints
- Active pharmaceutical ingredient concentration:Opioid analgesic manufacturing depends on concentrated Indian and Chinese API suppliers, exposing formulation sponsors to import inspection volatility and geopolitical friction.
- EMA abuse-deterrent formulation standards:Centralized marketing authorization procedures impose bioequivalence and tamper-resistance testing burdens that extend development timelines for oral extended-release products.
- Implantable device battery chemistry:Lithium-ion cell supply constraints and raw material price volatility compress neuromodulation device margins and extend order-to-delivery cycles.
Strategic Opportunities
- Germany's statutory health insurance digitization:Telehealth-integrated pain management programs receive preferential reimbursement coding, creating channel access for remote patient monitoring vendors.
- Biologic-neuromodulation convergence:Combined anti-nerve growth factor antibody and dorsal root ganglion stimulation protocols address mixed nociceptive-neuropathic pain phenotypes currently underserved by monotherapy.
- United States IRA price negotiation provisions:Selected Medicare Part D analgesics face inflation-adjusted rebate obligations, redirecting R&D investment toward device and biologic categories exempt from price controls.
Industry Challenges
- Interventional pain physician training pipelines:Fellowship positions in pain medicine fail to match procedural volume growth, creating access bottlenecks for spinal cord stimulation and intrathecal pump placements.
- CE marking transition under EU MDR:Legacy neuromodulation devices require renewed clinical evidence and notified body engagement, straining regulatory affairs bandwidth across European portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Pain Treatment Market |
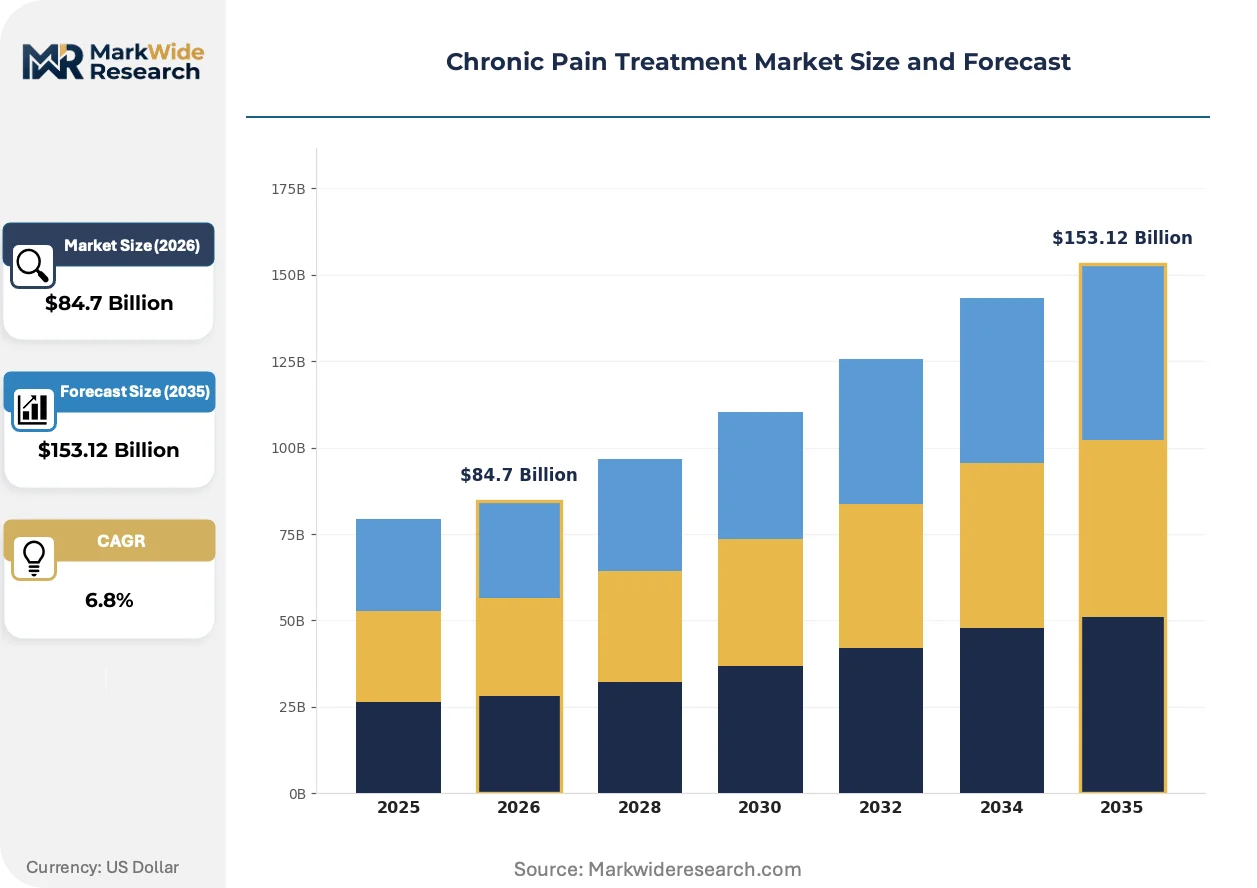
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $153.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Antidepressants, Antiepileptics, Topical Treatments Therapy Area: Neuropathic Pain, Fibromyalgia, Arthritis, Osteoporosis Delivery Mode: Oral, Injection, Transdermal, Intrathecal End User: Hospitals, Clinics, Homecare, Rehabilitation Centers |
| Companies Covered | Pfizer Inc., Abbott Laboratories, Novartis AG, Medtronic PLC, Johnson & Johnson, Teva Pharmaceutical Industries Ltd., Becton, Dickinson, and Company, Eli Lilly and Company, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Pain Treatment Market Emerging Trajectories
Closed-loop adaptive stimulation algorithms and patient-controlled dosing interfaces are compressing the gap between pharmacologic and interventional pain management, enabling real-time therapy personalization previously confined to acute care settings.
Closed-loop spinal cord stimulation systems with evoked compound action potential sensing are electrifying the implantable device category. Pain management clinics in the United States and Germany are adopting these platforms at replacement-cycle velocity. The technology is electrifying competitive positioning by collapsing the efficacy gap between tonic and burst stimulation paradigms while reducing programming burden on implanters.
The European Union's Medical Device Regulation (MDR) recast classification rules for active implantable pain devices, elevating clinical evidence requirements for novel neuromodulation indications. Manufacturers now face extended notified body queue times and expanded post-market surveillance obligations. High-frequency spinal cord stimulation systems and dorsal root ganglion leads encounter the most pronounced regulatory friction, with several sponsors withdrawing legacy products rather than pursuing MDR recertification.
Hospital systems are unbundling pain device procurement from bundled procedural payments, shifting toward device-specific value analysis committees. This purchasing pattern displaces traditional surgeon preference item autonomy with centralized supply chain governance. The transformation is most visible in United States integrated delivery networks, where implantable device contracts now span three- to five-year terms with volume commitments and outcomes-based performance guarantees.
Chronic Pain Treatment Market Segmentation
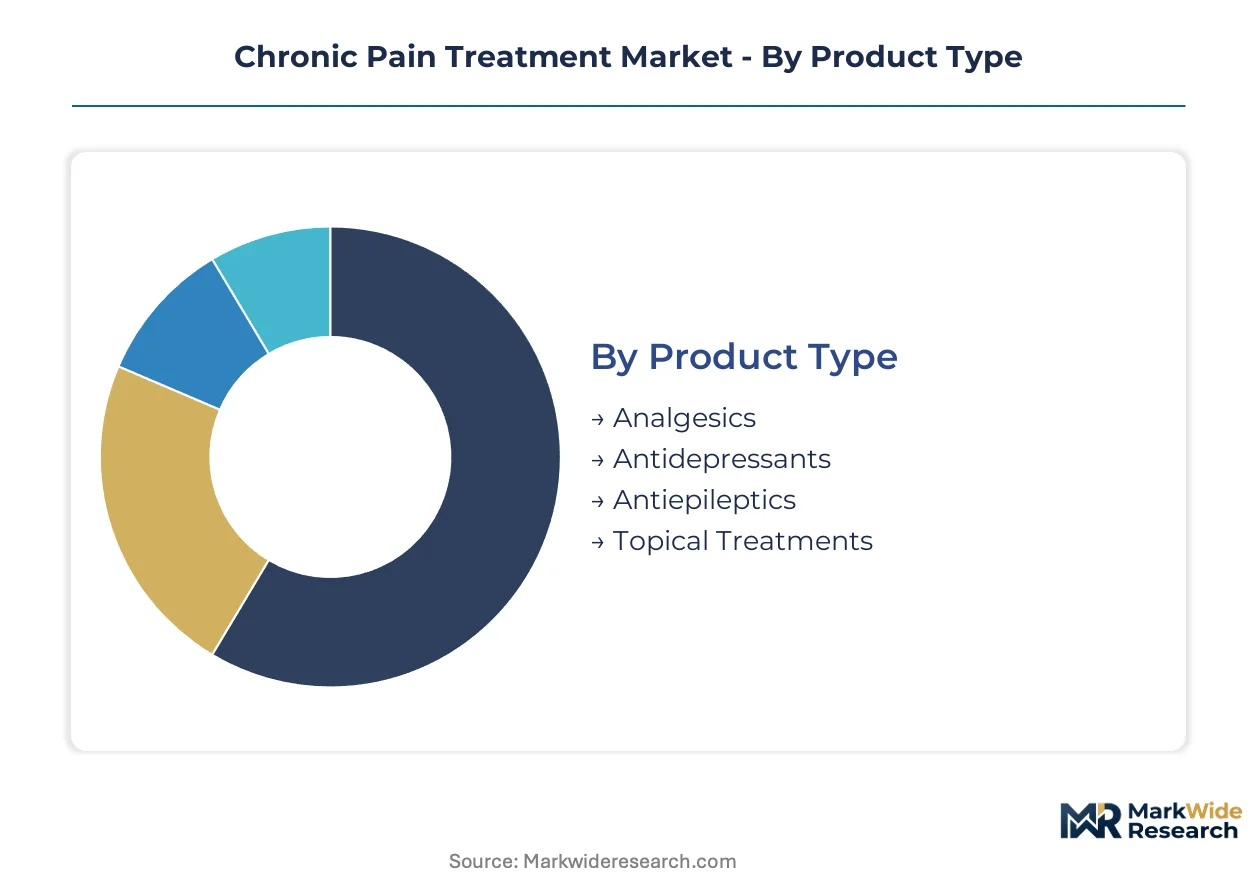
Chronic pain treatment exhibits distinct capital requirements across product categories, with implantable neuromodulation devices demanding heavy R&D infrastructure while oral pharmaceuticals leverage existing manufacturing footprints. Therapy selection increasingly depends on reimbursement pathways and patient compliance profiles rather than clinical efficacy alone.
Product Type:
Capital intensity varies sharply across pharmaceutical and device categories, with analgesic manufacturing requiring API synthesis infrastructure and neuromodulation systems demanding cleanroom assembly and biocompatibility testing facilities.
- Analgesics:Opioid and non-opioid formulations dominate prescription volumes, with extended-release morphine and oxycodone facing FDA REMS compliance costs. Manufacturing concentrates among Indian and Chinese API suppliers, exposing sponsors to import inspection volatility and geopolitical friction.
- Antiepileptics:Pregabalin and gabapentin formulations represent the steepest expansion trajectory as prescribers shift from opioid dependency. Voltage-gated calcium channel modulation offers neuropathic pain efficacy with lower abuse liability, driving formulary preference in United States Medicare Part D plans.
- Antidepressants:Duloxetine and milnacipran target noradrenergic reuptake inhibition for fibromyalgia and chronic musculoskeletal pain.
- Topical Treatments:Lidocaine patches and capsaicin formulations serve localized neuropathic pain with minimal systemic exposure.
Most installed capacity flows through Analgesics. Expansion is steepest in Antiepileptics.
Therapy Area:
Patient volume distribution reflects aging demographics and disease prevalence patterns, with arthritis and osteoporosis tracking closely to Medicare-eligible population growth.
- Neuropathic Pain:Diabetic peripheral neuropathy and post-herpetic neuralgia drive device-eligible patient identification, with spinal cord stimulation candidacy screening expanding in United States pain clinics. Dorsal root ganglion stimulation addresses focal neuropathic phenotypes previously resistant to tonic stimulation paradigms.
- Arthritis:Osteoarthritis and rheumatoid arthritis generate the largest addressable population for oral analgesic and biologic combination therapy, with anti-nerve growth factor antibodies entering late-stage development for moderate-to-severe joint pain.
- Fibromyalgia:Central sensitization syndromes require multimodal pharmacologic approaches with limited interventional options.
- Osteoporosis:Vertebral compression fractures create acute-on-chronic pain episodes treated through kyphoplasty and vertebroplasty alongside pharmacologic bone density management.
Patient identification concentrates in Neuropathic Pain. Therapy development investment is climbing fastest in Arthritis.
Delivery Mode:
Route selection balances bioavailability requirements against patient adherence and healthcare setting constraints, with home-compatible options capturing preference from payers and patients.
- Oral:Immediate and extended-release tablets dominate prescription economics, with abuse-deterrent formulations commanding premium pricing under EMA centralized authorization procedures. Bioequivalence testing burdens extend development timelines for generic sponsors.
- Transdermal:Fentanyl and buprenorphine patches deliver steady plasma concentrations with reduced dosing frequency, expanding homecare adoption among elderly patients with polypharmacy complexity. Patient compliance advantages over injection routes support reimbursement preference in German statutory health insurance.
- Injection:Intramuscular and subcutaneous routes serve acute breakthrough pain and clinical setting administration.
- Intrathecal:Implanted pump systems target refractory pain with programmable morphine and ziconotide delivery, requiring specialized implanter training.
Prescription volume flows predominantly through Oral delivery. Homecare setting compatibility is expanding fastest in Transdermal systems.
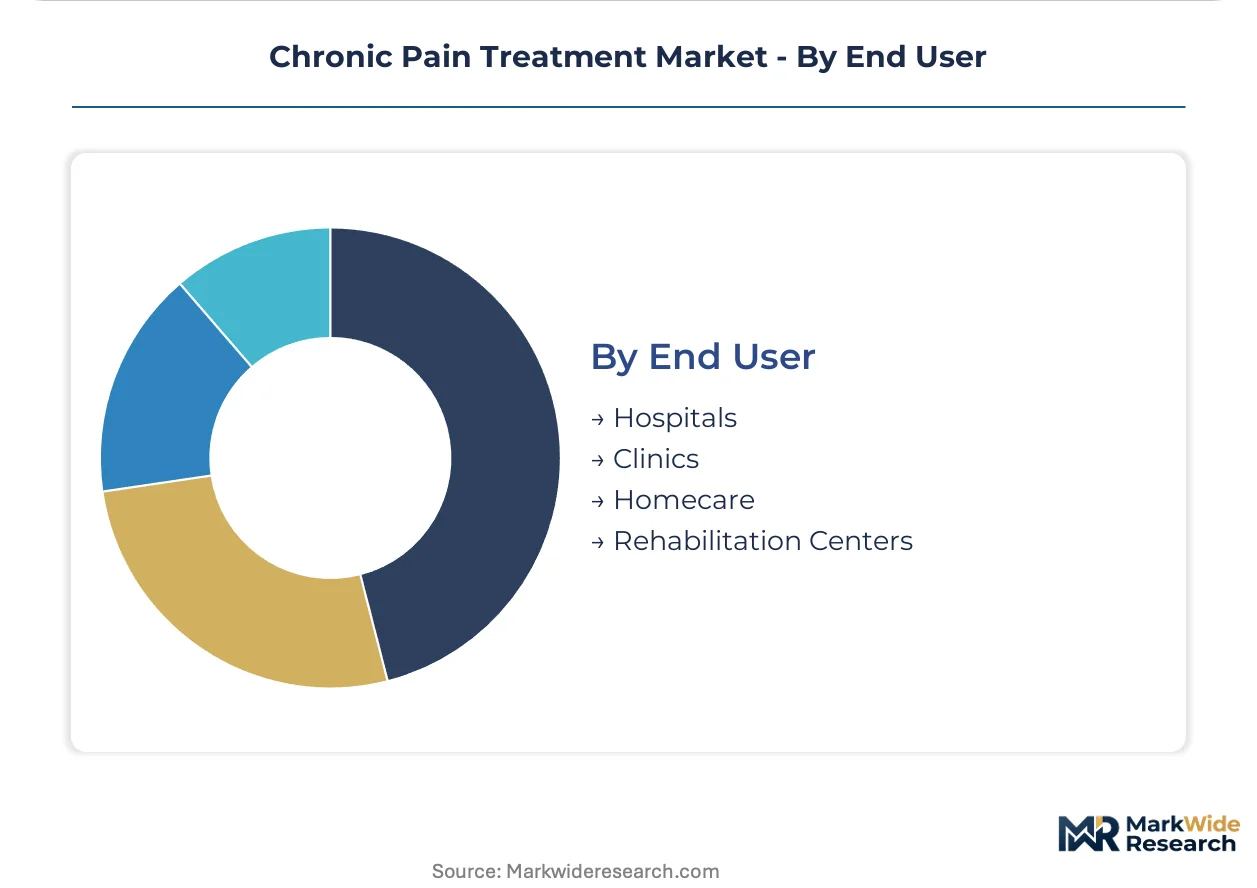
End User:
Procurement authority is fragmenting across institutional and decentralized settings, with value analysis committees displacing traditional surgeon preference autonomy.
- Hospitals:Integrated delivery networks in the United States unbundle device procurement from bundled payments, imposing three- to five-year contracts with volume commitments and outcomes-based performance guarantees. Spinal cord stimulation implantation concentrates in high-volume academic centers.
- Homecare:Transdermal and oral therapies enable patient-managed pain control outside institutional settings, with telehealth-integrated monitoring programs receiving preferential reimbursement coding in Germany. Remote patient monitoring vendors capture channel access through statutory health insurance digitization initiatives.
- Clinics:Outpatient pain medicine practices face fellowship training pipeline constraints limiting procedural growth.
- Rehabilitation Centers:Post-acute settings coordinate multimodal therapy transitions following surgical or interventional procedures.
Device implantation volume concentrates in Hospitals. Service expansion is accelerating fastest in Homecare settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory health insurance digitization outpaces Japan's neuromodulation reimbursement velocity, while the United States maintains the largest installed base of implantable pain devices despite tighter FDA opioid protocols.
United States
Medicare-eligible population expansion and integrated delivery network consolidation drive device procurement centralization. The FDA's REMS protocols for extended-release opioids redirect prescribing toward spinal cord stimulation and peripheral nerve field procedures. Pain medicine fellowship programs in academic medical centers face training pipeline constraints that limit procedural growth.
Germany
Statutory health insurance digitization enables telehealth-integrated pain management reimbursement coding for remote patient monitoring vendors. The country's national pharmaceutical regulator evaluates abuse-deterrent formulations under centralized marketing authorization alignment with EMA standards. Medical device clusters in Baden-Württemberg and North Rhine-Westphalia concentrate neuromodulation manufacturing and notified body engagement capacity.
Japan
Aging demographics exceeding 29% population over 65 years generate neuropathic pain prevalence from diabetic peripheral complications. PMDA accelerated review pathways compress market access timelines for novel neuromodulation devices addressing unmet indications. Tokyo and Osaka metropolitan areas concentrate pain clinic infrastructure and dorsal root ganglion stimulation candidacy screening programs.
United Kingdom
NHS Integrated Care Systems consolidate chronic pain service commissioning across hospital and community settings. The national pharmaceutical regulator maintains alignment with EMA post-Brexit through retained EU law frameworks for device certification. London and Southeast England anchor spinal cord stimulation implantation volume with concentration in high-volume teaching hospitals.
India
Active pharmaceutical ingredient synthesis infrastructure supplies concentrated opioid and antiepileptic precursors to global formulation sponsors. The country's national pharmaceutical regulator enforces import inspection protocols that expose sponsors to supply volatility and geopolitical friction. Manufacturing clusters in Maharashtra and Gujarat concentrate API production for pregabalin and extended-release morphine intermediates.
Chronic Pain Treatment Market Vendor Landscape
United States producers anchor the pharmaceutical tier; Swiss and Irish specialists hold device manufacturing concentration. The vendor base splits between consolidated implantable neuromodulation systems and fragmented oral analgesic formulation. Three archetypes dominate: diversified pharmaceutical conglomerates with pain portfolios, pure-play neuromodulation device sponsors, and generic API-to-formulation integrators. Competitive moves center on strategic partnerships for closed-loop stimulation algorithms and backward integration into lithium-ion cell supply for implantable power systems.
Among United States-based pharmaceutical conglomerates, Pfizer Inc. and Eli Lilly and Company exemplify the diversified archetype spanning biologic and small-molecule pain pathways. Abbott Laboratories anchors the device-specialist tier alongside Medtronic PLC, with both occupying positions in spinal cord stimulation and dorsal root ganglion lead systems. These three names represent the competitive core around which prescribing authority and procurement contracting consolidate across hospital systems and integrated delivery networks.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Abbott Laboratories |
| Novartis AG |
| Medtronic PLC |
| Johnson & Johnson |
| Teva Pharmaceutical Industries Ltd. |
| Becton, Dickinson, and Company |
| Eli Lilly and Company |
| Boston Scientific Corporation |
| Others |
Supply Flow & Price Mechanics
Closed-loop adaptive stimulation algorithms are compressing device programming costs while concentrating manufacturing expertise among United States and Irish neuromodulation specialists, simultaneously reshaping implantable device economics and API sourcing patterns for oral analgesics.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for pregabalin and gabapentin intermediates. Three-tier pricing structure across premium, standard, and economy levels separates branded extended-release formulations from authorized generics and commodity API-sourced tablets. Price differentiation hinges on FDA REMS compliance certification and abuse-deterrent formulation complexity. Pricing pressure stems from Medicare Part D rebate obligations under IRA provisions, squeezing margins on selected oral analgesics while device categories remain exempt. Hospital procurement committees demonstrate highest price sensitivity through volume-commitment contracting, whereas homecare patients prioritize compliance convenience over unit cost.
Supply Chain Analysis
Regional distribution centers in Maharashtra and Gujarat anchor API warehousing for opioid and antiepileptic precursors before forwarding to formulation plants in the United States and Germany. Manufacturing concentration rests on India and China for active pharmaceutical ingredients, with Ireland and Switzerland specializing in neuromodulation device assembly. Raw material dependencies include lithium-ion cells for implantable power systems, platinum-iridium electrodes for stimulation leads, and concentrated poppy alkaloid streams for morphine synthesis. Single-source vulnerability in Indian API inspection protocols exposes sponsors to import delays and geopolitical friction. Distribution runs through hospital system value analysis committees and German statutory health insurance pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
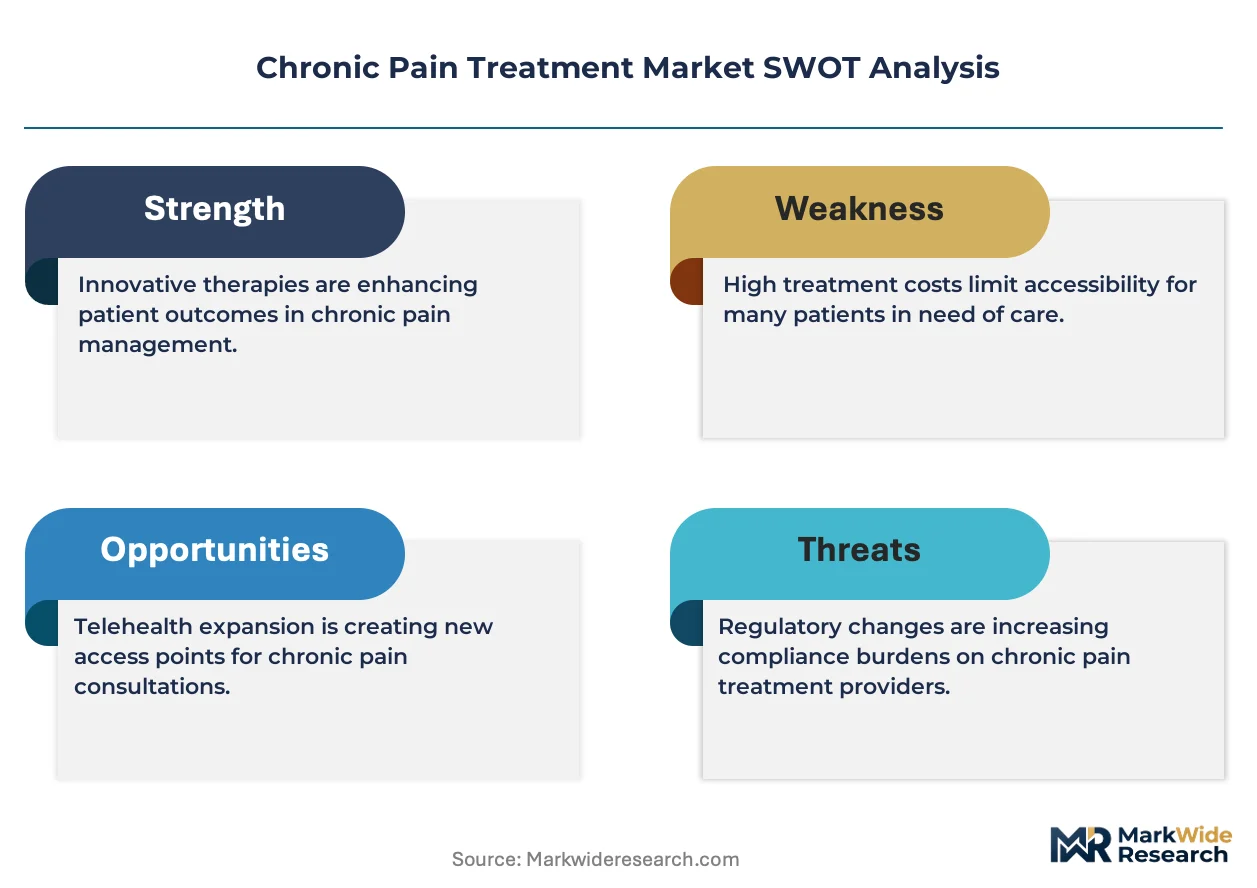
This market functions as a regulatory compounder where FDA REMS protocols for extended-release opioids have permanently reallocated prescribing authority toward device and non-opioid categories.
For Market Incumbents: Deepen backward integration into lithium-ion cell supply to secure implantable device margins against raw material volatility. Fortify positions in closed-loop stimulation algorithms through exclusive licensing arrangements with adaptive sensing technology developers. Prioritize CE marking pathway completion under EU MDR recast rules before legacy device certificates expire, as notified body queue times extend recertification risk. For New Entrants and Emerging Players: Begin with telehealth-integrated pain management platforms targeting German statutory health insurance digitization reimbursement codes. Remote patient monitoring vendors capture channel access through preferential coding for homecare settings, the most penetrable segment given elderly population growth and polypharmacy complexity. Partner with established neuromodulation implanters to bypass fellowship training pipeline constraints limiting procedural volume expansion. For Investors and Strategic Acquirers: Valuations sit cheapest among generic API-to-formulation integrators facing import inspection volatility and geopolitical friction. Long-term viability across the analysis window favors device-specialist sponsors with proprietary closed-loop algorithms and dorsal root ganglion stimulation portfolios. Watch PMDA accelerated review pathway approvals for novel neuromodulation indications as inflection signals for Japanese market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR recast rules elevate clinical evidence requirements for legacy neuromodulation device recertification. |
| Hospital System Partnership | Integrated delivery networks impose three-to-five-year device contracts with outcomes-based performance guarantees. |
| Reimbursement Strategy | Medicare coverage expansion for spinal cord stimulation reduces out-of-pocket burdens for eligible patients. |
| Software Companion Development | Patient-controlled dosing interfaces enable real-time therapy personalization previously confined to acute care. |
| Backward Integration | Captive lithium-ion cell supply secures implantable device margins against raw material price volatility. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged pain medicine fellowship directors, hospital value analysis committee chairs, GPO contracts managers, and formulary directors at United States Medicare Part D plans. Secondary validation drew from FDA REMS program documentation, EMA centralized marketing authorization procedures, PMDA accelerated review pathway decisions, CMS Medicare reimbursement databases, and ClinicalTrials.gov neuromodulation device registrations. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Historical reference periods established baseline prescribing patterns before FDA opioid protocol intensification, with projection horizons extending through device replacement cycles and pharmaceutical patent cliffs. Segmentation dimensions spanned product type, therapy area, delivery mode, and end-user procurement authority, with regional regulatory clusters capturing FDA, EMA, and PMDA jurisdiction differences. CAGRs derived from fitted growth curves applied to Medicare-eligible population expansion and homecare setting penetration rates. Forecast inputs included fellowship training pipeline constraints, notified body queue time projections, and lithium-ion cell supply elasticity assumptions.
Caveats apply where PMDA review timeline compression, EU MDR recast enforcement intensity, or Indian API inspection protocol changes could materially shift the outlook. Forecasts reflect documented assumptions regarding reimbursement threshold stability and geopolitical friction in concentrated supply geographies. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Chronic Lower Back Pain Treatment Market
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
Palliative Care Market
Pain Management
Global Pain Management Market
Pain Management
Axial Spondyloarthritis Management Market
Pain Management
Pain Therapeutic Solutions Market
Pain Management
Visceral Pain Market
Pain Management
Non Opioid Pain Treatment Market
Pain Management
Global Chiropractic Care Market
Pain Management
Central Pain Syndrome Management Market
Pain Management
Cancer Pain Market
Pain Management
Cancer Pain Management Market
Pain Management
Chinese Fibromyalgia Market
Pain Management
Cluster Headache Market
Pain Management
Bone Pain Treatment Market
Pain Management
Spine Pain Market