
 Allergy Skin Test Market | 2026-2036
Allergy Skin Test Market Size, Share, and Industry Trends Forecast 2026-2036
Allergy Skin Test Market Analysis
Point-of-care molecular integration is fragmenting the traditional allergy skin test workflow across clinics and laboratories. Thermo Fisher Scientific leverages its immunoassay platform breadth to sustain dominance in high-throughput laboratory settings. Siemens Healthineers anchors its position through diagnostic imaging and laboratory automation synergies that extend into allergy testing workflows.
Allergy skin tests are diagnostic procedures that expose the skin to controlled allergen concentrations—typically ranging from 1 to 30 common antigens per panel—to elicit localized immune responses measurable as wheal diameter or erythema. These tests serve the primary commercial purpose of identifying specific IgE-mediated sensitivities to guide therapeutic intervention and allergen avoidance strategies. Prick testing occupies the highest volume tier due to its simplicity and rapid turnaround, while molecular diagnostics represents the fastest-expanding segment as multiplexed allergen component testing commands premium pricing. Serum-specific IgE testing captures growing demand from patients unable to undergo direct skin exposure protocols.
The FDA regulates allergy skin test devices and reagents as Class II medical devices requiring 510(k) clearance, while Clinical Laboratory Improvement Amendments govern quality standards for diagnostic laboratories performing these tests. The Centers for Medicare & Medicaid Services reimbursement frameworks directly shape test utilization patterns across hospital and independent laboratory settings. Stakeholders must monitor evolving precision medicine guidelines that increasingly demand component-resolved diagnostics over whole-allergen screening.
Market Dynamics
Diagnostic laboratories are consolidating testing volumes through standardized protocols, while point-of-care molecular platforms fragment the traditional skin prick workflow into decentralized settings.
Growth Catalysts
- Component-Resolved Diagnostics:Multiplexed allergen component testing protocols command premium positioning as clinicians demand precise IgE sensitivity profiles for therapeutic targeting.
- CLIA Laboratory Expansion:The Centers for Medicare & Medicaid Services reimbursement frameworks incentivize high-throughput diagnostic laboratory consolidation across hospital and independent settings.
- Serum-Specific IgE Accessibility:Patients with contraindications to direct skin exposure protocols drive volume toward blood-based alternatives, expanding addressable testing populations.
Market Restraints
- Reagent Supply Concentration:Controlled allergen extract production concentrates among specialized biologics suppliers, creating input vulnerability for test panel manufacturers.
- FDA 510(k) Clearance Timelines:Class II medical device pathways impose extended validation requirements that compress commercialization windows for novel test formats.
- Serum IgE Substitution Pressure:Blood-based diagnostics displace skin prick protocols in pediatric and dermatitis populations where direct allergen exposure carries elevated risk profiles.
Strategic Opportunities
- At-Home Testing Channels:Direct-to-consumer distribution models bypass clinical gatekeepers for preliminary sensitivity screening, capturing wellness-oriented patient segments.
- Precision Medicine Mandates:Evolving clinical guidelines increasingly require component-resolved diagnostics over whole-allergen screening, creating upgrade cycles for existing laboratory infrastructure.
- AI-Assisted Image Analysis:Machine learning algorithms applied to wheal diameter measurement are virtualizing technician interpretation, reducing variability and enabling remote result verification.
Industry Challenges
- Technician Training Shortfalls:Standardized intradermal administration and wheal measurement protocols require specialized competency that outpaces educational program output.
- Interoperability Friction:Laboratory information systems and electronic health record platforms maintain fragmented data exchange standards, complicating result integration into clinical workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allergy Skin Test Market |
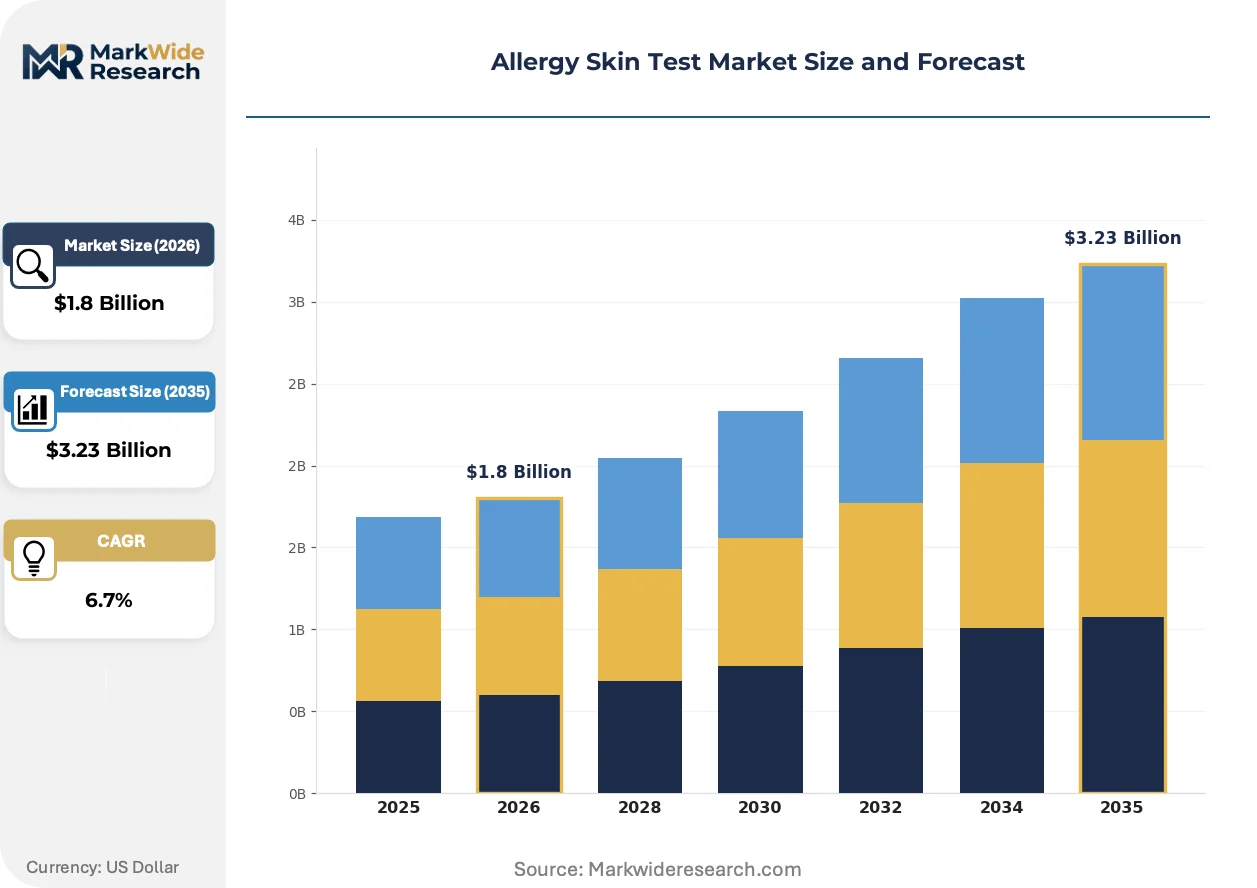
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Prick Test, Intradermal Test, Patch Test, Serum-Specific IgE Test Indication: Food Allergies, Inhalant Allergies, Drug Allergies, Insect Allergies End User: Hospitals, Diagnostic Laboratories, Allergists, Home Care Technology: Immunoassays, Molecular Diagnostics, Skin Test Kits, Microarrays |
| Companies Covered | Thermo Fisher Scientific Inc., Siemens Healthineers AG, Lincoln Diagnostics, Inc., Stallergenès Greer, HYCOR Biomedical, Alk-Abello A/S, Allergy Therapeutics, Chemotechnique MB Diagnostics AB, HAL Allergy B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allergy Skin Test Market Emerging Trajectories
Molecular specificity is displacing crude allergen extracts across diagnostic protocols, while automation compresses manual interpretation steps and digital platforms enable remote result delivery.
Multiplexed microarray platforms simultaneously quantify IgE responses against hundreds of allergen components from minimal serum volumes. Reference laboratories in the United States and Germany are deploying these systems at scale for complex polysensitized patient workups. This capability is virtualizing the sequential single-allergen testing model that dominated historical practice.
The FDA's updated in vitro diagnostic guidance tightens analytical and clinical validation requirements for new allergen-specific IgE assays. Manufacturers must demonstrate reproducibility across multiple laboratory sites and operator conditions prior to 510(k) clearance. High-complexity molecular diagnostic developers face the steepest compliance burden as they navigate expanded predicate device comparisons.
Patient self-referral patterns are compressing traditional primary-care gatekeeper roles in allergy diagnostic access. Direct-to-consumer serum collection kits and telehealth result consultations displace in-person specialist encounters for initial sensitivity screening. This channel shift concentrates in metropolitan United States markets where healthcare consumerism and high-deductible insurance plans intersect.
Allergy Skin Test Market Segmentation
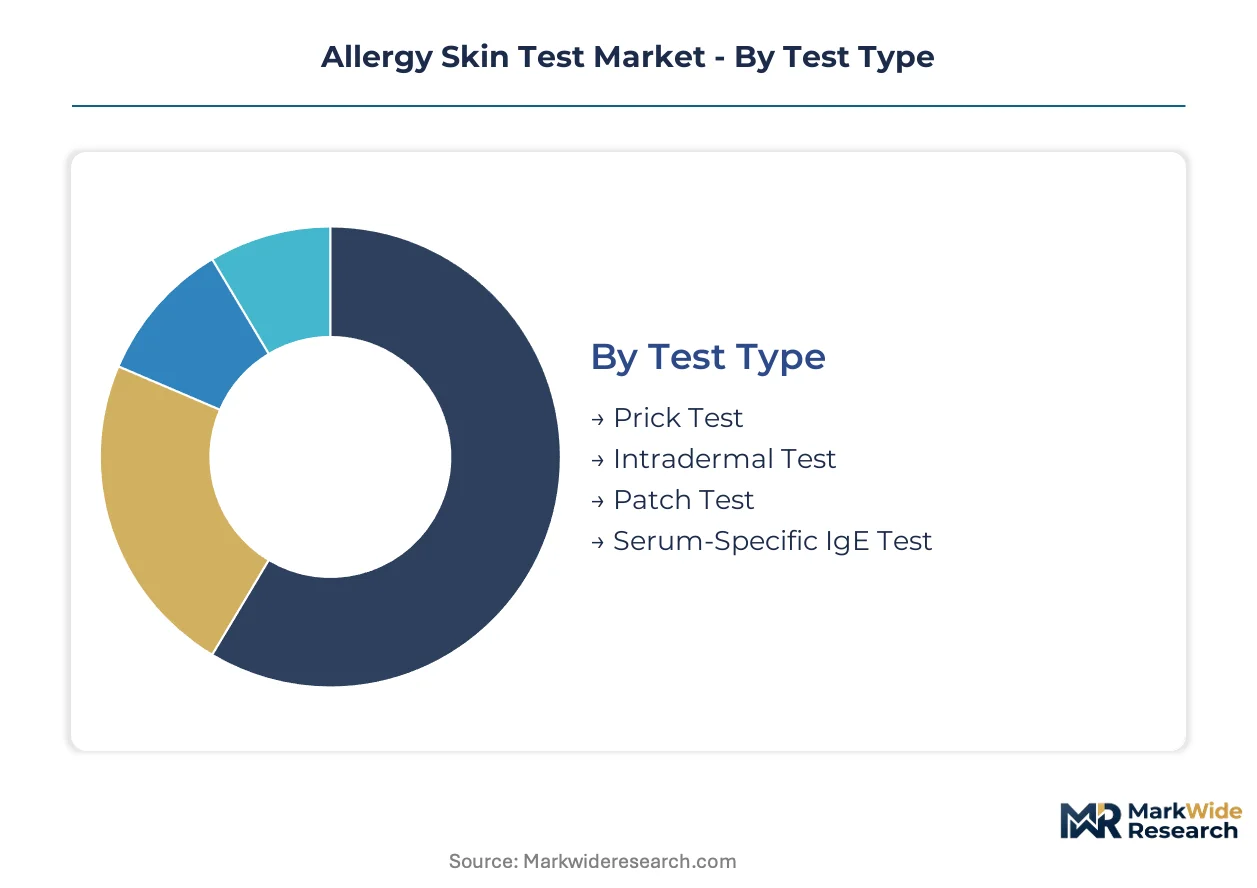
Segmentation in allergy skin testing reveals divergent commercial trajectories across clinical workflows and patient access models. Test format selection determines reimbursement pathways, while technology choices reshape laboratory capital deployment and point-of-care penetration.
Test Type:
Use-case spectrum spans rapid screening protocols to complex serological workups, with each format commanding distinct clinical settings and reimbursement tiers.
- Prick Test:Percutaneous allergen application via lancet or multi-test device produces wheal-and-flare responses within 15–20 minutes. Demand concentrates in allergist offices across the United States, where high patient throughput and immediate result interpretation sustain volume leadership despite technician training requirements.
- Serum-Specific IgE Test:Quantitative immunoassay detection of circulating allergen-specific antibodies eliminates direct skin exposure risks. Pediatric populations and dermatitis patients in Germany and Japan drive fastest adoption as contraindications to skin prick protocols expand addressable testing pools.
- Intradermal Test:Intradermal allergen injection at 0.01–0.05 mL volumes detects lower-sensitivity IgE responses. Venom and penicillin allergy confirmation in hospital settings sustains niche demand.
- Patch Test:48-hour occluded allergen exposure identifies delayed-type hypersensitivity reactions. Contact dermatitis workups in dermatology clinics anchor utilization.
Established volume favors prick testing; emerging adoption favors serum-specific IgE alternatives.
Indication:
Application urgency varies from acute anaphylaxis prevention to chronic rhinitis management, shaping test frequency and panel complexity.
- Inhalant Allergies:Seasonal and perennial aeroallergen sensitivity screening dominates test volumes. Dust mite, pollen, and pet dander panels in United States metropolitan markets sustain recurring demand as environmental exposure patterns shift.
- Food Allergies:Component-resolved diagnostics for peanut, tree nut, and shellfish sensitivities command premium positioning. Pediatric allergy specialists in the United Kingdom and Australia drive fastest expansion as oral food challenge reduction becomes a clinical priority.
- Drug Allergies:Beta-lactam and NSAID hypersensitivity evaluation supports perioperative safety protocols. Hospital-based testing in France and Spain concentrates in anesthesia and surgical departments.
- Insect Allergies:Hymenoptera venom sensitivity assessment guides immunotherapy decisions. Rural and suburban geographies with higher exposure prevalence sustain specialized panel demand.
Respiratory indication captures highest test frequency; food allergy testing climbs the fastest as precision diagnostics penetrate pediatric practice.
End User:
Customer type determines channel economics, with consolidated laboratory purchasing power contrasting fragmented clinic procurement.
- Diagnostic Laboratories:High-throughput reference labs in the United States deploy automated immunoassay platforms for standardized panel processing. CLIA-certified facilities consolidate regional test volumes through centralized extraction and analysis workflows.
- Hospitals:Emergency department and perioperative allergy assessment requires rapid turnaround capabilities. Integrated health systems in Canada and Switzerland favor in-house testing for patient flow optimization.
- Allergists:Specialist practices retain direct skin testing for immediate clinical decision-making. Office-based prick and intradermal protocols sustain reimbursement advantages in fee-for-service markets.
- Home Care:Direct-to-consumer serum collection kits bypass clinical gatekeepers. Wellness-oriented segments in United States metropolitan areas drive channel experimentation despite regulatory uncertainty.
Laboratory consolidation favors diagnostic laboratories; decentralization momentum favors home care channels.
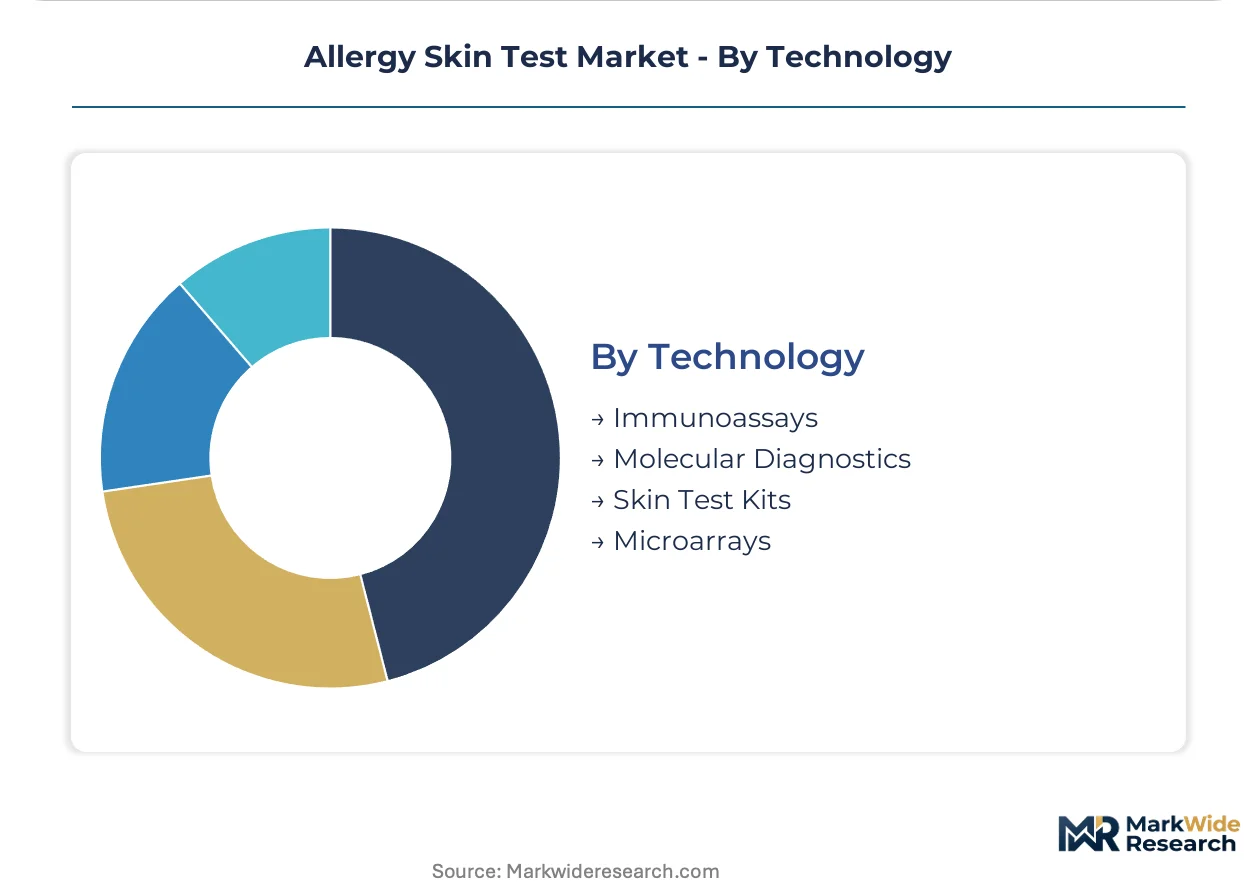
Technology:
Platform maturity spans decades-old extraction methods to emerging multiplexed molecular systems, with capital intensity and regulatory burden varying accordingly.
- Molecular Diagnostics:Multiplexed allergen component testing quantifies IgE against purified recombinant proteins. Reference laboratories in Germany and the United States deploy microarray platforms for complex polysensitized patient characterization.
- Immunoassays:Enzyme-linked and fluorescent detection systems dominate serum-specific IgE quantification. Established reagent ecosystems and FDA-cleared instrument menus sustain broad laboratory adoption.
- Microarrays:Solid-phase allergen chips enable hundreds of simultaneous IgE measurements from sub-milliliter serum samples. Academic medical centers pilot expanded panels for research and complex case resolution.
- Skin Test Kits:Pre-loaded allergen panels and standardized lancet devices streamline office-based administration. Allergist practices in Japan and Italy favor disposable kit formats for inventory simplicity.
Immunoassay infrastructure commands current volume; molecular platforms gain share fastest as precision medicine mandates intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss precision diagnostics exporters supply multiplexed allergen component platforms to reference laboratories across the United States and Japan. Cross-border reagent trade concentrates among specialized biologics suppliers serving CLIA-certified facilities.
United States
Large reference laboratories in Boston and Raleigh-Durham consolidate regional test volumes through automated immunoassay platforms. FDA Class II medical device pathways govern 510(k) clearance timelines for novel allergen-specific IgE assays. The Southeast corridor from Atlanta to Research Triangle Park anchors high-throughput diagnostic laboratory expansion.
Germany
Academic medical centers in Munich and Heidelberg pilot expanded microarray panels for complex polysensitized patient characterization. EMA diagnostic guidance shapes analytical validation requirements for multiplexed allergen component testing. The Baden-Württemberg cluster around Freiburg concentrates recombinant allergen production for European reference laboratories.
Japan
Pediatric allergy specialists in Tokyo and Osaka drive fastest serum-specific IgE adoption as contraindications to skin prick protocols expand. PMDA regulatory frameworks govern in vitro diagnostic registration pathways for imported assay platforms. The Kansai region surrounding Osaka hosts concentrated allergist practice networks retaining direct skin testing workflows.
United Kingdom
Component-resolved diagnostics for peanut and tree nut sensitivities command premium positioning in London and Manchester pediatric practices. NHS reimbursement frameworks directly shape test utilization patterns across hospital and independent laboratory settings. The Cambridge-Oxford corridor anchors molecular diagnostic platform development for allergy component testing.
Australia
Oral food challenge reduction priorities in Sydney and Melbourne pediatric allergy units drive fastest food allergy testing expansion. TGA medical device regulations govern allergen extract and reagent import approvals. The Melbourne biomedical precinct concentrates immunoassay platform deployment for southern hemisphere reference laboratories.
Allergy Skin Test Market Vendor Landscape
On the supply side, the industry is consolidating around diversified life sciences conglomerates and specialized allergen extract manufacturers. Thermo Fisher Scientific leverages immunoassay platform breadth to sustain dominance in high-throughput laboratory settings. Siemens Healthineers anchors position through diagnostic imaging and laboratory automation synergies. Strategic moves concentrate on M&A for molecular diagnostic capabilities and capacity expansion for standardized reagent production.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Siemens Healthineers AG exemplify scale-driven positions spanning reagent, instrument, and software ecosystems. Among specialized allergen-focused developers, Stallergenès Greer and Alk-Abello A/S occupy positions anchored in controlled allergen extract production for both diagnostic and therapeutic applications. Lincoln Diagnostics, Inc. represents the regional instrument and disposable kit fabricator archetype serving office-based allergist workflows.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Siemens Healthineers AG |
| Lincoln Diagnostics, Inc. |
| Stallergenès Greer |
| HYCOR Biomedical |
| Alk-Abello A/S |
| Allergy Therapeutics |
| Chemotechnique MB Diagnostics AB |
| HAL Allergy B.V. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in recombinant allergen production across Germany and the United States tightens supplier pricing power while compressing margins for test panel assemblers. This utilization imbalance forces diagnostic laboratories into longer-term offtake commitments to secure extract supply, embedding cost rigidity into downstream pricing structures.
Pricing Analysis
The technology-generation pricing gap separates legacy immunoassay platforms from next-generation multiplexed microarray systems and prior-generation manual skin prick kits. Three-tier pricing structure across premium, standard, and economy levels stratifies by analytical specificity and automation grade, with FDA-cleared molecular diagnostics commanding certification premiums. Cost compression in standard-tier immunoassays is intensifying because reference laboratories consolidate purchasing volumes. Pediatric allergy specialists exhibit highest price sensitivity due to reimbursement constraints, while academic medical centers demonstrate lowest sensitivity for complex polysensitized case resolution.
Supply Chain Analysis
Contract-manufacturing concentration for recombinant allergen proteins rests with specialized biologics suppliers in Germany, Denmark, and the Netherlands. Controlled allergen extract production draws from birch pollen cultivation in the Baden-Württemberg region, hymenoptera venom harvesting in rural France, and shellfish protein isolation in coastal Spain. Single-source vulnerability concentrates in recombinant Bet v 1 and Phl p 5 component supply. Distribution runs through CLIA-certified reference laboratories and allergist practice networks with direct kit procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
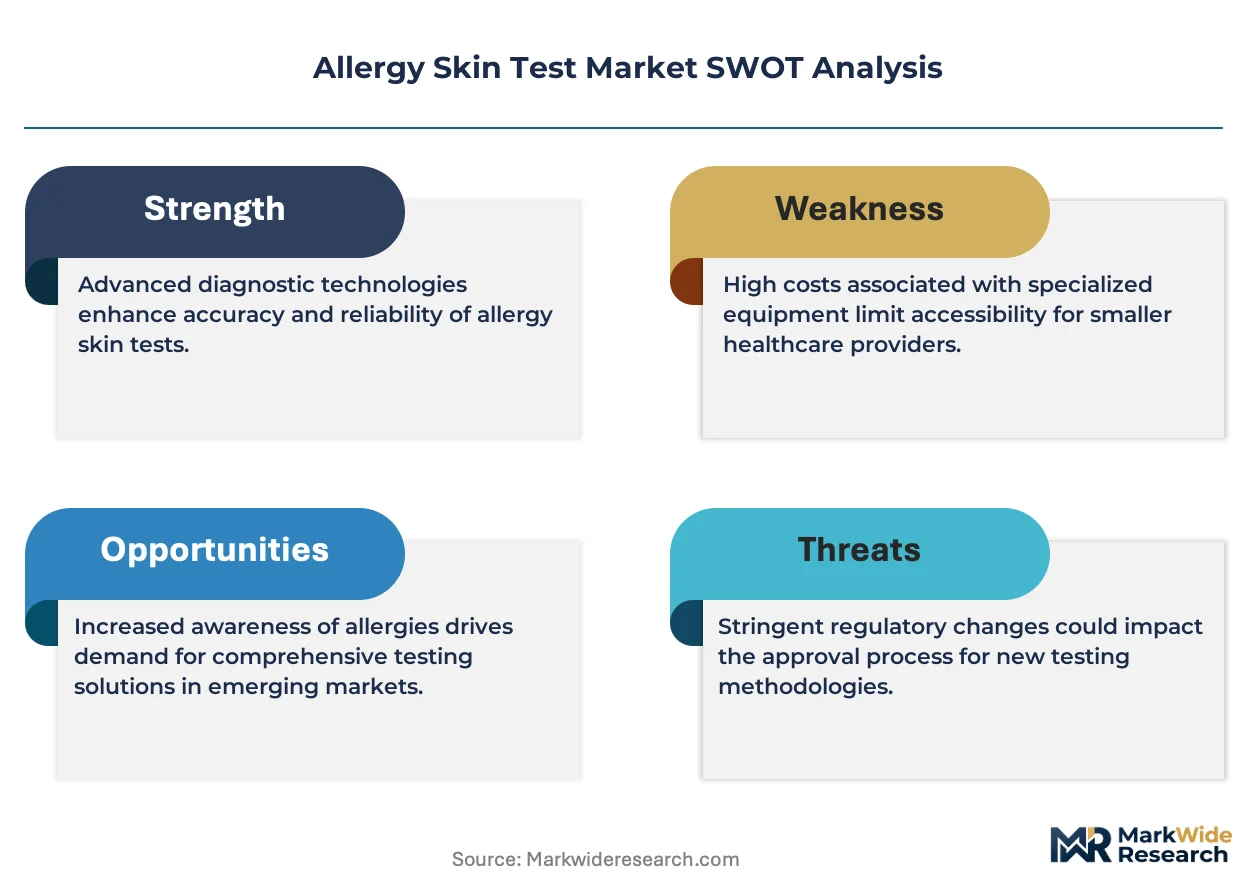
The allergy skin test market is in cyclical recovery driven by deferred diagnostic demand from pandemic-era allergy service backlogs. Normalization of in-person specialist visits and laboratory throughput restoration support volume rebuilding across key geographies.
For Market Incumbents: Build regulatory-data moats through expanded FDA 510(k) predicate libraries and EMA diagnostic dossier accumulation. Incumbents should deepen backward integration into recombinant allergen production to offset extract supply vulnerability, while investing in AI-assisted wheal measurement software to virtualize technician-dependent interpretation steps. Serum-IgE substitution pressure from blood-based diagnostics demands defensive positioning through rapid point-of-care molecular platforms.
For New Entrants and Emerging Players: Pursue direct-to-consumer serum collection channels in United States metropolitan markets where high-deductible insurance plans and healthcare consumerism intersect. White-space targets include at-home preliminary sensitivity screening for wellness-oriented segments and telehealth-integrated result delivery. The most penetrable entry point is component-resolved food allergy testing for pediatric populations, with go-to-market execution through telehealth platform partnerships rather than traditional allergist channel development.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized allergen extract manufacturers with long-term supply contracts to reference laboratories. Long-term viability over the five-to-ten year window favors molecular diagnostic platform developers with multiplexed microarray capabilities. Acquisition target archetypes include CLIA-certified regional laboratories with established payer contracts and recombinant protein production facilities with validated allergen component pipelines. The signal to watch is FDA guidance evolution on in vitro diagnostic analytical validation requirements as inflection indicator for compliance cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Multiplexed Microarray Platform Launch | Enables simultaneous quantification of hundreds of allergen components from minimal serum volumes. |
| Recombinant Allergen Production Scale-Up | Secures controlled extract supply for test panel manufacturers facing input concentration risk. |
| CLIA Laboratory Partnership Network | Consolidates regional test volumes through centralized extraction and analysis workflows. |
| AI-Assisted Image Analysis Development | Virtualizes technician interpretation of wheal diameter measurements for remote result verification. |
| Direct-to-Consumer Channel Establishment | Bypasses clinical gatekeepers for preliminary sensitivity screening in wellness-oriented segments. |
Methodological Framework
A spread of perspectives from diagnostic laboratory directors, allergist practitioners, regulatory affairs specialists, and biomedical procurement managers converged on the working assumptions. Primary interviews with CLIA-certified facility operators and pediatric allergy specialists combined with secondary validation from FDA 510(k) filings, EMA diagnostic guidance documents, CMS reimbursement frameworks, and hospital procurement databases. Bottom-up test volume modeling and top-down market sizing triangulation anchored quantitative outputs.
Demand-supply-balance framing across the analysis window integrated patient referral pattern shifts, laboratory capacity utilization, and reagent supply concentration. Segmentation dimensions modeled include test format, indication category, end-user type, and technology platform tier. CAGRs derived from historical growth trajectory analysis and forward-looking procedure volume projections. Forecast inputs incorporated precision medicine guideline evolution and point-of-care molecular adoption curves.
Sensitivities concentrate around FDA in vitro diagnostic guidance revisions, recombinant allergen production capacity expansion, and serum-IgE substitution rates in pediatric populations. Forecasts reflect documented assumptions on regulatory clearance timelines and reimbursement stability. Quarterly review of CLIA laboratory consolidation activity and component-resolved diagnostic guideline updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Mycological Testing Market
Testing Services
Global C-Reactive Protein Testing Market
Testing Services
Infusion Toxicology Services Market
Testing Services
Global Metabolic Testing Market
Testing Services
STD Testing Devices Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Endocrine Peptides Test Market
Testing Services
Global Electronystagmography Testing Market
Testing Services
Tuberculosis Testing Market
Testing Services
Metabolic Biomarker Testing Market
Testing Services
Global Mosquito Borne Infections Testing Market
Testing Services
Retrovirus Testing Market
Testing Services
Toxicology Drug Screening Market
Testing Services
Hospital Acquired Disease Testing Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
Global HIV Self Test Kits Market