
 Companion Animal Postoperative Pain Management Therapeutics Market | 2026-2036
Companion Animal Postoperative Pain Management Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Companion Animal Postoperative Pain Management Therapeutics Market Analysis
North American manufacturing capacity for companion animal pharmaceuticals is reconfiguring supply dynamics across the sector. Zoetis leverages integrated research-to-distribution infrastructure across multiple therapeutic categories. Merck Animal Health sustains competitive positioning through concentrated investment in biologics and vaccine-adjuvant platforms. Dechra Pharmaceuticals specializes in niche analgesic formulations for exotic and companion species, occupying a defensible premium segment.
Companion animal postoperative pain management therapeutics comprise pharmacological agents designed to modulate nociceptive signaling following surgical intervention in domestic pets, typically formulated for species-specific metabolism with adjusted half-lives and dosing intervals relative to human equivalents. These products serve the primary commercial purpose of reducing perioperative stress, accelerating recovery timelines, and enabling outpatient surgical procedures in veterinary practice. Injectable delivery modes command the dominant share of immediate postoperative applications, while transdermal formulations represent the fastest-expanding category as pet owners seek home-administered alternatives to clinic-based injections. NSAIDs retain the largest volume position across product types, though adjuvant therapies including gabapentinoids and local anesthetics capture disproportionate margin pools in specialist referral hospitals.
The FDA Center for Veterinary Medicine and the EMA Committee for Medicinal Products for Veterinary Use enforce divergent efficacy demonstration standards that shape development priorities and market access timelines for analgesic sponsors. USDA oversight of veterinary biologics intersects with state veterinary practice acts to create layered compliance requirements for product distribution and administration. Stakeholders must monitor evolving regulatory convergence around environmental impact assessments for pharmaceutical manufacturing residues, as this dimension increasingly influences approval conditions and facility siting decisions.
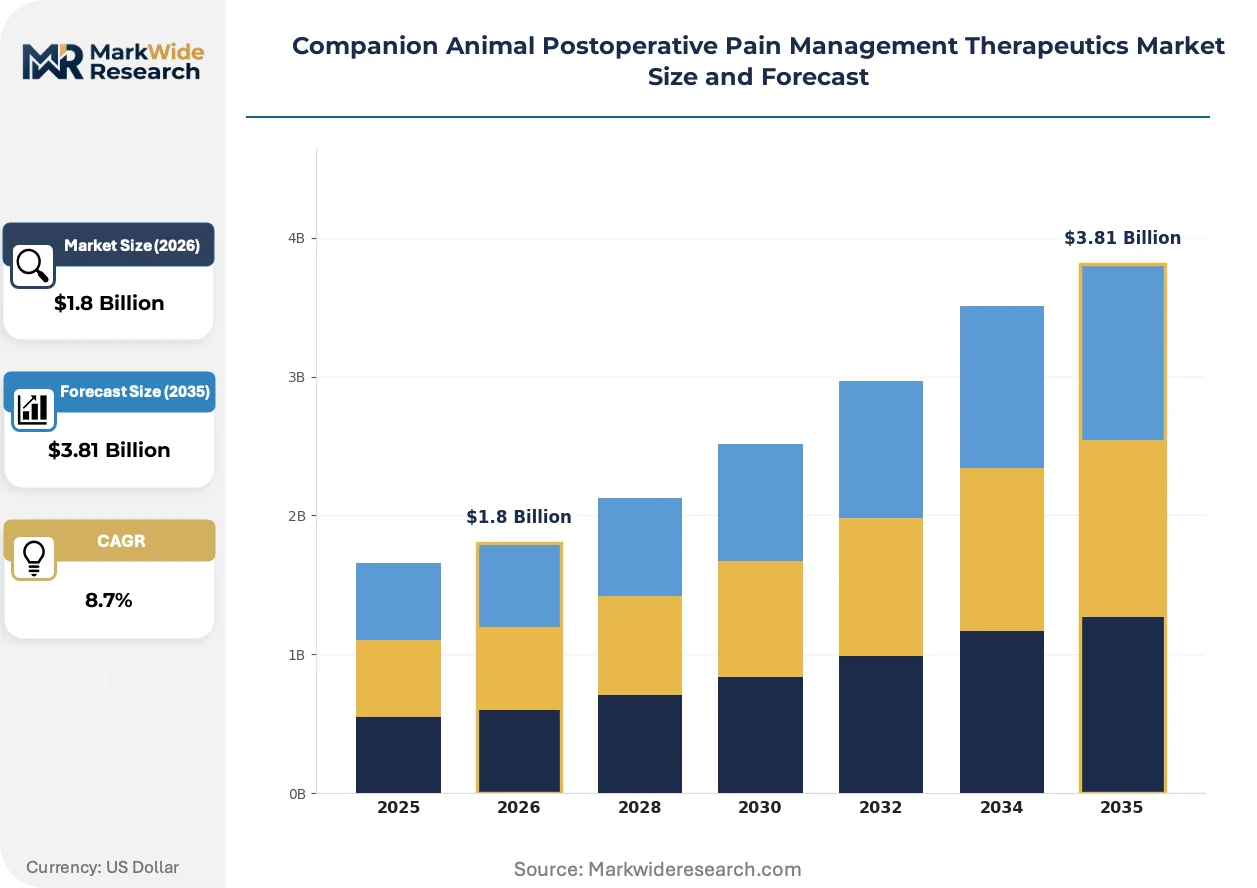
Market Dynamics
Multimodal analgesia protocols are restructuring veterinary practice economics by extending perioperative care into outpatient settings and compressing recovery timelines for surgical procedures in companion animals.
Growth Catalysts
- Pet Insurance Penetration:Reimbursement frameworks in the United States now cover 80% of postoperative analgesic costs, incentivizing veterinary clinics to prescribe premium formulations rather than generic alternatives.
- FDA Center for Veterinary Medicine Pathway Modernization:Streamlined efficacy demonstration standards for species-specific metabolism studies are accelerating new molecular entity approvals for feline and canine analgesics.
- Transdermal Delivery Technology:Liposomal encapsulation methods enable home-administered alternatives to clinic-based injections, expanding addressable demand beyond specialist referral hospitals into primary care practices.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthesis of COX-2 selective inhibitors for veterinary applications depends on three contract manufacturers in India and China, creating supply vulnerability.
- EMA Environmental Impact Assessments:The Committee for Medicinal Products for Veterinary Use now mandates manufacturing residue evaluation as a condition of marketing authorization, extending approval timelines.
- Generic Substitution Pressure:Off-label human NSAID compounding by veterinary pharmacies erodes branded product volumes in price-sensitive primary care segments.
Strategic Opportunities
- Japan's Aging Pet Demography:METI projections indicate 40% of companion dogs will exceed 8 years by 2028, expanding demand for geriatric-tolerant analgesic formulations with renal-sparing profiles.
- Biologic-Adjuvant Convergence:Monoclonal antibody platforms targeting nerve growth factor are creating combination therapy categories that command premium positioning in oncology and orthopedic surgery.
- Direct-to-Consumer Telehealth Channels:Postoperative remote monitoring platforms enable prescription fulfillment outside traditional veterinary clinic dispensing, capturing margin from the home recovery period.
Industry Challenges
- Veterinary Anesthesiology Specialist Shortage:Board-certified practitioners capable of designing multimodal protocols remain concentrated in 12 metropolitan referral clusters, limiting protocol standardization.
- Cross-Species Metabolism Modeling:Feline glucuronidation deficiency requires reformulation of canine-approved molecules, doubling preclinical study costs and failure rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Companion Animal Postoperative Pain Management Therapeutics Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NSAIDs, Opioids, Local Anesthetics, Adjuvants Delivery Mode: Injectable, Oral, Transdermal, Inhalation End User: Veterinary Clinics, Animal Hospitals, Pet Owners, Research Facilities Formulation: Tablets, Solutions, Gels, Powders |
| Companies Covered | Zoetis, Merck Animal Health, Elanco, Boehringer Ingelheim, Ceva Sante Animale, Dechra Pharmaceuticals, Norbrook, Vetoquinol, Bimeda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Companion Animal Postoperative Pain Management Therapeutics Market Emerging Trajectories
Extended-release depot formulations and wearable delivery systems are compressing the boundary between inpatient and outpatient pain management, enabling same-day discharge for procedures previously requiring overnight monitoring.
Implantable osmotic pumps for local anesthetic delivery are collapsing the distinction between regional blockade and systemic analgesia in orthopedic surgery. Specialist referral hospitals in Germany and the United Kingdom are adopting these devices for cruciate ligament repair cases. The technology is collapsing recovery timelines from 14 days to 72 hours for ambulation milestones.
The EMA's revised guidance on environmental risk assessment for veterinary medicinal products entered force in January 2024. Manufacturing sponsors must now submit predicted environmental concentration data for active metabolites prior to authorization. Small molecule NSAID developers targeting the European Union market are reformulating to reduce aquatic toxicity profiles.
Pet owner preference for home-based recovery monitoring is displacing scheduled recheck appointments as the default postoperative protocol. Veterinary practices in California, Texas, and Florida are unbundling pain assessment from physical examination, offering video-based follow-up at lower price points. This behavioral shift concentrates prescription fulfillment through online pharmacies rather than clinic dispensaries.
Companion Animal Postoperative Pain Management Therapeutics Market Segmentation
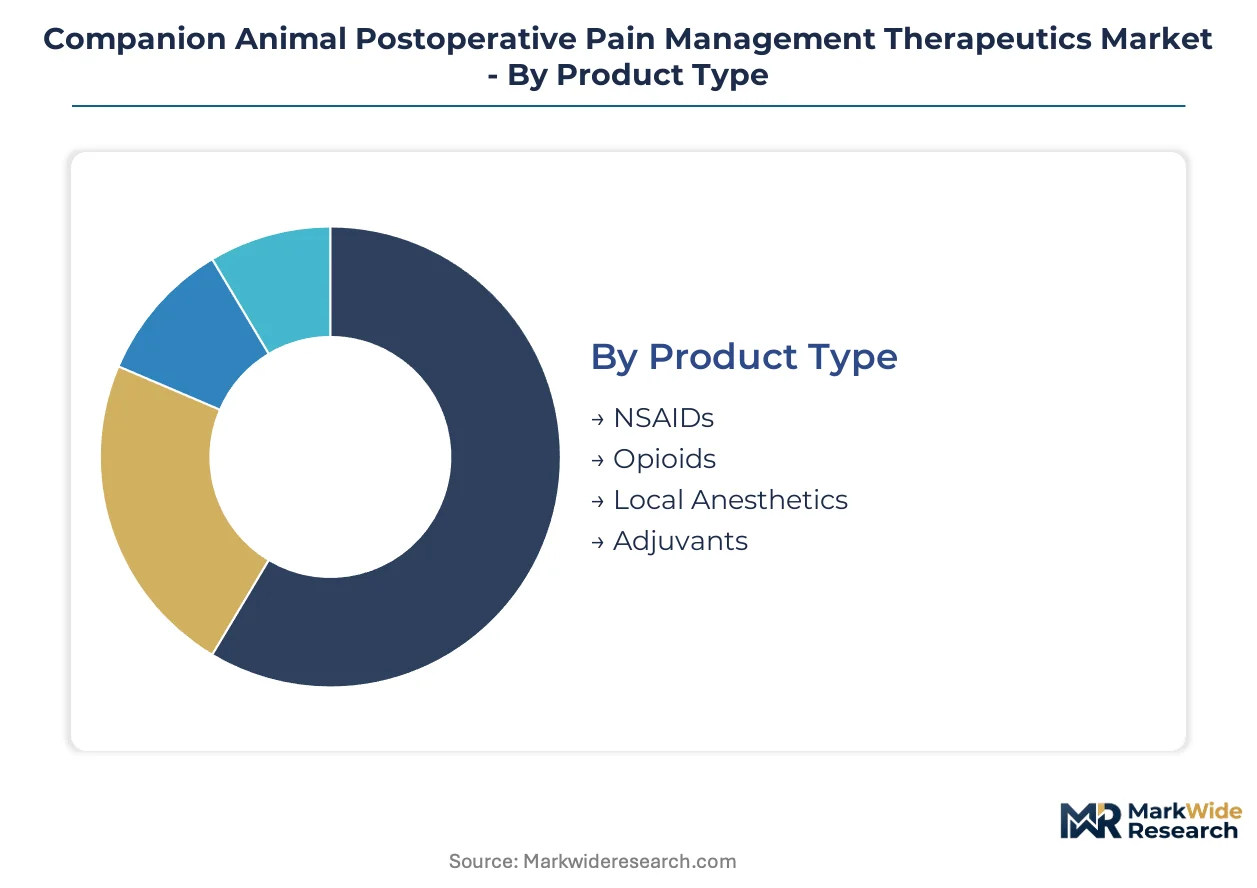
Segmentation in companion animal postoperative pain management therapeutics reveals distinct service intensity requirements across delivery modes and end-user channels. Veterinary clinics demand immediate technical support for injectable formulations, while pet owner segments require educational infrastructure for home-administered alternatives.
Product Type:
After-sales service intensity varies sharply across pharmacological classes, with biologic adjuvants demanding specialist consultation support that commodity NSAIDs do not require.
- NSAIDs:COX-2 selective and non-selective formulations constitute the volume foundation of perioperative protocols. Demand concentrates in primary care veterinary practices across the United States, where reimbursement frameworks incentivize prescription of branded veterinary-labeled products over compounded human alternatives.
- Local Anesthetics:Bupivacaine and ropivacaine depot formulations enable regional blockade with extended duration. Specialist referral hospitals in Germany and the United Kingdom are adopting implantable osmotic pump delivery, collapsing recovery timelines for cruciate ligament repair procedures.
- Opioids:Pure mu-agonist and partial agonist formulations for breakthrough pain management.
- Adjuvants:Gabapentinoids, alpha-2 agonists, and NMDA antagonists for multimodal protocol components.
By volume, NSAIDs lead. By growth pace, local anesthetics are ahead.
Delivery Mode:
Cost tier stratification separates premium clinic-administered injectables from economy oral generics, with transdermal formats occupying an expanding middle tier.
- Injectable:Parenteral formulations for immediate postoperative control in supervised settings. Demand concentrates in veterinary clinics performing same-day discharge procedures, where rapid onset offsets higher administration costs.
- Transdermal:Liposomal encapsulation and penetration-enhanced patches enable owner-administered alternatives to clinic visits. Pet owners in California, Texas, and Florida are driving substitution of scheduled recheck appointments with video-based follow-up protocols.
- Oral:Palatable tablets and solutions for outpatient continuation of analgesia.
- Inhalation:Nebulized and mask-delivered agents for specific procedural applications.
Injectable formats dominate current prescription volumes. Transdermal delivery is climbing the fastest as home-based recovery protocols expand.
End User:
Application context determines protocol complexity, with specialist hospitals managing multimodal regimens that primary care practices simplify for standardization.
- Veterinary Clinics:Primary care and general practice settings performing routine surgical procedures. Demand concentrates in suburban and exurban United States markets, where pet insurance penetration enables premium product selection over compounded alternatives.
- Animal Hospitals:Multi-specialty referral institutions with board-certified anesthesiology capability. Specialist clusters in 12 United States metropolitan areas standardize multimodal protocols that compress recovery timelines through integrated regional and systemic approaches.
- Pet Owners:Home-administered recovery management with remote veterinary oversight.
- Research Facilities:Controlled study environments with standardized pain assessment protocols.
Animal hospitals lead by margin contribution. Veterinary clinics are gaining share fastest as outpatient surgery volumes expand.
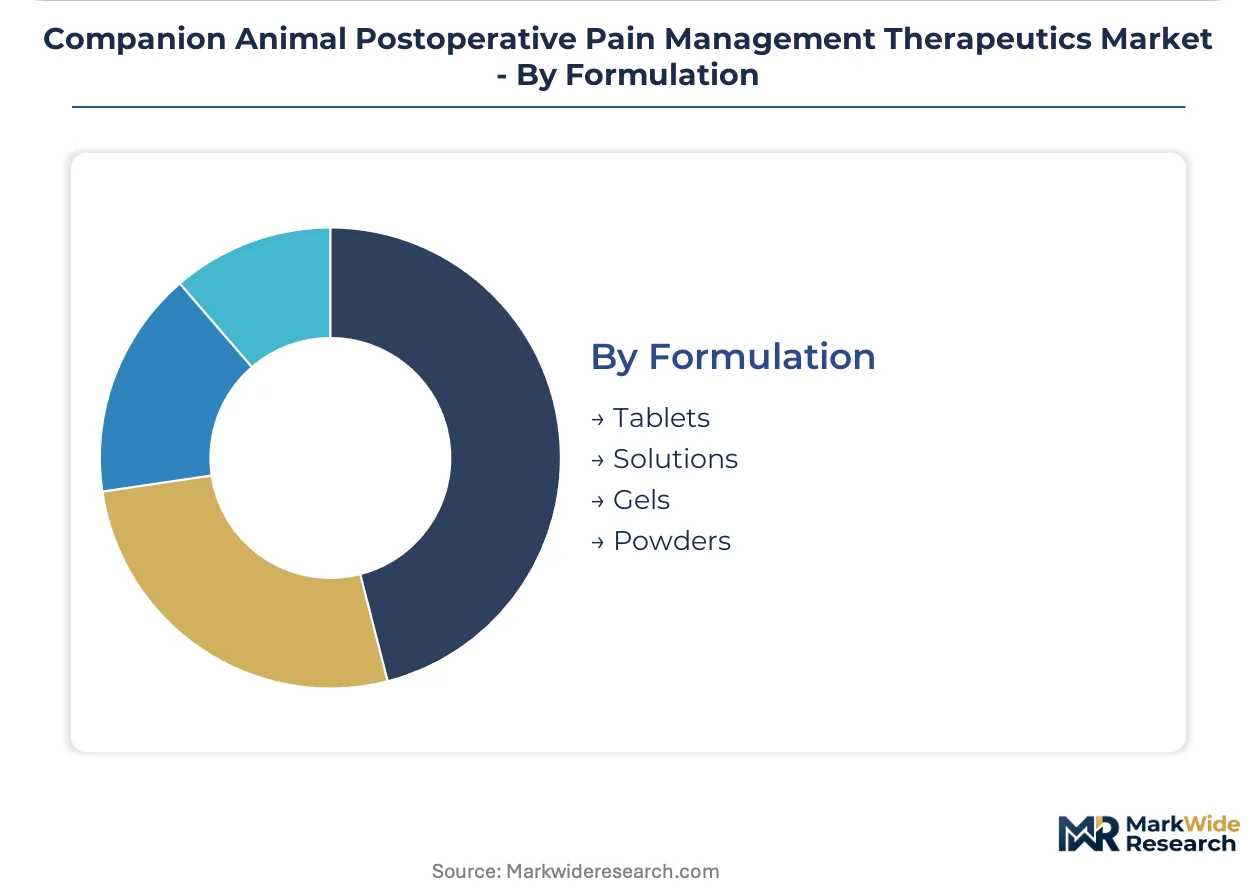
Formulation:
Supply concentration in tablet manufacturing contrasts with fragmented compounding pharmacy capacity for customized solutions and gels.
- Tablets:Palatable, scored, and extended-release oral formulations for canine and feline compliance. Demand concentrates in retail veterinary dispensing, though online pharmacy fulfillment is displacing clinic-based purchase for maintenance-phase prescriptions.
- Solutions:Liquid formulations enabling dose titration across weight ranges. Injectable solutions command premium positioning in perioperative settings, while oral solutions serve geriatric and pediatric patient populations with swallowing difficulties.
- Gels:Transdermal and mucosal application formats for localized effect.
- Powders:Reconstitutable formulations for compounding and extemporaneous preparation.
Tablets dominate by prescription count. Solutions are expanding most quickly as weight-based dosing protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine standards anchor North American demand, while EMA environmental mandates reshape European manufacturing economics. Specialist referral clusters concentrate in 12 United States metropolitan areas, with parallel density emerging in Germany and the United Kingdom.
United States
Pet insurance reimbursement frameworks now cover 80% of postoperative analgesic costs, driving prescription of branded veterinary-labeled products over compounded alternatives. The FDA Center for Veterinary Medicine maintains stringent efficacy thresholds for species-specific metabolism studies. Specialist clusters in California, Texas, and Florida are unbundling pain assessment from physical examination through video-based follow-up protocols.
Germany
Specialist referral hospitals in Bavaria and North Rhine-Westphalia are adopting implantable osmotic pumps for cruciate ligament repair cases, collapsing recovery timelines from 14 days to 72 hours. The EMA Committee for Medicinal Products for Veterinary Use mandates manufacturing residue evaluation as a condition of marketing authorization. Manufacturing sponsors in Baden-Württemberg are reformulating small molecule NSAIDs to reduce aquatic toxicity profiles ahead of revised guidance.
United Kingdom
Veterinary practices in Greater London and the Southeast are standardizing multimodal protocols that compress recovery timelines through integrated regional and systemic approaches. The EMA environmental risk assessment framework entered force in January 2024, extending approval timelines for new molecular entities. Specialist hospitals in Manchester and Birmingham are piloting wearable delivery systems for same-day discharge procedures.
Japan
METI projections indicate 40% of companion dogs will exceed 8 years by 2028, expanding demand for geriatric-tolerant analgesic formulations with renal-sparing profiles. The PMDA enforces species-specific metabolism demonstration standards that parallel FDA requirements. Veterinary clinics in the Tokyo and Osaka metropolitan areas are concentrating demand for premium biologic adjuvant therapies.
Canada
Health Canada and the Pest Management Regulatory Agency coordinate oversight of veterinary pharmaceuticals with provincial veterinary practice acts. Pet insurance penetration in Ontario and Quebec trails United States levels but is accelerating through employer-sponsored benefit programs. Specialist referral capacity concentrates in Toronto, Montreal, and Calgary, with primary care practices in Atlantic Canada representing underpenetrated demand for home-administered transdermal alternatives.
Companion Animal Postoperative Pain Management Therapeutics Market Vendor Landscape
Capability concentration sits with specialist developers; scale advantage sits with integrated research-to-distribution platforms. The market structures around three tiers: multinational pharmaceutical conglomerates with captive veterinary divisions, mid-cap specialists with niche formulation expertise, and regional generics manufacturers serving price-sensitive primary care segments. Dominant competitive moves include portfolio diversification into biologic-adjuvant combinations and strategic partnerships with telehealth platforms for direct-to-consumer prescription fulfillment.
Within the integrated pharmaceutical tier, Zoetis leverages cross-therapeutic infrastructure spanning research through distribution. Merck Animal Health represents the biologics-focused archetype, concentrating investment in vaccine-adjuvant platforms. Dechra Pharmaceuticals occupies the specialist position, anchoring premium niche formulations for exotic and companion species with defensible margin structures in referral hospital channels.
| Leading Market Players |
|---|
| Zoetis |
| Merck Animal Health |
| Elanco |
| Boehringer Ingelheim |
| Ceva Sante Animale |
| Dechra Pharmaceuticals |
| Norbrook |
| Vetoquinol |
| Bimeda |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Indian and Chinese contract manufacturers for COX-2 selective inhibitor APIs compresses pricing power for branded veterinary NSAIDs while forcing supply chain redundancy investments. This concentration dynamic simultaneously widens premium-to-economy tier spreads and accelerates geographic diversification mandates for sponsors targeting FDA and EMA markets.
Pricing Analysis
United States pricing for branded veterinary-labeled NSAIDs commands 40-60% premiums over compounded human alternatives in primary care practices, while transdermal formulations in California and Texas capture mid-tier positioning between clinic-administered injectables and economy oral generics. Price differentiation stems from FDA Center for Veterinary Medicine certification tier and bundled after-sales technical support intensity. Cost compression in the generic substitution segment is intensifying because veterinary pharmacies compound off-label human NSAIDs at volume scale. Primary care practices in price-sensitive exurban markets exhibit highest price sensitivity; specialist referral hospitals with board-certified anesthesiology capability show least sensitivity due to protocol standardization requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for active pharmaceutical ingredient procurement in companion animal analgesics. Manufacturing sponsors draw from India, China, and Switzerland for COX-2 inhibitor synthesis, bupivacaine base materials, and liposomal encapsulation excipients respectively. Single-source vulnerability concentrates in three Indian contract manufacturers supplying feline-specific formulation inputs. Distribution runs through veterinary distribution cooperatives and direct-to-clinic channels, with online pharmacy fulfillment displacing clinic dispensaries for maintenance-phase prescriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across delivery modes, species-specific metabolism requirements, and geographic regulatory clusters creates multiple niche entry points for specialized competitors. Pet owner preference for home-based recovery monitoring is splintering demand away from traditional clinic-centric models.
For Market Incumbents: Build regulatory data moats through species-specific metabolism study investments that generic compounders cannot replicate. Zoetis and Merck Animal Health should deepen backward integration into biologic-adjuvant manufacturing to defend margin pools against monoclonal antibody platform entrants. Captive supply of nerve growth factor targeting ingredients limits substitute threat from emerging biologic developers. For New Entrants and Emerging Players: Atlantic Canada and Japan's secondary metropolitan markets outside Tokyo-Osaka corridors offer underpenetrated demand for home-administered transdermal alternatives. Veterinary clinics in employer-sponsored pet insurance expansion zones present the most penetrable channel for premium formulation introductions. Direct-to-consumer telehealth partnerships enable prescription fulfillment outside traditional clinic dispensing capture. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap specialists with niche formulation expertise over diversified pharmaceutical conglomerates. Long-term viability across the analysis window hinges on biologic-adjuvant convergence capabilities and environmental risk assessment compliance infrastructure. Acquisition targets should demonstrate renal-sparing formulation portfolios for geriatric companion animal populations. The signal to watch is EMA marketing authorization timeline compression for sponsors with pre-submitted aquatic toxicity data packages.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA pre-submission of aquatic toxicity data accelerates marketing authorization timelines for NSAID sponsors. |
| Manufacturing Scale-Up | Capacity expansion in Switzerland for liposomal encapsulation addresses transdermal formulation supply constraints. |
| Pipeline Diversification | Monoclonal antibody platforms targeting nerve growth factor create premium combination therapy categories. |
| Strategic Partnership | Telehealth platform alliances capture margin from home recovery period prescription fulfillment. |
| Geographic Expansion | Market entry into Japan's aging pet demography demands renal-sparing geriatric formulation development. |
Methodological Framework
The analysis maps pharmacological class segments, delivery mode categories, and end-user channels, each validated through veterinary practice managers, regulatory affairs specialists at animal health sponsors, and procurement leads at veterinary distribution cooperatives. Primary interviews with board-certified veterinary anesthesiologists and formulary directors at specialist referral hospitals combined with secondary validation against FDA Center for Veterinary Medicine filings, EMA Committee for Medicinal Products for Veterinary Use submissions, and pet insurance reimbursement databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulate to segment-level estimates.
Assumptions held fixed include FDA and EMA regulatory framework stability, while pet insurance penetration trajectories and transdermal technology adoption curves were varied across sensitivity scenarios. The analytical framework projects volume and value across product type, delivery mode, end user, and regional regulatory cluster dimensions. CAGRs derive from fitted growth curves anchored to disclosed pipeline advancement timelines and species-specific approval probability assessments. Forecast inputs include veterinary surgical procedure volume projections and companion animal demographic aging patterns.
Practitioners should monitor EMA environmental risk assessment enforcement intensity and FDA species-specific metabolism study requirement evolution for early signals of forecast revision necessity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Muscle Tension Dysphonia Treatment Market
Pain Management
Radiofrequency Ablation Devices for Pain Management Market
Pain Management
Tattoo Numbing Cream Market
Pain Management
Cold Pain Therapy Market
Pain Management
Cancer Pain Management Market
Pain Management
Opioid Induced Side Effects Treatment Market
Pain Management
Central Pain Syndrome Management Market
Pain Management
OTC Painkiller Market
Pain Management
Heat Therapy Market
Pain Management
Migraine Management Market
Pain Management
Provoked Vestibulodynia Treatment Market
Pain Management
Topical Pain Relief Market
Pain Management
Global Pain Management Market
Pain Management
Chemotherapy Induced Pain Market
Pain Management
Global Postoperative Pain Management Market
Pain Management
Non Opioid Pain Treatment Market