
 Erythromelalgia Treatment Market | 2026-2036
Erythromelalgia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Erythromelalgia Treatment Market Foresight
Specialty pharmacy distribution is fragmenting as erythromelalgia therapeutics require cold-chain handling and patient-specific dosing protocols. Pfizer Inc. leverages its established rare disease infrastructure to navigate this complexity. Teva Pharmaceutical Industries Ltd. anchors its position through generic oral medication portfolios that compete on cost. Xenon Pharmaceuticals Inc. specializes in ion-channel modulators, differentiating its pipeline through mechanism-specific targeting.
Erythromelalgia treatment encompasses pharmacological and device-based interventions for a rare neurovascular disorder characterized by episodic erythema, burning pain, and elevated skin temperature in distal extremities; primary formulations include topical compounded agents with vasodilatory or vasoconstrictive properties, oral sodium channel blockers, and intravenous lidocaine infusions for refractory cases. The therapy area segments reveal chronic pain and neuropathic conditions commanding the deepest margin pools due to limited alternatives and prolonged treatment duration, while infusion treatments represent the fastest-growing product type as hospital outpatient departments expand ambulatory infusion capacity for refractory patients.
The FDA's orphan drug program shapes development economics through tax credits and market exclusivity, while the EMA's parallel designation streamlines European access for developers pursuing dual filings. The EPA and state-level hazardous drug handling regulations (USP <800>) constrain compounding pharmacy operations, elevating compliance costs for topical formulation suppliers. Stakeholders must monitor how FDA guidance on patient-reported outcome measures for rare pain conditions evolves, as this will determine trial design and eventual labeling claims for novel entrants.
Market Dynamics
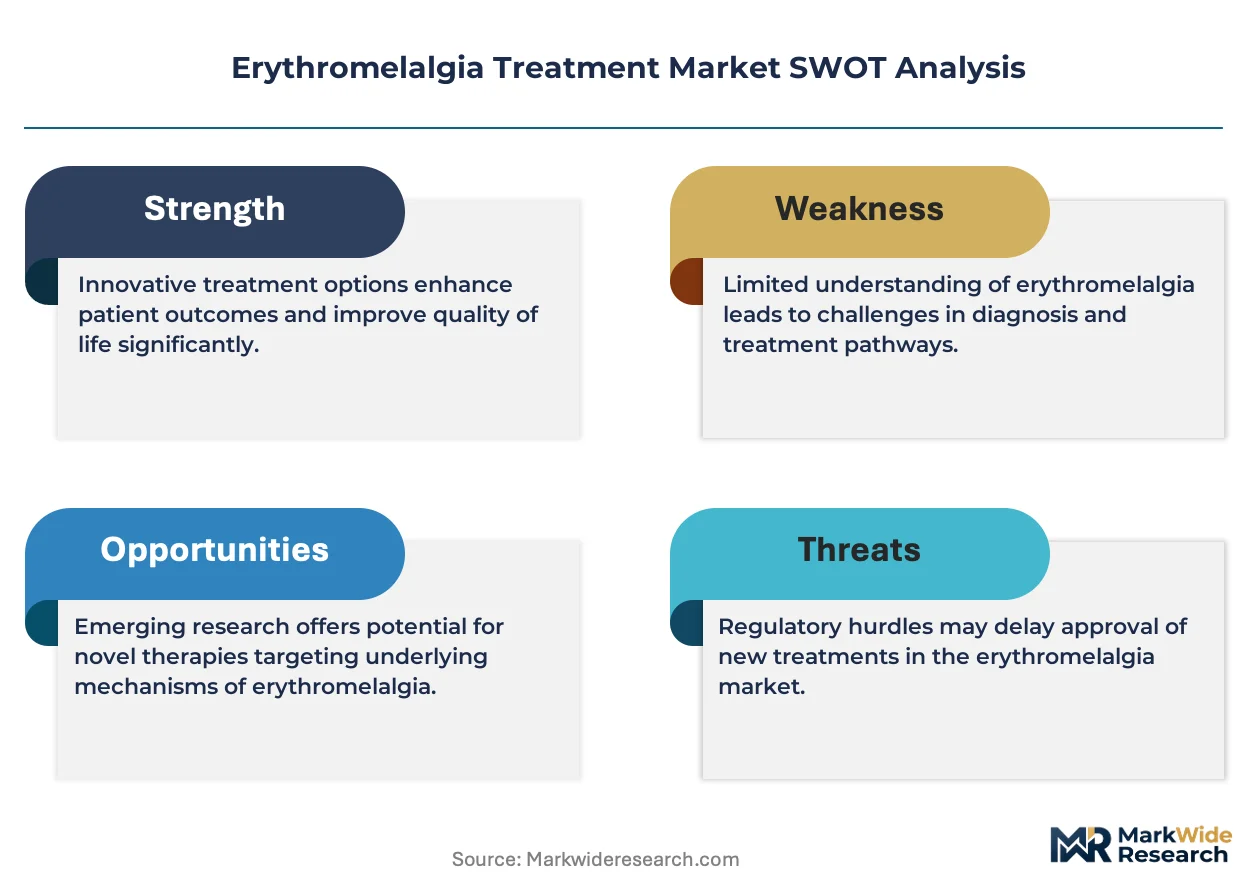
FDA's orphan drug designation pathway is compressing development timelines for erythromelalgia therapies while specialty pharmacy infrastructure expands cold-chain capabilities for temperature-sensitive formulations.
Growth Catalysts
- Orphan Drug Tax Credits:The FDA's program reduces clinical trial costs for developers pursuing sodium channel modulators, accelerating pipeline progression for primary erythromelalgia indications.
- Ambulatory Infusion Centers:Hospital outpatient departments in the United States are expanding dedicated capacity for intravenous lidocaine administration, creating accessible treatment nodes for refractory patients.
- Ion-Channel Targeting:Precision pharmacology approaches targeting Nav1.7 mutations are opening mechanism-specific therapeutic categories previously unaddressed by generic analgesics.
Market Restraints
- Compounded Formulation Costs:USP <800> hazardous drug handling requirements elevate compliance expenditures for topical vasodilator preparations, concentrating supply among certified specialty pharmacies.
- Diagnostic Recognition Gaps:Primary care physicians frequently misattribute erythromelalgia symptoms to common neuropathies, delaying specialist referral and treatment initiation.
- Reimbursement Fragmentation:Payer categorization of erythromelalgia as an off-label indication for many approved agents creates prior authorization bottlenecks for oral sodium channel blockers.
Strategic Opportunities
- Patient-Reported Outcome Measures:FDA guidance development for rare pain condition endpoints offers first-mover advantages for sponsors designing registrational trials with validated symptom scales.
- European Parallel Designation:EMA's orphan drug pathway enables synchronized US-EU filings, reducing regulatory duplication costs for developers with transatlantic commercialization strategies.
- Telemedicine Triage Networks:Academic medical centers are deploying remote consultation platforms to identify undiagnosed cases in rural catchment areas, expanding addressable patient pools.
Industry Challenges
- Specialty Pharmacy Integration:Cold-chain logistics for patient-specific topical formulations require coordination between compounders, distributors, and home-delivery networks.
- Clinical Endpoint Validation:Absence of standardized outcome measures for erythema severity and pain episode frequency complicates cross-trial comparability and regulatory review.
- Physician Education Requirements:Low disease prevalence limits residency exposure, necessitating sustained investment in continuing medical education for diagnostic proficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Erythromelalgia Treatment Market |
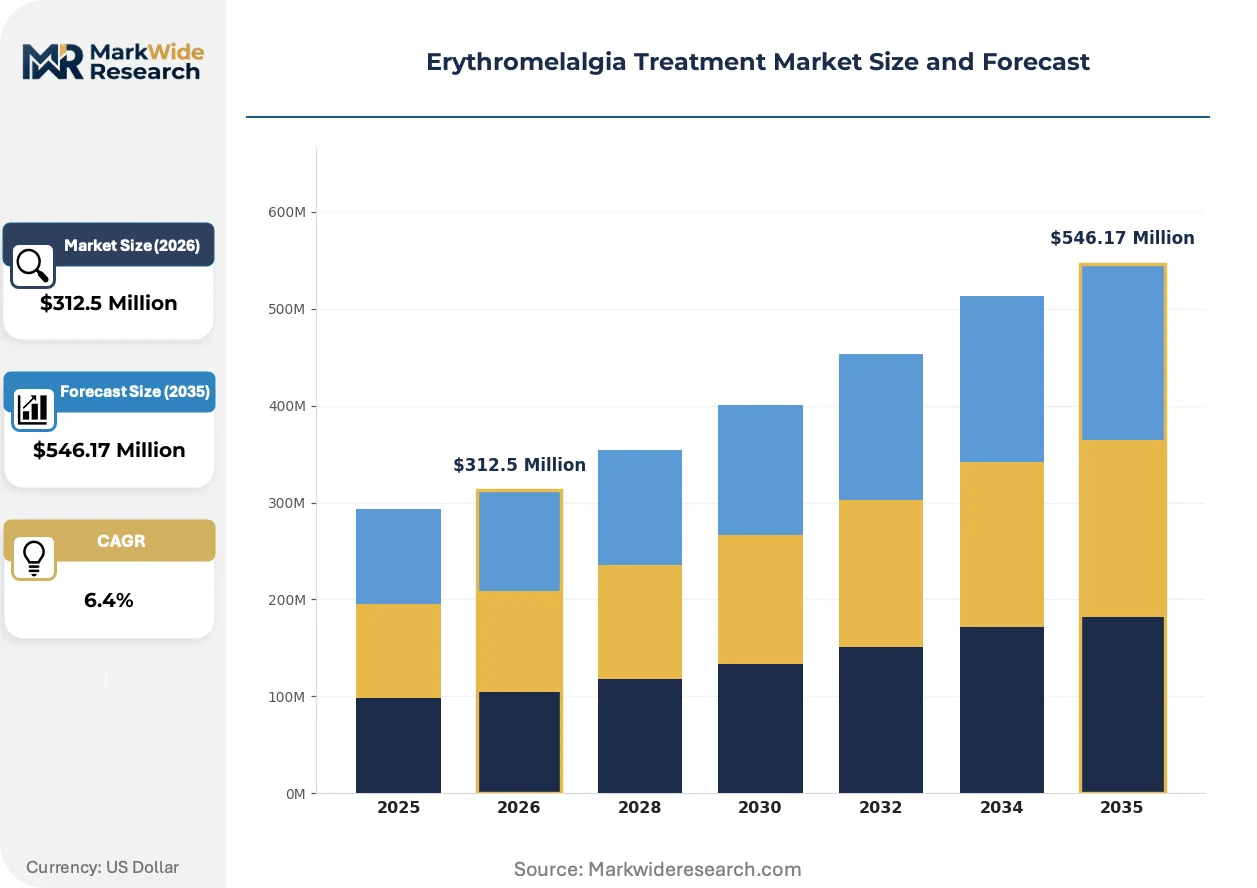
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Oral Medications, Infusion Treatments, Pain Management Devices Therapy Area: Chronic Pain, Skin Disorders, Neuropathic Conditions, Vascular Abnormalities Administration Route: Topical Application, Oral Route, Intravenous, Subcutaneous End User: Hospitals, Outpatient Clinics, Home Care Settings, Specialty Pharmacies |
| Companies Covered | Pfizer Inc., Teva Pharmaceutical Industries Ltd., Biogen Inc., Novartis AG, AbbVie Pharmaceuticals, Galderma S.A., Acorda Therapeutics Inc., Xenon Pharmaceuticals Inc., Amneal Pharmaceuticals LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Erythromelalgia Treatment Market Shifts & Advancements
Mechanism-based drug discovery is displacing empirical analgesic development in erythromelalgia, while regulatory frameworks adapt to accommodate ultra-rare disease trial designs.
Nav1.7 sodium channel inhibitors are hybridizing pharmacological approaches for inherited erythromelalgia, combining small-molecule chemistry with genetic stratification protocols. Academic medical centers with specialized pain genetics programs are adopting these agents through expanded access pathways ahead of formal approval. This precision-medicine convergence is compressing the traditional gap between genotype identification and targeted therapy deployment.
EMA's parallel orphan designation process is streamlining European market access for therapies simultaneously filed with the FDA, reducing duplicative regulatory submissions. Developers pursuing dual-track approvals are consolidating clinical data packages to satisfy both agencies' evidentiary requirements. Small-cap biopharma sponsors with limited regulatory affairs bandwidth are most affected, driving outsourcing partnerships with specialized consultancies.
Academic medical centers are anchoring decentralized clinical trial networks for erythromelalgia, replacing single-site enrollment with coordinated multi-hospital recruitment. Patient advocacy organizations are facilitating direct-to-specialist referral pathways that bypass primary care diagnostic delays. This network configuration is most visible in the United States, where the Erythromelalgia Association maintains geographic directories of experienced clinicians.
Erythromelalgia Treatment Market Segmentation
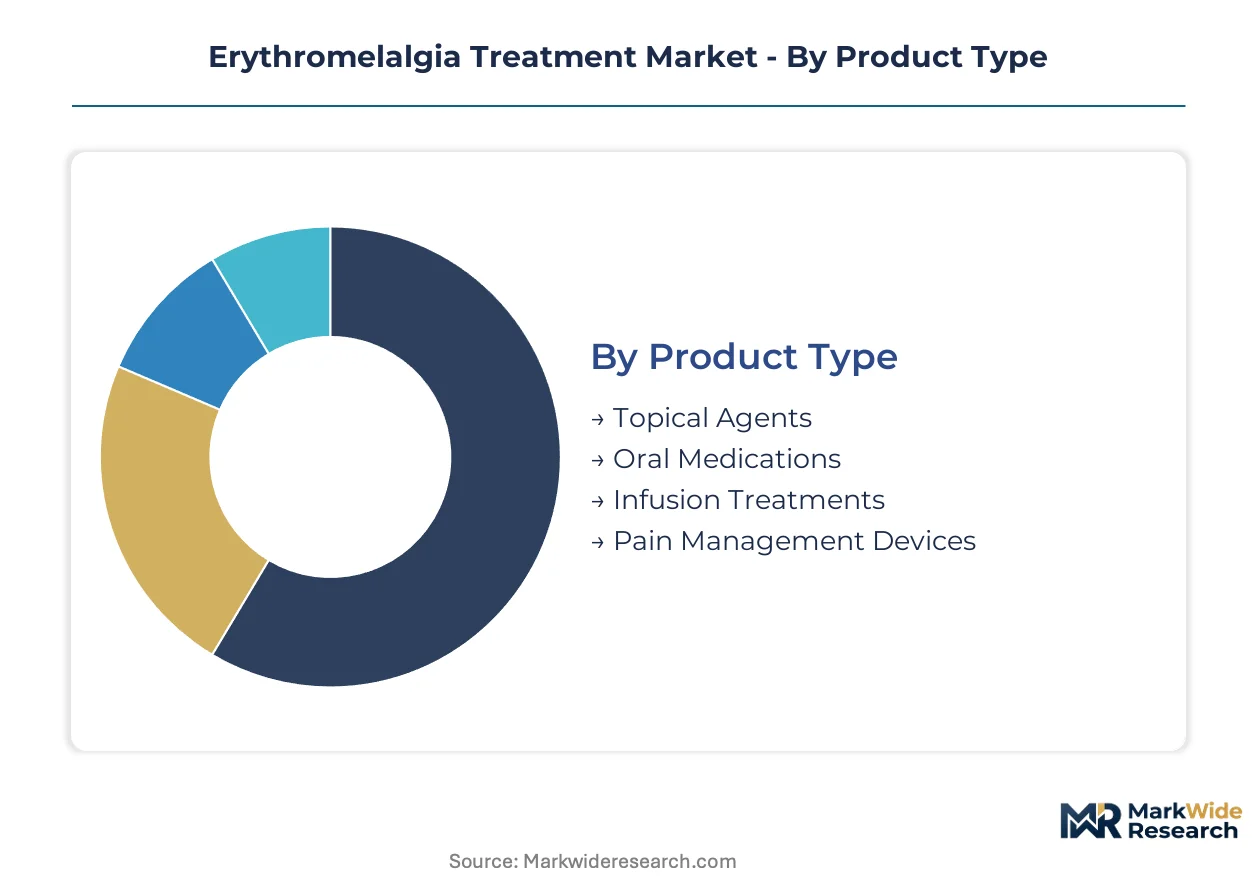
Erythromelalgia therapeutics fragment across four distinct axes that determine reimbursement pathways, supply chain complexity, and clinical adoption velocity. Product type stratification separates commoditized oral agents from high-touch infusion services, while therapy area segmentation reveals where mechanism-based premiums command sustainable margins.
Product Type:
Mature oral formulations dominate prescription volumes while emerging precision biologics reshape the innovation frontier.
- Topical Agents:Compounded vasodilatory and vasoconstrictive preparations require USP <800> compliant handling infrastructure. Academic medical centers in the United States anchor demand for patient-specific formulations, though hazardous drug regulations concentrate supply among certified specialty pharmacies with elevated compliance costs.
- Oral Medications:Sodium channel blockers and generic analgesics constitute the standard-of-care backbone for primary erythromelalgia. Teva Pharmaceutical Industries Ltd. competes aggressively on cost in this segment, while diagnostic recognition gaps among primary care physicians limit treatment initiation velocity.
- Infusion Treatments:Intravenous lidocaine protocols for refractory cases.
- Pain Management Devices:Neuromodulation and cooling apparatus for adjunctive therapy.
Oral medications handle the majority of throughput; infusion treatments are gaining share fastest as ambulatory capacity expands.
Therapy Area:
Margin concentration tracks disease severity and therapeutic alternatives available, with neuropathic conditions capturing premium positioning.
- Chronic Pain:Long-duration treatment protocols with limited alternatives sustain deep margin pools. Hospital outpatient departments in the United States deploy multimodal approaches combining pharmacological and interventional techniques, driving sustained utilization.
- Neuropathic Conditions:Mechanism-specific targeting through Nav1.7 modulators commands pricing power unavailable to empirical analgesics. Xenon Pharmaceuticals Inc. anchors development in this segment, with genetic stratification protocols enabling precision-medicine deployment.
- Skin Disorders:Erythema management through topical and systemic approaches.
- Vascular Abnormalities:Microcirculatory dysfunction interventions.
Chronic pain commands the deepest margin pools; neuropathic conditions show the steepest expansion trajectory as genetic diagnostics proliferate.
Administration Route:
Route selection determines site-of-care economics and patient adherence profiles, with parenteral options requiring institutional infrastructure.
- Topical Application:Patient-administered compounded preparations with cold-chain logistics dependencies. Specialty pharmacies in the United States coordinate home-delivery networks for temperature-sensitive formulations, creating coordination complexity between compounders and distributors.
- Oral Route:Convenience-driven preference for maintenance therapy.
- Intravenous:Lidocaine infusions for refractory episodes.
- Subcutaneous:Emerging delivery formats for chronic management.
Oral route handles the majority of throughput; intravenous administration is expanding most quickly with ambulatory center investment.
End User:
Care setting fragmentation reflects therapy intensity and reimbursement categorization, with specialty pharmacies mediating access for complex formulations.
- Specialty Pharmacies:Cold-chain distribution and patient-specific compounding capabilities concentrate here. Pfizer Inc. leverages established rare disease infrastructure to navigate this channel complexity, while USP <800> compliance requirements elevate barriers to entry.
- Hospitals:Acute episode management and infusion services.
- Outpatient Clinics:Diagnostic workup and treatment initiation.
- Home Care Settings:Maintenance therapy and symptom monitoring.
Specialty pharmacies mediate the most complex formulations; hospital outpatient departments are climbing fastest on infusion service expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug tax credits compress clinical trial costs for developers targeting Nav1.7 mutations, while EMA parallel designation streamlines European market entry. Academic medical centers in specific countries anchor patient identification networks and expanded access protocols.
United States
Academic medical centers in Massachusetts and California coordinate multi-site trial networks for inherited erythromelalgia subtypes. The FDA's orphan drug program accelerates sodium channel modulator development through tax incentives and market exclusivity provisions. Boston and San Francisco clusters specialize in pain genetics programs that deploy mechanism-based therapies through expanded access pathways.
Germany
Specialized pain clinics in Bavaria and North Rhine-Westphalia manage refractory cases through multimodal protocols combining pharmacological and interventional techniques. EMA orphan designation reduces regulatory duplication costs for developers pursuing dual US-EU filings. The Heidelberg and Munich medical clusters advance genetic stratification protocols for precision-medicine deployment of ion-channel inhibitors.
Switzerland
Basel anchors rare disease therapeutic development through established pharmaceutical R&D infrastructure and specialized regulatory consultancy networks. Swissmedic maintains streamlined pathways for orphan drug evaluation that align with EMA procedures. The Zurich and Geneva university hospitals coordinate referral networks for complex neurovascular pain conditions across Central European catchment areas.
United Kingdom
NHS specialized commissioning frameworks concentrate erythromelalgia care in London, Oxford, and Cambridge academic medical centers with dedicated pain genetics services. The MHRA operates recognition procedures for EMA orphan designations that accelerate market access timelines. The Oxford cluster leads phenotype-genotype correlation studies that inform patient stratification for mechanism-specific therapies.
Japan
PMDA's orphan drug designation system provides tax incentives and priority review for sodium channel modulators targeting rare pain conditions. Tokyo and Osaka university hospitals maintain specialized outpatient clinics for erythromelalgia and related small-fiber neuropathies. The Kansai region clusters diagnostic expertise in thermoregulatory disorders that supports clinical trial recruitment for novel therapeutics.
Erythromelalgia Treatment Market Competitive Landscape
On the supply side, the industry is bifurcated between established rare disease infrastructure holders and emerging precision-medicine specialists. Large-cap pharmaceutical companies leverage existing specialty pharmacy networks and regulatory affairs bandwidth to navigate orphan drug pathways. Mid-cap biopharma sponsors concentrate on mechanism-specific ion-channel targeting with genetic stratification protocols. Competitive moves center on portfolio diversification into rare neurovascular indications and strategic partnerships with academic medical centers for trial recruitment.
Within the established infrastructure tier, Pfizer Inc. and Teva Pharmaceutical Industries Ltd. occupy positions that exemplify divergent strategic archetypes. Pfizer leverages rare disease commercial infrastructure to navigate specialty pharmacy complexity and cold-chain distribution requirements. Teva anchors the oral medication segment through cost-competitive generic portfolios that address standard-of-care maintenance therapy demand. Xenon Pharmaceuticals Inc. represents the precision-medicine specialist archetype, with development focus concentrated on Nav1.7 sodium channel modulators that enable genetic stratification protocols.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Biogen Inc. |
| Novartis AG |
| AbbVie Pharmaceuticals |
| Galderma S.A. |
| Acorda Therapeutics Inc. |
| Xenon Pharmaceuticals Inc. |
| Amneal Pharmaceuticals LLC |
| Others |
Supply & Pricing Matrix
Specialty pharmacy compounding concentration in the United States anchors margin capture for patient-specific topical formulations, while cold-chain logistics costs cascade downstream to determine pricing power across administration routes. USP <800> hazardous drug handling compliance elevates barriers for small compounders, consolidating supply among certified operators who extract premiums for temperature-controlled distribution.
Pricing Analysis
Volume-discount tiering separates academic medical center procurement from individual patient cash-pay segments, with institutional purchasers leveraging formulary placement for sodium channel blockers. Price differentiation rests on USP <800> certification status and genetic stratification protocol availability, with mechanism-specific Nav1.7 therapies commanding premiums unavailable to generic analgesics. Cost compression in oral maintenance therapy intensifies as Teva Pharmaceutical Industries Ltd. and Amneal Pharmaceuticals LLC compete on portfolio breadth. Hospital outpatient departments exhibit lowest price sensitivity for infusion services due to bundled reimbursement structures, while uninsured patients in home care settings face highest out-of-pocket exposure for compounded topicals.
Supply Chain Analysis
Contract manufacturing for active pharmaceutical ingredients concentrates among Indian and Chinese suppliers serving oral sodium channel blocker production, while sterile compounding capacity clusters in United States specialty pharmacies with USP <797> and USP <800> certifications. Raw material dependencies include lidocaine HCl, mexiletine API, and temperature-stable packaging substrates. Single-source vulnerability runs through certified cold-chain logistics providers for patient-specific topical formulations. Distribution feeds from compounders through specialty pharmacy networks to home-delivery endpoints, with hospital outpatient departments maintaining direct procurement relationships for infusion protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital purchasing organizations and specialty pharmacy networks, as formulary placement and distribution access become scarcer than manufacturing capacity.
For Market Incumbents: Harden rare disease commercial infrastructure against emerging precision-medicine specialists by deepening captive supply relationships with certified USP <800> compounders. Expand ambulatory infusion center partnerships to lock in site-of-care control before generic lidocaine competitors erode service margins. Prioritize FDA patient-reported outcome measure validation to secure labeling advantages that reimbursement committees recognize. For New Entrants and Emerging Players: Pursue European parallel designation filings to capture EMA orphan drug benefits without duplicative regulatory expenditure, targeting Germany and Switzerland as initial access points. Exploit telemedicine triage networks in rural United States catchment areas where diagnostic recognition gaps delay treatment initiation and create addressable patient pools. Lead with mechanism-specific Nav1.7 genetic stratification protocols to differentiate from empirical analgesic incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward precision-medicine biopharma sponsors with validated genetic biomarker platforms and expanded access pathway experience, as these capabilities compound over the therapeutic development cycle. Long-term viability hinges on regulatory exclusivity duration and reimbursement precedent establishment. Monitor FDA guidance publication timelines for rare pain condition endpoints as the critical inflection signal determining first-mover trial design advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pathway | FDA tax credits and market exclusivity provisions accelerate sodium channel modulator development economics. |
| Specialty Pharmacy Partnership | USP <800> certified compounders control patient-specific formulation access and cold-chain distribution capacity. |
| Patient-Reported Outcome Validation | Standardized erythema severity scales enable registrational trial designs that support labeling claims. |
| Academic Medical Center Alliance | Pain genetics programs at Massachusetts and California clusters anchor expanded access protocol deployment. |
| European Parallel Filing | EMA synchronized submissions reduce regulatory duplication costs for transatlantic commercialization strategies. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA orphan drug filings, ClinicalTrials.gov records, EMA submission databases, and specialty pharmacy distribution reports. Bottom-up patient prevalence estimates and top-down therapeutic category spending triangulation anchored market size quantification.
Demand-supply-balance modeling across the projection horizon incorporated treatment line stratification, dosage form segmentation, administration route economics, and regional regulatory cluster differentiation. CAGRs were derived from epidemiological progression assumptions, therapy penetration curves, and pricing trajectory analysis. Forecast inputs included ambulatory infusion center capacity expansion rates and genetic diagnostic adoption patterns in academic medical center networks.
Sensitivities concentrate around FDA guidance timing for rare pain condition endpoints, EMA parallel designation processing velocity, and USP <800> enforcement intensity affecting compounding pharmacy supply concentration. Quarterly review of orphan drug approval timelines, specialty pharmacy certification expansions, and telemedicine triage network deployment metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Muscle Tension Dysphonia Treatment Market
Pain Management
Over-The-Counter Pain Medication Market
Pain Management
Cluster Headache Market
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
Neuropathic Pain Market
Pain Management
Chemotherapy Induced Pain Market
Pain Management
Global Morphine Market
Pain Management
Pain Therapeutic Solutions Market
Pain Management
Pain Relief Oil Market
Pain Management
Pain Management Therapeutics Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Global Visceral Pain Treatment Market
Pain Management
Global Non-Opioid Pain Patch Market
Pain Management
Global Pain Management Market
Pain Management
Postoperative Pain Market
Pain Management
Dyspareunia Market