
 Palliative Care Market | 2026-2036
Palliative Care Market Size, Share, and Industry Trends Forecast 2026-2036
Palliative Care Market Intelligence
The fragmented landscape of home care providers is consolidating as larger entities seek to expand their service networks and standardize care protocols. Chemed Corporation, through its VITAS Healthcare subsidiary, specializes in end-of-life care across numerous US states. Amedisys Inc. competes by offering a broad spectrum of home health and hospice services. Meanwhile, Kindred Healthcare leverages its extensive network of transitional care hospitals and rehabilitation facilities to offer integrated palliative solutions.
Palliative care is an interdisciplinary medical approach focused on optimizing quality of life by anticipating, preventing, and treating suffering. It addresses physical symptoms like pain and dyspnea, as well as psychosocial and spiritual needs, independent of the prognosis. The oncology therapy area continues to represent the largest source of patient referrals for palliative services. Within end-user settings, home care providers and hospices are experiencing significant expansion, driven by patient preference and cost-effectiveness.
Reimbursement frameworks, such as those from the Centers for Medicare & Medicaid Services (CMS) in the United States, directly shape provider viability and service availability. Concurrently, drug approvals from bodies like the European Medicines Agency (EMA) and the US FDA determine the toolkit of available pain and symptom management medications. Provider success will depend on effectively navigating these complex, value-based payment structures while integrating new care delivery technologies.
Market Dynamics
The central dynamic shaping the palliative care market is the growing misalignment between traditional, facility-based healthcare reimbursement and the strong patient preference for home-based services. This tension is forcing providers and payers to develop new, flexible care delivery models.
Growth Catalysts
- Supportive Reimbursement Frameworks:Value-based payment initiatives from bodies like the Centers for Medicare & Medicaid Services (CMS) in the US create financial incentives for providers to adopt coordinated, patient-centered palliative care models, particularly in hospice settings.
- Aging Global Demographics:Countries with rapidly aging populations, notably Japan and Germany, are experiencing a surge in chronic and life-limiting illnesses, which directly expands the addressable patient base for palliative interventions.
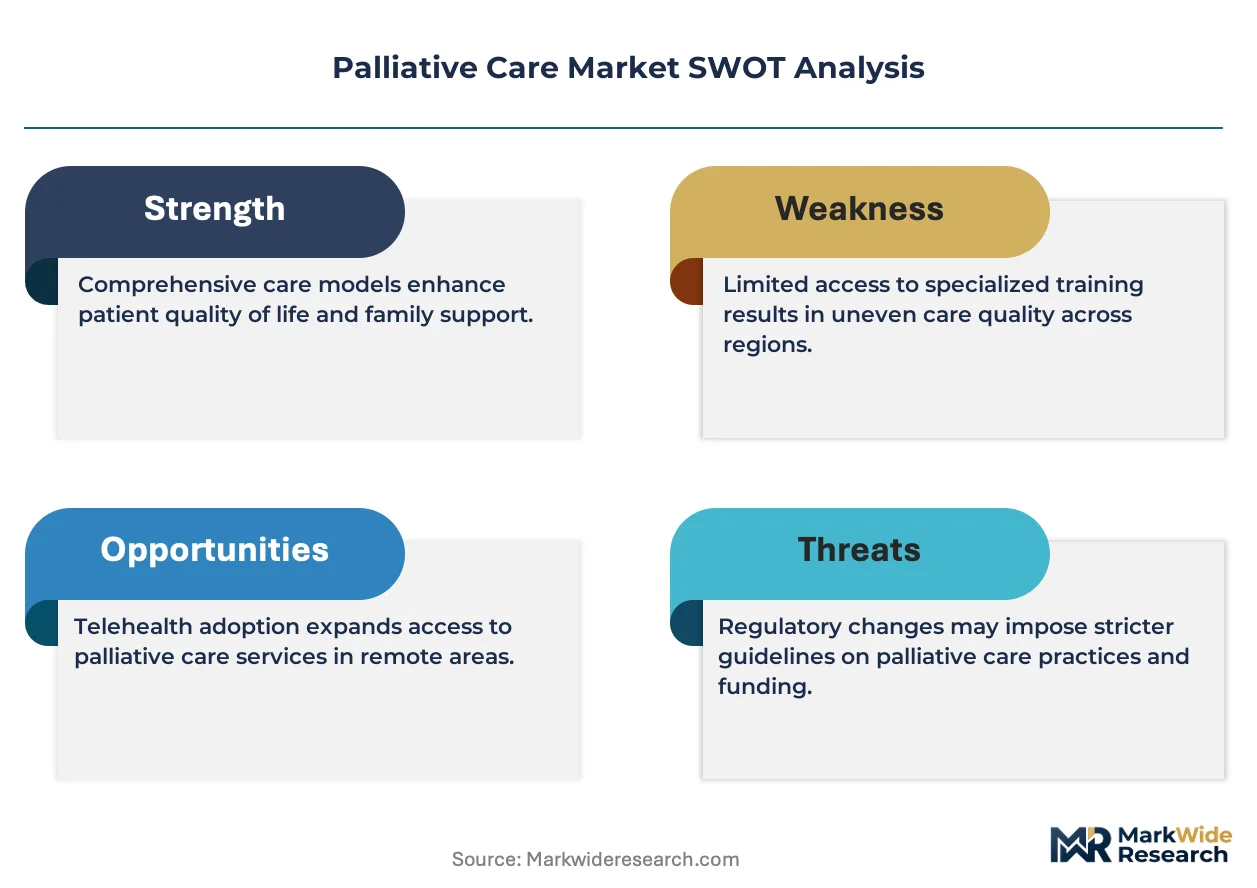
- Telehealth Integration:The widespread adoption of telehealth platforms improves access to specialist palliative consultations for patients in rural or underserved areas, overcoming geographical barriers to care and enabling more frequent check-ins.
Market Restraints
- Workforce Shortages:A structural deficit of physicians, nurses, and social workers with specialized training and certification in palliative medicine creates a primary bottleneck, limiting the capacity to meet patient needs across geographies.
- Inconsistent Payer Coverage:Ambiguity and variation in reimbursement policies for palliative services among private and public payers, especially for non-hospice care, generate financial uncertainty for providers and limit patient access.
- Public Misconceptions:The persistent, incorrect association of palliative care exclusively with end-of-life or hospice care among patients and some clinicians delays referrals, preventing early intervention for symptom management and quality-of-life improvement.
Strategic Opportunities
- Non-Oncology Program Development:There is significant opportunity to design and market specialized palliative programs for patients with non-cancer diagnoses, such as advanced heart failure, COPD, and neurological disorders, which remain an underserved population.
- Pediatric Palliative Care Expansion:The development of dedicated pediatric palliative services represents a key growth area, addressing the unique physical, psychosocial, and spiritual needs of children with life-limiting conditions and their families.
- AI for Patient Identification:Leveraging artificial intelligence and machine learning algorithms to analyze electronic health records can proactively identify patients who would benefit most from an early palliative care consultation, improving outcomes and resource allocation.
Industry Challenges
- Interoperability of Health Records:The lack of seamless data sharing between different electronic health record systems used by hospitals, clinics, and home care agencies complicates care coordination and creates communication gaps within interdisciplinary teams.
- Measuring Quality and Outcomes:Standardizing and consistently measuring meaningful quality-of-life outcomes, patient satisfaction, and symptom burden across diverse patient populations presents a significant operational challenge for demonstrating value to payers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Palliative Care Market |
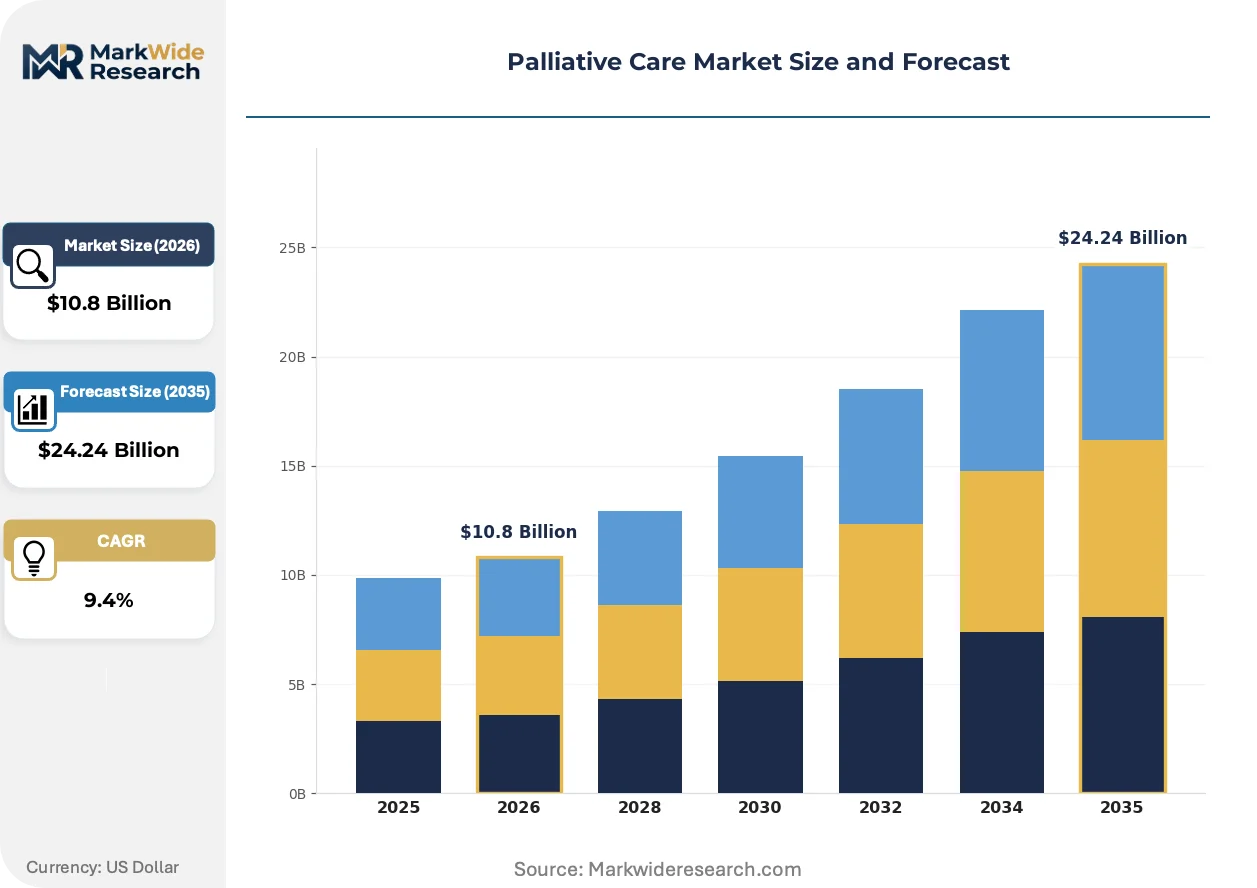
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $24.24 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pain Relief Medications, Symptom Management Devices, Nutritional Supplements, Respiratory Aids, Psychological Support Tools Therapy Area: Oncology, Neurological Disorders, Cardiovascular Conditions, Chronic Respiratory Diseases, Renal Failure End User: Hospices, Home Care Providers, Rehabilitation Centers, Nursing Facilities, Community Health Services Care Delivery Mode: Inpatient Units, Outpatient Clinics, Home-Based Care, Telehealth Services, Mobile Care Units |
| Companies Covered | Chemed Corporation (VITAS Healthcare), Amedisys Inc., Genesis HealthCare Corporation, Kindred Healthcare, Lifepoint Health (Gentiva Health Services), Sunrise Senior Living, Honor Technology Inc. (Home Instead, Inc.), LHC Group, AccentCare Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Palliative Care Market Strategic Shifts & Innovations
The evolution of care delivery is defined by a decisive shift from institutional settings to the patient's home, a transition enabled by digital health technologies. This change is altering provider business models and forcing a re-evaluation of how care is financed and delivered.
Telehealth platforms combined with remote patient monitoring devices allow for continuous symptom assessment and virtual consultations. Home care and hospice providers are adopting these tools to manage care for patients with complex needs more effectively. This integration of digital health is decentralizing care delivery, moving it away from centralized hospitals and into the community.
Value-based payment structures, particularly from the US Centers for Medicare & Medicaid Services (CMS), are linking provider reimbursement to patient outcomes rather than service volume. This policy shift incentivizes early and comprehensive palliative interventions that reduce hospital readmissions and improve quality of life. Home health and hospice agencies are most affected, driving investment in data analytics to document performance.
A strong patient preference for receiving care in familiar surroundings is altering service utilization patterns. This behavioral shift reduces reliance on long-term stays in transitional care facilities for palliative needs, favoring instead mobile teams from hospice and home health agencies. The trend is most visible in developed countries with established home care infrastructure, such as the United States and Canada.
Palliative Care Market Segmentation
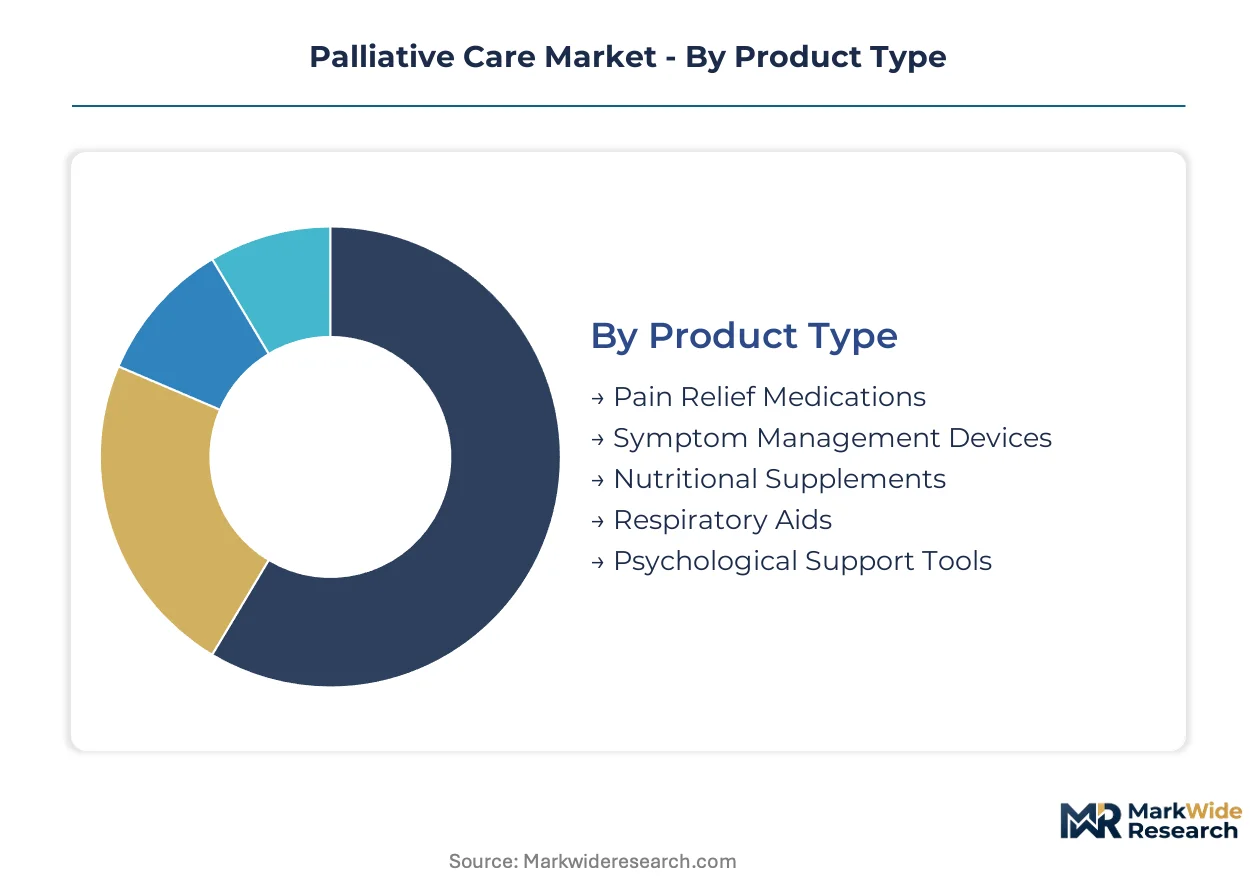
The palliative care market segments across various dimensions, reflecting the diverse patient needs, care settings, and therapeutic approaches required to optimize quality of life. Understanding these distinctions is critical for providers to tailor services and for payers to develop appropriate reimbursement models.
Product Type:
Product type segmentation highlights how diverse patient needs drive demand for specific palliative interventions, from pharmacological relief to supportive devices.
- Pain Relief Medications:These pharmaceutical agents, including opioids, NSAIDs, and adjuvant analgesics, are central to managing chronic and acute pain, a primary symptom across many life-limiting conditions. Demand concentrates in both hospice and home care settings, driven by the imperative to maintain patient comfort.
- Symptom Management Devices:This category encompasses medical equipment designed to alleviate specific symptoms, such as nebulizers for dyspnea, anti-nausea pumps, or specialized wound care products. Their utility is expanding within home-based care, supported by remote monitoring technologies and skilled nursing visits.
- Nutritional Supplements:Products providing essential nutrients or caloric support for patients experiencing cachexia, dysphagia, or other nutrition-related challenges.
- Respiratory Aids:Devices like oxygen concentrators, CPAP machines, and ventilators used to manage respiratory distress and improve breathing comfort.
- Psychological Support Tools:Resources such as therapeutic apps, meditation guides, or counseling services aimed at addressing the emotional and mental well-being of patients.
Pain Relief Medications lead volumes today; Symptom Management Devices are gaining share fastest.
Therapy Area:
The application of palliative care varies significantly across different therapy areas, reflecting distinct symptom profiles and disease progression.
- Oncology:Palliative care within oncology focuses on managing pain, fatigue, nausea, and psychological distress associated with cancer and its treatments, often integrated from diagnosis. Patient referrals from oncology departments represent the largest source of demand for specialized palliative services.
- Cardiovascular Conditions:This segment addresses symptoms like dyspnea, fatigue, and edema in patients with advanced heart failure or other severe cardiovascular diseases, improving their functional capacity and quality of life. The aging global demographic in countries like Germany is driving an expansion of these services.
- Neurological Disorders:Palliative interventions for conditions such as Parkinson's, ALS, or advanced dementia aim to manage motor symptoms, cognitive decline, and communication difficulties.
- Chronic Respiratory Diseases:Services target symptom control for conditions like COPD and pulmonary fibrosis, focusing on breathlessness management and respiratory support.
- Renal Failure:Palliative care for end-stage renal disease addresses symptoms such as fatigue, pruritus, and pain, often in conjunction with dialysis decisions.
Oncology services remain the largest segment; Cardiovascular Conditions are expanding most quickly.
End User:
End-user categories reflect distinct operational models and patient care settings, influencing service delivery.
- Hospices:These organizations provide comprehensive end-of-life care, typically for patients with a prognosis of six months or less, focusing on comfort and quality of life at home or in dedicated facilities. Reimbursement frameworks from the Centers for Medicare & Medicaid Services significantly influence their operational viability in the United States.
- Home Care Providers:Agencies delivering medical and non-medical services directly to patients in their residences, enabling individuals to receive palliative support in familiar surroundings. Patient preference for home-based care in countries like Canada is driving substantial growth in this segment.
- Rehabilitation Centers:Facilities offering specialized therapies to restore function and improve quality of life for patients recovering from illness or injury, sometimes incorporating palliative approaches.
- Nursing Facilities:Long-term care institutions providing skilled nursing services and personal care for individuals with chronic health conditions, often integrating palliative support.
- Community Health Services:Public or private organizations offering health promotion, disease prevention, and direct care within community settings, including mobile palliative teams.
Hospices serve a significant portion of patients; Home Care Providers are climbing the fastest.
Care Delivery Mode:
Care delivery modes showcase varying levels of maturity and integration within the broader healthcare system.
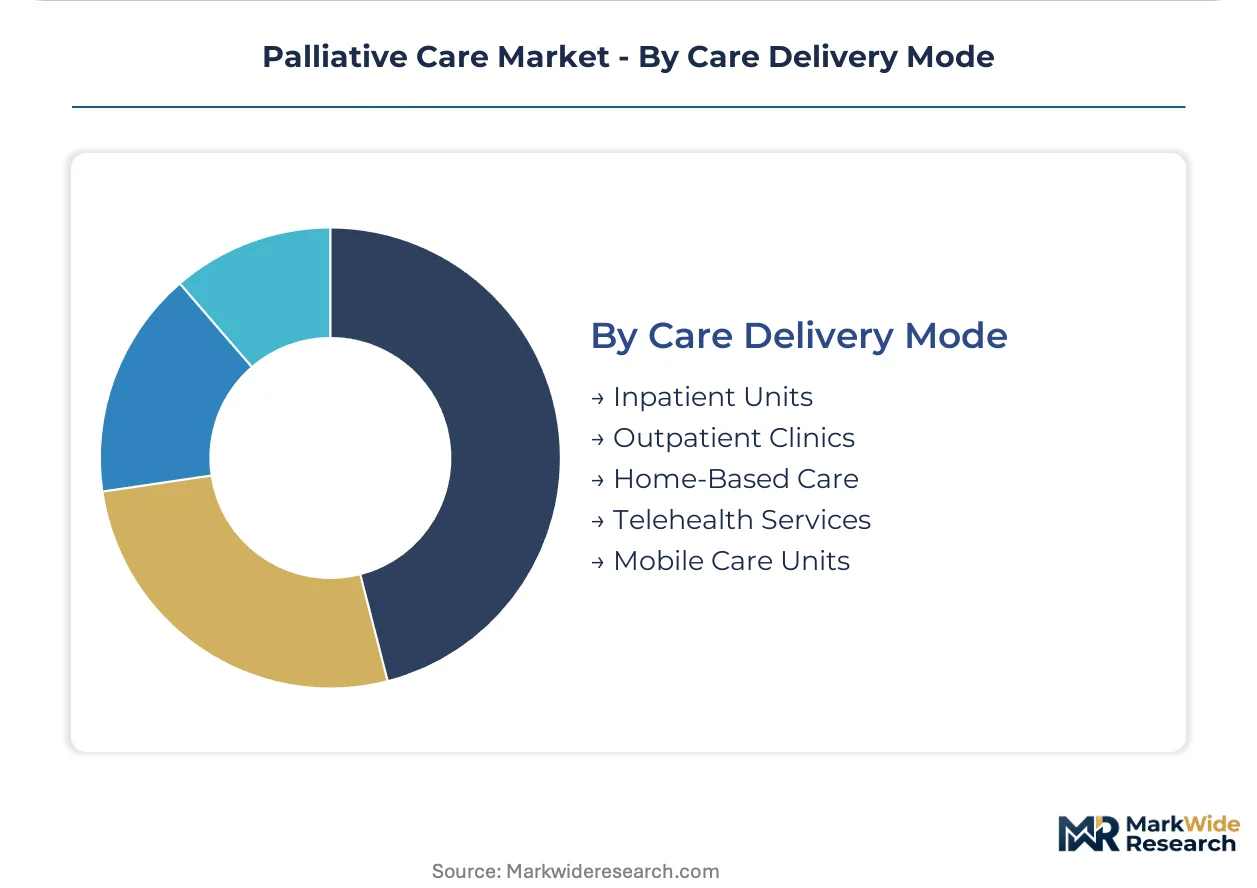
- Home-Based Care:This mode involves interdisciplinary teams providing palliative services directly in the patient's home, offering comfort and continuity of care. The strong patient preference for familiar surroundings is making this a dominant delivery model in developed countries.
- Telehealth Services:Utilizing digital communication technologies for remote consultations, symptom monitoring, and family support, overcoming geographical barriers and improving access to specialist care. The widespread integration of telehealth is a key technological shift influencing care delivery models in the United States.
- Inpatient Units:Dedicated hospital or hospice units providing intensive palliative care for complex symptom management or short-term respite.
- Outpatient Clinics:Hospital-affiliated or standalone clinics offering scheduled palliative consultations and follow-up care for patients not requiring inpatient admission.
- Mobile Care Units:Teams equipped to provide urgent or episodic palliative interventions in various community settings, often complementing home-based care.
Inpatient Units represent a traditional mode; Telehealth Services exhibit the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The varying regulatory and reimbursement landscapes across nations create distinct operational environments for palliative care providers. Providers often adapt service models to navigate these differences, seeking optimal delivery methods within diverse policy frameworks. This dynamic influences investment and service expansion in specific regions.
United States
The United States market sees strong demand driven by patient preference for home-based care and the shift towards value-based models. Centers for Medicare & Medicaid Services (CMS) reimbursement frameworks significantly influence provider viability. Major metropolitan areas like New York and Los Angeles are witnessing consolidation among home care providers.
Japan
Japan's rapidly aging population and the surge in chronic illnesses fuel a substantial demand for palliative interventions. The Ministry of Health, Labour and Welfare (MHLW) actively promotes integration of palliative care into the national health system. Urban centers such as Tokyo and Osaka are at the forefront of developing integrated community-based palliative care networks.
Germany
German demographics, characterized by an aging population, drive an expanding need for palliative services, particularly for cardiovascular conditions. German health insurance funds (Krankenkassen) critically shape reimbursement for specialized palliative home care. Cities like Berlin and Munich function as key centers for advanced palliative medicine research and specialized clinics.
Canada
Canadian patients exhibit a strong preference for receiving palliative care in their familiar home surroundings, altering service utilization patterns. Health Canada guidelines support provincial efforts to expand access to comprehensive palliative services. The provinces of Ontario and British Columbia are leading the development of integrated palliative care programs.
India
India faces a rising prevalence of non-communicable diseases, leading to growing demand for effective symptom management. The country's national health policy aims to integrate palliative care into primary healthcare. Major cities like Mumbai and Chennai are experiencing the emergence of specialized palliative care units and non-governmental organizations.
Palliative Care Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue integrated home-based solutions and digital health technologies. The palliative care market exhibits fragmentation, particularly among home care providers, yet consolidation efforts are underway. This landscape features large diversified healthcare conglomerates, specialized hospice and home health providers, and technology-driven service enablers. Strategic partnerships and geographic expansion define much of the current competitive activity.
Within the specialized hospice and home health segment, Chemed Corporation, through its VITAS Healthcare subsidiary, exemplifies a focus on end-of-life care across numerous US states. Amedisys Inc. occupies a position as a broad home health and hospice service provider, offering a wide spectrum of services to patients requiring comfort. Kindred Healthcare represents an integrated approach, leveraging its extensive network of transitional care and rehabilitation facilities to deliver comprehensive palliative solutions, integrating various care settings.
| Leading Market Players |
|---|
| Chemed Corporation (VITAS Healthcare) |
| Amedisys Inc. |
| Genesis HealthCare Corporation |
| Kindred Healthcare |
| Lifepoint Health (Gentiva Health Services) |
| Sunrise Senior Living |
| Honor Technology Inc. (Home Instead, Inc.) |
| LHC Group |
| AccentCare Inc. |
| Others |
Cost & Logistics Intelligence
Vertical integration of care providers anchors service delivery and influences pricing power in the palliative care market. This strategy allows larger entities to standardize care protocols and optimize resource allocation.
Pricing Analysis
Provider reimbursement rates critically shape pricing in palliative care, driven largely by value-based payment models from entities like CMS. The dominant pricing structure is contract-based, bundling services into daily rates for hospice or fee-for-service for specific interventions. Price differentiation stems from service intensity, such as specialized symptom management, and the care setting. Pricing pressure stems from payer demands for outcome-based metrics, with private insurance beneficiaries typically exhibiting less price sensitivity than those reliant on public programs.
Supply Chain Analysis
Single-source vulnerability sits with the specialized palliative care workforce, particularly physicians and nurses with specific certifications, creating a bottleneck across geographies. Key material dependencies include pain relief medications, sourced primarily from India and China, and specialized medical devices from Germany and the United States. A structural risk involves inconsistent payer coverage, which limits service availability and provider investment. Distribution runs through a fragmented network of home care agencies, hospices, and hospital-based outpatient clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The palliative care market acts as a stable compounder, driven by the persistent global demographic shift towards an aging population. This fundamental need ensures consistent expansion and long-term viability for providers.
For Market Incumbents: Acquire specialized home health agencies to expand geographic reach and patient-facing capacity. Large providers must integrate telehealth platforms to counter workforce shortages and enhance care coordination. Consolidate fragmented local providers to standardize care protocols and leverage economies of scale against rising operational costs. Invest in training programs to mitigate the structural deficit of certified palliative care professionals.
For New Entrants and Emerging Players: Launch via specialized non-oncology palliative programs for underserved conditions like advanced heart failure or COPD. Target rural and underserved urban areas where access to specialist consultations remains limited. Develop AI-powered patient identification tools to proactively engage suitable candidates for early intervention. Focus on developing pediatric palliative care services, leveraging community health partnerships for market entry.
For Investors and Strategic Acquirers: Roll-up economics work for home care providers and hospices because of market fragmentation and strong patient preference for home-based care. The long-term viability for investors spans a decade, driven by aging demographics and value-based care incentives. Target regional home health networks with strong local reputations and established referral pathways. A signal to watch is the consistent expansion of CMS value-based payment models to new palliative care settings.
| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Integration | Enhances access to specialist care for remote patients, overcoming geographical barriers. |
| Non-Oncology Program Development | Addresses unmet needs in chronic conditions like heart failure, broadening the patient base. |
| Workforce Training Investment | Mitigates specialist shortages and improves service quality across care settings. |
| Home Care Provider Acquisition | Expands service networks and standardizes care protocols for larger entities. |
| AI-Driven Patient Identification | Proactively identifies patients for early palliative intervention, optimizing resource allocation. |
Research Approach
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region. This report combines extensive primary interviews with industry stakeholders such as hospice administrators, palliative care physicians, and CMS policy experts. Secondary validation draws from sources including FDA filings, WHO reports, and national health ministry data. Both bottom-up and top-down triangulation methods were employed to ensure data accuracy.
Rate-of-change decomposition analyzes market expansion across the analysis window, considering historical trends and future projections. The model segments by product type, therapy area, end user, care delivery mode, and regional demographics. CAGRs were derived through a weighted average of segment-specific growth rates. Key forecast inputs include aging population statistics and healthcare expenditure trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant regulatory shifts or unforeseen public health crises. Forecasts reflect assumptions regarding reimbursement policy stability and the pace of telehealth adoption. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Radiofrequency Ablation Devices for Pain Management Market
Pain Management
Global Post Herpetic Neuralgia Treatment Market
Pain Management
Pain Relief Oil Market
Pain Management
Medical Morphine Market
Pain Management
Pain Management Therapeutics Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Arthralgia Management Market
Pain Management
Cancer Pain Market
Pain Management
Cancer Pain Management Market
Pain Management
Global Morphine Market
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
Pain Management Software Market
Pain Management
Global Postoperative Pain Management Market
Pain Management
Neuropathic Pain Market
Pain Management
Neuralgia Treatment Market
Pain Management
Postoperative Pain Market