
 Plantar Fasciitis Treatment Market | 2026-2036
Plantar Fasciitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Plantar Fasciitis Treatment Market Intelligence
Medical-grade biomechanical support is collapsing into the consumer-accessible tier, forcing incumbent manufacturers to defend specification thresholds. Bayer AG leverages its pharmaceutical portfolio to anchor pain relief medication supply across retail and clinical channels. Superfeet Worldwide Inc. differentiates through in-house production of custom-moldable orthotic geometries. Bauerfeind AG dominates European distribution of compression-based foot support systems.
Plantar fasciitis treatment encompasses interventions targeting degeneration and inflammation of the plantar fascia ligament, spanning load-distributing orthotics with durometer ratings between 40 and 70 Shore A, extracorporeal shockwave systems delivering 0.12–0.25 mJ/mm² energy flux density, and surgical release procedures for recalcitrant cases. Conservative therapy occupies the largest patient volume pool due to first-line clinical guidelines, while shockwave therapy devices represent the fastest-growing treatment mode as outpatient reimbursement expands. Orthotic devices sustain the deepest margin structure through repeat purchase cycles and direct-to-consumer channel migration.
FDA 510(k) pathways govern shockwave device commercialization in the United States, while CE marking under the EU Medical Device Regulation controls market access across European member states. Germany's KBA-equivalent medical device surveillance framework, alongside BfArM oversight, shapes orthotic prescription and reimbursement thresholds. Stakeholders must monitor evolving CMS outpatient procedure codes for extracorporeal shockwave therapy and their ripple effects on capital equipment purchasing decisions.
Market Dynamics
Extracorporeal shockwave therapy is compressing treatment timelines and shifting capital allocation from surgical suites to outpatient sports medicine facilities, forcing orthotic manufacturers to defend their repeat-purchase revenue streams against durable device alternatives.
Growth Catalysts
- CMS outpatient reimbursement expansion:New procedure codes for extracorporeal shockwave therapy in the United States are accelerating capital equipment purchases by ambulatory surgery centers and orthopedic clinics.
- Durometer-optimized materials:Advanced thermoplastic elastomers with Shore A ratings between 40 and 70 are enabling mass-customized orthotic geometries that match individual biomechanical load profiles.
- Germany:The country's dense network of orthopedic technicians and statutory health insurance coverage for prescription orthotics sustains the deepest per-capita treatment penetration in Europe.
Market Restraints
- Medical-grade silicone volatility:Input cost swings for platinum-cured silicone sheets used in custom orthotic fabrication compress margins for small-batch manufacturers.
- Shockwave device concentration:Three European equipment suppliers control over 80% of extracorporeal shockwave system production, creating procurement bottlenecks for North American distributors.
- Energy flux density ceiling:FDA 510(k) clearance thresholds cap maximum therapeutic output at 0.25 mJ/mm², limiting treatment efficacy for recalcitrant plantar fascia cases.
Strategic Opportunities
- Direct-to-consumer channel migration:Telehealth-integrated foot scanning apps are opening bypass routes around traditional podiatric prescription workflows.
- Japan:PMDA's accelerated review pathway for Class II orthopedic devices reduces time-to-market for next-generation shockwave systems by 40% versus standard routes.
- Hybrid orthotic-shockwave protocols:Converging mechanical support with acoustic wave stimulation is creating bundled reimbursement opportunities in integrated care networks.
Industry Challenges
- Biomechanical modeling talent scarcity:The shortage of engineers trained in patient-specific finite element analysis delays custom orthotic design cycles.
- CE marking timeline compression:EU Medical Device Regulation technical documentation requirements are extending conformity assessment durations for novel orthotic materials.
- Legacy EHR integration:Shockwave therapy outcome tracking systems require expensive middleware development to connect with hospital enterprise platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plantar Fasciitis Treatment Market |
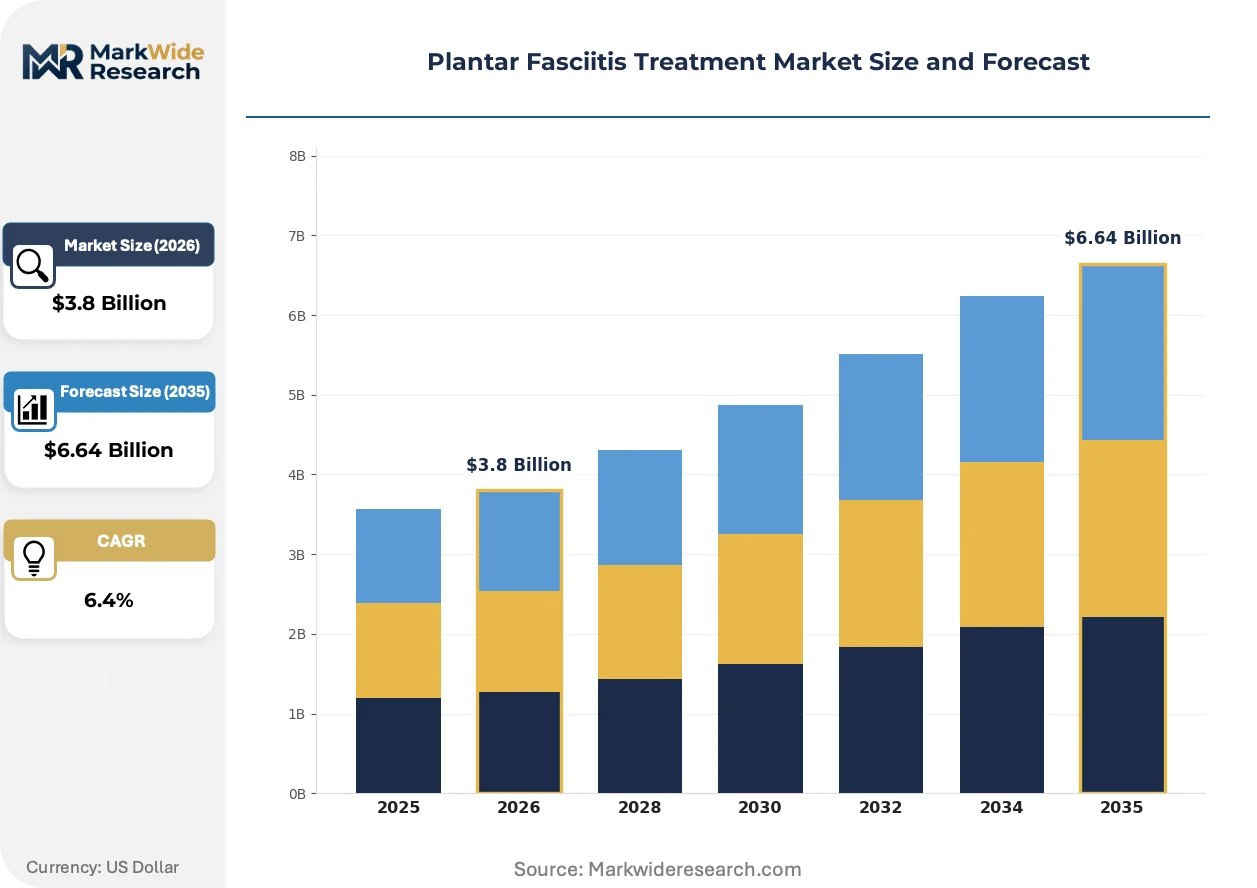
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthotic Devices, Footwear, Physiotherapy Equipment, Shockwave Therapy Devices, Surgical Instruments Therapy Area: Pain Relief, Inflammation Reduction, Tissue Repair, Mobility Enhancement, Biomechanical Support End User: Specialty Clinics, Rehabilitation Centers, Ambulatory Services, Sports Medicine Facilities, Physiotherapy Practices Treatment Mode: Conservative Therapy, Minimally Invasive Procedures, Surgical Interventions, Extracorporeal Shockwave Therapy, Night Splinting |
| Companies Covered | Bayer AG, Superfeet Worldwide Inc., Bauerfeind AG, Ottobock SE & Co. KGaA, Pfizer Inc., A. Algeo Limited, Hanger Inc., Shapecrunch Technology Pvt. Ltd., 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plantar Fasciitis Treatment Market Strategic Shifts & Innovations
Digital foot mapping and additive manufacturing are collapsing the traditional boundary between clinical-grade and consumer-accessible orthotic solutions, compressing specification hierarchies that once separated prescription devices from retail inserts.
Radial pressure wave technology is fragmenting the shockwave therapy device landscape. Sports medicine clinics in the United States are adopting lower-cost radial systems for first-line plantar fasciitis cases, displacing premium-focused distributors and enabling mid-tier equipment suppliers to capture outpatient volume previously reserved for hospital-grade focused shockwave platforms.
EU Medical Device Regulation technical documentation requirements are reshaping orthotic commercialization pathways. Manufacturers must now submit clinical evaluation reports for even Class I devices, extending time-to-market and favoring larger competitors with dedicated regulatory affairs functions over small-batch German and Italian orthotic workshops.
Subscription-based orthotic replacement programs are displacing single-transaction retail models. Direct-to-consumer brands in the United States are capturing recurring revenue through annual replacement guarantees, while traditional podiatric supply houses in Germany resist this shift due to statutory insurance reimbursement structures that favor durable medical equipment classification over consumable service contracts.
Plantar Fasciitis Treatment Market Segmentation
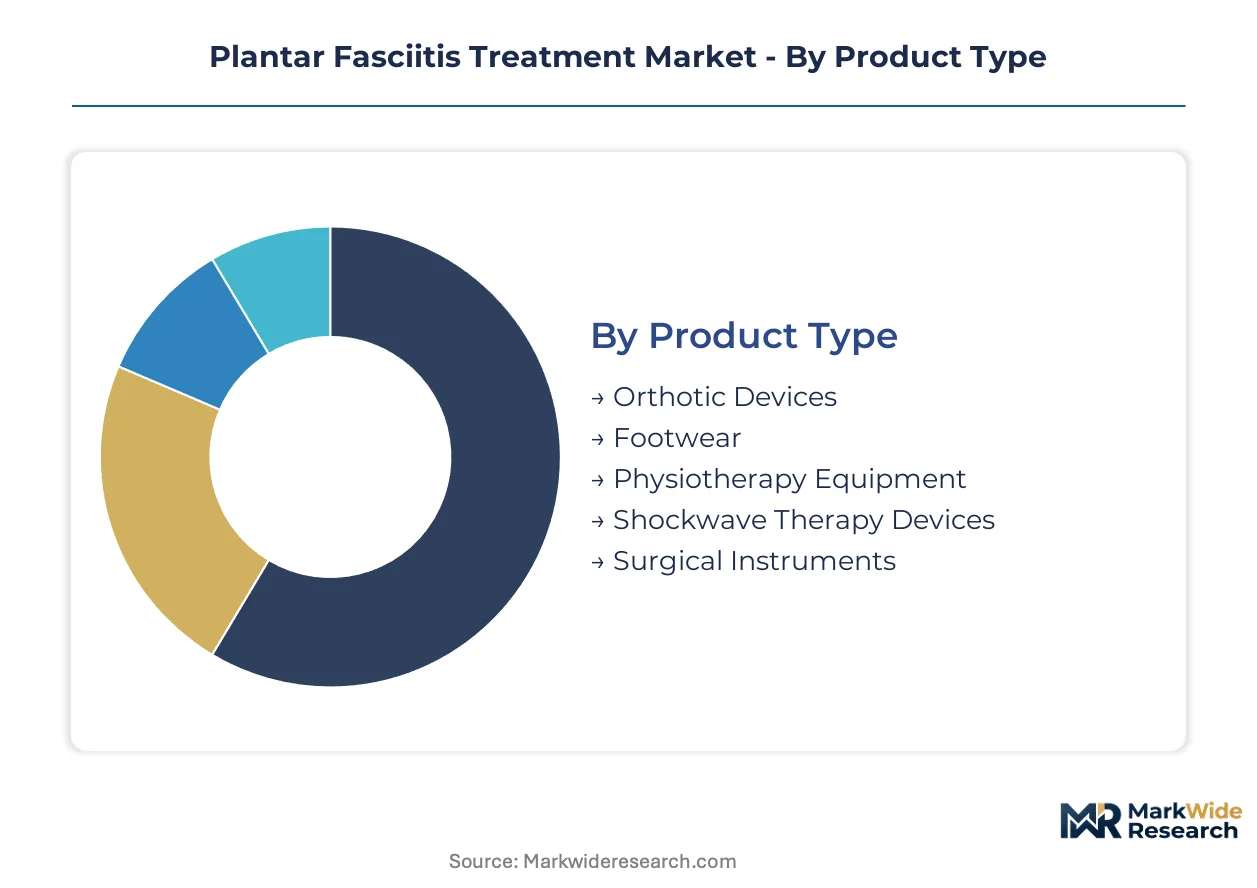
Treatment mode and product specifications in plantar fasciitis care diverge sharply between reimbursed clinical pathways and direct-to-consumer channels. Understanding where each segment concentrates geographically reveals procurement bottlenecks and margin structure differences.
Product Type:
Orthotic devices and shockwave systems split between domestic prescription fulfillment and export-led capital equipment sales, with manufacturing clusters in Germany and the United States serving distinct demand pools.
- Orthotic Devices:Load-distributing inserts fabricated from thermoplastic elastomers with Shore A durometer ratings between 40 and 70 dominate prescription volume in Germany's statutory health insurance system. Bauerfeind AG and Ottobock SE anchor European supply, while U.S. direct-to-consumer brands bypass podiatric workflows through telehealth-integrated foot scanning.
- Shockwave Therapy Devices:Extracorporeal systems delivering 0.12–0.25 mJ/mm² energy flux density concentrate production among three European equipment suppliers, creating procurement bottlenecks for North American distributors. FDA 510(k) clearance pathways govern U.S. commercialization, while CE marking under EU MDR controls European access.
- Footwear:Motion-control and stability designs with medial posting and heel counters target retail consumers seeking biomechanical support without prescription delays.
- Physiotherapy Equipment:Stretching bands, cold therapy systems, and massage rollers serve home-based conservative treatment protocols.
- Surgical Instruments:Endoscopic plantar fascia release tools and open heel spur resection kits address recalcitrant cases failing conservative management.
Orthotic devices hold the largest share; momentum sits with shockwave therapy devices.
Therapy Area:
Cost tier stratification separates premium reimbursed interventions from retail-accessible symptom management, with tissue repair commanding the highest per-procedure reimbursement.
- Pain Relief:Topical NSAIDs, oral analgesics, and corticosteroid injections anchor first-line clinical protocols. Bayer AG's pharmaceutical portfolio supplies retail and clinical channels across North America and Europe.
- Tissue Repair:Extracorporeal shockwave therapy triggers neovascularization and collagen remodeling in degenerated plantar fascia. CMS outpatient reimbursement expansion in the United States accelerates capital equipment deployment.
- Inflammation Reduction:Cryotherapy and anti-inflammatory pharmacology address acute symptom flares.
- Mobility Enhancement:Gait training and range-of-motion protocols restore functional capacity.
- Biomechanical Support:Custom-moldable orthotic geometries from Superfeet Worldwide Inc. match individual load profiles through in-house production.
Pain relief captures the deepest patient volume; tissue repair climbs the fastest on expanded outpatient reimbursement.
End User:
Volume concentration shifts toward ambulatory settings as shockwave therapy compresses treatment timelines away from hospital surgical suites.
- Specialty Clinics:Podiatric and orthopedic practices in Germany's dense network of orthopedic technicians generate prescription orthotic volume sustained by statutory insurance coverage.
- Sports Medicine Facilities:U.S. outpatient centers adopt lower-cost radial pressure wave systems for first-line cases, displacing premium-focused distributors.
- Rehabilitation Centers:Structured physiotherapy protocols address post-surgical recovery and chronic case management.
- Ambulatory Services:Same-day procedure centers capture shockwave therapy volume previously reserved for hospital-grade focused platforms.
- Physiotherapy Practices:Independent practitioners deliver conservative care through manual therapy and exercise prescription.
Specialty clinics retain the largest share; sports medicine facilities gain share fastest on radial system adoption.
Treatment Mode:
Maturity differentiation separates established conservative protocols from emerging device-based alternatives, with reimbursement status determining geographic penetration depth.
- Conservative Therapy:Orthotics, stretching, and activity modification occupy the largest patient pool per first-line clinical guidelines. Repeat purchase cycles sustain margin structure through direct-to-consumer channel migration.
- Extracorporeal Shockwave Therapy:Outpatient reimbursement expansion in the United States and Japan's PMDA accelerated review pathway compress time-to-market for next-generation systems.
- Minimally Invasive Procedures:Ultrasound-guided fascial release and percutaneous needle tenotomy address intermediate severity cases.
- Surgical Interventions:Open or endoscopic plantar fascia release reserved for recalcitrant cases failing twelve months of conservative management.
- Night Splinting:Passive dorsiflexion devices maintain tissue elongation during sleep.
Conservative therapy holds the largest share; extracorporeal shockwave therapy shows the steepest expansion trajectory on capital equipment deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three European equipment suppliers control over 80% of extracorporeal shockwave system production, creating procurement bottlenecks for North American distributors while Germany's dense orthopedic technician network sustains the deepest per-capita treatment penetration in Europe.
United States
CMS outpatient reimbursement expansion for extracorporeal shockwave therapy accelerates capital equipment purchases by ambulatory surgery centers and orthopedic clinics. FDA 510(k) clearance pathways govern device commercialization with energy flux density capped at 0.25 mJ/mm². Sports medicine facilities in Florida and Arizona adopt lower-cost radial pressure wave systems for first-line cases.
Germany
Bauerfeind AG and Ottobock SE maintain strong orthotic manufacturing bases sustained by statutory health insurance coverage for prescription devices. BfArM oversight shapes orthotic prescription thresholds alongside KBA-equivalent medical device surveillance. The Bavaria and North Rhine-Westphalia regions concentrate production of compression-based foot support systems.
Japan
PMDA's accelerated review pathway for Class II orthopedic devices reduces time-to-market for next-generation shockwave systems by 40% versus standard routes. METI industrial policy supports medical device export competitiveness. The Kanto region around Tokyo anchors domestic distribution networks for physiotherapy equipment.
China
NMPA regulatory harmonization with international standards streamlines market entry for foreign orthotic manufacturers. MIIT industrial upgrading programs target advanced medical device localization. The Yangtze River Delta manufacturing corridor scales production of thermoplastic elastomer components for export markets.
United Kingdom
NHS commissioning frameworks prioritize conservative therapy protocols for plantar fasciitis, sustaining orthotic prescription volume through podiatric services. MHRA post-Brexit regulatory autonomy maintains CE marking recognition during transition periods. The Southeast England cluster concentrates digital health startups developing telehealth-integrated foot scanning applications.
Plantar Fasciitis Treatment Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the plantar fasciitis treatment landscape. The market structures around three tiers: pharmaceutical incumbents with analgesic portfolios, specialized orthotic fabricators with prescription channel access, and medical device suppliers with regulatory-cleared shockwave platforms. Dominant competitive moves include direct-to-consumer channel migration bypassing traditional podiatric workflows and hybrid protocol bundling that combines mechanical support with acoustic wave stimulation.
Among diversified healthcare conglomerates, Bayer AG and 3M exemplify archetypes that anchor pain relief medication supply across retail and clinical channels. Within the specialized orthotic tier, Bauerfeind AG occupies a position representing European prescription-grade manufacturing depth, while Superfeet Worldwide Inc. exemplifies the direct-to-consumer vector with in-house production capabilities. These three named entities collectively illustrate how competitive positioning fragments across pharmaceutical, clinical-device, and consumer-accessible domains.
| Leading Market Players |
|---|
| Bayer AG |
| Superfeet Worldwide Inc. |
| Bauerfeind AG |
| Ottobock SE & Co. KGaA |
| Pfizer Inc. |
| A. Algeo Limited |
| Hanger Inc. |
| Shapecrunch Technology Pvt. Ltd. |
| 3M |
| Others |
Cost & Logistics Intelligence
Platinum-cured silicone sheet production at three German and Italian workshops anchors orthotic manufacturing scale, compressing unit costs for thermoplastic elastomer components while concentrating price-setting power among volume-capable fabricators serving statutory insurance channels.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across shockwave therapy devices, separating hospital-grade focused systems from radial pressure wave alternatives adopted by sports medicine facilities. Price differentiation rests on energy flux density certification levels and CMS reimbursement eligibility rather than hardware cost alone. Pricing pressure intensifies in the direct-to-consumer orthotic tier as telehealth-integrated foot scanning apps bypass podiatric prescription workflows. Hospital purchasing committees demonstrate lowest price sensitivity due to bundled reimbursement protocols, while independent physiotherapy practices face acute cost compression from capital equipment leasing requirements.
Supply Chain Analysis
Rotterdam port congestion and Rhine water level volatility intermittently choke thermoplastic elastomer feedstock deliveries from BASF Ludwigshafen to orthotic fabricators across Bavaria. Manufacturing concentration in Germany, China, and the United States draws from platinum-cured silicone sheets, Shore A-rated TPE compounds, and piezoelectric shockwave generator crystals. Single-source vulnerability pervades the piezoelectric component tier where three European equipment suppliers control focused shockwave system production. Distribution runs through orthopedic technician networks in Germany, GPO contracts in the United States, and hospital procurement consortia in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA 510(k) and EU MDR certification creates formidable defensive moats for incumbent orthotic and shockwave device manufacturers, with switching costs locking hospital systems into validated supplier relationships.
For Market Incumbents: Fortify prescription channel control by deepening relationships with Germany's statutory health insurance funds and securing exclusive GPO contracts with U.S. ambulatory surgery centers. Invest in backward integration into platinum-cured silicone sheet production to offset raw material volatility threatening small-batch margin structures. Counter radial pressure wave entrants by bundling diagnostic imaging with shockwave therapy protocols in integrated care networks. For New Entrants and Emerging Players: Japan's PMDA accelerated review pathway for Class II orthopedic devices offers the most penetrable regulatory entry point, reducing time-to-market by forty percent versus standard routes. Target the direct-to-consumer orthotic segment through telehealth-integrated foot scanning applications that bypass traditional podiatric prescription workflows. Pursue white-label manufacturing partnerships with Yangtze River Delta TPE component suppliers to achieve cost parity with established brands. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid protocol developers combining mechanical support with acoustic wave stimulation in bundled reimbursement arrangements. Long-term viability hinges on capturing outpatient volume migration from hospital surgical suites to ambulatory settings. Monitor CMS outpatient procedure code expansions for extracorporeal shockwave therapy as the primary inflection signal for capital equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements extend conformity assessment durations, favoring dedicated regulatory affairs functions. |
| Hospital System Partnership | GPO contract consolidation in the United States locks in multi-year shockwave device procurement commitments. |
| Software Companion Development | Telehealth-integrated foot scanning apps enable direct-to-consumer channel migration bypassing podiatric workflows. |
| Reimbursement Strategy | CMS outpatient procedure code expansion accelerates capital equipment purchases by ambulatory surgery centers. |
| Backward Integration | In-house platinum-cured silicone sheet production insulates margins from raw material volatility. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, CMS reimbursement databases, and hospital procurement records. Conversations with orthopedic surgeons, podiatric clinicians, biomedical engineers, GPO contracts managers, and shockwave device distributors informed demand-side validation. Supply-side perspectives drew from regulatory affairs leads at orthotic manufacturers and procurement directors at sports medicine facilities. Bottom-up patient volume estimates triangulated against top-down capital equipment shipment data.
Segmentation dimensions modeled include treatment mode, product type specifications, therapy area, and end-user facility category across the projection horizon. CAGRs derive from patient incidence modeling, reimbursement trajectory analysis, and equipment replacement cycle assumptions. Shockwave therapy device forecasts incorporate PMDA accelerated review pathway adoption rates and radial versus focused system mix shifts. Orthotic demand projections weight statutory insurance coverage depth against direct-to-consumer channel penetration.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement expansion, stable platinum-cured silicone input costs, and continued EU MDR regulatory harmonization would require recalibration. Forecasts assume current FDA energy flux density ceilings and statutory health insurance orthotic coverage frameworks. Practitioners should keep alternative scenarios live as outpatient procedure code valuations and medical device surveillance protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Medicated Pain Relieving Plasters Market
Pain Management
Global Fibromyalgia Treatment Market
Pain Management
Pain Management Software Market
Pain Management
Cold Pain Therapy Market
Pain Management
Global Visceral Pain Treatment Market
Pain Management
Pain Relievers for Teeth Market
Pain Management
Cluster Headache Market
Pain Management
Pain Management Therapeutics Market
Pain Management
Postoperative Pain Market
Pain Management
Dyspareunia Market
Pain Management
Pain Patches Market
Pain Management
Neuralgia Treatment Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Over-The-Counter Pain Medication Market
Pain Management
Arthralgia Management Market
Pain Management
OTC Painkiller Market