
 Neuropathic Pain Market | 2026-2036
Neuropathic Pain Market Size, Share, and Industry Trends Forecast 2026-2036
Neuropathic Pain Market Intelligence
Public health mandates aimed at reducing opioid dependence, such as those from the US Department of Health and Human Services, is consolidating focus onto safer, long-term neuropathic pain therapies. Pfizer Inc. leverages its extensive neurology pipeline and global commercial infrastructure to address diabetic neuropathy. Eli Lilly and Company competes with novel antidepressants that have demonstrated efficacy in pain modulation and comorbid depression. Novartis AG specializes in targeted agents for less common indications like trigeminal neuralgia.
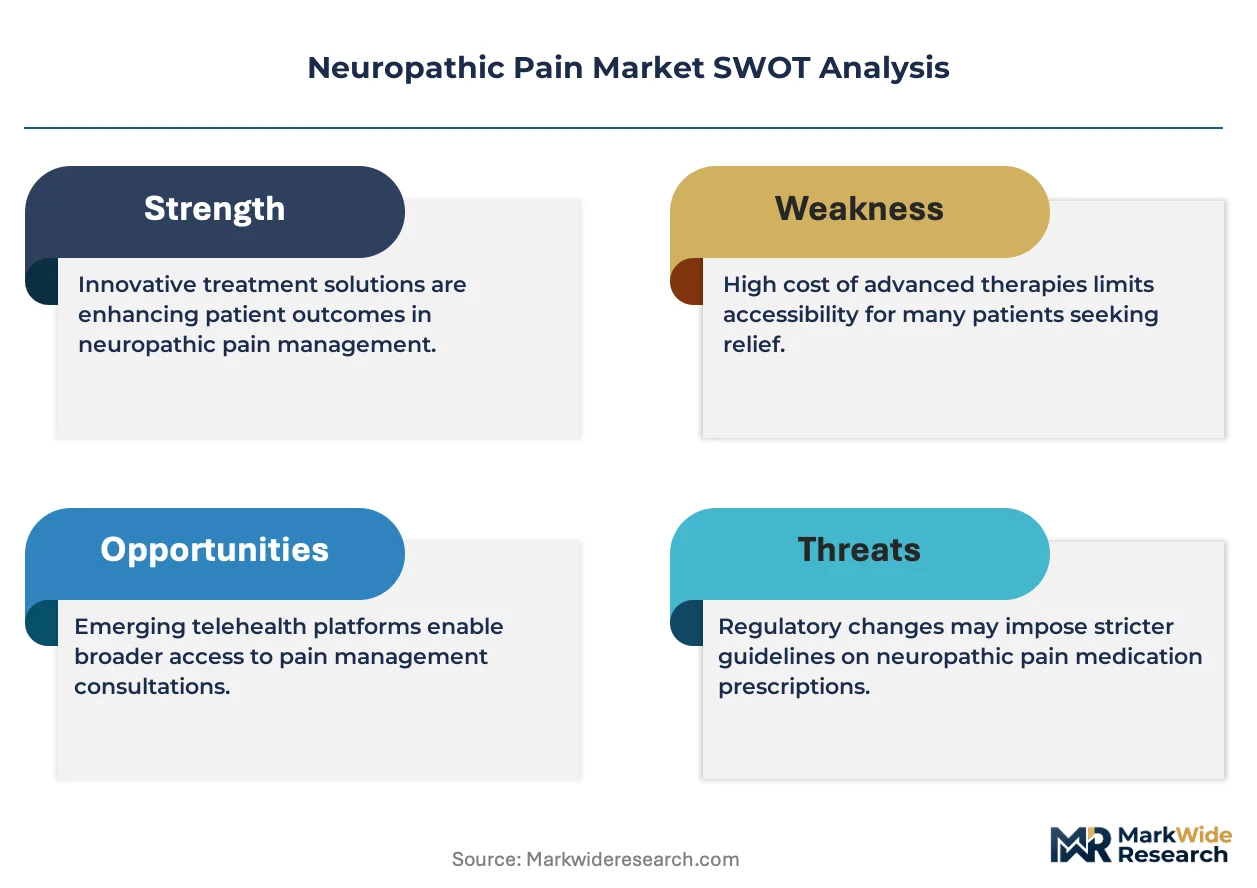
Neuropathic pain treatments are interventions targeting chronic pain that originates from damage or disease within the somatosensory nervous system. These therapies function by modulating specific neurotransmitter pathways or ion channels to interrupt abnormal pain signals at the source. Anticonvulsants and antidepressants constitute the largest product segments, often prescribed as first-line treatments under established clinical guidelines. Diabetic neuropathy represents the fastest-growing therapy area, with hospitals serving as the primary end-user for initial diagnosis and acute care.
Market access is governed by stringent clinical trial requirements for efficacy and safety, overseen by regulators like the US FDA and the European Medicines Agency (EMA). In Japan, the PMDA's approval pathways and reimbursement policies directly influence the commercial viability of new pain management technologies. The critical strategic decision for developers is balancing investment between broad-spectrum analgesics and highly targeted, orphan-indication therapies.
Market Dynamics
Public health initiatives, particularly those from agencies like the US Department of Health and Human Services, are compelling a structural shift away from opioid-based pain management. This pressure accelerates R&D investment into non-addictive, long-term neuropathic pain therapies.
Growth Catalysts
- Abuse-Deterrent Guidance:FDA policies promoting abuse-deterrent formulations stimulate R&D for non-opioid analgesics, creating pathways for therapies with superior safety profiles.
- Aging Demographics:The rising prevalence of chronic conditions like postherpetic neuralgia in aging populations, particularly in Japan and Germany, expands the addressable patient base.
- Clinical Setting Expansion:Hospitals and specialty clinics are broadening the application of neuropathic pain treatments for post-surgical management, solidifying a key end-user segment.
Market Restraints
- Clinical Trial Complexity:Strict efficacy and safety mandates from the FDA and EMA result in prolonged, expensive clinical trials, acting as a significant barrier to entry.
- Adverse Effect Profiles:The side effects of first-line treatments, including anticonvulsants and antidepressants, frequently result in poor patient compliance and treatment discontinuation.
- Reimbursement Constraints:Navigating Japan's PMDA reimbursement policies for new pain technologies presents a commercial viability challenge for developers targeting that market.
Strategic Opportunities
- Digital Therapeutics Integration:The convergence of drug therapies with digital health platforms for patient monitoring and adherence offers a new avenue for outcome improvement.
- Orphan Indication Focus:Developing targeted agents for less common conditions like trigeminal neuralgia provides a path to enter high-value, niche therapeutic areas.
- Post-Surgical Pain Management:A significant opportunity exists in developing non-opioid analgesics specifically for acute post-operative neuropathic pain within hospital settings.
Industry Challenges
- Patient Stratification Complexity:Accurately diagnosing and stratifying patients based on the underlying pathophysiology of their neuropathic pain remains a significant clinical challenge, hindering personalized treatment.
- High Placebo Response Rates:The consistently high placebo response rates observed in clinical trials for pain make it difficult to demonstrate a drug's true efficacy, complicating regulatory approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuropathic Pain Market |
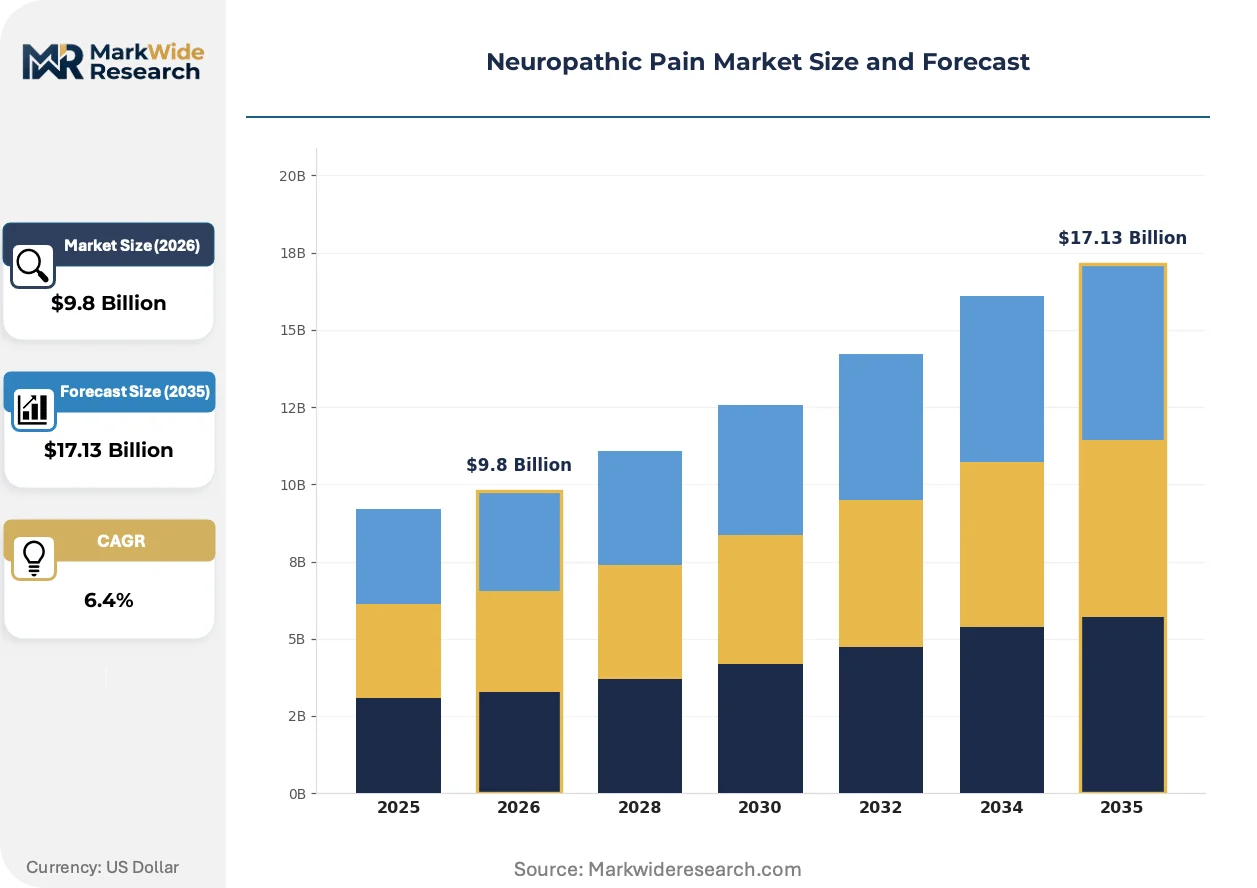
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticonvulsants, Antidepressants, Topical Analgesics, Opioids, Nonsteroidal Anti-Inflammatory Drugs, Capsaicin Creams Therapy Area: Diabetic Neuropathy, Postherpetic Neuralgia, Trigeminal Neuralgia, Chemotherapy-Induced Neuropathy, Phantom Limb Pain, Radiculopathy End User: Hospitals, Specialty Clinics, Pain Management Centers, Ambulatory Surgical Centers, Home Healthcare Providers, Rehabilitation Facilities Delivery Mode: Oral, Topical, Transdermal, Intravenous, Subcutaneous, Epidural |
| Companies Covered | Pfizer Inc., Eli Lilly and Company, Novartis AG, Johnson & Johnson Services, Inc., Abbott, Medtronic, Teva Pharmaceutical Industries Ltd., GlaxoSmithKline PLC, Astellas Pharma Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuropathic Pain Market Strategic Shifts & Innovations
A fundamental shift toward precision and safety is moving the market beyond broad-spectrum analgesics. This evolution is driven by new therapeutic modalities and regulatory frameworks prioritizing patient-specific outcomes and risk mitigation over generalized pain suppression.
Targeted gene therapies and monoclonal antibodies represent a new treatment class, designed to modulate specific ion channels or inflammatory pathways. Pharmaceutical developers are advancing these biologics through clinical trials, targeting patient populations with specific genetic markers. This precision approach is integrating principles of personalized medicine into pain management, moving away from older one-size-fits-all models.
The European Medicines Agency (EMA) increasingly emphasizes real-world evidence (RWE) in its evaluation of new pain therapies. This shift requires developers to collect data from patient registries to support long-term effectiveness claims post-approval. Antidepressant and anticonvulsant segments are most affected, as firms must generate RWE to defend market access.
Hospital formularies and specialty clinics exhibit a notable shift in purchasing criteria, prioritizing total cost of care over acquisition price. This value-based approach favors therapies that reduce readmissions, displacing drugs with higher side-effect management costs. The trend is most visible in the US and Germany, where integrated health systems track long-term outcomes.
Neuropathic Pain Market Segmentation
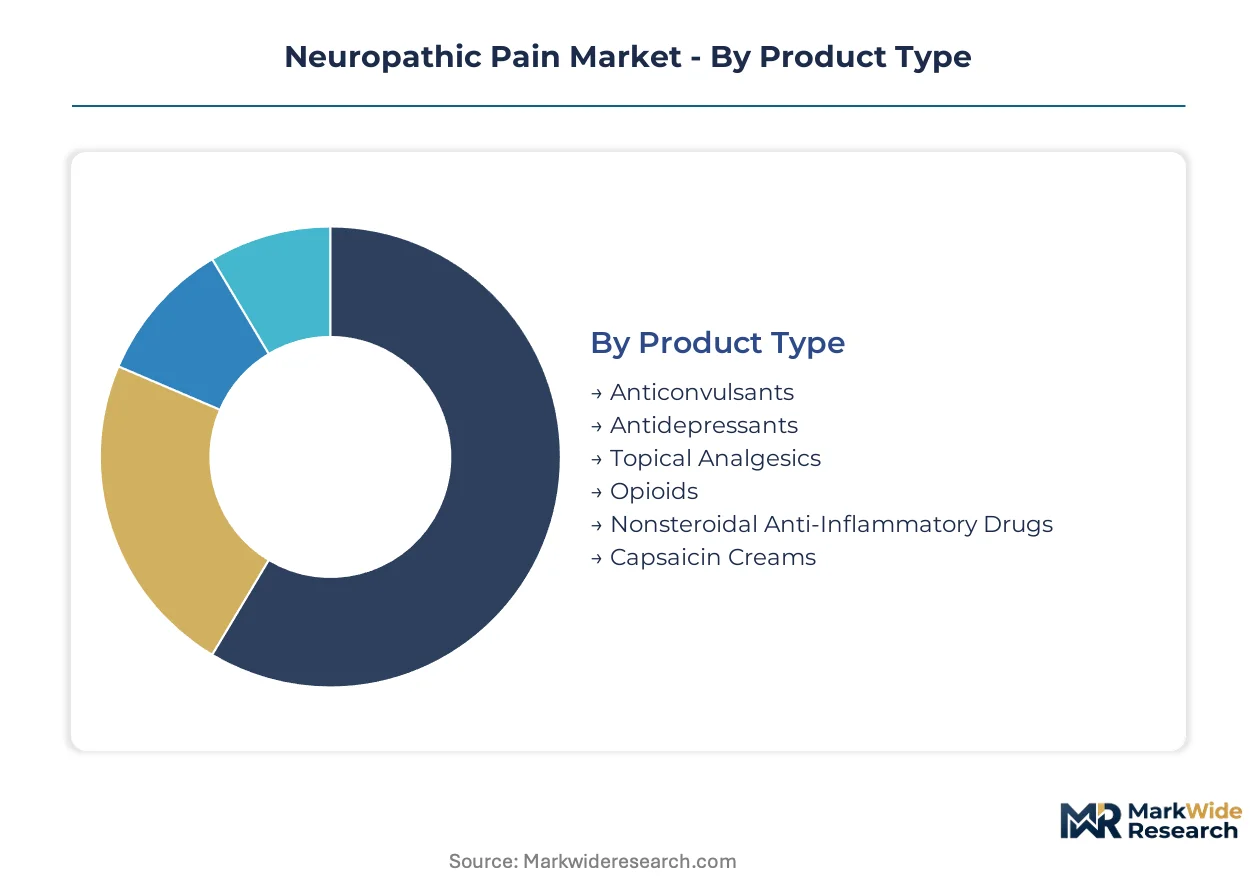
Understanding the Neuropathic Pain Market through detailed segmentation offers crucial insights into therapeutic development and commercial strategy. This granular breakdown helps stakeholders identify specific patient populations, preferred treatment modalities, and key points of care for intervention.
Product Type:
Product type segmentation reveals how various therapeutic agents function as either standalone treatments or integrated components within broader pain management protocols.
- Anticonvulsants:These agents stabilize hyperexcited nerve membranes by modulating voltage-gated ion channels, reducing abnormal neuronal firing. Demand concentrates in primary care settings for initial management of generalized neuropathic pain.
- Antidepressants:Tricyclic antidepressants and serotonin-norepinephrine reuptake inhibitors modulate pain pathways by increasing neurotransmitter levels in the spinal cord. Demand is significant in specialty clinics addressing comorbid depression.
- Topical Analgesics:These formulations deliver pain relief directly to localized areas, minimizing systemic side effects.
- Opioids:Potent analgesics bind to opioid receptors in the central nervous system, used for severe, refractory pain.
- Nonsteroidal Anti-Inflammatory Drugs:NSAIDs reduce inflammation and pain through cyclooxygenase enzyme inhibition, primarily for inflammatory components.
- Capsaicin Creams:These topical agents desensitize nerve endings by depleting substance P, targeting localized neuropathic pain.
Anticonvulsants lead volumes today; antidepressants are gaining share fastest.
Therapy Area:
Therapy area segmentation highlights the specific clinical conditions driving demand for specialized neuropathic pain interventions.
- Diabetic Neuropathy:This condition results from nerve damage due to high blood glucose, manifesting as pain, numbness, and tingling. Demand is expanding rapidly in hospital settings due to rising global diabetes prevalence.
- Postherpetic Neuralgia:Persistent nerve pain follows a shingles outbreak, often characterized by burning and shooting sensations. Geriatric populations, particularly in Germany and Japan, show high demand.
- Trigeminal Neuralgia:Characterized by severe facial pain, this condition requires highly targeted interventions for effective management.
- Chemotherapy-Induced Neuropathy:Nerve damage caused by cancer treatments leads to chronic pain, necessitating specialized supportive care.
- Phantom Limb Pain:Persistent pain perceived in an absent limb presents a complex challenge for pain management centers.
- Radiculopathy:Nerve root compression causes pain, numbness, or weakness, often managed with a combination of therapies.
Diabetic neuropathy exhibits the steepest expansion trajectory, while postherpetic neuralgia maintains significant volume.
End User:
End user segmentation delineates the primary care settings delivering neuropathic pain treatments across the patient care continuum.
- Hospitals:These institutions provide initial diagnosis, acute pain management, and complex interventional procedures for severe neuropathic conditions. Demand concentrates for post-surgical pain management and acute exacerbations.
- Specialty Clinics:Clinics focusing on neurology or pain management offer specialized diagnostics, advanced therapies, and long-term patient follow-up. These clinics are critical for managing chronic conditions.
- Pain Management Centers:These dedicated centers offer multidisciplinary approaches, including interventional procedures and rehabilitation services.
- Ambulatory Surgical Centers:ASCs perform outpatient procedures for specific neuropathic pain interventions, emphasizing cost-effectiveness.
- Home Healthcare Providers:These providers deliver ongoing care and medication management, supporting patients with chronic neuropathic pain at home.
- Rehabilitation Facilities:Facilities focus on physical therapy and functional restoration for patients recovering from nerve injuries or chronic pain.
Hospitals represent the largest end-user segment, with specialty clinics demonstrating robust growth in chronic care.
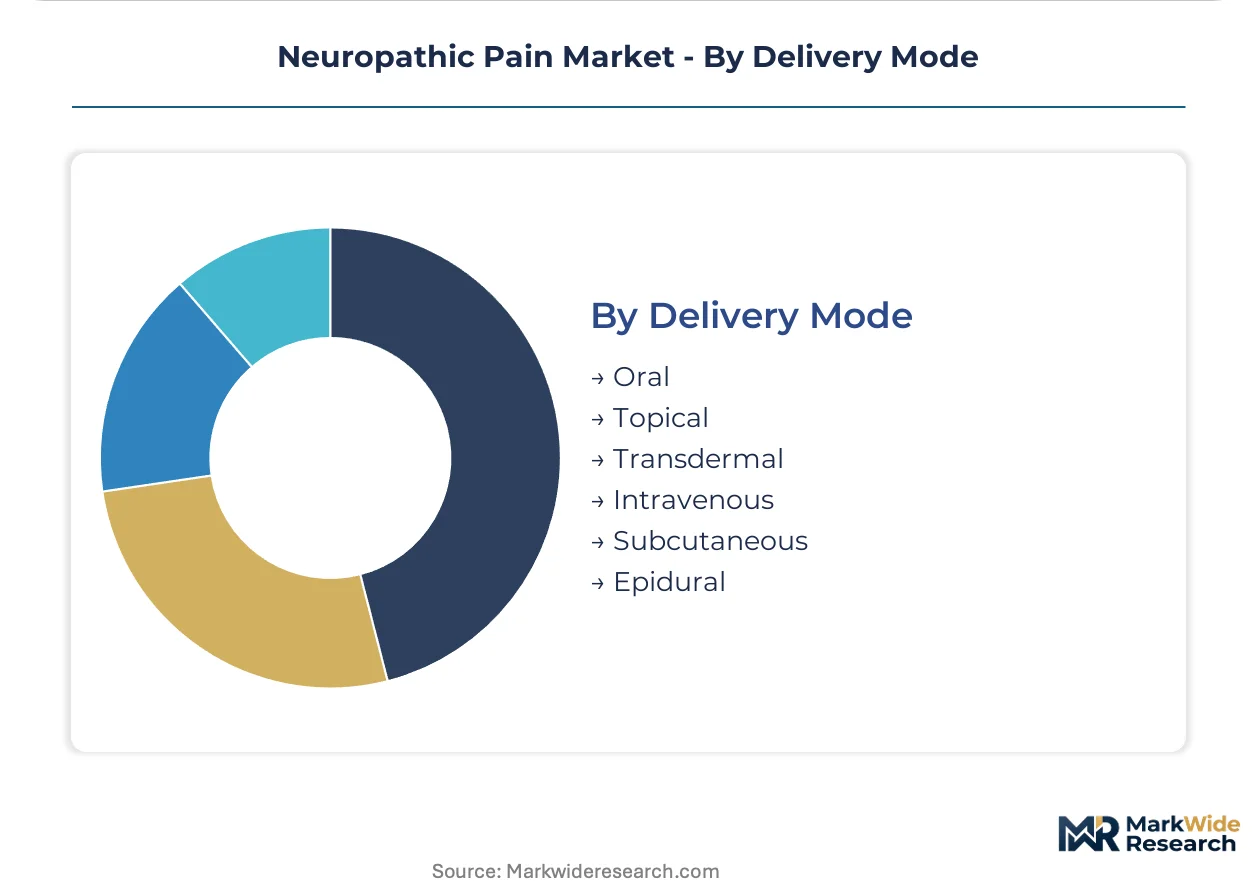
Delivery Mode:
Delivery mode segmentation illustrates the diverse physiological targeting strategies employed for administering neuropathic pain therapies.
- Oral:This common route offers convenience and systemic drug delivery, suitable for many first-line anticonvulsants and antidepressants. Patient adherence remains a critical factor.
- Topical:Applied directly to the skin, topical agents provide localized pain relief with minimal systemic absorption, reducing adverse effects. Demand is significant for postherpetic neuralgia.
- Transdermal:Patches deliver continuous drug release through the skin into the bloodstream, offering sustained systemic effects.
- Intravenous:IV administration provides rapid systemic drug delivery, typically reserved for acute pain crises or hospital settings.
- Subcutaneous:Injections beneath the skin allow for slower absorption and can be self-administered for specific therapies.
- Epidural:Direct delivery into the epidural space targets spinal nerves, providing localized analgesia for severe radicular pain.
Oral delivery remains the most prevalent mode, while topical applications are gaining traction for localized treatment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The neuropathic pain market's foundational developments largely originated in Western economies, particularly within pharmaceutical research hubs that pioneered early analgesic and neurological therapies. These regions established the initial frameworks for clinical trials and regulatory oversight, influencing subsequent global therapeutic advancements. This historical trajectory continues to shape market growth and regulatory approaches across key geographies.
United States
Demand for neuropathic pain treatments in the United States stems from high diabetes prevalence and an aging population requiring post-herpetic neuralgia management. The US Department of Health and Human Services drives mandates to reduce opioid dependence, promoting non-addictive pain therapies. Pharmaceutical R&D in Boston's biotech corridor focuses on novel non-opioid analgesics and targeted biologics.
Germany
Germany's market for neuropathic pain therapies is propelled by an aging demographic and advanced healthcare infrastructure supporting chronic pain management. The European Medicines Agency (EMA) emphasizes real-world evidence for new pain therapies, impacting market access for anticonvulsants. Munich and Berlin serve as key centers for clinical research and specialty pain clinics.
Japan
Japan exhibits significant demand for neuropathic pain treatments due to its rapidly aging population and high incidence of postherpetic neuralgia. The Pharmaceuticals and Medical Devices Agency (PMDA) approval pathways and reimbursement policies directly influence commercial viability for new pain management technologies. Tokyo's medical technology clusters advance digital therapeutics integrated with drug regimens.
United Kingdom
Chronic pain conditions, including diabetic neuropathy and chemotherapy-induced neuropathy, drive treatment demand across the United Kingdom. The National Institute for Health and Care Excellence (NICE) guidelines influence prescribing patterns, favoring evidence-based and cost-effective therapies. London's academic medical centers are central to clinical trials for targeted gene therapies.
France
France's neuropathic pain market gains momentum from increasing awareness of trigeminal neuralgia and phantom limb pain. The Agence Nationale de Sécurité du Médicament et des produits de santé (ANSM) regulates market entry, ensuring stringent efficacy and safety standards for new treatments. Paris hosts numerous specialty clinics and research institutions focused on advanced pain modulation.
Neuropathic Pain Market Key Industry Players
Premium-margin players sit above commodity-margin players across therapeutic innovation and specialized treatment areas within the neuropathic pain market. This landscape is tiered and highly specialized, reflecting varying investment levels in R&D and market access capabilities. The structural shift away from opioid-based pain management further influences this competitive dynamic. Large pharmaceutical conglomerates, biotech innovators, and niche specialty developers represent distinct strategic archetypes. Companies engage in strategic partnerships to expand their neurology pipelines and pursue portfolio diversification through non-opioid analgesic development.
Within the large pharmaceutical conglomerate archetype, Pfizer Inc. exemplifies extensive neurology pipeline development and global commercial infrastructure. Eli Lilly and Company, an Indianapolis-based pharmaceutical firm, occupies a position focused on novel antidepressants with efficacy in pain modulation. Novartis AG, a Swiss multinational pharmaceutical company, sits within the specialized segment, focusing on targeted agents for less common indications like trigeminal neuralgia. These entities anchor significant R&D investment into non-addictive, long-term neuropathic pain therapies.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Eli Lilly and Company |
| Novartis AG |
| Johnson & Johnson Services, Inc. |
| Abbott |
| Medtronic |
| Teva Pharmaceutical Industries Ltd. |
| GlaxoSmithKline PLC |
| Astellas Pharma Inc. |
| Others |
Cost & Logistics Intelligence
The cost of active pharmaceutical ingredients (APIs) for complex neurologics reflects global manufacturing inputs, cascading into tiered pricing across neuropathic pain therapies. This dynamic influences both product development costs and market access strategies for new treatments.
Pricing Analysis
Value-based pricing models increasingly govern formulary decisions for neuropathic pain treatments, prioritizing therapies demonstrating superior long-term patient outcomes. Price differentiation stems from clinical efficacy, safety profiles, and novel mechanisms of action, especially for targeted biologics. Pricing pressure stems from public health mandates to reduce opioid dependence, compelling a shift towards non-addictive alternatives. Hospitals and specialty clinics exhibit lower price sensitivity for therapies that reduce readmissions and overall treatment costs.
Supply Chain Analysis
Dual-sourcing requirements for critical active pharmaceutical ingredients (APIs) aim to mitigate supply disruptions across the neuropathic pain market. Geographic supply concentration for these complex APIs often centers in India and China, creating dependencies. Key raw material dependencies include specialized excipients and biologics manufacturing components, essential for advanced therapies. Single-source vulnerability for novel biologics represents a structural risk within this supply chain. Distribution runs through established hospital formularies and specialty pharmacy networks for patient access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The neuropathic pain market acts as a regulatory compounder, with FDA guidance on abuse-deterrent formulations driving demand for non-opioid analgesics. This regulatory push creates a fertile ground for innovation and strategic investment.
For Market Incumbents: To counter the structural shift away from opioid-based pain management, incumbents must accelerate R&D investment into novel non-addictive therapies. Leveraging extensive neurology pipelines and global commercial infrastructure will facilitate rapid market penetration for new treatments. Strategic partnerships can diversify portfolios, addressing specific therapy areas like diabetic neuropathy. Capacity expansion in biologics manufacturing will secure future supply for advanced agents.
For New Entrants and Emerging Players: Enter via targeted orphan indications like trigeminal neuralgia, offering high-value niche therapeutic areas for specialized players. Developing non-opioid analgesics specifically for acute post-operative neuropathic pain presents a significant white-space opportunity within hospital settings. A precision medicine approach, integrating digital health platforms for patient monitoring, provides a distinct go-to-market angle. Focus on demonstrating superior safety profiles to gain regulatory and market acceptance.
For Investors and Strategic Acquirers: Asymmetric upside sits with biotech innovators pioneering targeted gene therapies and monoclonal antibodies for specific neuropathic pain pathways. The long-term viability favors companies with robust pipelines in non-opioid and personalized pain management solutions. Acquisition targets should include firms with advanced clinical-stage assets or established digital therapeutics platforms. Successful Phase 3 clinical trial readouts for novel non-opioid analgesics serve as a critical inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates regulatory approval for novel non-opioid analgesics, addressing unmet patient needs. |
| Pipeline Diversification | Expands therapeutic offerings beyond traditional anticonvulsants and antidepressants, reducing market risk. |
| Digital Health Integration | Enhances patient monitoring and adherence, improving long-term outcomes for chronic neuropathic pain. |
| Targeted Orphan Drug Development | Captures high-value niche markets like trigeminal neuralgia with specialized therapeutic agents. |
| Strategic Partnerships | Leverages complementary R&D expertise and commercial infrastructure for broader market reach. |
Research Approach
Coverage spans the United States, Germany, Japan, United Kingdom, and France, with primary inputs from each region's healthcare ecosystem. This approach combines in-depth interviews with drug development executives, regulatory affairs leads, formulary directors, and pain specialists. Secondary validation draws from FDA filings, EMA submissions, PMDA approval documents, and clinical trial registries, ensuring comprehensive data triangulation through bottom-up and top-down analyses.
Market volume and value were modeled at a granular level across product type, therapy area, end user, and delivery mode segmentation. The analytical framework integrated prevalence rates of diabetic neuropathy and regulatory approval timelines for novel non-opioids as key forecast inputs. Compound Annual Growth Rates were derived from historical data analysis and projected market dynamics across the analysis window, reflecting expected shifts in treatment paradigms.
Inputs from public health organizations, regulatory bodies, and clinical trial sponsors were available through the study window; gaps in long-term patient adherence data introduce uncertainty bands. Forecasts reflect assumptions regarding ongoing R&D success and evolving reimbursement policies. Deviation in major regulatory shifts or clinical trial outcomes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Opioid Induced Side Effects Treatment Market
Pain Management
Medicated Pain Relieving Plasters Market
Pain Management
Central Pain Syndrome Management Market
Pain Management
Cluster Headache Market
Pain Management
Non Opioid Pain Treatment Market
Pain Management
Pain Management Therapeutics Market
Pain Management
Bone Pain Treatment Market
Pain Management
Global Non-Opioid Pain Patch Market
Pain Management
Heat Therapy Market
Pain Management
Chemotherapy Induced Pain Market
Pain Management
Chronic Pain Market
Pain Management
Ketorolac Market
Pain Management
Topical Pain Relief Cream Market
Pain Management
Plantar Fasciitis Treatment Market
Pain Management
Erythromelalgia Treatment Market
Pain Management
Migraine Management Market