
 Ketoprofen API Market | 2026-2036
Ketoprofen API Market Size, Share, and Industry Trends Forecast 2026-2036
Ketoprofen API Market Insights
China is reconfiguring capacity expansion across Zhejiang and Hubei provinces for ketoprofen API output. Zhejiang Jiuzhou Pharmaceutical leverages backward integration into key starting materials to sustain cost competitiveness in oral-grade supply. Hubei Xunda Pharmaceutical anchors export volumes to regulated European markets through EU-GMP certification. EUROAPI dominates specialty parenteral-grade production with technology leadership in controlled-release formulations.
Ketoprofen API, the active pharmaceutical ingredient of the propionic acid class NSAID, functions as a cyclooxygenase inhibitor with a molecular weight of 254.28 g/mol and requires chiral resolution or asymmetric synthesis for enantiopure output. The substance serves primarily as the pharmacological core of oral, topical, and injectable dosage forms prescribed for rheumatoid arthritis, musculoskeletal pain, and post-surgical inflammation management. Tablet and capsule formulations within the oral delivery mode category occupy the largest volume share due to established bioequivalence pathways and stable hospital procurement contracts. Injectable and intravenous segments command premium positioning in post-operative care settings where rapid onset and controlled dosing protocols outweigh higher production costs.
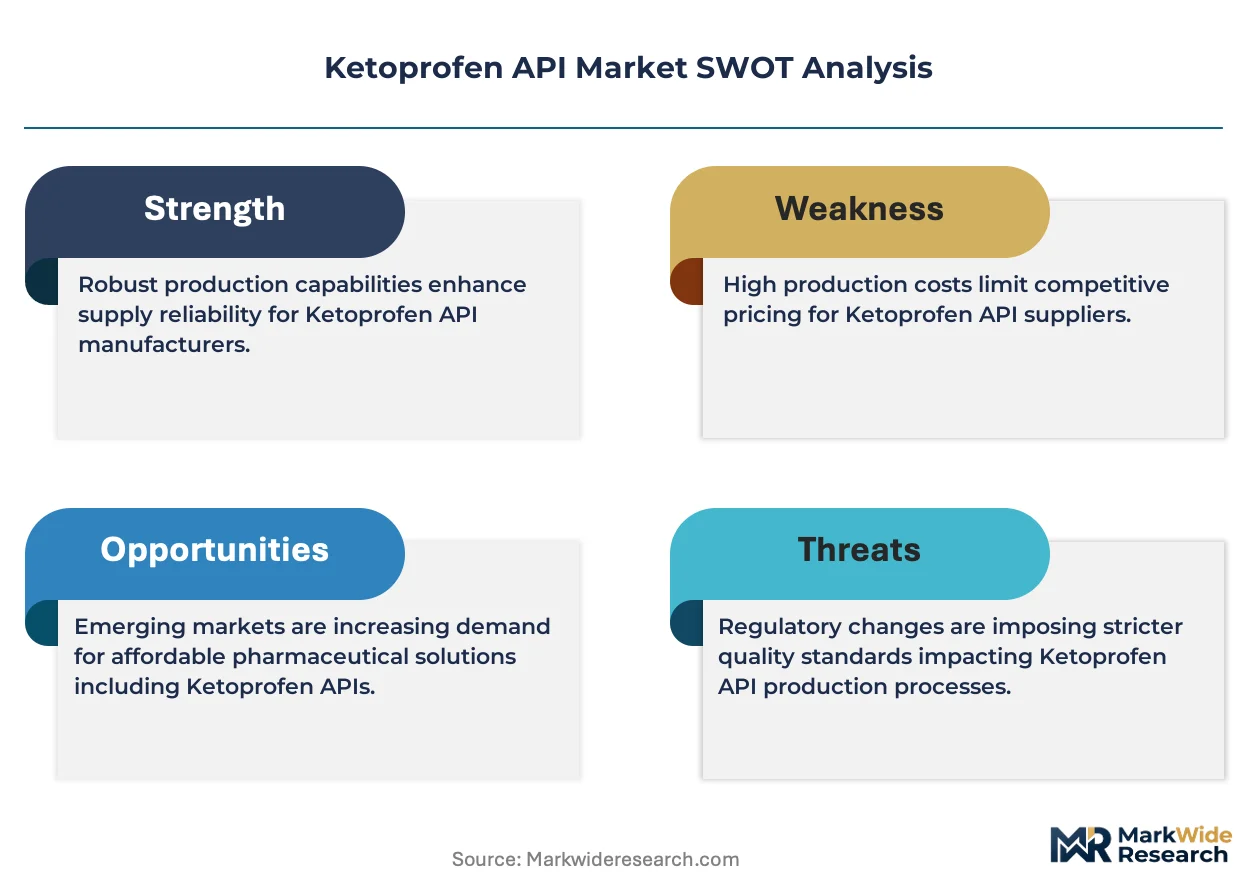
FDA, EMA, and China's NMPA enforce divergent nitrosamine impurity limits and ICH Q3D elemental impurity guidelines that reshape batch-release testing burdens and facility investment thresholds for ketoprofen API manufacturers. REACH registration in Europe and India's CDSCO active pharmaceutical ingredient master filing requirements further segment market access by regulatory stringency. Stakeholders must monitor evolving pharmacopoeial harmonization between USP, EP, and ChP monographs while calibrating capacity decisions against the pace of generic formulation tender awards in emerging markets.
Market Dynamics
Tightened nitrosamine impurity limits from FDA, EMA, and China's NMPA are forcing API manufacturers to reconfigure batch-release protocols and upgrade analytical capabilities, compressing margins for smaller producers while favoring scaled, certified suppliers.
Growth Catalysts
- Generic tender acceleration in Southeast Asia:Hospital procurement contracts for NSAID formulations in Vietnam, Indonesia, and Thailand are expanding volume commitments for oral-grade ketoprofen API.
- REACH registration completion:European market access for Indian and Chinese manufacturers now hinges on full dossier compliance, creating first-mover advantages for early registrants.
- Chiral resolution technology maturation:Asymmetric synthesis methods are reducing enantiopure production costs, enabling broader adoption in parenteral-grade supply.
Market Restraints
- Starting material cost volatility:Fluctuations in propionic acid derivative feedstocks from petrochemical supply chains compress margin predictability for non-integrated producers.
- Regulatory testing burden:ICH Q3D elemental impurity guidelines and nitrosamine screening protocols have doubled batch-release timelines and analytical capex requirements.
- Substitution pressure from diclofenac and celecoxib APIs:Formulation sponsors in pain management are diversifying pharmacological cores to mitigate single-source API risk.
Strategic Opportunities
- EU-GMP certified parenteral-grade supply gap:Post-operative care settings in Germany, France, and Italy face shortages of controlled-release injectable ketoprofen formulations.
- Backward integration into key starting materials:Captive production of propionic acid intermediates insulates margin structures from commodity volatility.
- CDSCO PLI scheme alignment:India's production-linked incentive framework for active pharmaceutical ingredients offers cost-offset pathways for greenfield capacity.
Industry Challenges
- Analytical chemist scarcity:Nitrosamine impurity profiling and ICH Q3D compliance require specialized mass spectrometry expertise that outpaces current training pipeline output.
- Multi-pharmacopoeial harmonization delays:Divergent USP, EP, and ChP monograph specifications force redundant method development and dual validation runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ketoprofen API Market |
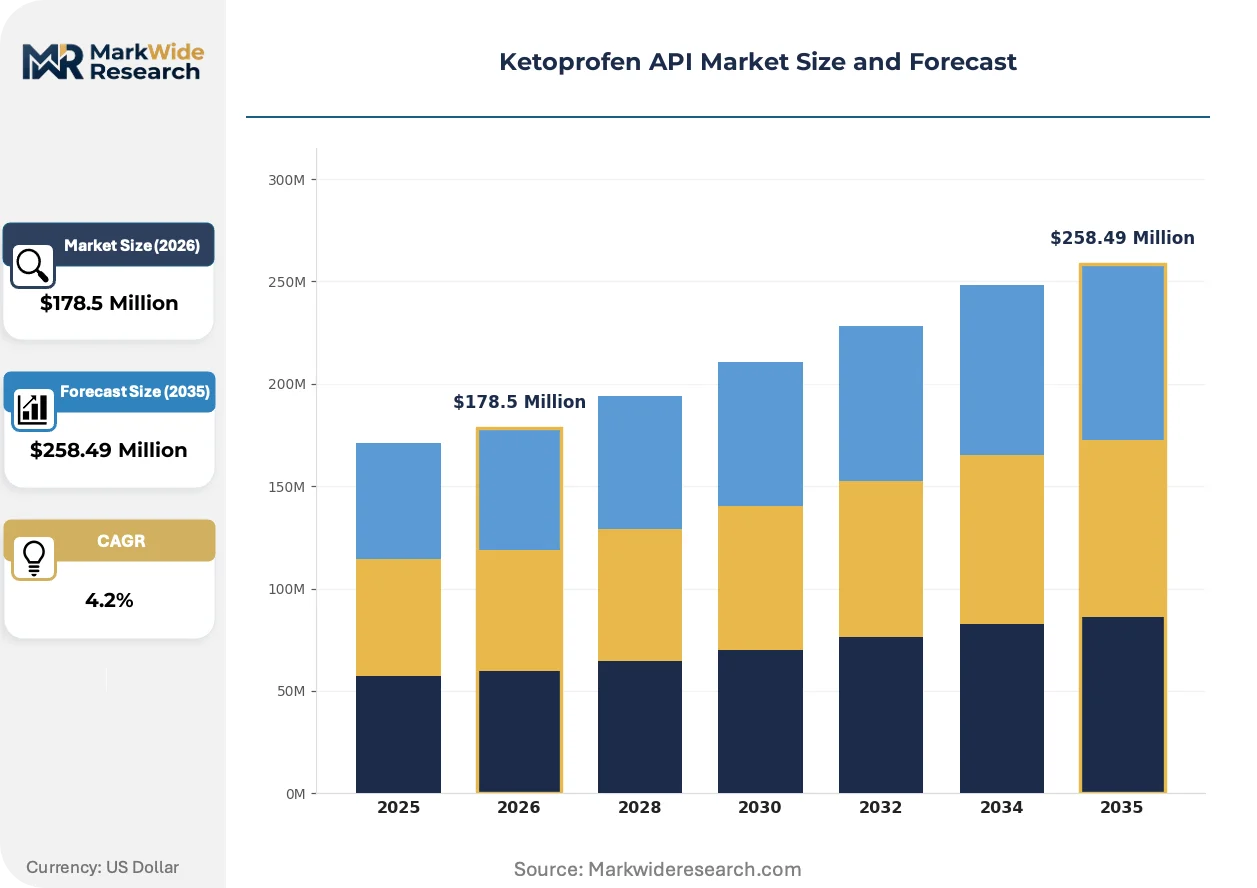
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $258.49 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Injectable, Topical Therapy Area: Pain Management, Inflammation, Arthritis, Post-operative Care End User: Hospitals, Clinics, Home Care, Pharmacies Delivery Mode: Oral, Parenteral, Transdermal, Intravenous |
| Companies Covered | Hubei Xunda Pharmaceutical, Nanjing Dorra Pharmaceutical Technology, Zhejiang Jiuzhou Pharmaceutical, Anhui Sinotech Industrial, Mac-Chem Products (India), BEC Chemicals, KOLON Life Science, Midas Pharma, EUROAPI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ketoprofen API Market Trends and Innovations
Process analytical technology and continuous manufacturing are compressing batch cycle times while regulatory digitalization is reshaping documentation and audit protocols across ketoprofen API supply chains.
Continuous flow chemistry is virtualizing traditional batch reactor operations in ketoprofen synthesis. Mid-scale API manufacturers in Zhejiang and Hubei provinces are retrofitting pilot plants with microreactor arrays to reduce solvent waste and improve thermal control. This technology is virtualizing capital allocation patterns, diverting investment from large-volume stainless-steel vessels toward modular, skid-mounted systems that enable rapid product changeover.
EMA's updated nitrosamine risk assessment guidelines now mandate comprehensive survey testing for all chemically synthesized APIs with secondary or tertiary amine structures. European formulation sponsors are demanding extended impurity characterization datasets from API suppliers, shifting contract terms toward outcome-based quality agreements. Parenteral-grade manufacturers face the steepest compliance curve, as intravenous applications trigger the most stringent acceptable intake thresholds.
Hospital procurement consortia in Germany and France are consolidating NSAID API purchasing through centralized tender platforms, displacing fragmented distributor networks. These entities now specify EU-GMP certification, nitrosamine test documentation, and supply chain transparency as mandatory bid criteria. The shift concentrates volume with vertically integrated suppliers capable of direct technical engagement with pharmacovigilance departments.
Ketoprofen API Market Segmentation
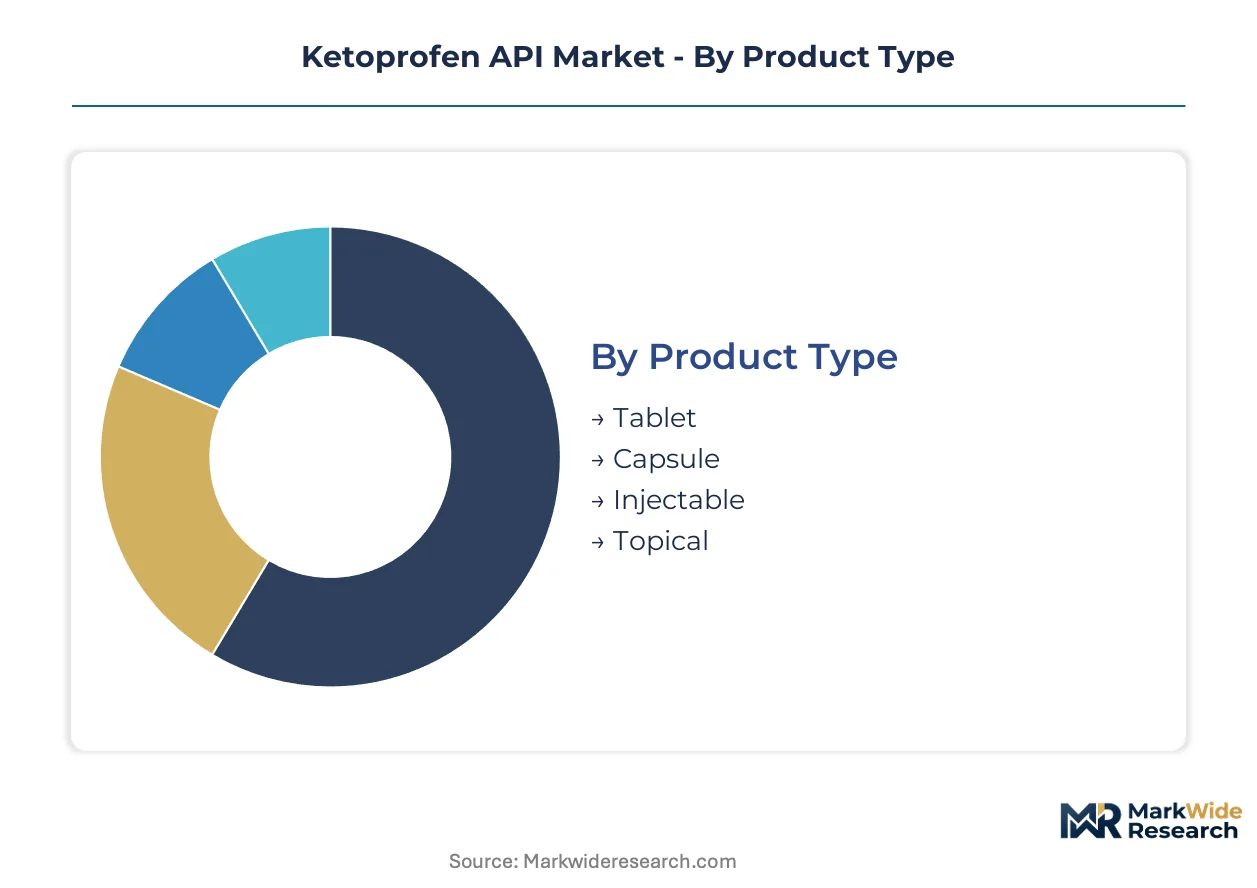
Ketoprofen API demand fragments across formulation physics, clinical settings, and regulatory pathways. Each segment carries distinct purity specifications, batch-release burdens, and margin structures that reshape supplier positioning.
Product Type:
Oral solid dosage forms dominate mature markets while parenteral formats command premium positioning in acute care.
- Tablet:Compressed oral dosage forms with established bioequivalence pathways anchor hospital procurement contracts in Southeast Asia. CDSCO and NMPA impurity profiling requirements compress margins for non-integrated manufacturers supplying this segment.
- Capsule:Gelatin or HPMC-encapsulated formulations offer dose flexibility for rheumatoid arthritis maintenance therapy. Demand concentrates in Indian generic exports to African and Latin American tender markets where capsule tooling costs undercut tablet press investments.
- Injectable:Sterile solution formulations for post-operative pain management require EU-GMP certification and nitrosamine survey documentation. German and French hospital consortia specify controlled-release injectable grades in centralized tenders.
- Topical:Gel and cream formulations for musculoskeletal pain deliver localized action with reduced systemic exposure. Transdermal penetration enhancer compatibility limits API supplier pools to specialized manufacturers.
Tablet handles the majority of throughput; Injectable is expanding most quickly on share.
Therapy Area:
Clinical indication determines pharmacokinetic targeting, dosing frequency, and regulatory dossier complexity for API sponsors.
- Pain Management:Acute and chronic pain protocols drive volume across oral and parenteral grades. Vietnam, Indonesia, and Thailand hospital procurement consortia are accelerating NSAID tender awards for post-trauma and cancer pain protocols.
- Inflammation:Soft tissue and systemic inflammatory conditions require sustained-release formulations with validated dissolution profiles. EMA nitrosamine risk assessments impose extended characterization datasets on suppliers targeting this indication.
- Arthritis:Rheumatoid and osteoarthritis maintenance therapy favors oral solid dosage forms with established generic substitution pathways. Indian PLI scheme alignment supports cost-competitive API output for this chronic indication.
- Post-operative Care:Rapid-onset intravenous and intramuscular formulations command premium pricing in German, French, and Italian surgical settings. EU-GMP certified parenteral-grade supply gaps concentrate volume with EUROAPI and vertically integrated Chinese exporters.
Pain Management captures the largest addressable base; Post-operative Care climbs the fastest on margin contribution.
End User:
Procurement authority and reimbursement pathways fragment demand across institutional and retail channels.
- Hospitals:Centralized purchasing consortia in Germany and France specify EU-GMP certification, nitrosamine documentation, and supply chain transparency as mandatory bid criteria. Volume concentrates with vertically integrated suppliers capable of direct pharmacovigilance engagement.
- Clinics:Outpatient surgical and pain management centers favor multi-source procurement to mitigate API supply risk. Diclofenac and celecoxib API substitution pressure is strongest in this channel.
- Home Care:Patient-administered oral and topical formulations require stable room-temperature storage profiles. REACH registration completion creates first-mover advantages for Indian and Chinese manufacturers targeting European retail distribution.
- Pharmacies:Community dispensing channels depend on generic formulation tender awards and bioequivalence study timing. Southeast Asian markets show accelerating volume commitments as national health insurance schemes expand NSAID coverage.
Hospitals direct the steepest volume concentration; Home Care is gaining share fastest as chronic pain management shifts outside institutional settings.
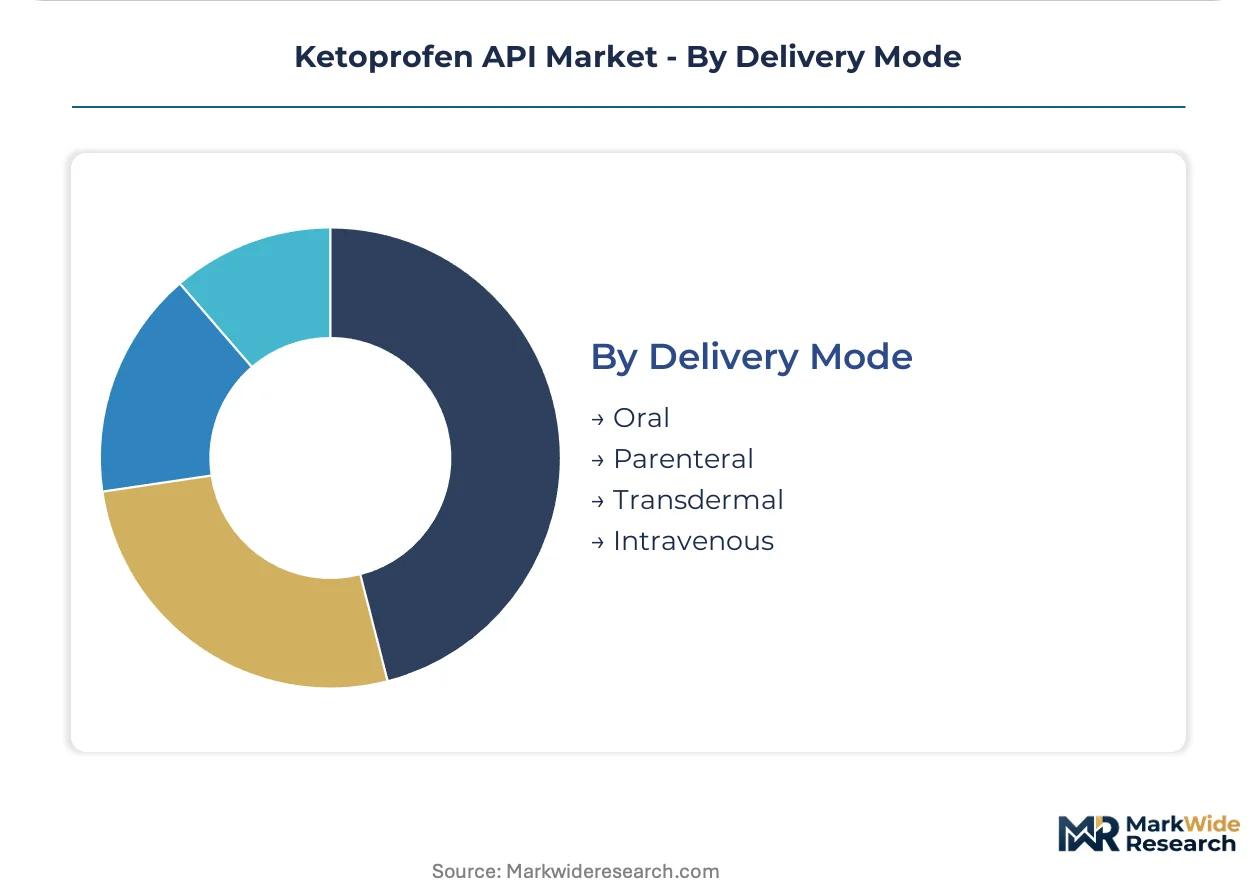
Delivery Mode:
Route of administration determines sterility requirements, impurity thresholds, and manufacturing capital intensity.
- Oral:Tablet and capsule absorption through gastrointestinal tract dominates total API consumption. Established USP, EP, and ChP monograph specifications enable multi-pharmacopoeial sourcing strategies.
- Parenteral:Intramuscular and subcutaneous injection formats for rapid onset in acute pain settings. EMA updated nitrosamine guidelines mandate the most stringent acceptable intake thresholds for this delivery mode.
- Transdermal:Patch and gel formulations bypass hepatic first-pass metabolism for localized musculoskeletal applications. Penetration enhancer compatibility and adhesive stability testing extend development timelines.
- Intravenous:Direct vascular administration in surgical and emergency settings demands sterile API with endotoxin control. EU-GMP certified controlled-release injectable formulations face supply shortages in Italian and Spanish hospital systems.
Oral maintains absolute volume leadership; Intravenous shows the steepest expansion trajectory as post-operative care protocols intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortia in Germany and France favor parenteral-grade ketoprofen API for post-operative protocols, while Southeast Asian markets concentrate demand in oral solid dosage forms for chronic pain management. This consumption-mix differential shapes supplier certification requirements and capacity investment priorities across geographies.
China
Zhejiang and Hubei provinces anchor ketoprofen API manufacturing capacity, with Zhejiang Jiuzhou Pharmaceutical leveraging backward integration into propionic acid intermediates. NMPA tightened nitrosamine impurity profiling requirements in 2023, elevating compliance costs for smaller producers. Hubei Xunda Pharmaceutical maintains EU-GMP certification to serve regulated European export markets.
Germany
Hospital procurement consortia in Bavaria and North Rhine-Westphalia specify EU-GMP certification and nitrosamine documentation as mandatory tender criteria. EMA updated nitrosamine risk assessment guidelines mandate extended impurity characterization for parenteral-grade supply. Frankfurt and Munich clusters concentrate formulation sponsors demanding controlled-release injectable grades.
India
Maharashtra and Gujarat host generic pharmaceutical manufacturers scaling ketoprofen API procurement for pain management formulations. CDSCO active pharmaceutical ingredient master filing requirements segment market access by regulatory stringency. India's PLI scheme for APIs offers cost-offset pathways for greenfield capacity in oral-grade production.
France
Île-de-France hospital consortia consolidate NSAID API purchasing through centralized tender platforms displacing fragmented distributor networks. ANSM enforces REACH registration completion for European market access, creating first-mover advantages for early registrants. Lyon and Paris clusters demand supply chain transparency and direct pharmacovigilance engagement.
Vietnam
Hospital procurement contracts for NSAID formulations are expanding volume commitments for oral-grade ketoprofen API in Ho Chi Minh City and Hanoi. The country's national pharmaceutical regulator aligns with ASEAN harmonization initiatives for impurity limits. Southeast Asian contract manufacturing markets concentrate demand in tablet and capsule formulations.
Ketoprofen API Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The ketoprofen API market structures around vertically integrated manufacturers with captive starting material production and specialized parenteral-grade suppliers with EU-GMP certification. Three archetypes dominate: backward-integrated Chinese producers, European specialty manufacturers, and Indian generic-scale suppliers. Competitive moves center on REACH registration completion for European access and CDSCO PLI scheme alignment for Indian cost positioning.
Among Chinese producers, Zhejiang Jiuzhou Pharmaceutical and Hubei Xunda Pharmaceutical occupy positions reflecting scale-driven and export-certified archetypes respectively. EUROAPI represents the European specialty tier with technology positioning in controlled-release formulations. These named entities exemplify how geographic origin and certification status stratify competitive positioning without requiring specific product or financial disclosures.
| Leading Market Players |
|---|
| Hubei Xunda Pharmaceutical |
| Nanjing Dorra Pharmaceutical Technology |
| Zhejiang Jiuzhou Pharmaceutical |
| Anhui Sinotech Industrial |
| Mac-Chem Products (India) |
| BEC Chemicals |
| KOLON Life Science |
| Midas Pharma |
| EUROAPI |
| Others |
Pricing and Supply Chain Analysis
Zhejiang province's concentrated ketoprofen API capacity anchors downstream pricing power for oral-grade supply, while Hubei Xunda Pharmaceutical's EU-GMP certification commands premium positioning in European parenteral markets. Cost compression from NMPA nitrosamine compliance requirements is feeding back into supplier consolidation decisions, favoring scaled producers with captive starting material production.
Pricing Analysis
Geographic price spreads separate Indian oral-grade exports to Southeast Asian tender markets from EU-GMP certified parenteral supply into German hospital consortia. Pricing stratifies across premium, standard, and economy tiers driven by certification grade and volume scale commitments. Cost compression in the standard tier is intensifying because propionic acid derivative feedstock volatility squeezes non-integrated manufacturers. Southeast Asian contract manufacturers exhibit the highest price sensitivity, while French and German hospital procurement consortia prioritize supply chain transparency over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are becoming standard contract features as Indian and Chinese manufacturers compete for European formulation sponsor relationships. Manufacturing concentration rests on China, India, and Italy, with Zhejiang and Hubei provinces anchoring Chinese output and Maharashtra and Gujarat hosting Indian generic scale. Propionic acid intermediates, chiral resolution catalysts, and nitrosamine testing reagents constitute critical input dependencies. Single-source vulnerability around EU-GMP certified parenteral-grade supply creates structural risk for German and French hospital systems. Distribution runs through centralized tender platforms displacing fragmented distributor networks in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ketoprofen API market functions as a capability-scarcity environment where mass spectrometry expertise for nitrosamine profiling and EU-GMP certification capacity lag behind demand from European hospital consortia.
For Market Incumbents: Harden analytical chemistry capabilities through specialized mass spectrometry training partnerships to defend against CDSCO and NMPA impurity profiling escalation. Deepen backward integration into propionic acid intermediates to insulate margin structures from petrochemical feedstock volatility threatening non-integrated competitors. For New Entrants and Emerging Players: Vietnamese and Indonesian hospital procurement consortia present the most penetrable white-space for oral-grade ketoprofen API supply, as national health insurance expansion accelerates NSAID tender awards. India's PLI scheme alignment offers cost-offset pathways for greenfield capacity targeting chronic pain management formulations. A REACH registration-first go-to-market strategy secures European access before competitors complete dossier compliance. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because nitrosamine testing burdens and EU-GMP certification requirements are structurally elevating barriers for sub-scale producers. Acquisition targets should exhibit backward-integrated starting material production plus existing European regulatory dossiers. The signal to watch is EMA pharmacovigilance engagement depth among API suppliers, as direct hospital consortium relationships become mandatory bid criteria.| Strategic Initiative | Industry Significance |
|---|---|
| EU-GMP Certification Investment | Unlocks access to German and French hospital procurement consortia specifying mandatory certification. |
| Backward Integration into Propionic Acid Intermediates | Insulates margin structures from petrochemical feedstock volatility compressing non-integrated producers. |
| REACH Registration Completion | Creates first-mover advantage for Indian and Chinese manufacturers targeting European retail distribution. |
| Continuous Flow Chemistry Retrofit | Zhejiang and Hubei pilot plants reduce solvent waste and improve thermal control in ketoprofen synthesis. |
| CDSCO PLI Scheme Alignment | India's production-linked incentive framework offers cost-offset pathways for oral-grade API greenfield capacity. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors across India, China, Germany, and France. Secondary validation drew from FDA filings, EMA submissions, CDSCO active pharmaceutical ingredient master filings, and REACH registration databases. Bottom-up capacity modeling and top-down tender award tracking were triangulated to reconcile volume estimates.
Calibration against historical batch-release timelines and facility investment patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include dosage form, therapy area, delivery mode, end-user channel, and regional regulatory cluster. CAGRs were derived from weighted capacity expansion announcements and tender award velocity. Industry-specific forecast inputs incorporated nitrosamine testing protocol adoption curves and EU-GMP certification pipeline status.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing, currency volatility affecting Indian and Chinese export competitiveness, or regulatory harmonization delays between USP, EP, and ChP monographs would shift the trajectory. Forecasts reflect documented assumptions about tender award timing and certification completion rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Global Artemisinin Combination Therapy Market
Pharmacology
Global Olanzapine Market
Pharmacology
Immunotherapy Drugs Market
Pharmacology
Global Pharmacokinetics Services Market
Pharmacology
Hypertension Drug Market
Pharmacology
Angiotensin II Receptor Blockers (Arbs) Market
Pharmacology
Medication Adherence Market
Pharmacology
Intranasal Drug and Vaccine Delivery Market
Pharmacology
Pegylated Drugs Market
Pharmacology
Influenza Medication Market
Pharmacology
Antithrombotic Drugs Market
Pharmacology
Alexipharmic Drugs Market
Pharmacology
Semaglutide API Market
Pharmacology
Global Asthma Therapeutics Market
Pharmacology
Alzheimer Drugs Market
Pharmacology
Drug Delivery Across the Blood-Brain Barrier Market