
 Intravenous (IV) Ibuprofen Market | 2026-2036
Intravenous (IV) Ibuprofen Market Size, Share, and Industry Trends Forecast 2026-2036
Intravenous (IV) Ibuprofen Market Intelligence
Oral ibuprofen formulations are realigning toward intravenous delivery in perioperative settings where gastrointestinal absorption is compromised. Fresenius Kabi leverages its parenteral manufacturing infrastructure to sustain supply contracts with major hospital purchasing organizations. Cumberland Pharmaceuticals differentiates through dedicated hospital sales infrastructure focused on acute care formulary access.
Intravenous ibuprofen denotes the sterile, aqueous formulation of the propionic acid derivative (2-(4-isobutylphenyl)propionic acid) administered via direct vascular access, typically dosed at 400–800 mg in 100 mL infusion bags for patients unable to tolerate oral intake. The product functions primarily as a non-opioid analgesic and antipyretic in surgical, trauma, and febrile contexts where rapid onset and predictable bioavailability prove clinically essential. Concentrated solution formats dominate current production volumes due to pharmacy compounding efficiency and reduced storage footprint, while pre-filled syringe packaging is capturing fastest-growing demand segments driven by anesthesia workflow standardization and medication safety protocols. Emergency medical services as an end-user channel remains underdeveloped relative to hospital adoption, presenting latent expansion potential as pre-hospital pain management protocols mature.
FDA cGMP standards and USP Chapter <797> sterile compounding requirements govern manufacturing quality and batch release for injectable ibuprofen, with EMA's Good Manufacturing Practice inspections creating parallel compliance obligations for European supply routes. The US Drug Enforcement Administration's scheduling pressures on opioid analgesics indirectly amplifies prescriber interest in IV NSAID alternatives, while hospital Joint Commission pain management standards reinforce non-opioid multimodal protocols. Stakeholders must monitor evolving USP <800> hazardous drug handling guidelines and state-level pharmacy board regulations that could reshape compounding economics and point-of-care preparation requirements.
Market Dynamics
ERAS protocol standardization across US tertiary hospitals is consolidating demand around non-opioid multimodal analgesia, with formulary committees now mandating intravenous NSAID inclusion in perioperative order sets.
Growth Catalysts
- DEA Scheduling Pressure:The US Drug Enforcement Administration's tightening controls on opioid analgesics are redirecting prescriber preference toward IV NSAID alternatives in acute surgical settings.
- Enhanced Recovery Protocols:Hospital systems implementing ERAS pathways for colorectal and orthopedic procedures require reliable non-opioid analgesics for patients with compromised GI function.
- Ambulatory Surgical Center Expansion:Same-day discharge mandates in US outpatient facilities prioritize rapid-onset analgesics with minimal sedation profiles.
Market Restraints
- Sterile Manufacturing Concentration:Contract manufacturing capacity for aseptic NSAID production concentrates among limited FDA-registered facilities, creating supply vulnerability.
- API Sourcing Dependency:Ibuprofen active pharmaceutical ingredient supply chains route through concentrated Asian manufacturing clusters, exposing margin pressure from freight and customs volatility.
- Compounding Economics:USP Chapter 797 compliance costs for hospital-based sterile compounding are compressing the cost advantage of bagged versus pre-filled presentations.
Strategic Opportunities
- Emergency Medical Services Channel:Pre-hospital pain management protocols in US municipal ambulance systems remain underpenetrated relative to hospital adoption.
- Pediatric Formulary Expansion:Weight-based dosing protocols for post-operative pain in children's hospitals represent an underserved application segment.
- Pre-filled Syringe Standardization:Anesthesia workflow safety initiatives are creating demand for ready-to-administer unit-dose packaging in surgical suites.
Industry Challenges
- Sterile Compounding Workforce Scarcity:US hospital pharmacies face persistent recruitment gaps for pharmacists certified in hazardous drug handling under USP 800 guidelines.
- Batch Release Timeline Compression:FDA cGMP endotoxin testing and sterility validation protocols extend production lead times, constraining just-in-time inventory models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intravenous (IV) Ibuprofen Market |
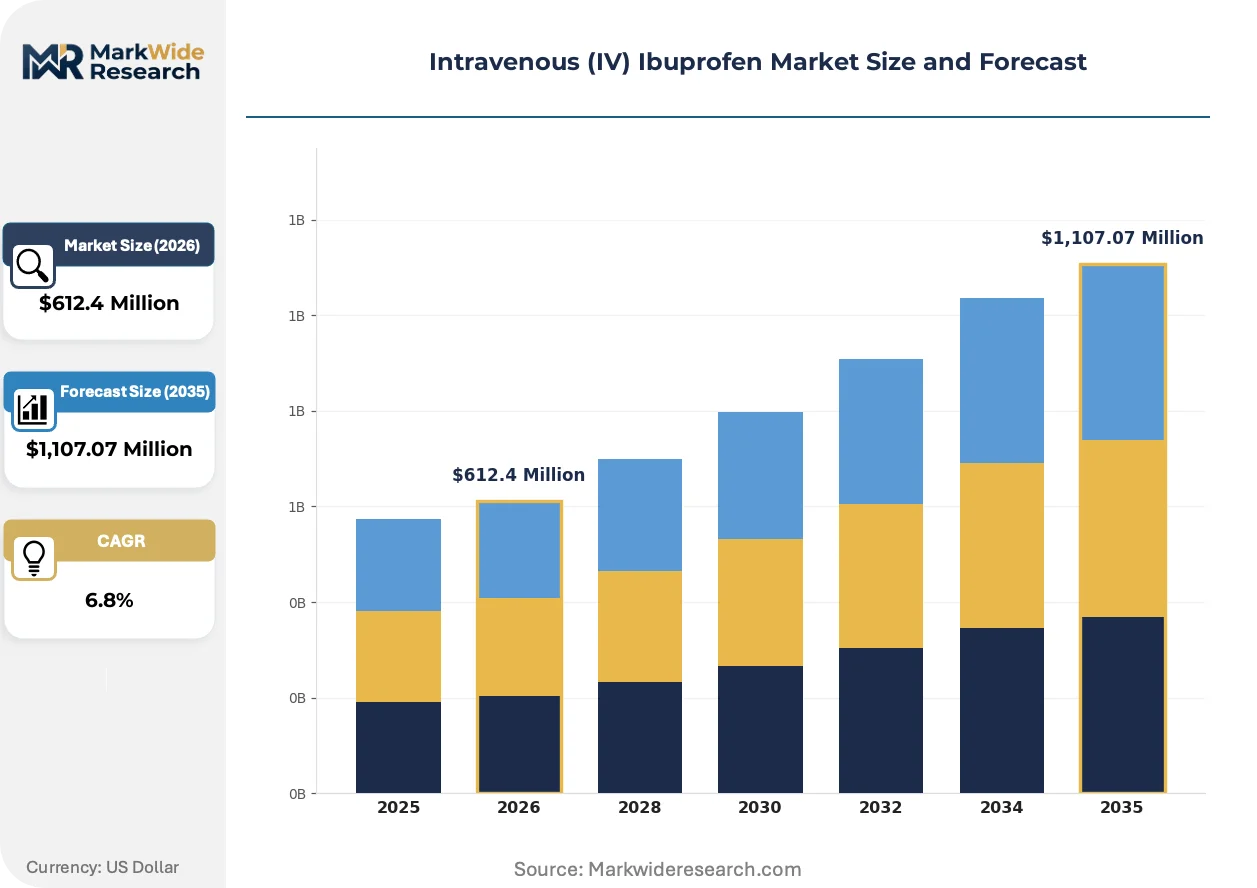
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated Solution, Diluted Solution, Starter Dose, Continuous Infusion End User: Hospitals, Clinics, Home Care, Emergency Medical Services Delivery Mode: Direct Infusion, Pump-Driven, Gravity Fed, Autoinjector Packaging Type: Vials, Pre-filled Syringes, Ampoules, Bottles |
| Companies Covered | Fresenius Kabi, Hyloris Pharmaceuticals, Cumberland Pharmaceuticals, XGEN Pharmaceuticals, Recordati, AFT Pharmaceuticals, CSL Limited, Hikma Pharmaceuticals, Grifols, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intravenous (IV) Ibuprofen Market Strategic Shifts & Innovations
Formulation stability and packaging innovation are converging to reshape competitive positioning, with manufacturers prioritizing cold-chain elimination and point-of-care preparation simplification.
Ready-to-use concentrated solutions are absorbing pharmacy compounding volume previously handled through traditional bag-based reconstitution. Hospital formularies in the US Midwest and Southeast are adopting these formats to reduce preparation errors and inventory footprint. This absorption is compressing demand for conventional dilution workflows and shifting procurement criteria toward stability-at-room-temperature claims.
FDA's ongoing emphasis on non-opioid alternatives for acute pain is reshaping hospital formulary decision architecture. The agency's 2022 and 2023 guidance documents on multimodal analgesia are embedding IV NSAIDs into Joint Commission survey expectations. Surgical services and anesthesia departments in US academic medical centers are responding by standardizing IV ibuprofen in pre-operative order sets.
Anesthesia groups are consolidating purchasing decisions through multi-hospital affiliations, displacing fragmented individual hospital procurement. GPO-negotiated contracts with mandatory compliance thresholds are replacing legacy spot-buying patterns. This concentration is most visible in Texas, Florida, and California health systems where anesthesia management companies control formulary access across dozens of facilities.
Intravenous (IV) Ibuprofen Market Segmentation
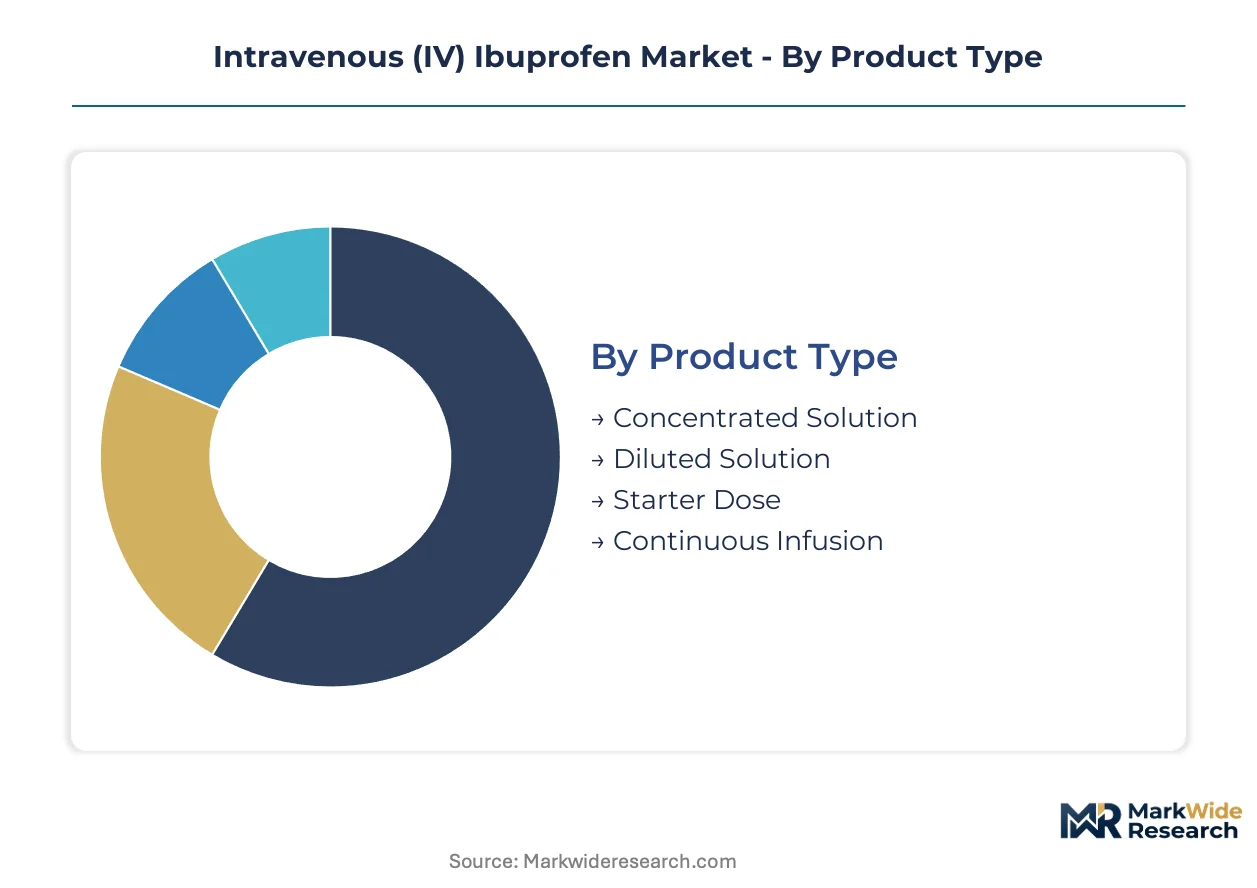
Segmentation in IV ibuprofen reveals how formulation economics, clinical workflow requirements, and regulatory packaging standards create distinct competitive battlegrounds. Manufacturers must align product architecture with specific channel constraints rather than pursuing uniform market entry.
Product Type:
Volume production concentrates in concentrated formats, while premium positioning attaches to ready-to-use configurations that eliminate compounding steps.
- Concentrated Solution:High-potency ibuprofen in reduced fluid volume enables pharmacy dilution to patient-specific concentrations. Hospital systems in the US Southeast and Midwest favor this format for inventory efficiency and compounding flexibility under USP 797 guidelines.
- Diluted Solution:Pre-diluted formulations arrive at standard clinical concentrations, bypassing pharmacy preparation entirely. Ambulatory surgical centers with limited sterile compounding infrastructure are driving demand for this plug-and-administer approach.
- Starter Dose:Single-administration units designed for initial post-operative loading.
- Continuous Infusion:Extended-delivery formulations for prolonged analgesic coverage.
Mature deployment sits with concentrated solutions. Newer deployment is concentrated in diluted solutions.
End User:
Procurement authority fragments across institutional purchasing hierarchies, with each channel imposing distinct technical and commercial requirements on suppliers.
- Hospitals:Tertiary medical centers with integrated pharmacy operations and formulary committees drive standardization decisions. Academic medical centers in Texas, Florida, and California health systems mandate IV ibuprofen inclusion in ERAS protocols, with anesthesia management companies consolidating purchasing across multi-facility networks.
- Clinics:Outpatient surgical facilities with same-day discharge mandates prioritize rapid-onset analgesics with minimal sedation profiles. These settings favor pre-filled presentations that reduce medication preparation time between cases.
- Home Care:Post-acute settings with limited clinical supervision.
- Emergency Medical Services:Pre-hospital ambulance systems remain underpenetrated relative to hospital adoption, presenting latent expansion potential as municipal protocols mature for field pain management.
Procurement consolidation is most advanced in hospitals. Channel development is accelerating fastest in emergency medical services.
Delivery Mode:
Technology selection tracks anesthesia workflow standardization and nursing labor availability, with automation premiums justified by error reduction.
- Direct Infusion:Manual bolus administration through established vascular access remains the baseline delivery method. This approach dominates in resource-constrained settings where pump capital expenditure is deferred.
- Pump-Driven:Programmable infusion devices enable precise rate control and documentation compliance. US hospital systems with Joint Commission accreditation requirements are standardizing pump-compatible presentations to satisfy medication safety protocols.
- Gravity Fed:Simple drip-rate administration without electronic control.
- Autoinjector:Self-contained spring-powered devices for emergency or field use.
Established infrastructure favors direct infusion. Capability investment is concentrating in pump-driven systems.
Packaging Type:
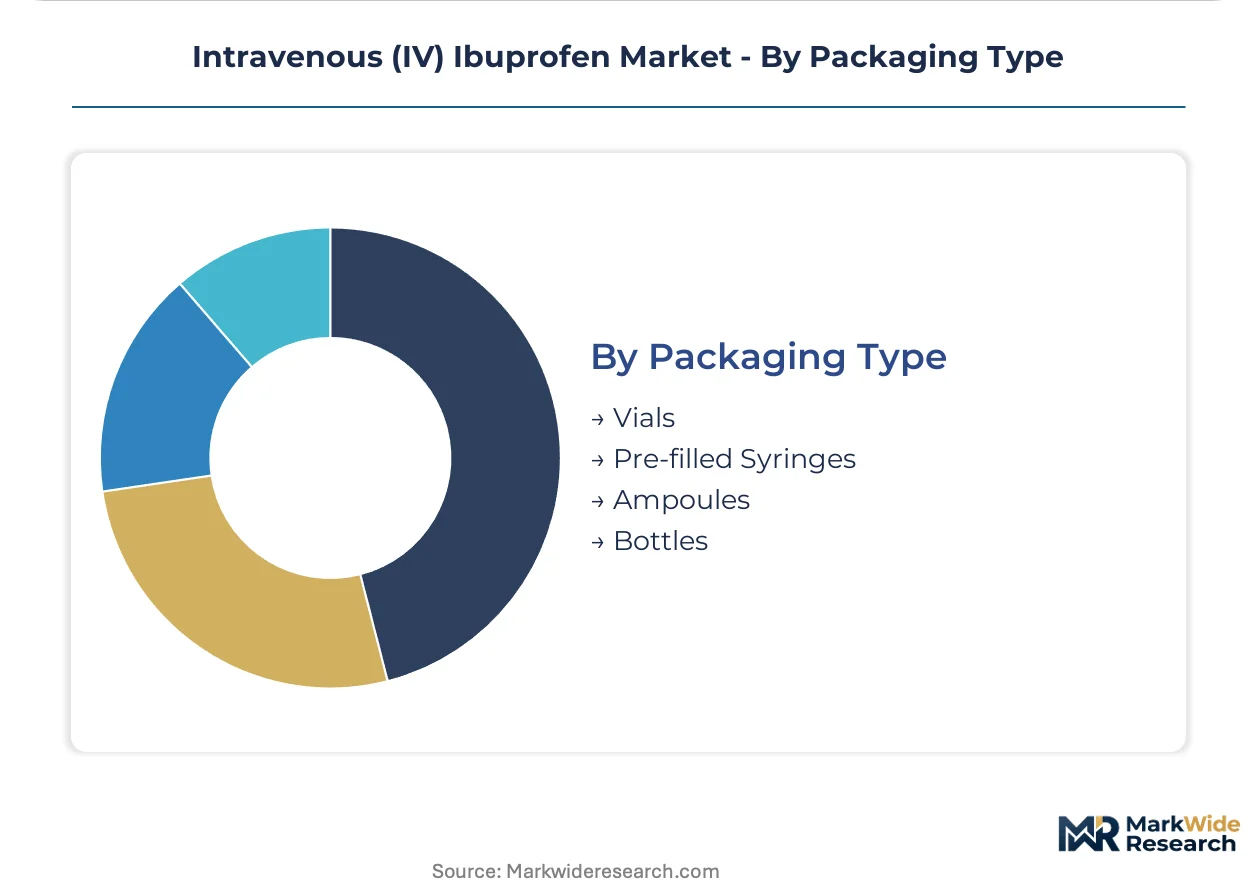
Packaging economics reflect the tension between pharmacy compounding efficiency and point-of-care preparation simplification, with safety protocols driving format migration.
- Pre-filled Syringes:Unit-dose presentations with attached needles or Luer locks eliminate preparation steps and reduce contamination risk. Anesthesia workflow safety initiatives in US surgical suites are creating demand for these ready-to-administer formats.
- Vials:Multi-dose glass or plastic containers for pharmacy withdrawal and compounding. These formats retain cost advantages in high-volume hospital settings with active sterile compounding operations.
- Ampoules:Single-dose glass containers requiring breaking and transfer.
- Bottles:Large-volume containers for bulk pharmacy preparation.
Cost optimization centers on vials. Safety-driven conversion is shifting volume toward pre-filled syringes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems concentrate the majority of IV ibuprofen procurement volume, with ambulatory surgical centers and tertiary hospitals driving adoption through ERAS protocol mandates. Regional variation reflects formulary committee structures and anesthesia management company consolidation patterns.
United States
Texas, Florida, and California health systems anchor domestic demand through anesthesia management company networks that standardize purchasing across dozens of facilities. FDA guidance documents on multimodal analgesia from 2022-2023 embed IV NSAIDs into Joint Commission survey expectations. The Southeast and Midwest favor concentrated solution formats for pharmacy compounding efficiency under USP 797 guidelines.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia integrate IV ibuprofen into perioperative protocols for colorectal and orthopedic procedures. EMA Good Manufacturing Practice inspections create parallel compliance obligations for European supply routes. The country's parenteral manufacturing infrastructure supports regional distribution across Central European hospital networks.
Japan
Metropolitan Tokyo and Osaka surgical centers adopt IV NSAIDs for same-day discharge mandates in outpatient facilities. PMDA regulatory frameworks govern sterile injectable approval timelines and post-market surveillance requirements. Kanto region hospitals prioritize pump-compatible presentations to satisfy medication safety protocols.
United Kingdom
London and Southeast England NHS trusts incorporate IV ibuprofen into enhanced recovery pathways for reduced opioid exposure. The country's national pharmaceutical regulator maintains batch release standards aligned with EMA guidelines. Midlands and North England hospital pharmacies face workforce recruitment gaps for USP 800 hazardous drug handling certification.
Australia
New South Wales and Victoria health districts deploy IV NSAIDs in emergency departments for rapid analgesic intervention. TGA scheduling frameworks influence prescriber preference for non-opioid alternatives in acute trauma settings. Queensland ambulance services present latent expansion potential as pre-hospital pain management protocols mature.
Intravenous (IV) Ibuprofen Market Key Industry Players
Formulary access consolidation dominates the current landscape as anesthesia management companies displace fragmented hospital procurement. The vendor base organizes around three tiers: multinational parenteral specialists with integrated manufacturing, mid-cap pharmaceutical firms with dedicated hospital sales infrastructure, and regional injectable suppliers with GPO contract expertise. Capacity expansion and strategic partnerships represent the two primary competitive moves, with manufacturers prioritizing FDA-registered aseptic production lines and GPO-negotiated compliance thresholds.
Among multinational parenteral specialists, Fresenius Kabi anchors the manufacturing infrastructure tier through supply contracts with major hospital purchasing organizations. Cumberland Pharmaceuticals occupies a position exemplifying dedicated acute care formulary access, while Hikma Pharmaceuticals represents the regional injectable supplier archetype with GPO contract penetration. These three entities collectively illustrate how competitive positioning tracks sterile manufacturing capability against hospital sales force deployment.
| Leading Market Players |
|---|
| Fresenius Kabi |
| Hyloris Pharmaceuticals |
| Cumberland Pharmaceuticals |
| XGEN Pharmaceuticals |
| Recordati |
| AFT Pharmaceuticals |
| CSL Limited |
| Hikma Pharmaceuticals |
| Grifols |
| Others |
Cost & Logistics Intelligence
Anesthesia management companies consolidating purchasing across Texas, Florida, and California health systems command contract-based pricing leverage that favors volume-tiered arrangements over spot procurement. This buyer concentration feeds directly into GPO-negotiated compliance thresholds that reshape supplier margin structures.
Pricing Analysis
Volume procurement through hospital purchasing organizations anchors the lower-margin tier, while ready-to-use pre-filled syringes capture premium positioning for anesthesia workflow safety. Price differentiation rests on USP 797 compliance burden and cold-chain elimination claims. Cost compression in concentrated solution formats is intensifying because pharmacy compounding workforce scarcity elevates preparation labor costs. Ambulatory surgical centers exhibit highest price sensitivity due to same-day discharge economics, whereas academic medical centers prioritize formulary standardization over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Joint Commission-accredited hospital systems require FDA-registered aseptic manufacturing qualification across multiple contract facilities. API supply routes through India and China expose margin pressure from freight volatility and customs processing. Finished dose production concentrates in United States and German parenteral manufacturing clusters. Distribution runs through GPO-contracted distribution networks with mandatory compliance thresholds replacing legacy spot-buying patterns. Single-source vulnerability in sterile compounding capacity creates supply interruption risk during FDA inspection cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as USP 800 hazardous drug handling certification requirements force smaller compounders out of hospital pharmacy contracts. Surviving players must secure FDA-registered aseptic capacity or exit.
For Market Incumbents: Deploy GPO contract lock-in mechanisms to secure multi-year formulary access across anesthesia management company networks. Expand FDA-registered aseptic production lines in the US Southeast to reduce freight exposure and capture regional pharmacy compounding demand. Counter Hikma Pharmaceuticals' regional injectable supplier model by deepening hospital sales force deployment in Texas and Florida health systems. For New Entrants and Emerging Players: Emergency medical services channels in US municipal ambulance systems offer the most penetrable white-space target, with pre-hospital pain management protocols still maturing. Pediatric weight-based dosing protocols for children's hospitals represent a second underserved application segment with limited dedicated formulation competition. Pursue partnership routes with regional GPOs rather than direct hospital sales force buildout to accelerate formulary access. For Investors and Strategic Acquirers: The window for entry favors mid-cap pharmaceutical firms with existing hospital sales infrastructure and pending FDA aseptic manufacturing registrations. Acquisition targets should demonstrate active sterile compounding contracts with at least one major anesthesia management company. Monitor DEA scheduling pressure intensity as the inflection indicator for IV NSAID demand acceleration versus opioid recapture risk.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Aseptic Manufacturing Registration | Unlocks GPO contract eligibility for hospital purchasing organization compliance thresholds. |
| Pre-filled Syringe Format Launch | Captures anesthesia workflow safety premiums in US academic medical center surgical suites. |
| USP 800 Compliance Certification | Satisfies Joint Commission hazardous drug handling requirements for hospital pharmacy contracts. |
| Pediatric Formulary Expansion | Addresses weight-based dosing gap in children's hospital post-operative pain protocols. |
| Emergency Medical Services Partnership | Establishes pre-hospital channel presence before municipal ambulance protocol standardization. |
Research Approach
Document review covered FDA cGMP inspection records, USP Chapter 797 and 800 guidance documents, and GPO contract disclosure databases, complemented by interviews with hospital pharmacy directors, anesthesia department chiefs, formulary committee members, and sterile compounding supervisors. Secondary validation drew from FDA Orange Book listings, EMA GMP inspection reports, and hospital procurement database aggregators. Bottom-up demand modeling from ambulatory surgical center procedure volumes was cross-referenced against top-down pharmaceutical shipment data.
Historical volume trajectories were cross-referenced against expert panel input from parenteral manufacturing specialists and anesthesia management company procurement leads. The analytical framework segmented across product type, end user, delivery mode, and packaging format, with regional regulatory cluster differentiation. CAGR derivation incorporated ERAS protocol adoption curves, DEA scheduling pressure indices, and sterile compounding workforce availability metrics. Industry-specific inputs included USP 797 compliance cost trajectories and anesthesia group consolidation patterns.
Revisions become necessary when FDA aseptic manufacturing inspection backlogs extend batch release timelines or DEA rescheduling decisions alter opioid substitution economics. Deviation in GPO contract renewal rates or USP 800 pharmacist certification availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Visceral Pain Market
Pain Management
Global Visceral Pain Treatment Market
Pain Management
Pain Management Therapeutics Market
Pain Management
Pain Relievers for Teeth Market
Pain Management
Plantar Fasciitis Treatment Market
Pain Management
Medical Morphine Market
Pain Management
Axial Spondyloarthritis Management Market
Pain Management
Migraine Management Market
Pain Management
Ketorolac Market
Pain Management
Tattoo Numbing Cream Market
Pain Management
Cold Pain Therapy Market
Pain Management
Pain Management Devices Market
Pain Management
Palliative Care Market
Pain Management
Neuropathic Pain Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Pain Management Software Market