
 Asia-Pacific Chronic Disease Management Market | 2026-2036
Asia-Pacific Chronic Disease Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Chronic Disease Management Market Insights
ISO 13485 certification for medical device quality management is bifurcating the competitive landscape between qualified and non-qualified platform vendors. Shenzhen Mindray Bio-Medical Electronics Co., Ltd leverages its vertically integrated manufacturing base to dominate hardware supply for remote monitoring deployments. Philips sustains brand strength across hospital systems through deep clinical workflow integration. Oracle Health competes on cloud-native architecture designed for multi-site health network orchestration.
Chronic disease management encompasses coordinated clinical interventions, digital monitoring systems, and patient engagement protocols designed to reduce acute episodes and slow disease progression in conditions such as diabetes, hypertension, and cardiovascular disorders. Platforms typically integrate continuous glucose monitors, blood pressure sensors, and medication adherence trackers with predictive algorithms that flag deterioration before emergency intervention becomes necessary. Software solutions currently anchor the product mix due to recurring subscription economics and lower deployment friction compared to capital-intensive hardware rollouts. AI Analytics within the technology stack represents the fastest-expanding capability layer as payers demand outcome validation and risk stratification from population health datasets. Diabetes Management applications command the deepest clinical investment given the region's prevalence trajectory and established reimbursement pathways for connected care.
India's CDSCO regulates software-as-medical-device classifications, while China's NMPA governs connected health product registrations through its medical device catalog system. Japan's PMDA imposes clinical evidence requirements that shape how AI diagnostic features gain market access across the region. Stakeholders must monitor how harmonization between national digital health frameworks affects cross-border platform scalability and data sovereignty compliance.
Market Dynamics
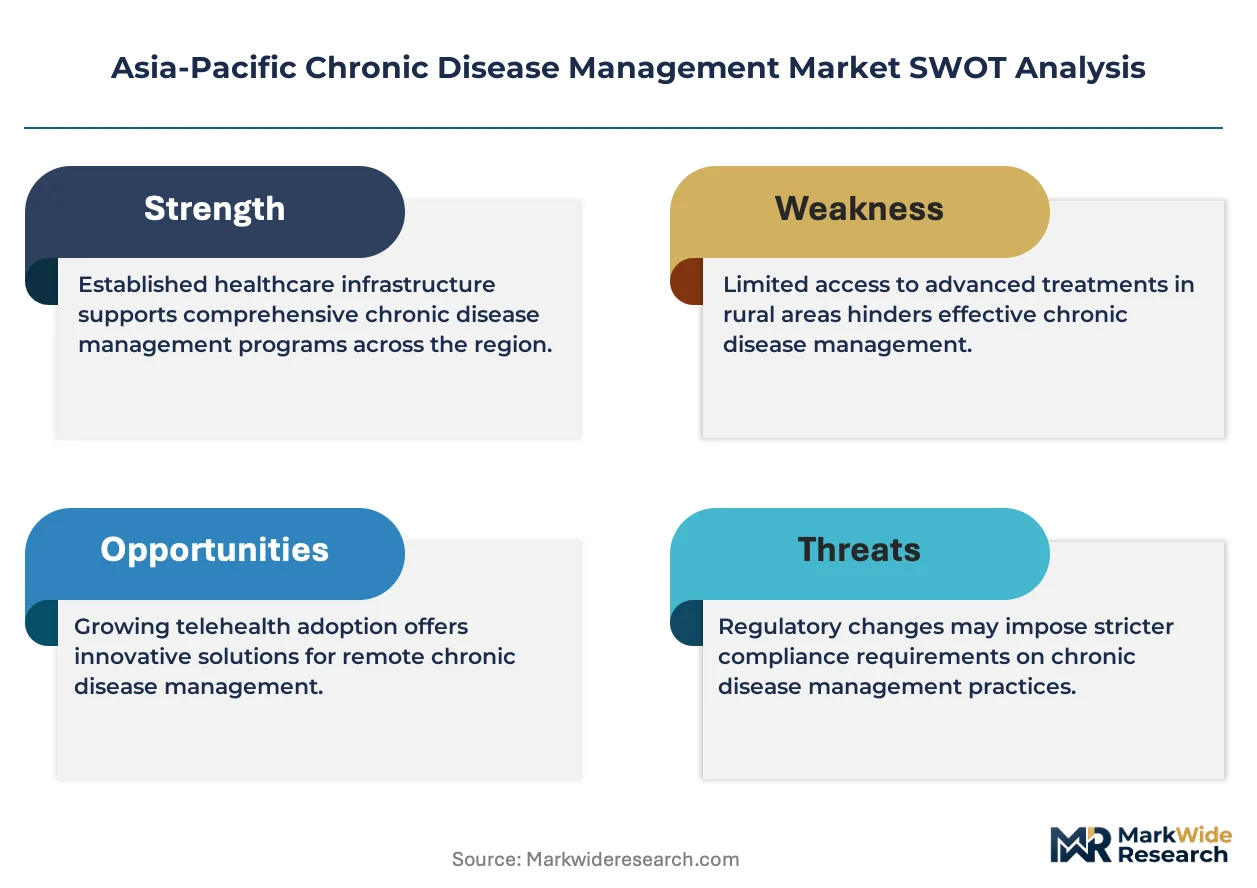
Hospital procurement committees across the Asia-Pacific region are consolidating vendor relationships around platforms demonstrating ISO 13485 certification, compressing competitive access for uncertified software vendors and elevating hardware-integrated suite providers.
Growth Catalysts
- China's NMPA medical device catalog expansion:The regulator's streamlined registration pathways for Class II connected health devices accelerate market entry timelines for glucose monitoring systems and blood pressure sensors.
- Hospital network consolidation in Australia:Integrated care platforms gain traction as Queensland and New South Wales health systems merge procurement across previously siloed facilities.
- Continuous glucose monitoring adoption:Endocrinology departments in tier-one Chinese cities deploy factory-calibrated sensors reducing clinician calibration burden and enabling remote patient dashboards.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundry capacity constraints create 16-24 week lead times for biosensor chipsets critical to connected monitoring devices.
- Japan's PMDA clinical evidence requirements:The regulator's demand for prospective validation studies extends AI diagnostic feature approval timelines beyond comparable ASEAN pathways.
- Legacy EHR integration costs:Proprietary data formats in incumbent hospital information systems force middleware expenditures consuming 30-40% of platform deployment budgets.
Strategic Opportunities
- India's tier-two and tier-three city penetration:Underpenetrated diagnostic infrastructure in Lucknow, Indore, and Coimbatore creates first-mover advantage for hub-and-spoke chronic care models.
- PLI scheme domestic manufacturing:India's production-linked incentive framework for medical devices enables cost-competitive local assembly of blood pressure monitors and pulse oximeters.
- 5G-enabled remote monitoring convergence:South Korea's MFDS fast-track approval for ultra-reliable low-latency communication devices opens real-time cardiac telemetry for ambulatory patients.
Industry Challenges
- Interoperability standard fragmentation:Divergent data exchange protocols between China's GB/T standards, Japan's JIS frameworks, and Australia's NEHTA specifications force redundant engineering for cross-border platform deployments.
- AI/ML talent scarcity:Shortage of clinicians with dual competency in predictive algorithm development and chronic disease protocols constrains feature rollout timelines for risk stratification modules.
- Data sovereignty compliance complexity:China's Cybersecurity Law and Australia's Privacy Act impose conflicting localization requirements on cloud-hosted patient records, complicating regional platform architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Chronic Disease Management Market |
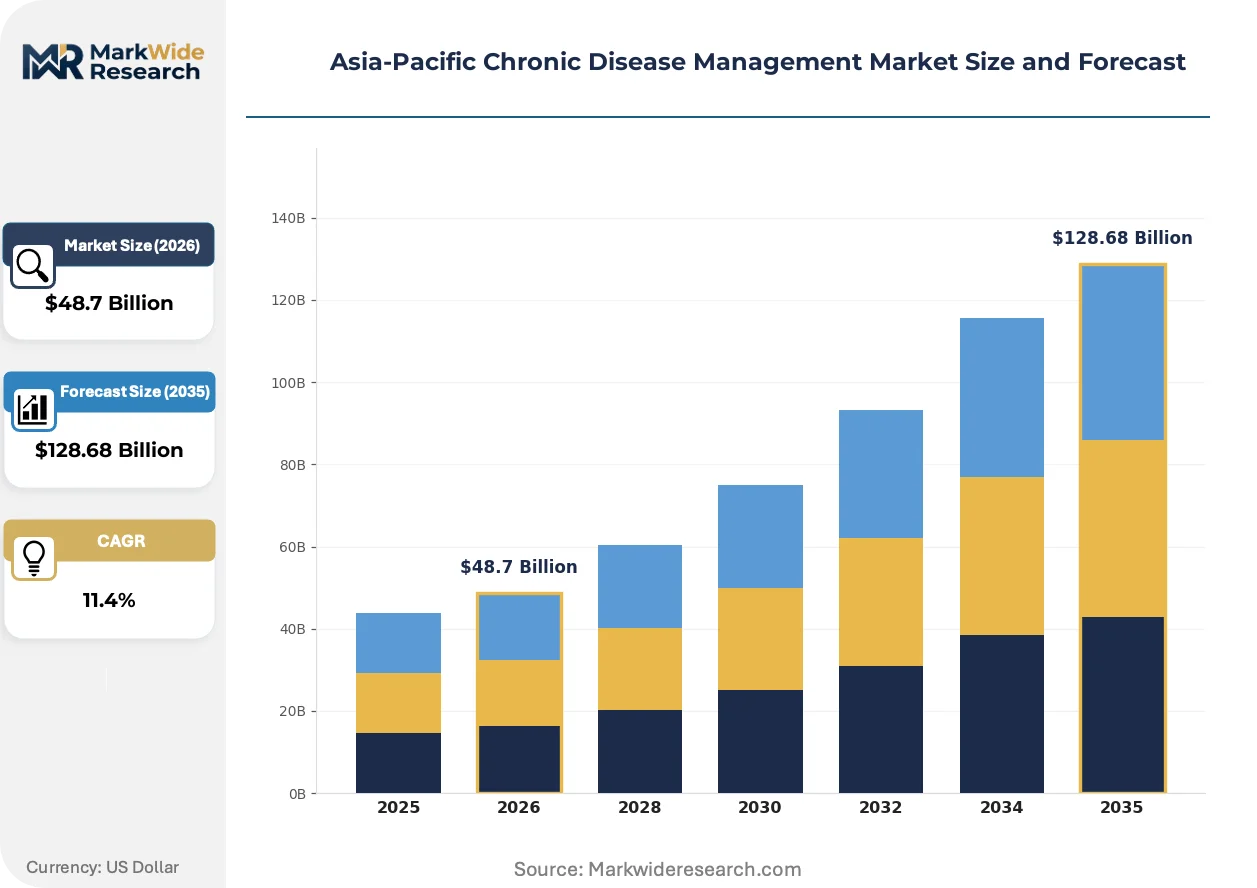
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Wearable Devices, Telehealth Services, Remote Monitoring Tools End User: Hospitals, Clinics, Homecare Agencies, Patients Technology: Telemedicine, Mobile Health, Cloud Computing, AI Analytics Application: Diabetes Management, Hypertension Control, Respiratory Care, Cardiovascular Monitoring |
| Companies Covered | Shenzhen Mindray Bio-Medical Electronics Co., Ltd, Nipro Corporation, Shimadzu Corporation, Philips, Allscripts Healthcare Solutions, Inc., Oracle Health, IBM Pvt Ltd, Qualcomm Life, Inc., EXL Healthcare, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Chronic Disease Management Market Trends and Innovations
Platform architectures are fragmenting into modular, API-first components that allow health systems to swap algorithm providers without replacing hardware infrastructure, fundamentally altering how procurement committees evaluate total cost of ownership.
Edge computing is decomposing the traditional cloud-centric model for chronic disease platforms. Continuous glucose monitors and blood pressure sensors now embed onboard inference engines processing anomaly detection locally. Australian hospital networks deploy these devices in rural clinics with intermittent connectivity. The shift compresses latency for critical alerts while reducing recurring cloud bandwidth expenditures that previously dominated operational budgets.
China's NMPA revised its software-as-medical-device classification guidance in 2023, explicitly delineating AI diagnostic features requiring clinical trial submission from lower-risk monitoring functions qualifying for expedited review. Domestic platform vendors restructure product roadmaps to segregate algorithm training pipelines from deployment codebases. Diabetes management applications face the steepest compliance burden given the regulator's heightened scrutiny of insulin dosing recommendations.
Hospital procurement committees now unbundle hardware acquisition from software subscription negotiations, treating connected monitoring devices as commodity endpoints while competing algorithm performance on predictive accuracy metrics. This bifurcation pressures device manufacturers to decouple sensor margins from platform recurring revenue. The pattern is most pronounced in Singapore's public hospital cluster procurement cycles, where three-year software contracts are tendered separately from capital equipment refresh programs.
Asia-Pacific Chronic Disease Management Market Segmentation
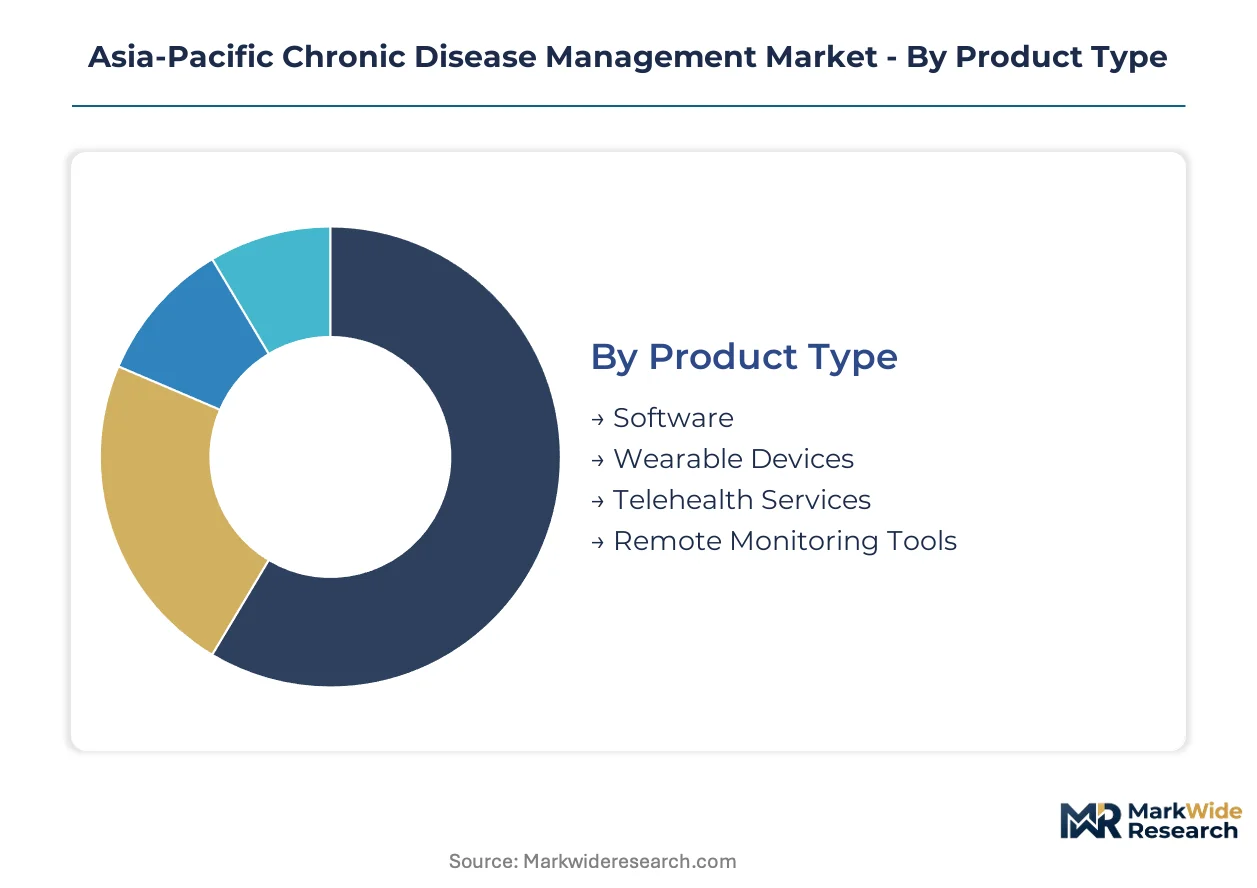
Segmentation in chronic disease management reveals where procurement committees allocate budgets across hardware, software, and service layers. Platform vendors configure pricing architectures around these divisions, with subscription economics diverging sharply from capital equipment cycles.
Product Type:
Margin pools concentrate in software subscriptions where recurring revenue compounds across multi-year hospital contracts, while hardware margins compress under procurement unbundling.
- Software:Cloud-native platforms integrate EHR connectivity, patient dashboards, and algorithm-driven risk alerts. Australian hospital networks prioritize ISO 13485-certified suites for Queensland and New South Wales consolidation programs. Subscription pricing dominates commercial models.
- Wearable Devices:Factory-calibrated continuous glucose monitors and blood pressure sensors embed edge computing for local anomaly detection. Demand clusters in China's tier-one cities where aging demographics intersect with digital health infrastructure deployment.
- Telehealth Services:Virtual consultation platforms with asynchronous messaging and prescription management.
- Remote Monitoring Tools:Hub-and-spoke diagnostic kits for rural clinic deployments in India's tier-two cities.
Software holds installed capacity. Wearable Devices are rotating up the share rankings.
End User:
Volume concentrates in institutional procurement channels where multi-site contracts override individual purchasing decisions.
- Hospitals:Integrated care platforms serve as the anchor customer for chronic disease management vendors. Australia's merged health systems in Queensland and New South Wales tender three-year software contracts separately from capital equipment, compressing vendor margins on hardware while elevating algorithm performance requirements.
- Homecare Agencies:Hub-and-spoke models extend hospital-grade monitoring into residential settings. India's underpenetrated tier-two cities present first-mover positioning for Lucknow, Indore, and Coimbatore deployments where diagnostic infrastructure remains sparse.
- Clinics:Rural and community-based facilities with intermittent connectivity needs.
- Patients:Direct-to-consumer channels for self-managed chronic conditions.
Hospitals command procurement volume. Homecare Agencies are climbing the fastest as reimbursement pathways mature.
Technology:
Application programming interface architectures determine how health systems swap algorithm providers without infrastructure replacement.
- AI Analytics:Predictive algorithms process population health datasets for risk stratification and outcome validation. Payers across the region now require evidence-based deterioration flagging before authorizing reimbursement, placing clinical-AI hybrid talent at a premium.
- Cloud Computing:Multi-tenant architectures host patient records while navigating China's Cybersecurity Law localization mandates against Australia's Privacy Act requirements. Data sovereignty compliance consumes substantial engineering resources for cross-border platform scalability.
- Telemedicine:Synchronous video consultation with integrated prescription workflows.
- Mobile Health:Smartphone-native applications for patient engagement and medication adherence tracking.
Cloud Computing holds current deployment share. AI Analytics is gaining share fastest as payer validation requirements harden.
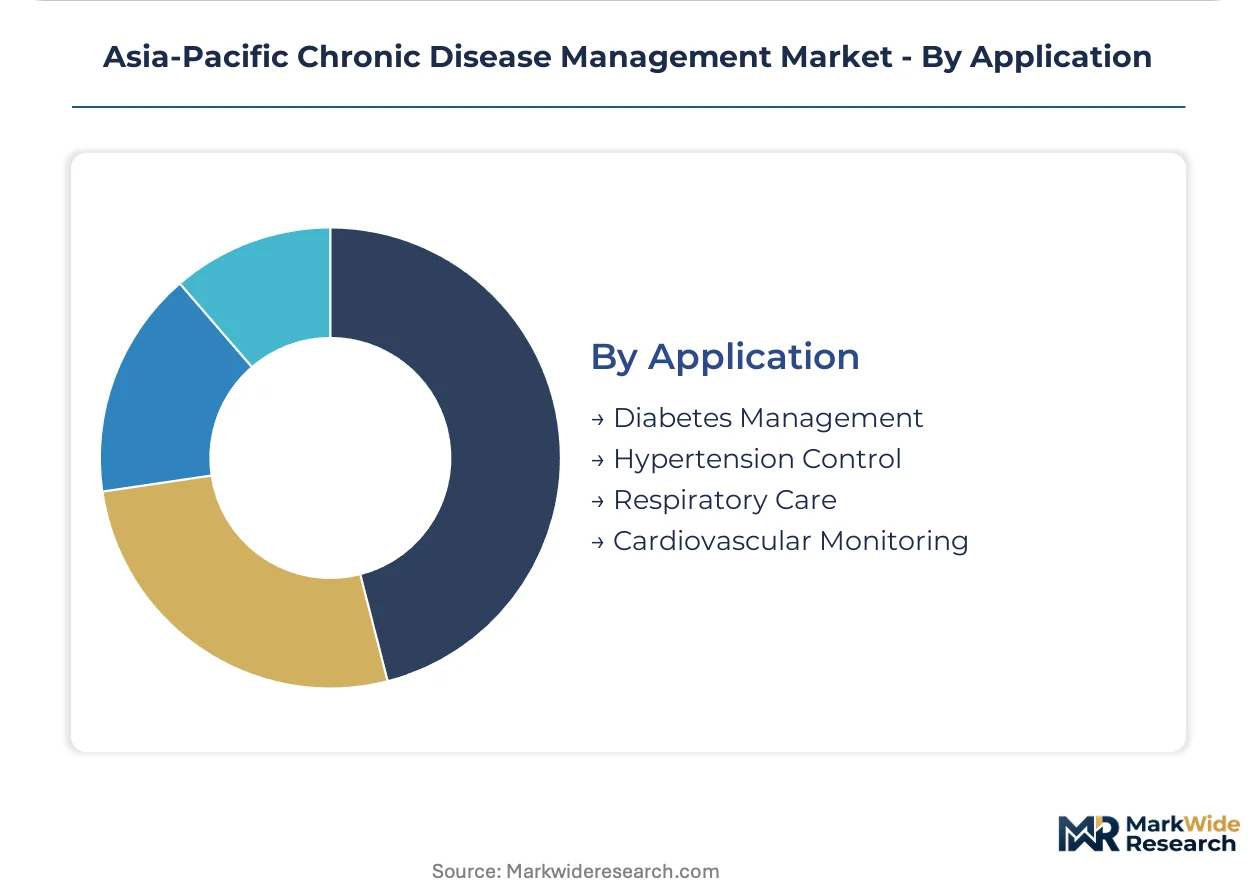
Application:
Clinical investment depth correlates with disease prevalence trajectories and established reimbursement pathways for connected care.
- Diabetes Management:Continuous glucose monitoring systems with predictive insulin dosing recommendations face the steepest regulatory scrutiny. China's NMPA explicitly segregates AI diagnostic features requiring clinical trial submission from lower-risk monitoring functions, forcing domestic vendors to restructure algorithm training pipelines.
- Cardiovascular Monitoring:Real-time cardiac telemetry benefits from South Korea's MFDS fast-track approval for 5G-enabled ultra-reliable low-latency communication devices. Ambulatory patient monitoring expands as reimbursement covers factory-calibrated blood pressure sensors.
- Hypertension Control:Connected blood pressure monitoring with medication adherence integration.
- Respiratory Care:Pulse oximetry and spirometry platforms for chronic obstructive pulmonary disease tracking.
Diabetes Management anchors current clinical investment. Cardiovascular Monitoring is rotating up the share rankings as 5G infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Asia-Pacific region's chronic disease management infrastructure depends on submarine cable landings at Singapore's Changi and Japan's Shima that enable cross-border health data flows. These digital arteries connect hospital networks across disparate regulatory jurisdictions.
China
Tier-one cities Beijing, Shanghai, and Shenzhen drive connected glucose monitor deployment through aging demographics and dense 5G coverage. NMPA's 2023 software-as-medical-device guidance imposes clinical trial requirements on AI insulin dosing features. Domestic vendors restructure algorithm pipelines to segregate training from deployment codebases.
Japan
Endocrinology departments in Tokyo and Osaka demand prospective validation studies for predictive risk algorithms. PMDA's clinical evidence requirements extend approval timelines beyond ASEAN pathways. Kanto region hospitals prioritize ISO 13485-certified platforms for multi-site procurement consolidation.
India
Hub-and-spoke diagnostic models penetrate Lucknow, Indore, and Coimbatore where specialist infrastructure remains sparse. CDSCO regulates software-as-medical-device classifications for glucose monitoring applications. PLI scheme incentives enable cost-competitive domestic assembly of blood pressure monitors and pulse oximeters.
Australia
Queensland and New South Wales health system mergers tender three-year software contracts separately from capital equipment. TGA oversight shapes procurement committee vendor consolidation around ISO 13485 certification. Rural clinics deploy edge-computing sensors with intermittent connectivity.
South Korea
MFDS fast-track approval for ultra-reliable low-latency communication devices enables real-time cardiac telemetry for ambulatory patients. Seoul Capital Area hospitals lead 5G-enabled remote monitoring adoption. Busan-Ulsan manufacturing clusters supply biosensor chipsets facing Taiwan foundry capacity constraints.
Asia-Pacific Chronic Disease Management Market Competitive Landscape
Listed leaders compete with private specialists across certification status and integration depth. Hospital procurement committees compress vendor access around ISO 13485 qualification, elevating hardware-integrated suite providers above uncertified software vendors. Three archetypes dominate: vertically integrated electronics manufacturers, cloud-native health IT platforms, and clinical workflow integrators. Dominant competitive moves include strategic partnerships with hospital networks and portfolio diversification into edge-computing sensor hardware.
Within the vertically integrated tier, Shenzhen Mindray Bio-Medical Electronics Co., Ltd exemplifies captive manufacturing control over biosensor supply chains. Philips and Oracle Health occupy positions on opposite vectors—Philips anchors clinical workflow integration across hospital systems, while Oracle Health represents cloud-native architecture designed for multi-site network orchestration. These three entities illustrate how certification status and infrastructure control determine procurement committee access.
| Leading Market Players |
|---|
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd |
| Nipro Corporation |
| Shimadzu Corporation |
| Philips |
| Allscripts Healthcare Solutions, Inc. |
| Oracle Health |
| IBM Pvt Ltd |
| Qualcomm Life, Inc. |
| EXL Healthcare |
| Others |
Pricing and Supply Chain Analysis
Sixteen-to-twenty-four week lead times for Taiwan-sourced biosensor chipsets compress procurement flexibility across Asia-Pacific hospital networks, concentrating pricing power with vertically integrated manufacturers while forcing buyers into longer-term contract commitments to secure allocation.
Pricing Analysis
Three-tier pricing structure across ISO 13485-certified premium suites, mid-tier integrated platforms, and economy hardware-only bundles dominates procurement negotiations. Certification grade and volume scale drive price differentiation, with Queensland and New South Wales health system mergers extracting steeper discounts through multi-site software contracts. Pricing pressure stems from procurement committees unbundling hardware from algorithm subscriptions, eroding device margins while elevating recurring revenue competition. Homecare agencies in India's tier-two cities exhibit highest price sensitivity; hospital networks in China's tier-one cities prioritize predictive accuracy over unit cost.
Supply Chain Analysis
Strategic stockpiling of biosensor chipsets supersedes just-in-time preferences as Taiwan foundry capacity constraints extend lead times. Manufacturing concentrates in China for finished glucose monitors, South Korea for 5G-enabled cardiac telemetry components, and Taiwan for semiconductor foundry output. Raw material dependencies include silicon wafers, medical-grade polymers, and lithium-ion cells for wearable power systems. Single-source vulnerability in Taiwan-based foundry capacity creates systemic exposure. Distribution runs through hospital procurement committees in Australia, government tenders in India, and direct vendor relationships with tier-one city health bureaus in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software subscription layers expand faster than hardware deployment cycles across Asia-Pacific chronic disease management, transforming vendor economics toward service-attach models with recurring revenue multiples exceeding capital equipment valuations.
For Market Incumbents: Compound ISO 13485 certification advantages into multi-year hospital network contracts before regulatory harmonization elevates compliance baselines. Defend algorithm performance leadership through clinical-AI hybrid talent acquisition as AI/ML capability scarcity constrains feature rollout timelines. Deepen backward integration into edge-computing sensor hardware to capture margin pools migrating from commodity endpoints toward predictive analytics engines. For New Entrants and Emerging Players: Anchor in India's tier-two and tier-three city diagnostic infrastructure gaps, where Lucknow, Indore, and Coimbatore present first-mover positioning for hub-and-spoke chronic care models. Target cardiovascular monitoring applications as 5G infrastructure matures and South Korea's MFDS fast-track approval pathway accelerates real-time telemetry market entry. Pursue white-label partnerships with domestic device manufacturers under India's PLI scheme to achieve cost-competitive positioning without captive manufacturing investment. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate health IT divisions lacking cloud-native architecture depth for multi-site network orchestration. Long-term viability favors platforms demonstrating clinical workflow integration and regulatory pathway expertise across NMPA, PMDA, and CDSCO jurisdictions. Monitor harmonization progress between China's Cybersecurity Law and Australia's Privacy Act as inflection indicator for regional platform scalability and cross-border consolidation feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Queensland and New South Wales mergers tender separate software contracts elevating algorithm performance requirements. |
| Software Companion Development | NMPA's 2023 guidance forces segregation of AI diagnostic features from monitoring functions, restructuring product roadmaps. |
| CE Marking Pathway | ISO 13485 certification bifurcates competitive access between qualified suite providers and uncertified vendors. |
| Reimbursement Strategy | Payer authorization for connected care in diabetes management requires evidence-based deterioration flagging from population datasets. |
| Backward Integration into Sensors | Taiwan foundry capacity constraints create 16-24 week lead times for critical biosensor chipsets. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement committee chairs, biomedical engineers, GPO contracts managers, and endocrinology department heads and refined through secondary validation against hospital procurement databases, GPO contract filings, CMS Medicare reimbursement data, and regulatory submission records from NMPA, PMDA, and CDSCO. Bottom-up estimates of platform deployments by city tier and hospital bed count were triangulated against top-down market sizing from software subscription economics and hardware shipment volumes.
Variance-decomposition across the projection horizon isolates volume drivers from pricing dynamics. The analytical framework models segmentation across product type, end user, technology layer, and application area, with regional regulatory clusters treated as distinct adoption envelopes. CAGRs were derived from fitted growth curves calibrated to historical deployment trajectories and payer reimbursement pathway maturation. Forecast inputs include semiconductor foundry capacity utilization rates and 5G infrastructure rollout schedules by metropolitan area.
Material uncertainties — Taiwan foundry capacity allocation shifts, NMPA software-as-medical-device reclassification, and Cybersecurity Law data localization enforcement — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and reimbursement authorization continuity. Practitioners should keep alternative scenarios live as harmonization between national digital health frameworks evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Neuropathic Pain Market
Pain Management
Provoked Vestibulodynia Treatment Market
Pain Management
Medicated Pain Relieving Plasters Market
Pain Management
Global Chiropractic Care Market
Pain Management
Pain Management Software Market
Pain Management
Pain Management Therapeutics Market
Pain Management
Pain Relief Oil Market
Pain Management
Opioid Withdrawal Management Market
Pain Management
Global Fibromyalgia Treatment Market
Pain Management
Plantar Fasciitis Treatment Market
Pain Management
Pain Therapeutic Solutions Market
Pain Management
Chronic Pain Treatment Market
Pain Management
Global Postoperative Pain Management Market
Pain Management
Pain Patches Market
Pain Management
Medical Morphine Market
Pain Management
Painkillers Market