
 Global Flange Fasteners Market | 2026-2036
Global Flange Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flange Fasteners Market Intelligence
Heightened demand from specialized Equipment Manufacturers for application-specific components is redrawing the competitive landscape previously defined by large-volume procurement from Building Contractors. STANLEY Engineered Fastening leverages its extensive distribution network to serve this evolving customer base. Wilhelm Bollhoff GmbH und Co. KG specializes in high-performance, custom-engineered solutions for demanding industrial uses. Parker-Hannifin Corporation differentiates through its integrated systems where fasteners are a critical performance component.
Flange fasteners are mechanical connectors, including bolts and nuts, characterized by an integrated washer-like flange under the head. This design distributes clamping force over a wider area, eliminating the need for a separate washer and improving load-bearing capacity. Among product types, flange bolts and nuts command the largest share due to their ubiquitous use in assembly operations. Material selection, particularly the choice between standard carbon steel and corrosion-resistant stainless steel, dictates suitability for applications from construction machinery to marine vessels.
Product quality and market access are governed by international standards such as ISO 898 for mechanical properties of fasteners. In Europe, compliance with CE marking directives is mandatory for fasteners used in regulated construction applications. Concurrently, standards from organizations like ASME in the United States dictate specifications for components in pressure vessels and piping. Vendor selection increasingly hinges on the ability to provide certified, traceable components that meet divergent regional and application-specific requirements.
Market Dynamics
The central dynamic in the flange fasteners market is the bifurcation of demand between high-volume, standardized components for construction and specialized, high-performance fasteners for critical industrial equipment, forcing suppliers to manage divergent certification and material science requirements.
Growth Catalysts
- Infrastructure Project Pipelines:Sustained public and private investment in global energy infrastructure, particularly LNG facilities in the United States and oilfield developments in the Middle East, creates consistent, large-scale demand for high-strength flange bolts and nuts.
- Renewable Energy Expansion:The construction of wind turbine towers and solar panel arrays requires vast quantities of corrosion-resistant fasteners capable of withstanding extreme environmental stress, driving consumption of specialized stainless steel and coated products.
- Mandatory Industrial Standards:The enforcement of codes like ASME for pressure vessels and piping systems mandates the use of certified and traceable fasteners, compelling end-users in chemical processing and power generation to procure premium, compliant components.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the pricing of key inputs like nickel, chromium, and high-grade carbon steel directly impact manufacturer cost structures, creating margin pressure and pricing instability for specialized alloy fasteners.
- Threat from Alternative Joining:The advancement of structural adhesives and welding techniques in specific automotive and aerospace applications presents a substitution risk, particularly where weight reduction is prioritized over disassembly and serviceability.
- Geopolitical Supply Risks:Heavy reliance on a few countries, notably China, for the primary production of steel and ferroalloys creates supply chain vulnerabilities, exposing fastener manufacturers to trade policy shifts and logistical disruptions.
Strategic Opportunities
- Additive Manufacturing for Customization:3D printing of metal alloys offers a pathway to produce highly customized, complex flange fasteners on-demand for prototyping, aerospace, and specialized machinery applications where traditional manufacturing is cost-prohibitive.
- Digital Component Traceability:Implementing QR code or blockchain-based systems for material certification and lifecycle tracking provides a value-added service, meeting end-user demand for quality assurance and compliance with standards like ISO 898.
- Lightweight Composite Fasteners:Developing non-metallic fasteners from advanced composites can unlock new applications in marine, electric vehicle, and chemical industries where superior corrosion resistance and weight savings are critical performance drivers.
Industry Challenges
- Complex Certification Pathways:Manufacturers face significant administrative and testing burdens to secure and maintain divergent regional certifications, such as Europe's CE marking and various ASME codes in North America, for a global product portfolio.
- Counterfeit Component Infiltration:The operational challenge of preventing non-certified and counterfeit fasteners from entering the supply chain remains a persistent risk, threatening structural integrity in critical applications like infrastructure and heavy equipment.
- Precision Manufacturing Skill Gaps:A shortage of skilled machinists and quality control technicians trained in advanced metallurgy and metrology impedes the ability of some manufacturers to consistently produce high-tolerance, zero-defect fasteners for demanding sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flange Fasteners Market |
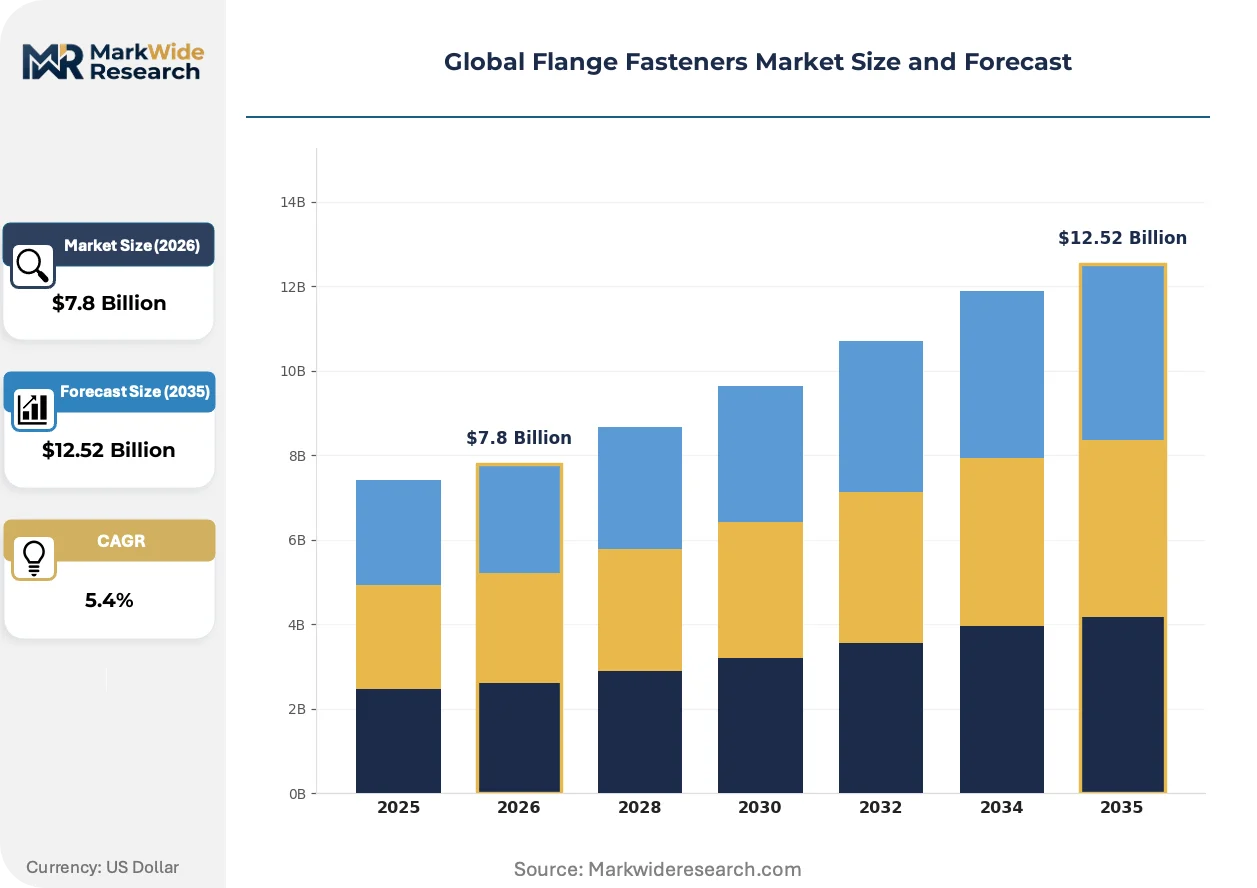
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bolts, Nuts, Studs, Washers, Retaining Rings Material: Carbon Steel, Stainless Steel, Alloy Steel, Brass, Titanium Application: Oilfield Equipment, Power Plants, Marine Vessels, Construction Machinery, Heavy Equipment End User: Energy Producers, Shipbuilders, Building Contractors, Equipment Manufacturers, Repair Workshops |
| Companies Covered | STANLEY Engineered Fastening, FULLER, Locknut Technology, Ramco Specialties, Wilhelm Bollhoff GmbH und Co. KG, Jergens, Parker-Hannifin Corporation, Penn Engineering & Manufacturing, AF Fasteners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flange Fasteners Market Strategic Shifts & Innovations
The market's evolution is defined by the integration of digital intelligence into mechanical components and a demand-side pull for verifiable performance data. This shift prioritizes fasteners not just as connectors, but as critical assets for ensuring operational integrity and safety.
Smart fasteners embedded with miniature sensors are gaining traction for monitoring clamp load, temperature, and vibration in real-time. Critical industries like aerospace and wind energy are adopting this technology to enable predictive maintenance and prevent catastrophic failures. This integration of sensing technology is miniaturizing the bulky external monitoring equipment once required, embedding diagnostic functions directly within the fastener itself and simplifying system design.
Regulatory frameworks are tightening performance and traceability mandates for structural components. The European Union's Construction Products Regulation (CPR) requires CE marking, which obligates manufacturers to provide a Declaration of Performance for fasteners used in buildings and civil engineering works. This directly impacts all suppliers in the European market, compelling investment in rigorous quality control and transparent documentation to prove compliance and maintain access.
A notable behavioral shift is occurring as original equipment manufacturers move away from transactional purchasing toward strategic partnerships for fastener supply. This trend displaces the traditional multi-tiered distribution model, with manufacturers in sectors like agricultural machinery and industrial robotics engaging directly with fastener specialists for application engineering support. This direct-sourcing model is most advanced in Germany's automotive sector, where supply chain integration is key to production efficiency.
Global Flange Fasteners Market Segmentation
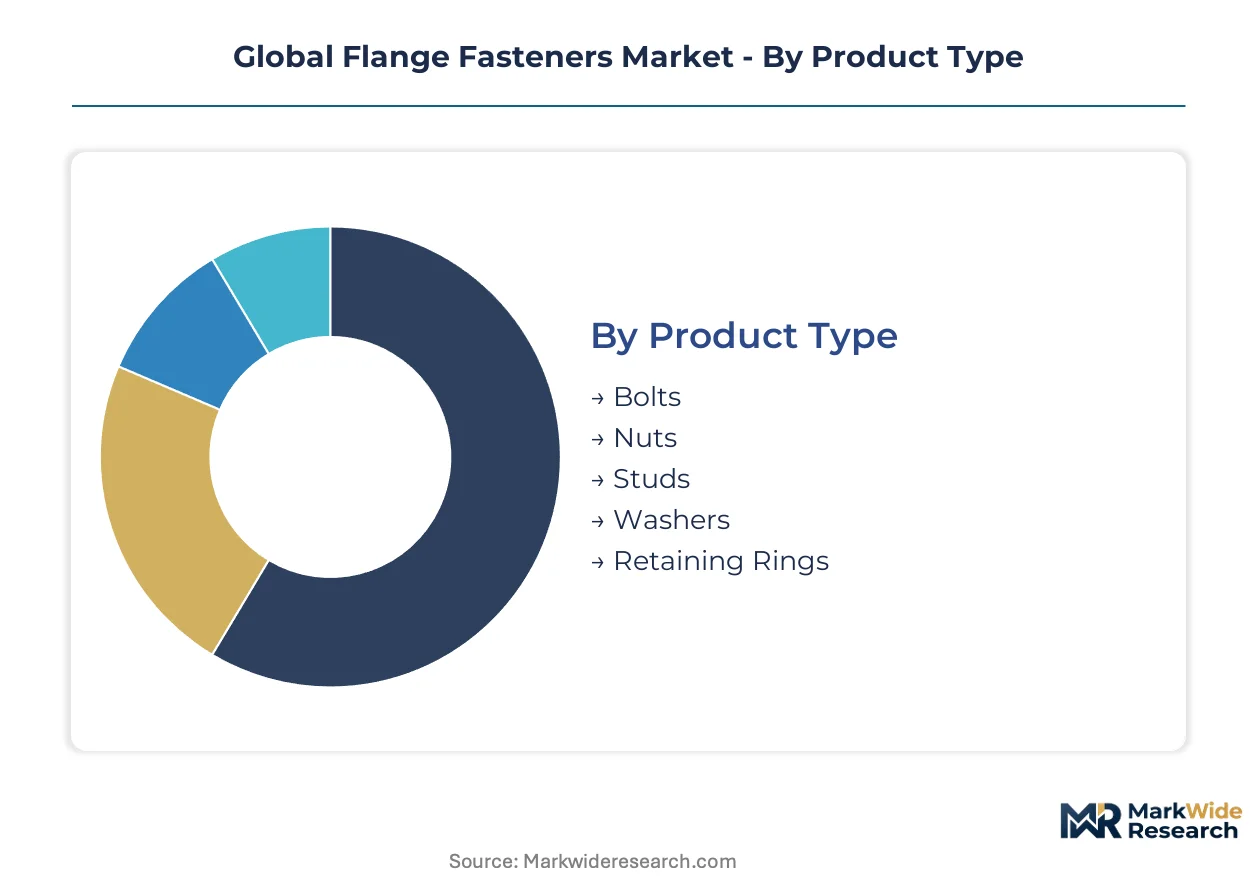
The flange fasteners market exhibits distinct segmentation across product types, materials, applications, and end-users, reflecting the diverse performance demands of industrial sectors. Understanding these segments is crucial for manufacturers to align product development and market strategies with evolving customer requirements. Each segment presents unique challenges and opportunities for specialized suppliers.
Product Type:
Regulatory compliance significantly influences the selection and specification of flange fastener product types across global industries.
- Bolts:These mechanical connectors feature an external thread and are designed to mate with a nut or a pre-tapped hole, providing high clamping force. Their ubiquitous use in structural and mechanical assemblies, particularly in large-scale infrastructure projects in the United States and China, drives consistent demand for certified components meeting ISO 898 standards.
- Nuts:Characterized by an internal thread, nuts are essential for securing bolts and distributing load effectively across a joint, often featuring an integrated flange. Demand concentrates in critical piping and pressure vessel applications within chemical processing plants in Europe, where ASME codes mandate robust and traceable fastening solutions.
- Studs:Threaded on both ends, studs facilitate connections where through-holes are impractical or require precise alignment in heavy machinery.
- Washers:These flat, thin plates distribute clamping load, prevent loosening from vibration, and protect mating surfaces in various construction environments.
- Retaining Rings:Designed to secure components onto shafts or within bores, retaining rings offer precise axial positioning in compact mechanical assemblies.
Established volume favors Bolts; emerging adoption favors Retaining Rings.
Material:
Material selection dictates both performance characteristics and overall cost efficiency for flange fasteners across diverse industrial settings.
- Stainless Steel:Known for superior corrosion resistance and aesthetic appeal, stainless steel fasteners are critical in marine, chemical processing, and food production environments. Consumption is particularly high in shipbuilding sectors in South Korea and Japan, where resistance to saltwater and harsh chemicals is paramount for structural integrity.
- Alloy Steel:Engineered for exceptional strength, hardness, and fatigue resistance, alloy steel fasteners withstand extreme temperatures and pressures, making them indispensable in oilfield equipment and power generation facilities. Significant demand comes from LNG export terminals in the US Gulf Coast and new nuclear power plant constructions in China.
- Carbon Steel:Offering a balance of strength and economy, carbon steel fasteners serve as the standard for general construction and non-corrosive industrial applications.
- Brass:Chosen for its corrosion resistance, electrical conductivity, and non-magnetic properties, brass fasteners find use in electrical equipment and decorative applications.
- Titanium:Prized for its high strength-to-weight ratio and excellent corrosion resistance, titanium fasteners are specified for aerospace, medical, and high-performance automotive uses.
Durability and environmental resilience drive material choices, with specialized applications increasingly favoring advanced alloys.
Application:
Diverse industrial applications create distinct demand profiles for flange fasteners, each requiring specific performance attributes and certification.
- Oilfield Equipment:Fasteners for oilfield equipment must endure extreme pressures, corrosive chemicals, and high temperatures in drilling rigs, pipelines, and refineries. Sustained investment in Middle Eastern oil and gas infrastructure, alongside new North American shale plays, creates consistent demand for high-strength, certified components.
- Power Plants:Critical for securing turbines, boilers, and piping systems in thermal, nuclear, and renewable energy facilities, these fasteners require high-temperature stability and long-term reliability. Global expansion of wind energy projects, particularly across Europe and Asia, drives consumption of specialized corrosion-resistant fasteners.
- Marine Vessels:Requiring high resistance to saltwater corrosion and robust mechanical properties, fasteners are essential for shipbuilding and offshore platforms.
- Construction Machinery:Heavy-duty applications in excavators, bulldozers, and cranes demand high-strength fasteners capable of withstanding significant shock and vibration.
- Heavy Equipment:This segment includes fasteners for mining machinery, agricultural equipment, and industrial vehicles, where durability and resistance to harsh operating conditions are critical.
Criticality of function drives customization in specific applications, while volume remains high in foundational industries.
End User:
Procurement patterns among end-users vary significantly, influencing supplier relationships and product specifications within the flange fasteners market.
- Equipment Manufacturers:Original Equipment Manufacturers (OEMs) integrate flange fasteners as critical components into their machinery, requiring precise specifications, consistent quality, and often application-specific engineering support. This demand for integrated supply relationships is particularly pronounced in Germany's advanced automotive and industrial robotics sectors.
- Energy Producers:Companies involved in oil, gas, and power generation procure large volumes of certified flange fasteners for new facility construction, maintenance, and upgrades. Major energy projects in the United States and the Middle East consistently drive demand for high-strength, traceable components that meet stringent industry standards.
- Shipbuilders:These entities require large quantities of corrosion-resistant fasteners meeting marine-specific standards for the construction and repair of various vessels.
- Building Contractors:Focused on large-volume procurement for construction projects, building contractors prioritize cost-effectiveness and adherence to general construction codes.
- Repair Workshops:These workshops source a diverse range of replacement flange fasteners for maintenance and overhaul operations across multiple industrial sectors.
Value chain integration deepens with specialized end-users, contrasting with transactional purchasing by volume-driven segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The trade flow of specialized flange fasteners from European manufacturers to critical infrastructure projects in the Middle East highlights regional interdependencies. Demand patterns for these essential mechanical connectors vary significantly across global geographies. Each region presents unique regulatory landscapes.
United States
Investment in LNG export terminals and oilfield developments drives demand for high-strength flange bolts and nuts in the United States. ASME codes for pressure vessels mandate certified and traceable components, ensuring reliability. The US Gulf Coast, with its expanding energy infrastructure, procures premium, compliant fasteners for new projects.
China
China's heavy manufacturing and shipbuilding sectors, alongside nuclear power plant constructions, create vast demand for certified flange fasteners. Compliance with GB standards is crucial for market access and product acceptance. The Yangtze River Delta region, a hub for industrial production, requires extensive quantities of certified components.
Germany
Specialized equipment manufacturers in Germany require high-performance, custom-engineered flange fasteners for advanced automotive and industrial robotics. CE marking directives are mandatory for fasteners in regulated construction applications, ensuring product safety. Bavaria's industrial heartland, home to numerous OEMs, drives demand for application-specific fastening solutions.
South Korea
South Korea's prominent shipbuilding sector demands large quantities of corrosion-resistant stainless steel fasteners for marine vessels and offshore platforms. Local marine-specific standards govern material and performance requirements. The Busan-Ulsan region, a major shipbuilding hub, consistently procures specialized fasteners for new vessel construction.
Saudi Arabia
Major energy projects in Saudi Arabia, encompassing oilfield equipment and power generation, consistently procure large volumes of certified flange fasteners. Procurement adheres to stringent industry standards for safety and reliability in extreme environments. The Eastern Province, central to the Kingdom's energy production, requires traceable components for its operations.
Global Flange Fasteners Market Key Industry Players
Player mix skews toward a blend of large-scale industrial suppliers and specialized engineering firms. The market structure exhibits a tiered approach, with some entities focusing on high-volume, standardized components while others target bespoke, high-performance solutions. Strategic archetypes include global distributors, custom solution providers, and integrated system specialists. Capacity expansion and strategic partnerships remain dominant competitive moves across the industry.
Within the specialized solutions segment, Wilhelm Bollhoff GmbH und Co. KG exemplifies a focus on high-performance, custom-engineered fasteners for demanding industrial applications. STANLEY Engineered Fastening represents a global distribution powerhouse, leveraging its extensive network to serve a diverse customer base, including specialized equipment manufacturers. Parker-Hannifin Corporation anchors the integrated systems approach, where fasteners function as critical performance components within broader product offerings. These entities demonstrate how market players differentiate through engineering expertise, distribution reach, and system integration capabilities, catering to distinct customer requirements within the flange fasteners market.
| Leading Market Players |
|---|
| STANLEY Engineered Fastening |
| FULLER |
| Locknut Technology |
| Ramco Specialties |
| Wilhelm Bollhoff GmbH und Co. KG |
| Jergens |
| Parker-Hannifin Corporation |
| Penn Engineering & Manufacturing |
| AF Fasteners |
| Others |
Cost & Logistics Intelligence
Scale economies in flange fastener manufacturing heavily influence supply concentration, establishing specific price floors for high-volume, standardized components. This dynamic shapes both global supply chain structures and regional pricing power for specialized solutions.
Pricing Analysis
The pricing gap between certified, high-performance flange fasteners and commodity-grade alternatives remains significant due to material science and testing requirements. Per-unit transactional pricing dominates for standard components, while contract-based long-term offtake agreements are common for specialized products. Price differentiation hinges on quality grade, certification level (e.g., ISO 898, ASME compliance), and volume scale. Raw material price volatility, particularly for nickel and chromium, creates margin pressure across all tiers. Building contractors often exhibit the highest price sensitivity, contrasting with the lower sensitivity of equipment manufacturers and energy producers for critical applications.
Supply Chain Analysis
Strategic stockpiling of critical raw materials is common among specialized flange fastener manufacturers to mitigate geopolitical supply risks. Geographic supply concentrates heavily in China for primary steel and ferroalloys, and in Germany for advanced manufacturing capabilities. The supply chain relies on key inputs like high-grade carbon steel, nickel, and chromium. Geopolitical trade policy shifts, particularly affecting China, pose a significant structural risk. Downstream distribution runs through multi-tiered networks for commodity fasteners, while specialized solutions increasingly favor direct sourcing and strategic partnerships with original equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flange fasteners market is at a platform-economics inflection point, driven by the interoperability of smart fasteners with real-time monitoring ecosystems.
For Market Incumbents:
Consolidate market share by acquiring specialized engineering firms with advanced material science capabilities. This move helps counter the threat from alternative joining techniques and counterfeit component infiltration. Invest heavily in expanding global distribution networks, particularly in emerging infrastructure markets, to leverage existing scale. Deepen certification expertise across diverse regional standards to maintain a competitive edge against new entrants.
For New Entrants and Emerging Players:
A service-layer gap exists in customized, application-specific solutions for niche industrial sectors. Target aerospace, specialized machinery, and marine applications where superior corrosion resistance and weight savings are critical performance drivers. Focus on a go-to-market strategy centered on additive manufacturing for rapid prototyping and on-demand production of complex designs. Offer digital traceability solutions as a value-added service to meet stringent compliance requirements.
For Investors and Strategic Acquirers:
Recurring-revenue conversion is highest among specialized solution providers offering integrated systems with long-term maintenance contracts. Long-term viability (over the next 5-10 years) remains strong, anchored by sustained global infrastructure investment. Target acquisition candidates should be specialized engineering firms possessing strong intellectual property in advanced alloys or sensor integration. The signal to watch is the increasing adoption rate of smart fasteners in critical infrastructure projects, indicating a shift towards performance-based procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification & Compliance Investment | Ensures access to regulated markets and meets stringent end-user requirements for safety-critical applications. |
| Additive Manufacturing Capability | Enables rapid prototyping and on-demand production of highly customized, complex flange fasteners. |
| Digital Traceability Integration | Provides end-to-end material certification and lifecycle tracking, enhancing quality assurance and compliance. |
| Advanced Materials R&D | Develops lightweight composite and corrosion-resistant fasteners for new applications in marine and EV sectors. |
| Strategic OEM Partnerships | Secures long-term supply agreements and integrates fastener design early into original equipment development cycles. |
Research Approach
A spread of perspectives from equipment manufacturers, energy producers, material scientists, and certification bodies converged on the working assumptions that underpin this analysis. This approach combined extensive primary interviews with industry stakeholders and rigorous secondary validation. Data was sourced from ISO/ASME standards, trade association reports, national statistical agencies, and corporate financial filings, ensuring a comprehensive bottom-up and top-down triangulation.
Product types, materials, applications, end-users, and regional regulatory compliance formed the segmentation dimensions modeled in this study. The analytical framework projects market trajectories across the analysis window. Compound annual growth rates were derived from historical trends and projected demand drivers, including infrastructure project pipelines and raw material availability. The model integrates specific inputs such as global energy investment trends and regional manufacturing output forecasts.
Forecasts assume regulatory continuity in key regimes like the European Union and the United States; material policy shifts would require re-modeling. The analysis reflects assumptions regarding geopolitical trade policies and raw material supply stability. Revision becomes warranted when unforeseen technological disruptions or significant raw material supply shocks cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Floor Pads Market
Tools
Gear Hobbing Cutter Market
Tools
Trim Press Market
Tools
Edging Tool Market
Tools
Cordless Impact Wrench Market
Tools
Mortiser Market
Tools
Machine Vise Market
Tools
Oxy-Fuel Torches Market
Tools
Tool Storage Market
Tools
Deburring Tool Market
Tools
Cutting Pipe and Perforating Pipe Drilling Tools Market
Tools
Landscaping Tools Market
Tools
Mechanical Springs Market
Tools
Boring Tools Market
Tools
Automatic Heat Press Machines Market
Tools
Adjustable Gripping Hand Tools Market