
 South Africa Prefabricated Buildings Market | 2026-2036
South Africa Prefabricated Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Prefabricated Buildings Market Insights
Buyer concentration among government agencies and large construction firms is expanding as public infrastructure tenders consolidate under fewer prime contractors. Kwikspace Modular Buildings leverages its Johannesburg manufacturing base to dominate bulk orders for education and health facilities. Prefab Group competes through specialized steel-frame modular units engineered for mining camp applications. Viva Group sustains its position by controlling distribution channels across the Western Cape and Eastern Cape provinces.
Prefabricated buildings are factory-manufactured structural assemblies incorporating steel frames, insulated panels, and composite cladding, transported to site for rapid erection with bolted or welded connections. These structures serve commercial, residential, and institutional functions where construction speed and cost predictability outweigh permanent-build aesthetics. Modular Buildings anchors the product mix through standardized volumetric units deployed repeatedly in school and clinic programs. Steel leads the material dimension due to its seismic resilience and compatibility with South Africa's established metal fabrication supply chain. Panelized Systems represent the fastest-growing product category as developers seek hybrid solutions blending factory precision with site flexibility.
South Africa's National Regulator for Compulsory Specifications enforces SANS 10400-XA energy efficiency standards that directly shape insulation specifications and glazing requirements in prefabricated designs. The country's Construction Industry Development Board grading system restricts tender eligibility, filtering market access toward certified manufacturers with proven delivery records. Stakeholders must monitor evolving municipal bylaws in Cape Town and eThekwini that increasingly prescribe permanent foundation standards even for nominally temporary structures.
Market Dynamics
Government procurement consolidation around standardized modular classrooms and clinics is compressing supplier margins while favoring manufacturers with captive steel fabrication and in-house transport logistics.
Growth Catalysts
- SANS 10400-XA Mandate:South Africa's energy efficiency standards for thermal performance are forcing insulation upgrades across all prefabricated education and health facilities, creating specification pull-through for composite panel systems.
- Mining Workforce Housing:Bulk procurement from platinum and coal operators in the North West and Mpumalanga provinces sustains demand for rapid-deployment steel-frame camps with integrated utilities.
- Panelized Hybrid Systems:Developers in Johannesburg's peri-urban corridor are specifying factory-cut structural insulated panels that combine volumetric precision with on-site foundation flexibility.
Market Restraints
- Steel Price Volatility:ArcelorMittal South Africa's domestic hot-rolled coil pricing tracks import parity, exposing modular manufacturers to input cost swings that tender-based contracts cannot pass through.
- Foundation Classification Disputes:Municipal bylaws in Cape Town and eThekwini increasingly reclassify nominally temporary structures as permanent builds, triggering full SANS 10400 compliance and extended approval timelines.
- Conventional Construction Substitution:Informal brick-and-mortar builders in low-income residential segments compete on perceived durability and resale value, limiting prefab penetration outside institutional buyers.
Strategic Opportunities
- Eastern Cape Undersupply:Viva Group's distribution control leaves room for new entrants to capture school and clinic tenders in Buffalo City and Nelson Mandela Bay municipalities.
- Renewable Energy Integration:Solar-ready roof specifications and battery storage pre-wiring are opening specification windows for modular units serving off-grid mining and agricultural operations.
- Construction Industry Development Board Certification:CIDB grading requirements for public tenders are filtering out uncertified competitors, creating margin expansion for established manufacturers with proven 9-rated delivery records.
Industry Challenges
- Welding Certification Bottlenecks:SANS-qualified structural welders are concentrated in Gauteng, forcing manufacturers to relocate skilled crews or absorb travel costs for KwaZulu-Natal and Western Cape deployments.
- Transport Modality Constraints:Abnormal load permits for volumetric module haulage face provincial coordination delays, compressing installation windows and triggering liquidated damages clauses in government contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Prefabricated Buildings Market |
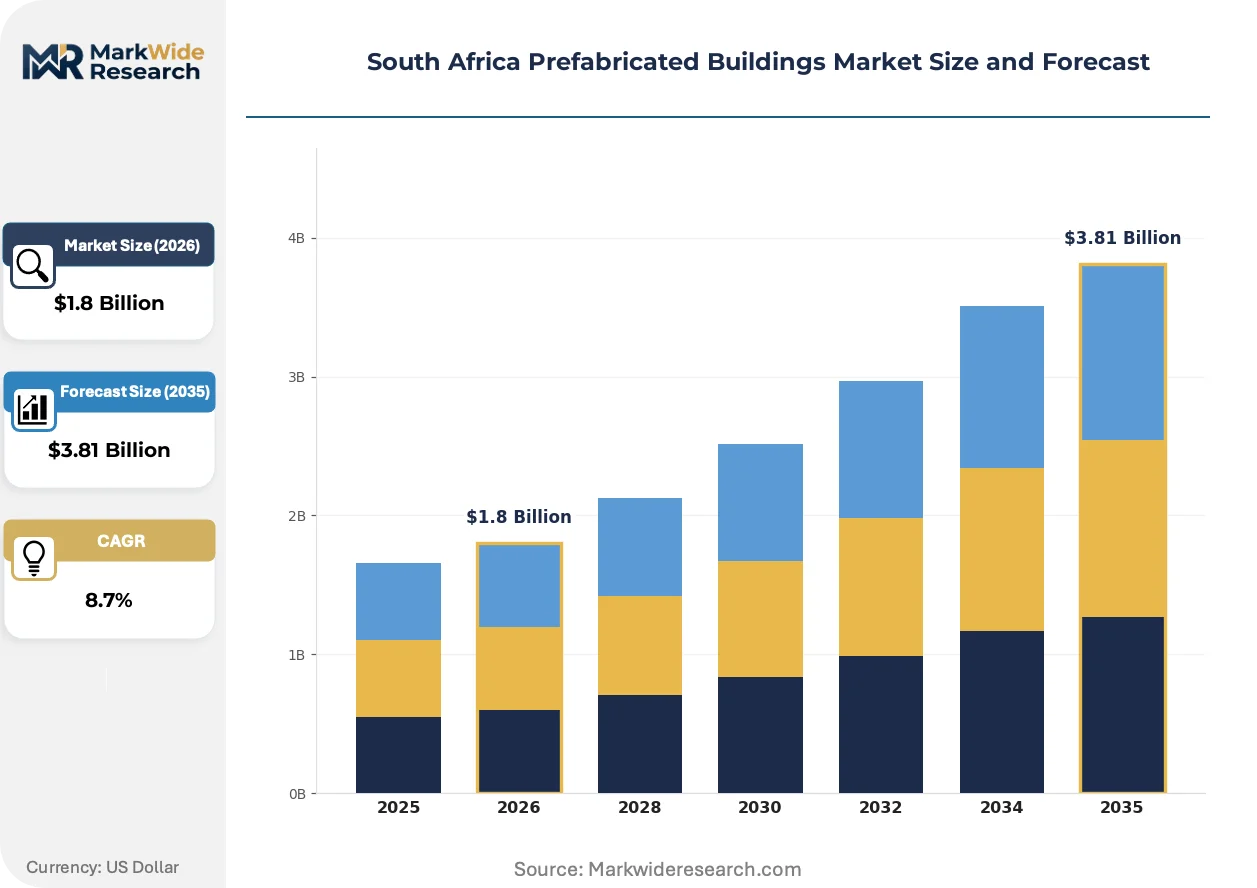
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Buildings, Transportable Units, Pre-Engineered Structures, Panelized Systems Application: Residential Use, Commercial Use, Temporary Structures, Disaster Relief End User: Construction Companies, Government Agencies, NGOs, Private Developers Material: Steel, Wood, Concrete, Composite Materials |
| Companies Covered | Kwikspace Modular Buildings, Prefab Group, Mobile Units, Viva Group, Proto Buildings, Park Homes, Speedspace, Modular Inspace, Waco Modular, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Prefabricated Buildings Market Trends and Innovations
Digital fabrication and regulatory tightening are converging to reshape how prefabricated structures are specified, manufactured, and deployed across South Africa's institutional and industrial buyer base.
Light-gauge steel framing integrated with structural insulated panels is unifying thermal performance and seismic resilience in a single factory-fabricated envelope. Mining operators in the Rustenburg platinum belt are specifying these hybrid systems for 18-month camp cycles. The technology is compressing traditional trade-stacking timelines by eliminating on-site insulation and cladding sequences.
SANS 10400-XA energy efficiency standards now mandate minimum R-values and solar gain coefficients for all prefabricated structures exceeding 50 square meters. Manufacturers must recertify panel assemblies through the South African Bureau of Standards, adding six to eight weeks to pre-production. Education facilities in Gauteng are responding by consolidating orders with suppliers holding current SABS mark certificates.
Bulk tender aggregation by provincial education and health departments is consolidating procurement around framework agreements with single-source accountability. Traditional competitive bidding for individual school projects is yielding to multi-year supply contracts with predetermined escalation clauses. This concentration is most visible in KwaZulu-Natal, where the provincial infrastructure department has reduced active modular classroom suppliers from twelve to four approved vendors.
South Africa Prefabricated Buildings Market Segmentation
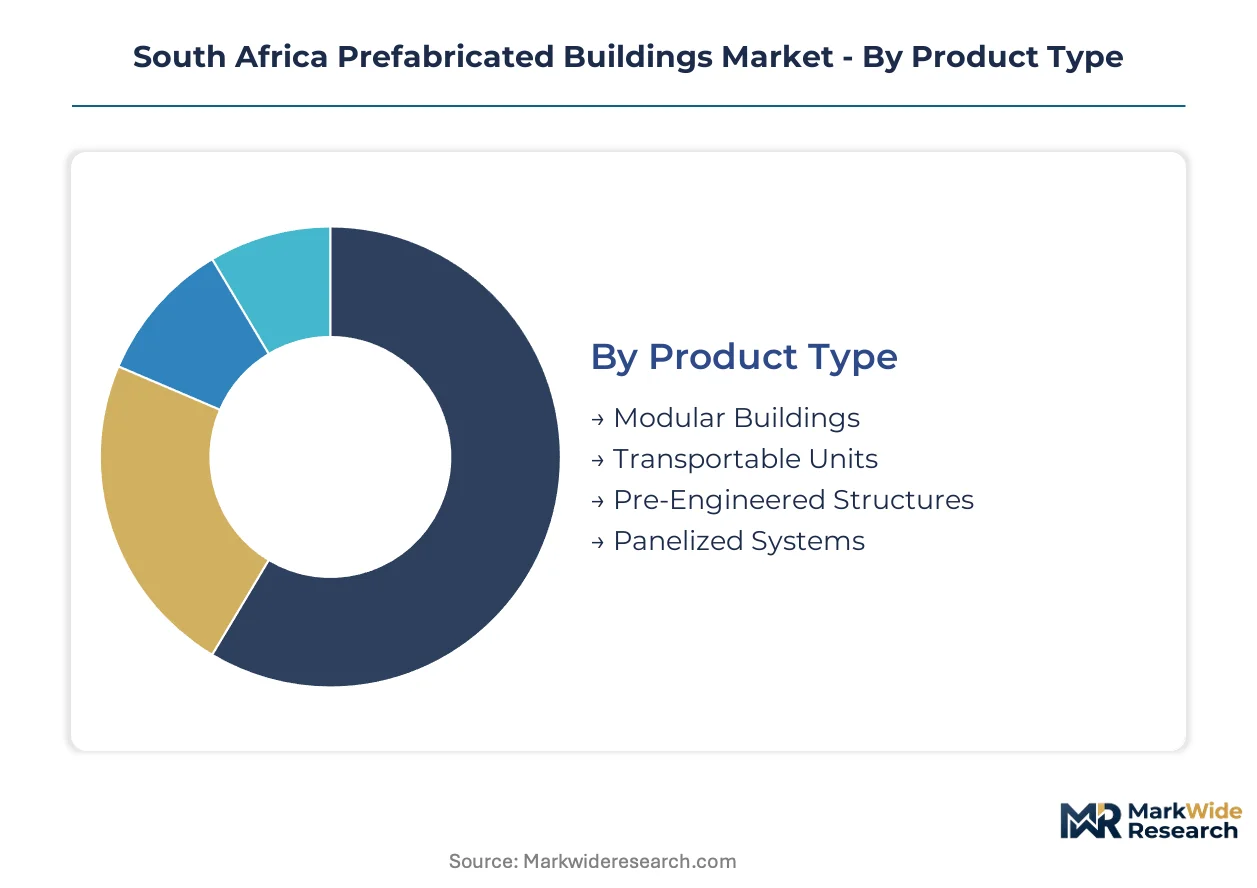
Segmentation in South Africa's prefabricated buildings market reveals how specification requirements, procurement channels, and material constraints reshape competitive positioning across institutional and industrial buyers. Understanding these divides exposes where margin pools concentrate and where new entrants face structural barriers.
Product Type:
Technical specification and factory integration depth separate winners from commodity players.
- Modular Buildings:Factory-finished volumetric units incorporating MEP systems, flooring, and cladding arrive site-ready for crane placement. Gauteng's education department tenders consolidate around these units for 50-plus classroom deployments where speed outweighs customization flexibility.
- Panelized Systems:Structural insulated panels factory-cut to precision tolerances enable hybrid construction blending off-site fabrication with on-site foundation adaptation. Johannesburg peri-urban developers specify these for workforce housing where land contours vary and crane access is limited.
- Pre-Engineered Structures:Steel-frame skeletons with bolted connections dominate mining camp applications requiring rapid erection without specialized welding crews.
- Transportable Units:Skid-mounted or wheel-based modules serve emergency health screening and mobile site offices where relocation frequency exceeds durability requirements.
Mature deployment sits with Modular Buildings. Newer deployment is concentrated in Panelized Systems.
Application:
Procurement channel and contract duration reshape product selection and margin structure.
- Temporary Structures:Nominal 5-15 year lifespan specifications dominate mining workforce camps and event infrastructure where capital recovery cycles compress tender pricing. North West platinum belt operators specify these with integrated solar pre-wiring for off-grid deployment.
- Commercial Use:Retail kiosks, remote banking facilities, and logistics site offices require SANS 10400-XA compliance for permanent occupancy classification, forcing insulation upgrades that separate certified from uncertified suppliers.
- Residential Use:Low-income housing programs and peri-urban densification projects face substitution pressure from informal brick-and-mortar builders competing on perceived resale value.
- Disaster Relief:Rapid-response specifications prioritize transportability over thermal performance, with KwaZulu-Natal flood recovery programs driving seasonal demand spikes.
Volume concentrates in Temporary Structures. Margin expansion is concentrated in Commercial Use.
End User:
Buyer sophistication and certification requirements filter supplier access.
- Government Agencies:Provincial education and health departments enforce CIDB 9-grade minimums and SABS panel certification, consolidating procurement around four approved vendors in KwaZulu-Natal.
- Construction Companies:Prime contractors on public infrastructure projects subcontract modular supply to meet accelerated completion clauses, creating tier-2 demand for certified manufacturers.
- Private Developers:Johannesburg logistics park and agricultural estate developers specify hybrid panelized systems where design flexibility outweighs standardization economies.
- NGOs:International relief organizations drive disaster response procurement with donor-funded specifications prioritizing speed over local content requirements.
Contract security sits with Government Agencies. Specification innovation is concentrated in Private Developers.
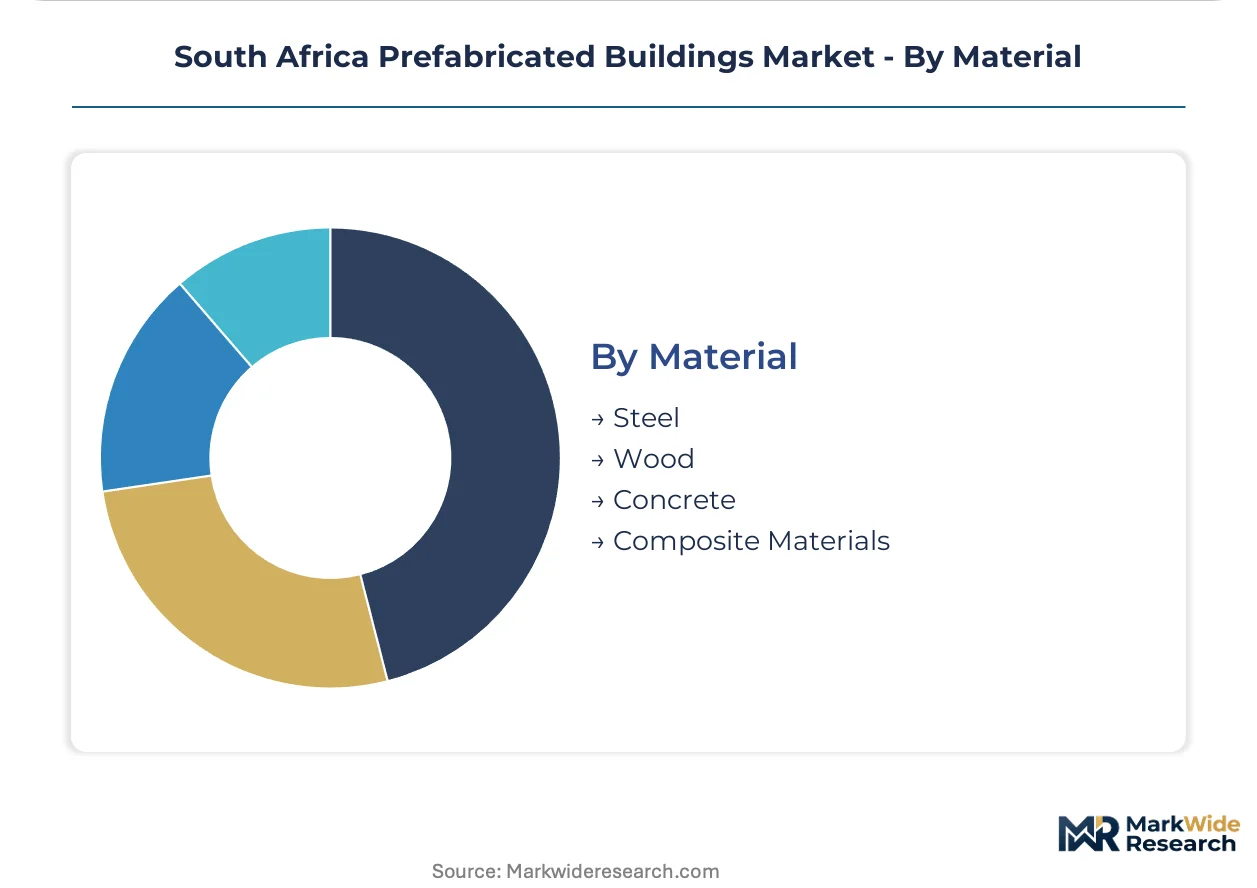
Material:
Supply chain geography and fabrication capability lock in competitive positions.
- Steel:Hot-rolled coil from ArcelorMittal South Africa and imported light-gauge sections feed Gauteng's metal fabrication cluster, with seismic resilience and established welding certification infrastructure sustaining dominance.
- Composite Materials:Glass-reinforced panels and insulated metal composites meet SANS 10400-XA thermal mandates while enabling thinner wall sections that maximize internal volume for transport constraints.
- Wood:Timber-frame modules face moisture degradation concerns in KwaZulu-Natal's humid coastal belt, limiting deployment to Western Cape applications with established treated-lumber supply chains.
- Concrete:Precast panel systems compete in permanent foundation classifications where municipal bylaws trigger full SANS 10400 compliance, extending approval timelines but enabling longer asset depreciation.
Supply maturity sits with Steel. Regulatory tailwinds are concentrated in Composite Materials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for prefabricated structures concentrates in South Africa's economic heartland, with provincial procurement programs and mining operations driving deployment patterns across distinct sub-regional corridors.
Gauteng
The Johannesburg peri-urban corridor hosts the densest concentration of modular manufacturing capacity, with provincial education and health departments tendering bulk classroom and clinic orders. SANS 10400-XA energy efficiency mandates force insulation upgrades on all structures exceeding 50 square meters. Pretoria's manufacturing cluster supplies standardized volumetric units to mining camps in the North West platinum belt.
KwaZulu-Natal
Flood recovery programs and school infrastructure backlogs sustain seasonal demand spikes across eThekwini and surrounding municipalities. The provincial infrastructure department consolidated approved modular classroom suppliers from twelve to four vendors, tightening procurement access. Durban's port logistics enable composite panel imports that feed panelized system assembly for coastal commercial projects.
Western Cape
Cape Town's municipal bylaws increasingly reclassify nominally temporary structures as permanent builds, triggering full SANS 10400 compliance and extended approval timelines. Viva Group controls distribution channels across the province, leaving limited tender access for new entrants. The Stikland industrial zone anchors timber-frame module production serving agricultural estate developments.
Eastern Cape
Buffalo City and Nelson Mandela Bay municipalities present undersupply opportunities for school and clinic tenders where incumbent distribution networks remain thin. The province's humid coastal belt degrades untreated wood structures, favoring steel-frame and composite material specifications. East London's manufacturing base lacks captive steel fabrication, forcing reliance on Gauteng supply chains.
North West
Platinum and coal mining operators in the Rustenburg belt sustain demand for rapid-deployment steel-frame camps with integrated solar pre-wiring for off-grid deployment. ArcelorMittal South Africa's hot-rolled coil pricing volatility directly impacts modular camp construction costs. The province's sparse population density favors transportable skid-mounted units over permanent foundation structures.
South Africa Prefabricated Buildings Market Competitive Landscape
Gauteng producers anchor one tier; Western Cape and KwaZulu-Natal specialists hold regional distribution positions. The market structure consolidates around framework agreements with provincial governments, compressing active vendor pools while expanding contract values. Three archetypes dominate: integrated manufacturers with captive steel fabrication, regional distributors controlling logistics corridors, and mining-focused specialists engineering seismic-resilient camps. Competitive moves center on CIDB 9-grade certification acquisition and abnormal load permit coordination to compress installation windows.
Among Johannesburg-based fabricators, Kwikspace Modular Buildings and Prefab Group exemplify divergent specialization vectors—one toward institutional bulk supply, the other toward mining camp engineering. Viva Group occupies a position as Western Cape distribution anchor, leveraging channel control to sustain margin structures against Gauteng competitors. These three names represent how geographic origin and procurement channel focus shape competitive positioning within a market filtering toward certified, proven delivery records.
| Leading Market Players |
|---|
| Kwikspace Modular Buildings |
| Prefab Group |
| Mobile Units |
| Viva Group |
| Proto Buildings |
| Park Homes |
| Speedspace |
| Modular Inspace |
| Waco Modular |
| Others |
Pricing and Supply Chain Analysis
Light-gauge steel framing integrated with structural insulated panels is compressing fabrication timelines while concentrating procurement leverage among Gauteng-based manufacturers with captive metalworking capacity. This production-method transition simultaneously elevates energy-efficiency compliance costs and locks in supplier tiers based on SABS certification status and CIDB grading.
Pricing Analysis
Volume concentrates in bulk government tenders for modular classrooms while margin expansion sits with specialized mining camp configurations. Three-tier pricing structure across premium certified, standard compliant, and economy ungraded levels separates SABS-mark holders from uncertified competitors. Cost compression in the economy tier is intensifying because steel input volatility from ArcelorMittal South Africa cannot be passed through fixed-price government contracts. Municipal education departments exhibit highest price sensitivity; platinum mining operators in the Rustenburg belt demonstrate lowest sensitivity due to rapid-deployment requirements.
Supply Chain Analysis
South Africa's local-content procurement rules for public infrastructure are reshaping sourcing patterns toward domestic steel fabrication and composite panel assembly. Supply concentration centers on Gauteng's metalworking cluster, with secondary nodes in Western Cape timber processing and KwaZulu-Natal port logistics. Hot-rolled coil from ArcelorMittal South Africa, imported light-gauge steel sections, and glass-reinforced composite panels constitute critical input dependencies. Single-source vulnerability runs through ArcelorMittal's domestic pricing parity with import benchmarks. Distribution runs through provincial framework agreements that consolidate vendor pools and compress installation windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Panelized hybrid systems are displacing conventional volumetric modular construction across Johannesburg's peri-urban corridor, creating a technology-transition window where certification investment and logistics coordination determine competitive survival.
For Market Incumbents: Deploy abnormal load permit coordination as a service differentiator to compress installation timelines and avoid liquidated damages. Acquire CIDB 9-grade certification lock-in through multi-year framework agreements with provincial education departments. Counter steel price volatility through backward integration into light-gauge roll-forming capacity or long-term offtake arrangements with ArcelorMittal South Africa. For New Entrants and Emerging Players: Enter via Eastern Cape school and clinic tenders in Buffalo City and Nelson Mandela Bay where Viva Group's distribution control remains thin. Target mining camp renewable energy integration as the most penetrable application, specifying solar-ready roof assemblies and battery pre-wiring for off-grid platinum belt deployments. Pursue subcontractor relationships with CIDB-graded prime contractors on accelerated public infrastructure completions. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated construction groups seeking modular capabilities for public sector framework eligibility. Long-term viability hinges on manufacturers navigating SANS 10400-XA recertification cycles and municipal foundation reclassification risks. Watch for abnormal load permit streamlining across provincial boundaries as the signal indicating logistics-coordination moat erosion.| Strategic Initiative | Industry Significance |
|---|---|
| CIDB 9-Grade Certification Investment | Unlocks eligibility for consolidated KwaZulu-Natal education tenders reducing active vendors from twelve to four. |
| Backward Integration into Steel Fabrication | Captures margin from ArcelorMittal coil volatility and secures supply continuity for bulk government orders. |
| Abnormal Load Permit Coordination | Compresses installation windows in government contracts with liquidated damages clauses for delayed delivery. |
| Solar-Ready Module Specification | Captures mining camp demand in North West platinum belt where off-grid deployment is mandatory. |
| Eastern Cape Distribution Partnership | Establishes channel presence in undersupplied Buffalo City and Nelson Mandela Bay municipal markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with modular manufacturing plant managers, provincial education procurement officers, mining camp facilities directors, and CIDB certification auditors supplied operational validation. Construction Industry Development Board grading registers, South African Bureau of Standards certification databases, and ArcelorMittal South Africa pricing disclosures constituted core documentary sources. Bottom-up unit deployment tracking across Gauteng, KwaZulu-Natal, and Western Cape provinces triangulated against top-down provincial infrastructure budget allocations.
Granularity-level modeling disaggregated volume and value across product type, application, end user, material, and provincial jurisdiction throughout the forecast period. Panelized systems, modular buildings, pre-engineered structures, and transportable units were modeled separately with distinct growth trajectories. Mining workforce housing, temporary institutional structures, commercial use, and residential applications carried differentiated specification and margin assumptions. CAGRs derived from regression against historical deployment patterns, provincial budget trajectory analysis, and mining capital expenditure cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained steel price volatility or accelerated municipal foundation reclassification. Projections reflect assumptions regarding CIDB consolidation pace, SANS 10400-XA enforcement intensity, and abnormal load permit coordination improvements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Russia Prefabricated Buildings Market
Building Construction
GCC Green Buildings Market
Building Construction
Singapore Data Center Construction Market
Building Construction
North America Modular Construction Market
Building Construction
UAE Facade Market
Building Construction
Global Dry Construction Market
Building Construction
El Salvador Construction Market
Building Construction
Italy Construction Market
Building Construction
United Arab Emirates Infrastructure Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
India Prefabricated Buildings Market
Building Construction
GCC Construction Market
Building Construction
Construction Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
China Construction Market
Building Construction
France Prefab Wood Building Market