
 Education Building Design Market | 2026-2036
Education Building Design Market Size, Share, and Industry Trends Forecast 2026-2036
Education Building Design Market Insights
Building performance modeling as a subscription service is decoupling design fees from capital expenditure cycles, letting districts spread costs across operating budgets. CannonDesign leverages this shift through its proprietary analytics platform for K-12 energy benchmarking. Stantec anchors its position with integrated sustainability consulting bundled into long-term facility management contracts. HOK competes by dominating university science and technology precincts where lab flexibility commands premium design fees.
Education building design encompasses the programming, spatial planning, and systems integration of learning environments, requiring coordination of HVAC loads, acoustic performance targets, and daylighting metrics to support pedagogical outcomes. The discipline serves public and private institutions seeking to optimize capital efficiency while meeting evolving instructional delivery models. University and high school segments concentrate the largest project values, with university work sustaining higher margins due to complex research facility requirements. Modular construction methods are gaining share fastest in elementary and vocational institute projects where speed-to-occupancy drives procurement decisions. Public funding remains the dominant capital source, though private investment is expanding in charter school and international branch campus developments.
The US Department of Education, EPA, and ADA standards jointly shape facility compliance thresholds, with energy benchmarking mandates and accessibility upgrades filtering directly into design scope expansion. State-level carbon reduction targets in California and New York are extending these requirements into embodied carbon calculations and electrification roadmaps. Stakeholders must monitor how bond market volatility and shifting enrollment demographics redistribute project opportunity across district types and institutional tiers.
Market Dynamics
Hybrid learning infrastructure mandates are compressing traditional design-bid-build timelines as districts demand simultaneous physical retrofit and digital integration, forcing firms to restructure fee models around operational rather than capital expenditure cycles.
Growth Catalysts
- EPA Energy Benchmarking Mandates:Federal compliance thresholds are expanding design scope into continuous monitoring systems, creating recurring revenue streams for firms with analytics capabilities.
- Texas Enrollment Surge:Rapid population growth in Dallas-Fort Worth and Houston corridors is accelerating K-12 bond referendums and university expansion projects.
- Mass Timber Systems:Cross-laminated timber and glulam assemblies are reducing embodied carbon footprints while enabling faster enclosure schedules for multi-story academic buildings.
Market Restraints
- Skilled Labor Concentration:MEP contractors capable of complex laboratory integration cluster in California, Texas, and Massachusetts, creating geographic bottlenecks for national project execution.
- Steel and Aluminum Volatility:Structural metal price swings are destabilizing guaranteed maximum price contracts and eroding contingency reserves on fixed-fee engagements.
- ADA Title II Compliance Friction:Accessibility upgrade scopes are expanding unpredictably during construction administration, triggering change order disputes with public agency clients.
Strategic Opportunities
- Vocational Institute Modernization:Federal Perkins Act reauthorization is channeling capital into career and technical education facilities requiring specialized equipment integration and industry partnership spaces.
- Electrification Roadmaps:New York and California state carbon mandates are mandating all-electric HVAC transitions, opening consulting revenue streams for firms with thermal modeling expertise.
- Performance-Based Procurement:Ohio and Virginia districts are piloting design-build-finance-operate-maintain contracts that transfer long-term energy risk to design teams in exchange for extended fee structures.
Industry Challenges
- Building Information Modeling Talent Scarcity:Firms struggle to hire technicians capable of clash detection and 4D sequencing for complex research facility coordination.
- Commissioning Timeline Compression:Accelerated occupancy demands are truncating functional testing periods, risking post-occupancy performance failures in laboratory environments.
- Legacy System Integration:Campus-wide digital twin implementations require interoperability with decades-old BAS infrastructure, creating data standardization bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Education Building Design Market |
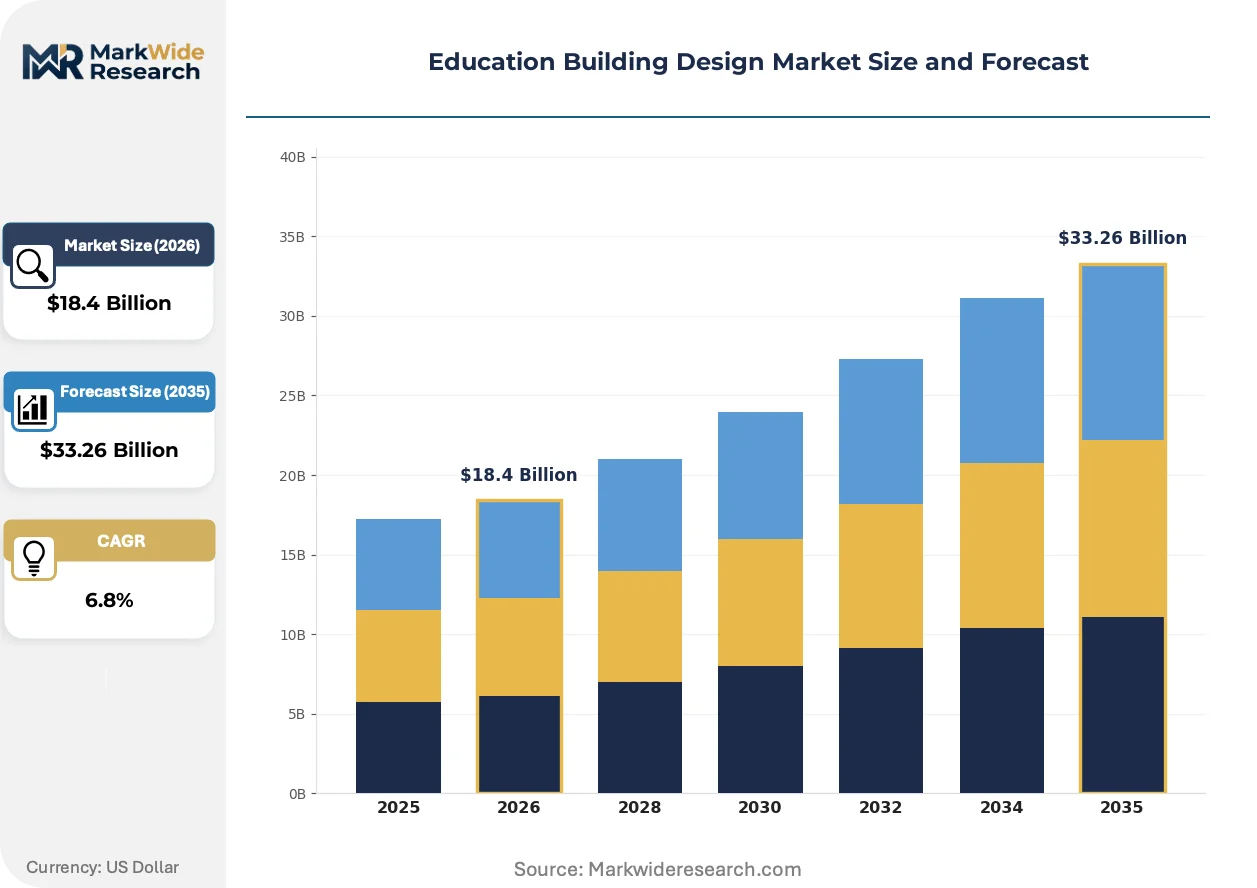
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $33.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Elementary School, High School, University, Vocational Institute Design Feature: Sustainability, Accessibility, Flexibility, Safety Enhancements Construction Method: Modular, Traditional, Green Building, Pre-engineered Funding Source: Public Funding, Private Investment, Grants, Donations |
| Companies Covered | CannonDesign, Stantec, Gensler, HOK, HDR, Perkins&Will, DLR Group, Page, SmithGroup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Education Building Design Market Trends and Innovations
Computational design tools and prefabrication methods are restructuring how learning environments are conceived, procured, and delivered, with implications for project risk allocation and professional liability frameworks.
Generative design algorithms are overtaking traditional space planning workflows by automating daylighting optimization and HVAC load distribution across complex building geometries. University science precincts in California and Massachusetts are adopting these tools at the schematic phase, compressing programming cycles from months to weeks while enabling real-time cost feedback that is overtaking static square-footage pricing models.
The EPA's proposed Lead and Copper Rule revisions are mandating full plumbing replacement in pre-1990 school buildings, extending construction schedules and activating hazardous material protocols. Districts in Illinois and Pennsylvania face the most severe compliance exposure due to aging building stock, with many accelerating summer renovation windows to accommodate extended abatement timelines.
Districts are consolidating design services under single-source master contracts rather than project-specific RFPs, compressing vendor rosters and privileging firms with multi-state licensure and surety capacity. Ohio and Florida education departments have adopted this model most aggressively, with five-year indefinite delivery contracts replacing annual competitive bidding for architectural and engineering services.
Education Building Design Market Segmentation
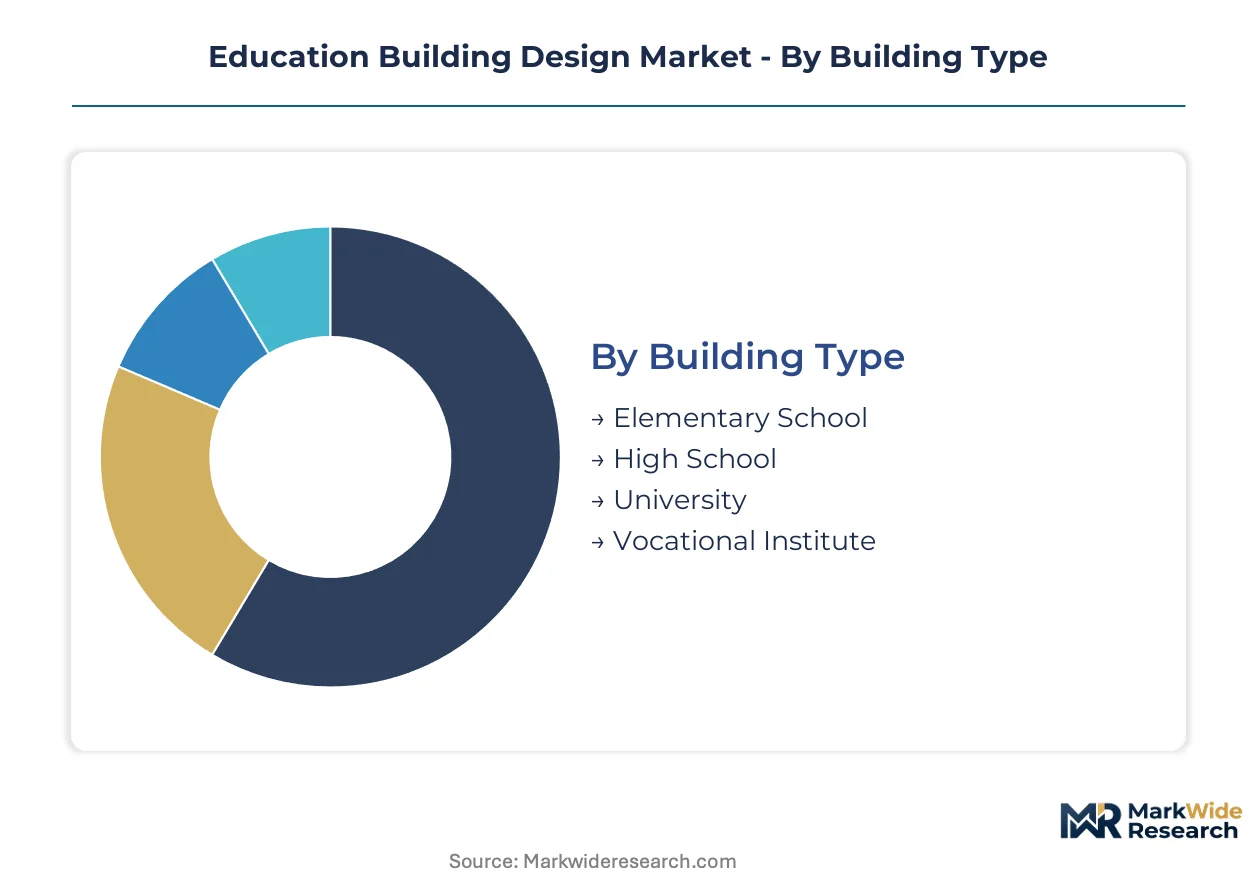
Education building design procurement divides sharply across institutional tiers and capital sources, with university and vocational segments commanding premium fee structures while K-12 work concentrates project volume. Understanding these fault lines clarifies where design firms must build specialized capabilities versus scalable delivery capacity.
Building Type:
Capital allocation intensity determines segment attractiveness, with research facility complexity sustaining margins that general classroom work cannot match.
- University:Laboratory specifications drive MEP coordination depth, with flexible research suites requiring adaptive structural systems and hazardous material containment infrastructure. Science and technology precincts in California and Massachusetts concentrate the highest-value commissions where principal-led design teams capture extended engagement scopes.
- Vocational Institute:Career and technical education facilities integrate industry partnership spaces and specialized equipment bays that demand direct manufacturer coordination. Federal Perkins Act capital is channeling into Texas and Ohio districts where equipment-heavy programs are expanding fastest.
- High School:Performing arts centers and athletic complexes anchor capital programs in suburban districts with active bond referendums.
- Elementary School:Speed-to-occupancy priorities favor modular methods and repeatable prototypes across fast-growing Florida and Texas corridors.
Volume sits with Elementary School; growth tilts toward Vocational Institute.
Design Feature:
Regulatory compliance thresholds are expanding baseline scope, transforming optional enhancements into mandatory deliverables that reshape fee structures.
- Sustainability:Energy benchmarking mandates from the EPA and state carbon reduction targets in California and New York now embed continuous monitoring systems and embodied carbon calculations into standard design contracts. Firms with thermal modeling and lifecycle assessment capabilities are capturing recurring analytics revenue alongside traditional architectural fees.
- Accessibility:ADA Title II compliance friction is extending construction administration scopes unpredictably, with pre-1990 building stock in Illinois and Pennsylvania facing the most severe upgrade exposure. Full plumbing replacement under proposed Lead and Copper Rule revisions is activating hazardous material protocols that compress summer renovation windows.
- Flexibility:Hybrid learning infrastructure demands simultaneous physical retrofit and digital integration, compressing traditional design-bid-build timelines.
- Safety Enhancements:Ballistic glazing and secure entry sequences are becoming standard in high-visibility districts.
Accessibility commands the largest absolute scope expansion; sustainability offers the steepest fee growth trajectory.
Construction Method:
Speed premiums and risk transfer preferences are redistributing procurement toward factory-based delivery systems that compress site schedules.
- Modular:Volumetric classroom units and repetitive bay configurations are gaining share fastest in elementary and vocational projects where enrollment surge demands immediate capacity. Texas and Florida districts are accepting design-build-modular packages that transfer enclosure risk to integrated delivery teams.
- Green Building:Mass timber systems using cross-laminated timber and glulam assemblies are reducing embodied carbon while enabling faster enclosure schedules for multi-story academic buildings in the Pacific Northwest and Northeast corridors.
- Traditional:Design-bid-build remains dominant for complex university science facilities requiring specialized MEP integration.
- Pre-engineered:Metal building systems serve vocational shop spaces and auxiliary structures where span requirements are standardized.
Traditional methods retain university dominance; modular is climbing the fastest in K-12 procurement.
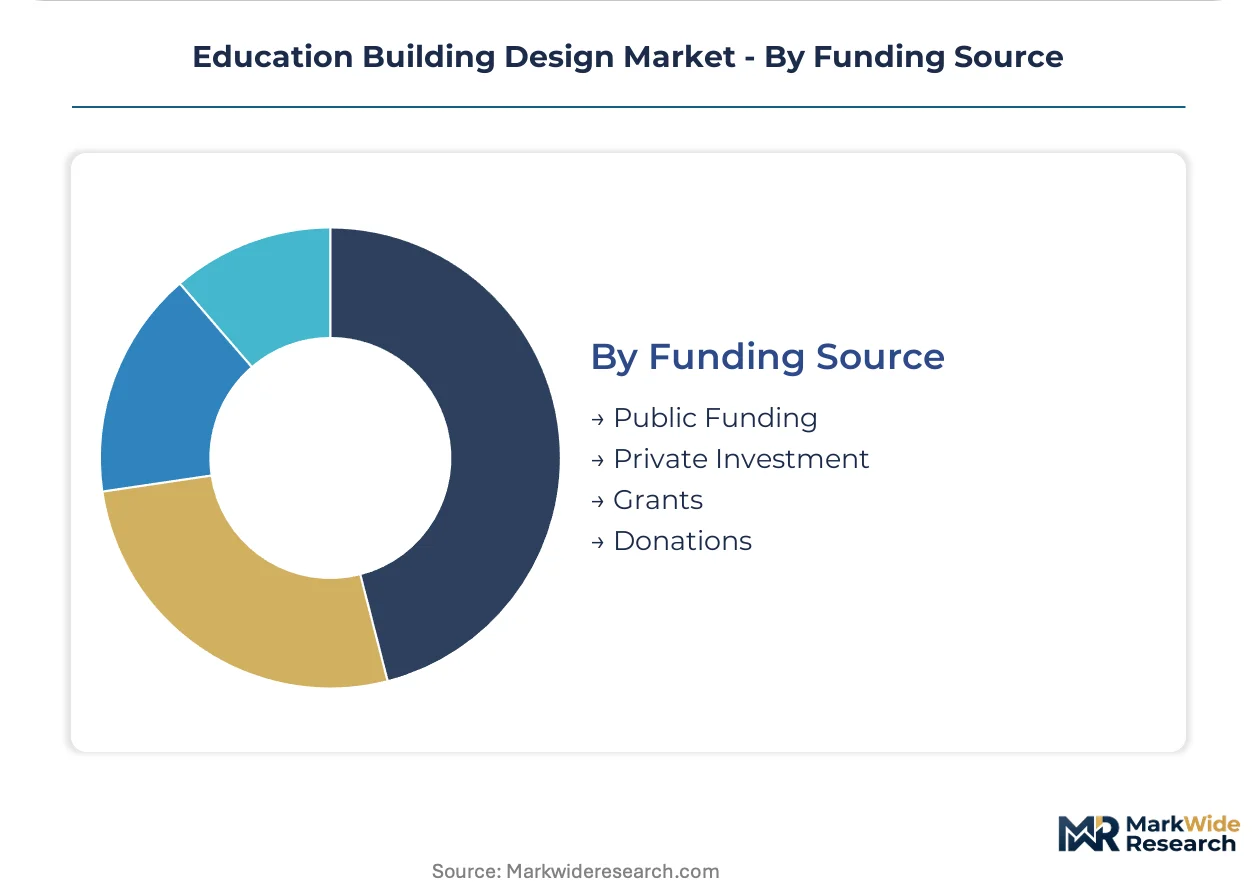
Funding Source:
Capital source determines client sophistication, timeline pressure, and the availability of long-term performance contracting structures.
- Public Funding:Bond referendums in Texas, Florida, and California are accelerating project pipelines, with Ohio and Virginia districts piloting design-build-finance-operate-maintain contracts that transfer energy risk to design teams. Master service agreements are replacing project-specific RFPs, privileging firms with multi-state licensure and surety capacity.
- Private Investment:Charter school networks and international branch campuses are expanding procurement flexibility, enabling outcome-based specifications and extended fee structures tied to occupancy performance. Private capital concentrates in Arizona, Colorado, and Georgia where regulatory frameworks permit alternative delivery methods.
- Grants:Federal and state facility modernization programs target specific building systems or demographic priorities.
- Donations:Named gift funding sustains signature architecture at selective private institutions.
Public Funding anchors project volume; Private Investment is expanding most quickly in alternative delivery penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dallas-Fort Worth and Houston corridors anchor North American education design activity, with enrollment surges and bond referendums compressing procurement timelines across multiple state jurisdictions.
United States
Texas enrollment growth and California carbon mandates drive project pipelines. The EPA's Energy Benchmarking Mandates expand design scope into continuous monitoring systems. Dallas-Fort Worth and Houston corridors concentrate K-12 bond activity, while Massachusetts science precincts sustain premium laboratory commissions.
Canada
Provincial carbon reduction targets and mass timber adoption reshape academic construction standards. Health Canada guidelines influence indoor air quality specifications for K-12 retrofits. British Columbia and Ontario districts lead CLT implementation for multi-story institutional buildings.
United Kingdom
Department for Education capital programs and net-zero public building targets accelerate retrofit pipelines. The UK Green Deal framework extends into embodied carbon calculations for school estates. Greater London and Manchester corridors concentrate academy trust consolidation projects.
Germany
Federal-state education infrastructure programs and energy efficiency ordinances drive facility modernization. KBA building codes intersect with EU Green Deal requirements for public sector decarbonization. Bavaria and North Rhine-Westphalia anchor vocational institute expansion tied to industrial partnership models.
Australia
State government school infrastructure programs and climate resilience standards expand design scope. The NCC energy efficiency provisions mandate thermal performance modeling for new academic buildings. New South Wales and Victoria concentrate university precinct developments with integrated sustainability consulting.
Education Building Design Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered procurement structures. Large integrated practices with multi-state licensure capture master service agreements, while boutique specialists dominate signature science precincts. Three archetypes prevail: analytics-platform firms bundling energy benchmarking into recurring revenue, integrated sustainability consultants anchoring long-term facility management contracts, and laboratory specialists commanding premium fees for hazardous material containment expertise. Competitive moves concentrate on geographic expansion through licensure acquisition and portfolio diversification into modular delivery methods.
Among North American integrated practices, CannonDesign, Stantec, and HOK occupy distinct positioning vectors. CannonDesign exemplifies the analytics-platform archetype through proprietary energy benchmarking tools that decouple fees from capital cycles. Stantec anchors the integrated sustainability tier with bundled consulting and facility management structures. HOK represents laboratory specialization dominance, particularly within university science and technology precincts where adaptive structural systems command extended engagement scopes.
| Leading Market Players |
|---|
| CannonDesign |
| Stantec |
| Gensler |
| HOK |
| HDR |
| Perkins&Will |
| DLR Group |
| Page |
| SmithGroup |
| Others |
Pricing and Supply Chain Analysis
Generative design algorithm adoption is compressing schematic-phase timelines from months to weeks while simultaneously shifting cost economics toward software licensing models and concentrating procurement leverage among firms with proprietary analytics platforms. This technology transition decouples design fees from capital expenditure cycles, enabling subscription-based revenue streams that reshape supplier-buyer power dynamics across public district and private institutional segments.
Pricing Analysis
Outcome-based pricing anchored to energy performance guarantees now commands premium positioning in Ohio and Virginia pilot programs where design-build-finance-operate-maintain contracts transfer long-term thermal risk to design teams. Three-tier pricing structure across premium, standard, and economy levels separates principal-led laboratory commissions from repeatable K-12 prototypes and modular vocational packages. Cost compression in elementary and vocational segments is intensifying because Texas and Florida districts prioritize speed-to-occupancy over customization depth. Public agency clients exhibit highest price sensitivity due to bond referendum accountability, while private charter networks and international branch campuses accept extended fee structures tied to occupancy performance.
Supply Chain Analysis
Cross-laminated timber supply rests on British Columbia and Pacific Northwest manufacturing clusters, with glulam assembly capacity concentrated in Austria and Germany for European project sourcing. Structural steel, MEP components, and specialty laboratory containment systems constitute critical input dependencies for complex university science facilities. Single-source vulnerability runs through California, Texas, and Massachusetts MEP contractors capable of hazardous material integration, creating geographic bottlenecks for national project execution. Distribution runs through design-build-modular integrators in fast-growing Sun Belt corridors, with master service agreements consolidating vendor rosters under five-year indefinite delivery contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Building performance modeling platforms are displacing traditional square-footage pricing models, creating a technology-transition phase where analytics capabilities determine competitive survival. Firms lacking proprietary energy benchmarking tools or thermal modeling expertise face margin erosion as EPA mandates and state carbon targets expand baseline scope.
For Market Incumbents: Deepen vertical integration into modular delivery methods and mass timber systems to capture enrollment surge demand in Texas and Florida corridors. Acquire multi-state licensure capacity to qualify for consolidated master service agreements replacing project-specific RFPs in Ohio and Florida education departments. Prioritize thermal modeling R&D investments to defend against analytics-platform competitors bundling continuous monitoring into recurring revenue streams. For New Entrants and Emerging Players: EPA Energy Benchmarking Mandates in the United States open a window for specialized analytics firms to capture recurring revenue from districts spreading compliance costs across operating budgets. Target vocational institute modernization in Texas and Ohio where Perkins Act capital channels into equipment-heavy career and technical education facilities. Pursue design-build-modular partnerships with regional contractors to bypass incumbent surety capacity requirements and establish project track records. For Investors and Strategic Acquirers: Exit pathways concentrate in analytics-platform acquisitions by integrated practices seeking to decouple fees from capital cycles. Long-term viability hinges on firms' ability to embed sustainability consulting and facility management into extended engagement structures. Watch EPA Lead and Copper Rule revision timelines as inflection indicators for hazardous material abatement service demand spikes in Illinois and Pennsylvania districts.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Analytics Platform Development | CannonDesign's energy benchmarking tools demonstrate how software subscriptions capture recurring revenue from EPA compliance mandates. |
| Integrated Sustainability Consulting Bundle | Stantec's long-term facility management contracts embed lifecycle assessment capabilities that extend client retention beyond traditional design phases. |
| Laboratory Specialization Investment | HOK's science precinct dominance commands premium fees through adaptive structural systems and hazardous material containment expertise. |
| Modular Delivery Method Expansion | Texas and Florida districts accepting design-build-modular packages transfer enclosure risk while accelerating speed-to-occupancy for enrollment surge capacity. |
| Multi-State Licensure Acquisition | Master service agreements in Ohio and Florida privilege firms with geographic coverage to capture consolidated procurement under five-year indefinite delivery contracts. |
Research Methodology
Document review covered EPA facility standards, state carbon reduction targets, and bond referendum databases, complemented by interviews with K-12 district facility directors, university capital planning officers, MEP contractors, modular construction integrators, and sustainability consulting leads. Secondary validation incorporated US Department of Education facility expenditure reports, AIA firm survey data, and construction industry trade publications. Bottom-up project pipeline analysis triangulated against top-down market sizing from public funding authorization records.
Historical enrollment trends and bond issuance patterns were cross-referenced against expert panel input from regional architecture and engineering executives to establish growth assumptions across the projection horizon. Segmentation modeling incorporated building type, design feature, construction method, and funding source dimensions with regional regulatory cluster variations. CAGRs were derived from enrollment projection alignment with capital expenditure authorization timelines, with thermal modeling adoption curves and modular penetration rates as industry-specific forecast inputs.
The model assumes a particular technology adoption path for generative design and building performance analytics; alternative pathways for computational design tool diffusion would alter the outlook for incumbent fee structures and new entrant positioning. Forecasts reflect assumptions regarding EPA mandate enforcement consistency, state carbon target durability, and bond market volatility for district capital programs. A small set of named triggers—Perkins Act reauthorization scope, Lead and Copper Rule finalization timeline, and mass timber code adoption pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
Door Hardware Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
Cement Grinding Aids Market
Building & Construction Materials
Global Floor and Wall Glazed Tiles Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market
Building & Construction Materials
Global Concrete Repair Mortars Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
Household Mosaic Tiles Market
Building & Construction Materials
PU Roof Window Market
Building & Construction Materials
Windows and Doors Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
North America Industrial Flooring Market