
 Ceiling Tiles Market | 2026-2036
Ceiling Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Ceiling Tiles Market Analysis
Healthcare procurement consolidation is decoupling from traditional commercial construction buying patterns, with hospital systems now negotiating direct supply agreements for infection-resistant ceiling assemblies. Armstrong World Industries leverages its captive mineral fiber supply chain to serve these integrated delivery networks. Knauf Gips KG anchors its position through gypsum-based acoustic systems engineered for operating theater specifications.
Ceiling tiles are rigid panel products manufactured from mineral fiber, gypsum, metal, or PVC, typically measuring 600mm by 600mm or 600mm by 1200mm, designed to suspend from or adhere directly to structural ceilings for acoustic control, fire resistance, and aesthetic finish. Mineral fiber tiles dominate specification in open-plan commercial environments where NRC ratings above 0.70 drive procurement decisions, while PVC tiles are gaining traction in moisture-critical zones such as laboratories and food processing areas due to their washability and mold resistance. The application split reveals commercial spaces as the mature volume base, with healthcare facilities representing the fastest-growing specification channel as hygiene protocols tighten.
The EPA regulates formaldehyde emissions from composite wood products under TSCA Title VI, directly constraining substrate choices for manufacturers serving the US market, while REACH and the EU Green Deal impose disclosure requirements on recycled content and embodied carbon for products entering European commercial projects. OSHA workplace noise standards sustain demand for high-NRC assemblies in industrial and educational settings. Stakeholders must monitor evolving MEE enforcement in China and emerging BIS standards in India as these jurisdictions expand their commercial building codes to include acoustic performance mandates.
Market Dynamics
Healthcare procurement consolidation is decoupling from traditional commercial construction buying patterns, with hospital systems now negotiating direct supply agreements for infection-resistant ceiling assemblies that bypass conventional distributor networks.
Growth Catalysts
- EU F-Gas Regulation:Tightening material compliance requirements for indoor air quality are accelerating specification of low-emission mineral fiber products in German hospital renovation programs.
- Acoustic performance mandates:OSHA workplace noise standards sustain demand for high-NRC assemblies in industrial and educational settings across the United States.
- Mineral fiber dominance:NRC ratings above 0.70 drive procurement decisions in open-plan commercial environments, cementing specification share for acoustic control solutions.
Market Restraints
- Formaldehyde emission constraints:EPA TSCA Title VI directly limits substrate choices for manufacturers serving the US market, compressing allowable material inputs.
- Raw material concentration:Captive mineral fiber supply chains concentrate upstream leverage with integrated producers, constraining independent manufacturers.
- PVC substitution ceiling:Washable PVC tiles face technical limitations in fire-rated assemblies, blocking penetration into full-spectrum commercial specifications.
Strategic Opportunities
- India BIS standards expansion:Emerging commercial building codes incorporating acoustic performance mandates create specification white space in metropolitan construction.
- Integrated delivery networks:Direct supply agreements with hospital systems bypass traditional distribution, capturing margin from consolidated healthcare procurement.
- REACH recycled content disclosure:EU Green Deal embodied carbon requirements reward manufacturers with verified circular material flows.
Industry Challenges
- Certification timeline compression:Multi-jurisdiction compliance with REACH, TSCA Title VI, and emerging MEE enforcement in China strains technical documentation capacity.
- Legacy system integration:Suspension grid interoperability with existing T-bar infrastructure complicates specification of next-generation ceiling assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceiling Tiles Market |
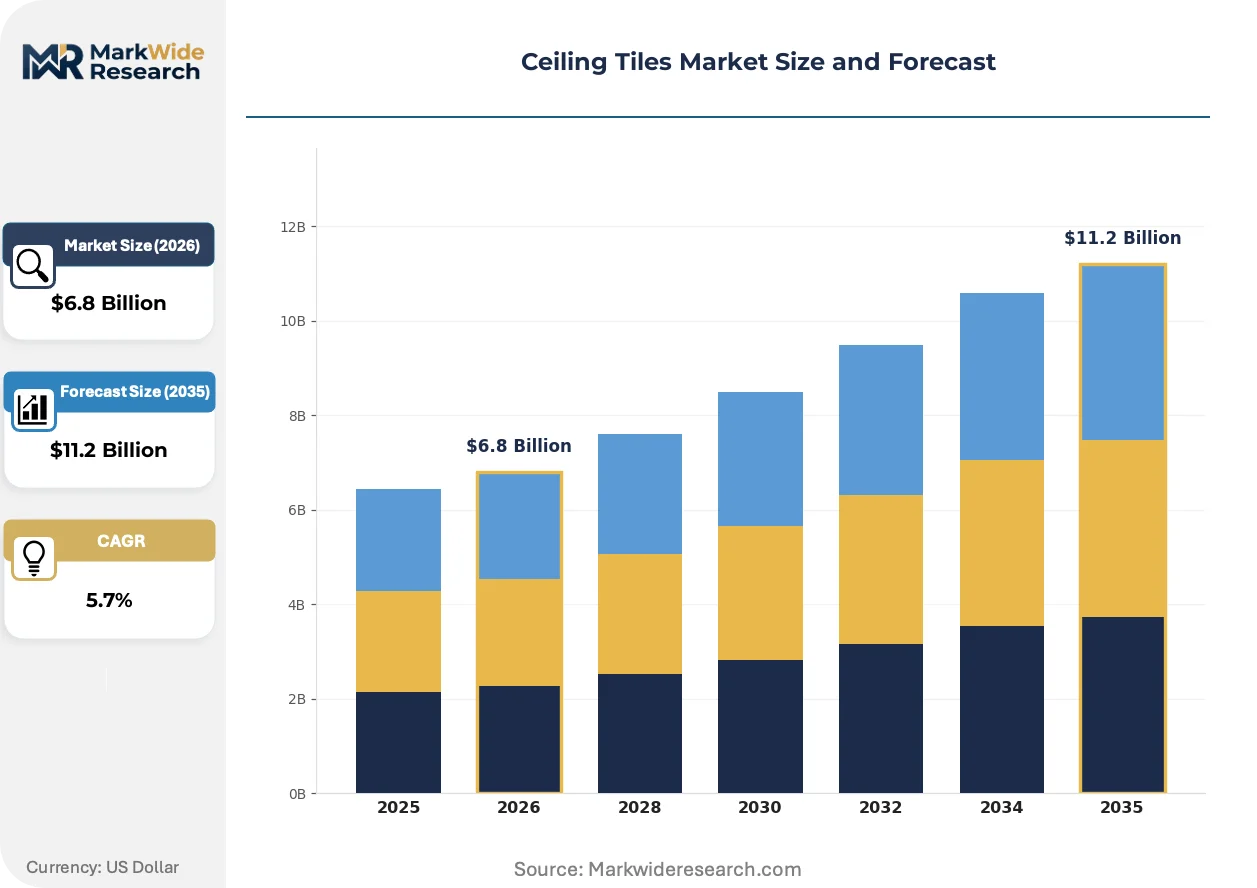
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
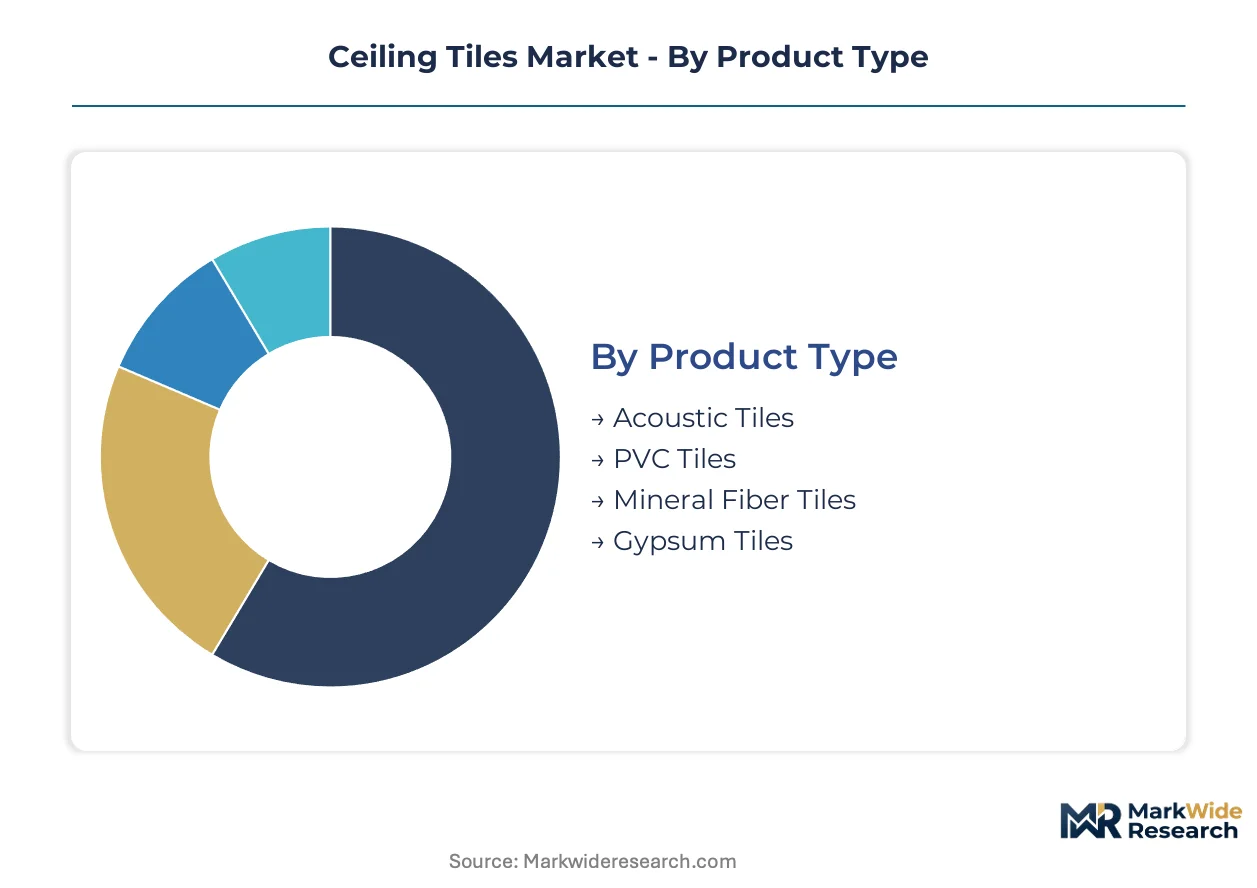
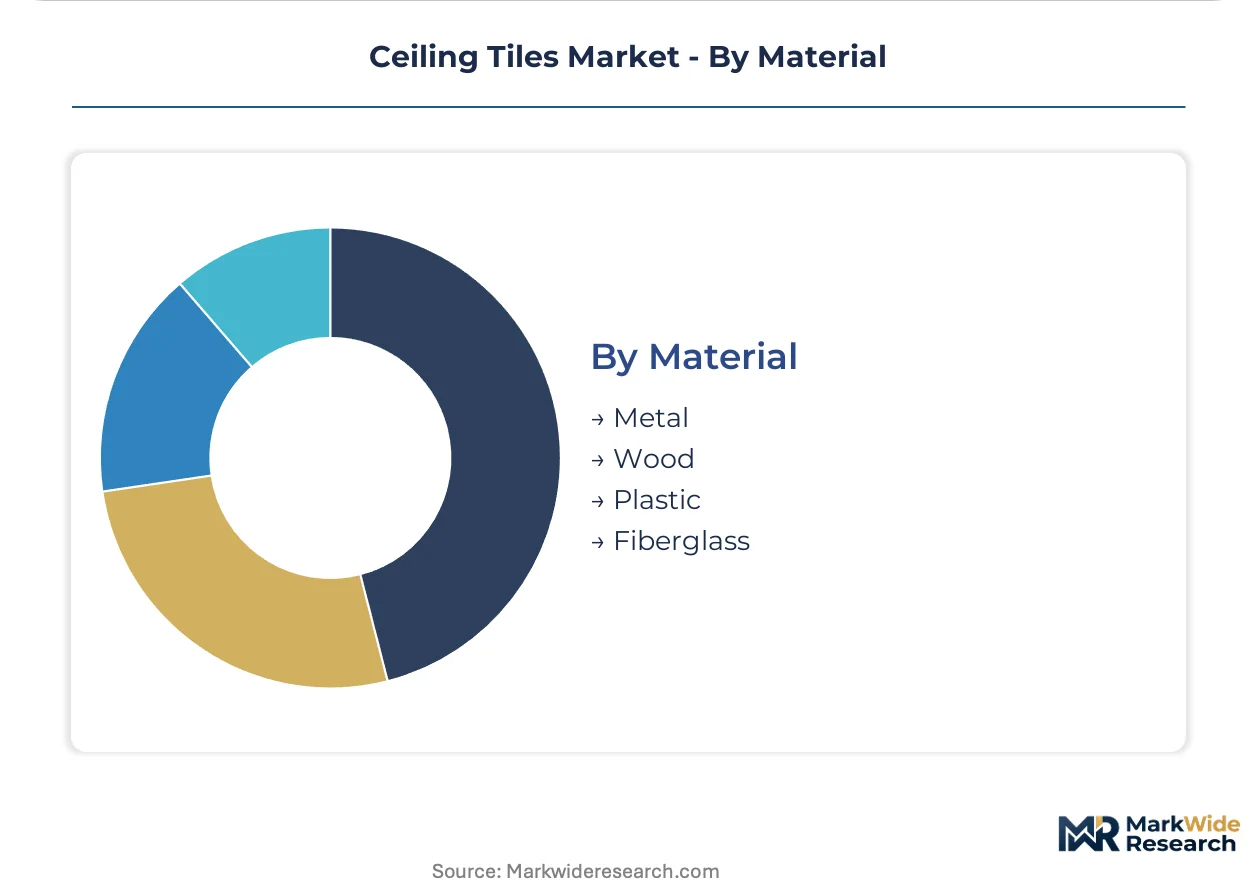
| Segmentation | Product Type: Acoustic Tiles, PVC Tiles, Mineral Fiber Tiles, Gypsum Tiles Application: Commercial Spaces, Residential Areas, Educational Institutions, Healthcare Facilities Installation Type: Suspended, Direct, Grid, Clip-in Material: Metal, Wood, Plastic, Fiberglass |
| Companies Covered | Armstrong World Industries, ROCKWOOL International A/S, Knauf Gips KG, Saint-Gobain Gyproc, USG Corporation, CertainTeed, Odenwald Faserplattenwerk GmbH, SAS International, Hunter Douglas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceiling Tiles Market Emerging Trajectories
Material science advances and regulatory disclosure requirements are rewriting specification criteria across commercial and healthcare verticals, compressing the gap between acoustic performance and hygiene compliance.
Biocidal surface treatments integrated into mineral fiber substrates are rewriting the competitive logic of healthcare specification. Hospital systems in Germany and the Netherlands are accelerating adoption of infection-resistant ceiling assemblies. The technology is rewriting procurement evaluation frameworks by collapsing acoustic, fire, and hygiene performance into single-product specifications.
REACH and the EU Green Deal impose granular disclosure requirements on recycled content and embodied carbon for products entering European commercial projects. Manufacturers must now document supply chain provenance to maintain specification eligibility. Healthcare facilities in France and Belgium face the steepest compliance burden due to concurrent national green building standards.
Buying committees at consolidated hospital networks are consolidating supplier rosters around full-system providers capable of warranting acoustic, fire, and hygiene performance in single contracts. Traditional distributor relationships are losing relevance as integrated delivery networks negotiate directly with manufacturers. This pattern is most visible in German hospital renovation programs and accelerating commercial real estate upgrades in Munich and Hamburg.
Ceiling Tiles Market Segmentation
Ceiling tile procurement varies sharply across end-use contexts, with acoustic ratings, fire certification, and hygiene compliance creating distinct specification pathways. Manufacturers must align product portfolios with the regulatory burden and performance tier demanded by each segment.
Product Type:
Certification requirements diverge sharply: mineral fiber demands REACH recycled content disclosure, PVC requires fire-rated assembly compatibility, while acoustic tiles face OSHA noise standard verification in US industrial applications.
- Mineral Fiber Tiles:Engineered from compressed mineral wool with NRC ratings above 0.70, these panels dominate open-plan commercial specifications in Germany where hospital renovation programs prioritize acoustic control alongside EU Green Deal compliance.
- Acoustic Tiles:Purpose-built for sound absorption with porous surface structures, these assemblies sustain procurement volume in US educational and industrial settings where OSHA workplace noise standards mandate high-performance ceiling systems.
- PVC Tiles:Washable, mold-resistant panels gaining traction in moisture-critical zones such as laboratories and food processing areas, though fire-rated assembly limitations constrain full-spectrum penetration.
- Gypsum Tiles:Dense, fire-resistant substrates engineered for operating theater specifications in European healthcare facilities facing concurrent national green building standards.
Leading the category by volume: mineral fiber tiles. Growing fastest: PVC tiles in hygiene-critical applications.
Application:
Cost tier stratification separates specification patterns, with healthcare facilities paying premium rates for infection-resistant assemblies while commercial spaces prioritize standard acoustic performance at scale.
- Commercial Spaces:The mature volume base for ceiling tile demand, with open-plan offices driving procurement of cost-optimized mineral fiber products where NRC ratings above 0.70 dictate selection criteria.
- Healthcare Facilities:The fastest-expanding specification channel as hospital systems negotiate direct supply agreements for biocidal surface-treated assemblies that collapse acoustic, fire, and hygiene performance into single-product contracts.
- Educational Institutions:US schools and universities sustain demand under OSHA workplace noise standards, with procurement concentrated in high-NRC assemblies for classrooms and lecture halls.
- Residential Areas:Lower-specification segment where aesthetic finish and basic acoustic dampening drive selection, with limited regulatory compliance burden compared to institutional end-uses.
Commercial spaces anchor procurement volume. Healthcare facilities are climbing the fastest as hygiene protocols tighten across German and Dutch hospital systems.
Installation Type:
Application context determines installation method selection, with renovation projects favoring retrofit-compatible systems while new construction permits integrated ceiling architecture.
- Suspended:T-bar grid systems dominating commercial and healthcare specifications, though legacy system interoperability complicates adoption of next-generation ceiling assemblies in renovation programs.
- Direct:Adhesive-mounted panels suited to low-ceiling residential and retrofit applications where grid depth constraints prohibit suspended configurations.
- Grid:Standardized 600mm by 600mm or 600mm by 1200mm module systems forming the infrastructure backbone for mineral fiber and acoustic tile deployment.
- Clip-in:Metal ceiling systems employing concealed suspension for premium aesthetic specifications in corporate and transportation hub applications.
Suspended installation commands the greatest volume. Clip-in systems are expanding most quickly in premium commercial segments.
Material:
Supply concentration varies by raw material, with captive mineral fiber supply chains concentrating upstream leverage among integrated producers while metal and plastic feedstocks face broader sourcing.
- Fiberglass:High-performance acoustic substrates with tunable density for NRC optimization, specified where fire resistance and sound control must coexist in healthcare and educational assemblies.
- Metal:Aluminum and steel panels deployed in clip-in and lay-in configurations for durable, washable ceiling systems in transportation and retail environments.
- Plastic:PVC and thermoplastic formulations serving moisture-critical zones, with washability and mold resistance offsetting fire-rated assembly limitations.
- Wood:Aesthetic-focused panels for premium residential and hospitality specifications, constrained by EPA TSCA Title VI formaldehyde emission limits in US market access.
Fiberglass leads material volume through mineral fiber dominance. Metal is gaining share fastest in transportation and retail upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital renovation programs in Germany concentrate specification demand for acoustic and infection-resistant ceiling systems, while regulatory tightening across multiple jurisdictions redirects procurement toward low-emission mineral fiber products.
Germany
Hospital renovation programs and commercial real estate upgrades in Munich and Hamburg accelerate specification rates for mineral fiber and gypsum-based acoustic products. The EU F-Gas Regulation and EU Green Deal impose strict embodied carbon disclosure requirements on ceiling assemblies entering federal healthcare projects. Bavaria and North Rhine-Westphalia host the densest concentration of specification activity, with integrated delivery networks negotiating direct supply agreements for operating theater-grade systems.
United States
OSHA workplace noise standards sustain procurement volume for high-NRC ceiling assemblies across educational and industrial verticals. EPA TSCA Title VI constrains formaldehyde emissions from composite wood substrates, compressing allowable material inputs for domestic manufacturers. The Southeast and Midwest construction corridors drive specification volume, with hospital systems in Texas and Illinois consolidating supplier rosters around full-system providers.
China
Expanding commercial building codes incorporating acoustic performance mandates create specification white space in metropolitan construction. MEE enforcement tightens indoor air quality standards for public buildings, accelerating demand for low-emission mineral fiber products. The Yangtze River Delta and Pearl River Delta clusters concentrate manufacturing and specification activity, with Shanghai and Shenzhen leading hospital and commercial upgrade cycles.
India
Emerging BIS standards for commercial building acoustic performance open specification opportunities in metropolitan construction markets. The PLI scheme for construction materials supports domestic manufacturing scale-up for ceiling system components. Maharashtra and Karnataka lead procurement volume, with Mumbai and Bangalore hospital networks piloting infection-resistant ceiling specifications ahead of national code adoption.
Netherlands
Hospital systems accelerate adoption of biocidal surface-treated ceiling assemblies that collapse acoustic, fire, and hygiene performance into single-product contracts. REACH recycled content disclosure requirements reward manufacturers with verified circular material flows. The Randstad corridor concentrates specification activity, with Amsterdam and Rotterdam healthcare facilities facing concurrent national green building standards that exceed baseline EU requirements.
Ceiling Tiles Market Vendor Landscape
German producers anchor one tier through gypsum-based acoustic systems engineered for healthcare specifications; US specialists hold another through captive mineral fiber supply chains serving integrated delivery networks. The vendor base organizes around three strategic archetypes: integrated mineral fiber producers with backward control over raw material inputs, gypsum specialists targeting operating theater fire ratings, and metal systems fabricators capturing premium transportation and retail segments. Dominant competitive moves include portfolio diversification into infection-resistant surface treatments and geographic expansion through direct supply agreements with consolidated hospital networks.
Within the integrated producer tier, Armstrong World Industries and Knauf Gips KG exemplify archetypes built on material-specific supply chain control. Armstrong occupies a position representing captive mineral fiber sourcing for healthcare procurement consolidation. Knauf sits within the gypsum-specialist vector, anchoring fire-resistant system specifications for European healthcare facilities. ROCKWOOL International A/S represents the mineral wool substrate tier, with its Denmark-based structure aligning with Nordic sustainability disclosure requirements. These three companies illustrate how upstream material control and regulatory compliance documentation determine specification eligibility across tightening procurement frameworks.
| Leading Market Players |
|---|
| Armstrong World Industries |
| ROCKWOOL International A/S |
| Knauf Gips KG |
| Saint-Gobain Gyproc |
| USG Corporation |
| CertainTeed |
| Odenwald Faserplattenwerk GmbH |
| SAS International |
| Hunter Douglas |
| Others |
Supply Flow & Price Mechanics
Mineral wool fiber price indices cascade through captive supply chains into three distinct procurement tiers, with integrated producers commanding premium positioning in German hospital renovation programs while independent manufacturers absorb cost compression in standard commercial specifications.
Pricing Analysis
Volume concentrates in standard-grade mineral fiber tiles where NRC ratings above 0.70 drive commoditized procurement, while margins pool in infection-resistant assemblies with biocidal surface treatments for European healthcare facilities. Price differentiation rests on certification tier—REACH recycled content disclosure and EU Green Deal embodied carbon verification separate premium specifications from economy-grade commercial products. Pricing pressure stems from EPA TSCA Title VI formaldehyde emission constraints compressing allowable substrate choices for US market access. Healthcare procurement committees show lowest price sensitivity as consolidated hospital systems prioritize single-contract warranty coverage over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Denmark-based mineral wool substrate producers serving integrated manufacturers like ROCKWOOL International A/S, constraining independent competitors without backward integration into raw fiber production. Upstream concentration centers on Germany, China, and the United States for mineral fiber processing, with gypsum mining and processing anchored in Spain and Thailand for Knauf Gips KG's European supply base. Supply chain risk manifests in REACH regulatory restriction exposure for recycled content verification documentation. Distribution runs through specification-influencer channels—architects and acoustic consultants in commercial construction, biomedical engineers and infection control officers in healthcare procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ceiling tiles market sits in a material-science transition phase, with biocidal surface treatments displacing legacy acoustic-only specifications as hospital procurement committees consolidate supplier rosters around full-system providers.
For Market Incumbents: Hedge against PVC substitution ceilings in fire-rated assemblies by deepening captive mineral fiber supply and accelerating infection-resistant surface treatment R&D. Threat concentration sits with emerging BIS standards in India opening specification white space to regional challengers. Certification investment in REACH recycled content disclosure and EU Green Deal embodied carbon verification represents the critical defensive lever. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms offer the most penetrable route into consolidated healthcare procurement networks, bypassing traditional distributor relationships that Armstrong World Industries and Knauf Gips KG dominate. White space concentrates in Indian metropolitan construction ahead of BIS acoustic performance mandate adoption, and in moisture-critical laboratory specifications where washable PVC tiles face fire-rated assembly limitations. Go-to-market positioning should anchor on operating theater-grade gypsum systems for European healthcare facilities facing concurrent national green building standards. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale mineral fiber producers with partial backward integration in Germany and the Netherlands, where hospital renovation program acceleration outpaces working capital availability. Long-term viability across the analysis window hinges on specification-influencer channel control and verified circular material flow documentation. The signal to watch is MEE enforcement tightening in China—accelerated indoor air quality standards would compress margins for non-integrated competitors and trigger consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Biocidal Surface Treatment Integration | Collapses acoustic, fire, and hygiene performance into single-product specifications for German hospital systems. |
| Captive Mineral Fiber Supply Expansion | Secures upstream leverage against REACH recycled content disclosure requirements for EU Green Deal compliance. |
| Direct Hospital Supply Agreements | Bypasses traditional distributor networks as integrated delivery networks consolidate procurement. |
| India BIS Standards Pre-Positioning | Captures specification white space in Mumbai and Bangalore ahead of national acoustic mandate adoption. |
| Embodied Carbon Verification Investment | Maintains eligibility for French and Belgian healthcare facilities facing green building standards beyond baseline EU requirements. |
Methodological Framework
Document review covered trade association filings, customs records for mineral fiber and gypsum imports, and EPA TSCA Title VI compliance databases, complemented by interviews with hospital procurement managers, acoustic specification consultants, and mineral fiber plant operations directors. Secondary validation drew from EU ECHA REACH disclosure registries, BIS draft standard notifications, and MEE indoor air quality enforcement bulletins. Bottom-up volume estimates triangulated against top-down construction spending allocation models across commercial, healthcare, and educational verticals.
Cross-referencing historical specification patterns with panel input from architects and infection control officers anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application context, installation method, and material substrate, with regulatory compliance tier treated as an orthogonal specification filter. CAGRs derived from construction spend elasticity coefficients applied to ceiling system replacement cycles, incorporating OSHA noise standard enforcement intensity and EU F-Gas Regulation phase-down schedules as demand shifters.
The model holds under steady regulatory enforcement trajectories; deviation in MEE tightening velocity or BIS standards acceleration would shift volume allocation between mineral fiber and PVC tile specifications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Steep Slope Roofing Materials Market
Building & Construction Materials
PU Waterstops Market
Building & Construction Materials
Door Canopy Market
Building & Construction Materials
Concrete Repair Product Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
Garage Doors Market
Building & Construction Materials
US Commercial Windows Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
US Parking Deck Coatings Market
Building & Construction Materials
SBS Waterproofing Membrane Market
Building & Construction Materials
Global Iron and Steel Casting Market
Building & Construction Materials
Drinking Water Pipe Repair Market
Building & Construction Materials
France Ceramic Tiles Market
Building & Construction Materials
Runway Pavement Grade Asphalt Market
Building & Construction Materials
India UPVC Doors and Windows Market