
 Door Canopy Market | 2026-2036
Door Canopy Market Size, Share, and Industry Trends Forecast 2026-2036
Door Canopy Market Analytics
Maintenance subscription programs for canopy weatherproofing and seasonal inspection is pivoting vendor revenue models from one-time hardware sales toward recurring service contracts. Eide Industries, Inc. leverages its West Coast fabrication footprint to anchor large commercial installations across California and Arizona. Lawrence Fabric & Metal Structures Inc. specializes in custom architectural metalwork that commands premium positioning in municipal and institutional bids. Shade Structures, Inc. competes aggressively on lead-time compression for standardized residential wall-mounted units.
A door canopy is a protective overhead covering, typically fabricated from acrylic, polycarbonate, metal, or fabric membranes, engineered to deflect precipitation and reduce solar heat gain at building entrances through cantilevered or bracket-supported geometries. Its primary commercial purpose is to extend facade durability while improving occupant comfort during entry and egress transitions. Polycarbonate segments lead on impact resistance and light transmission specifications, though metal canopies capture the majority of margin pools in premium commercial applications. Wall-mounted installation dominates volume due to lower foundation requirements, while retractable systems represent the fastest-growing configuration as hospitality operators seek flexible outdoor dining coverage.
US municipalities enforce ICC building codes and FHA accessibility standards that dictate minimum headroom clearances and snow-load ratings for entrance structures, directly shaping product engineering specifications and installation protocols. The EU Green Deal and national building renovation passports in France and Italy are tightening thermal performance criteria at building envelopes, creating compliance-driven replacement cycles for outdated entry coverings. Stakeholders must monitor evolving wind-load certification requirements and local historic preservation overlay districts that restrict modern design styles in heritage corridors.
Market Dynamics
The door canopy market pivots on regulatory tightening of building envelope thermal performance, forcing wholesale replacement cycles across European residential stock and accelerating specification of insulated composite assemblies over legacy single-skin metalwork.
Growth Catalysts
- EU Green Deal renovation passports:France and Italy now mandate documented thermal upgrades at entry points, triggering compliance-driven canopy replacements in single-family housing.
- Polycarbonate impact resistance:Material specifications for hail-prone suburban North America favor UV-stabilized polycarbonate over acrylic, pulling volume toward certified impact-rated systems.
- Suburban residential retrofit:Weather-resistant entrance protection concentrates demand in Germany, where renovation rates for detached housing sustain replacement velocity.
Market Restraints
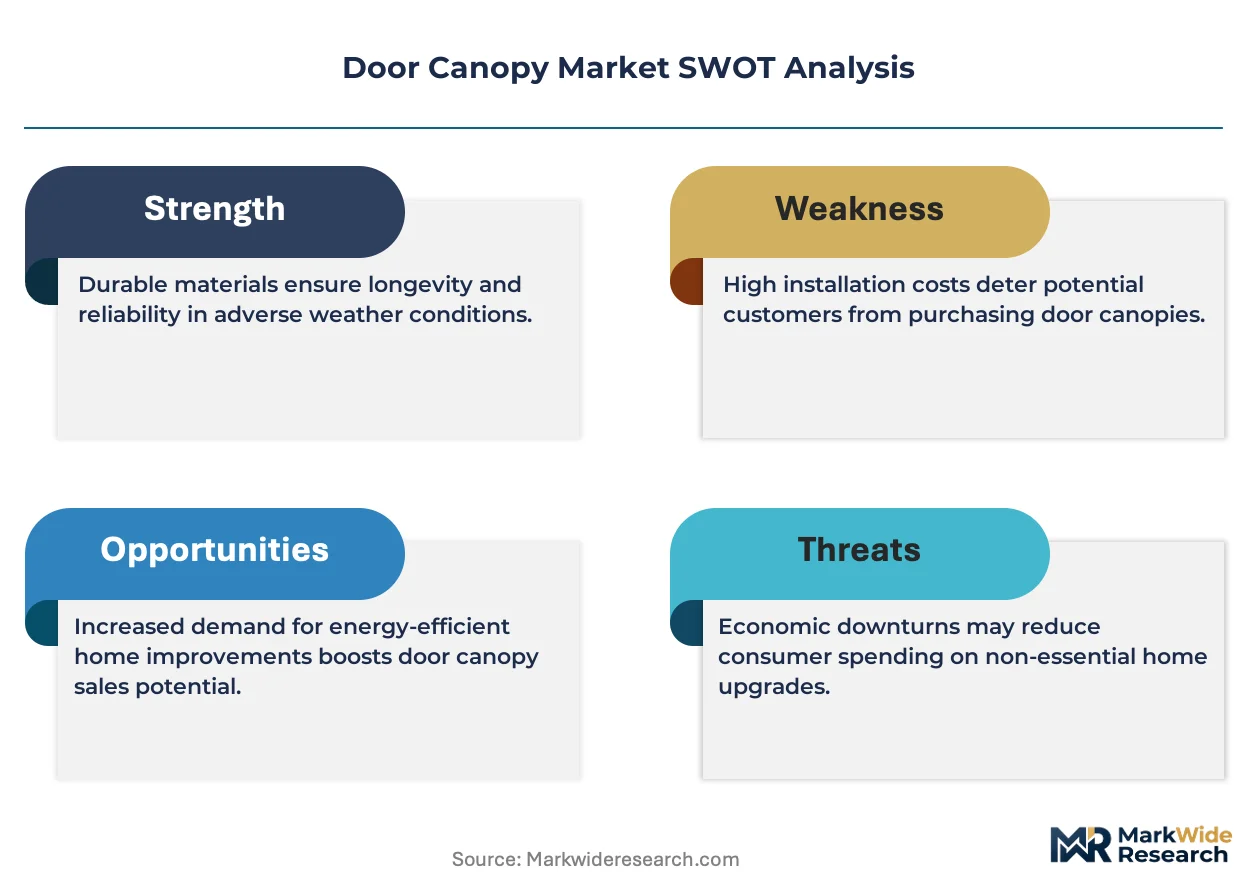
- Aluminum price volatility:Extrusion feedstock cost swings compress margin pools for metal canopy fabricators serving commercial bids.
- Foundation engineering for freestanding systems:Soil-bearing calculations and pier requirements inflate installed costs versus wall-mounted alternatives, limiting adoption in retrofit contexts.
- Historic preservation overlay districts:Local design review boards in heritage corridors restrict modern geometries, fragmenting addressable demand.
Strategic Opportunities
- Retractable canopy systems:Hospitality operators in California and Arizona seek flexible outdoor dining coverage, opening premium volume for motorized membrane assemblies.
- Maintenance subscription programs:Seasonal inspection and weatherproofing services pivot vendor economics from hardware sales toward recurring revenue streams.
- Integrated solar PV membranes:Building-integrated photovoltaics convergence with canopy substrates creates net-zero entry solutions for municipal and institutional clients.
Industry Challenges
- Wind-load certification timelines:ASTM E1592 and ASCE 7 testing protocols delay product launches by 4-6 months, compressing competitive windows.
- Fabrication workforce scarcity:Qualified aluminum welders and membrane seaming technicians concentrate on the West Coast, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Door Canopy Market |
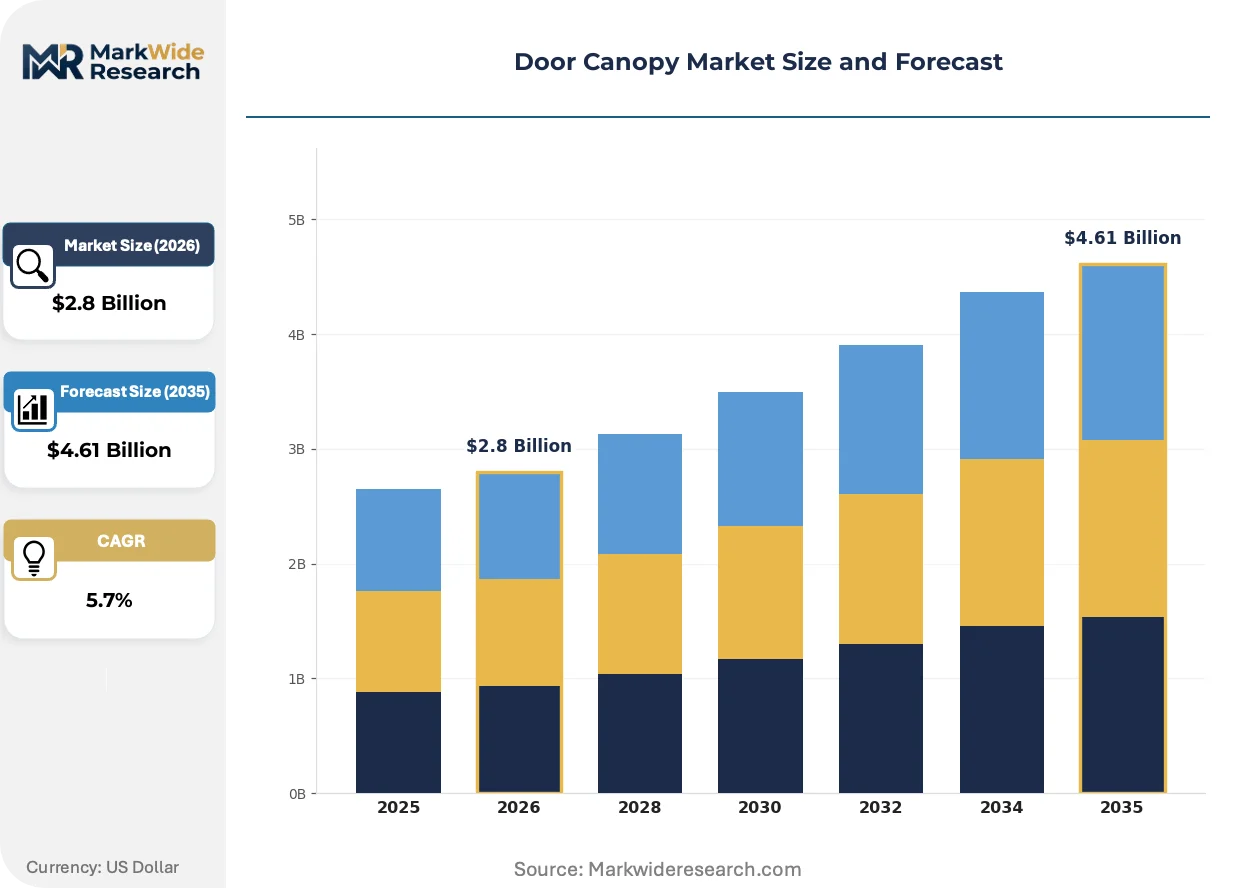
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polycarbonate, Metal, Fabric Installation Type: Freestanding, Wall-mounted, Retractable, Fixed End User: Residential, Commercial, Industrial, Government Design Style: Modern, Traditional, Rustic, Contemporary |
| Companies Covered | Eide Industries, Inc., Shade Structures, Inc., Lawrence Fabric & Metal Structures Inc., KD Kanopy, Inc., Advanced Design Awnings & Signs, Sunair Awnings, Canopies UK Ltd., Impact Canopies USA, Vitabri, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Door Canopy Market Evolving Landscape
Fabrication automation and digital specification tools are compressing design-to-installation cycles while elevating thermal performance thresholds. Three developments dominate competitive positioning.
Modular aluminum frame systems with clip-together connections are modularizing field assembly, reducing skilled labor hours by half. Regional fabricators in Germany and the Netherlands adopt these platforms to serve scattered single-family retrofits without maintaining large installation crews. The technology is modularizing supply chain geography, enabling distributed micro-factories closer to end demand.
EU Green Deal national implementation acts are tightening U-value requirements at building envelopes. The industrial consequence is specification of insulated composite panels with thermal breaks replacing conductive single-skin metal canopies. Germany's building renovation passport scheme most affects this transition, with inspectors now flagging non-compliant entry coverings for mandatory upgrade.
Digital specification portals allowing architects to configure, price, and order canopies without distributor intermediation are compressing procurement cycles. Municipal and institutional buyers in France and Italy increasingly route purchases through these direct channels, displacing traditional wholesale relationships. This pattern concentrates in public sector bids where transparency requirements favor documented digital trails.
Door Canopy Market Segmentation
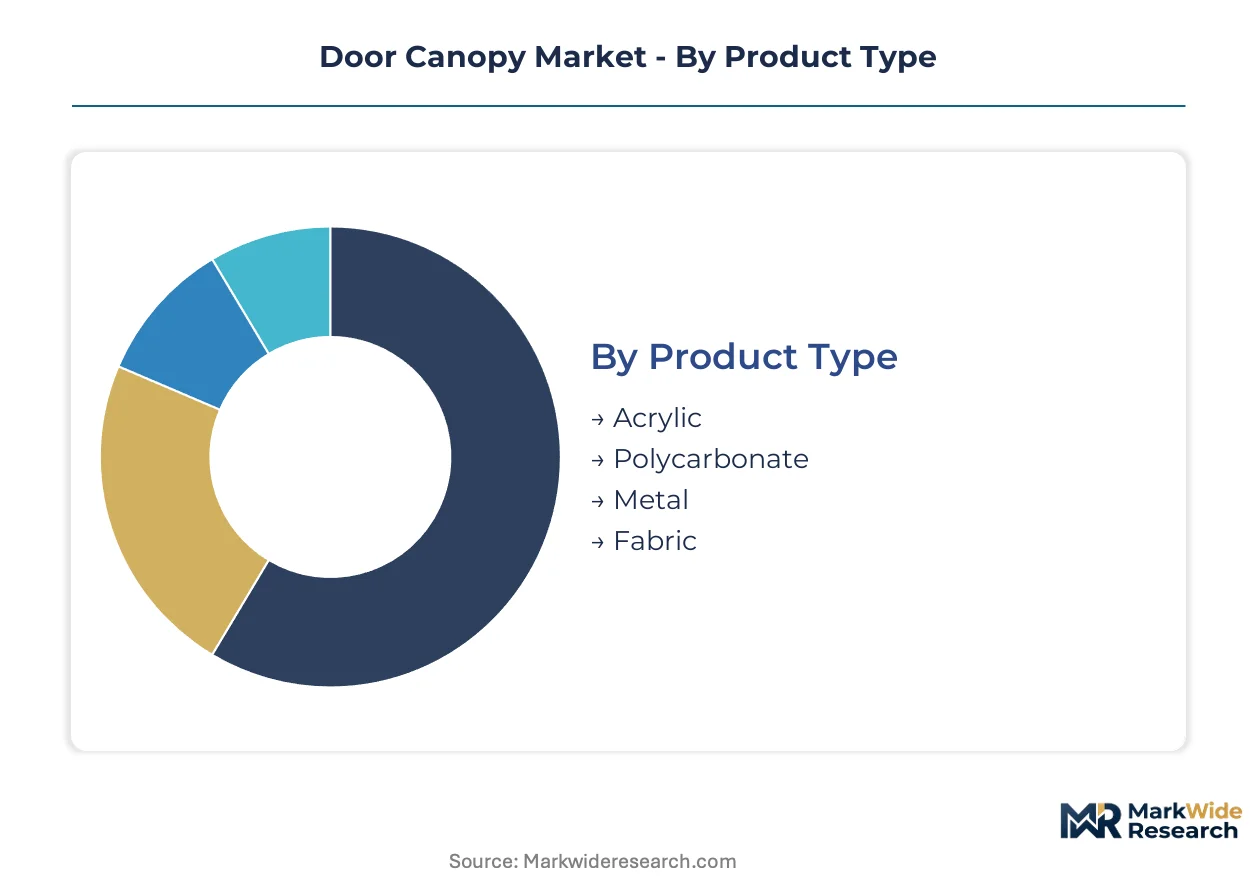
Product differentiation in door canopies shapes procurement patterns across retrofit and new construction channels. Specification decisions cascade from material thermal performance, installation geometry constraints, and facade compliance requirements.
Product Type:
Material selection drives upgrade cycles as building codes tighten thermal envelope standards and impact resistance mandates.
- Polycarbonate:UV-stabilized polymer sheets deliver certified hail impact ratings alongside high light transmission. German single-family renovation passports favor polycarbonate assemblies for documented thermal upgrades at entry points.
- Metal:Aluminum and steel extrusions with thermal break insulation capture premium commercial margins. France and Italy now flag conductive single-skin metalwork as non-compliant under EU Green Deal implementation, forcing replacement toward insulated composite alternatives.
- Acrylic:Cast polymer offers cost-effective clarity for residential retrofits where impact certification is not mandated.
- Fabric:Tensioned membrane substrates enable retractable configurations for hospitality outdoor dining coverage in California and Arizona.
Volume placements concentrate in Metal; the faster expansion belongs to Polycarbonate.
Installation Type:
Foundation engineering requirements segment installed cost structures and retrofit feasibility across building stock vintages.
- Wall-mounted:Cantilevered bracket systems eliminate pier foundations, cutting labor hours and soil-bearing calculations. This geometry dominates suburban North American residential retrofits where existing slab conditions constrain excavation.
- Retractable:Motorized membrane assemblies on aluminum track systems command premium pricing for flexible coverage. Hospitality operators in California and Arizona specify these for seasonal outdoor dining expansion.
- Freestanding:Pier-supported structures require geotechnical assessment, limiting adoption to new construction and commercial campuses with engineered foundations.
- Fixed:Permanent rigid-frame canopies anchor institutional bids where durability warranties extend to twenty years.
Wall-mounted systems anchor current volume; Retractable configurations are climbing the fastest.
End User:
Customer procurement authority separates specification complexity, compliance documentation, and maintenance contract attach rates.
- Residential:Single-family detached housing in Germany sustains replacement velocity through renovation passport compliance triggers.
- Commercial:Retail and hospitality chains in California and Arizona prioritize lead-time compression and seasonal weatherproofing subscriptions.
- Industrial:Manufacturing facility entrances specify heavy-duty metal assemblies with integrated snow-load ratings.
- Government:Municipal and institutional buyers in France and Italy route purchases through digital specification portals for transparency documentation.
Residential channels dominate placement volume; Commercial end-use is gaining share fastest.
Design Style:
Aesthetic compliance with local historic preservation overlays fragments addressable demand in heritage corridors.
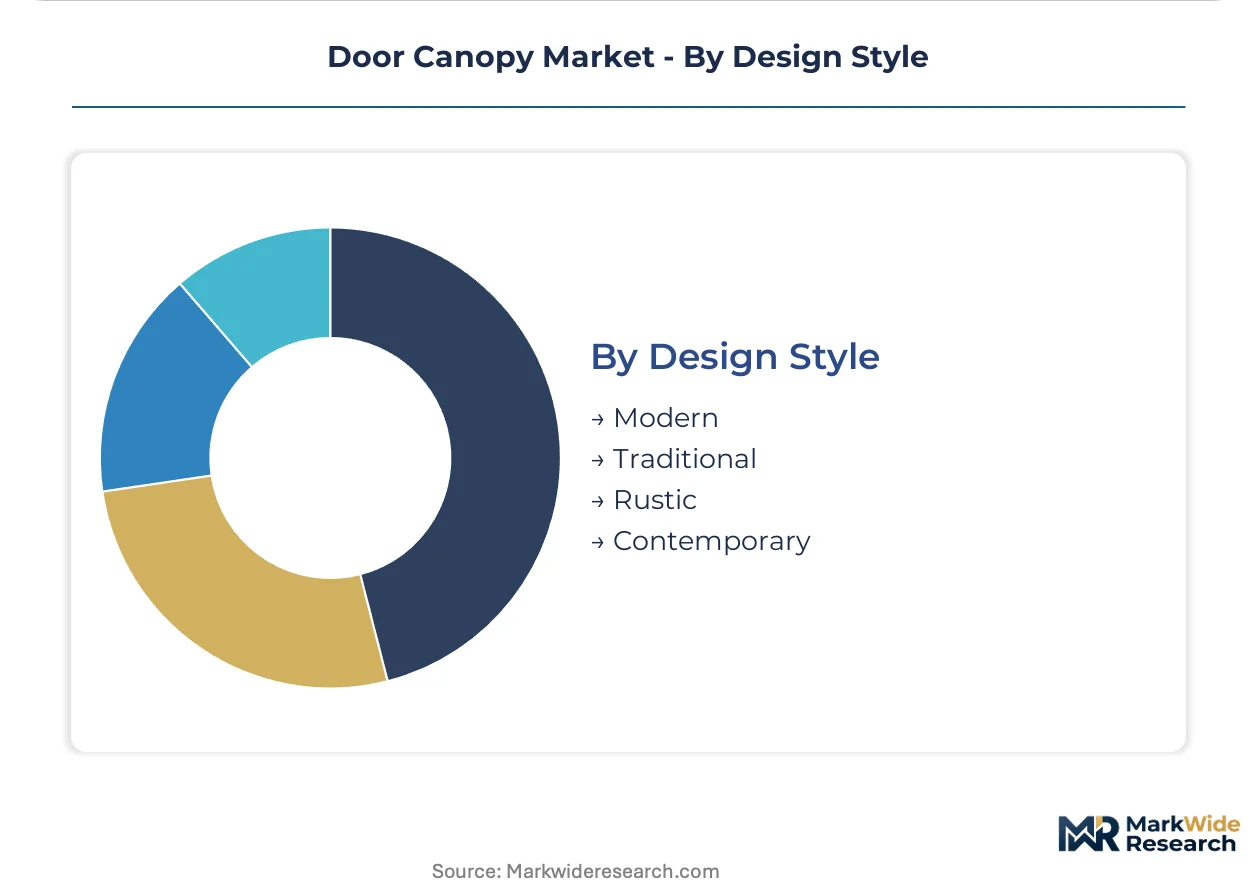
- Modern:Clean-line geometries with minimal bracket visibility face design review restrictions in European heritage districts.
- Traditional:Pitched-roof profiles with decorative corbels satisfy preservation board requirements in Italian and French historic centers.
- Contemporary:Curved-plane polycarbonate assemblies target suburban North American retrofits without overlay restrictions.
- Rustic:Timber-accented metal frames serve mountain resort hospitality in Arizona and California.
Traditional styling commands placement volume in regulated heritage markets; Contemporary designs are expanding most quickly in unrestricted suburban construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabrication capacity clusters in Germany and the United States while consumption concentrates in suburban retrofit corridors across France, Italy, and North American Sun Belt metros. This geographic split shapes trade flows and installation service deployment.
United States
Suburban residential retrofits in California and Arizona drive wall-mounted polycarbonate specifications for hail resistance. ICC building codes and FHA accessibility standards mandate minimum headroom clearances and snow-load ratings. Phoenix and Los Angeles fabrication hubs serve commercial hospitality bids for retractable membrane systems.
Germany
Single-family detached housing renovation passports trigger compliance-driven canopy replacements at entry points. EU Green Deal national implementation acts tighten U-value requirements for thermal envelope components. Bavaria and Baden-Württemberg host aluminum extrusion and modular frame assembly operations for distributed micro-factory networks.
France
Historic preservation overlay districts in Paris and Lyon constrain modern geometries, fragmenting addressable demand toward traditional pitched-roof profiles. National building renovation passports flag non-compliant entry coverings for mandatory thermal upgrades. Île-de-France municipal buyers route procurement through digital specification portals for transparency documentation.
Italy
Heritage corridor restrictions in Rome and Florence preserve demand for decorative corbel-supported traditional styling. EU Green Deal thermal performance criteria accelerate insulated composite panel adoption over conductive single-skin metalwork. Northern Italian fabricators in Lombardy and Veneto supply clip-together modular systems for scattered single-family retrofits.
United Kingdom
Conservation area designations in London and Edinburgh limit contemporary canopy geometries in heritage districts. Building regulations Part L energy efficiency standards influence thermal break specifications for entrance structures. Midlands-based metalwork specialists serve institutional bids requiring twenty-year durability warranties.
Door Canopy Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the door canopy market. Metal extrusion and membrane fabrication require significant fixed-asset investment, while specification-only architects and digital portal operators capture margin without production infrastructure. Three archetypes dominate: West Coast commercial fabricators with integrated installation crews, European modular system specialists serving scattered residential retrofits, and hospitality-focused retractable membrane designers. Capacity expansion and maintenance subscription program launches constitute the primary competitive vectors as vendors pivot from hardware sales toward recurring revenue.
Among United States-based fabricators, Eide Industries, Inc. anchors large commercial installations through West Coast production footprint, while Lawrence Fabric & Metal Structures Inc. occupies premium positioning in municipal and institutional bid channels. Shade Structures, Inc. exemplifies the lead-time compression specialist competing aggressively on standardized residential wall-mounted unit velocity. These three represent distinct strategic postures without overlapping core market focus.
| Leading Market Players |
|---|
| Eide Industries, Inc. |
| Shade Structures, Inc. |
| Lawrence Fabric & Metal Structures Inc. |
| KD Kanopy, Inc. |
| Advanced Design Awnings & Signs |
| Sunair Awnings |
| Canopies UK Ltd. |
| Impact Canopies USA |
| Vitabri |
| Others |
Value Network & Pricing Analysis
Aluminum LME spot pricing volatility cascades through extrusion feedstock contracts into three-tier pricing structure across premium, standard, and economy levels, with German fabricators passing alloy surcharges to municipal buyers while Arizona hospitality operators absorb membrane cost spikes through seasonal subscription bundling.
Pricing Analysis
Margin tightening in standard-grade metal canopies reflects aluminum extrusion feedstock swings and EU Green Deal thermal compliance retrofit mandates. Pricing stratifies across premium, standard, and economy tiers based on certification grade (ASTM E1592 wind-load) and after-sales service bundling. Cost-down pressure on economy residential units accelerates because polycarbonate sheet imports from Asia compress domestic fabricator margins. Single-family renovators in Germany exhibit highest price sensitivity; institutional buyers in France least.
Supply Chain Analysis
Regional distribution centers in Bavaria and Phoenix anchor hub-and-spoke patterns serving scattered residential retrofit crews without large inventory holdings. Manufacturing concentrates in Germany, the United States, and Italy. Raw material flows draw from aluminum extrusion feedstock, UV-stabilized polycarbonate resin, and tensioned membrane substrates. Single-source vulnerability sits with qualified aluminum welders and membrane seaming technicians clustering on the West Coast. Distribution runs through digital specification portals displacing traditional wholesale relationships in municipal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The door canopy market occupies a technology-transition phase where insulated composite panel assemblies displace conductive single-skin metalwork under EU Green Deal thermal envelope mandates.
For Market Incumbents: To counter aluminum price volatility and fabrication workforce scarcity, secure captive supply of extrusion feedstock through backward integration into regional aluminum rolling capacity, and anchor retention through maintenance subscription programs that pivot revenue from transactional hardware to recurring weatherproofing services.
For New Entrants and Emerging Players: Launch via direct-to-architect digital specification portals targeting underpenetrated municipal and institutional bid channels in France and Italy, where transparency requirements favor documented procurement trails and incumbent wholesale relationships fragment.
For Investors and Strategic Acquirers: Distressed-cycle entries favor modular frame system specialists with distributed micro-factory networks in Germany and the Netherlands, positioned to serve scattered single-family renovation passport compliance without large installation crew overhead. Monitor EU Green Deal national implementation act enforcement velocity as inflection indicator for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Maintenance Subscription Launch | Recurring revenue streams from seasonal weatherproofing services reduce customer acquisition cost dependence in residential retrofits. |
| Modular Frame System Expansion | Clip-together aluminum platforms halve skilled labor hours, enabling distributed micro-factory deployment closer to scattered German demand. |
| Digital Specification Portal Development | Direct architect engagement bypasses wholesale intermediaries, capturing margin in French municipal transparency-driven procurement. |
| Insulated Composite Panel Transition | Thermal break technology satisfies EU Green Deal U-value mandates, displacing non-compliant single-skin metalwork in renovation passports. |
| Retractable Membrane Capacity Addition | Motorized track systems serve California and Arizona hospitality outdoor dining expansion with premium pricing power. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews involving canopy fabricators, municipal procurement officers, architectural specification consultants, and aftermarket service providers. Secondary sources included EU Green Deal national implementation acts, ASTM and ASCE certification databases, building renovation passport registries, and aluminum industry association shipment reports. Bottom-up unit economics triangulated against top-down construction spending allocations across the analysis window.
Data-stream reconciliation across material cost indices, installation labor surveys, and retrofit permit filings informed the analytical framework. Segmentation dimensions encompassed material substrate, installation geometry, end-user channel, and regional regulatory cluster. CAGRs derived from trend extrapolation of renovation velocity and compliance-driven replacement cycles, with polycarbonate penetration rates and retractable system adoption curves as industry-specific forecast inputs throughout the forecast period.
Aluminum price volatility, EU regulatory enforcement variance, and fabrication workforce availability are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
EPS Sandwich Panels Market
Building & Construction Materials
Structural Insulated Panels (Sips) Market
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
North America Ready-Mix Concrete Market
Building & Construction Materials
Branched Reinforced Fittings Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Insulated Concrete Form (ICF) Market
Building & Construction Materials
Facade Anchor Systems Market
Building & Construction Materials
Asia-Pacific Particle Board Market
Building & Construction Materials
France Ceramic Tiles Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
Global Panelized and Modular Building System Market
Building & Construction Materials
Steel Casing Pipes Market
Building & Construction Materials
Philippines Building System Components Market
Building & Construction Materials
Artificial Wood Beams Market
Building & Construction Materials
North America Plywood Market