
 Global Sandwich Panels Market | 2026-2036
Global Sandwich Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sandwich Panels Market Analysis
Cold storage developers are redrawing procurement priorities across the sandwich panels value chain. Kingspan Group leverages its vertical manufacturing footprint to control core-to-facade delivery timelines. ArcelorMittal anchors steel-facing supply through integrated flat-rolled production in European mills. Tata Steel competes on coated substrate formulations tailored to humid-climate performance requirements.
Sandwich panels consist of rigid insulating cores bonded between two structural facings, typically steel or aluminum sheets, delivering thermal resistance values ranging from 0.20 to 0.65 W/m²K depending on core material and thickness. These composite assemblies serve as primary building envelope elements where energy conservation and rapid installation determine total project economics. Mineral wool cores command specification share in fire-rated vertical applications across European commercial construction. Polystyrene and EPS variants dominate cost-sensitive cold-storage builds in emerging Asian manufacturing clusters. Polyurethane formulations sustain premium positioning where maximum thermal efficiency per unit thickness governs design constraints.
The EU Green Deal and F-Gas Regulation constrain hydrofluorocarbon-based blowing agents in polyurethane core production, redirecting formulation investment toward pentane and hydro-olefin alternatives. ECHA REACH compliance requirements extend material disclosure obligations through the full sandwich panel supply chain, affecting importer certification burdens. Stakeholders must track evolving fire-safety test protocols under the EU Construction Products Regulation and assess core-material substitution timelines against project bid windows.
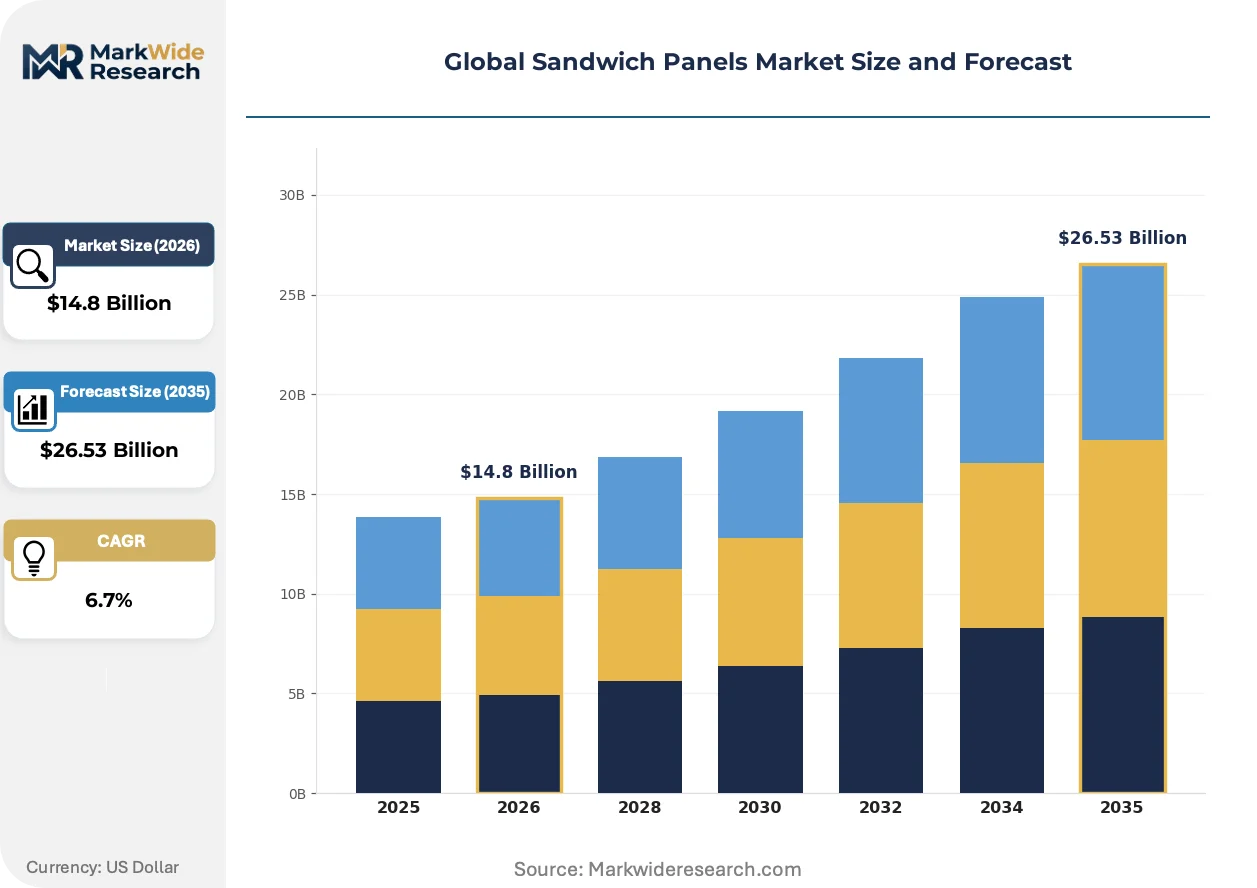
Market Dynamics
Polyurethane core formulation chemistry is fragmenting under pressure from the EU F-Gas Regulation, forcing manufacturers to abandon hydrofluorocarbon blowing agents and rebuild supply chains around pentane and hydro-olefin alternatives. This technical transition concentrates capital in integrated producers capable of captive chemical synthesis.
Growth Catalysts
- Cold-chain infrastructure buildout:Food logistics operators in Germany and the Netherlands are specifying insulated envelope systems for automated warehousing. This drives specification upgrades across temperature-controlled facilities.
- EU Green Deal building renovation mandates:Member-state energy performance standards for commercial envelopes accelerate mineral wool core adoption in fire-rated vertical applications.
- Mineral wool fire-safety preference:ECHA REACH disclosure requirements extend through the full supply chain, advantaging domestic European producers with certified material traceability systems.
Market Restraints
- Steel-facing input volatility:Flat-rolled steel prices fluctuate with energy costs at European mills, compressing margin predictability for panel fabricators without captive metallurgical supply.
- Core chemistry transition costs:Pentane-based polyurethane formulations require production line retooling and explosion-proofing investments that disadvantage smaller regional manufacturers.
- Construction cycle timing risk:Industrial project bid windows in Germany and Poland misalign with ECHA certification timelines, delaying specification approvals.
Strategic Opportunities
- India cold-storage underpenetration:FSSAI food safety mandates and PLI scheme incentives for food processing infrastructure create first-mover positioning for insulated panel suppliers establishing local fabrication.
- Building-integrated photovoltaics convergence:Sandwich panel facings serve as mounting substrates for thin-film solar laminates, opening specification in net-zero industrial construction.
- Direct-to-developer digital channels:Configurator platforms bypass traditional distributor markups for standardized cold-storage envelope packages.
Industry Challenges
- Fire-safety test protocol complexity:EU Construction Products Regulation updates require re-certification of existing core-facial bonding systems against revised reaction-to-fire classifications.
- Specialized application engineering talent scarcity:Thermal bridge calculation and hygrothermal modeling expertise concentrates at established technical consultancies, constraining in-house capability building at mid-tier fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sandwich Panels Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Polystyrene, Mineral Wool, EPS End User: Construction, Refrigeration, Cold Storage, Industrial Thickness: 50mm, 75mm, 100mm, 150mm Application: Wall Panels, Roof Panels, Floor Panels, Partition Panels |
| Companies Covered | Kingspan Group, ArcelorMittal, Metecno Group, Tata Steel, Assan Panel A.S., Nucor Corporation, DANA Group of Companies, Owens Corning, Isopan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sandwich Panels Market Emerging Trajectories
Refrigeration-grade envelope engineering is diverging from generic building insulation as temperature-controlled logistics operators impose performance guarantees and lifecycle accountability on panel suppliers.
Polyisocyanurate core chemistry is fragmenting the high-performance segment as cold-storage developers demand thermal resistance values below 0.25 W/m²K in reduced wall thicknesses. Pharmaceutical distribution centers in Germany and the Netherlands specify these formulations for validated temperature corridors. The technology compresses competitive positioning around chemical synthesis capabilities rather than panel fabrication scale.
REACH substance restriction proposals under ECHA review are tightening disclosure obligations for flame retardant additives in mineral wool cores. Industrial construction specifiers in France and Belgium now require extended safety data sheets for full panel assemblies. Fire-rated vertical applications face the steepest compliance burden as downstream liability extends to installation contractors.
Buyer consolidation among pan-European cold-chain operators concentrates procurement leverage at three-to-five major logistics developers. These entities unbundle after-sales technical service from panel supply contracts, awarding multi-year envelope performance agreements to engineering-capable fabricators. The model is most advanced in German food-retail distribution infrastructure.
Global Sandwich Panels Market Segmentation
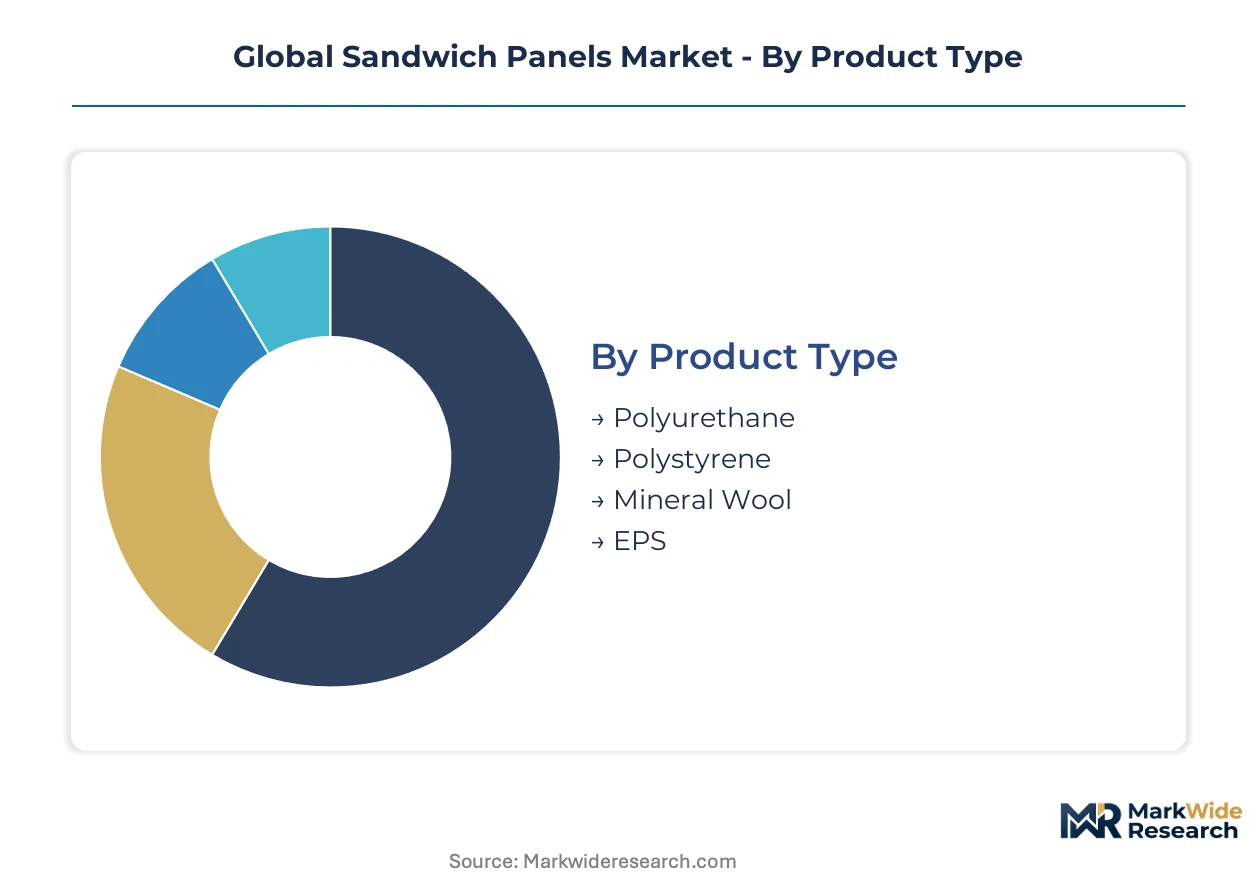
Sandwich panel procurement splits along thermal performance mandates and fire-safety compliance pathways. Specification engineers weight core chemistry against facade integration requirements and lifecycle energy accounting.
Product Type:
ECHA REACH disclosure obligations and EU F-Gas Regulation constraints differentiate core chemistry procurement across European member states.
- Polyurethane:Closed-cell rigid foam delivers thermal resistance values below 0.25 W/m²K in reduced thickness configurations. German pharmaceutical distribution centers specify these formulations for validated temperature corridors where maximum insulation per unit depth governs envelope design.
- Mineral Wool:Inorganic fiber cores bonded between steel facings achieve reaction-to-fire Class A2-s1,d0 ratings under EU Construction Products Regulation testing protocols. French and Belgian industrial construction specifiers now require extended safety data sheets for full panel assemblies containing these cores.
- Polystyrene:Expanded polymer formulations serve cost-sensitive cold-storage builds in emerging Asian manufacturing clusters where thermal efficiency requirements permit higher conductivity values.
- EPS:Molded bead foam cores dominate standardized warehouse envelope packages through distributor-configurator platforms targeting rapid-installation logistics facilities.
Polyurethane handles the majority of throughput; mineral wool is the fastest mover on share.
End User:
Customer procurement leverage concentrates at pan-European operators with multi-year envelope performance agreements.
- Construction:Commercial envelope retrofits under EU Green Deal building renovation mandates accelerate specification of fire-rated vertical panel systems. German industrial construction drives premium core substitution timelines.
- Cold Storage:Automated warehousing operators in the Netherlands and Germany unbundle after-sales technical service from supply contracts, awarding lifecycle accountability agreements to engineering-capable fabricators.
- Refrigeration:Temperature-controlled logistics infrastructure demands thermal bridge calculation expertise that concentrates at established technical consultancies.
- Industrial:Manufacturing facility envelopes balance installation speed against energy performance standards enforced through member-state building codes.
Construction absorbs the largest volume commitment; cold storage is climbing the fastest on procurement intensity.
Thickness:
Panel depth selection tracks thermal resistance targets and structural span requirements across building typologies.
- 100mm:Standard specification for commercial cold-storage walls where U-value targets meet racking load transfer requirements.
- 150mm:Deep-core configurations serve ultra-low temperature pharmaceutical corridors in German distribution hubs demanding sub-0.20 W/m²K envelope performance.
- 75mm:Mid-range thickness dominates roof applications where dead load constraints limit core depth.
- 50mm:Shallow profiles address partition and internal envelope applications with reduced thermal performance requirements.
100mm configurations carry the highest shipment volume; 150mm specifications are gaining share fastest in premium cold-chain infrastructure.
Application:
Facade position determines facing specification, fastening systems, and weathering performance guarantees.
- Wall Panels:Vertical envelope elements face the steepest fire-safety compliance burden as EU Construction Products Regulation updates require re-certification of core-facial bonding systems against revised reaction-to-fire classifications.
- Roof Panels:Structural deck applications integrate standing-seam or secret-fix joint systems designed for snow load and wind uplift resistance in Northern European climates.
- Floor Panels:Load-bearing composite decks serve mezzanine construction in automated warehousing where point loads from material handling equipment govern facing gauge selection.
- Partition Panels:Non-load-bearing internal divisions prioritize rapid installation and demountability for flexible industrial space configuration.
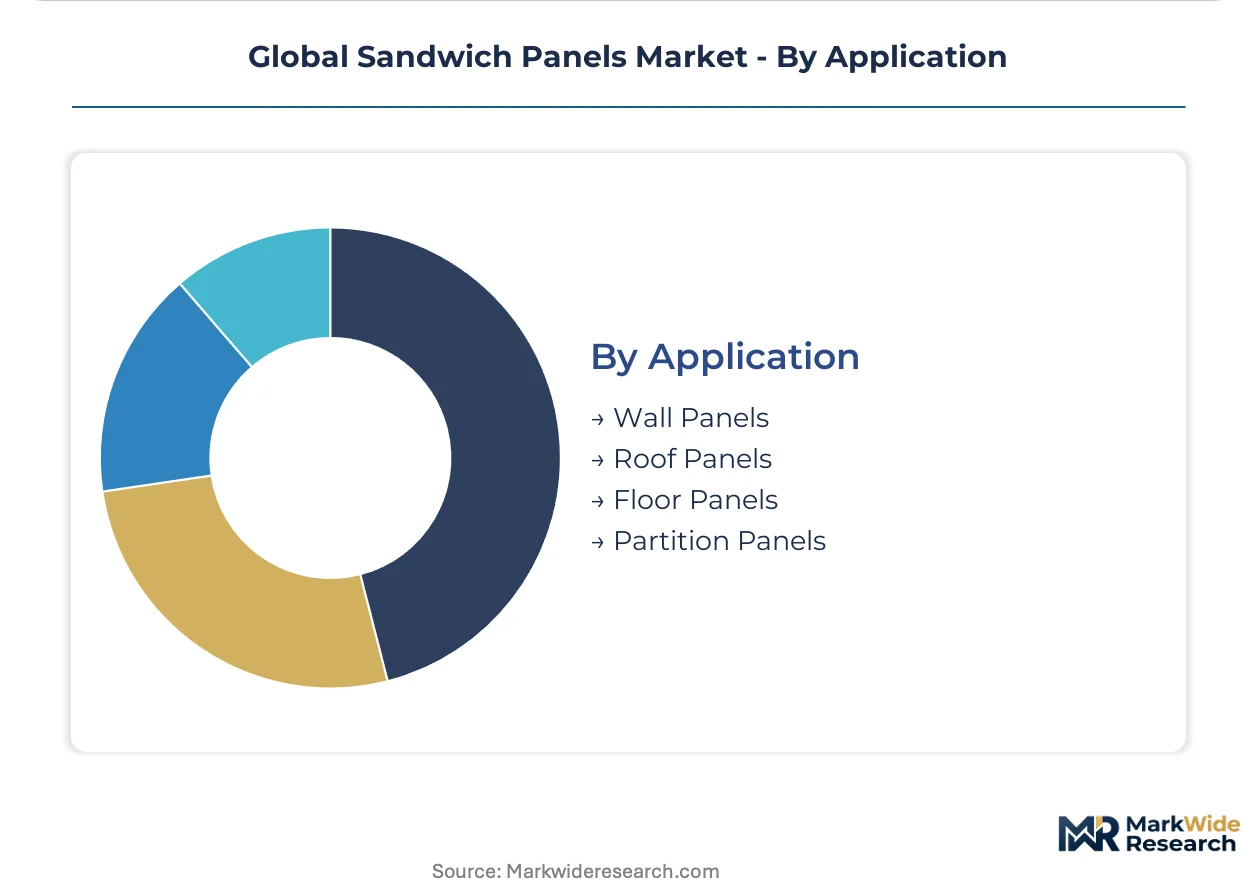
Wall panels command the dominant specification share; roof panels are expanding most quickly in net-zero industrial construction with building-integrated photovoltaics convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pan-European cold-chain operators and German industrial developers concentrate procurement leverage for insulated envelope systems. Specification engineers in temperature-controlled logistics drive demand for fire-rated mineral wool cores and high-performance polyurethane formulations. Asian manufacturing clusters absorb cost-sensitive polystyrene variants for standardized warehouse construction.
Germany
Pharmaceutical distribution centers in Frankfurt-Rhine-Main and Hamburg specify 150mm polyisocyanurate cores for sub-0.20 W/m²K thermal corridors. The EU F-Gas Regulation accelerates pentane-based polyurethane formulation transitions at Ruhr Valley chemical synthesis facilities. Automated warehousing investments in Lower Saxony unbundle technical service contracts from panel supply agreements.
Netherlands
Rotterdam-Antwerp port logistics operators demand lifecycle accountability guarantees for refrigerated envelope performance. ECHA REACH disclosure requirements tighten flame retardant documentation for mineral wool assemblies serving Dutch cold-storage retrofits. Food retail distribution hubs in North Brabant specify reaction-to-fire Class A2-s1,d0 rated wall systems under revised EU Construction Products Regulation protocols.
United States
USDA-inspected meat processing facilities and FDA-regulated pharmaceutical cold chains drive specification for insulated envelope systems in Midwest industrial corridors. EPA enforcement of hydrofluorocarbon phase-down timelines redirects blowing agent chemistry investments toward hydro-olefin alternatives. Dallas-Fort Worth logistics clusters absorb standardized 100mm wall panel configurations through distributor-configurator platforms.
India
FSSAI food safety mandates and PLI scheme incentives for food processing infrastructure create procurement acceleration in Maharashtra and Gujarat manufacturing belts. BIS certification requirements for imported core materials extend compliance timelines for European panel fabricators. Bangalore-Chennai industrial corridor developers specify cost-optimized EPS cores for rapid-installation warehouse envelopes.
China
MIIT industrial energy efficiency standards and dual carbon goals accelerate mineral wool substitution in coastal manufacturing facility retrofits. GB standards for construction fire safety tighten reaction-to-fire classifications for vertical panel applications in Yangtze River Delta logistics parks. Ningbo-Shanghai port cold-chain infrastructure absorbs polyurethane-core roof systems with building-integrated photovoltaics mounting compatibility.
Global Sandwich Panels Market Vendor Landscape
Player mix skews toward integrated steel-metallurgy conglomerates and specialized insulation fabricators with captive chemical synthesis capabilities. Market structure concentrates specification influence among pan-European operators with multi-year envelope performance agreements. Two strategic archetypes dominate: vertically integrated producers controlling core-to-facade delivery timelines, and regional fabricators competing on distributor-configurator platform efficiency. Competitive moves center on backward integration into steel-facing supply and pentane-based polyurethane production line retooling.
Among European-integrated producers, Kingspan Group and ArcelorMittal exemplify the metallurgy-chemistry convergence archetype, with the former representing specialized insulation-system fabrication and the latter anchoring steel-facing supply through flat-rolled production control. Tata Steel occupies a position within the coated-substrate formulation tier, reflecting humid-climate performance specialization. These three entities illustrate how competitive positioning fragments between chemical synthesis capability and metallurgical supply security.
| Leading Market Players |
|---|
| Kingspan Group |
| ArcelorMittal |
| Metecno Group |
| Tata Steel |
| Assan Panel A.S. |
| Nucor Corporation |
| DANA Group of Companies |
| Owens Corning |
| Isopan |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements with quarterly price-indexation clauses lock in flat-rolled steel supply for German and Dutch cold-storage developers while insulating fabricators from spot-market volatility in European metallurgical inputs. These structures concentrate procurement leverage among pan-European logistics operators capable of committing multi-year envelope performance contracts.
Pricing Analysis
Cost-plus contracts indexed to European steel benchmark indices dominate procurement between integrated producers and large-scale cold-chain developers. Three-tier pricing structure across premium, standard, and economy levels separates polyisocyanurate formulations with sub-0.25 W/m²K performance from mineral wool fire-rated systems and cost-optimized EPS cores. Pricing pressure stems from pentane-based polyurethane retooling investments that smaller regional fabricators struggle to amortize. Cold-storage operators in automated warehousing show lowest price sensitivity; emerging Asian manufacturing clusters absorb economy-tier polystyrene variants.
Supply Chain Analysis
Inventory cycles extending twelve to sixteen weeks for specialized core chemistries strain working capital at mid-tier fabricators lacking captive synthesis capabilities. Supply concentrates in Germany, the Netherlands, and Belgium for high-performance polyurethane formulations; China and India host cost-sensitive polystyrene and EPS production. The chain draws from flat-rolled steel, blowing agent chemicals, and mineral wool fiber inputs. Single-source vulnerability in pentane supply channels creates disruption exposure during EU F-Gas Regulation transition periods. Distribution runs through direct-to-developer configurator platforms and traditional distributor networks serving standardized warehouse packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against cross-laminated timber and structural insulated panel systems gaining specification share in low-rise industrial construction. Incumbents must navigate material substitution threats while rebuilding core chemistry capabilities under tightening environmental regulations.
For Market Incumbents: Shield specification position by accelerating backward integration into pentane-based polyurethane synthesis before REACH disclosure timelines tighten. Prioritize certification investment for reaction-to-fire Class A2-s1,d0 mineral wool assemblies to capture EU Green Deal renovation mandates. Channel control through direct-to-developer digital platforms defends margin position against distributor markup compression.
For New Entrants and Emerging Players: After-sales technical service unbundling from panel supply contracts presents white-space opportunity where established fabricators under-serve lifecycle accountability requirements. Target Indian cold-storage infrastructure under FSSAI compliance deadlines with local fabrication partnerships bypassing BIS import certification burdens. Configurator platform efficiency for standardized 100mm wall packages offers the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated producers with captive chemical synthesis and steel-facing supply security rather than pure-play fabricators exposed to input volatility. Long-term viability hinges on EU F-Gas Regulation compliance positioning and pentane formulation transition completion. Watch for ECHA flame retardant restriction proposals affecting mineral wool core certification timelines as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Chemistry | Pentane-based polyurethane synthesis secures supply continuity under EU F-Gas Regulation constraints. |
| Fire-Safety Certification Investment | Reaction-to-fire Class A2-s1,d0 ratings unlock EU Green Deal commercial envelope retrofit mandates. |
| Direct-to-Developer Digital Platform | Configurator tools bypass distributor markups for standardized cold-storage envelope packages. |
| Local Fabrication Partnership | Indian joint ventures navigate BIS certification burdens under FSSAI infrastructure buildout timelines. |
| Lifecycle Performance Contracting | Multi-year envelope accountability agreements align with Dutch automated warehousing procurement models. |
Methodological Framework
Desk research of customs trade databases, EU Construction Products Regulation certification registries, and ECHA REACH substance restriction proposals preceded structured interviews with cold-storage logistics procurement directors, sandwich panel fabrication plant managers, polyurethane chemical synthesis technical leads, and industrial construction specification engineers. Primary fieldwork combined with secondary validation against SEC filings of integrated steel-metallurgy conglomerates and European flat-rolled steel production data. Bottom-up shipment analysis by core chemistry and thickness tier triangulated against top-down envelope investment flows across temperature-controlled logistics infrastructure.
Variance decomposition across core material substitution timelines, steel input cost pass-through elasticity, and regulatory compliance deadline clustering shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include core chemistry type, facing material specification, thickness configuration, end-use application, and regional regulatory cluster. CAGRs derived from installed base growth in cold-chain infrastructure and replacement demand from EU Green Deal renovation mandates. Forecast inputs incorporated ECHA substance restriction proposal probability weightings and F-Gas Regulation phase-down trajectory assumptions.
Forecasts assume regulatory continuity in EU REACH and F-Gas Regulation enforcement regimes; material policy shifts would require re-modeling of core chemistry substitution timelines and certification burden impacts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US and Canada Corner Beads and Caps Market
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
Global Hydraulic Door Closer Market
Building & Construction Materials
India UPVC Doors and Windows Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
Global Steel Sections Market
Building & Construction Materials
Clay Roof Tiles Market
Building & Construction Materials
Global Fiber Cement Board Market
Building & Construction Materials
US Precast Concrete Market
Building & Construction Materials
Watertight Doors Market
Building & Construction Materials
Non-Residential Polished Concrete Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
South America Ready Mix Concrete Market
Building & Construction Materials
Waterproofing Solution Market
Building & Construction Materials
Asia-Pacific Particle Board Market
Building & Construction Materials
I-Joist Market