
 East Africa Gypsum Plaster Market | 2026-2036
East Africa Gypsum Plaster Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Gypsum Plaster Market Intelligence
Market Context
ISO 9001 quality management certification is rotating as the baseline qualification separating formal suppliers from informal traders across East Africa. Knauf Gypsum East Africa Limited leverages its German parent company's technical standards to sustain premium positioning in Kenyan urban projects. Tanzania Gypsum Limited anchors its supply chain through captive quarry access near Dodoma, while Erdemann Gypsum Limited differentiates via specialized decorative plaster formulations for hospitality interiors in Zanzibar and Mombasa.
Technical Definition and Segment Structure
East Africa gypsum plaster comprises calcium sulfate hemihydrate derived from natural gypsum rock or synthetic flue-gas desulfurization sources, mixed with water to form a workable paste that sets through rehydration into interlocking gypsum crystals, achieving compressive strengths of 2-6 MPa depending on formulation. Base Coat products dominate volume flows across the region's new-build residential towers, while Joint Compound segments capture disproportionate margin pools from commercial fit-out contractors demanding crack-resistant seam finishing. Decorative plaster lines represent the fastest-expanding category as Nairobi architects specify textured finishes for luxury apartment lobbies and retail flagship spaces.
Regulatory Framework
Kenya's National Construction Authority enforces KS 02-789 standards for gypsum-based building materials, while Tanzania's Tanzania Bureau of Standards mandates TZS 834 compliance for imported plaster products, effectively filtering substandard imports from Gulf and Asian suppliers. The East African Community's harmonized standards framework is reducing cross-border technical barriers between Kenya, Tanzania, Uganda, and Rwanda, enabling regional manufacturers to achieve scale through multi-country distribution. Stakeholders must monitor whether EAC mutual recognition agreements expand to cover environmental product declarations, as green building certification spreads from Nairobi to Kigali and Kampala.
Market Dynamics
The East Africa gypsum plaster market is reconfiguring around Kenya's National Construction Authority enforcement of KS 02-789 standards, which is systematically filtering informal suppliers from formal procurement channels across Nairobi's high-rise residential pipeline.
Growth Catalysts
- Building code harmonization:The East African Community's mutual recognition agreements are dissolving cross-border technical barriers between Kenya, Tanzania, Uganda, and Rwanda. Regional manufacturers now achieve scale through multi-country distribution networks.
- Natural gypsum quarry access:Tanzania Gypsum Limited's captive supply near Dodoma secures input cost stability unavailable to import-dependent competitors. Domestic rock extraction insulates production from currency volatility affecting synthetic gypsum imports.
- Decorative finish specification:Nairobi architects are specifying textured plaster systems for luxury apartment lobbies and retail flagship interiors. Hospitality developers in Zanzibar and Mombasa drive premium formulation demand.
Market Restraints
- Import dependency for synthetic gypsum:Flue-gas desulfurization-derived plaster relies on Asian and Gulf supply chains vulnerable to shipping rate spikes and port congestion at Mombasa and Dar es Salaam.
- Cement finish substitution:Traditional cement-based wall finishes retain cost advantage in rural construction and low-income housing segments outside major urban clusters.
- TZS 834 compliance friction:Tanzania Bureau of Standards testing protocols for imported products create multi-week clearance delays that advantage domestic producers with pre-certified production lines.
Strategic Opportunities
- Green building certification spread:Environmental product declaration requirements are emerging from Nairobi toward Kigali and Kampala. Early movers in lifecycle-assessed plaster production capture specification preference.
- Rwanda construction acceleration:Kigali's urban densification programs and commercial tower pipeline remain underpenetrated by established Kenyan and Tanzanian suppliers.
- Prefabricated wall system integration:Gypsum plasterboard manufacturers are converging with modular construction firms to supply finished interior systems rather than raw material inputs.
Industry Challenges
- Skilled applicator scarcity:Decorative plaster finishing requires trained craftsmen capable of achieving specified textures and durability standards. Vocational training capacity lags behind project demand in both Kenya and Tanzania.
- ISO 9001 certification timelines:Formal quality management system implementation demands documented process controls that informal traders cannot replicate without substantial organizational investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Gypsum Plaster Market |
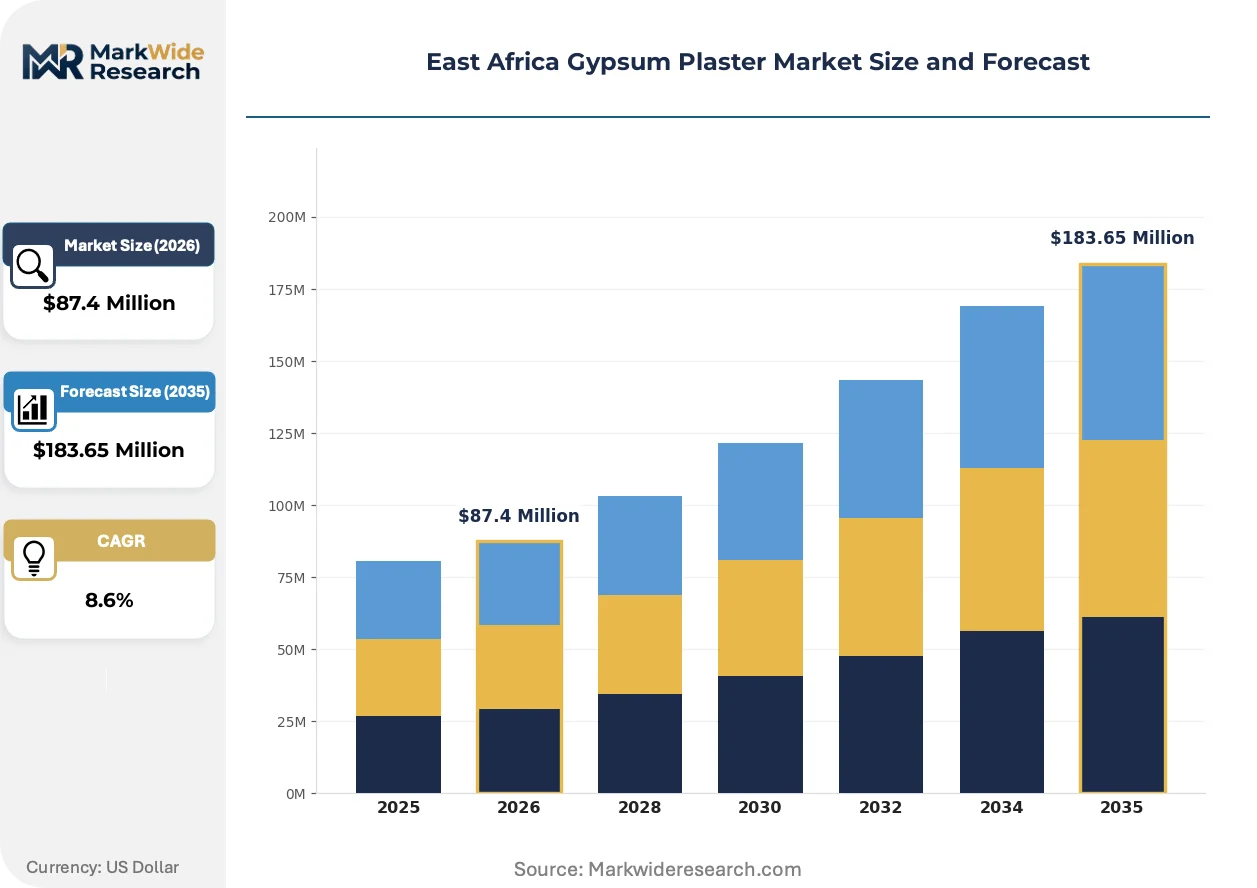
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $183.65 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Finishing, Base Coat, Joint Compound, Decorative Application: Residential, Commercial, Industrial, Renovation Distribution Channel: Direct Sales, Retail, Online, Wholesalers End User: Builders, Contractors, Architects, DIY Enthusiasts |
| Companies Covered | Knauf Gypsum East Africa Limited, Tanzania Gypsum Limited, Erdemann Gypsum Limited, Shazad Enterprise, Decordura, LafargeHolcim Ltd, Etex Group, Orathens Decor Limited, Saint-Gobain Construction Products Kenya Limited, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Gypsum Plaster Market Strategic Shifts & Innovations
Synthetic gypsum sourcing and application technology are converging to reshape competitive positioning across East Africa's construction supply base. Three distinct vectors are compressing traditional supply relationships.
Lightweight gypsum plaster formulations incorporating expanded perlite aggregate are decomposing the weight-based logistics economics that have favored dense cement finishes. High-rise contractors in Nairobi and Dar es Salaam are specifying these systems to reduce structural load and crane-time costs. The technology is compressing the installed-cost gap between gypsum and traditional finishes in vertical construction.
Kenya's National Construction Authority is tightening KS 02-789 enforcement through site inspection protocols and product batch testing. Non-compliant imports from Gulf and Asian traders are being rejected at port and project level. Commercial fit-out contractors now demand mill certificates and third-party test reports as standard procurement documentation.
Architect specification behavior is rotating toward performance-guaranteed interior systems rather than commodity material supply. Hospitality and luxury residential developers in Mombasa and Zanzibar are bundling plaster application warranties with material procurement. This pattern is most visible in high-end segments where defect liability periods extend beyond traditional trade warranties.
East Africa Gypsum Plaster Market Segmentation
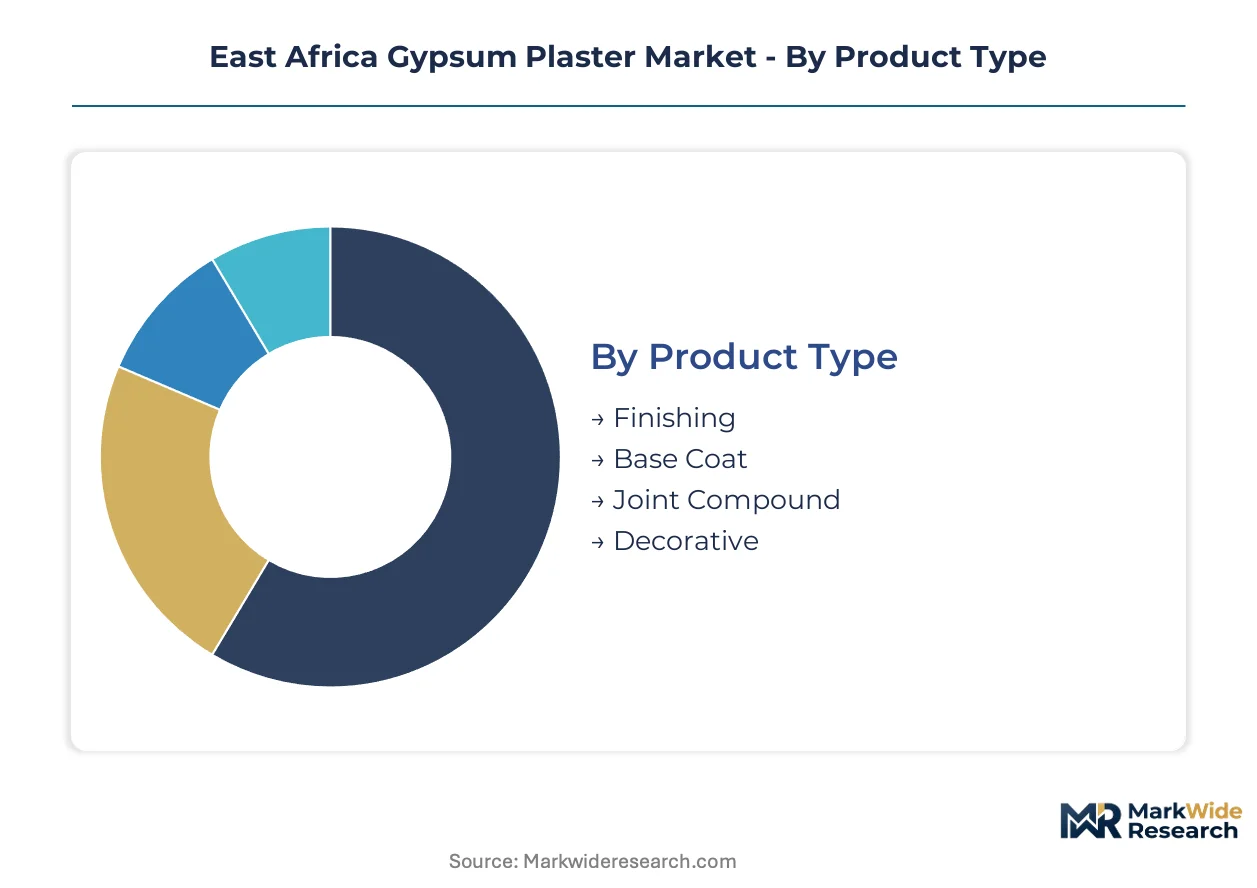
East Africa's gypsum plaster market fragments across four distinct dimensions that shape procurement patterns and margin structures. Product type and application concentration determine which suppliers capture specification preference in Nairobi's high-rise pipeline versus Tanzania's hospitality developments.
Product Type:
Domestic quarry access near Dodoma and Athi River favors natural gypsum-derived segments, while import-dependent synthetic formulations concentrate in coastal logistics hubs.
- Base Coat:Calcium sulfate hemihydrate formulations with 2-4 MPa compressive strength dominate volume flows into Kenya's National Construction Authority-certified residential towers. Nairobi contractors specify these systems for structural substrate preparation where drying speed and crack resistance outweigh finish quality.
- Decorative:Textured and polished plaster systems incorporating mineral aggregates and pigments command specification from hospitality developers in Zanzibar and Mombasa. Architects bundle these finishes with extended defect liability warranties, compressing procurement into integrated interior system contracts.
- Finishing:Thin-coat surface preparations achieving smooth substrates for paint or wallpaper application.
- Joint Compound:Crack-resistant seam finishing compounds for plasterboard systems in commercial fit-out projects.
Base Coat commands the established base. The steepest expansion runs through Decorative.
Application:
Cost tier differentiation separates premium specification in commercial hospitality from commodity procurement in mass residential.
- Residential:High-rise apartment construction across Nairobi and Dar es Salaam absorbs standard-grade base coat and finishing plaster through developer-contractor direct procurement. Kenya's tightening KS 02-789 enforcement is filtering informal suppliers from formal channels in this segment.
- Commercial:Office towers and retail flagships demand performance-guaranteed systems with third-party test documentation. Tanzania Bureau of Standards TZS 834 compliance creates multi-week clearance friction that advantages pre-certified domestic producers.
- Renovation:Existing building upgrade projects favor ready-mixed formulations with predictable setting characteristics.
- Industrial:Manufacturing facility specifications prioritize chemical resistance and durability in high-humidity environments.
Residential captures the volume concentration. Commercial delivers the margin premium.
Distribution Channel:
Supply chain configuration determines which channels dominate urban versus peri-urban penetration.
- Direct Sales:Large-scale developers in Nairobi and Dar es Salaam procure bulk plaster through manufacturer-direct contracts with volume pricing and technical support. This channel captures the majority of base coat volume in projects exceeding 500 units.
- Wholesalers:Regional distributors with multi-country East African Community networks supply smaller contractors across Kenya, Tanzania, and Rwanda. Harmonized standards are enabling cross-border scale for established wholesalers with ISO 9001 certification.
- Retail:Hardware stores and building material outlets serve renovation contractors and small-scale builders.
- Online:Emerging digital procurement platforms target DIY enthusiasts and small contractors with delivery logistics.
Direct Sales anchors the project pipeline. Wholesalers are gaining cross-border scale fastest.
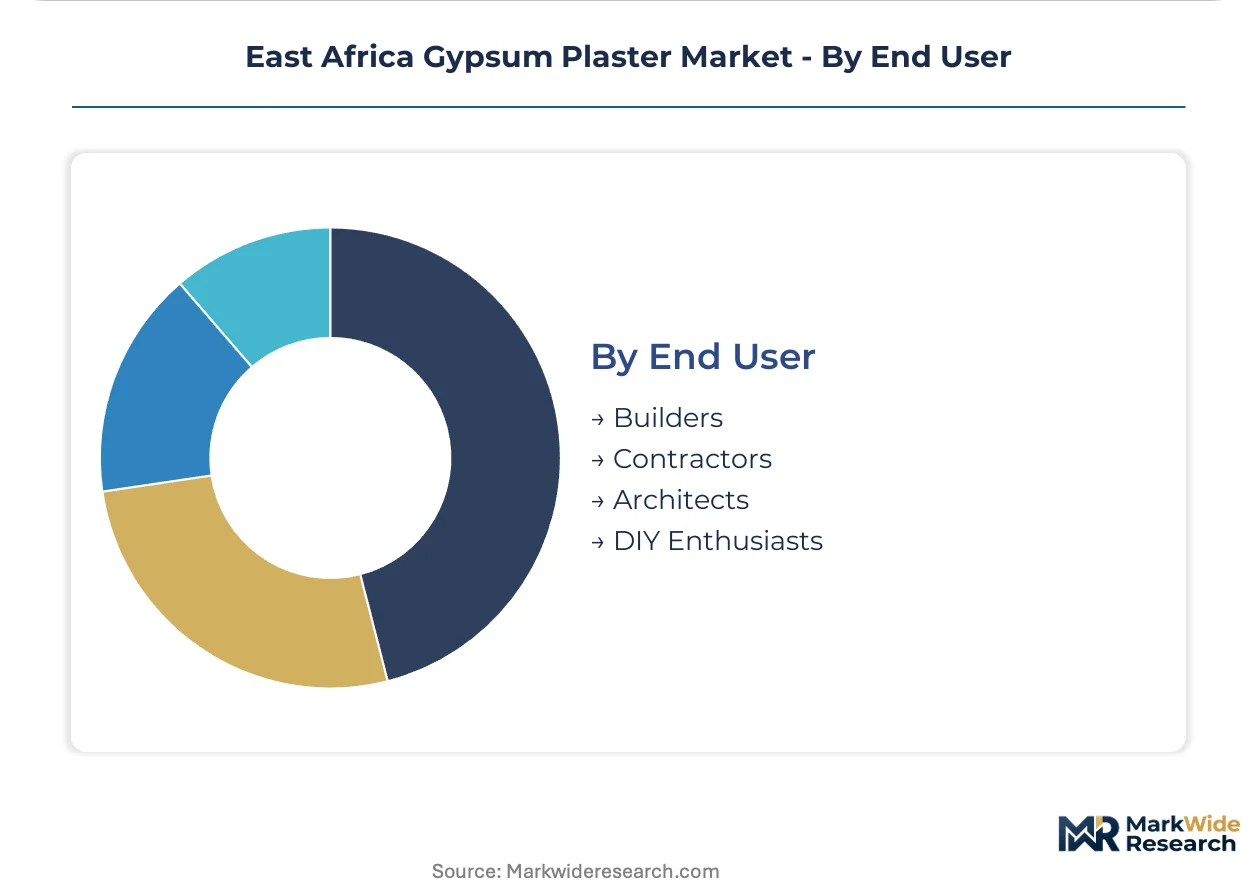
End User:
Technical capability requirements separate specification influencers from execution-focused purchasers.
- Contractors:Commercial fit-out and residential tower builders drive procurement decisions through performance specifications and application warranties. Skilled applicator scarcity in both Kenya and Tanzania is forcing contractors toward pre-mixed systems with predictable workability.
- Architects:Nairobi and Zanzibar design firms specify decorative plaster systems and texture finishes, bundling material selection with interior design vision. Their influence concentrates in hospitality and luxury residential segments.
- Builders:Developer-led construction firms prioritize cost certainty and supply reliability in volume procurement.
- DIY Enthusiasts:Small-scale renovation participants favor retail-accessible ready-mixed products with simplified application.
Contractors control the procurement volume. Architects are expanding specification influence most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale developers and commercial fit-out contractors concentrate procurement decisions across Nairobi, Dar es Salaam, and emerging secondary cities. Kenya's National Construction Authority enforcement of KS 02-789 standards filters informal suppliers from formal channels. Tanzania's Tanzania Bureau of Standards maintains parallel compliance frameworks for cross-border trade.
Kenya
Nairobi's high-rise residential pipeline absorbs base coat volumes through developer-direct procurement exceeding 500 units. The National Construction Authority's site inspection protocols and product batch testing reject non-compliant imports at Mombasa port. Athi River industrial corridor hosts domestic quarry operations supplying natural gypsum to ISO 9001-certified manufacturers serving the capital's construction boom.
Tanzania
Dar es Salaam's commercial tower developments drive specification of performance-guaranteed plaster systems with third-party documentation. The Tanzania Bureau of Standards' TZS 834 testing protocols create multi-week clearance delays that advantage pre-certified domestic producers. Dodoma's captive quarry access secures input cost stability for regional manufacturers expanding distribution across the East African Community.
Uganda
Kampala's emerging green building certification programs attract lifecycle-assessed plaster production from Kenyan suppliers leveraging harmonized EAC standards. The country's national standards body is aligning technical requirements with regional mutual recognition agreements. Entebbe Road corridor developments are specifying decorative finishes for hospitality and retail flagship interiors.
Rwanda
Kigali's urban densification programs and commercial tower pipeline remain underpenetrated by established regional suppliers. The Rwanda Standards Board is implementing construction material quality frameworks compatible with EAC harmonization. The Kigali Special Economic Zone is attracting prefabricated wall system integrators seeking modular construction partnerships.
Ethiopia
Addis Ababa's state-led infrastructure expansion creates demand for standardized interior finishing systems in government residential projects. The Ethiopian Conformity Assessment Enterprise maintains import testing requirements that filter substandard Asian supply. Bole Road corridor developments are absorbing cement-gypsum hybrid finishes in mid-market construction segments.
East Africa Gypsum Plaster Market Key Industry Players
Player mix skews toward quarry-anchored domestic producers and import-dependent multinational affiliates. Market structure consolidates around three to four established suppliers with ISO 9001 certification and National Construction Authority compliance documentation. Two strategic archetypes dominate: captive-quarry operators with input cost stability and premium-positioned technical specialists with German parent-company standards. Competitive moves concentrate on backward integration into quarry assets and cross-border distribution network expansion through East African Community harmonization.
Within the quarry-anchored tier, Tanzania Gypsum Limited exemplifies captive supply chain control through Dodoma rock extraction. Among Kenya-based fabricators, Erdemann Gypsum Limited and Saint-Gobain Construction Products Kenya Limited occupy positions spanning standard construction and premium specification segments. Knauf Gypsum East Africa Limited represents the multinational affiliate archetype leveraging parent-company technical standards for urban project penetration.
| Leading Market Players |
|---|
| Knauf Gypsum East Africa Limited |
| Tanzania Gypsum Limited |
| Erdemann Gypsum Limited |
| Shazad Enterprise |
| Decordura |
| LafargeHolcim Ltd |
| Etex Group |
| Orathens Decor Limited |
| Saint-Gobain Construction Products Kenya Limited |
| Others |
Cost & Logistics Intelligence
Captive quarry capacity near Dodoma and Athi River generates scale economies that compress unit production costs below import-dependent competitors, anchoring regional price floors while concentrating procurement leverage among ISO 9001-certified manufacturers serving Nairobi's high-rise pipeline.
Pricing Analysis
Long-term offtake contracts with Kenyan and Tanzanian developers typically index natural gypsum input costs to domestic extraction benchmarks rather than international synthetic gypsum spot markets. Three-tier pricing structure across premium decorative formulations, standard base coat, and economy-grade finishing plaster separates specification tiers by KS 02-789 certification status and volume commitment scale. Price erosion runs through economy segments as cement finish substitution intensifies in peri-urban construction. Small-scale renovation contractors exhibit highest price sensitivity, while hospitality developers in Zanzibar and Mombasa absorb premium formulation markups for extended defect liability coverage.
Supply Chain Analysis
Just-in-time delivery dominates Nairobi and Dar es Salaam commercial projects where crane-time scheduling penalizes inventory holding, while strategic stockpiling of natural gypsum rock insulates Dodoma-based producers from Mombasa port congestion cycles. Supply concentrates in Tanzania, Kenya, and emerging Ugandan distribution hubs drawing from Athi River and Dodoma extraction sites. Raw material flows depend on natural gypsum rock, synthetic flue-gas desulfurization feedstock, and expanded perlite aggregate for lightweight formulations. Single-source vulnerability runs through Mombasa and Dar es Salaam port chokepoints where TZS 834 and KS 02-789 testing protocols create clearance friction. Distribution runs through manufacturer-direct contracts for large-scale developers and ISO 9001-certified wholesalers serving cross-border East African Community trade.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Africa's gypsum plaster market is accelerating through regulatory inflection as Kenya's National Construction Authority tightens KS 02-789 enforcement, systematically filtering informal suppliers and compressing procurement into certified channels.
For Market Incumbents: Secure captive quarry access near Dodoma or Athi River to anchor input cost stability against currency volatility affecting synthetic gypsum imports. Deepen backward integration into lightweight perlite aggregate processing to capture specification preference from Nairobi high-rise contractors prioritizing structural load reduction. Defend against cement finish substitution in peri-urban segments by bundling application warranties with material supply. For New Entrants and Emerging Players: Anchor in Rwanda's underpenetrated Kigali corridor where urban densification programs outpace established Kenyan and Tanzanian distribution networks. Target green building certification-driven specification in Kampala's Entebbe Road hospitality developments as lifecycle-assessed plaster demand spreads from Nairobi. Pursue prefabricated wall system partnerships with modular construction firms to bypass skilled applicator scarcity constraints. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among quarry-anchored domestic producers with pre-certified TZS 834 and KS 02-789 production lines serving multi-year developer contracts. Long-term viability over the projection horizon rests on backward integration depth and cross-border East African Community scale rather than import-dependent trading models. Acquisition priority targets quarry-anchored mid-caps with dormant Rwandan or Ugandan distribution licenses. The signal to watch is Rwanda Standards Board alignment with EAC mutual recognition agreements, which would unlock multi-country procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Quarry Acquisition | Dodoma and Athi River rock access insulates production from Mombasa port currency volatility. |
| ISO 9001 Certification Investment | Quality management documentation filters informal competitors from National Construction Authority procurement channels. |
| Lightweight Formulation R&D | Perlite-aggregate systems reduce crane-time costs for Nairobi high-rise contractors. |
| Cross-Border Distribution Expansion | East African Community harmonization enables multi-country scale from Kenyan and Tanzanian production bases. |
| Prefabricated System Partnership | Modular construction integration bypasses skilled decorative applicator scarcity in hospitality segments. |
Research Approach
Initial hypotheses were tested against primary input from commercial construction procurement managers, gypsum plant operations directors, National Construction Authority compliance officers, and hospitality project developers, then refined through secondary validation against Tanzania Bureau of Standards regulatory filings, Kenya National Bureau of Statistics construction data, East African Community trade harmonization protocols, and ISO certification registry records. Bottom-up volume estimates from quarry extraction reports and plasterboard installation permits were triangulated against top-down construction spending flows across the analysis window.
Variance decomposition across product type, application concentration, distribution channel, and end-user technical capability shaped the segmentation framework. CAGRs were derived from installed-base expansion in Nairobi and Dar es Salaam high-rise pipelines, cement-gypsum substitution elasticity estimates, and regulatory compliance cost pass-through assumptions. Key inputs included National Construction Authority site inspection frequency data and Tanzania Bureau of Standards import clearance duration trends.
Decision-makers should treat outputs as directional under sustained East African Community standards harmonization and stable quarry extraction licensing; material deviation would warrant model refresh. Revision becomes warranted when Rwanda Standards Board EAC alignment or Kenya National Construction Authority enforcement intensity crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Noise Insulation Jackets Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
North America Siding and Decking Market
Building & Construction Materials
US Windows Market
Building & Construction Materials
Bamboo Engineered Wood Market
Building & Construction Materials
USA and Canada Fence Screen Market
Building & Construction Materials
Marble Market
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
Global Awning Market
Building & Construction Materials
Fire-Retardant Treated Wood Market
Building & Construction Materials
Asia-Pacific Construction Adhesives Market
Building & Construction Materials
Oriented Strand Board (OSB) Market
Building & Construction Materials
North America Laminated Veneer Lumber Market
Building & Construction Materials
Concrete Conditioner Market
Building & Construction Materials
Red Brick Market
Building & Construction Materials
Building and Construction Plastic Fasteners Market