
 Pre-Engineered Building Market | 2026-2036
Pre-Engineered Building Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Engineered Building Market Intelligence
The EU Green Deal's embodied carbon benchmarks for construction materials is restructuring procurement priorities across European commercial real estate. BlueScope Steel Limited leverages its integrated steelmaking and coating capabilities to supply lower-emission structural sections. Nucor Corporation anchors North American supply through its electric-arc furnace network and scrap-based production model. Zamil Steel Holding Company dominates Middle Eastern and African project flows with region-specific engineering centers.
Pre-engineered buildings are factory-fabricated structural systems comprising rigid steel frames, secondary purlins and girts, and metal cladding, engineered to precise load specifications and shipped for bolted field assembly. Primary industrial purpose centers on rapid-deployment enclosures for warehousing, manufacturing, and distribution with construction timelines compressed versus conventional methods. Steel Buildings command the largest product type share due to recyclability and span flexibility, while Hybrid Structures capture expanding margin pools as owners blend structural steel with insulated concrete panels for thermal performance. Warehousing leads application demand as fulfillment center operators prioritize speed-to-occupancy over bespoke architectural expression.
ISO 3834 welding quality standards and EN 1090 structural steel execution classes govern European market access and fabricator certification requirements. India's BIS certification and PLI scheme for specialty steel production shape domestic sourcing mandates and import substitution dynamics. China's GB standards and dual carbon goals impose emissions intensity ceilings on steel-intensive construction inputs. Stakeholders must track evolving carbon border adjustment mechanisms and their interaction with national building codes to anticipate cost pass-through structures and supplier qualification barriers.
Market Dynamics
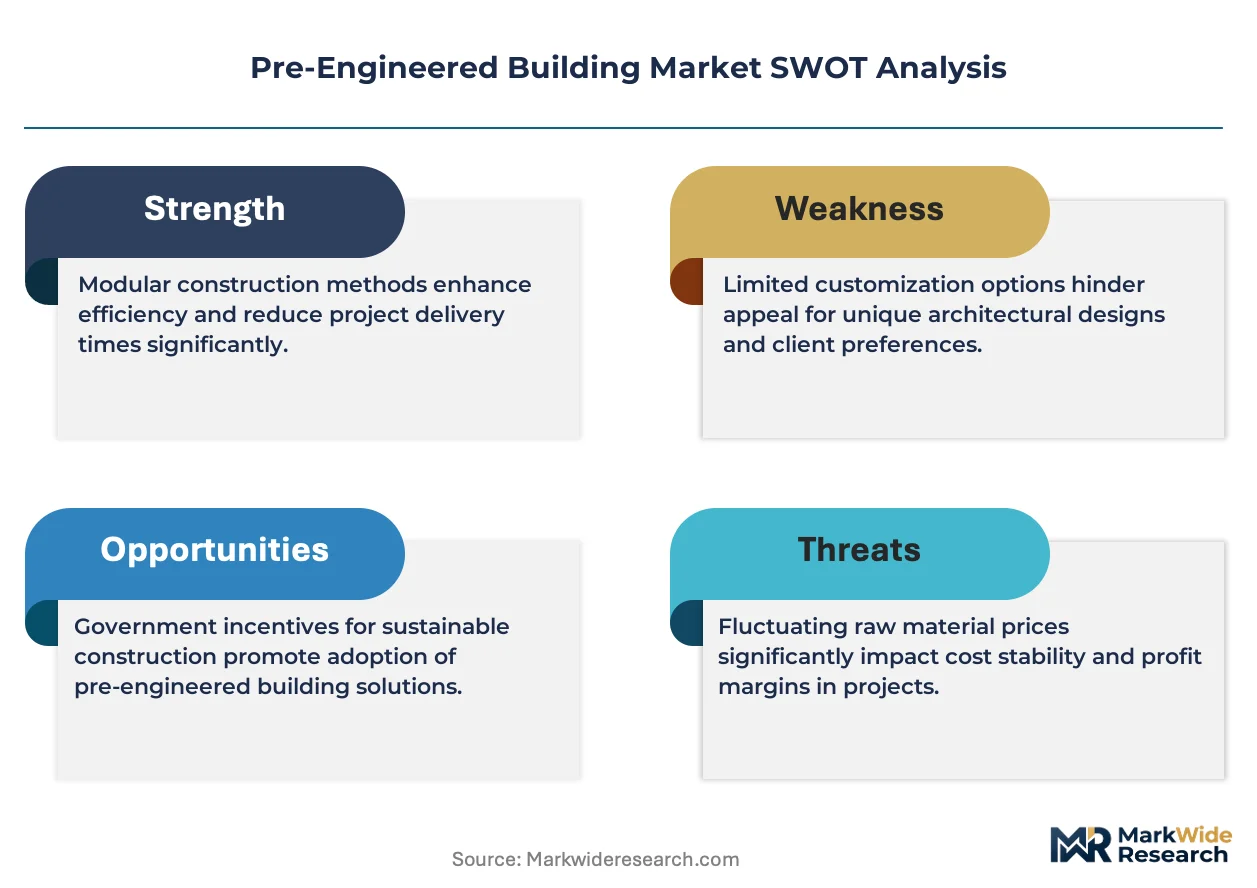
The EU Green Deal's embodied carbon benchmarks are compressing procurement timelines for structural steel across European commercial real estate, forcing fabricators to certify lower-emission supply chains before contract award.
Growth Catalysts
- E-commerce fulfillment networks:Third-party logistics operators in the United States are specifying pre-engineered buildings for speculative warehouse development to compress speed-to-occupancy below conventional construction cycles.
- India's PLI scheme for specialty steel:Domestic production incentives are accelerating import substitution for high-grade structural sections used in industrial PEB installations across Gujarat and Tamil Nadu manufacturing corridors.
- Electric-arc furnace deployment:Scrap-based steelmaking in North America is lowering embodied carbon intensity in structural sections, aligning output with procurement specifications from institutional real estate investors.
Market Restraints
- Hot-rolled coil price volatility:Input cost swings for primary steel sections compress fabricator margins and complicate fixed-price contract bidding for projects with six-month delivery windows.
- Chinese supply concentration:Dependence on integrated mills in Hebei and Jiangsu provinces for specialized structural sections creates exposure to export duty fluctuations and carbon intensity ceilings under dual carbon goals.
- Concrete tilt-up substitution:Insulated concrete panel systems are capturing mid-span industrial projects in markets where local labor pools favor cast-in-place construction methods.
Strategic Opportunities
- Vietnam and Indonesia manufacturing zones:Industrial park developers in Ho Chi Minh City and Batam are specifying PEB systems for electronics and automotive supplier facilities to meet accelerated production ramp schedules.
- EU Carbon Border Adjustment Mechanism:The phased implementation is creating first-mover advantage for European fabricators with certified low-emission supply chains against import competition.
- Building information modeling convergence:Integration of structural engineering software with automated fabrication equipment is compressing design-to-delivery timelines for complex multi-span configurations.
Industry Challenges
- Welding certification bottlenecks:ISO 3834 and EN 1090 compliance timelines for fabricator qualification are extending project pursuit cycles by four to eight months in European markets.
- Site coordination complexity:Bolted field assembly of precision-fabricated components demands specialized erection crews, with labor scarcity in remote project locations delaying commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Engineered Building Market |
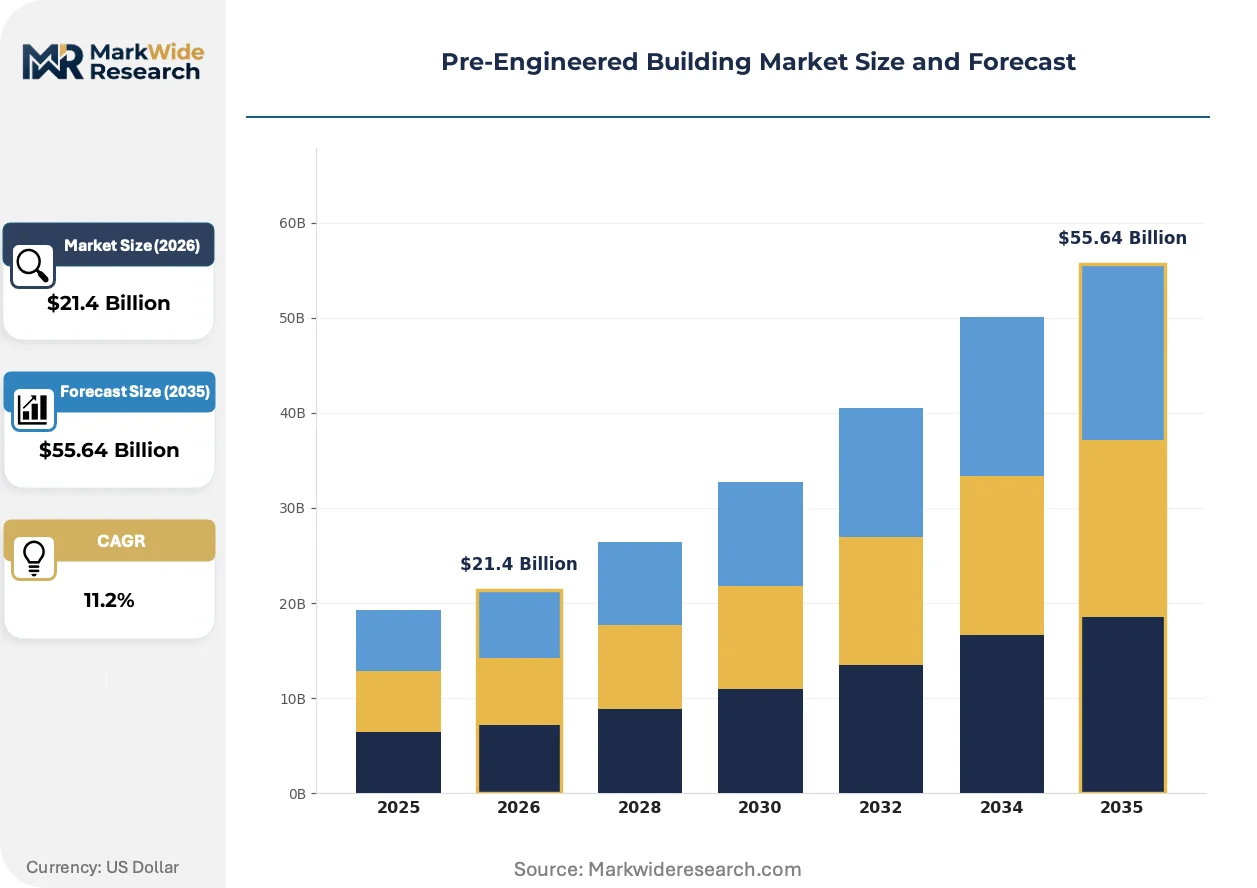
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $55.64 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Buildings, Concrete Buildings, Hybrid Structures, Modular Units End User: Commercial, Residential, Industrial, Agricultural Application: Warehousing, Retail Space, Manufacturing Facilities, Aircraft Hangars Installation Type: On-site Assembly, Prefabricated Units, Custom Design, Standardized Kits |
| Companies Covered | BlueScope Steel Limited, Zamil Steel Holding Company, Nucor Corporation, Kirby Building Systems, Tata BlueScope Steel, PEB Steel Buildings Co. Ltd., Interarch Building Products Pvt. Ltd., Everest Industries, Tiger Steel Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Engineered Building Market Strategic Shifts & Innovations
Digital fabrication and embodied carbon accounting are rewriting how structural systems are specified, priced, and delivered across industrial construction markets.
High-strength low-alloy steel formulations with optimized yield-to-weight ratios are rewriting span capabilities for wide-clearance warehousing. E-commerce fulfillment operators in the United States are specifying these sections for speculative buildings exceeding 200,000 square feet. The technology is rewriting competitive positioning between integrated mills and mini-mills in structural product lines.
The EU Green Deal's carbon performance benchmarks for construction materials are restructuring tender evaluation criteria across member states. Fabricators must now document cradle-to-gate emissions through Environmental Product Declarations before contract shortlisting. Steel building suppliers with electric-arc furnace feedstock are capturing premium positioning in German and French industrial procurement.
Design-build delivery models are displacing traditional design-bid-award sequences for speculative industrial projects. Institutional investors in United States logistics real estate are engaging PEB fabricators during site acquisition to compress entitlement-to-occupancy timelines. The shift is most visible in Dallas-Fort Worth and Phoenix distribution corridors where land competition accelerates capital deployment velocity.
Pre-Engineered Building Market Segmentation
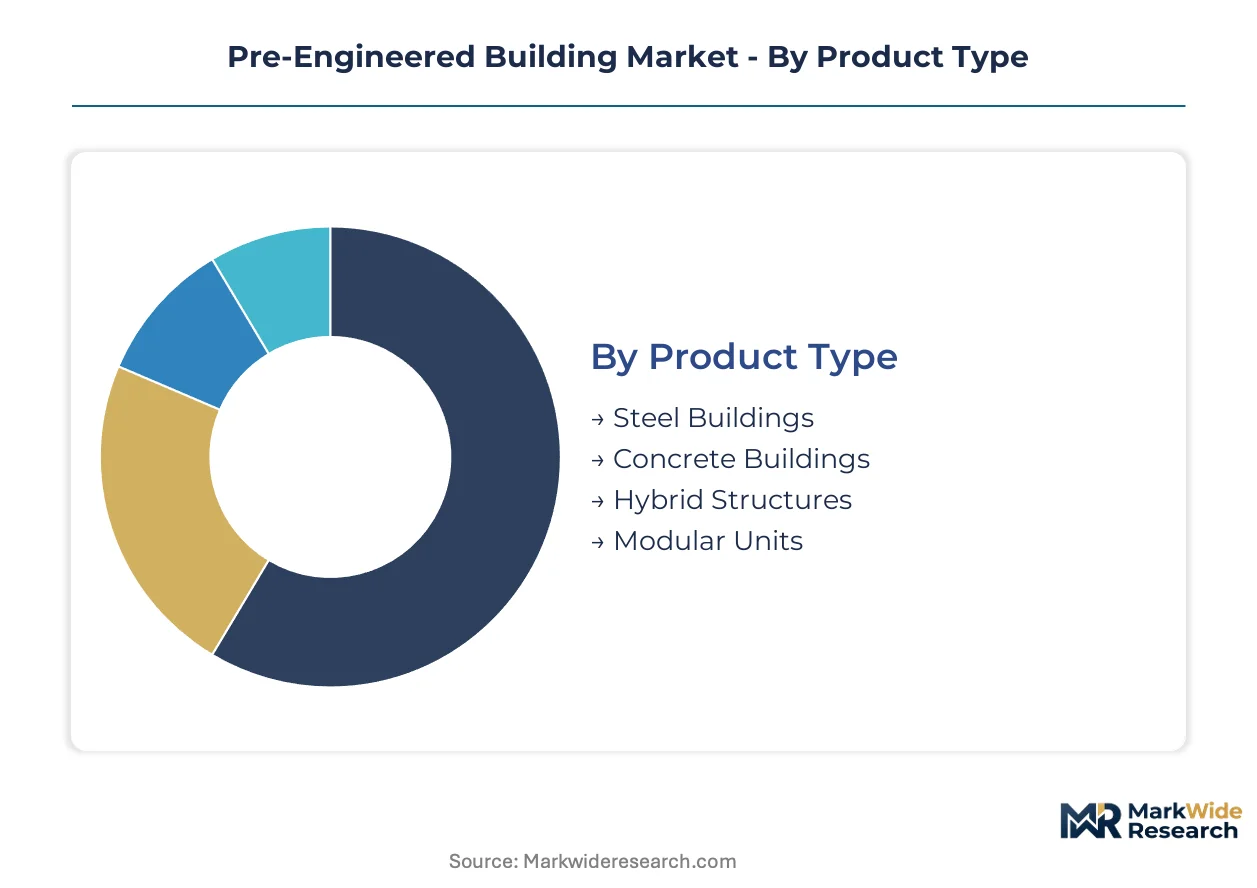
Pre-engineered building procurement decisions cascade through multiple segment dimensions, each triggering distinct certification requirements, cost structures, and supply chain configurations. Fabricators must align production capabilities across product types, end-user specifications, and installation modalities to capture contract awards in this specification-intensive market.
Product Type:
EN 1090 execution classes and ISO 3834 welding certifications apply differentially across structural material categories, with steel-intensive systems demanding the most extensive fabricator qualification documentation.
- Steel Buildings:Rigid steel frames with secondary purlins and girts engineered to precise load specifications dominate industrial warehousing applications. E-commerce fulfillment operators in the United States specify these systems for speculative developments exceeding 200,000 square feet where speed-to-occupancy compresses conventional construction timelines.
- Hybrid Structures:Blended configurations combining structural steel with insulated concrete panels capture expanding margin pools as thermal performance benchmarks tighten under EU Green Deal embodied carbon regulations. German and French industrial procurement increasingly mandates Environmental Product Declarations for these composite systems.
- Concrete Buildings:Precast concrete structural systems with factory-cast panels and tilt-up assembly methods serve markets where local labor pools favor cast-in-place construction expertise.
- Modular Units:Fully volumetric factory-finished enclosures shipped as complete spatial units address remote site access constraints and accelerated commissioning requirements.
Steel Buildings sits at the top of the volume ranking, with Hybrid Structures climbing the fastest as carbon accounting reshapes material selection criteria.
End User:
Customer procurement sophistication varies sharply across end-user categories, with institutional investors and corporate owner-operators demanding divergent documentation packages and performance guarantees.
- Industrial:Manufacturing and distribution facility operators prioritize rapid-deployment enclosures with compressed entitlement-to-occupancy timelines. Third-party logistics providers in Dallas-Fort Worth and Phoenix distribution corridors engage fabricators during site acquisition to accelerate capital deployment velocity.
- Commercial:Retail and office developers specify pre-engineered systems where architectural expression takes secondary priority to functional enclosure and cost predictability.
- Agricultural:Farm operators and agribusiness enterprises utilize standardized structural kits for equipment storage and livestock housing where span flexibility accommodates machinery dimensions.
- Residential:Single-family and multi-family housing applications remain peripheral to mainstream PEB demand, constrained by aesthetic customization expectations and local zoning variances.
Industrial end users command the largest contract values, with Commercial applications expanding most quickly as design-build delivery models displace traditional sequences.
Application:
Functional use cases determine load specification complexity, with aviation and heavy manufacturing imposing the most demanding engineering requirements on fabricator technical capabilities.
- Warehousing:Fulfillment center enclosures with wide-clearance spans and minimal internal column grids dominate speculative development pipelines. High-strength low-alloy steel formulations with optimized yield-to-weight ratios are rewriting span capabilities for facilities serving e-commerce distribution networks.
- Manufacturing Facilities:Heavy industrial enclosures with crane-capable frames and process-specific environmental controls require customized engineering beyond standardized kit capabilities.
- Aircraft Hangars:Extra-wide span structures with specialized door systems and clear height specifications serve military and civilian aviation maintenance operations.
- Retail Space:Big-box and strip mall enclosures with branded facade treatments balance structural efficiency against tenant visibility requirements.
Warehousing holds the dominant share by project count, with Manufacturing Facilities gaining share fastest as reshoring initiatives accelerate industrial construction across Gujarat and Tamil Nadu manufacturing corridors.
Installation Type:
Field assembly methodology determines labor skill requirements, equipment mobilization costs, and project schedule risk allocation between fabricator and general contractor.
- On-site Assembly:Bolted field erection of precision-fabricated components demands specialized crews with ISO 3834-compliant welding qualifications where field modifications become necessary.
- Prefabricated Units:Factory-complete volumetric modules minimize site labor exposure and accelerate commissioning schedules for remote project locations with scarce skilled trades.
- Custom Design:Engineer-to-order configurations address non-standard span requirements, process loads, or aesthetic specifications outside standardized kit parameters.
- Standardized Kits:Catalog-based structural systems with pre-engineered connection details and repetitive bay spacing optimize fabricator production economics for speculative warehouse development.
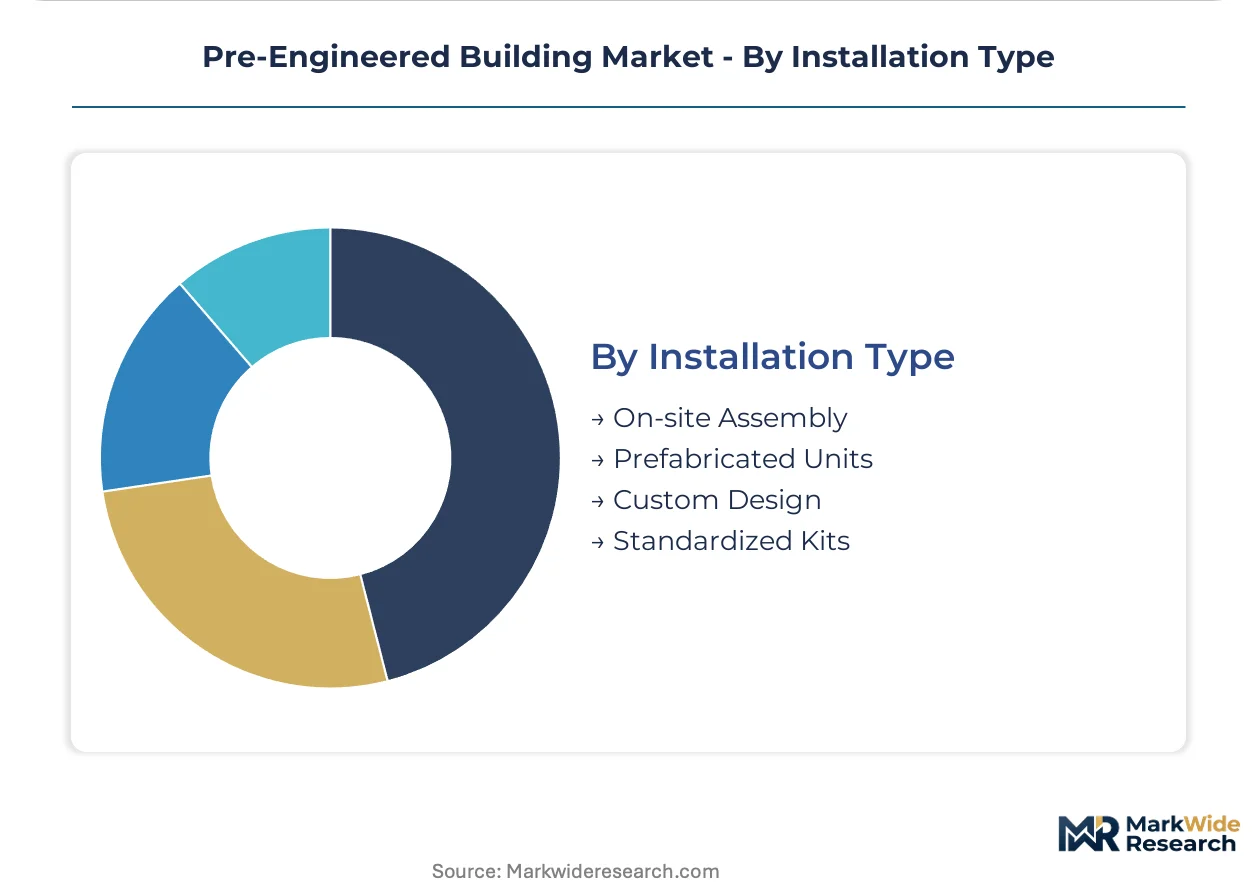
On-site Assembly accounts for the majority of installed square footage, with Prefabricated Units showing the steepest expansion trajectory as labor scarcity in remote locations extends commissioning schedules for conventional methods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pre-engineered building systems originated in mid-20th century United States military and industrial construction, where standardized steel framing enabled rapid deployment across dispersed sites. That heritage shapes today's geographic concentration of engineering expertise and fabrication capacity.
United States
Third-party logistics operators specify PEB systems for speculative warehouse developments exceeding 200,000 square feet across Dallas-Fort Worth and Phoenix distribution corridors. EPA industrial emissions guidelines and state-level green building codes influence material selection for institutional investors. Design-build delivery models compress entitlement-to-occupancy timelines in these Sun Belt logistics clusters.
Germany
Industrial procurement mandates increasingly require Environmental Product Declarations documenting cradle-to-gate emissions before contract shortlisting. EU Green Deal embodied carbon benchmarks restructure tender evaluation criteria across commercial real estate development. Fabricators in the Ruhr industrial region and Bavarian manufacturing zones certify lower-emission supply chains to maintain market access.
India
Manufacturing corridor developers in Gujarat and Tamil Nadu specify PEB installations for electronics and automotive supplier facilities under accelerated production ramp schedules. BIS certification requirements and the PLI scheme for specialty steel production shape domestic sourcing mandates and import substitution dynamics. High-grade structural sections now flow from domestic mills to industrial park construction sites.
China
Integrated mills in Hebei and Jiangsu provinces supply specialized structural sections subject to dual carbon goals emissions intensity ceilings. GB standards govern fabrication quality and structural execution classes for domestic and export markets. Yangtze River Delta manufacturing zones absorb substantial PEB output for warehouse and logistics facility construction.
United Arab Emirates
Industrial park developers in Dubai and Abu Dhabi specify pre-engineered systems for trade zone warehousing and light manufacturing facilities. MOHAP building safety regulations and emirate-level construction codes govern structural certification requirements. Gulf Cooperation Council logistics hub expansion drives demand for rapid-deployment enclosures across free zone developments.
Pre-Engineered Building Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification depth and integrated steelmaking capabilities. The vendor base stratifies between integrated mills with captive structural section supply, specialized fabricators with regional engineering centers, and turnkey contractors assembling imported kits. Three archetypes dominate: steel producers backward-integrated into fabrication, independent engineering specialists, and construction conglomerates with captive PEB divisions. Capacity expansion and strategic partnerships constitute the dominant competitive moves.
Among integrated steelmakers with fabrication arms, BlueScope Steel Limited and Nucor Corporation exemplify the premium-tier archetype through scrap-based and electric-arc furnace production models. Zamil Steel Holding Company occupies a position as a regional engineering specialist with Middle Eastern and African market concentration. These three anchors represent distinct strategic postures—integrated mill dominance, North American recycling leadership, and emerging market engineering depth—without claims to specific product configurations or financial performance.
| Leading Market Players |
|---|
| BlueScope Steel Limited |
| Zamil Steel Holding Company |
| Nucor Corporation |
| Kirby Building Systems |
| Tata BlueScope Steel |
| PEB Steel Buildings Co. Ltd. |
| Interarch Building Products Pvt. Ltd. |
| Everest Industries |
| Tiger Steel Engineering |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap fabricators across South Korea and Turkey anchor regional pricing discipline through long-term mill relationships and limited balance-sheet capacity for speculative inventory. Their ownership structure constrains aggressive price-cutting during hot-rolled coil volatility, preserving margin pools for integrated producers with captive steel supply.
Pricing Analysis
Project-based fixed-price contracting dominates procurement for industrial warehousing developments, with bid bonds and performance guarantees separating qualified fabricators from commodity assemblers. Price differentiation hinges on EN 1090 execution class certification and electric-arc furnace feedstock documentation for EU Green Deal compliance. Pricing pressure stems from hot-rolled coil volatility compressing fabricator margins on six-month delivery windows. Third-party logistics operators show highest price sensitivity on speculative developments, while institutional investors with ESG mandates accept premium positioning for certified low-carbon supply chains.
Supply Chain Analysis
India's PLI scheme for specialty steel and domestic-content mandates in Saudi Arabia's Vision 2030 industrial zones are reshaping sourcing patterns away from Chinese integrated mills. Structural steel sections draw from India, South Korea, and Turkey as alternative supply nodes to Hebei and Jiangsu provinces. Galvanized coil, high-strength low-alloy plate, and engineered connection hardware constitute critical input dependencies. Single-source vulnerability concentrates in specialized structural sections from Chinese integrated mills subject to export duty fluctuations. Distribution runs through fabricator-owned engineering centers with regional project management capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU carbon border adjustment exposure and Indian domestic-content incentives, with cost differentials exceeding fifteen percentage points on embodied carbon-compliant structural sections.
For Market Incumbents: Hedge margin compression by securing long-term offtake agreements with electric-arc furnace mills in North America and India before carbon border adjustment mechanisms phase in. Deepen backward integration into coating and connection hardware production to capture value pools escaping to component suppliers. ISO 3834 welding certification investments create switching costs against emerging regional competitors. For New Entrants and Emerging Players: Enter via Vietnam and Indonesia manufacturing corridors where industrial park developers specify PEB systems for electronics and automotive supplier facilities with accelerated ramp schedules. White-space concentrates in prefabricated modular units for remote mining and energy projects where labor scarcity extends conventional assembly timelines. Go-to-market positioning should anchor on design-build delivery integration with regional engineering centers. For Investors and Strategic Acquirers: Valuations sit cheapest among independent fabricators without captive steel supply facing margin compression from hot-rolled coil volatility. Long-term viability favors assets with certified low-emission supply chains and regional engineering depth in high-growth manufacturing corridors. Watch for EU Carbon Border Adjustment Mechanism implementation pace as inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steelmaking | Captive electric-arc furnace supply secures margin pools against coil volatility and carbon border exposure. |
| Regional Engineering Center Expansion | Local design capabilities in Gujarat and Vietnam compress entitlement-to-occupancy timelines for industrial developers. |
| EN 1090 Certification Investment | Execution class documentation unlocks German and French procurement mandates under EU Green Deal benchmarks. |
| Prefabricated Modular Unit Development | Factory-complete volumetric modules address labor scarcity in remote mining and energy project locations. |
| Environmental Product Declaration Program | Cradle-to-gate emissions documentation captures premium positioning with institutional ESG-mandated investors. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with PEB fabricator executives, industrial real estate developers, structural steel procurement managers, and third-party logistics operators with secondary validation. Trade data from customs authorities, SEC filings from integrated steelmakers, EU ETS emissions registries, and industrial construction permit databases anchored volume estimates. Bottom-up project pipeline analysis and top-down steel consumption modeling were triangulated against disclosed capacity expansions.
Segment-weighting applied product type, end user, application, and installation modality dimensions across the projection horizon. CAGRs derived from regression against industrial construction spending, e-commerce fulfillment square footage absorption, and manufacturing reshoring announcements. Forecast inputs incorporated hot-rolled coil price elasticity, welding certification backlog durations, and carbon border adjustment implementation schedules.
Inputs from fabricator executives and permitting databases were available through the study window; gaps in proprietary project margin data introduce uncertainty bands around profitability estimates. Forecasts reflect documented assumptions on steel price trajectories and regulatory implementation pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
UAE Facade Market
Building Construction
India Commercial Construction Market
Building Construction
Ireland Data Center Construction Market
Building Construction
Middle East Data Center Construction Market
Building Construction
Japan Construction Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
Turkey Construction Market
Building Construction
Global Modular Fabrication Market
Building Construction
Africa Construction Market
Building Construction
China Prefabricated Buildings Market
Building Construction
Vietnam Construction Market
Building Construction
India Prefabricated Buildings Market
Building Construction
Egypt Residential Construction Market
Building Construction
UAE Transportation Infrastructure Construction Market
Building Construction
China Construction Market
Building Construction
Modular and Prefabricated Construction Market