
 United States Roofing Market | 2026-2036
United States Roofing Market Size, Share, and Industry Trends Forecast 2026-2036
United States Roofing Market Insights
Cool-roof membrane technology is narrowing the performance gap between traditional asphalt shingles and premium reflective systems in the southern and western states. GAF Materials Corporation leverages its national manufacturing footprint to supply contractors with integrated solar-shingle bundles. Owens Corning sustains R&D intensity in fiberglass mat reinforcement for extended warranty positions. CertainTeed Corporation anchors its position through specialty-accessory depth and color-matching systems that reduce field waste.
United States roofing encompasses the design, fabrication, and installation of weatherproof envelope systems that protect structures from precipitation, thermal transfer, and wind uplift, with asphalt fiberglass shingles typically rated for 110 mph wind speeds and metal panels achieving Class 4 hail impact resistance. The primary purpose spans new construction weatherproofing, existing roof replacement at end of service life, and retrofit upgrades for energy performance or code compliance. Shingles retain volume leadership in residential replacement due to installer familiarity and supply-chain ubiquity, though margin pools concentrate in metal roofing where material costs support higher project values. Membranes dominate commercial flat-roof applications where TPO and PVC single-ply systems address thermoplastic welding standards and extended membrane warranties. The residential end-user segment shows structural resilience through insurance-driven replacement cycles following severe weather events.
EPA Energy Star roof specifications and local amendments to the International Energy Conservation Code shape product qualification requirements for reflectivity and thermal emittance. The Inflation Reduction Act's residential clean energy credits create direct demand pull for cool-roof and solar-ready assemblies, while OSHA fall-protection standards govern contractor labor costs and project scheduling. Stakeholders must monitor evolving municipal net-zero building ordinances and insurance-industry resilience scoring that will progressively favor impact-resistant and fire-rated roof assemblies over conventional commodity products.
Market Dynamics
Residential replacement cycles are compressing across the Sun Belt as stricter energy codes and storm-resilience mandates force homeowners toward higher-performance assemblies. The Inflation Reduction Act's tax credits have redirected contractor investment toward reflective membranes and solar-integrated systems, reshaping material procurement patterns.
Growth Catalysts
- Inflation Reduction Act tax credits:Direct financial incentives for cool-roof and solar-ready installations are accelerating contractor retraining and inventory shifts toward reflective assemblies in southern states.
- Florida and Texas storm-resilience mandates:Insurance industry pressure and building code amendments are forcing replacement of conventional shingles with impact-resistant systems in hurricane-exposed counties.
- TPO membrane welding advances:Automated seaming technology is reducing commercial flat-roof installation labor hours and extending warranty eligibility for thermoplastic assemblies.
Market Restraints
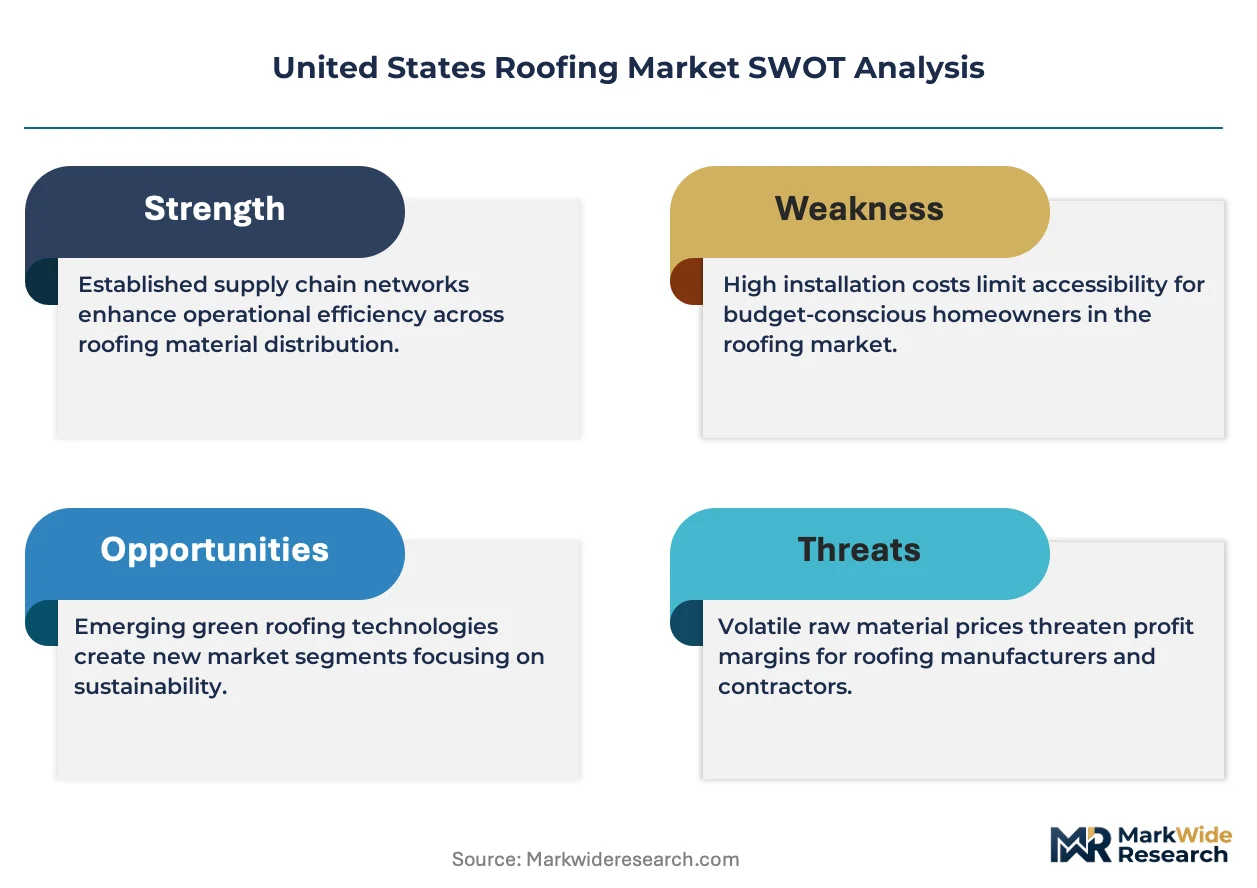
- Asphalt binder cost volatility:Petroleum-derived feedstock fluctuations compress margins for fiberglass shingle manufacturers and complicate project bidding timelines.
- Western states supply concentration:Cementitious tile and clay roofing production clusters in California and Arizona create freight cost penalties for Rocky Mountain and Pacific Northwest contractors.
- International Energy Conservation Code adoption friction:Local amendment processes delay cool-roof reflectivity requirements in municipalities with limited inspector training capacity.
Strategic Opportunities
- Mountain West underpenetration:Metal roofing's share in Colorado and Utah remains below Sun Belt levels despite comparable hail exposure and wildfire risk profiles.
- Solar-integrated assembly convergence:Building-integrated photovoltaics combined with reflective substrates are creating new product categories for net-zero residential retrofits in California.
- Direct-to-contractor digital platforms:E-procurement channels are disintermediating traditional distributor markups for mid-size roofing fleets in Texas and Florida.
Industry Challenges
- Cool-roof installer certification bottlenecks:Manufacturer warranty programs require specialized training that outpaces vocational program capacity in high-growth southern markets.
- Legacy ERP integration complexity:Contractor software migration to cloud-based estimation and permitting tools faces resistance from family-owned operations with decades of historical data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Roofing Market |
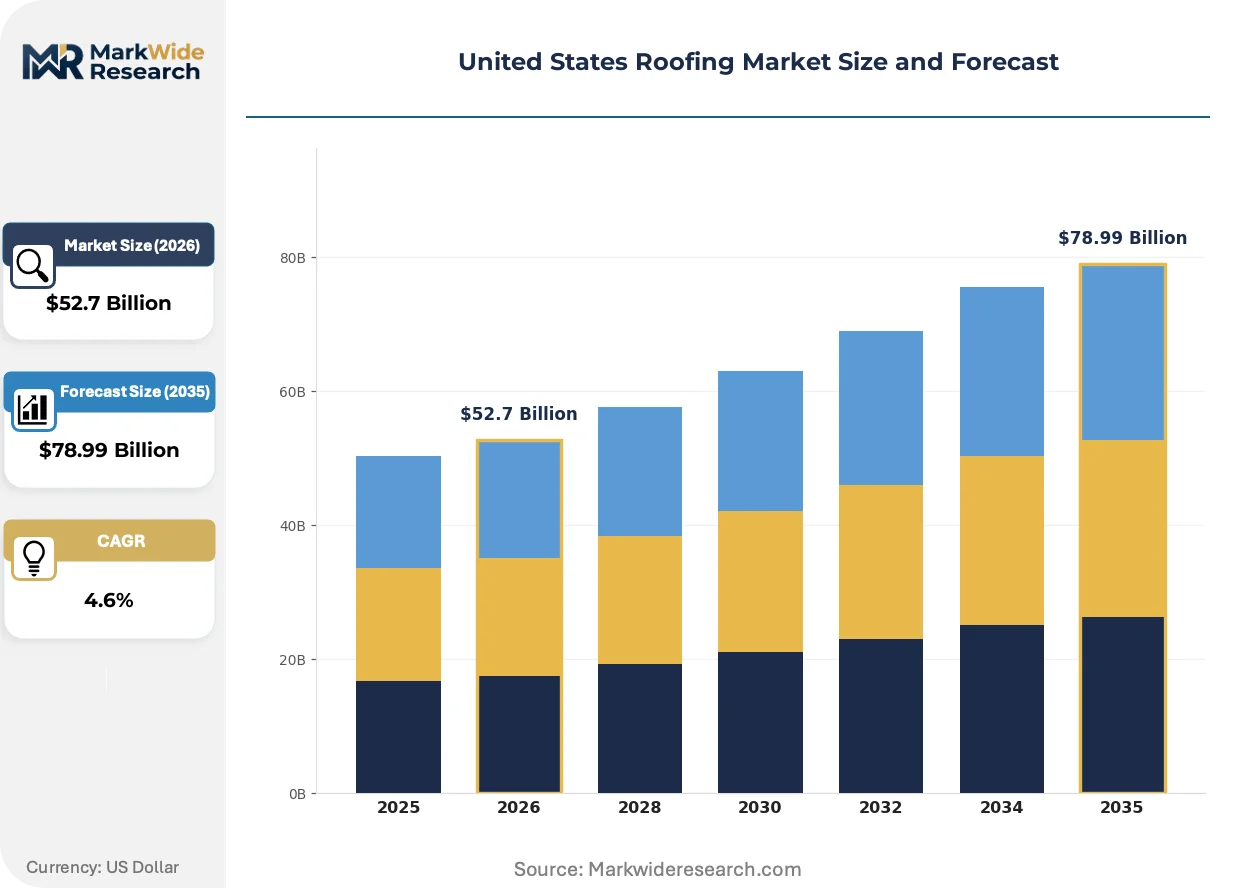
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $78.99 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shingles, Tiles, Metal Roofing, Membranes End User: Residential, Commercial, Industrial, Institutional Installation Type: New Construction, Replacement, Repair, Renovation Material: Asphalt, Wood, Slate, PVC |
| Companies Covered | Tecta America, CentiMark Corporation, GAF Materials Corporation, Owens Corning, CertainTeed Corporation, TAMKO Building Products, Cornerstone Building Brands, Carlisle SynTec Systems, IKO Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Roofing Market Trends and Innovations
Material science advances and regulatory pressure are converging to reshape product specifications and installation methods. Three developments are altering competitive positioning across residential and commercial segments.
Solar-reflective granule technology is migrating from niche commercial membranes toward residential asphalt shingles. Owens Corning and GAF are embedding ceramic-coated minerals into fiberglass mats to achieve Energy Star reflectivity thresholds without aesthetic compromise. Southern California and Arizona contractors report accelerating specification of these assemblies as default options rather than upgrades.
EPA Energy Star roof specifications are tightening thermal emittance requirements for low-slope commercial applications. The updated testing protocols disqualify older single-ply formulations and force reformulation of TPO and PVC compounds. Texas and Florida commercial roofing contractors are pre-qualifying replacement membranes against the 2024 criteria to avoid project delays.
Insurance-driven procurement is compressing contractor selection cycles in catastrophe-prone counties. Homeowners in Florida and the Gulf Coast are bypassing traditional three-bid processes in favor of pre-approved vendor networks with demonstrated claims support capacity. This behavior concentrates volume among carriers with established adjuster relationships and certified installation documentation systems.
United States Roofing Market Segmentation
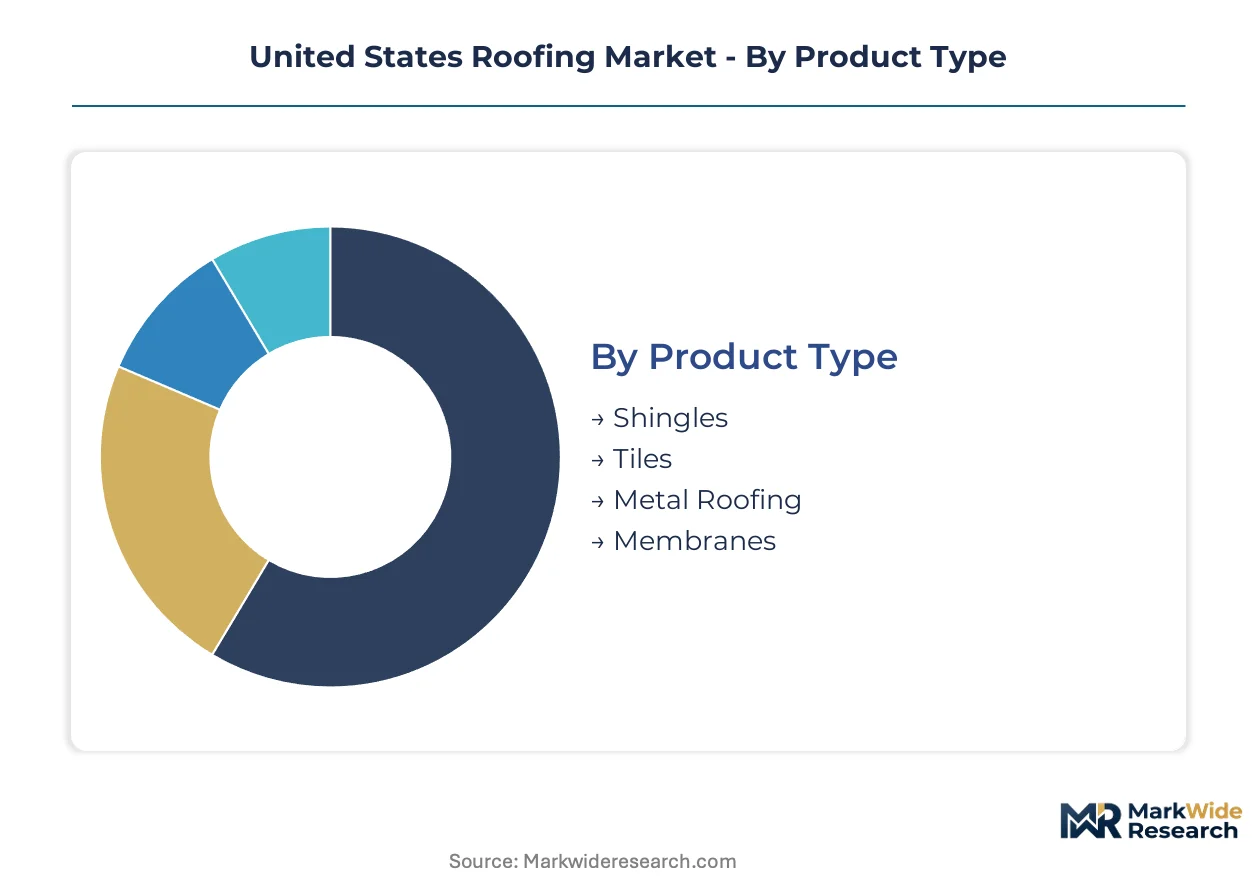
Segmentation in the United States roofing market reveals distinct capital intensity and replacement cadence patterns. Contractors align inventory and labor specialization to the turnover velocity of each segment, from rapid-cycle residential repairs to decade-spanning commercial membrane installations.
Product Type:
Replacement intervals vary dramatically by material durability and climate exposure, creating tiered service-life economics for contractors and distributors.
- Shingles:Fiberglass-reinforced asphalt assemblies dominate residential replacement volume with 20-30 year service ratings. Texas and Florida contractors face compressed cycles as storm-resilience mandates accelerate tear-offs of conventional three-tab products.
- Metal Roofing:Standing-seam and metal-shingle systems achieve 40-70 year durability with Class 4 hail ratings. Colorado and Utah installers report underpenetration relative to Sun Belt adoption despite comparable weather exposure.
- Tiles:Clay and concrete products concentrate in California and Arizona production clusters, creating freight penalties for Rocky Mountain contractors.
- Membranes:TPO and PVC single-ply systems anchor commercial flat-roof specifications with thermoplastic welding standards.
Shingles anchors the volume base while metal roofing gains share at the steepest rate.
End User:
Customer procurement sophistication spans insurance-driven urgency at the residential level to extended capital planning cycles in institutional portfolios.
- Residential:Single-family and multi-family owners respond to catastrophic weather events with compressed vendor selection timelines. Gulf Coast carriers pre-approve contractor networks with certified documentation systems.
- Commercial:Property managers and REITs execute membrane replacements on 15-25 year depreciation schedules with Energy Star compliance requirements.
- Industrial:Manufacturing facilities prioritize uptime protection with metal panel systems and rapid-installation assemblies.
- Institutional:School districts and municipal buildings navigate public procurement processes with extended bid cycles and prevailing wage requirements.
Residential commands the largest project count while commercial delivers the highest average contract values.
Installation Type:
Work mix determines contractor labor allocation between new-construction crews and specialized tear-off teams.
- New Construction:Production homebuilders in Sun Belt states specify builder-grade shingles with 110 mph wind ratings for volume efficiency.
- Replacement:End-of-service-life tear-offs generate the majority of contractor revenue as housing stock ages across the Midwest and Northeast.
- Repair:Storm-damage patching requires rapid-response capacity and adjuster coordination in catastrophe-prone counties.
- Renovation:Energy-code upgrades and solar-ready retrofits concentrate in California municipalities with net-zero ordinances.
Replacement work sustains baseline contractor revenue while renovation projects expand most quickly under IRA incentive programs.
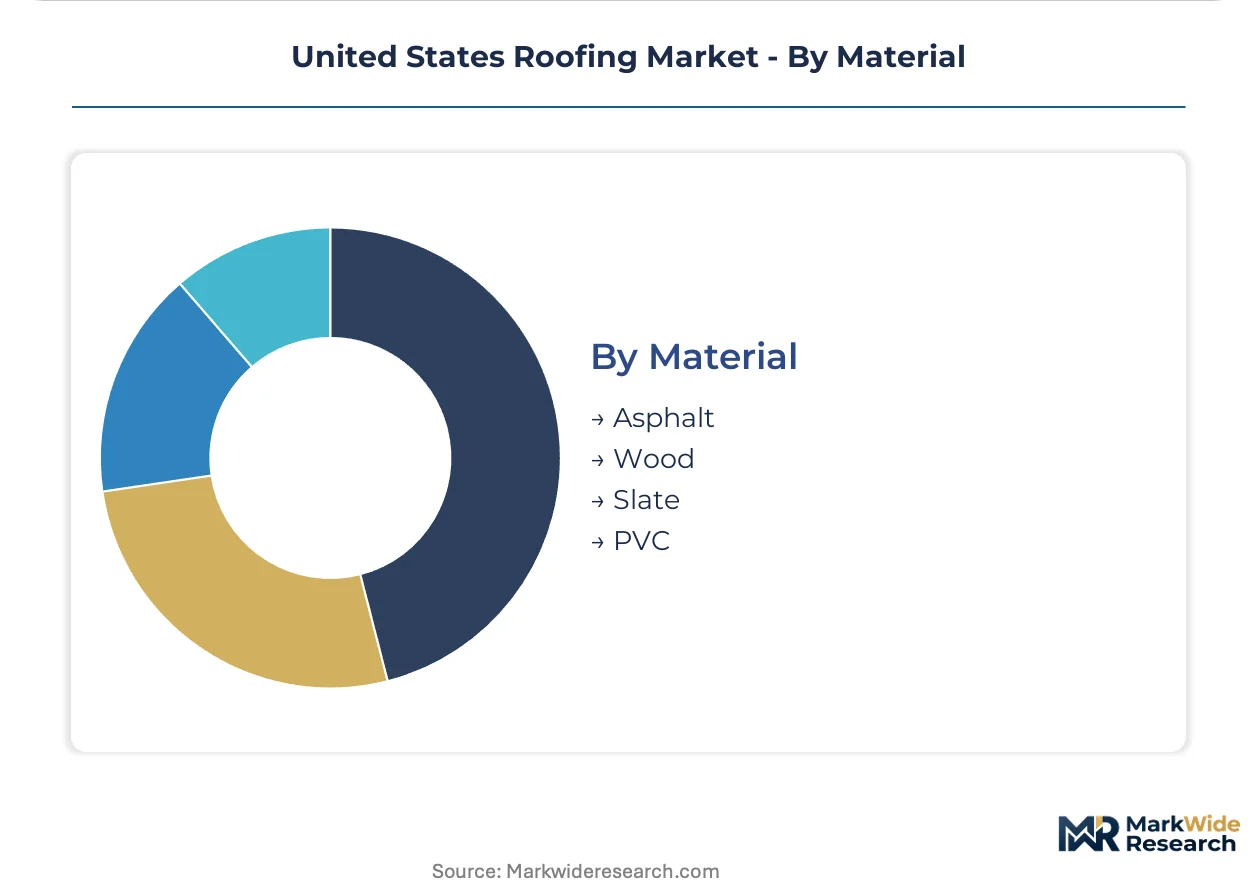
Material:
Feedstock cost structures and regional availability shape specification patterns from petroleum-derived binders to mineral-based alternatives.
- Asphalt:Petroleum-derived fiberglass shingles retain installer familiarity and supply-chain ubiquity despite binder price volatility.
- Wood:Cedar shakes and shingles concentrate in Pacific Northwest markets with moisture-resistant species specifications.
- Slate:Natural stone products serve historic preservation and premium residential segments with century-scale durability.
- PVC:Chlorinated membranes deliver chemical resistance and extended warranties for commercial applications with aggressive effluent exposure.
Asphalt materials dominate tonnage while PVC compounds capture premium commercial specification share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian membrane manufacturers export thermoplastic roofing systems to northern-tier U.S. states, while Mexican clay tile producers supply southwestern border markets. Regional demand patterns track climate exposure, energy code stringency, and insurance market dynamics.
California
Net-zero building ordinances in Los Angeles and San Francisco accelerate cool-roof retrofits on commercial flat roofs. Title 24 energy standards mandate solar-ready construction for new residential developments. Sacramento-area distributors stock reflective membrane inventory for Central Valley agricultural processing facilities.
Texas
Hail-driven metal roofing demand concentrates in Dallas-Fort Worth and Houston metro corridors. Windstorm insurance requirements under the Texas Department of Insurance shape impact-resistant shingle specifications in coastal counties. San Antonio contractors report rapid-response capacity shortages following spring storm seasons.
Florida
Hurricane exposure compresses asphalt shingle replacement intervals to 12-15 years in Miami-Dade and Broward counties. Florida Building Code Chapter 15 mandates high-velocity hurricane zone ratings for all roofing assemblies. Tampa Bay fabricators specialize in tile-to-metal conversion projects for waterfront properties.
Colorado
Wildfire-risk mapping by the Colorado Division of Fire Prevention drives Class A fire-rated assembly specifications in mountain counties. Front Range contractors underpenetrate the metal roofing segment relative to comparable hail exposure in Texas. Denver distributors maintain surge inventory for Front Range hail events.
Pacific Northwest
Moisture-resistant cedar shake specifications concentrate in Seattle and Portland residential markets. Oregon energy trust incentives support cool-roof membrane installations on municipal buildings in Eugene and Salem. Spokane contractors source composite shake alternatives from Idaho manufacturing clusters.
United States Roofing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct tier positions. The vendor base organizes around national manufacturing footprints, regional installation networks, and specialty membrane technology. Three archetypes dominate: integrated building-materials conglomerates with captive distribution, pure-play roofing manufacturers with contractor-direct programs, and commercial-membrane specialists with specification-engineering capabilities. Competitive moves center on backward integration into raw material supply and certification program expansion to lock contractor loyalty.
Within the integrated-materials tier, GAF Materials Corporation, Owens Corning, and CertainTeed Corporation exemplify scale-driven positioning. GAF occupies a channel-controlling position through national manufacturing density. Owens Corning represents fiberglass mat technology specialization. CertainTeed anchors specialty-accessory depth and color-matching systems that reduce field waste for contractor networks.
| Leading Market Players |
|---|
| Tecta America |
| CentiMark Corporation |
| GAF Materials Corporation |
| Owens Corning |
| CertainTeed Corporation |
| TAMKO Building Products |
| Cornerstone Building Brands |
| Carlisle SynTec Systems |
| IKO Industries |
| Others |
Pricing and Supply Chain Analysis
Petroleum-derived asphalt binder volatility compresses margin spreads between economy-grade three-tab shingles and premium impact-rated systems while simultaneously forcing distributors toward regional inventory pre-positioning strategies that fragment procurement economics across climate zones.
Pricing Analysis
The performance-tier pricing gap separates prior-generation three-tab fiberglass shingles from current-generation architectural laminates and emerging solar-integrated assemblies. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and wind-speed rating, with Class 4 impact resistance commanding substantial premiums in Florida and Texas coastal counties. Cost compression in the economy tier is intensifying because petroleum feedstock fluctuations outpace contractor pass-through capacity. Residential repair customers show highest price sensitivity, while commercial REITs prioritize warranty length over unit cost.
Supply Chain Analysis
Upstream petroleum refining and fiberglass mat production concentrate in Texas, Louisiana, and Ohio manufacturing corridors. Raw material procurement draws from crude oil derivatives, limestone filler, and ceramic granule feedstocks. Single-source vulnerability persists in specialty membrane polymer supply, where chlorinated PVC compounds face limited domestic formulation capacity. Distribution runs through manufacturer-branded distribution centers, independent two-step distributors, and emerging direct-to-contractor digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as Inflation Reduction Act tax credits redirect contractor investment toward solar-ready and cool-roof assemblies that were previously niche specifications.
For Market Incumbents: Entrench channel control through captive distribution investments in high-growth Sun Belt metros and accelerated certification program expansion to lock contractor loyalty against emerging direct-procurement platforms. Backward integration into reflective granule supply secures margin position as Energy Star requirements tighten. Prioritize TPO membrane welding technology licensing to capture commercial flat-roof specification share. For New Entrants and Emerging Players: Pursue Mountain West metal roofing penetration where Colorado and Utah adoption lags comparable hail exposure in Texas despite comparable weather risk profiles. Target solar-integrated assembly convergence in California net-zero retrofit markets where incumbent bundling remains incomplete. Lead with digital estimation and permitting tools that bypass legacy ERP resistance among family-owned contractor operations. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors membrane specialists with specification-engineering capabilities and solar-integration partnerships over pure-play shingle manufacturers. Long-term viability across the analysis window hinges on regulatory credit durability and insurance-industry resilience scoring adoption. Watch municipal net-zero ordinance proliferation as the inflection indicator for cool-roof demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cool-Roof Certification Program Expansion | Locks contractor loyalty through IRA-compliant installation training and warranty eligibility in southern states. |
| Solar-Integrated Assembly Partnership | Captures building-photovoltaic convergence demand in California Title 24 compliance markets. |
| Direct-to-Contractor Digital Platform Launch | Disintermediates traditional distributor markups for mid-size Texas and Florida roofing fleets. |
| Membrane Welding Technology Licensing | Reduces commercial installation labor hours and extends TPO warranty eligibility for thermoplastic assemblies. |
| Mountain West Distribution Capacity Addition | Addresses metal roofing underpenetration in Colorado and Utah hail-exposed counties. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with residential roofing contractors, commercial property managers, distributor procurement leads, and manufacturer specification engineers. Secondary validation drew from EPA Energy Star certification databases, OSHA incident reporting systems, state building code amendment filings, and insurance industry claims data. Bottom-up project pipeline analysis triangulated against top-down construction spending trends.
Calibration against historical replacement cycle data and regulatory implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user category, installation type, and material feedstock, with additional granularity on climate-zone exposure and energy code stringency. CAGRs were derived from replacement interval compression rates and incentive program uptake curves, incorporating storm-frequency indices and municipal ordinance adoption patterns as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in petroleum price trajectories, mortgage rate environments, or federal tax credit continuity would shift the trajectory. Forecasts reflect documented assumptions on contractor training capacity expansion and insurance carrier pre-approval network formation. Cross-checking against regional construction permit issuance data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Ultra High Performance Concrete (UHPC) Market
Building & Construction Materials
Fiberboard Ceiling Market
Building & Construction Materials
Waterproofing Solution Market
Building & Construction Materials
North America Concrete Sealer Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Europe Particle Board Market
Building & Construction Materials
Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Concrete Protective Liners Market
Building & Construction Materials
Door System Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
Wood Truss Market
Building & Construction Materials
Structural Insulated Panels (Sips) Market
Building & Construction Materials
Precast Concrete Market
Building & Construction Materials
North Africa Cement Market
Building & Construction Materials
Steel Bolts and Nuts Market