
 Saudi Arabia Concealed Cistern Market | 2026-2036
Saudi Arabia Concealed Cistern Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Concealed Cistern Market Insights
A shift from single-source procurement to multi-source vendor panels is realigning supply chain resilience among Saudi contractors. TOTO leverages its ceramic manufacturing depth to dominate premium hospitality specifications. Kohler sustains brand pull through dedicated showrooms in Riyadh and Jeddah. RAK Ceramics anchors its position via regional production proximity and aggressive distributor incentives.
A concealed cistern is a water reservoir embedded within wall cavities or furniture units, typically constructed from high-density polyethylene or ceramic composites, designed to supply flush water to wall-hung toilets while maximizing usable floor space. Dual flush mechanisms lead volume due to SASO water efficiency mandates, while low-noise variants command margin premiums in hospitality and high-end residential towers. Wall-mounted installation types are outpacing floor-mounted alternatives as developers prioritize space optimization in compact urban units across Riyadh and Dammam.
SASO (Saudi Standards, Metrology and Quality Organization) enforces mandatory water consumption limits that directly shape product certification requirements for concealed cisterns entering the Kingdom. The Saudi Building Code and Ministry of Municipal and Rural Affairs specifications further dictate installation standards and material compatibility for commercial and institutional projects. Stakeholders must monitor evolving efficiency thresholds and localization incentives as the market tilts toward in-country value-add manufacturing.
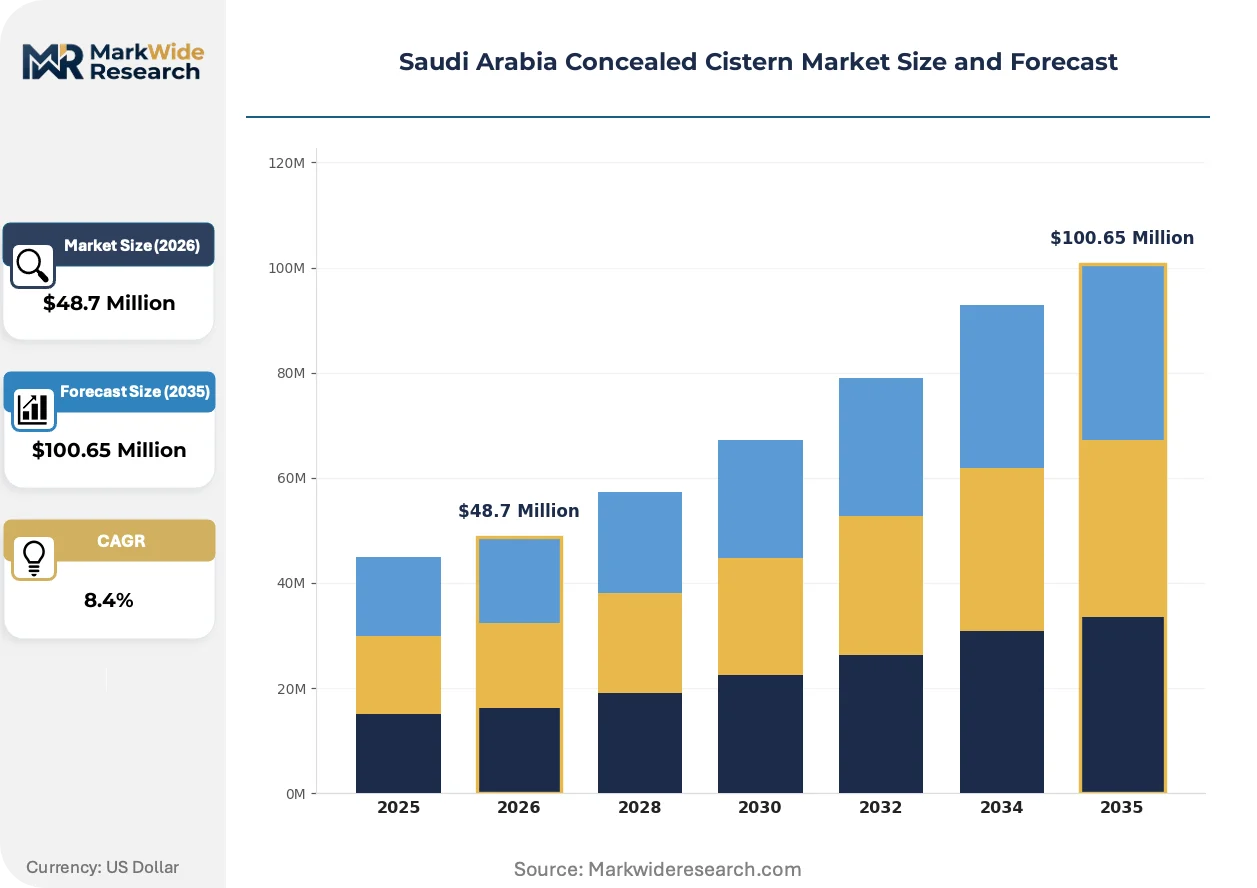
Market Dynamics
SASO water efficiency mandates are compressing flush-volume thresholds while Riyadh's luxury hospitality pipeline pulls specification-grade concealed cisterns into high-rise developments. This regulatory-demand tension is restructuring procurement patterns across Saudi contractors.
Growth Catalysts
- SASO Efficiency Mandates:The Saudi Standards, Metrology and Quality Organization enforces dual-flush requirements that accelerate replacement cycles in commercial buildings.
- Luxury Hospitality Pipeline:Riyadh and Jeddah hotel developments specify wall-mounted installations to maximize floor space in premium guest bathrooms.
- Central Region Urban Density:The Riyadh metro corridor concentrates residential tower construction where space-optimized plumbing fixtures command priority placement.
Market Restraints
- High-Density Polyethylene Price Volatility:Resin input costs fluctuate with petrochemical feedstock markets, squeezing margin stability for cistern manufacturers serving price-sensitive mid-market segments.
- Installation Skill Concentration:Qualified contractors capable of cavity-wall embedding remain concentrated in Riyadh and Jeddah, limiting deployment velocity in secondary cities.
- Ceramic Composite Substitution:Traditional exposed cisterns retain cost advantage in budget residential developments outside major metropolitan zones.
Strategic Opportunities
- Eastern Province Industrial Zones:Dammam and Khobar commercial complexes present underpenetrated demand for low-noise variants in high-density office towers.
- In-Country Value Manufacturing:Saudi Industrial Development Fund incentives support localized production of polyethylene cistern components to replace imported assemblies.
- Smart Flush Integration:Sensor-activated mechanisms converging with building management systems create specification openings in premium hospitality and healthcare verticals.
Industry Challenges
- Certification Timeline Compression:SASO product approval processes create lag between design finalization and site delivery, complicating just-in-time construction schedules.
- Legacy Infrastructure Compatibility:Retrofit installations in existing Riyadh residential stock require structural wall modifications that extend project timelines and labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Concealed Cistern Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $100.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual Flush, Single Flush, Low-Noise, High-Efficiency End User: Residential, Commercial, Hospitality, Institutions Installation Type: Wall-Mounted, Floor-Mounted, Pre-Installation, Retrofit Material: Ceramic, Plastic, Stainless Steel, Others |
| Companies Covered | TOTO, Kohler, Roca, Lixil, Fluidmaster, RAK Ceramics, Grohe, Cera, Duravit, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Concealed Cistern Market Trends and Innovations
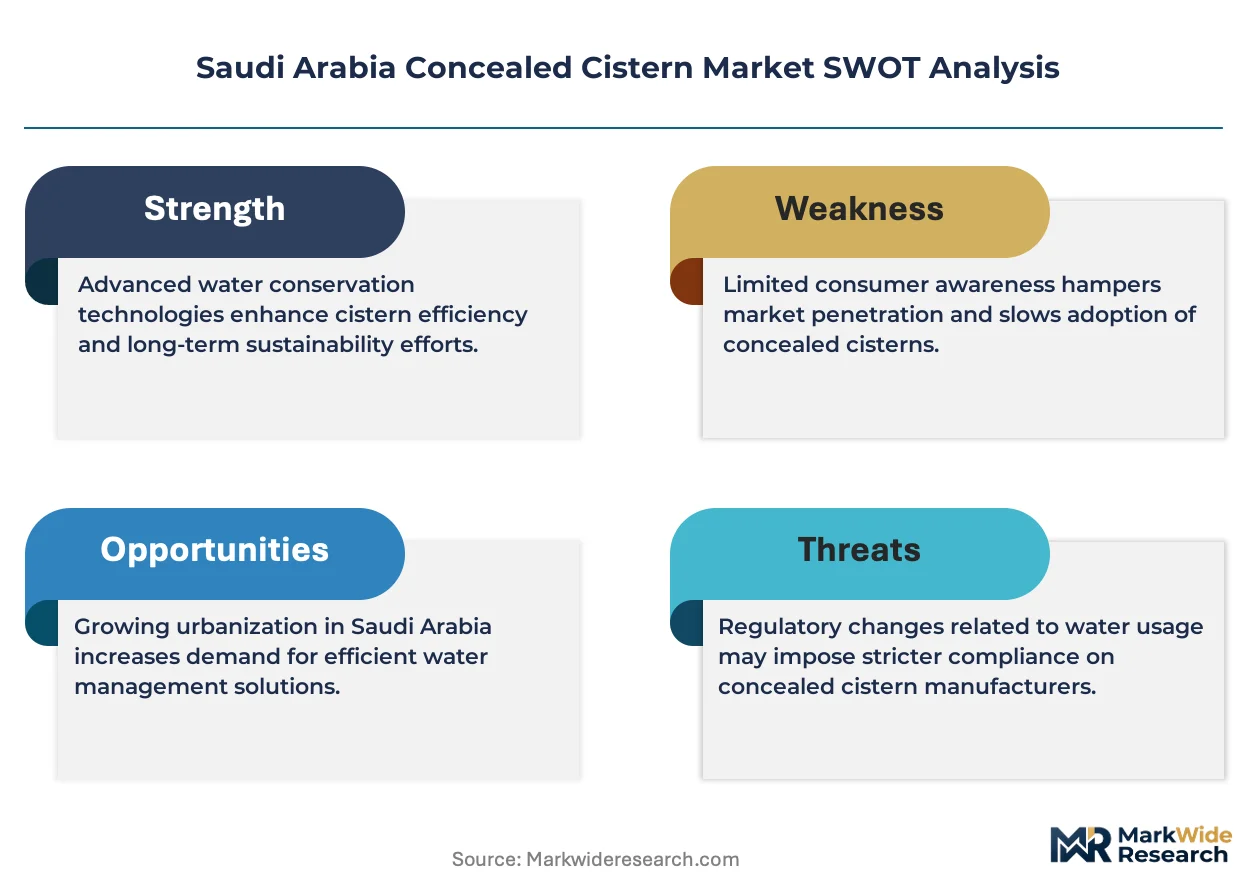
Material science advances and regulatory tightening are reshaping concealed cistern specifications across Saudi commercial and residential construction. Three developments are actively reconfiguring competitive positioning.
Low-noise ceramic composite cisterns are expanding into high-end residential towers across Riyadh's northern districts. Developers of premium apartment complexes specify these units to meet acoustic comfort standards in dense urban configurations. The technology is compressing demand for conventional polyethylene alternatives in segments where noise mitigation commands price premiums.
SASO's progressive water consumption limits are forcing manufacturers to redesign internal valve mechanisms ahead of each compliance deadline. The Saudi Building Code's tightening flush-volume thresholds require engineering investment that smaller regional suppliers struggle to fund. Commercial hospitality projects in Jeddah's waterfront district are responding earliest, embedding pre-certified dual-flush systems to avoid construction-phase regulatory delays.
Multi-source vendor panels are displacing single-supplier procurement contracts among major Saudi contractors. Project developers now segment cistern specifications across premium, standard, and economy tiers to mitigate supply concentration risk. This pattern is most visible in Riyadh's metro-adjacent mixed-use developments, where general contractors rotate polyethylene and ceramic suppliers by building phase to maintain installation continuity.
Saudi Arabia Concealed Cistern Market Segmentation
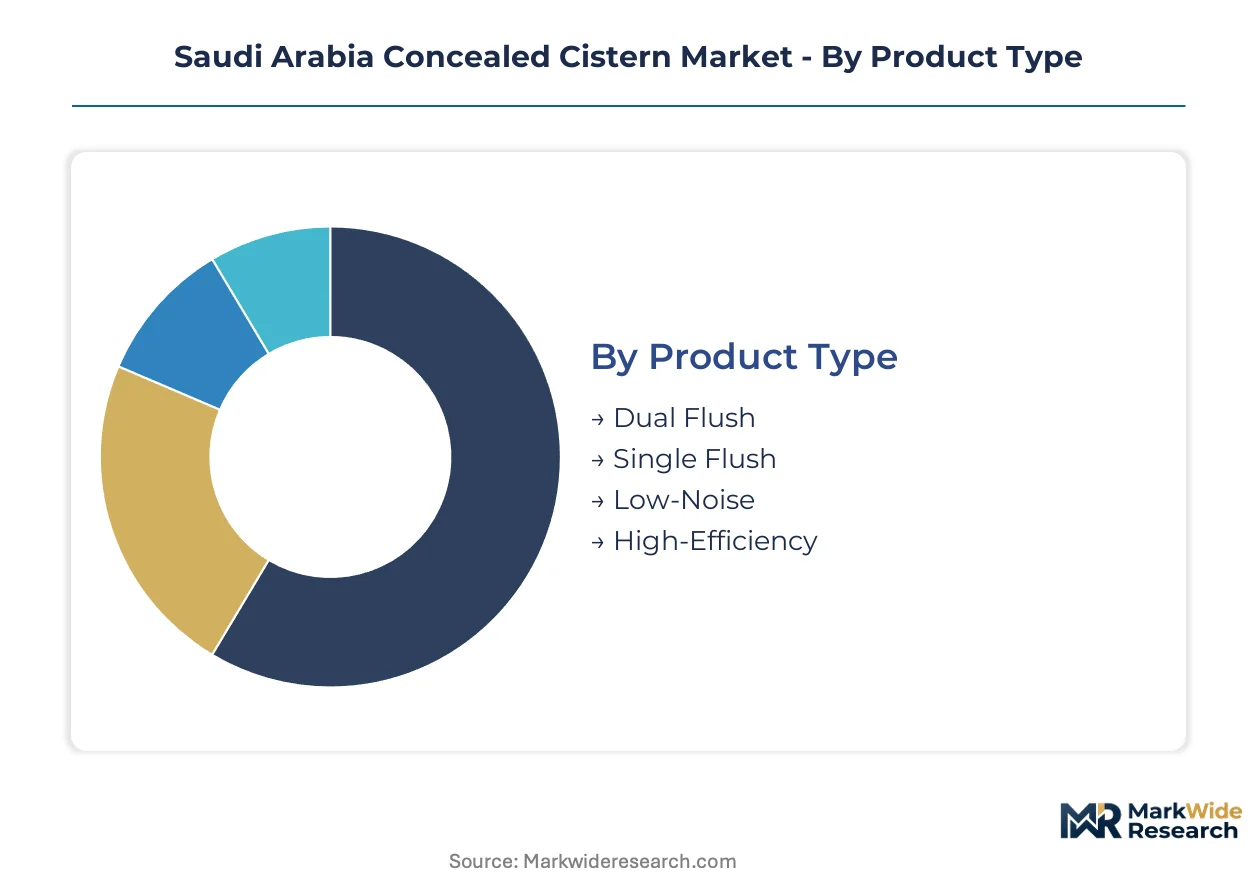
Segmentation in Saudi Arabia's concealed cistern market reveals how SASO mandates and Riyadh's construction density pull demand toward specific technical configurations. Procurement patterns diver sharply between hospitality-driven premium specifications and residential volume plays.
Product Type:
Volume concentrates in dual-flush mechanisms while premium margins attach to acoustic performance variants.
- Dual Flush:Two-stage valve systems deliver 3-liter and 6-liter flush options through a single actuator plate. Riyadh's commercial tower developments specify these units to preempt SASO compliance deadlines in bulk procurement contracts.
- Low-Noise:Ceramic composite construction with insulated fill valves reduces operational decibel levels below 20 dB. Jeddah's waterfront luxury hotels command these specifications to meet guest comfort standards in dense floor plans.
- Single Flush:Fixed-volume mechanisms dominate budget residential retrofits in secondary cities where contractor familiarity lags.
- High-Efficiency:Sub-3-liter flush volumes using pressure-assisted technology target healthcare and institutional verticals with intensive usage cycles.
Mature deployment sits with dual-flush variants. Newer deployment is concentrated in low-noise specifications.
End User:
Customer type determines specification grade more than geography, with hospitality projects driving the steepest margin expansion.
- Commercial:Office towers across Riyadh's King Abdullah Financial District prioritize space optimization through wall-mounted configurations with dual-flush certification.
- Hospitality:Premium hotel developments specify low-noise ceramic cisterns with integrated sensor activation for guest bathroom installations.
- Residential:Compact urban apartments in Dammam and Khobar favor polyethylene wall-mounted units for cost-efficient space recovery.
- Institutions:Schools and healthcare facilities require vandal-resistant actuator plates with high-cycle durability ratings.
Commercial segment anchors current procurement volume. Hospitality applications are expanding most quickly.
Installation Type:
Pre-installation timing separates new construction from replacement demand, with retrofit complexity limiting secondary city penetration.
- Wall-Mounted:Cavity-embedded frames support suspended toilet bowls, maximizing floor space in Riyadh's high-rise residential towers.
- Pre-Installation:Builder-rough frames installed during concrete pouring dominate metro-corridor developments with accelerated construction schedules.
- Floor-Mounted:Conventional exposed-cistern alternatives retain share in budget residential projects outside major metropolitan zones.
- Retrofit:Structural wall modifications for existing Riyadh housing stock extend project timelines and concentrate qualified contractor demand.
Pre-installation dominates new construction pipelines. Retrofit applications face the steepest contractor scarcity constraints.
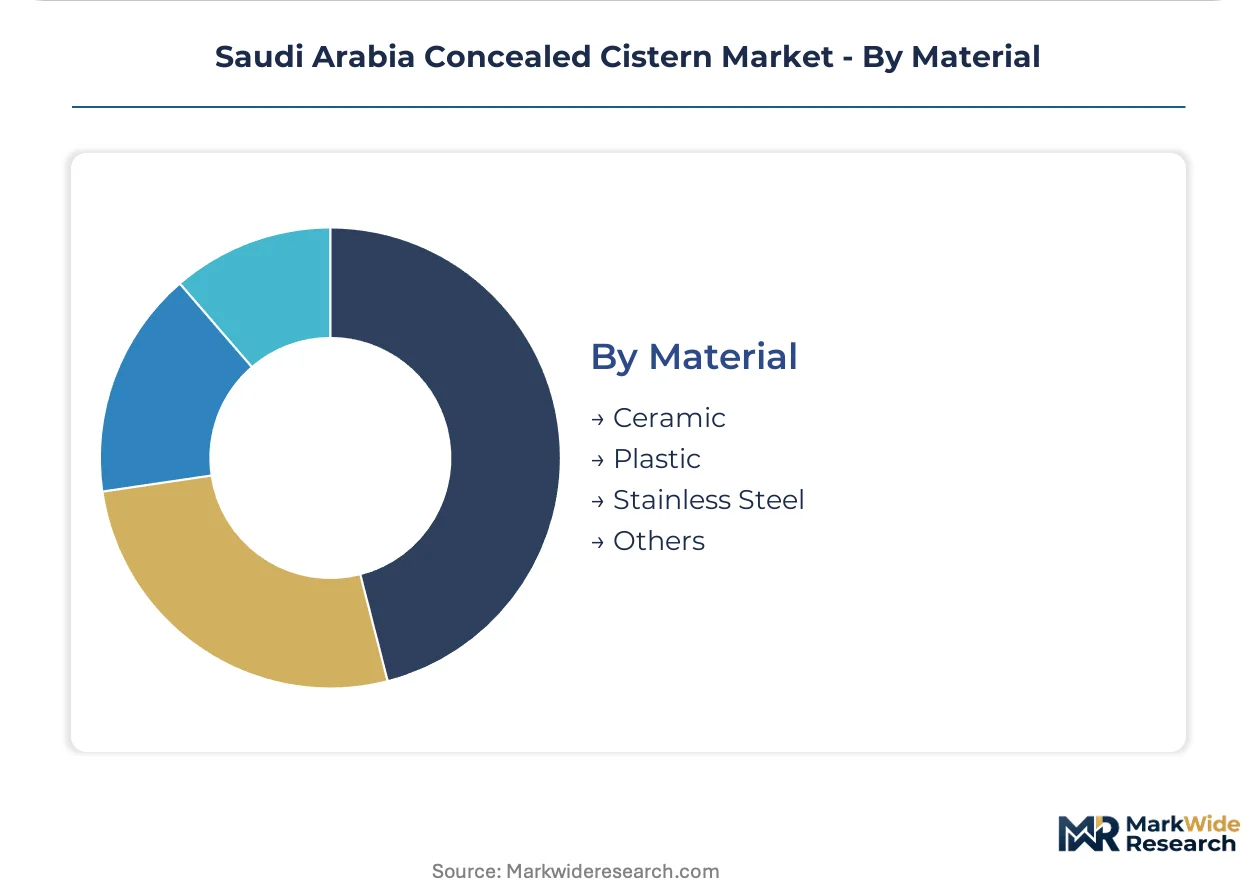
Material:
Material selection tracks price tier and acoustic requirements, with ceramic commanding hospitality specifications and polyethylene anchoring volume residential.
- Ceramic:Fired clay composite construction delivers acoustic dampening and premium aesthetic compatibility with designer actuator plates.
- Plastic:High-density polyethylene rotational-molded tanks serve cost-optimized residential and standard commercial installations.
- Stainless Steel:Welded 304-grade reservoirs target institutional applications requiring maximum durability and vandal resistance.
- Others:Glass-reinforced polymer and concrete composite variants address niche structural load-bearing requirements in specialized commercial builds.
Plastic variants anchor residential volume deployment. Ceramic materials are gaining share fastest in premium hospitality specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in the Eastern Province anchors Saudi Arabia's concealed cistern manufacturing base. Riyadh's construction density pulls finished product demand northward, creating a domestic supply-demand corridor.
Riyadh
Luxury hotel developments and metro-corridor residential towers drive wall-mounted cistern specifications. SASO water efficiency mandates accelerate dual-flush adoption in commercial towers. King Abdullah Financial District concentrates office construction where space-optimized plumbing fixtures command priority.
Eastern Province
Dammam and Khobar commercial complexes generate underpenetrated demand for low-noise variants in high-density office towers. Saudi Industrial Development Fund incentives support localized polyethylene component manufacturing. Jubail petrochemical clusters supply high-density polyethylene feedstock for rotational-molded tank production.
Western Region
Jeddah's waterfront luxury hotels specify ceramic composite cisterns with acoustic dampening below 20 dB. The Saudi Building Code's installation standards tighten material compatibility requirements for coastal humidity exposure. Makkah hospitality infrastructure commands vandal-resistant actuator plates for high-cycle durability.
NEOM Northwest
Giga-project construction embeds smart flush integration with building management systems from foundation phase. Ministry of Municipal and Rural Affairs specifications for sustainable cities mandate sub-3-liter flush volumes. Trojena and The Line developments pre-install cavity-wall frames during concrete pouring.
Saudi Arabia Concealed Cistern Market Competitive Landscape
Global majors compete with regional champions across specification-grade versus volume-market positioning. The vendor base stratifies into three tiers: premium ceramic specialists, mid-market polyethylene fabricators, and budget exposed-cistern alternatives. Two strategic archetypes dominate: hospitality-focused specification houses leveraging showroom networks, and petrochemical-integrated manufacturers optimizing resin input costs. Competitive moves center on distributor incentive expansion and in-country value manufacturing partnerships.
Among Japanese-origin specification leaders, TOTO and Lixil exemplify the premium ceramic archetype through manufacturing depth and acoustic engineering capabilities. RAK Ceramics anchors the regional proximity advantage with UAE-based production serving Saudi contractor panels. Kohler sustains brand pull through dedicated Riyadh and Jeddah showrooms that influence architect specifications. These three represent distinct competitive vectors: acoustic performance engineering, regional logistics optimization, and direct-to-specifier marketing investment.
| Leading Market Players |
|---|
| TOTO |
| Kohler |
| Roca |
| Lixil |
| Fluidmaster |
| RAK Ceramics |
| Grohe |
| Cera |
| Duravit |
| Others |
Pricing and Supply Chain Analysis
SASO water efficiency mandates gate both qualified supply and premium-tier pricing access by restricting certification to manufacturers with proven dual-flush engineering capabilities. This regulatory filter compresses margins for uncertified polyethylene fabricators while enabling ceramic specialists to command installation premiums in Riyadh hospitality specifications.
Pricing Analysis
Warranty bundling separates premium ceramic cisterns from unbundled polyethylene alternatives across Saudi contractor panels. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and acoustic performance tier. Pricing pressure stems from resin input cost volatility squeezing mid-market polyethylene suppliers. Budget residential developers in secondary cities exhibit highest price sensitivity, while luxury hospitality projects in Jeddah and Riyadh prioritize specification compliance over unit cost.
Supply Chain Analysis
Specialized cavity-wall installation crews concentrate in Riyadh and Jeddah, constraining deployment velocity in Dammam and Khobar. High-density polyethylene feedstock draws from Jubail petrochemical clusters, while ceramic composites source from UAE-based RAK Ceramics and Japanese manufacturing networks. Single-source vulnerability runs through qualified contractor scarcity outside major metropolitan zones. Distribution runs through dedicated distributor networks with showroom influence over architect specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's concealed cistern market operates as a vertical-integration race where captive control over polyethylene resin feedstock determines margin sustainability. Players are pursuing backward integration into rotational-molded tank production to offset import dependency and capture Saudi Industrial Development Fund incentives.
For Market Incumbents: Deploy certification investment as the primary defensive lever. Accelerate SASO pre-certification for next-generation sub-3-liter flush mechanisms ahead of regulatory deadlines. Deepen distributor incentive structures to lock out emerging polyethylene fabricators from Riyadh metro-corridor procurement panels. For New Entrants and Emerging Players: Launch via white-label supply to Eastern Province commercial developers underserved by established Riyadh-Jeddah installation networks. Target Dammam and Khobar office towers with low-noise variants where acoustic specifications remain unmet. Pursue direct contractor training partnerships to bypass qualified labor scarcity constraints. For Investors and Strategic Acquirers: SASO compliance deadline acceleration is the leading indicator that consolidation pressure will intensify among uncertified regional suppliers. Position for acquisition of polyethylene fabricators with latent certification capacity and established distributor relationships. Monitor Saudi Industrial Development Fund disbursement velocity as the signal for localized manufacturing viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Molding | Captive polyethylene production captures SIDF incentives and insulates margin from petrochemical feedstock volatility. |
| Certification Pre-Investment | Early SASO dual-flush approval secures specification lock-in for Riyadh hospitality pipeline ahead of compliance deadlines. |
| Contractor Training Academy | Qualified cavity-wall installation capacity expansion unlocks Eastern Province commercial penetration beyond Riyadh-Jeddah concentration. |
| Smart Flush Integration Partnership | Sensor-activated mechanism development opens NEOM and premium healthcare verticals with building management system convergence. |
| Multi-Source Vendor Panel Positioning | Tiered supplier segmentation by building phase maintains installation continuity for metro-corridor mixed-use developments. |
Research Methodology
Independent corroboration across distributor sales data, contractor procurement records, and regulatory filing documentation underwrites the qualitative findings in this analysis. Primary interviews with specification architects, commercial general contractors, hotel development procurement managers, and polyethylene manufacturing plant managers combined with secondary validation from SASO certification registries, Saudi Building Code amendments, and Ministry of Municipal and Rural Affairs project databases. Bottom-up unit deployment estimates triangulated against top-down construction pipeline valuations.
Rate-of-change decomposition across product type, end user, installation timing, and material composition segments enabled projection framework construction. Modeled dimensions included flush mechanism tier, customer specification grade, pre-installation versus retrofit timing, and regional construction density. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs incorporated Riyadh metro-corridor residential tower completion schedules and NEOM giga-project phase commitments.
Regulatory enforcement variance, petrochemical feedstock price disruption, and qualified contractor labor availability are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding SASO compliance timeline adherence and construction schedule execution. Material deviation in named triggers warrants pause and re-evaluation of segment-level growth trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
India Stainless Steel Plumbing Pipes and Fittings Market
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
Precast Concrete Members Market
Building & Construction Materials
Aluminum Curtain Wall Market
Building & Construction Materials
Concrete Formwork System Market
Building & Construction Materials
Vitrified Tiles Market
Building & Construction Materials
Russia Cross Laminated Timber Market
Building & Construction Materials
Vapor Barriers Market
Building & Construction Materials
Residential Elevator Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
Steep Slope Roofing Materials Market
Building & Construction Materials
Fiberboard Ceiling Market
Building & Construction Materials
North America Cross-Laminated Timber Market
Building & Construction Materials
EMEA Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Residential Energy Efficient Windows Market
Building & Construction Materials
Glazed Tiles Market