
 Global Prefab Wood Building Market | 2026-2036
Global Prefab Wood Building Market Size, Share, and Industry Trends Forecast 2026-2036
Global Prefab Wood Building Market Foresight
Performance-based maintenance contracts and digital twin subscriptions is repositioning how prefab wood building vendors capture lifetime value from each structure. Stora Enso leverages its integrated forest-to-factory ownership to control raw material quality and cost across Nordic and Central European supply zones. Binderholz GmbH anchors its competitive stance through massive-scale glulam and CLT production capacity serving German-speaking markets. Honkarakenne specializes in precision-engineered log homes for cold-climate residential segments, sustaining brand loyalty through decades of Arctic-region installations.
Prefab wood buildings are factory-manufactured structural enclosures assembled from engineered timber components such as cross-laminated timber panels rated for fire resistance and load-bearing spans exceeding fifteen meters, designed to reduce on-site construction duration and material waste versus conventional concrete or steel framing. Modular panels dominate volume production for multi-story residential and commercial applications where repeatability and transport logistics favor standardized dimensions. Cross-laminated timber technology leads growth in structural applications above four stories as fire engineering and acoustic performance certifications expand its addressable building height range. Structural insulated panels occupy a narrower but higher-margin niche in educational and recreational buildings where thermal envelope performance drives specification decisions.
The EU Green Deal and national building codes including Germany's EnEV thermal standards and Austria's Holzbau Austria certification framework mandate lower embodied carbon and higher energy efficiency, directly favoring timber-based prefabrication over mineral-intensive alternatives. REACH chemical compliance and CE marking requirements for structural timber products shape which adhesive systems and preservative treatments gain market access across European construction supply chains. Stakeholders must monitor evolving fire safety regulations for tall timber buildings and the pace at which automated fabrication equipment depreciates against labor cost differentials in key manufacturing clusters.
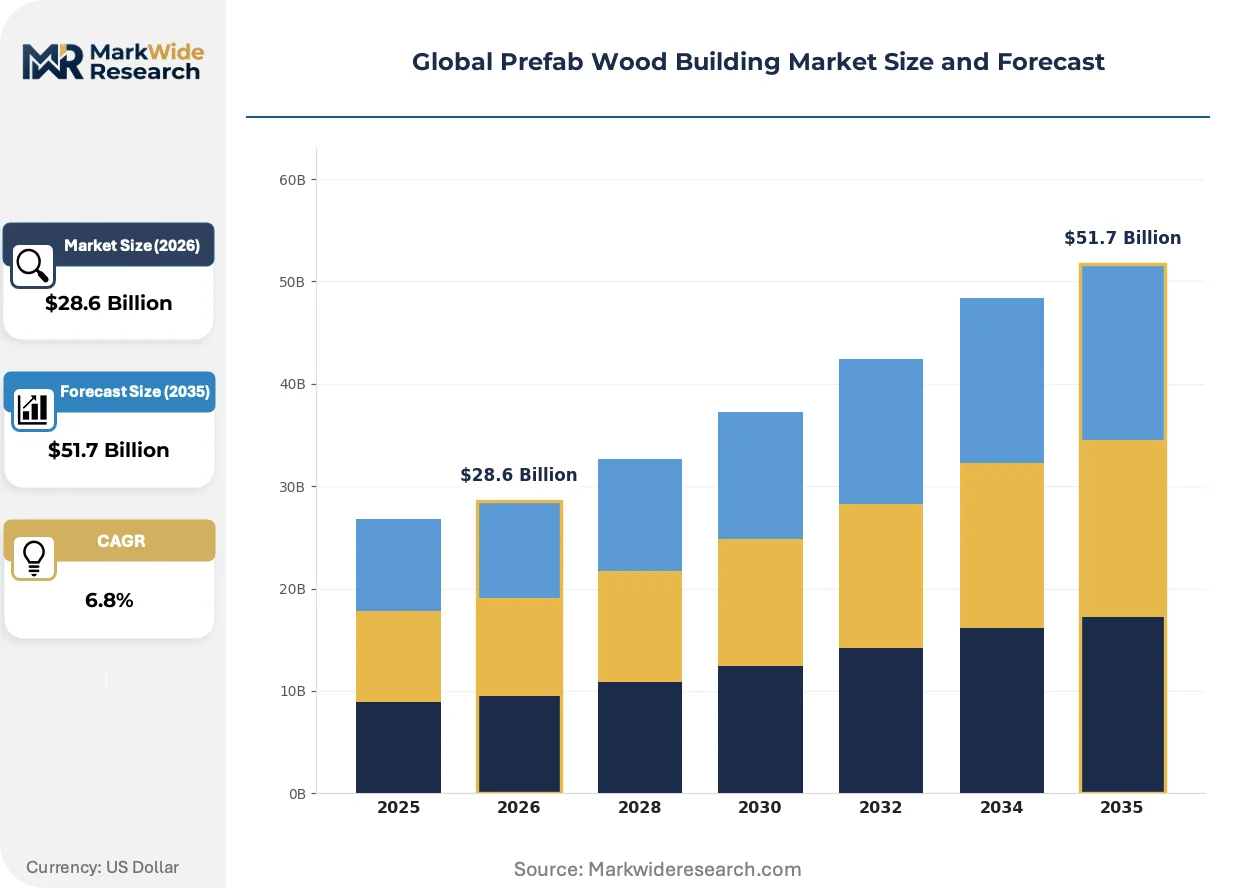
Market Dynamics
EU Green Deal carbon limits are forcing residential developers across Germany, Austria, and Scandinavia to abandon mineral-intensive framing in favor of factory-manufactured engineered timber systems with verified embodied carbon footprints.
Growth Catalysts
- EU Green Deal embodied carbon mandates:Binding 2030 reduction targets for new construction are disqualifying concrete and steel from public tenders across member states, redirecting procurement toward cross-laminated timber alternatives.
- Cross-laminated timber fire engineering advances:Extended load-bearing duration certifications above four stories are expanding addressable building height ranges for multi-story residential applications.
- Central European forestry-to-factory integration:Automated prefabrication facilities in Germany and Austria source raw material directly from managed Nordic and Alpine forest concessions, compressing lead times and quality variance.
Market Restraints
- Adhesive supply concentration:Structural timber manufacturing depends on polyurethane and melamine resin systems controlled by a narrow supplier base concentrated in German and Austrian chemical clusters.
- Transport radius economics:CLT panel dimensions and weight restrict profitable delivery to approximately 500-kilometer radii from fabrication facilities, constraining market reach from Central European production hubs.
- Site labor substitution limits:Foundation and utility connection work remains concrete-dependent, preventing full construction-cycle displacement by prefabricated timber superstructures.
Strategic Opportunities
- Japan cold-climate residential expansion:METI building efficiency standards and seismic engineering adaptations for engineered timber are opening specification opportunities in Hokkaido and northern Honshu prefectures.
- Performance-based maintenance subscriptions:Digital twin platforms tracking structural health and thermal envelope degradation enable recurring revenue capture from institutional building owners.
- US Inflation Reduction Act commercial tax credits:Section 179D deductions for energy-efficient construction are repositioning mass timber as a qualifying technology for office and educational building developers.
Industry Challenges
- Fire safety certification timelines:Extended approval cycles for tall timber buildings under evolving national building codes delay project financing and construction starts.
- Digital fabrication skill scarcity:CNC programming and automated panel assembly expertise remains concentrated among German-speaking technical institutes, constraining workforce scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Prefab Wood Building Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Panels, Prefabricated Frames, Wood Cladding, Structural Insulated Panels Application: Residential Housing, Commercial Complexes, Educational Facilities, Recreational Buildings Technology: Cross-Laminated Timber, Glue-Laminated Timber, Nail-Laminated Timber, Dowel-Laminated Timber End User: Construction Contractors, Real Estate Developers, Architecture Firms, Government Agencies |
| Companies Covered | Skyline Champion, Stora Enso, Binderholz GmbH, American Homestar, Southland Log Homes, Fertighaus Weiss, American Modular Systems, Honkarakenne, KLH Massivholz GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Prefab Wood Building Market Shifts & Advancements
Factory automation and regulatory carbon accounting are converging to compress production cycles and unlock specification in building categories previously reserved for mineral framing.
Robotic panel fabrication systems are automating cutting, routing, and hardware insertion for CLT and glulam components. Multi-story residential developers in Austria and Germany are deploying these systems at scale to achieve 48-hour superstructure assembly cycles on site. This compression is automating the displacement of conventional stick-framing crews and reducing weather-dependent construction risk.
Germany's EnEV thermal standards and Austria's Holzbau Austria certification framework mandate granular embodied carbon disclosure for structural materials. These requirements are disqualifying untraceable supply chains and favoring vertically integrated forest-to-factory operators with verified chain-of-custody documentation. German-speaking markets exhibit the fastest regulatory compliance adoption, with building permit applications now requiring third-party timber sourcing attestations.
Institutional buyers are consolidating procurement around performance-guaranteed envelope systems rather than component-level purchasing. University and municipal housing authorities in Scandinavia now contract for guaranteed thermal performance over 25-year horizons, shifting vendor relationships from transactional panel sales to long-term energy outcome accountability. This restructuring is most advanced in Sweden and Finland, where public housing associations command sufficient volume to enforce warranty-backed performance terms.
Global Prefab Wood Building Market Segmentation
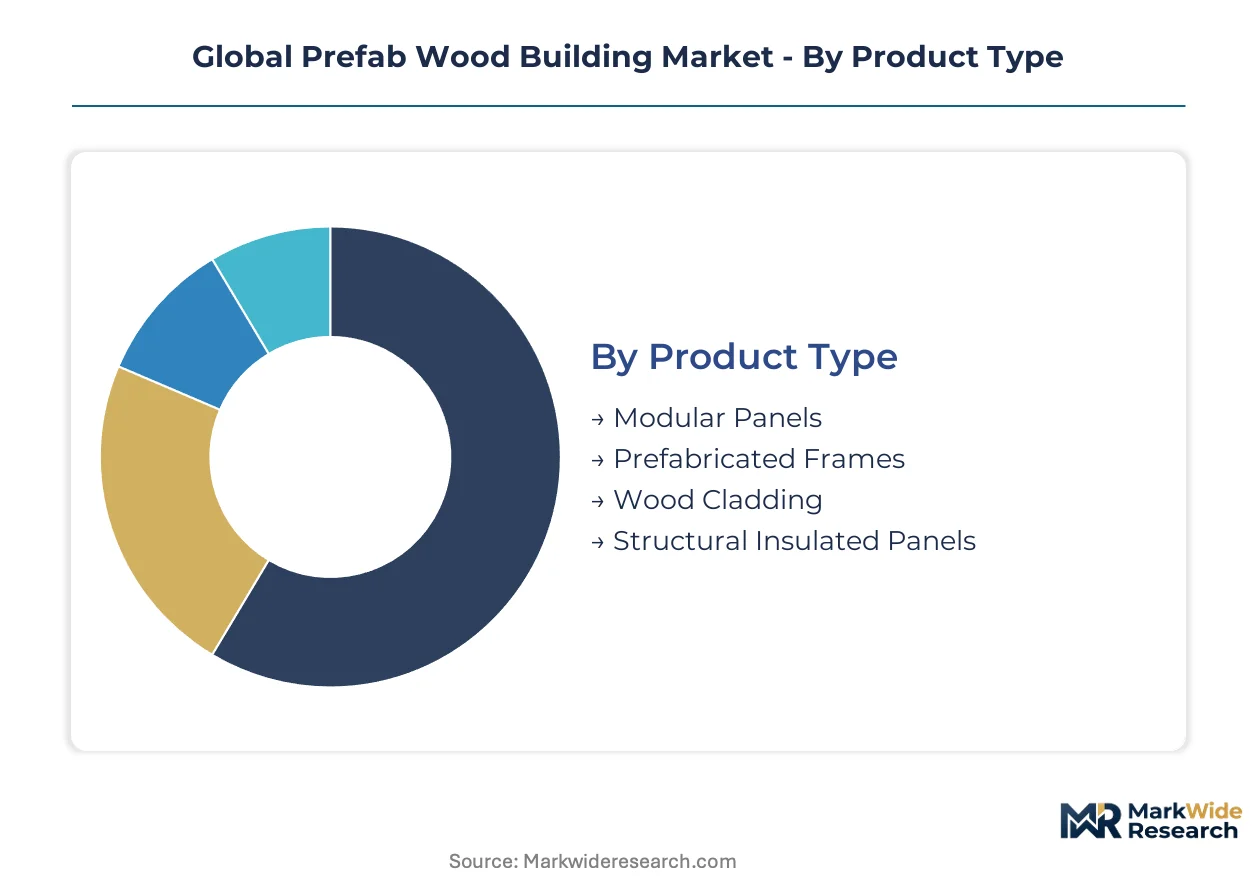
Prefab wood building procurement varies sharply across structural approaches, end-use requirements, and technical specifications. Each segment commands distinct fabrication workflows, certification standards, and margin profiles that reshape how vendors configure their factory investments and geographic reach.
Product Type:
Standardized factory output competes with project-specific engineered systems across this category, with repeatability and transport economics determining which formats achieve scale.
- Modular Panels:Factory-built wall, floor, and roof sections arrive with pre-installed insulation, windows, and electrical chases. German and Austrian multi-story residential developers specify these for 48-hour superstructure assembly cycles that compress weather-dependent construction risk.
- Structural Insulated Panels:Rigid foam cores laminated between oriented strand board faces deliver thermal envelope performance for educational and recreational buildings in Scandinavia. Specification concentrates where 25-year energy outcome guarantees drive procurement decisions.
- Prefabricated Frames:Pre-cut timber members with connection hardware shipped for site assembly serve single-family residential markets requiring design flexibility.
- Wood Cladding:Factory-finished exterior envelope components reduce on-site finishing labor for commercial facade renovations and new construction.
Most installed capacity flows through Modular Panels. Expansion is steepest in Structural Insulated Panels.
Application:
Building height, occupancy density, and fire safety classification segment demand into divergent engineering and certification pathways.
- Residential Housing:Single-family and multi-family structures dominate volume, with Central European markets leading adoption of cross-laminated timber systems above four stories as fire engineering certifications expand.
- Commercial Complexes:Office and retail developments in Germany and Austria specify mass timber for EU Green Deal compliance, with embodied carbon disclosure requirements disqualifying mineral-intensive alternatives from public tenders.
- Educational Facilities:Schools and universities in Sweden and Finland contract for guaranteed thermal performance over multi-decade horizons, shifting vendor relationships toward long-term energy accountability.
- Recreational Buildings:Sports halls and community centers in Alpine regions leverage timber's aesthetic and acoustic properties for high-visibility public architecture.
Residential Housing absorbs the greatest production volume. Commercial Complexes are climbing the fastest as carbon mandates tighten.
Technology:
Adhesive chemistry, mechanical fastening approaches, and dimensional stability characteristics differentiate structural timber systems for distinct load-bearing and fire-resistance requirements.
- Cross-Laminated Timber:Orthogonally bonded lumber layers create panels rated for fire resistance and load-bearing spans exceeding fifteen meters. Extended certification timelines for tall buildings remain the primary constraint on project financing velocity.
- Glue-Laminated Timber:Laminated dimensional lumber bonded with moisture-resistant adhesives serves long-span beams and columns in commercial and institutional applications across German-speaking markets.
- Nail-Laminated Timber:Mechanically fastened dimensional lumber offers lower adhesive dependency for projects prioritizing chemical content transparency.
- Dowel-Laminated Timber:Hardwood dowels replace adhesives entirely, serving niche specifications in health-sensitive and environmentally certified buildings.
Cross-Laminated Timber carries the heaviest installed base. Dowel-Laminated Timber is expanding most quickly among sustainability-premium segments.
End User:
Procurement sophistication and risk tolerance separate transactional component buyers from performance-contracting institutional clients.
- Real Estate Developers:Volume purchasers in Germany, Austria, and Scandinavia consolidate procurement around vertically integrated forest-to-factory operators with verified chain-of-custody documentation required by building permit applications.
- Government Agencies:Public housing authorities and municipal construction departments enforce warranty-backed performance terms, driving adoption of outcome-based contracting in Nordic markets.
- Construction Contractors:Project-based buyers prioritize lead time compression and weather-independent assembly schedules for labor cost management.
- Architecture Firms:Design-led specification influences material selection for high-visibility projects, though actual procurement typically flows through developer or contractor channels.
Real Estate Developers command the largest order flow. Government Agencies are gaining share fastest as public procurement rules harden carbon requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's factory automation density in timber prefabrication outpaces Japan's seismic-engineering adaptations, while both trail Nordic countries in public procurement mandates for mass timber. National building codes and forestry supply chain configurations determine where engineered timber systems achieve specification dominance.
Germany
Multi-story residential developers in Bavaria and Baden-Württemberg specify cross-laminated timber for 48-hour superstructure assembly cycles. The EnEV thermal standards and federal carbon disclosure requirements for public tenders disqualify concrete framing from municipal housing projects. Automated fabrication clusters around Rosenheim and Crailsheim compress lead times through direct Alpine forestry integration.
Austria
Holzbau Austria certification frameworks mandate granular embodied carbon documentation for structural timber across Tyrol and Styria. The country's building code amendments for tall timber construction above six stories accelerate fire engineering investments in Innsbruck-area technical institutes. Alpine sawmill cooperatives feed directly into prefabrication facilities along the Inn Valley corridor.
Sweden
Public housing associations in Stockholm and Gothenburg enforce 25-year thermal performance guarantees for institutional procurement. The National Board of Housing, Building and Planning tightened fire safety classifications for multi-story timber in 2023. Västerbotten County forestry concessions supply automated CLT factories in Skellefteå with verified chain-of-custody documentation.
Japan
METI building efficiency standards and seismic engineering adaptations for engineered timber open specification opportunities in Hokkaido and northern Honshu prefectures. The country's wooden architecture promotion act directs subsidies toward fire-resistant timber systems for public buildings. Sapporo-based fabricators develop cold-climate envelope solutions for residential developments facing Sea of Japan weather exposure.
United States
Section 179D tax deductions for energy-efficient construction reposition mass timber for office and educational building developers in Oregon and Washington. State-level carbon accounting rules in California and New York City local law 97 favor embodied carbon disclosure for structural materials. Pacific Northwest forestry networks supply cross-laminated timber facilities in Portland and Seattle metropolitan zones.
Global Prefab Wood Building Market Competitive Landscape
Top-tier vendors anchor integrated forest-to-factory operations, while mid-scale specialists concentrate on regional certification compliance and automated panel fabrication. The vendor base organizes around three strategic archetypes: vertically integrated forestry operators controlling raw material quality, precision-engineered component specialists serving cold-climate residential segments, and modular systems fabricators optimizing for transport logistics and site assembly speed. Capacity expansion and geographic licensing agreements constitute the dominant competitive moves as manufacturers seek to extend 500-kilometer profitable delivery radii.
Among Nordic forestry-integrated operators, Stora Enso anchors the premium tier through captive supply chain control across managed forest concessions. Binderholz GmbH exemplifies the German-speaking mass timber specialist archetype with large-scale glulam and CLT production capacity. Honkarakenne occupies a position within precision-engineered log home fabrication for Arctic-region residential installations. These three represent distinct competitive positioning vectors: upstream resource control, manufacturing scale concentration, and climate-specific engineering specialization.
| Leading Market Players |
|---|
| Skyline Champion |
| Stora Enso |
| Binderholz GmbH |
| American Homestar |
| Southland Log Homes |
| Fertighaus Weiss |
| American Modular Systems |
| Honkarakenne |
| KLH Massivholz GmbH |
| Others |
Supply & Pricing Matrix
Captive supply of Alpine and Nordic softwood resources anchors both cost position and pricing power for Central European prefabrication clusters, compressing input variance while insulating against spot-market volatility that disrupts non-integrated competitors.
Pricing Analysis
Capacity additions in Germany and Austria are reshaping price floors for cross-laminated timber panels as automated fabrication lines achieve scale economies. Three-tier pricing structure across certified premium, standard construction-grade, and project-specific custom tiers separates vendors by Holzbau Austria and EnEV compliance levels. Cost compression in standard-grade modular panels is intensifying because transport radius economics constrain profitable delivery beyond 500-kilometer radii from fabrication hubs. Government agencies and institutional buyers exhibit lowest price sensitivity due to 25-year performance guarantees, while project-based construction contractors face acute margin pressure from weather-risk transfer.
Supply Chain Analysis
Dual-sourcing requirements for structural adhesive systems are mandating multi-supplier qualification among polyurethane and melamine resin providers concentrated in German and Austrian chemical clusters. Geographic supply concentration centers on Germany, Austria, and Sweden, where automated CLT facilities draw from managed forest concessions with verified chain-of-custody documentation. Raw material dependencies rest on spruce and pine feedstock, formaldehyde-free adhesive chemistry, and CNC automation hardware. Single-source vulnerability in certified timber grading creates exposure where fire-engineering approvals concentrate among Innsbruck and Rosenheim technical institutes. Distribution runs through direct mill-to-site flatbed logistics for panels, with rail intermodal gaining share for Alpine corridor deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Prefab Wood Building Market functions as a stable compounder where EU Green Deal carbon mandates lock in decade-long procurement shifts toward engineered timber systems with verified embodied carbon footprints.
For Market Incumbents: To counter adhesive supply concentration and transport radius constraints, deepen backward integration into managed forest concessions in Västerbotten and Tyrol regions while expanding CNC programming partnerships with German-speaking technical institutes to automate panel fabrication scale-up. For New Entrants and Emerging Players: Begin with seismic-engineered timber adaptations for Japan's Hokkaido cold-climate residential segment, where METI efficiency standards and wooden architecture promotion act subsidies create specification white-space with limited incumbent presence, leveraging digital twin platform partnerships for performance-based maintenance revenue capture. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale automated fabricators with Holzbau Austria or equivalent certification because regulatory compliance barriers protect acquired cash flows from commoditization. Five-to-ten year viability hinges on EU member state adoption velocity for tall timber building codes, with fire safety certification timeline compression serving as the critical inflection signal for project financing velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Alpine Forestry Concession Acquisition | Secures captive softwood supply for CLT production with verified chain-of-custody documentation required by German building permits. |
| Fire Engineering Certification Investment | Accelerates tall timber approval timelines under evolving EU national building codes to unlock multi-story residential project financing. |
| Digital Twin Platform Development | Enables 25-year thermal performance subscriptions for Scandinavian public housing associations shifting to outcome-based contracting. |
| Seismic Adaptation Partnership | Positions engineered timber systems for Japan METI building efficiency standards in Hokkaido and northern Honshu prefectures. |
| Automated Panel Fabrication Scale-Up | Achieves 48-hour superstructure assembly cycles for German and Austrian multi-story residential developers compressing weather risk. |
Research Methodology
Multiple input streams — structured interviews with prefabrication plant managers, procurement leads at German residential developers, forestry cooperative executives, and regulatory affairs specialists — were reconciled against customs trade data, EU ETS carbon accounting disclosures, national building permit databases, and SEC filings from listed timber operators. Bottom-up capacity assessments across Rosenheim, Crailsheim, Innsbruck, and Skellefteå fabrication clusters were triangulated with top-down demand modeling from municipal housing authority procurement records.
Data-stream reconciliation across product type, application, technology, and end-user segmentation dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from regression analysis of historic permit issuance against carbon regulation implementation timelines, with cross-laminated timber fire certification velocity and automated fabrication equipment depreciation curves serving as primary forecast inputs.
Caveats apply where extended fire safety approval cycles, adhesive supply disruptions, or labor scarcity in CNC programming could materially shift the outlook. Deviation in EU member state transposition speed for tall timber building codes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
Asphalt Shingles Market
Building & Construction Materials
Building Insulation Market
Building & Construction Materials
North America Steel Roofing Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
US Precast Concrete Market
Building & Construction Materials
China Marble Market
Building & Construction Materials
North America Decks Market
Building & Construction Materials
Sawn Timber Market
Building & Construction Materials
North America Non-Residential Polished Concrete Market
Building & Construction Materials
EMEA Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
GCC Faucet Market
Building & Construction Materials
Timber Floor Joist Market
Building & Construction Materials
United States I-Joist Market