
 Thyroid Ablation Devices Market | 2026-2036
Thyroid Ablation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Thyroid Ablation Devices Market Intelligence
The gap between premium image-guided systems and commodity radiofrequency generators is repositioning procurement strategies across hospital systems. Medtronic Plc. leverages its end-to-end energy platform portfolio to dominate high-acuity installations in academic medical centers. Boston Scientific Corporation competes through specialized catheter designs that optimize thermal distribution in thyroid tissue. Olympus Corporation anchors its position via integrated ultrasound visualization systems that reduce procedure variability.
Thyroid ablation devices deliver controlled thermal or cryogenic energy to destroy pathological thyroid tissue while preserving surrounding structures, typically operating at frequencies between 460-480 kHz for radiofrequency systems and temperatures reaching 60-100°C for thermal modalities. Radiofrequency ablation systems command the largest installed base among product types due to established reimbursement pathways and clinician familiarity, while image-guided technology segments capture disproportionate margin pools through proprietary navigation software and real-time thermometry. Microwave ablation competes on speed and lesion predictability in larger goiter applications where treatment time directly impacts throughput economics.
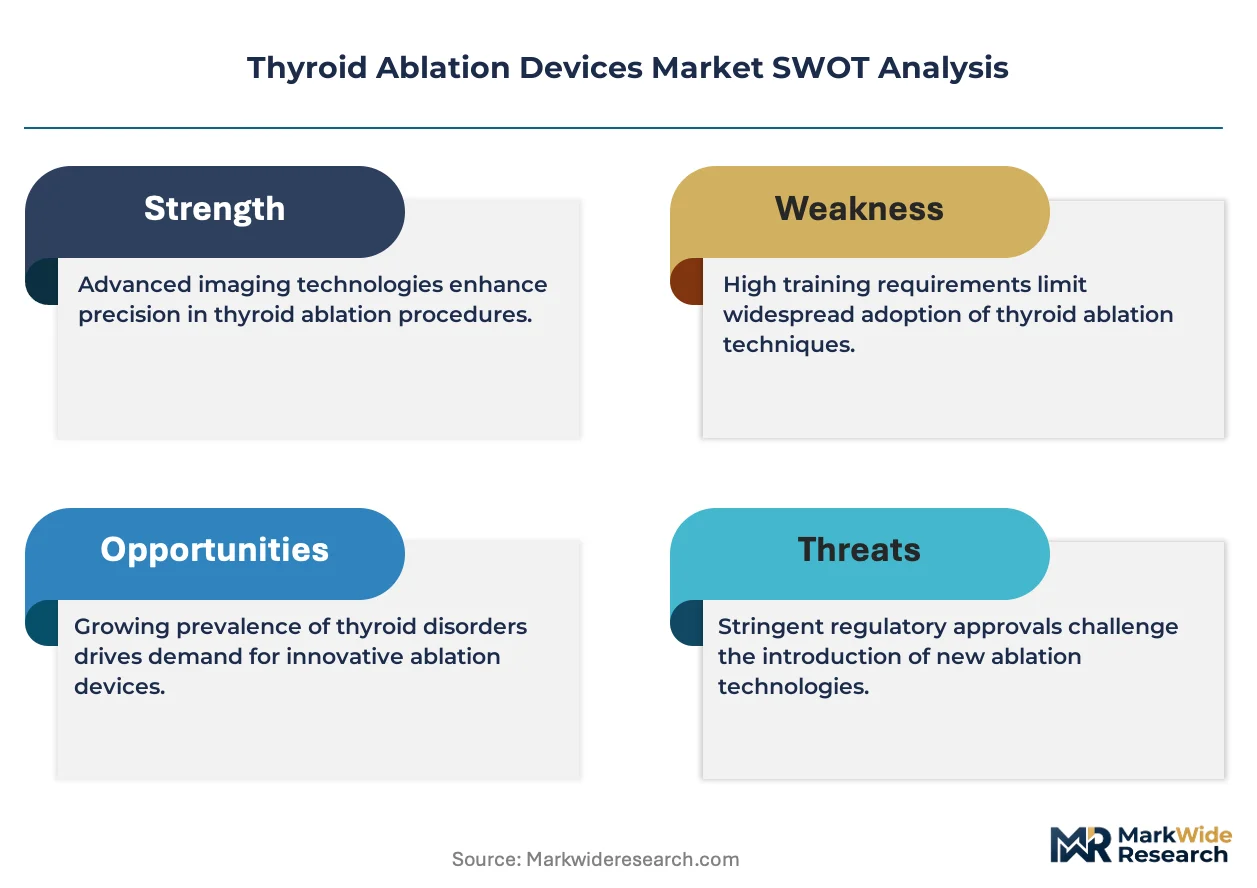
FDA 510(k) clearance requirements and EU MDR technical documentation standards shape device development timelines and clinical evidence burdens for manufacturers seeking market access. The EPA regulates disposal pathways for single-use ablation electrodes, adding operational compliance costs for outpatient surgical centers. Japan's PMDA maintains distinct thermal dose validation protocols that create incremental regulatory work for companies without prior Asia-Pacific submissions. Stakeholders must monitor evolving reimbursement decisions for benign nodule indications as these coverage determinations will dictate whether ablation displaces surgical lobectomy in routine practice.
Market Dynamics
The convergence of image-guidance software with thermal delivery hardware is compressing procedure times and expanding treatable patient populations beyond traditional surgical candidates.
Growth Catalysts
- EU MDR Streamlined Pathways:The EU Medical Device Regulation's Article 54 consultation process for well-established technologies accelerates CE marking timelines for radiofrequency ablation systems, reducing regulatory lag for European market entry.
- Ambulatory Surgery Center Expansion:United States outpatient facilities are building dedicated interventional thyroid service lines, creating installed base demand for compact, mobile-compatible ablation platforms.
- Microwave Ablation Speed Advantages:Faster lesion generation in large goiter applications improves throughput economics for high-volume thyroid clinics, particularly in Japan where procedure reimbursement ties to time-based efficiency metrics.
Market Restraints
- Single-Use Electrode Cost Volatility:Copper and platinum-iridium alloy prices directly impact per-procedure consumable costs, squeezing margins for outpatient surgical centers operating on fixed reimbursement schedules.
- PMDA Thermal Dose Validation:Japan's Pharmaceuticals and Medical Devices Agency maintains distinct protocols requiring additional clinical evidence packages, creating incremental regulatory work for manufacturers without prior Asia-Pacific submissions.
- Surgical Lobectomy Substitution Threat:Established thyroidectomy remains the default treatment pathway in many health systems, particularly where ablation lacks dedicated reimbursement codes or prior authorization pathways.
Strategic Opportunities
- Germany's Interventional Radiology Integration:German hospital systems are consolidating thyroid ablation into interventional radiology departments, creating demand for cross-trained specialists and hybrid imaging-therapy platforms.
- AI-Assisted Thermometry Convergence:Machine learning algorithms for real-time temperature mapping are merging with ultrasound navigation systems, enabling more predictable ablation zone control and reduced operator learning curves.
- Direct-to-Provider Distribution Models:Manufacturers are bypassing traditional device distributors to sell directly to ambulatory surgery centers, capturing margin and enabling faster service response times.
Industry Challenges
- Cross-Training Skill Deficits:Interventional radiologists require specialized thyroid anatomy training, while endocrinologists need ultrasound-guided needle skills, creating dual competency gaps that slow adoption.
- FDA 510(k) Clinical Evidence Burden:The FDA's evolving expectations for thermal ablation equivalence studies extend premarket submission timelines and increase trial costs for novel energy modalities.
- Legacy EMR Integration Complexity:Ablation procedure documentation standards vary across health systems, forcing device vendors to support multiple data export formats and interoperability protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thyroid Ablation Devices Market |
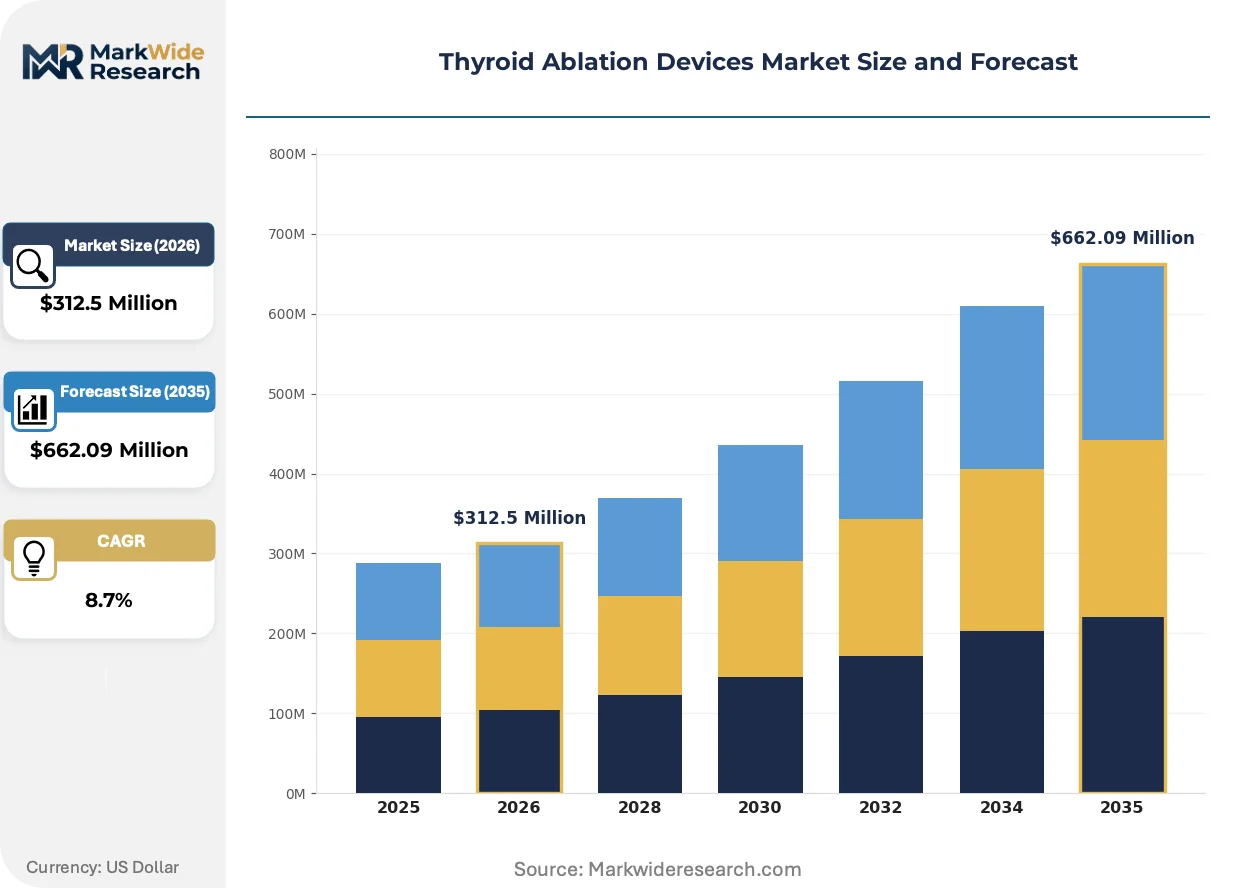
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency, Microwave, Laser, Cryoablation Technology: Contact, Non-Contact, Image-Guided, Robotic End User: Hospitals, Clinics, Outpatient Surgical Centers, Ambulatory Surgery Centers Application: Benign Nodules, Malignant Tumors, Hyperthyroidism, Goiter |
| Companies Covered | Medtronic Plc., Boston Scientific Corporation, Johnson & Johnson, Integra Life Sciences, Olympus Corporation, Terumo Corporation, BVM Medical System, StarMed Co. Ltd., Theraclion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thyroid Ablation Devices Market Strategic Shifts & Innovations
Hardware-software integration is eliminating the historical separation between energy delivery and real-time monitoring, collapsing the traditional two-vendor procurement model into single-source platform decisions.
Multipolar radiofrequency systems with integrated impedance feedback are rewriting treatment protocols for benign thyroid nodules. Academic medical centers in the United States are adopting these platforms for their ability to automate energy titration based on tissue resistance changes. The technology is compressing operator training requirements and enabling consistent outcomes across less experienced practitioners.
The EU MDR's heightened clinical evidence standards for class III devices are forcing manufacturers to maintain post-market surveillance registries. This regulatory friction disproportionately affects smaller device developers lacking dedicated regulatory affairs infrastructure. German notified bodies are processing submissions more slowly than their pre-MDR predecessors, concentrating market access advantages with established players.
Hospital procurement committees are consolidating thyroid ablation purchasing decisions under interventional radiology department budgets rather than distributed surgical divisions. This budget reallocation is displacing the traditional capital equipment committee model and favoring vendors offering bundled service contracts. The shift is most visible in Japan, where hospital group purchasing organizations are negotiating enterprise-wide platform commitments.
Thyroid Ablation Devices Market Segmentation
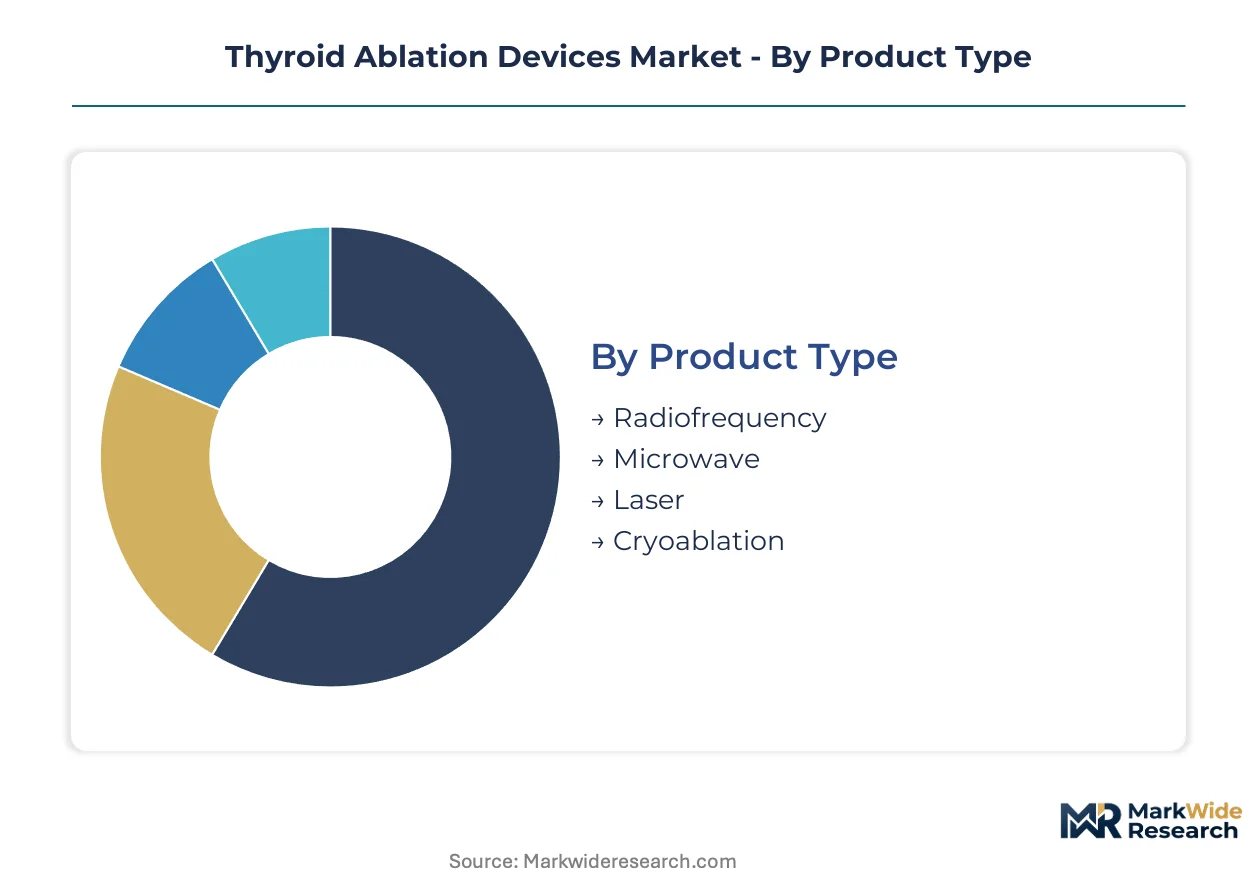
Thyroid ablation device procurement decisions fragment across energy modality, guidance technology, and care setting economics. Hospital systems weigh capital intensity against reimbursement pathways when selecting platform configurations.
Product Type:
Radiofrequency and microwave systems anchor the installed base as standalone capital purchases, while laser and cryoablation platforms increasingly embed within integrated surgical suites.
- Radiofrequency:These systems operate at 460-480 kHz frequencies with impedance feedback controls that automate energy titration. United States academic medical centers favor radiofrequency platforms for their established 510(k) clearance pathways and broad benign nodule reimbursement coverage.
- Microwave:Operating at 915 MHz or 2.45 GHz, microwave generators produce faster thermal lesions through dielectric heating mechanisms. Japanese high-volume thyroid clinics prioritize microwave systems where time-based reimbursement metrics reward shorter procedure durations.
- Laser:Nd:YAG and diode laser platforms deliver precise 980-1064 nm wavelength energy through thin fiberoptic applicators.
- Cryoablation:Argon-helium gas systems create controlled freeze-thaw cycles for tissue destruction.
Volume placements concentrate in radiofrequency systems; the faster expansion belongs to microwave platforms.
Technology:
Procurement patterns distinguish between basic energy delivery hardware and premium navigation-integrated platforms that command higher per-procedure fees.
- Contact:Direct tissue apposition electrodes remain the standard configuration for radiofrequency and microwave modalities, offering tactile feedback to operators.
- Non-Contact:Electromagnetic field delivery without physical electrode insertion suits superficial thyroid lesions.
- Image-Guided:Real-time ultrasound fusion with thermometry mapping enables precise ablation zone monitoring. German interventional radiology departments are consolidating purchasing decisions around image-guided platforms that reduce procedure variability and support cross-specialty training protocols.
- Robotic:Automated needle positioning systems with pre-planned trajectory mapping are gaining traction in Japan's hospital group purchasing organization negotiations.
Contact technology dominates current installed base; robotic-assisted delivery is climbing the fastest as precision requirements tighten.
End User:
Facility type determines capital budget allocation, with inpatient hospitals favoring multi-modality suites while outpatient centers prioritize mobile-compatible platforms.
- Hospitals:Large inpatient facilities maintain comprehensive ablation capabilities across radiology, surgery, and endocrinology departments. These installations favor platforms with EMR integration and multi-user credentialing systems.
- Clinics:Specialist endocrinology practices require compact systems with simplified workflow protocols.
- Outpatient Surgical Centers:United States freestanding facilities are building dedicated thyroid service lines around single-modality platforms that minimize per-procedure consumable costs.
- Ambulatory Surgery Centers:Medicare-certified ASCs demand portable generators compatible with existing ultrasound equipment and rapid room turnover protocols.
Hospital placements retain the largest share; ambulatory surgery centers are gaining share fastest as site-of-service migration accelerates.
Application:
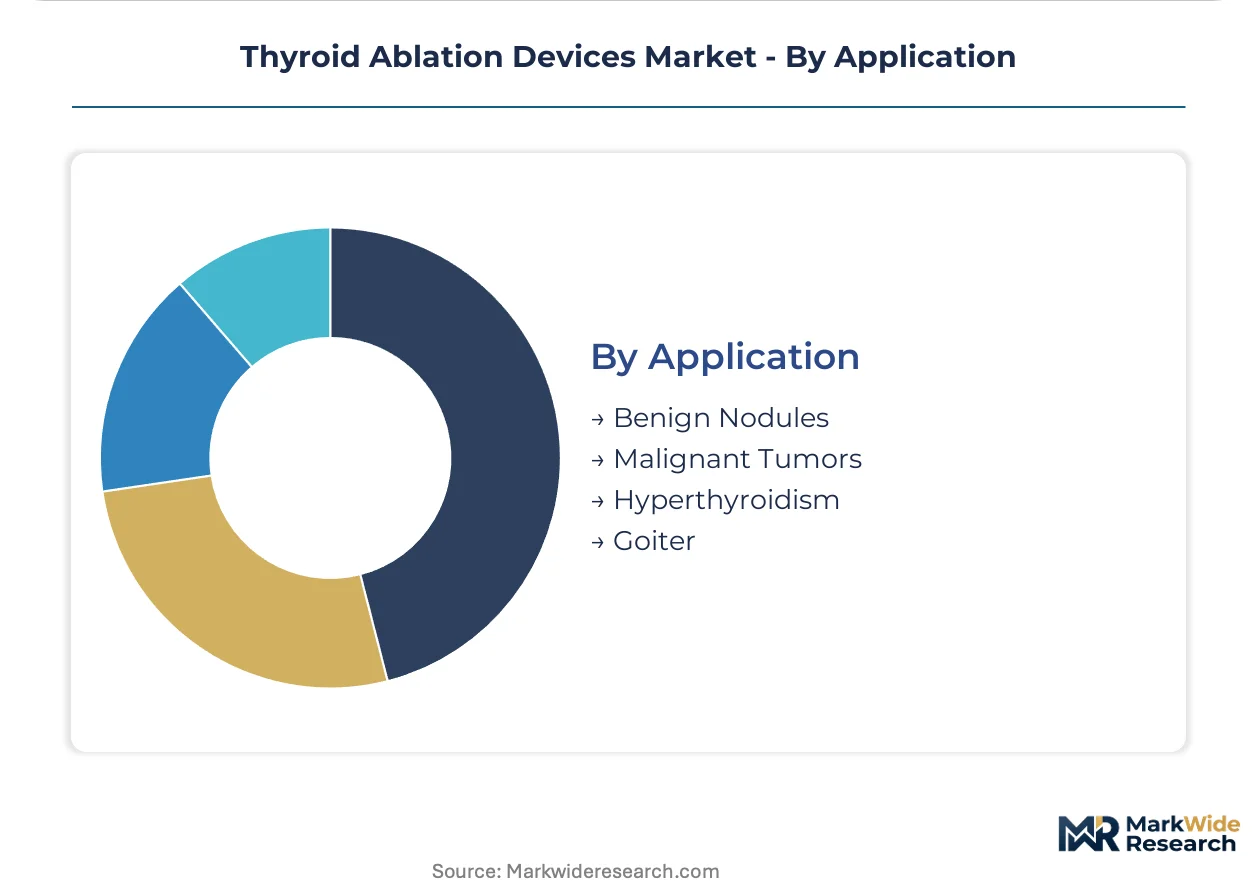
Clinical indication shapes regulatory pathway complexity and reimbursement certainty, with benign conditions offering clearer market access than oncologic applications.
- Benign Nodules:Symptomatic thyroid nodules represent the primary reimbursed indication across United States commercial payers and Japanese national health insurance. FDA 510(k) clearance standards are well-established for this indication.
- Malignant Tumors:Primary thyroid cancer ablation remains investigational in most jurisdictions, requiring IDE protocols or compassionate use frameworks.
- Hyperthyroidism:Thermal ablation for Graves' disease and toxic nodules is expanding in European centers with established MDR technical documentation.
- Goiter:Large multinodular goiter applications favor microwave speed advantages where treatment time scales with lesion volume.
Benign nodule procedures command current volume leadership; hyperthyroidism applications show the steepest expansion trajectory as evidence bases mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's Kanto corridor anchors thyroid ablation device deployment through Japan's dense concentration of high-volume thyroid clinics and time-based reimbursement structures that reward procedural efficiency.
United States
Ambulatory surgery centers in Texas and Florida are building dedicated thyroid service lines around compact, mobile-compatible ablation platforms. FDA 510(k) clearance pathways for benign nodule indications remain well-established, though evolving equivalence study expectations extend timelines for novel energy modalities. The Mayo Clinic Rochester campus anchors academic medical center adoption of multipolar radiofrequency systems with integrated impedance feedback.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia are consolidating thyroid ablation purchasing decisions under interventional radiology department budgets. EU MDR Article 54 consultation processes for well-established technologies accelerate CE marking timelines, though German notified bodies process submissions more slowly than pre-MDR predecessors. The Heidelberg University Hospital cluster drives demand for hybrid imaging-therapy platforms that support cross-specialty training protocols.
Japan
High-volume thyroid clinics in Osaka's Kansai region prioritize microwave ablation systems where national health insurance reimbursement ties to time-based efficiency metrics. PMDA thermal dose validation protocols require additional clinical evidence packages, creating incremental regulatory work for manufacturers without prior Asia-Pacific submissions. Hospital group purchasing organizations in Tokyo negotiate enterprise-wide platform commitments that favor bundled service contracts.
United Kingdom
Specialist endocrinology practices in London and the Southeast require compact systems with simplified workflow protocols for office-based benign nodule treatments. MHRA post-Brexit regulatory alignment with EU MDR technical documentation standards shapes device development timelines. The Cambridge biomedical cluster supports early-stage development of AI-assisted thermometry algorithms for real-time temperature mapping.
South Korea
Metropolitan Seoul's concentrated hospital networks are adopting robotic-assisted needle positioning systems with pre-planned trajectory mapping. MFDS maintains distinct validation protocols for thermal ablation devices that parallel Japan's evidence requirements. The Samsung Medical Center anchors demand for image-guided platforms that reduce procedure variability across less experienced practitioners.
Thyroid Ablation Devices Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the thyroid ablation device landscape, with integrated platform vendors holding installed base advantages in academic medical centers while specialized catheter developers capture margin in high-throughput outpatient settings. The vendor base organizes around three strategic archetypes: diversified energy platform conglomerates, focused interventional catheter specialists, and integrated visualization-therapy hybrid suppliers. Consolidation pressure runs through direct-to-provider distribution models that bypass traditional device distributors, and through hospital procurement committee centralization under interventional radiology budgets rather than distributed surgical divisions.
Among diversified energy platform conglomerates, Medtronic Plc. and Boston Scientific Corporation occupy positions that exemplify the capital-intensive end-to-end system approach. Olympus Corporation represents the integrated visualization-therapy archetype, anchoring market presence through ultrasound navigation convergence. These three entities sit within distinct competitive vectors: Medtronic leverages breadth across energy modalities, Boston Scientific competes through specialized thermal distribution optimization, and Olympus reduces procedure variability through real-time imaging integration.
| Leading Market Players |
|---|
| Medtronic Plc. |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Integra Life Sciences |
| Olympus Corporation |
| Terumo Corporation |
| BVM Medical System |
| StarMed Co. Ltd. |
| Theraclion |
| Others |
Cost & Logistics Intelligence
Multipolar radiofrequency systems with automated impedance feedback are compressing training costs and standardizing outcomes, simultaneously flattening price premiums for image-guided platforms while concentrating procurement power among manufacturers with integrated software-therapy ecosystems. This hardware-software convergence rewards vendors with captive navigation technology and squeezes standalone generator producers into commodity positioning.
Pricing Analysis
Throughput-based pricing anchors procurement decisions as ambulatory surgery centers prioritize per-procedure economics over capital outlay. Three-tier pricing structure across premium navigation-integrated, standard image-guided, and economy generator-only levels stratifies the installed base. Pricing pressure stems from fixed Medicare reimbursement schedules for benign nodule ablation that fail to capture technology premiums. Outpatient surgical centers exhibit highest price sensitivity due to thin operating margins, while academic medical centers prioritize outcome consistency over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German precision electronics suppliers for real-time thermometry sensors. Device assembly concentrates in the United States, Japan, and Germany, drawing from copper and platinum-iridium electrode suppliers in South Africa and Russia. Tariff exposure on critical alloys threatens consumable cost stability. Distribution runs through direct-to-provider models that displace traditional medical device distributors, compressing lead times for ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue captive control over ultrasound navigation software to escape commoditization of energy delivery hardware.
For Market Incumbents: Deepen software-therapy integration to defend against standalone generator competitors. Acquire specialized thermometry algorithm developers to automate energy titration and reduce operator learning curves. Lock in ambulatory surgery center purchasing committees with bundled service contracts that span capital equipment and per-procedure consumables. For New Entrants and Emerging Players: EU MDR Article 54 consultation pathways for well-established technologies in Germany open a window for radiofrequency platform entrants lacking FDA 510(k) precedence. Target United States outpatient surgical centers in Texas and Florida with mobile-compatible, single-modality systems priced below integrated platform tiers. Pursue direct-to-provider distribution to capture margin and accelerate service response. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified energy platform conglomerates seeking thyroid-specific catheter technology. Long-term viability favors vendors with proprietary navigation software and installed base lock-in. Watch PMDA thermal dose validation protocol harmonization across Asia-Pacific as the signal for regulatory barrier reduction and accelerated regional expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Establishes reimbursement eligibility for benign nodule indications in United States commercial payers. |
| CE Marking Under EU MDR | Article 54 consultation accelerates market access for radiofrequency systems in German hospital systems. |
| Hospital System Partnership | Heidelberg University Hospital cluster drives adoption of hybrid imaging-therapy platforms for cross-specialty training. |
| Software Companion Development | AI-assisted thermometry algorithms at Cambridge biomedical cluster enable predictable ablation zone control. |
| Reimbursement Strategy | Japanese time-based efficiency metrics reward microwave ablation speed in Osaka's high-volume thyroid clinics. |
Research Approach
Independent corroboration across hospital purchasing committee interviews, interventional radiology department heads, and biomedical engineering directors underwrites the qualitative findings. Primary fieldwork with GPO contracts managers and ambulatory surgery center administrators combined with secondary validation from FDA 510(k) filings, PMDA submission databases, EU MDR notified body registries, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates and top-down equipment shipment analysis triangulate market sizing.
Comparable-period anchoring to historical installed base growth and reimbursement expansion patterns structured the projection horizon. The analytical framework segments by energy modality, guidance technology, end-user facility type, and clinical indication across the modeling period. CAGRs derive from fitted growth curves adjusted for regulatory lag and site-of-service migration. Forecast inputs include PMDA validation timeline assumptions and ambulatory surgery center construction permits.
The model assumes a particular technology adoption path; alternative pathways for robotic-assisted needle positioning would alter the outlook. Forecasts reflect assumptions about EU MDR notification body processing speeds and United States Medicare coverage determinations for hyperthyroidism indications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Reprocessed Medical Devices Market
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
Medical Device Validation and Verification Market
Medical Devices
Wireless ECG Devices Market
Medical Devices
Sacroiliac Joint Fusion Market
Medical Devices
Medical Connector Market
Medical Devices
IV Poles Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
Asia-Pacific Integrated Operating Room System Market
Medical Devices
Pressure Ulcer Detection Devices Market
Medical Devices
South Korea Ultrasound Devices Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Otoscope Devices Market
Medical Devices
Indwelling Pleural Catheters Market
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
Coil Assisted Flow Diverters Market