
 Small Bone and Joint Devices Market | 2026-2036
Small Bone and Joint Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Small Bone and Joint Devices Market Intelligence
Ambulatory surgical centers are bifurcating demand away from traditional hospital purchasing committees for small bone and joint fixation hardware. Stryker Corporation anchors its position through captive distribution to outpatient surgery networks, while Zimmer Biomet competes via specialized foot-and-ankle portfolios that target ASC-specific procedural volumes. Arthrex, Inc. differentiates through arthroscopic instrumentation bundled with implant systems, a combination that ASCs favor for operational efficiency.
Small bone and joint devices comprise metallic and bioresorbable implants engineered for skeletal stabilization in the hand, wrist, foot, ankle, and clavicle, with titanium alloys offering strength-to-weight ratios near 110 ksi and osseointegration surfaces treated by plasma-sprayed hydroxyapatite. Their primary commercial purpose is to restore anatomical alignment and load-bearing function following trauma or degenerative collapse. Fracture repair leads device type consumption due to emergency presentation volumes, while joint reconstruction captures expanding margin pools as patient-specific instrumentation raises ASPs in arthroplasty. Biomaterials represent the fastest-expanding material category as surgeons seek to eliminate secondary removal surgeries in pediatric and geriatric cohorts.
FDA 510(k) premarket notification and EU MDR conformity assessment govern implant biocompatibility and clinical evidence requirements, with the latter extending notified body review timelines and concentrating market access among well-capitalized registrants. The EU AI Act introduces post-market surveillance obligations for software-enabled surgical planning tools that increasingly accompany joint reconstruction procedures. Stakeholders must monitor regulatory divergence between US and European evidence standards when allocating R&D and clinical trial budgets across geographies.
Market Dynamics
Outpatient orthopedic migration is compressing hospital purchasing power while elevating ambulatory surgical centers as gatekeepers for implant procurement, forcing manufacturers to restructure distribution networks around same-day discharge protocols.
Growth Catalysts
- EU MDR clinical evidence mandates:Extended notified body review timelines favor well-capitalized registrants with established quality management systems, accelerating consolidation among implant manufacturers.
- Titanium alloy osseointegration surfaces:Plasma-sprayed hydroxyapatite coatings reduce revision rates in distal radius and ankle fractures, expanding addressable surgical volumes.
- Ambulatory surgical center expansion:United States outpatient migration for hand and foot procedures creates dedicated procurement channels outside traditional hospital supply chains.
Market Restraints
- Titanium sponge supply concentration:Russian and Ukrainian feedstock disruptions have elevated raw material costs for alloy producers, compressing margins on standard fixation plates.
- EU AI Act post-market surveillance:Software-enabled surgical planning tools now face ongoing monitoring obligations, extending compliance costs for patient-specific instrumentation.
- Bioresorbable polymer degradation variability:Inconsistent resorption rates in polylactic acid implants create liability exposure and limit pediatric application expansion.
Strategic Opportunities
- German foot-and-ankle arthroplasty:Aging demographics and sports medicine volume sustain hardware utilization in a market with above-average reimbursement rates.
- Arthroscopic instrumentation bundling:Combined implant and tool offerings reduce ASC operational complexity and capture higher procedural economics.
- China NMPA accelerated review pathways:Priority status for innovative orthopedic devices shortens time-to-market for domestic and multinational registrants.
Industry Challenges
- Notified body capacity constraints:EU MDR implementation has reduced available certification bodies to eleven, creating 12-18 month backlog queues for conformity assessment.
- Patient-specific instrumentation capex requirements:In-house additive manufacturing or contract sterilization partnerships demand 8-figure facility investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Bone and Joint Devices Market |
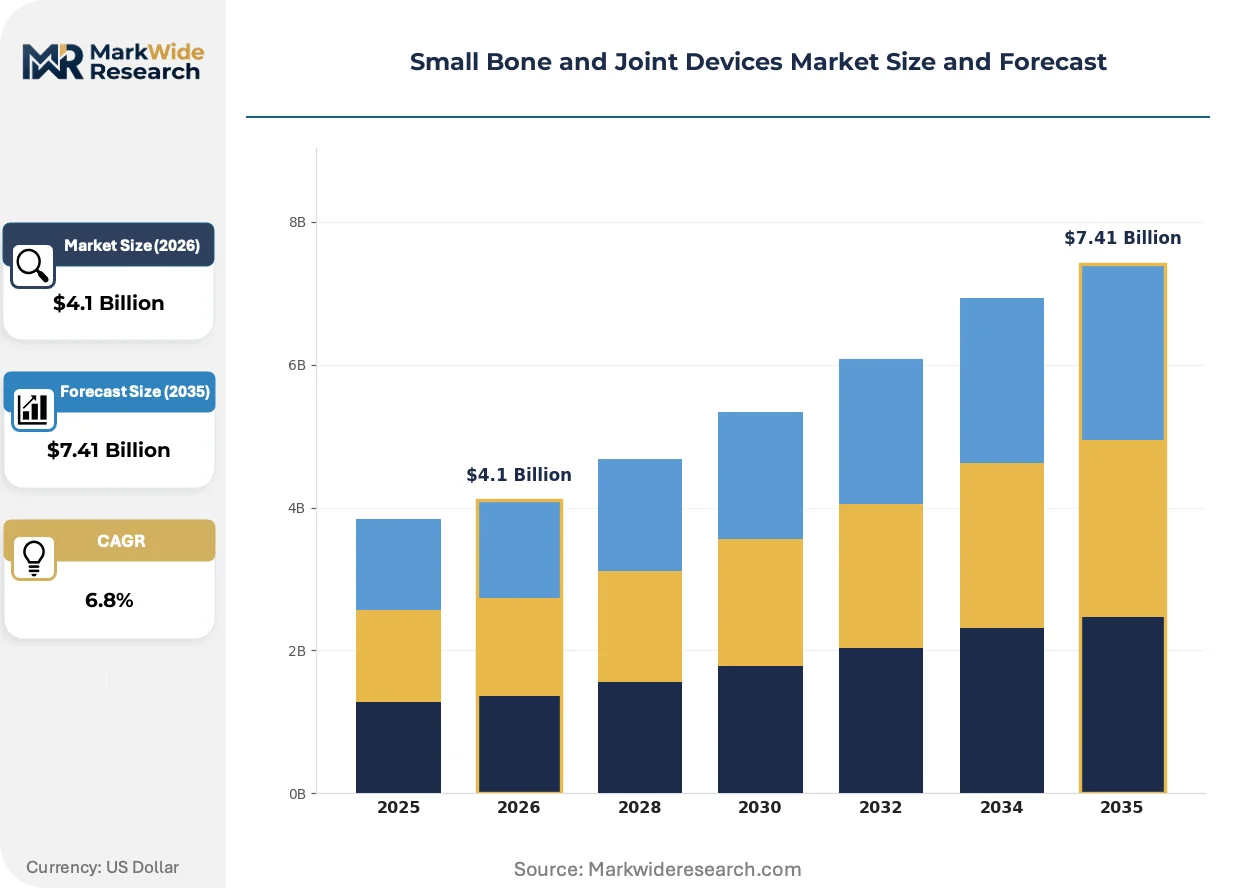
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Plates, Screws, Intramedullary Rods, Ex Fixators Material: Stainless Steel, Titanium, Biomaterials, Polymers End User: Orthopedic Clinics, Hospitals, Ambulatory Surgical Centers, Rehabilitation Centers Application: Fracture Repair, Joint Reconstruction, Arthroplasty, Bone Fixation |
| Companies Covered | Stryker Corporation, Zimmer Biomet, DePuy Synthes Companies, Smith & Nephew PLC, Arthrex, Inc., Acumed LLC, DJO Global, Inc., Orthofix US LLC, Paragon 28, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Bone and Joint Devices Market Strategic Shifts & Innovations
Biomaterial science and digital surgical planning are converging to eliminate secondary procedures and compress operative times, reshaping value capture across the implant supply chain.
Bioresorbable polymers are bifurcating metallic implant demand in pediatric and geriatric cohorts where hardware removal carries disproportionate risk. Surgeons in United States academic medical centers are adopting magnesium-based screws for scaphoid fixation at accelerating rates. This material transition is compressing long-term revenue streams from revision hardware while expanding initial procedure addressability.
EU MDR Article 117 clinical evaluation requirements are extending notified body review timelines from 9 to 18 months for Class III implantable devices. Manufacturers are responding by concentrating registration resources on high-margin arthroplasty portfolios rather than commoditized trauma plates. German and French orthopedic device firms report diverting clinical trial budgets toward US FDA 510(k) pathways to maintain revenue continuity.
ASC purchasing committees are consolidating vendor relationships around single-source implant and instrumentation contracts that bundle disposable consumables. Hospital supply chain departments are losing influence over small bone fixation procurement as outpatient volume migrates. This channel shift is most visible in Texas and Florida, where freestanding surgery center construction permits exceeded hospital orthopedic wing expansions by four-to-one in recent quarters.
Small Bone and Joint Devices Market Segmentation
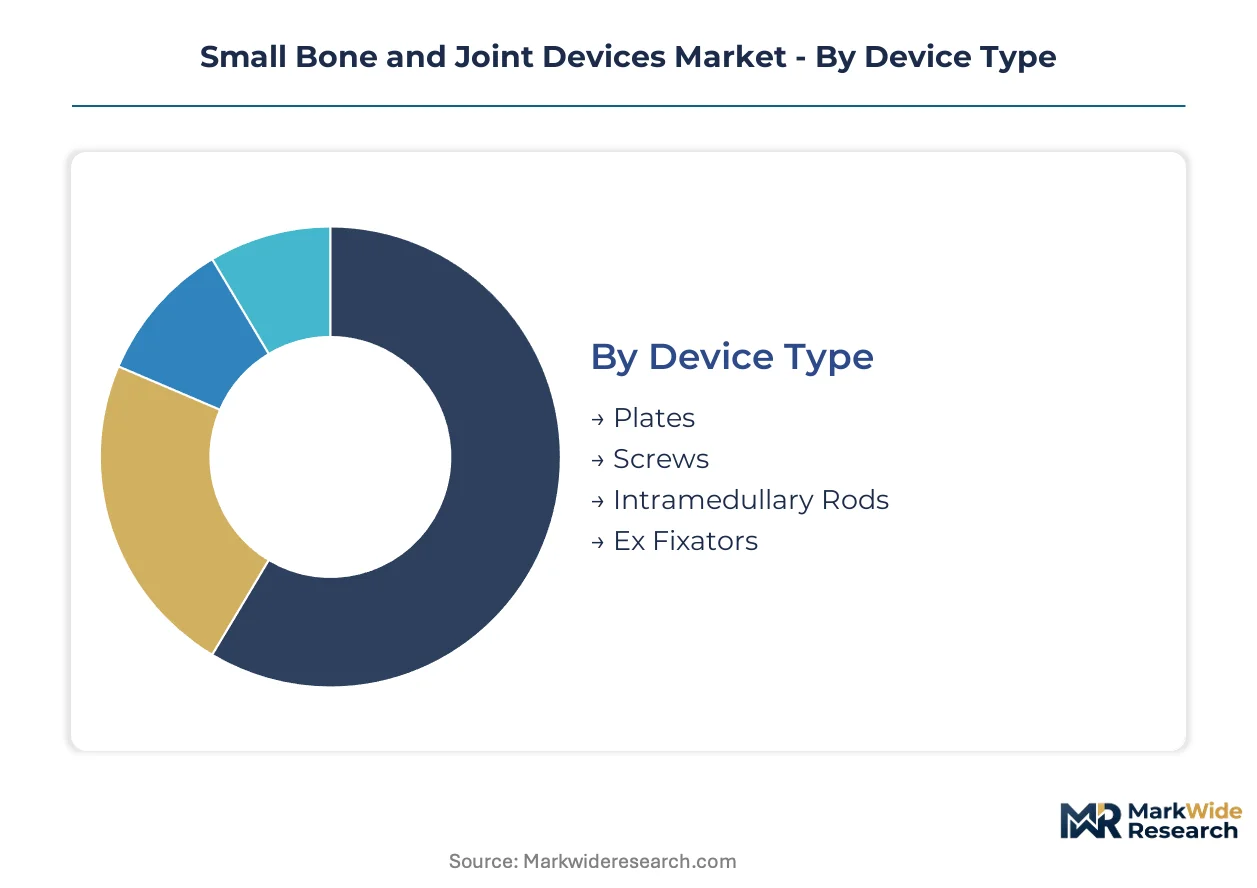
Segmentation in small bone and joint devices reveals how procurement channels, material science trajectories, and procedural site migration reshape competitive positioning. Manufacturers configure product portfolios around these fault lines to capture diverging margin pools across trauma versus elective reconstruction workflows.
Device Type:
Domestic production concentrates plates and screws in the United States and Germany, while intramedullary rods and external fixators draw more heavily from Asian contract manufacturers serving export markets.
- Plates:Contoured titanium or stainless steel constructs with locking screw interfaces provide rigid fixation for distal radius and calcaneal fractures. Demand clusters in United States ambulatory surgical centers performing same-day hand and foot procedures, where disposable instrument kits accompany plate systems to reduce sterilization burden.
- Screws:Cortical, cancellous, and cannulated screw geometries range from 1.0mm to 7.3mm diameter for phalangeal to ankle applications. German orthopedic clinics favor titanium alloy screws with plasma-sprayed hydroxyapatite coatings to accelerate osseointegration in osteoporotic bone.
- Intramedullary Rods:Intramedullary fixation devices stabilize long bone fractures in the clavicle and small long bones of the hand.
- Ex Fixators:External fixation systems enable temporary stabilization for open fractures and limb salvage procedures.
Plates hold the largest share; momentum sits with screws as patient-specific instrumentation expands addressable volumes.
Material:
Cost stratification separates premium titanium and biomaterials from standard stainless steel, with polymer development absorbing mid-tier pricing pressure.
- Stainless Steel:316L surgical stainless steel delivers cost-effective fixation for trauma plates in budget-constrained hospital systems. Indian and Chinese public hospitals specify stainless steel for high-volume fracture repair programs where implant cost dominates procurement criteria.
- Titanium:Ti-6Al-4V and Ti-6Al-7Nb alloys offer superior strength-to-weight ratios and MRI compatibility for upper extremity applications. United States academic medical centers specify titanium for scaphoid and talus procedures where implant longevity reduces revision exposure.
- Biomaterials:Magnesium and calcium phosphate ceramics enable resorbable fixation eliminating hardware removal surgery.
- Polymers:Polylactic acid and polyglycolic acid polymers provide temporary fixation in pediatric applications.
Titanium commands premium positioning; polymers are climbing the fastest as resorbable technology matures.
End User:
Volume concentration shifts toward outpatient settings as reimbursement incentives realign site-of-service economics.
- Orthopedic Clinics:Office-based surgical suites in Germany and Switzerland perform percutaneous fixation of metacarpal and phalangeal fractures under local anesthesia. These clinics source mini-fragment systems through specialized distributors rather than hospital supply chains.
- Hospitals:Academic medical centers in the United States manage complex polytrauma and revision arthroplasty requiring 3D-printed patient-specific instrumentation. Hospital purchasing committees negotiate enterprise contracts bundling trauma and joint reconstruction portfolios.
- Ambulatory Surgical Centers:Freestanding surgery centers in Texas and Florida drive demand for disposable instrument kits and streamlined implant systems.
- Rehabilitation Centers:Post-acute facilities coordinate with implanting surgeons on weight-bearing protocols and hardware monitoring.
Hospitals retain the largest share; ASCs are gaining share fastest as outpatient migration accelerates.
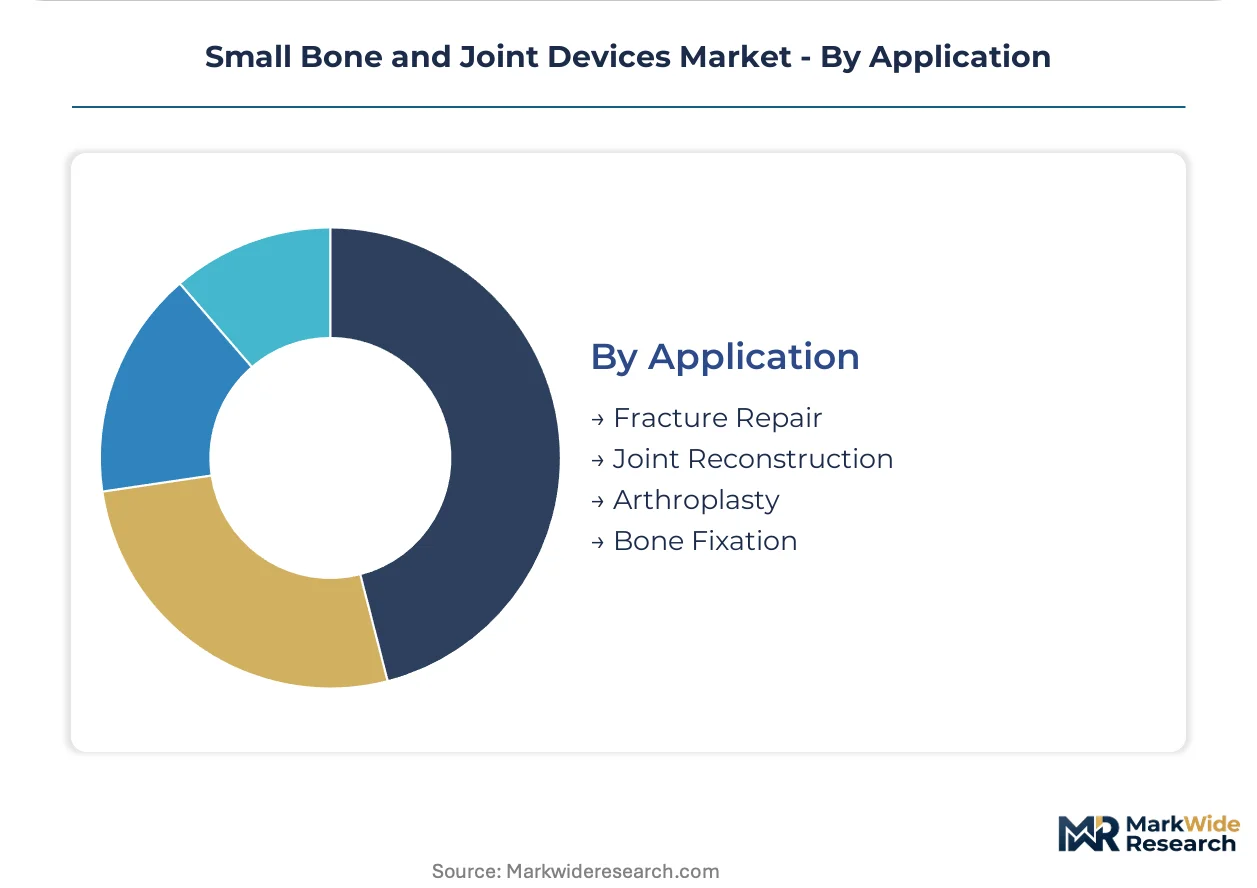
Application:
Procedure maturity separates established fracture repair from emerging joint reconstruction modalities with diverging technology investment requirements.
- Fracture Repair:Emergency trauma fixation consumes the highest unit volumes of plates, screws, and external fixators across all geographies. United States Level I trauma centers maintain 24/7 implant inventory for distal radius, ankle, and calcaneal fractures presenting through emergency departments.
- Joint Reconstruction:Ligament repair and fusion procedures in the foot and ankle require specialized screw and plate geometries. French and German surgeons lead adoption of arthroscopic-assisted techniques for subtalar and talonavicular fusion.
- Arthroplasty:Total joint replacement of the ankle and small joints of the hand represents the highest ASP category.
- Bone Fixation:Prophylactic and corrective osteotomy fixation supports deformity correction procedures.
Fracture repair holds the largest share; arthroplasty shows the steepest expansion trajectory as patient-specific instrumentation raises procedural economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics hub underwrites European distribution efficiency for implant manufacturers serving continental markets. This infrastructure asset enables rapid customs clearance and temperature-controlled warehousing for titanium alloy shipments arriving from Asian foundries.
United States
ASC construction permits in Texas and Florida exceeded hospital orthopedic expansions by four-to-one, concentrating demand for disposable instrument kits. FDA 510(k) clearance pathways maintain shorter review timelines than EU MDR equivalents, attracting German and French firms to prioritize US registration. The Dallas-Fort Worth metroplex hosts specialized distributors serving outpatient surgery networks across the Southwest.
Germany
Aging demographics and sports medicine volume sustain foot-and-ankle hardware utilization with above-average reimbursement rates. EU MDR notified body capacity constraints extend conformity assessment to 12-18 months, favoring well-capitalized registrants with established quality systems. The Stuttgart-Tübingen corridor concentrates orthopedic device engineering talent and precision manufacturing capabilities.
China
NMPA accelerated review pathways grant priority status to innovative orthopedic devices, shortening time-to-market for domestic and multinational registrants. Domestic titanium sponge production reduces import dependency following Russian and Ukrainian feedstock disruptions. The Suzhou industrial park clusters contract manufacturers serving export markets for standard fixation plates.
Japan
PMDA regulatory harmonization with FDA standards streamlines dual-registration strategies for premium arthroplasty portfolios. Academic medical centers in Tokyo and Osaka drive adoption of patient-specific instrumentation for complex joint reconstruction. The Kansai region maintains specialized machining capacity for magnesium-based bioresorbable implants.
Switzerland
Swissmedic maintains streamlined review procedures for CE-marked devices, preserving market access efficiency amid broader EU MDR turbulence. Geneva and Basel host headquarters operations for firms targeting premium-tier pricing in orthopedic trauma. The country's precision engineering heritage supports high-mix, low-volume production of specialized screw geometries.
Small Bone and Joint Devices Market Key Industry Players
Concentration sits with diversified orthopedic conglomerates commanding captive distribution networks and specialized foot-and-ankle portfolios. Three strategic archetypes dominate: integrated device manufacturers with ASC-focused supply chains, arthroscopy specialists bundling instrumentation with implants, and bioresorbable material innovators targeting pediatric and geriatric elimination of secondary procedures. Competitive moves center on M&A consolidation to absorb EU MDR compliance costs and vertical integration into titanium alloy sourcing to offset raw material volatility.
Among US-based diversified manufacturers, Stryker Corporation and Zimmer Biomet occupy positions reflecting contrasting channel strategies. Stryker exemplifies the ASC-integrated archetype through outpatient surgery network relationships, while Zimmer Biomet represents specialized portfolio concentration in foot-and-ankle segments. Arthrex, Inc. anchors the arthroscopy bundling tier, its position reflecting instrument-implant combination offerings that reduce ASC operational complexity. These three firms collectively illustrate how procurement channel bifurcation between hospitals and ambulatory surgical centers shapes competitive positioning.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet |
| DePuy Synthes Companies |
| Smith & Nephew PLC |
| Arthrex, Inc. |
| Acumed LLC |
| DJO Global, Inc. |
| Orthofix US LLC |
| Paragon 28 |
| Others |
Cost & Logistics Intelligence
Magnesium-based bioresorbable screws displacing titanium hardware in pediatric scaphoid fixation simultaneously shift sourcing geography toward Japanese and German precision foundries while compressing long-term pricing power for traditional alloy producers. This substitution dynamic reconfigures procurement economics as surgeons eliminate secondary removal procedures.
Pricing Analysis
Volume-discount tiering structures separate premium titanium arthroplasty systems from standard stainless steel trauma plates and economy-grade contract-manufactured fixation hardware. Price differentiation hinges on CE marking tier under EU MDR and plasma-sprayed hydroxyapatite coating certification. Cost compression in standard plates intensifies because Russian and Ukrainian titanium sponge disruptions elevated raw material expenses. Hospital purchasing committees exhibit highest price sensitivity for commoditized trauma hardware, while ASCs prioritize operational efficiency over per-unit implant cost.
Supply Chain Analysis
Inventory lead times for Class III implantable devices extended to 12-18 months following EU MDR notified body capacity constraints. Supply concentrates in United States, Germany, and China for domestic plate and screw production, while Asian contract manufacturers feed export markets for intramedullary rods. Raw material dependencies center on titanium sponge, magnesium alloy feedstock, and polylactic acid polymer resins. Single-source vulnerability in Russian and Ukrainian titanium sponge creates structural risk. Distribution runs through specialized orthopedic distributors serving ASC networks and hospital supply chain departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in post-pandemic surgical volume recovery as deferred orthopedic procedures return to operating schedules. The cyclical driver is outpatient migration accelerating ASC construction and implant procurement channel bifurcation.
For Market Incumbents: Consolidate distribution relationships around captive ASC networks to offset hospital purchasing committee erosion. Acquire specialized foot-and-ankle portfolios to defend against arthroscopy bundling specialists. Prioritize EU MDR quality system investment to exploit notified body backlog advantages over undercapitalized competitors.
For New Entrants and Emerging Players: Differentiate on bioresorbable material science to capture pediatric and geriatric hardware elimination demand. Target German and Swiss orthopedic clinics for percutaneous fixation mini-fragment systems. Pursue China NMPA accelerated review pathways for innovative device status.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed arthroscopy specialists lacking implant manufacturing depth. Five-to-ten year viability hinges on ASC channel control and software-enabled surgical planning integration. Watch FDA 510(k) versus EU MDR registration divergence as geographic investment allocation signal.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Quality System Investment | Notified body backlog advantages concentrate market access among well-capitalized registrants. |
| ASC Distribution Partnership | Outpatient migration elevates surgery centers as implant procurement gatekeepers outside hospital supply chains. |
| Bioresorbable Material R&D | Magnesium and polymer development eliminates secondary removal surgeries in pediatric applications. |
| Software Companion Development | Patient-specific instrumentation raises ASPs while triggering EU AI Act surveillance obligations. |
| Reimbursement Strategy | German foot-and-ankle arthroplasty rates sustain above-average hardware utilization economics. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with orthopedic surgeons, hospital purchasing committee members, ASC administrators, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR notified body registration databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up implant volume modeling triangulated against top-down market sizing.
Across the analysis window, forecasts segmented by device type, material category, end-user channel, and application procedure. CAGRs derived from surgical volume elasticity to demographic aging, sports medicine incidence, and outpatient migration rates. Modeled inputs included ASC construction permit trajectories in Texas and Florida, EU notified body capacity constraints, and China NMPA priority review allocations.
Material uncertainties — titanium sponge supply disruption persistence, EU AI Act implementation scope, bioresorbable polymer degradation liability — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory timeline stability and surgical site-of-service reimbursement parity. Revision becomes warranted when ASC migration velocity or notified body capacity crosses threshold inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ultrasound Biometry Devices Market
Medical Devices
North America Ablation Devices Market
Medical Devices
Vaginal Applicators Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
Global Medical Device Cleaning Market
Medical Devices
North America Cardiac Rhythm Management Devices Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
Lactate Meter Market
Medical Devices
Global Thermoelectric Devices in Medical and Laboratory Offering Market
Medical Devices
Pectus Bar System Market
Medical Devices
Global Bone Cement Market
Medical Devices
Bovine Pericardial Valve Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
Global Catheter Stabilization Devices Market
Medical Devices
Elbow Fixation Systems Market