
 Medical Connector Market | 2026-2036
Medical Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Connector Market Outlook
The gap between premium sterilization-resistant connectors and commodity-grade alternatives is consolidating as OEMs demand validated supply chains. TE Connectivity Ltd. leverages its vertical integration in polymer science to sustain qualification timelines that smaller rivals cannot match. Amphenol Corporation anchors North American hospital procurement through dedicated cleanroom manufacturing capacity. Fischer Connectors differentiates via hermetic sealing expertise for implantable device applications.
Medical connectors are electromechanical interfaces engineered to maintain signal integrity and fluid containment under sterilization cycles exceeding 134 degrees Celsius, serving the critical function of linking disposable catheters, sensors, and surgical instruments to capital equipment. Disposable connectors lead volume shipments due to infection control protocols, while hybrid technology combining fiber optic and electrical channels captures expanding margin pools in robotic surgery platforms. Specialty connectors for MRI-compatible and defibrillator-proof applications occupy the fastest-growing niche as diagnostic equipment complexity rises.
FDA 21 CFR Part 820 quality system requirements, ISO 13485 medical device standards, and EU MDR conformity obligations collectively elevate barrier-to-entry for new connector suppliers while accelerating replacement demand for legacy designs. The EPA's emerging scrutiny of perfluorinated compounds in medical plastics is forcing material transitions that will reshape supplier qualifications over the next product cycle. Stakeholders must monitor which manufacturers secure early validation for alternative polymer platforms before OEMs lock in next-generation device architectures.
Market Dynamics
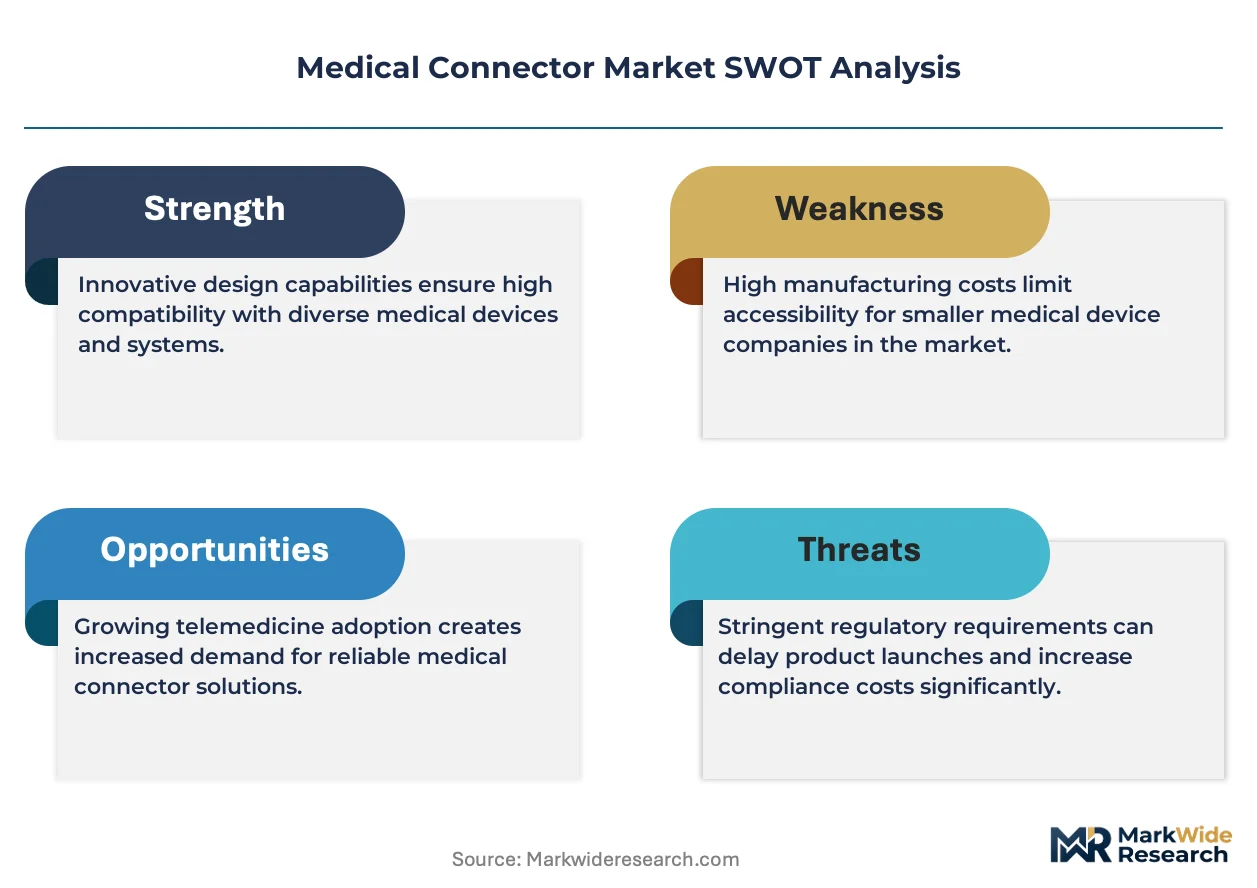
FDA 21 CFR Part 820 quality system mandates and EU MDR conformity obligations are compressing supplier qualification timelines while OEMs simultaneously demand validated sterilization-grade materials for next-generation device architectures.
Growth Catalysts
- Home healthcare expansion:Portable diagnostic equipment proliferation is pulling demand for lightweight, disposable connector solutions into ambulatory settings across the United States.
- ISO 13485 harmonization:Unified quality standards across device classes are reducing supplier audit burdens and accelerating cross-border procurement decisions.
- Robotic surgery platform integration:Hybrid fiber optic-electrical connectors are capturing premium positioning as capital equipment manufacturers consolidate vendor bases.
Market Restraints
- Specialty polymer supply concentration:High-performance thermoplastics for repeated autoclave cycles source predominantly from German and Swiss chemical suppliers, creating input vulnerability.
- EPA perfluorinated compound scrutiny:Emerging restrictions on PFAS in medical plastics are forcing premature material transitions before alternatives complete biocompatibility validation.
- Cleanroom manufacturing capex thresholds:ISO Class 7 certification requirements for sterilization-grade production exclude smaller molders from hospital procurement pools.
Strategic Opportunities
- India diagnostic device manufacturing:CDSCO streamlined approval pathways and PLI scheme incentives are attracting connector suppliers to co-locate with emerging OEM assembly operations.
- MRI-compatible connector niche:Non-ferrous material architectures for magnetic resonance environments remain underpenetrated relative to diagnostic equipment installation growth.
- Single-use surgical instrument convergence:Electromechanical-fluidic hybrid connectors for powered staplers and shavers represent white space as disposable instrument penetration deepens.
Industry Challenges
- Biocompatibility testing timeline compression:ISO 10993 cytotoxicity and sensitization protocols now extend 18-24 months, delaying product launches against compressed OEM design cycles.
- Legacy device obsolescence management:End-of-life notifications for established connector families force hospital supply chains into unplanned validation exercises for replacement sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Connector Market |
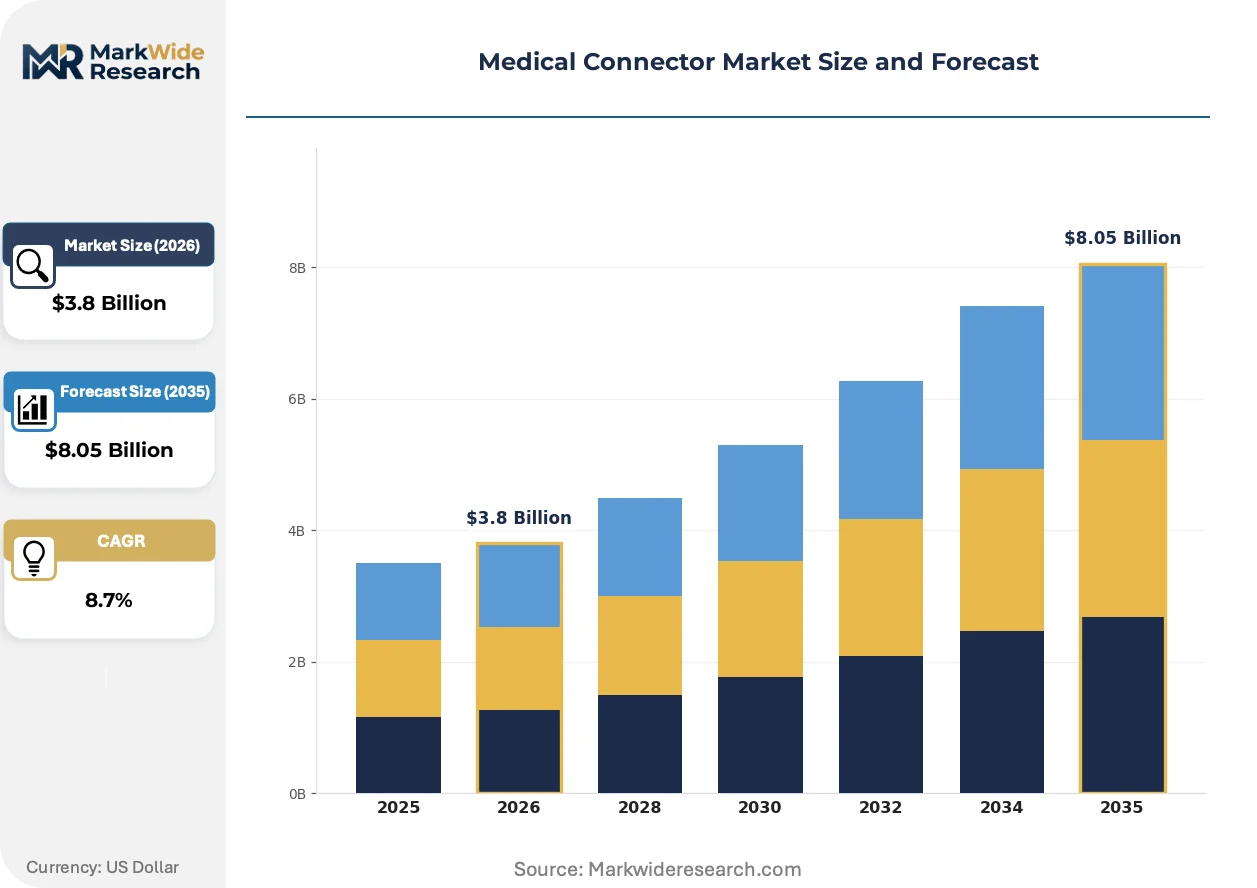
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Connectors, Reusable Connectors, Standard Connectors, Specialty Connectors Application: Infusion Therapy, Patient Monitoring, Diagnostic Equipment, Surgical Tools End User: Hospitals, Clinics, Research Laboratories, Home Healthcare Technology: Fiber Optic, Pneumatic, Electrical, Hybrid |
| Companies Covered | Amphenol Corporation, TE Connectivity Ltd., Smiths Interconnect, Fischer Connectors, Molex, ITT Interconnect Solutions, LEMO S.A., Samtec, ODU GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Connector Market Strategic Shifts
Material science breakthroughs and regulatory material bans are simultaneously expanding design possibilities and constraining supplier options across the connector value chain.
High-temperature liquid crystal polymers are expanding into implantable device applications where hermetic sealing and autoclave resilience must coexist. Cardiac rhythm management OEMs are qualifying these materials for lead connectors that withstand 500+ sterilization cycles. The shift is compressing traditional metal-to-polymer hybrid architectures into monolithic designs that reduce assembly steps.
EU MDR Article 10 technical documentation requirements are forcing connector suppliers to maintain clinical evaluation reports for accessories previously exempt under legacy directives. This regulatory burden is concentrating procurement toward suppliers with dedicated regulatory affairs functions. German device OEMs are responding by consolidating supplier panels to reduce audit overhead.
Hospital procurement teams are unbundling connector specifications from capital equipment service contracts, creating direct sourcing relationships with validated component suppliers. This disintermediation is most visible in United States academic medical centers where supply chain autonomy reduces OEM markup capture. Independent distributors with ISO 13485 certification are capturing this channel shift.
Medical Connector Market Segmentation
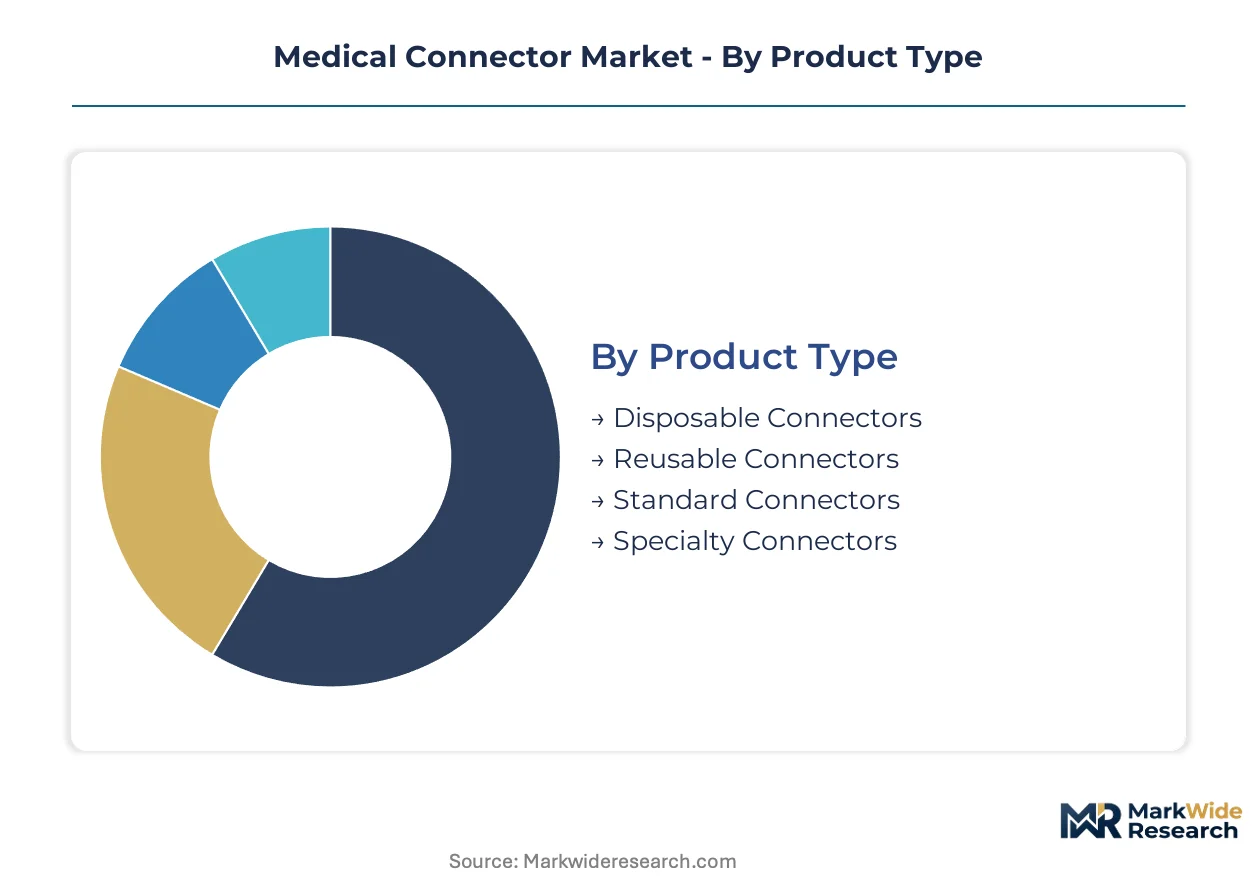
Medical connector procurement decisions pivot on sterilization cycles, signal integrity requirements, and end-use environmental constraints. Segmentation reveals how certification burdens concentrate in implantable and surgical applications while disposable alternatives dominate volume economics.
Product Type:
FDA 21 CFR Part 820 and ISO 13485 requirements intensify with connector reusability and implantation depth, creating tiered qualification barriers across this category.
- Disposable Connectors:Single-use polymer interfaces designed for infection control protocols in catheter and infusion applications. Demand concentrates in United States ambulatory surgery centers where single-use instrument penetration deepens fastest, driven by Joint Commission sterilization audit pressures.
- Specialty Connectors:MRI-compatible and defibrillator-proof architectures engineered from non-ferrous alloys and liquid crystal polymers. German cardiac rhythm management OEMs are qualifying these for lead connectors surviving 500+ autoclave cycles, displacing metal-to-polymer hybrid designs.
- Reusable Connectors:Autoclavable interfaces for capital equipment with validated cycle counts.
- Standard Connectors:Commodity-grade electromechanical interfaces for non-critical monitoring applications.
Leading the category by volume: Disposable Connectors. Growing fastest: Specialty Connectors.
Application:
Signal fidelity requirements and sterilization intensity separate high-margin surgical applications from monitoring segments where cost compression dominates.
- Surgical Tools:Electromechanical-fluidic hybrid connectors for powered staplers, shavers, and robotic instrument arms. United States academic medical centers are unbundling these specifications from OEM service contracts, creating direct procurement relationships with validated component suppliers.
- Diagnostic Equipment:Hybrid fiber optic-electrical channels for imaging and molecular diagnostic platforms. Japanese capital equipment manufacturers are consolidating vendor bases around suppliers with ISO Class 7 cleanroom certification.
- Infusion Therapy:Luer-lock and needleless connectors for drug delivery systems.
- Patient Monitoring:Low-density electrical interfaces for bedside and wearable sensors.
Highest margin capture: Surgical Tools. Steepest expansion trajectory: Diagnostic Equipment.
End User:
Procurement autonomy and validation infrastructure separate institutional buyers from distributed care settings with limited sterilization capacity.
- Hospitals:Centralized purchasing of sterilization-grade connectors with dedicated biocompatibility documentation. United States health systems are demanding EU MDR Article 10 technical files even for accessories, concentrating procurement toward suppliers with captive regulatory affairs functions.
- Home Healthcare:Lightweight, battery-compatible connectors for portable diagnostic and infusion devices. Demand is climbing across United States Medicare Advantage networks as remote patient monitoring reimbursement expands.
- Clinics:Cost-optimized disposable connectors for outpatient procedures.
- Research Laboratories:Custom-configured interfaces for preclinical device development.
Dominating procurement volume: Hospitals. Gaining share fastest: Home Healthcare.
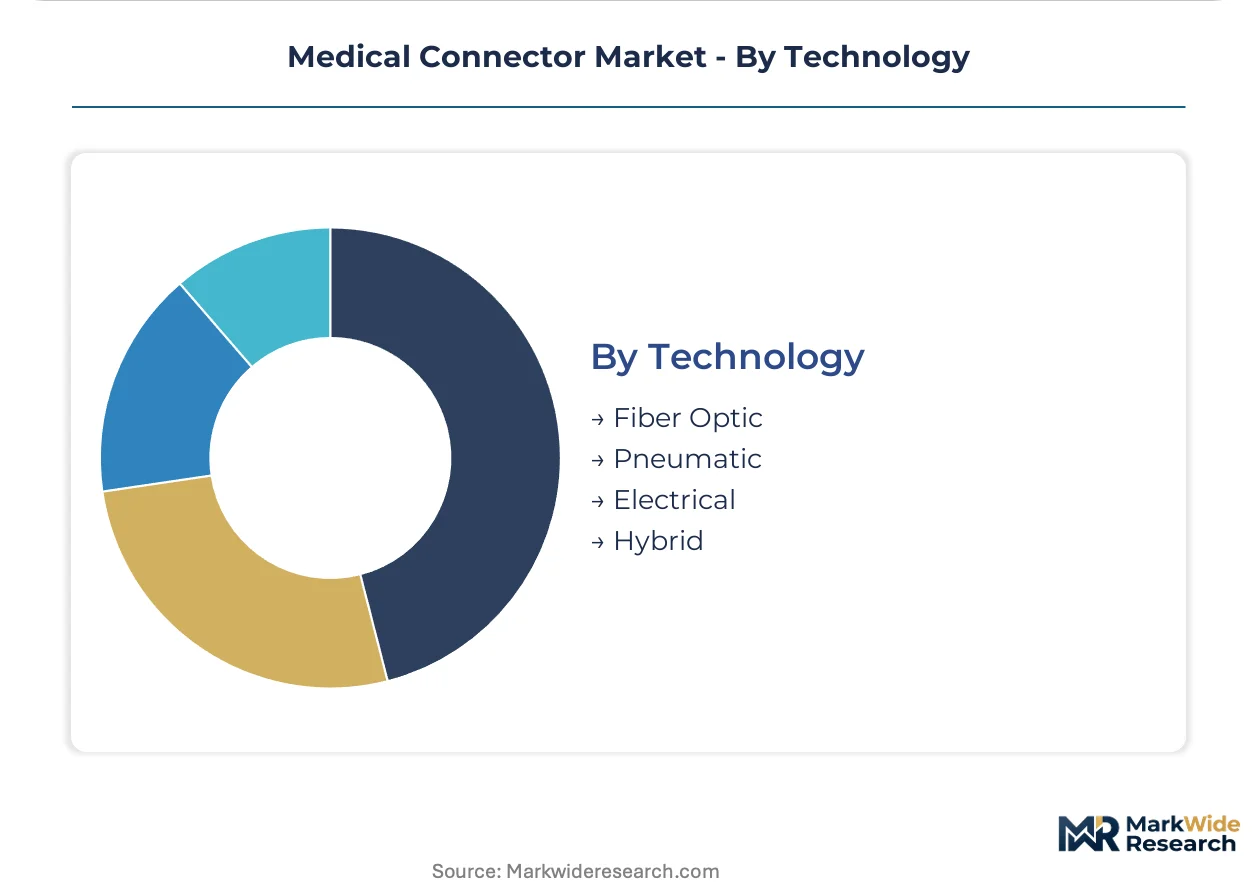
Technology:
Channel density and signal type determine material architectures and supplier qualification timelines across this dimension.
- Hybrid:Combined fiber optic and electrical channels for robotic surgery platforms and advanced imaging systems. Swiss precision engineering suppliers are capturing premium positioning as OEMs consolidate vendor bases around validated sterilization-grade material platforms.
- Fiber Optic:Silica-based light transmission for imaging and laser surgical applications with immunity to electromagnetic interference.
- Electrical:Copper-alloy signal and power transmission for standard monitoring and therapeutic devices.
- Pneumatic:Compressed air and vacuum interfaces for surgical instrumentation and fluid management systems.
Commanding premium positioning: Hybrid. Expanding most quickly: Fiber Optic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American medical connector procurement through its dense concentration of cardiac device OEMs and sterilization-grade component distributors.
United States
FDA 21 CFR Part 820 enforcement compresses supplier qualification timelines for Boston-area surgical robotics manufacturers. Academic medical centers in Philadelphia and Baltimore unbundle connector specifications from OEM service contracts, creating direct procurement channels with validated component suppliers. EPA scrutiny of PFAS compounds forces premature material transitions across Minnesota-based cardiac device supply chains.
Germany
EU MDR Article 10 technical documentation requirements concentrate procurement toward suppliers with captive regulatory affairs functions in Stuttgart and Munich. Freiburg's precision engineering cluster supplies high-performance thermoplastics for autoclave-resistant connector architectures. German cardiac rhythm management OEMs qualify liquid crystal polymer lead connectors surviving 500+ sterilization cycles.
Switzerland
Swissmedic device regulations align with EU MDR conformity obligations across Geneva and Basel manufacturing corridors. The Lake Geneva region hosts hermetic sealing specialists serving implantable device applications. Zurich-area precision suppliers capture premium positioning in hybrid fiber optic-electrical connector segments for robotic surgery platforms.
Japan
PMDA quality system mandates accelerate cross-border procurement decisions for Tokyo-based capital equipment manufacturers. Osaka's diagnostic imaging cluster consolidates vendor bases around suppliers with ISO Class 7 cleanroom certification. METI industrial policy supports domestic connector qualification for next-generation surgical instrument architectures.
India
CDSCO streamlined approval pathways attract connector suppliers to co-locate with emerging OEM assembly operations in Bengaluru and Hyderabad. PLI scheme incentives for diagnostic device manufacturing reshape supplier geography across Maharashtra's medical device parks. Mumbai-based distributors capture channel shifts as hospital procurement teams seek validated sterilization-grade materials.
Medical Connector Market Competitive Environment
Premium-margin players sit above commodity-margin players across sterilization-grade certification tiers, with FDA-validated suppliers commanding pricing separation from unqualified molders. The vendor base stratifies into three functional tiers: diversified interconnect conglomerates with polymer science capabilities, mid-scale specialists with dedicated cleanroom capacity, and regional molders serving non-critical monitoring applications. Dominant competitive moves include backward integration into specialty polymer compounding and geographic co-location with OEM assembly operations.
Within the diversified conglomerate tier, TE Connectivity Ltd. and Amphenol Corporation exemplify archetypes built on qualification timeline advantages and North American hospital procurement relationships respectively. Fischer Connectors occupies a position among hermetic sealing specialists serving implantable device applications. These three anchors represent distinct competitive vectors: polymer science verticalization, dedicated cleanroom manufacturing scale, and precision engineering specialization for extreme environment performance.
| Leading Market Players |
|---|
| Amphenol Corporation |
| TE Connectivity Ltd. |
| Smiths Interconnect |
| Fischer Connectors |
| Molex |
| ITT Interconnect Solutions |
| LEMO S.A. |
| Samtec |
| ODU GmbH & Co. KG |
| Others |
Value Chain & Pricing Dynamics
High-performance liquid crystal polymer feedstock indices cascade through medical connector value chains into three distinct certification-grade pricing tiers, with FDA-validated sterilization-grade materials commanding substantial premiums over commodity monitoring-grade alternatives. German and Swiss chemical suppliers anchor upstream pricing power, while OEM qualification timelines lock buyers into contracted supply relationships that resist spot-market arbitrage.
Pricing Analysis
Validated sterilization cycle counts serve as the primary value-based pricing anchor, with connectors qualified for 500+ autoclave cycles capturing premium positioning against single-use disposable alternatives. Price differentiation rests on ISO 13485 certification tier and cleanroom manufacturing grade, with hospital procurement teams demanding EU MDR Article 10 technical documentation as a non-negotiable threshold. Cost compression intensifies in standard monitoring-grade segments as Asian molders enter non-critical applications. Ambulatory surgery centers exhibit highest price sensitivity due to Joint Commission audit pressures, while cardiac rhythm management OEMs remain least sensitive given implantable device liability exposure.
Supply Chain Analysis
Dual-sourcing mandates from United States hospital procurement teams and German device OEMs force qualification of secondary suppliers across all sterilization-grade material categories. Supply concentrates in Germany, Switzerland, and Japan for high-performance thermoplastics, liquid crystal polymers, and precision-machined hermetic sealing components. Raw material dependencies include specialty polymer resins, non-ferrous alloys for MRI compatibility, and medical-grade silicone overmolding compounds. Single-source vulnerability concentrates in Freiburg-area polymer compounding and Lake Geneva hermetic sealing expertise. Distribution runs through ISO 13485-certified independent distributors capturing disintermediation from academic medical center direct sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EPA perfluorinated compound restrictions and compressed biocompatibility testing timelines force sub-scale molders toward exit or acquisition.
For Market Incumbents: Deepen backward integration into specialty polymer compounding to secure qualification timelines that smaller rivals cannot match against emerging PFAS material transitions. Expand captive regulatory affairs capacity to capture hospital procurement consolidation toward suppliers with dedicated EU MDR technical documentation functions. Defend against Asian molder encroachment in monitoring-grade segments by locking academic medical centers into direct sourcing contracts. For New Entrants and Emerging Players: Begin with India diagnostic device manufacturing corridors where CDSCO streamlined approvals and PLI scheme incentives reduce qualification barriers for sterilization-grade suppliers. Target MRI-compatible connector architectures as the most penetrable niche, with diagnostic equipment installation growth outpacing qualified non-ferrous material supply. Pursue co-location partnerships with emerging OEM assembly operations in Bengaluru and Hyderabad to bypass established distributor channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale specialists with ISO Class 7 cleanroom certification and captive regulatory affairs functions in Germany and Switzerland as material transition costs peak. Long-term viability over the next product cycle hinges on early validation for alternative polymer platforms before OEMs lock next-generation device architectures. Monitor which suppliers secure FDA pre-submission feedback on PFAS-free material qualifications as the primary inflection signal for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates market entry for sterilization-grade connector platforms in cardiac and surgical applications. |
| EU MDR Technical Documentation Investment | Captures procurement consolidation from German OEMs demanding captive regulatory affairs capacity. |
| Hospital System Direct Sourcing Partnership | Secures channel position as United States academic medical centers unbundle from OEM service contracts. |
| Specialty Polymer Backward Integration | Protects margin structure against German and Swiss chemical supplier pricing power in high-performance thermoplastics. |
| India Manufacturing Co-location | Aligns with CDSCO regulatory streamlining and PLI scheme incentives reshaping supplier geography. |
Study Parameters
Multi-period observation of FDA 510(k) clearance trajectories, ISO 13485 certification expansions, and hospital procurement contract awards anchored the trend analysis, supplemented by interviews with biomedical engineers, GPO contracts managers, hospital purchasing committee chairs, and regulatory affairs directors at cardiac device OEMs. Secondary validation drew from FDA 21 CFR Part 820 enforcement actions, EU MDR Article 10 technical documentation databases, CMS Medicare reimbursement schedules for remote patient monitoring, and hospital procurement databases tracking connector specification unbundling. Bottom-up demand modeling across end-user segments triangulated against top-down polymer consumption estimates from German and Swiss chemical suppliers.
Input-output matrices mapped sterilization cycle requirements to material cost structures across disposable, reusable, and implantable connector architectures over the projection horizon. Segmentation dimensions modeled included product type, application intensity, end-user procurement autonomy, and technology channel density. CAGRs were derived from regression analysis of historical qualification timelines against OEM design cycle compression. Industry-specific forecast inputs incorporated EPA PFAS regulatory trajectory scenarios and PMDA quality system harmonization progress.
EPA material ban acceleration, EU MDR audit backlog resolution, and OEM vendor base consolidation velocity are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding sterilization-grade material substitution timelines and hospital procurement autonomy expansion. A model refresh is warranted upon material change in FDA alternative polymer platform validation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pressure Ulcer Detection Devices Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Asia-Pacific Manual Resuscitators Market
Medical Devices
Mediastinoscope Market
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Epistaxis Devices Market
Medical Devices
Medical Device Connectivity Market
Medical Devices
Cervical Fusion Market
Medical Devices
Global Amniocentesis Needle Market
Medical Devices
Europe Insulin Pumps Market
Medical Devices
Arteriovenous Fistula Devices Market
Medical Devices
Ultra-Large Volume Wearable Injectors Market
Medical Devices
Photopheresis Products Market
Medical Devices
Specimen Retrieval Market
Medical Devices
Global Robotic Wheelchairs Market
Medical Devices
Global Automatic Stair Climbing Wheelchair Market