
 Indwelling Pleural Catheters Market | 2026-2036
Indwelling Pleural Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Indwelling Pleural Catheters Market Analytics
Silicone-grade biocompatibility is reorganizing competitive positioning among indwelling pleural catheter manufacturers. Smiths Medical leverages its critical care heritage to sustain hospital channel dominance across North American markets. ConvaTec differentiates through advanced wound care adjacencies that extend its interventional portfolio into outpatient pleural management.
Indwelling pleural catheters are implantable, flexible drainage devices typically constructed from silicone or polyurethane with multi-fenestrated tips, designed for repeated aspiration of recurrent pleural effusions or pneumothoraces without repeated needle thoracentesis. Dual-lumen catheter configurations command premium positioning due to their simultaneous irrigation and drainage capabilities, while single-lumen variants occupy cost-sensitive hospital contracts. Home care settings represent the fastest-growing end-user channel as payors shift reimbursement toward outpatient palliative protocols.
The FDA's 510(k) clearance framework governs market entry for these Class II devices, while ISO 13485 quality management standards shape manufacturing compliance across supplier bases. The European Medical Device Regulation imposes strengthened clinical evidence requirements that filter marginal competitors from EU market access. Stakeholders must monitor reimbursement policy divergence between institutional and home-based pleural drainage as this split determines portfolio investment priority.
Market Dynamics
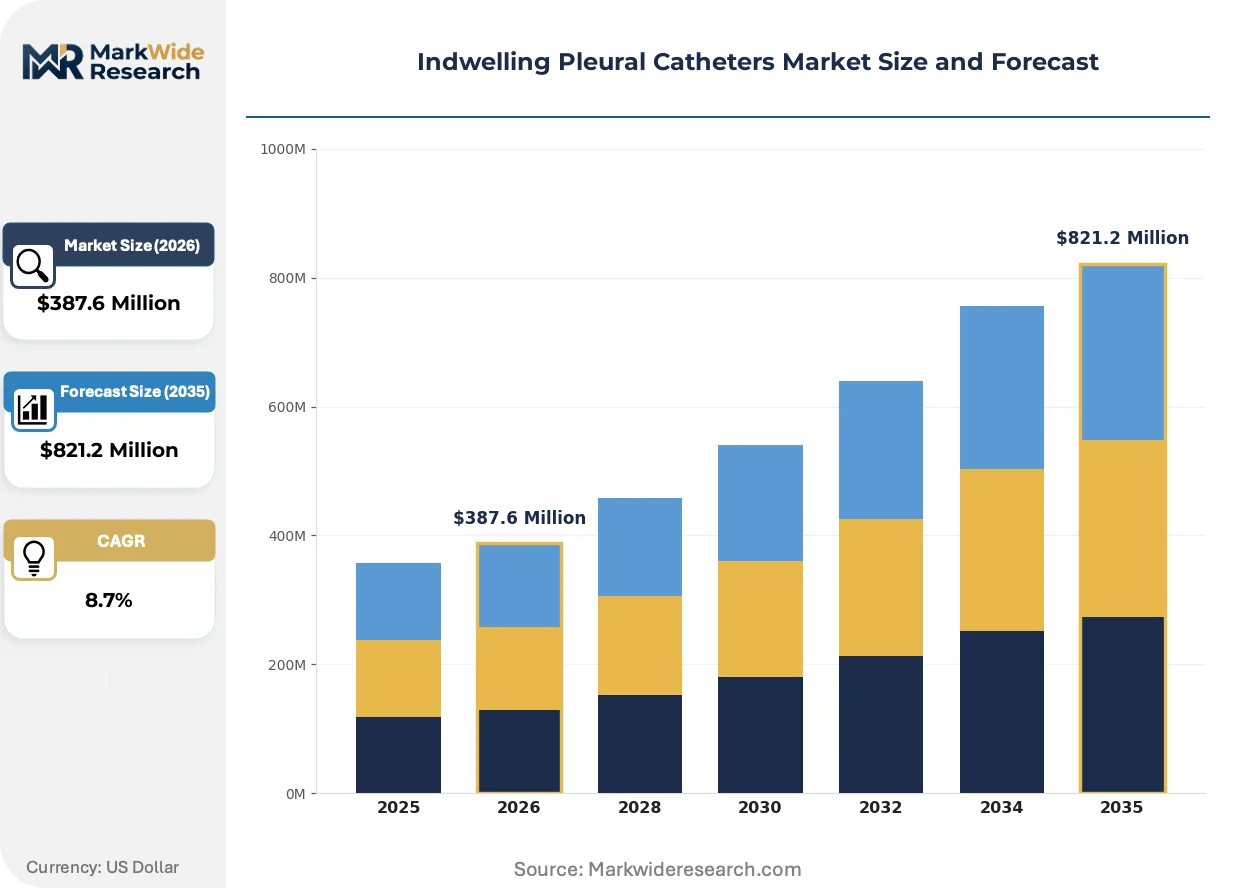
The shift toward home-based palliative care is restructuring demand patterns for indwelling pleural catheters, forcing manufacturers to redesign products for patient self-management while maintaining clinical safety thresholds.
Growth Catalysts
- Medicare reimbursement expansion:CMS coverage for home pleural drainage procedures under outpatient palliative protocols removes financial barriers for terminal cancer patients. Hospital discharge planners increasingly prioritize tunneled catheter placement over repeated thoracentesis.
- Silicone biocompatibility advances:Medical-grade silicone formulations with reduced protein adhesion properties extend indwelling duration and lower infection rates. Manufacturers leverage these material improvements to differentiate premium catheter portfolios.
- Aging demographics in developed markets:The United States, Japan, and Germany exhibit rising malignant pleural effusion incidence correlated with lung cancer and mesothelioma prevalence. Palliative intervention volumes track directly with oncology burden in these populations.
Market Restraints
- Medical-grade silicone supply concentration:Specialty silicone feedstock production concentrates among a limited supplier base in Germany and the United States. Input cost volatility constrains margin flexibility for catheter manufacturers.
- European Medical Device Regulation compliance burden:MDR clinical evidence requirements impose multi-year certification timelines and substantial documentation costs. Marginal competitors exit rather than absorb these fixed compliance investments.
- Thoracentesis as established substitute:Ultrasound-guided needle aspiration remains the first-line intervention for many clinicians despite recurrence limitations. Institutional habit and lower procedural cost sustain this alternative.
Strategic Opportunities
- Underpenetrated outpatient oncology networks:Community cancer centers in the United States lack dedicated interventional pulmonology services. Manufacturers can deploy clinical specialist teams to train community physicians on catheter placement protocols.
- Dual-lumen irrigation-drainage convergence:Combining tunneled drainage with intrapleural fibrinolytic administration addresses complex multiloculated effusions. This configuration commands premium positioning in tertiary care contracts.
- Remote monitoring integration:Bluetooth-enabled drainage measurement systems allow clinicians to track home-based output without clinic visits. Payers in Germany and the Netherlands pilot reimbursement for these connected care models.
Industry Challenges
- Interventional pulmonology training pipeline:Fellowship programs produce insufficient specialists to meet rising procedure demand. Community hospitals struggle to staff catheter placement services.
- ISO 13485 quality management system maintenance:Annual surveillance audits and corrective action documentation consume substantial regulatory affairs resources. Smaller manufacturers face disproportionate overhead.
- Legacy electronic health record integration:Home drainage documentation workflows lack standardized interoperability with hospital information systems. Data fragmentation complicates outcome tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indwelling Pleural Catheters Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-lumen Catheters, Dual-lumen Catheters, Biopsy Catheters, Drainage Catheters Application: Pneumothorax Treatment, Pleural Effusion Management, Cancer Treatment, Thoracentesis End User: Hospitals, Ambulatory Surgical Centers, Home Care Settings, Specialty Clinics Material: Silicone, PVC, Polyurethane, Others |
| Companies Covered | ConvaTec, Smiths Medical, Becton, Dickinson and Company, Cardinal Health, Rocket Medical, Teleflex Incorporated, Coloplast, Medtronic, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indwelling Pleural Catheters Market Evolving Landscape
Material science breakthroughs and regulatory harmonization efforts are converging to redefine product specifications and commercial models across the indwelling pleural catheter sector.
Antimicrobial-impregnated silicone formulations are supplanting standard medical-grade silicone in premium catheter segments. Tertiary care centers in the United States and Germany adopt these surfaces to reduce tunnel tract infections in immunocompromised oncology patients. This transition compresses addressable market share for conventional uncoated devices while elevating manufacturing complexity and regulatory filing requirements.
The European Medical Device Regulation's strengthened clinical evidence mandates filter marginal competitors from EU market access. Manufacturers must now submit prospective safety data rather than predicate-device equivalence for 510(k)-cleared products. This regulatory friction disproportionately affects single-product firms lacking dedicated clinical affairs infrastructure, consolidating competitive position among established multi-portfolio players.
Patient-directed procurement models disrupt traditional hospital-centered distribution channels. Home health agencies in the United States now contract directly with manufacturers for drainage kits and replacement valves, bypassing institutional purchasing intermediaries. This channel disintermediation concentrates in Medicare Advantage populations where capitated payments incentivize cost-efficient outpatient management.
Indwelling Pleural Catheters Market Segmentation
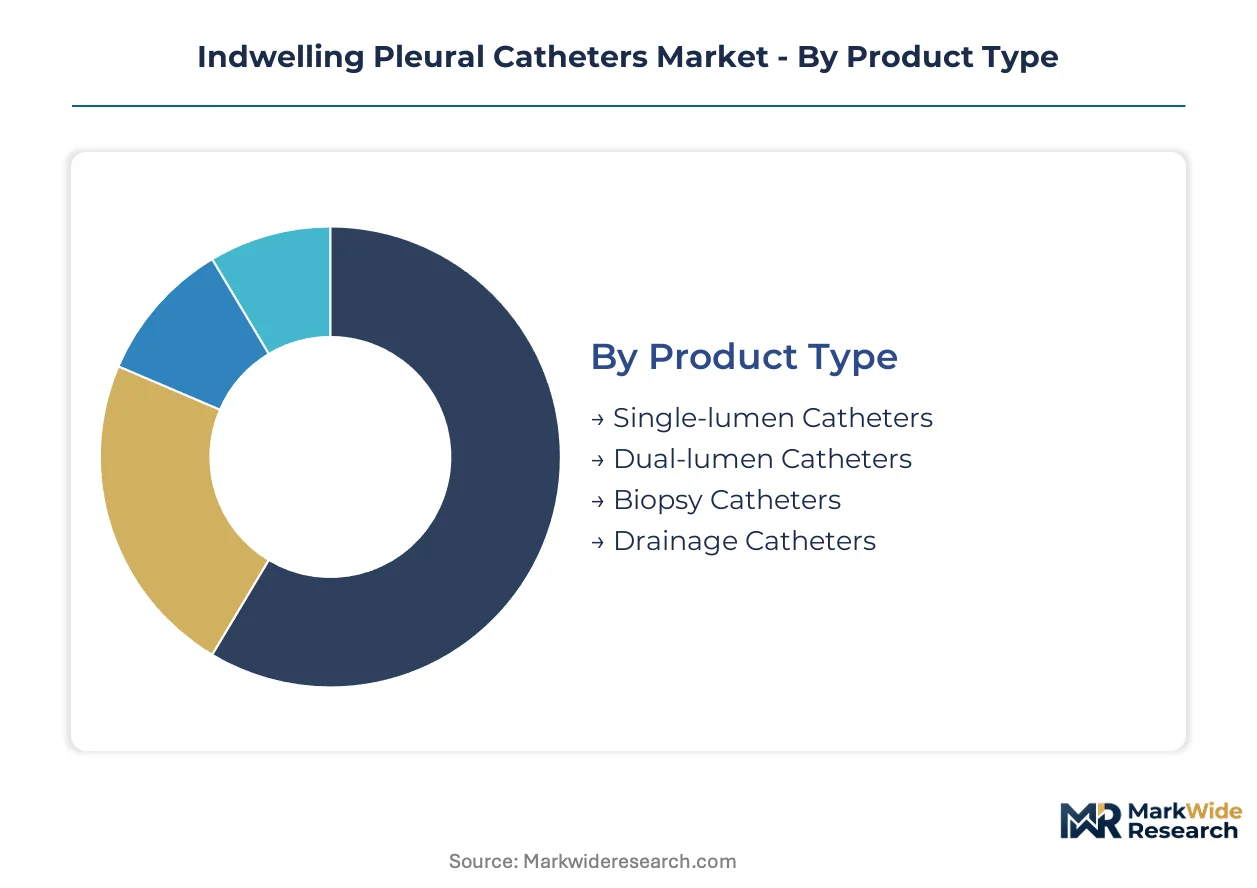
Segmentation in the indwelling pleural catheter market reveals how product specifications, clinical applications, and care delivery sites interact to determine procurement patterns. Manufacturers must align portfolio design with the divergent requirements of institutional purchasers versus home health agencies.
Product Type:
Channel distribution varies sharply by lumen configuration, with dual-lumen devices concentrated in tertiary hospital contracts while single-lumen variants flow through home health distributors.
- Single-lumen Catheters:These devices incorporate a single drainage channel with multi-fenestrated silicone tips for recurrent aspiration. Demand concentrates in Medicare-reimbursed home care programs across the United States, where cost efficiency and patient self-management capability drive selection over clinical sophistication.
- Dual-lumen Catheters:Separate irrigation and drainage lumens enable simultaneous fluid instillation and evacuation. Tertiary oncology centers in Germany and the United States specify these configurations for complex multiloculated effusions, commanding premium positioning in interventional pulmonology contracts.
- Biopsy Catheters:Integrated tissue sampling channels allow diagnostic procurement during drainage procedures.
- Drainage Catheters:General-purpose evacuation devices serve non-specialized pleural interventions across community hospital settings.
By volume, single-lumen catheters lead due to home care expansion. By growth pace, dual-lumen configurations are expanding most quickly as interventional complexity rises.
Application:
Reimbursement intensity and procedure setting diverge across clinical indications, with palliative applications shifting outpatient while acute interventions remain hospitalized.
- Pleural Effusion Management:Tunneled catheter placement for recurrent malignant effusions constitutes the dominant procedure category. The United States and Japan exhibit concentrated demand as lung cancer incidence tracks with aging demographics, while CMS outpatient palliative protocols accelerate home-based adoption.
- Pneumothorax Treatment:Persistent air leaks requiring prolonged drainage drive catheterization in thoracic surgery services. German pneumology departments favor tunneled solutions over chest tube alternatives for prolonged cases, supported by statutory health insurance coverage for extended indwelling duration.
- Cancer Treatment:Oncologic pleural interventions span diagnostic and palliative intents across combined modality programs.
- Thoracentesis:Catheter-based alternatives to needle aspiration address recurrence-prone presentations in interventional radiology.
Pleural effusion management commands the largest procedure volume. Pneumothorax treatment is gaining share fastest as thoracic surgeons adopt catheter-based protocols.
End User:
Procurement authority and technical specification requirements fragment across institutional hierarchies versus decentralized home health purchasing.
- Hospitals:Integrated delivery networks and academic medical centers wield centralized purchasing power over high-volume catheter contracts. The United States exhibits concentration in IDN-affiliated oncology services, where standardization committees enforce dual-source policies for interventional devices.
- Home Care Settings:Medicare Advantage capitation and hospice benefit redesign redirect pleural drainage from institutional to residential settings. Home health agencies in Florida, California, and Texas now contract directly with manufacturers for drainage kits, bypassing hospital distribution intermediaries.
- Ambulatory Surgical Centers:Freestanding interventional suites perform catheter placement under local anesthesia for select candidates.
- Specialty Clinics:Pulmonology and oncology-focused practices manage catheter maintenance and complication triage.
Hospitals retain the highest absolute procurement value. Home care settings are climbing the fastest as reimbursement shifts toward outpatient palliative models.
Material:
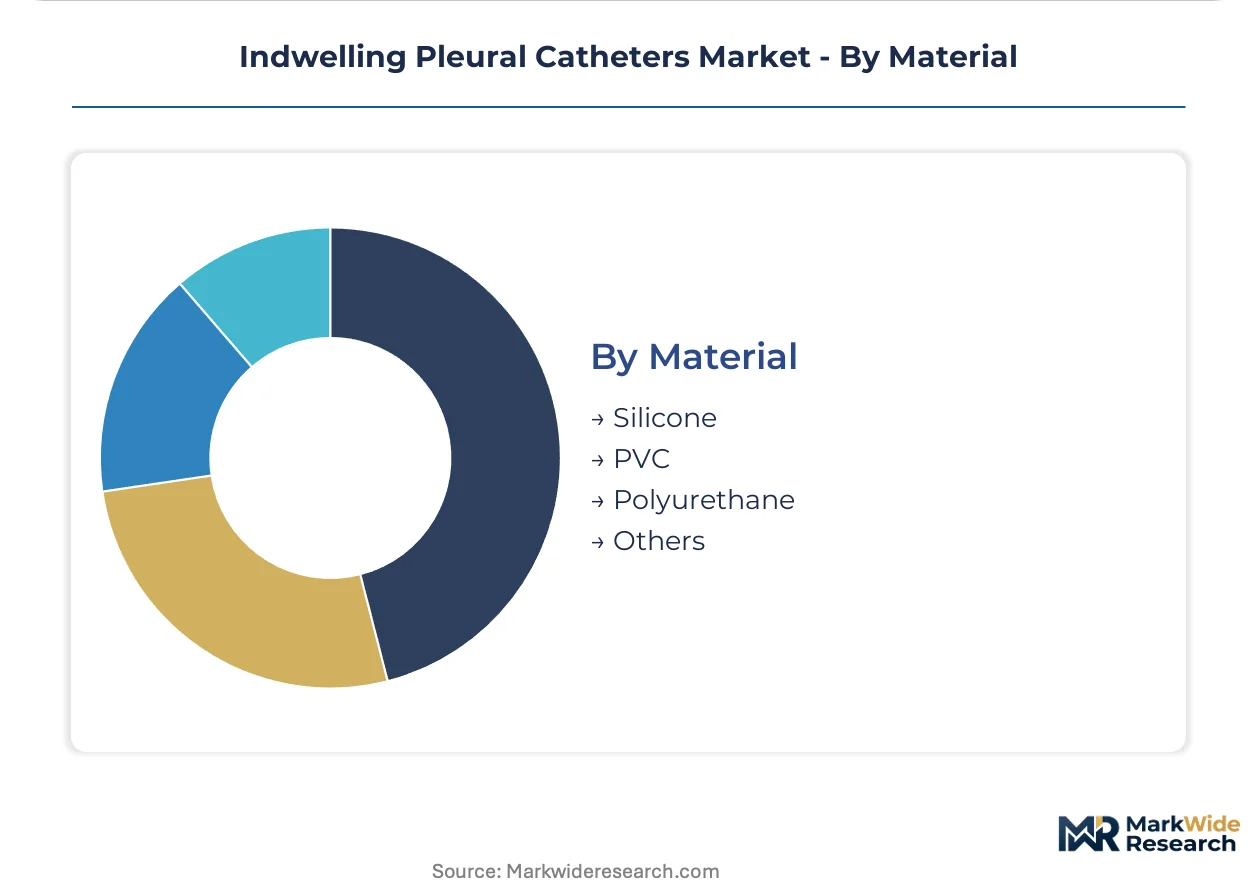
Biocompatibility certification tiers and supply chain concentration shape cost structures and regulatory filing requirements across substrate categories.
- Silicone:Medical-grade formulations with reduced protein adhesion dominate premium segments. FDA-cleared antimicrobial-impregnated variants from German and United States feedstock suppliers command price premiums in immunocompromised patient populations.
- Polyurethane:Higher tensile strength enables thinner wall construction for large-bore drainage. Japanese and German manufacturers specify these substrates for percutaneous insertion force reduction in outpatient protocols.
- PVC:Cost-sensitive applications in emerging markets utilize plasticized formulations with shorter indicated dwell times.
- Others:Experimental substrates including hydrogel coatings and bioabsorbable matrices remain pre-commercial.
Silicone leads by installed base and revenue contribution. Polyurethane is expanding most quickly as manufacturers optimize for insertion ergonomics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in indwelling pleural catheters favor manufacturing concentration in Germany and the United States, with finished devices shipped to deficit markets in Japan and Australia. Specialty silicone feedstock moves from German chemical clusters to catheter fabrication sites across North America. Reimbursement policy divergence between statutory health insurance and private payor systems shapes regional demand intensity.
United States
Medicare Advantage capitation and CMS outpatient palliative protocols accelerate home-based catheter adoption. FDA 510(k) clearance requirements govern Class II device market entry, with antimicrobial-impregnated variants facing heightened scrutiny. Minnesota and Massachusetts host concentrated manufacturing operations serving integrated delivery networks.
Germany
Statutory health insurance coverage for extended indwelling duration supports premium dual-lumen catheter procurement. EU Medical Device Regulation clinical evidence mandates filter marginal competitors from market access. Baden-Württemberg and Bavaria anchor specialty silicone feedstock production feeding catheter fabricators.
Japan
Aging demographics and lung cancer incidence drive malignant pleural effusion intervention volumes. PMDA regulatory timelines extend market entry for foreign manufacturers relative to domestic incumbents. Tokyo and Osaka medical centers concentrate interventional pulmonology expertise and catheter placement capacity.
United Kingdom
NHS England cancer strategy prioritizes outpatient palliative interventions to reduce hospital bed utilization. MHRA post-Brexit regulatory autonomy diverges from EU MDR implementation timelines. London and Manchester academic medical centers standardize tunneled catheter protocols across regional oncology networks.
Australia
Public hospital procurement concentrates catheter demand through state-based health service agreements. TGA conformity assessment requirements align with ISO 13485 quality management standards. Sydney and Melbourne thoracic surgery services drive adoption of catheter-based pneumothorax management.
Indwelling Pleural Catheters Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capacity and clinical affairs infrastructure. The vendor base stratifies into multi-portfolio conglomerates with dedicated interventional divisions and single-product firms dependent on contract manufacturing. Three archetypes dominate: critical care heritage players leveraging hospital channel relationships, wound care adjacency specialists extending into outpatient drainage, and diversified medtech conglomerates absorbing catheter lines within broader portfolios. Competitive moves concentrate on M&A absorption of catheter-specific clinical data assets and vertical integration into antimicrobial silicone coating capabilities.
Among diversified medtech conglomerates, Becton, Dickinson and Company and Medtronic occupy positions shaped by interventional portfolio breadth rather than catheter-specific focus. Teleflex Incorporated exemplifies the critical care heritage archetype, with Smiths Medical representing similar channel dominance patterns. ConvaTec sits within the wound care adjacency tier, leveraging ostomy and advanced wound management infrastructure toward outpatient pleural drainage. Cardinal Health and Cook Medical anchor distribution and interventional radiology positioning respectively, while Coloplast and Rocket Medical represent European-origin specialists with regional market concentration.
| Leading Market Players |
|---|
| ConvaTec |
| Smiths Medical |
| Becton, Dickinson and Company |
| Cardinal Health |
| Rocket Medical |
| Teleflex Incorporated |
| Coloplast |
| Medtronic |
| Cook Medical |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between catheter manufacturers and German silicone feedstock suppliers lock in both raw material access and multi-year price visibility, insulating production costs from spot market volatility while constraining margin flexibility for non-integrated competitors.
Pricing Analysis
Industrial OEM buyers anchor hospital system contracts, where three-tier pricing structure across premium, standard, and economy levels stratifies by antimicrobial coating certification and lumen complexity. Price differentiation hinges on FDA 510(k) clearance tier and volume scale commitments. Cost compression in single-lumen segments is intensifying because home health agencies negotiate direct procurement bypassing distributor markups. Community cancer centers exhibit highest price sensitivity; tertiary oncology networks prioritize clinical performance over unit cost.
Supply Chain Analysis
Specialty silicone polymer production in Baden-Württemberg and Bavaria underwrites catheter biocompatibility standards across North American and European fabrication facilities. Medical-grade silicone feedstock draws from German chemical clusters and United States specialty manufacturers, with polyurethane alternatives sourced from Japanese and South Korean resin suppliers. Single-source vulnerability concentrates in antimicrobial coating precursor supply. Distribution runs through integrated delivery network central procurement offices for hospital channels, while home health agencies contract directly with manufacturers for drainage kit fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drainage kit subscription services and remote monitoring data layers are expanding faster than hardware unit sales, transforming catheter economics from episodic device procurement toward recurring revenue relationships.
For Market Incumbents: Fortify antimicrobial silicone coating capabilities through backward integration into German feedstock suppliers or captive coating facilities, defending against emerging entrants with materials science differentiation. Secure hospital system partnership exclusivity by embedding clinical specialist training teams within interventional pulmonology fellowship programs, raising switching costs for competitor displacement. For New Entrants and Emerging Players: Lead with Bluetooth-enabled drainage measurement systems targeting Medicare Advantage capitated contracts in Florida and Texas, where remote monitoring reimbursement pilots create white-space access. Community cancer centers lacking dedicated interventional pulmonology services represent the most penetrable segment; deploy physician training programs as the primary go-to-market mechanism rather than device pricing alone. For Investors and Strategic Acquirers: Single-product catheter firms with ISO 13485 certification infrastructure and established CMS reimbursement codes present attractive acquisition targets as EU MDR compliance costs force exit decisions. Long-term viability frames around home care channel expansion rather than hospital volume capture. Watch for CMS outpatient palliative protocol expansion signals as inflection indicators for remote monitoring reimbursement scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Development | FDA 510(k) clearance for impregnated silicone variants commands premium positioning in immunocompromised patient segments. |
| Home Health Direct Contracting | Medicare Advantage capitation models in Florida and Texas enable margin capture bypassing hospital distribution intermediaries. |
| Interventional Pulmonology Training Programs | Fellowship partnerships at academic medical centers embed catheter protocols and raise competitive switching costs. |
| Remote Monitoring Platform Integration | Bluetooth drainage measurement systems align with German and Dutch payer pilots for connected care reimbursement. |
| EU MDR Clinical Evidence Investment | Prospective safety data submissions filter marginal competitors and consolidate position among multi-portfolio players. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with interventional pulmonologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR submission trackers. Bottom-up procedure volume estimates triangulated with top-down manufacturer revenue assessments across the analysis window.
Across the projection horizon, the analytical framework modeled lumen configuration, clinical application, care delivery site, and material substrate as core segmentation dimensions. CAGRs derived from procedure volume trajectories correlated with oncology burden demographics and reimbursement policy evolution. Forecast inputs incorporated interventional pulmonology fellowship pipeline capacity and silicone feedstock supply elasticity.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways and EU MDR clinical evidence requirements; material policy shifts would require re-modeling. Specific risks include Medicare reimbursement contraction for home drainage procedures and specialty silicone supply disruption from German chemical cluster consolidation. Practitioners should keep alternative scenarios live as outpatient palliative protocol adoption rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ventilator Accessories Market
Medical Devices
Invisible Orthodontics Market
Medical Devices
Transcranial Doppler Ultrasounds System Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
Asia-Pacific Medical Suction Device Market
Medical Devices
Autosamplers Market
Medical Devices
High Frequency Ventilators Market
Medical Devices
United Kingdom Anesthesia Devices Market
Medical Devices
Brain Base Knife Package Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Pleural Catheters Market
Medical Devices
Asia-Pacific Breast Biopsy Market
Medical Devices
Spinal Stenosis Implant Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Implant Handpiece Market
Medical Devices
Brachytherapy Afterloaders Market