
 Otoscope Devices Market | 2026-2036
Otoscope Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Otoscope Devices Market Outlook
ENT specialist availability is collapsing across rural healthcare networks, forcing primary care physicians to absorb aural diagnostic workloads. Welch Allyn leverages its installed base of traditional otoscopes to transition clinics toward connected digital platforms. HEINE Optotechnik anchors European demand through precision-engineered fiber-optic instruments with superior illumination control. Olympus Corporation dominates hospital procurement channels with integrated video otoscopy systems that pair with electronic health record infrastructure.
An otoscope device is a handheld instrument designed for visual examination of the external auditory canal and tympanic membrane, typically incorporating a light source, magnifying lens, and speculum attachment with working distances of 15-30 centimeters. Digital otoscope variants now integrate CMOS sensors and wireless transmission modules to capture and share high-resolution ear canal imagery for remote consultation and documentation. Video otoscope systems command premium positioning in hospital settings where procedural documentation requirements drive capital expenditure, while wireless otoscope units represent the fastest-expanding segment as homecare and telemedicine platforms adopt patient-operated screening tools. Fiber-optic otoscopes retain substantial share in cost-sensitive clinic environments where durability and minimal maintenance outweigh connectivity demands.
FDA 510(k) clearance requirements shape product development timelines and clinical validation obligations for manufacturers targeting the United States market. EMA Medical Device Regulation (MDR) compliance and CE marking standards govern European market access, with particular scrutiny applied to software-enabled diagnostic functions. Japan's PMDA maintains distinct documentation requirements for optical medical devices that influence regional product configurations. Stakeholders must monitor evolving telehealth reimbursement codes and cross-border data governance frameworks as remote aural diagnostics expand beyond traditional clinical settings.
Market Dynamics
The migration of aural diagnostics from ENT specialists to primary care physicians is compressing otoscope functionality requirements while expanding total addressable volume across ambulatory networks.
Growth Catalysts
- Telehealth reimbursement expansion:CMS and private payers in the United States now compensate remote otoscopy consultations, accelerating deployment of wireless digital systems in rural health clinics.
- EMA MDR software scrutiny:European diagnostic device regulations now explicitly cover AI-enabled image analysis, creating compliance frameworks that legitimate premium digital otoscope positioning.
- Fiber-optic illumination advances:LED-fiber coupling technologies from German precision optics suppliers are extending instrument lifespan while reducing maintenance intervals in high-throughput clinic environments.
Market Restraints
- CMOS sensor supply concentration:Image sensor fabrication for digital otoscopes clusters among Taiwanese and South Korean foundries, exposing manufacturers to geopolitical supply disruption.
- Reimbursement code fragmentation:Inconsistent CPT coding for video otoscopy across US state Medicaid programs creates revenue recognition uncertainty for hospital procurement committees.
- Disposable speculum cost inflation:Polymer supply chain volatility has elevated single-use attachment costs to 15-20% of total procedure economics in high-volume pediatric settings.
Strategic Opportunities
- Homecare screening penetration:Direct-to-consumer wireless otoscope adoption in Japan's aging-in-place programs demonstrates viable patient-operated diagnostic workflows.
- AI-otoscopy convergence:Machine learning classification of tympanic membrane pathology is miniaturizing onto edge processors, enabling real-time diagnostic assistance without cloud dependency.
- School-based hearing screening mandates:State-level audiological examination requirements in US public education systems are institutionalizing annual otoscopic assessment protocols.
Industry Challenges
- Cross-platform EHR integration:Video otoscopy systems must support disparate electronic health record architectures, forcing manufacturers to maintain multiple software validation tracks.
- Clinical validation timelines:FDA 510(k) submissions for software-as-medical-device functionality require prospective studies that extend product launch schedules by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Otoscope Devices Market |
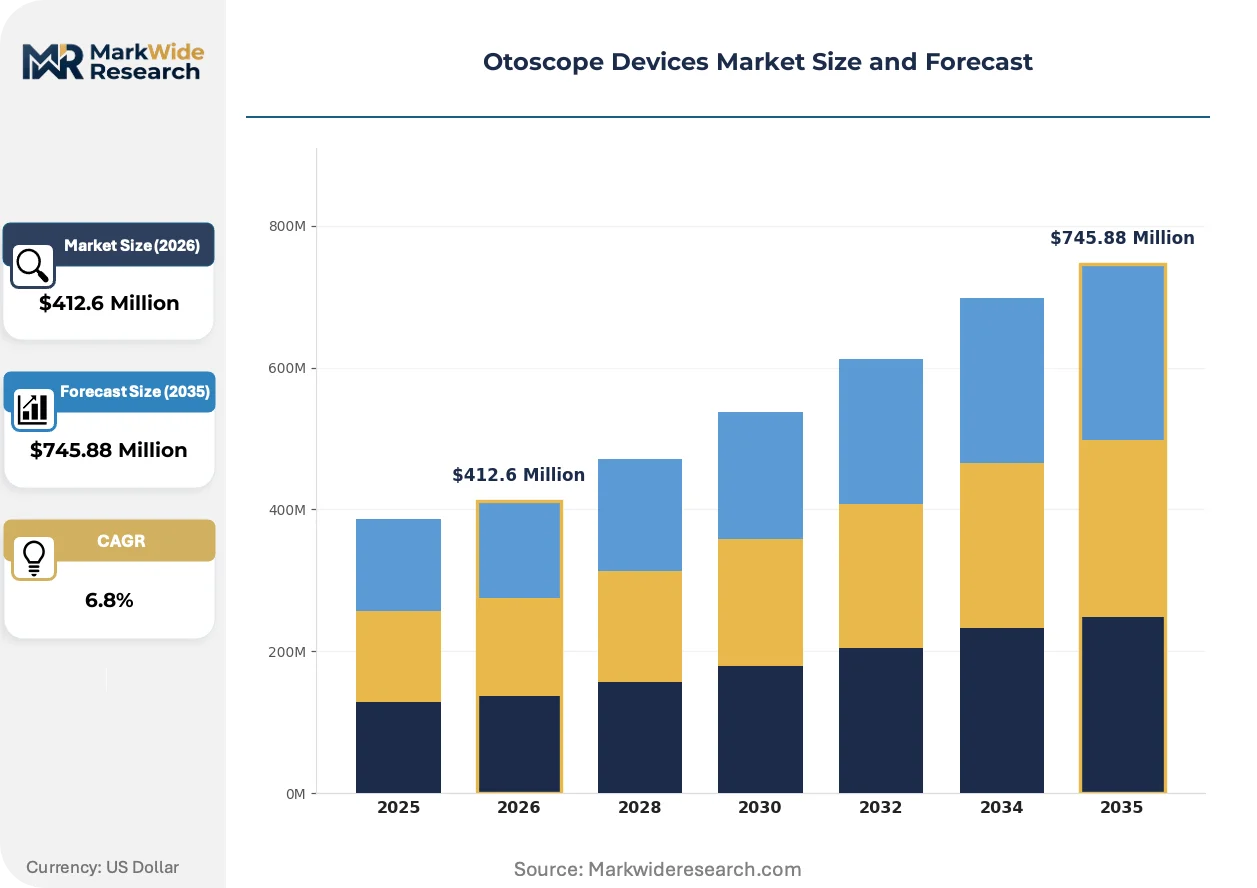
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Otoscope, Video Otoscope, Wireless Otoscope, Fiber-Optic Otoscope End User: Hospitals, Clinics, Homecare, Diagnostic Centers Technology: Optical Imaging, LED Lighting, Bluetooth Connectivity, High-Definition Imaging Application: Aural Examination, Ear Wax Removal, Diagnostic Procedures, Patient Education |
| Companies Covered | Rudolf Riester, Kirchner & Wilhelm, Welch Allyn, CellScope, Luxamed, HEINE Optotechnik, Olympus Corporation, Prestige Medical, American Diagnostic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Otoscope Devices Market Strategic Shifts
Digital otoscope architecture is bifurcating between hospital-grade video systems with full documentation suites and consumer-accessible wireless devices that feed telemedicine platforms.
CMOS sensor arrays with dedicated near-field optics are miniaturizing into handheld housings previously occupied by purely optical instruments. Primary care networks in Germany and Japan are deploying these compact digital units to extend diagnostic reach without specialist referral. The form factor compression is collapsing price differentiation between mid-tier clinic instruments and premium hospital systems.
FDA 510(k) clearance pathways for software-enabled otoscopy are tightening evidentiary standards for algorithm-assisted diagnostic claims. Manufacturers must now submit prospective clinical validation data rather than predicate device equivalence. This regulatory elevation favors established players with dedicated clinical affairs infrastructure while raising capital barriers for sensor-technology entrants targeting the US market.
Hospital procurement committees are unbundling video otoscope hardware from integrated software subscriptions. Buyers now demand à-la-carte pricing for image capture devices, cloud storage, and AI analysis modules. This disaggregation is most advanced in United States academic medical centers, where capital equipment committees operate independently from IT governance.
Otoscope Devices Market Segmentation
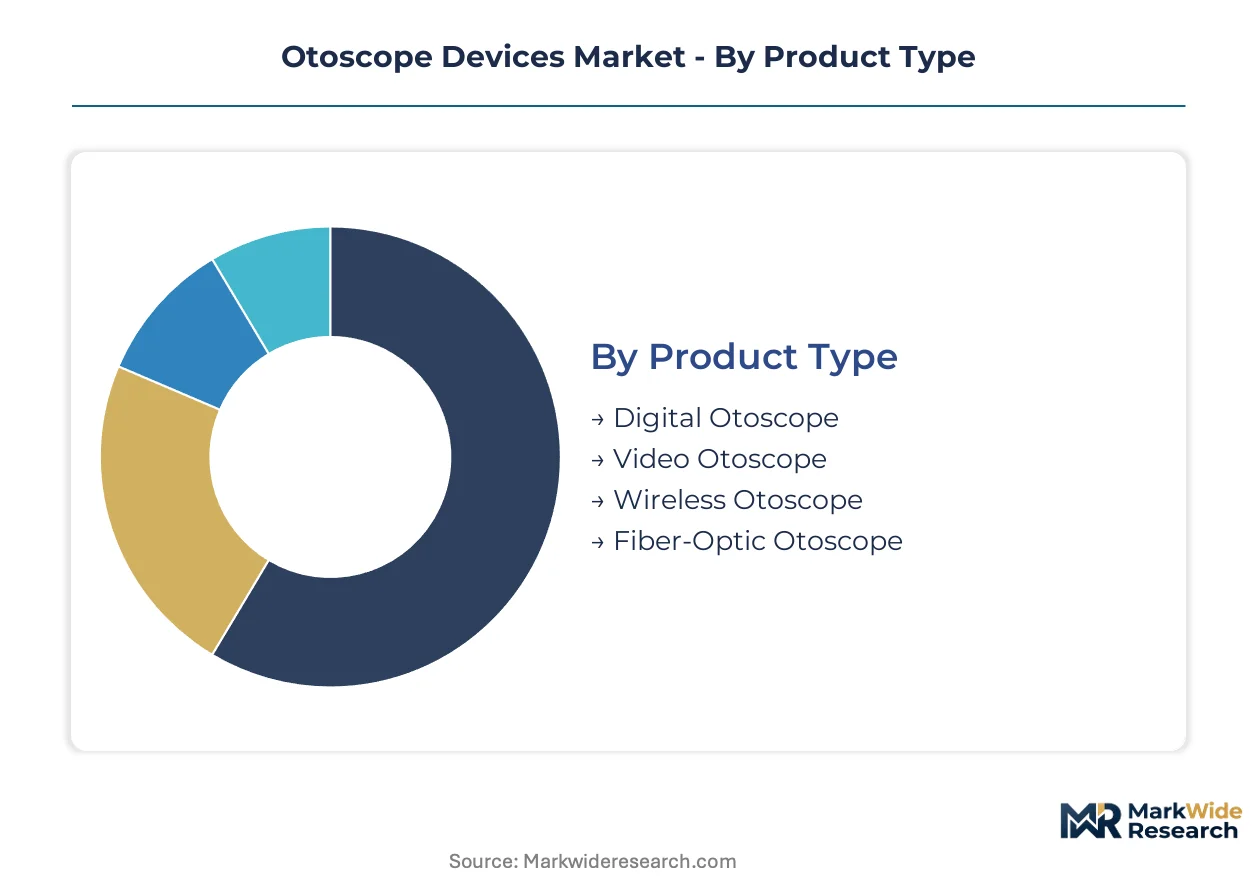
Otoscope device segmentation reveals divergent margin profiles across hardware architectures and care settings. Product type stratification separates capital-intensive hospital systems from high-volume disposable clinic instruments, while end-user fragmentation maps directly to reimbursement code availability and procurement authority.
Product Type:
Margin pools concentrate in video otoscope systems where bundled software subscriptions generate recurring revenue streams beyond hardware sales.
- Digital Otoscope:CMOS sensor-based handheld units capture 1280x720 to 1920x1080 resolution imagery with onboard storage and USB export. Primary care networks in Germany deploy these for same-day documentation without ENT referral, compressing diagnostic timelines while expanding billable encounters.
- Video Otoscope:Integrated camera-lens systems with dedicated monitors and EHR connectivity command premium positioning in hospital settings. Olympus Corporation and Welch Allyn dominate this tier through proprietary image management platforms that lock procurement committees into multi-year service contracts.
- Wireless Otoscope:Battery-powered units with WiFi/Bluetooth transmission to tablets or smartphones. Japan's aging-in-place programs and US rural telehealth initiatives drive volume expansion for patient-operated screening workflows.
- Fiber-Optic Otoscope:Halogen or LED-illuminated instruments with fiber light guides and no electronic components. HEINE Optotechnik anchors European demand through precision-engineered optics with 10-15 year service lifespans in cost-sensitive clinic environments.
The dominant share belongs to video otoscope systems, while wireless otoscope units are closing the gap fastest.
End User:
Procurement authority and reimbursement density determine profitability across care settings, with hospitals capturing the steepest price premiums.
- Hospitals:Academic medical centers and integrated delivery networks purchase video otoscopy suites with full documentation infrastructure. FDA 510(k) clearance for software-enabled diagnostic functions becomes a mandatory gating factor for vendor selection.
- Clinics:ENT specialty practices and primary care networks favor portable digital units with cloud connectivity. EMA MDR compliance requirements for software-as-medical-device functionality now extend to image storage and transmission modules.
- Homecare:Direct-to-consumer wireless devices bypass clinical procurement entirely. Japan's Ministry of Health, Labour and Welfare reimbursement codes for remote monitoring subsidize patient acquisition costs in metropolitan Tokyo and Osaka prefectures.
- Diagnostic Centers:High-throughput audiology and occupational health facilities prioritize fiber-optic durability over connectivity. Disposable speculum consumption drives recurring attachment revenue at 15-20% of total procedure economics.
Hospital procurement maintains the highest absolute margins, though clinic channel volume is expanding most rapidly.
Technology:
Component sophistication separates premium positioning from commodity competition, with imaging resolution and connectivity protocols as primary differentiation axes.
- Optical Imaging:Conventional lens-mirror systems with fixed magnification remain standard in pediatric and emergency settings where instrument durability outweighs documentation needs.
- LED Lighting:Solid-state illumination modules with 50,000-hour lifespans displace halogen bulbs across all product tiers. German precision optics suppliers dominate LED-fiber coupling technology.
- Bluetooth Connectivity:Low-energy wireless protocols enable real-time image transmission to EHR systems and telemedicine platforms. HIPAA compliance requirements shape US product configurations.
- High-Definition Imaging:1080p and emerging 4K sensor arrays with dedicated near-field optics. CMOS fabrication concentration in Taiwanese and South Korean foundries exposes supply chains to geopolitical disruption.
High-definition imaging commands the steepest price premiums, while Bluetooth connectivity is penetrating fastest across mid-tier product lines.
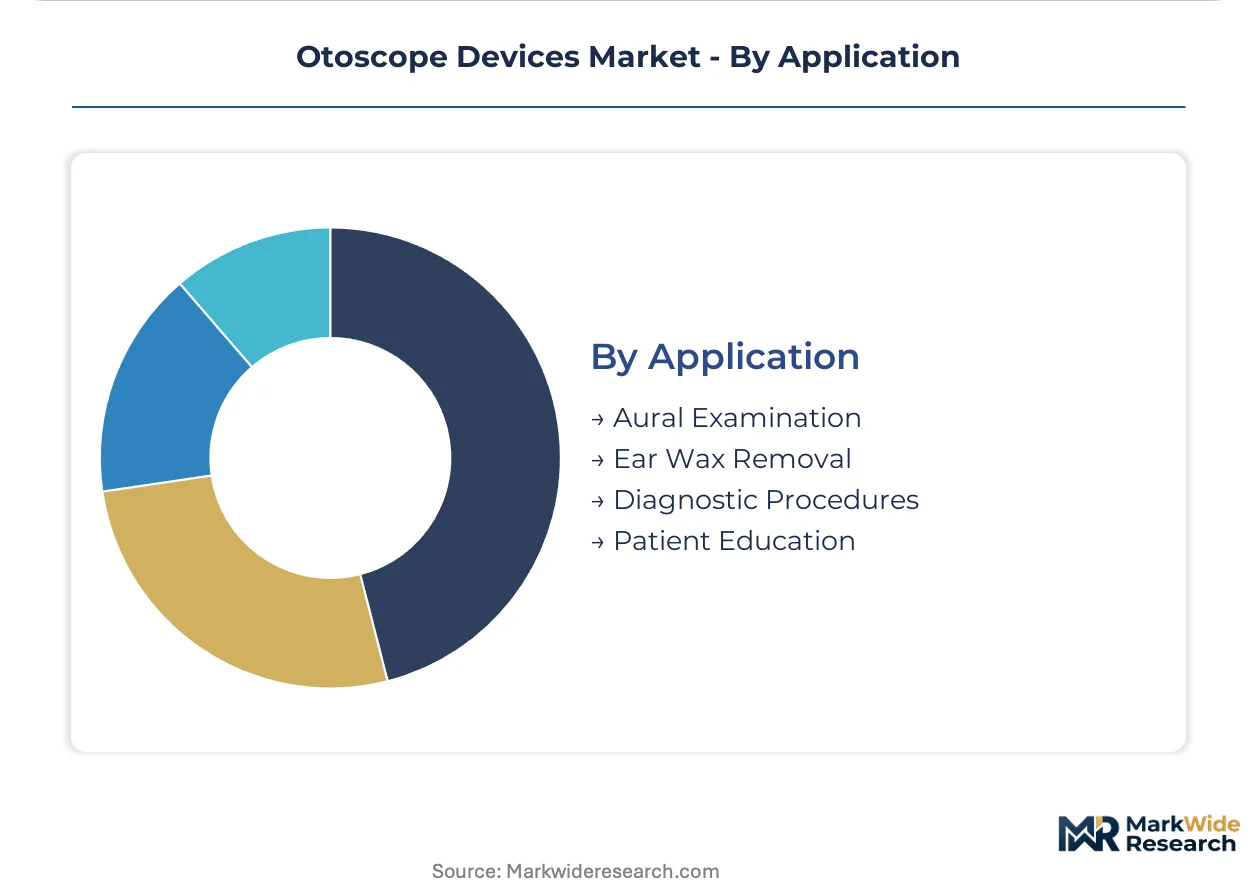
Application:
Clinical utility breadth determines replacement frequency and upsell potential, with procedural documentation requirements driving capital expenditure cycles.
- Aural Examination:Routine visualization of the external auditory canal and tympanic membrane constitutes the core use case across all device categories. Reimbursement code availability varies by US state Medicaid program.
- Ear Wax Removal:Integrated suction and irrigation capabilities in video otoscope systems support procedural billing at premium rates. High-volume ENT practices in Japan deploy dedicated cerumen removal suites.
- Diagnostic Procedures:Tympanic membrane pathology documentation for otitis media and perforation assessment. AI-enabled image classification is miniaturizing onto edge processors for real-time diagnostic assistance.
- Patient Education:Live or recorded ear canal imagery for compliance and shared decision-making. US academic medical centers unbundle this functionality as à-la-carte software subscriptions.
Diagnostic procedures generate the highest per-use revenue, while patient education applications are expanding fastest as telemedicine platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways anchor the United States as the dominant geography, while EMA MDR compliance and Japan's PMDA frameworks shape parallel development tracks. Ambulatory care expansion and telehealth reimbursement policies concentrate procurement authority in specific metropolitan clusters across three continents.
United States
CMS reimbursement codes for remote otoscopy consultations accelerate wireless digital deployment in rural health clinics. FDA 510(k) evidentiary standards now mandate prospective clinical validation for software-enabled diagnostic claims, extending product launch timelines. Hospital procurement committees in Boston and Houston unbundle video otoscope hardware from software subscriptions, demanding à-la-carte pricing for image capture and cloud storage modules.
Germany
EMA Medical Device Regulation software scrutiny legitimizes premium digital otoscope positioning through explicit AI-enabled image analysis frameworks. LED-fiber coupling technologies from precision optics suppliers extend instrument lifespans in high-throughput clinic environments. The Baden-Württemberg medical device cluster anchors European demand for fiber-optic instruments with superior illumination control.
Japan
PMDA documentation requirements for optical medical devices influence regional product configurations distinct from US and European standards. Ministry of Health, Labour and Welfare reimbursement codes for remote monitoring subsidize patient acquisition costs in metropolitan Tokyo and Osaka prefectures. Kanto region hospitals deploy integrated video otoscopy systems that pair with electronic health record infrastructure.
United Kingdom
NHS England procurement frameworks prioritize EHR connectivity in hospital-grade video otoscope selection. MHRA post-Brexit regulatory alignment with EMA MDR maintains CE marking relevance for market access. London academic medical centers drive unbundling trends, separating hardware capital expenditure from AI analysis module subscriptions.
South Korea
MFDS medical device approval pathways compress time-to-market for CMOS sensor-integrated digital otoscopes. National health insurance reimbursement for telemedicine consultations expands addressable volume in Seoul Capital Area ambulatory networks. Busan-Ulsan manufacturing clusters supply LED illumination modules to German and Japanese precision instrument makers.
Otoscope Devices Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in otoscope device manufacturing. Hospital procurement channels concentrate around video otoscopy systems with full documentation infrastructure, while clinic networks fragment across portable digital and durable fiber-optic alternatives. Three archetypes dominate: diversified medical technology conglomerates with EHR integration platforms, precision optics specialists with decade-long service lifespans, and sensor-technology entrants targeting wireless homecare penetration. Competitive moves center on software subscription unbundling and prospective clinical validation investments for FDA 510(k) clearance.
Among German precision engineering houses, Rudolf Riester and Kirchner & Wilhelm occupy positions within the fiber-optic instrument tier, exemplifying European durability-focused positioning against digital connectivity alternatives. HEINE Optotechnik anchors specialist tier consolidation through precision-engineered illumination systems. These three entities represent distinct responses to EMA MDR software scrutiny: Riester and Kirchner & Wilhelm emphasize hardware longevity, while HEINE bridges optical heritage with emerging digital integration requirements.
| Leading Market Players |
|---|
| Rudolf Riester |
| Kirchner & Wilhelm |
| Welch Allyn |
| CellScope |
| Luxamed |
| HEINE Optotechnik |
| Olympus Corporation |
| Prestige Medical |
| American Diagnostic Corporation |
| Others |
Value Chain & Pricing Dynamics
CMOS sensor fabrication scale economies in Taiwanese and South Korean foundries concentrate upstream supply for digital otoscope variants, compressing component costs for wireless units while fiber-optic instrument pricing remains anchored by German precision optics labor intensity and LED-fiber coupling specialization.
Pricing Analysis
United States hospital procurement committees pay premiums of 40-60% above German clinic pricing for identical video otoscope hardware due to FDA 510(k) validation costs and bundled software subscription structures. Three-tier pricing stratification separates premium hospital systems with full EHR integration from mid-tier digital handhelds and economy fiber-optic instruments for cost-sensitive primary care networks. Pricing pressure stems from unbundling demands in academic medical centers separating hardware capital expenditure from cloud storage and AI analysis module fees. Pediatric clinics exhibit highest price sensitivity due to disposable speculum cost inflation, while integrated delivery networks show lowest sensitivity where procedural documentation requirements dominate procurement criteria.
Supply Chain Analysis
Taiwan and South Korea anchor CMOS sensor and image signal processor fabrication for digital otoscope variants, while German precision optics suppliers dominate LED-fiber coupling modules and Japanese manufacturers control high-grade optical glass for lens systems. Raw material dependencies center on rare earth elements for LED phosphors, medical-grade polymers for disposable specula, and copper alloys for thermal management in video otoscope housings. Single-source vulnerability concentrates in Taiwanese foundry capacity for sub-10 micron pixel sensors, exposing manufacturers to geopolitical disruption. Distribution runs through regional medical device distributors with GPO contracts in the United States, direct hospital sales teams in Germany, and Ministry of Health procurement frameworks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) software-as-medical-device pathway tightening creates a regulatory inflection favoring clinical affairs infrastructure over pure sensor technology plays, compressing entry timelines for established manufacturers while extending validation burdens for new entrants.
For Market Incumbents: Fortify proprietary image management platform lock-in through expanded EHR integration partnerships, particularly targeting Epic and Cerner architectures that dominate United States academic medical centers. Deepen backward integration into CMOS sensor specification design to reduce foundry dependency exposure. Prioritize prospective clinical validation investments for AI-enabled diagnostic claims ahead of FDA evidentiary standard elevation. For New Entrants and Emerging Players: Lead with wireless otoscope form factors targeting Japan's Ministry of Health reimbursement codes for remote monitoring and United States rural telehealth initiatives where patient-operated screening workflows bypass traditional procurement gatekeepers. Penetrate homecare segment through direct-to-consumer channels with HIPAA-compliant cloud transmission architectures. Anchor go-to-market through telemedicine platform partnerships rather than hospital capital equipment committees. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision optics specialists with decade-long service lifespans and established clinical validation infrastructure over sensor-technology entrants facing FDA timeline extension. Long-term viability hinges on software subscription recurring revenue attachment rates and EHR integration depth. Acquisition target archetype: German or Japanese fiber-optic instrument manufacturers with digital bridge capabilities and existing CE marking or PMDA approval pathways. Signal to watch: CMS expansion of remote otoscopy reimbursement codes beyond rural health clinic designations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Software-Enabled Diagnostics | Prospective clinical validation investments now mandatory for algorithm-assisted diagnostic claims in United States market entry. |
| CE Marking Pathway under EMA MDR | Explicit AI-enabled image analysis frameworks legitimize premium digital otoscope positioning in European procurement. |
| Hospital System Partnership | Epic and Cerner EHR integration locks procurement committees into multi-year service contracts with proprietary platforms. |
| Software Companion Development | Cloud storage and AI analysis module unbundling responds to academic medical center capital equipment committee independence from IT governance. |
| Reimbursement Strategy | CMS remote otoscopy code expansion accelerates wireless digital deployment in rural health clinic networks. |
Study Parameters
A standing panel of ENT specialists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement code updates, and hospital procurement contract disclosures. Primary interviews with primary care network administrators and telemedicine platform operators combined with customs records for CMOS sensor imports and German precision optics export statistics. Bottom-up unit demand modeling triangulated against top-down healthcare expenditure allocation for diagnostic equipment.
Consistency checks validated volume and value outputs against external benchmarks including medical device trade association shipment reports and regional health ministry procurement disclosures across the analysis window. Segmentation dimensions modeled include product architecture, end-user setting, connectivity protocol, imaging resolution tier, and regional regulatory cluster. CAGRs derived from logistic diffusion curves for digital adoption in clinic environments and replacement cycle analysis for fiber-optic instrument durability. Industry-specific forecast inputs incorporated telehealth reimbursement code expansion trajectories and EMA MDR software scrutiny implementation timelines.
Forecasts assume regulatory continuity in FDA 510(k) evidentiary standards, EMA MDR AI-enabled device frameworks, and Japan PMDA optical medical device documentation requirements; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Lacrimal Duct Stent Tube Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Ovulation Microscope Market
Medical Devices
Biomedical Temperature Sensors Market
Medical Devices
Medical Coatings Market
Medical Devices
Bone-Cutting Technologies Market
Medical Devices
Asia-Pacific Bathroom and Toilet Assist Devices Market
Medical Devices
Facial Implant Market
Medical Devices
Robotic Hair Transplant System Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
Global Pulmonary Drug Delivery Systems Market
Medical Devices
Global Medical Sensor Market
Medical Devices
Global Cardiopulmonary Resuscitation Device Market
Medical Devices
Baby Thermometer Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Breast Biopsy Marker Market