
 IV Poles Market | 2026-2036
IV Poles Market Size, Share, and Industry Trends Forecast 2026-2036
IV Poles Market Outlook
Single-source procurement for stainless steel tubing is decoupling from historical mill-direct contracts as buyers diversify supply risk. Medline Industries leverages its domestic fabrication network to sustain cost-competitive adjustable pole lines. Cardinal Health anchors hospital GPO relationships through bundled infusion support offerings. Stryker Corporation differentiates via integrated bed-pole systems that control premium positioning in acute care.
An IV pole is a vertical support apparatus, typically constructed from tubular stainless steel or aluminum with a weighted base and telescoping height adjustment to 72 inches, designed to suspend fluid containers and infusion pumps at prescribed elevations above the patient. The device serves as foundational infrastructure across inpatient wards, operating suites, and home settings where gravity-fed or pump-assisted intravenous therapy is administered. Stainless steel mobile poles dominate installed base volumes in hospitals due to durability requirements, while aluminum variants capture margin pools in home healthcare where lightweight transportability commands price premiums. Multi-function IV poles with integrated pump mounting and power management represent the fastest-expanding product tier as infusion protocol complexity rises across oncology and parenteral nutrition applications.
FDA durable medical equipment regulations govern structural load testing and tip-stability thresholds for IV poles distributed in the United States, while ISO 13485 quality management standards shape manufacturing process compliance for suppliers serving international markets. The EPA's emerging scrutiny of chrome plating emissions is pressuring producers to transition toward powder-coated or electropolished finishes. Stakeholders must monitor how home healthcare reimbursement codes from CMS evolve to determine whether residential-grade pole specifications achieve parity with institutional devices in payment schedules.
Market Dynamics
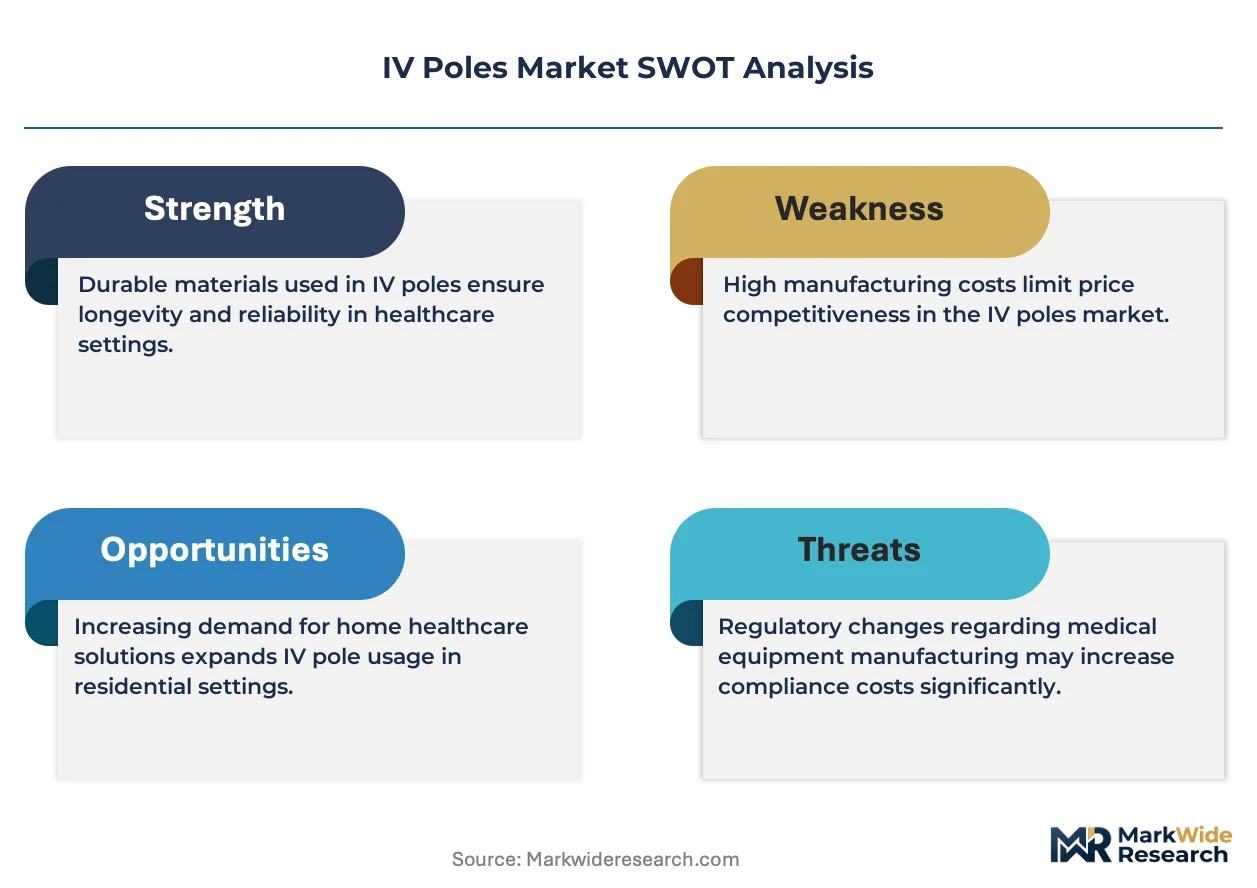
Hospital infrastructure renewal cycles and ambulatory surgery center expansion are compressing replacement timelines for adjustable IV pole units, forcing suppliers to align production capacity with institutional procurement windows rather than historical durability-driven schedules.
Growth Catalysts
- CMS home healthcare reimbursement expansion:Outpatient infusion therapy coverage is pulling durable medical equipment specifications into residential settings, creating parallel demand streams for lightweight aluminum variants alongside institutional stainless steel.
- Oncology protocol complexity:Multi-drug chemotherapy regimens require simultaneous pump mounting and power management, driving specification upgrades toward multi-function pole systems in cancer treatment centers.
- Aluminum extrusion advances:Improved hollow-section manufacturing is reducing weight penalties for home-use IV poles without sacrificing load-bearing capacity, expanding addressable patient populations.
Market Restraints
- Stainless steel tubing supply concentration:Mill-direct contract dependency in North American raw material markets creates input cost volatility when buyers attempt rapid supplier diversification.
- FDA structural load testing requirements:Durable medical equipment classification mandates tip-stability thresholds that extend product development timelines and certification costs for new entrants.
- Chrome plating environmental compliance:EPA emissions scrutiny is forcing finish transitions toward powder-coating or electropolishing, adding process conversion capital requirements.
Strategic Opportunities
- Rural home healthcare penetration:Underpenetrated counties in the United States present white space for rental and lease-based IV pole distribution models serving dispersed aging populations.
- Integrated bed-pole system convergence:Acute care equipment manufacturers can capture premium positioning by embedding IV suspension into patient bed architectures rather than standalone units.
- ISO 13485 certification arbitrage:Suppliers achieving quality management compliance can access institutional procurement channels in multiple jurisdictions with single certification investment.
Industry Challenges
- Welding technician scarcity:Tubular stainless steel fabrication requires specialized orbital welding skills that lag demand growth in domestic manufacturing regions.
- Legacy fleet interoperability:Multi-function IV poles with integrated electronics face integration friction with existing nurse call and EMR systems in older hospital wings.
- Electropolishing capacity bottlenecks:Chrome plating substitution is straining certified finish house throughput, extending order-to-delivery intervals for compliant products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IV Poles Market |
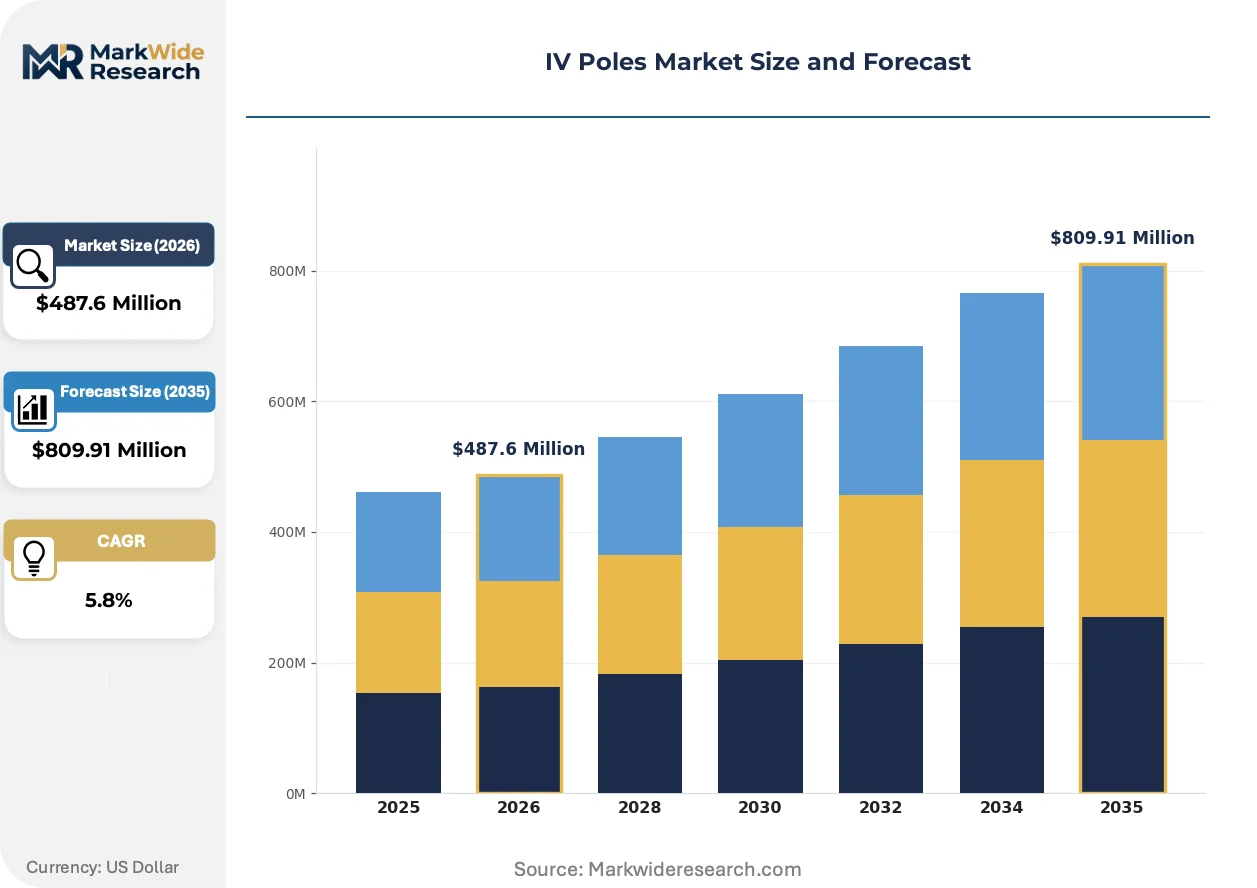
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile IV Poles, Fixed IV Poles, Adjustable IV Poles, Multi-Function IV Poles Material: Stainless Steel, Aluminum, Plastic, Carbon Fiber End User: Hospitals, Clinics, Home Healthcare, Long-Term Care Facilities Functionality: Standard IV Support, Multi-Channel IV Delivery, Infusion Pump Compatible, Weight Bearing |
| Companies Covered | Stryker Corporation, Medline Industries, Cardinal Health, Hill-Rom Holdings, B. Braun Melsungen AG, Fresenius Kabi, Drive DeVilbiss Healthcare, Invacare Corporation, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IV Poles Market Strategic Shifts
Active sensor integration and wireless connectivity are reshaping IV pole functionality from passive suspension hardware to monitored care infrastructure, requiring suppliers to develop electronics competencies alongside metal fabrication.
Carbon fiber composite tubing is absorbing premium segment demand from aluminum in weight-critical home healthcare applications. Hospice agencies and mobile infusion nursing services specify these units for vehicle transport efficiency. The material shift is compressing traditional metal-forming margin pools while opening service-revenue attachments through connectivity modules.
EPA chrome plating emissions enforcement is forcing finish technology transitions across domestic manufacturing. Powder-coated and electropolished surfaces now dominate new product introductions, with compliance costs concentrating among smaller fabrication shops lacking captive finishing capacity. Hospital GPOs are incorporating environmental compliance scorecards into supplier qualification criteria.
Hospital procurement departments are consolidating IV pole purchasing into bundled infusion support contracts rather than standalone capital equipment lines. This behavioral shift disintermediates traditional durable medical equipment distributors in favor of integrated supply partners. The pattern is most visible in United States health system consolidation markets where single-source agreements cover beds, poles, and pump accessories.
IV Poles Market Segmentation
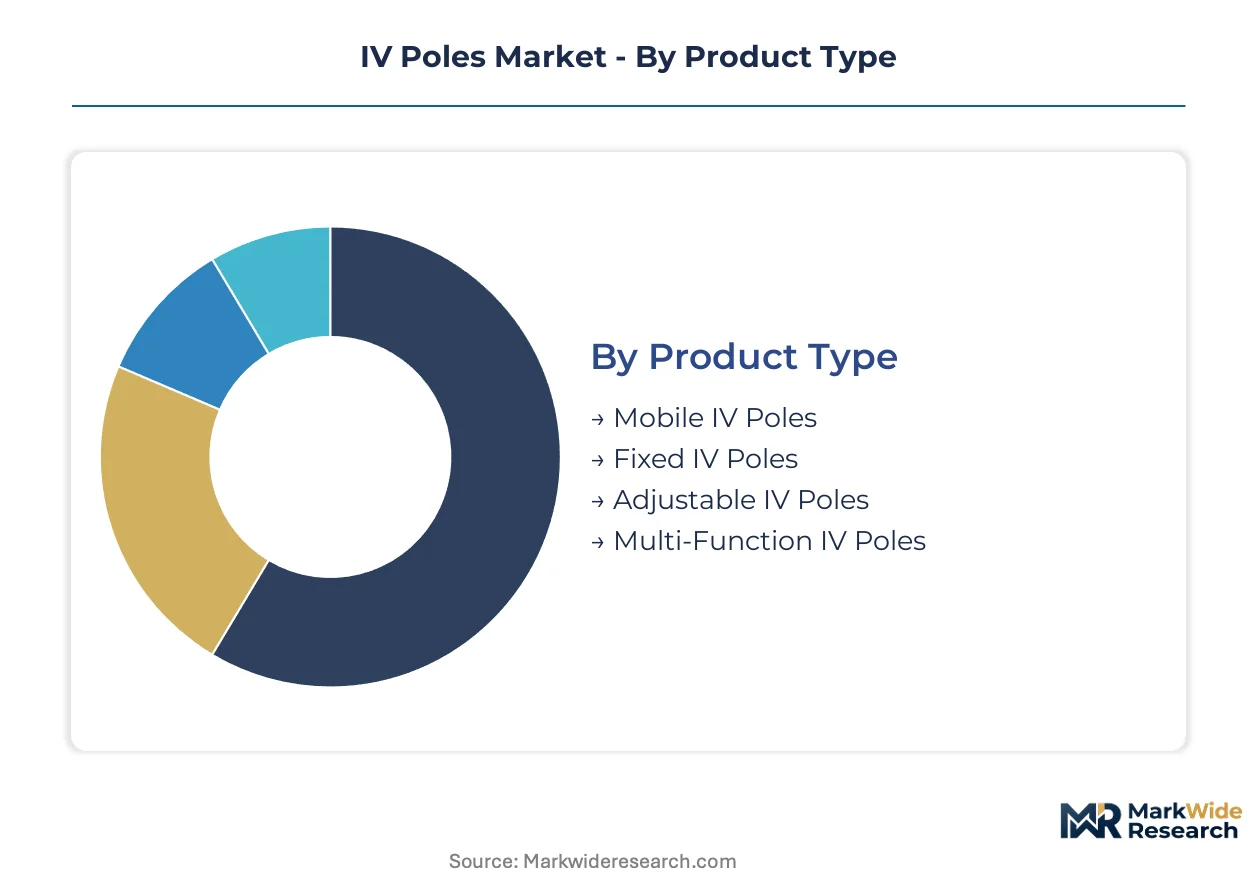
IV pole procurement patterns diverge sharply across care settings, with institutional buyers prioritizing durability and load tolerance while home healthcare operators weight transportability above all else. Material selection and functionality tiers separate premium positioning from commodity supply, creating distinct margin architectures within what appears as a homogeneous hardware category.
Product Type:
Buyers in this category differentiate by mobility requirements and the complexity of infusion protocols they must support.
- Mobile IV Poles:Castor-mounted units with weighted bases permit rapid repositioning between patient bays and procedure rooms. Hospital emergency departments and surgical suites in the United States specify these for protocol flexibility where staff cannot wait for fixed infrastructure.
- Fixed IV Poles:Wall-mounted or floor-anchored installations eliminate tip-over risk in behavioral health units and pediatric wards where patient interaction with equipment raises safety concerns. These units sacrifice flexibility for stability in high-risk care environments.
- Adjustable IV Poles:Telescoping height mechanisms accommodate patient bed configurations from standard to bariatric. These units dominate replacement cycles in general medical-surgical floors.
- Multi-Function IV Poles:Integrated pump mounting rails and power management transform passive suspension into active therapy platforms. Oncology infusion centers and parenteral nutrition services drive specification of these systems.
Mobile IV poles lead volumes today; multi-function units are gaining share fastest.
Material:
Cost-to-weight ratios and finish durability requirements segment buyers across institutional versus residential deployment.
- Stainless Steel:Tubular 304-grade construction withstands repeated disinfection cycles and structural load testing under FDA durable medical equipment standards. Acute care facilities in the United States specify these for decade-long service life.
- Aluminum:Hollow-section extrusions reduce unit weight by 40-50% without sacrificing load capacity, enabling single-nurse transport in home healthcare settings. CMS reimbursement expansion for outpatient infusion is accelerating residential-grade aluminum procurement.
- Plastic:Polymer construction targets disposable or short-term rental applications where capital recovery cycles compress below two years. These units serve temporary field hospitals and disaster response deployments.
- Carbon Fiber:Composite tubing absorbs premium positioning in mobile hospice and infusion nursing services where vehicle transport efficiency commands price tolerance. The material is displacing aluminum in weight-critical segments.
Stainless steel commands the installed base; carbon fiber shows the steepest expansion trajectory.
End User:
Procurement authority and reimbursement pathways fragment demand across institutional and residential channels.
- Hospitals:GPO-negotiated contracts bundle IV poles with bed systems and infusion pumps, favoring suppliers with comprehensive acute care portfolios. Infrastructure renewal cycles in the United States compress replacement timelines.
- Clinics:Ambulatory surgery centers and specialty infusion clinics prioritize rapid room turnover, specifying lightweight mobile units with quick-release height adjustments. These buyers lack captive biomedical engineering support.
- Home Healthcare:Durable medical equipment distributors serve dispersed patient populations through rental and lease models. CMS reimbursement codes determine whether residential-grade specifications achieve payment parity.
- Long-Term Care Facilities:Skilled nursing operators balance resident mobility assistance against infection control, selecting powder-coated finishes that resist corrosion in high-humidity environments.
Hospitals anchor procurement volumes; home healthcare is climbing the fastest as aging populations shift to outpatient infusion.
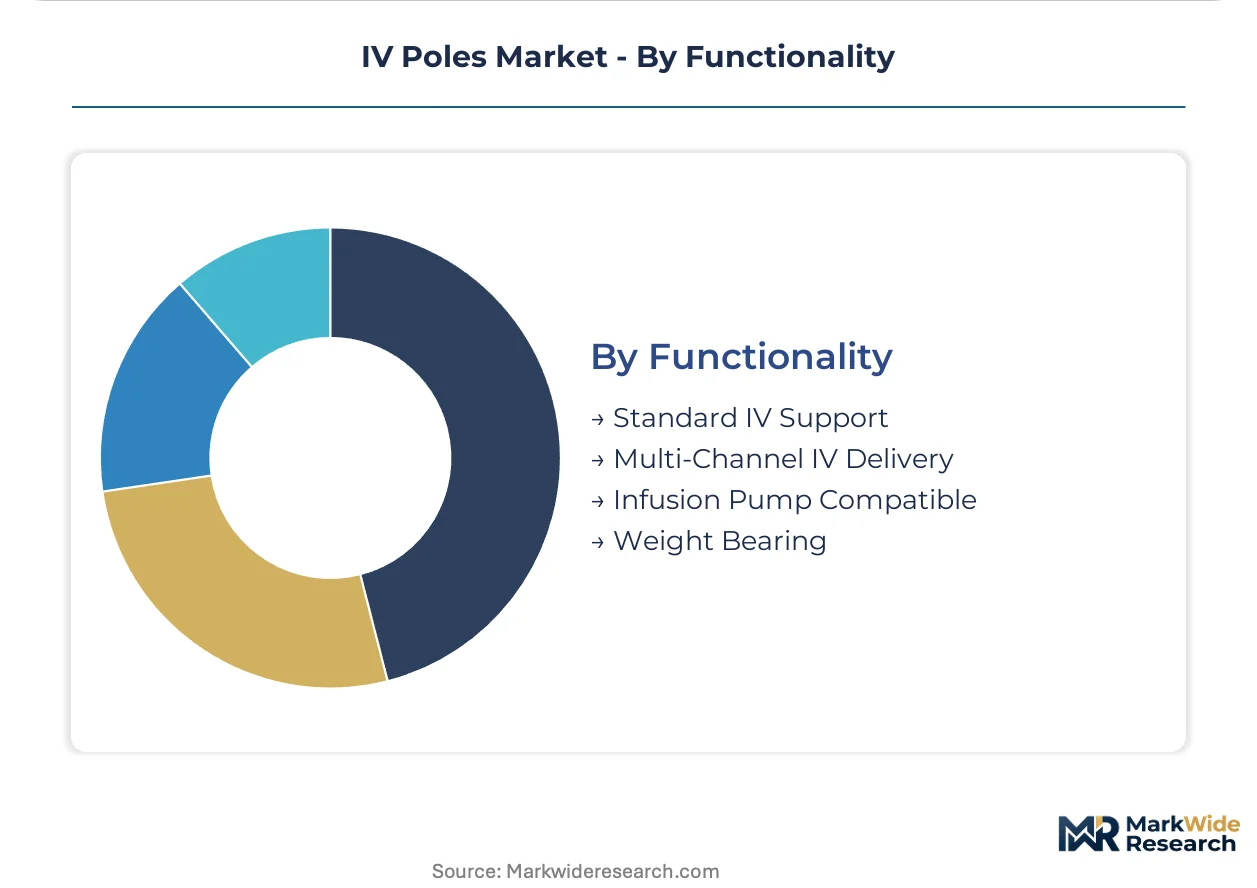
Functionality:
Protocol complexity and pump integration requirements stratify buyers by therapy intensity.
- Standard IV Support:Gravity-fed suspension for basic hydration and antibiotic delivery. These units serve general medical floors where pump assistance is unnecessary.
- Multi-Channel IV Delivery:Multiple hook positions and manifold mounting for simultaneous drug administration. Oncology and critical care units specify these for complex therapeutic regimens.
- Infusion Pump Compatible:Integrated mounting rails and cable management accommodate volumetric and syringe pumps. These specifications are becoming baseline for cancer treatment centers.
- Weight Bearing:Reinforced construction supports heavy parenteral nutrition bags and blood product containers. Bariatric and surgical units require these load-rated specifications.
Standard IV support leads current deployment; infusion pump compatible units are expanding most quickly as electronic delivery becomes standard of care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital infrastructure renewal in the United States compresses replacement cycles for adjustable IV pole units, while CMS reimbursement expansion pulls durable medical equipment specifications into residential settings across multiple geographies.
United States
Ambulatory surgery center expansion and health system consolidation drive bundled procurement of multi-function IV poles with integrated pump mounting. FDA durable medical equipment regulations govern structural load testing and tip-stability thresholds for devices distributed nationwide. The Midwest manufacturing corridor around Chicago anchors domestic fabrication capacity for stainless steel tubing and powder-coated finishes.
Germany
Precision engineering traditions support premium positioning for integrated bed-pole systems in acute care facilities. EU Medical Device Regulation (MDR) and ISO 13485 quality management standards shape manufacturing compliance for suppliers serving institutional channels. The Baden-Württemberg cluster around Stuttgart concentrates metal fabrication expertise serving hospital GPOs across Central Europe.
China
Domestic hospital construction and medical infrastructure upgrading generate volume demand for standard mobile IV poles. National Medical Products Administration (NMPA) device registration requirements align with international quality benchmarks for export-oriented manufacturers. The Yangtze River Delta region around Shanghai hosts aluminum extrusion and carbon fiber composite tubing operations supplying home healthcare exporters.
Japan
Aging demographics and outpatient chemotherapy expansion accelerate specification upgrades toward multi-channel IV delivery systems. Ministry of Economy, Trade and Industry (METI) industrial standards and Pharmaceutical and Medical Devices Agency (PMDA) oversight ensure compatibility with electronic medical record integration. The Kansai manufacturing belt around Osaka maintains specialized orbital welding capacity for tubular stainless steel medical equipment.
India
Private hospital chain expansion and government health infrastructure programs create dual demand streams for institutional and value-tier IV poles. Central Drugs Standard Control Organization (CDSCO) medical device rules and Bureau of Indian Standards (BIS) certification requirements structure market entry for domestic and import suppliers. The Maharashtra-Gujarat industrial corridor around Mumbai and Ahmedabad hosts emerging fabrication capacity serving South Asian and Middle Eastern export markets.
IV Poles Market Competitive Environment
Global majors compete with regional champions across supply chain integration and GPO relationship depth. The vendor base organizes around three tiers: diversified medical equipment conglomerates with comprehensive acute care portfolios, specialized durable medical equipment fabricators with domestic manufacturing networks, and emerging composite material specialists targeting weight-critical home healthcare segments. Competitive moves concentrate on backward integration into raw material supply and strategic partnerships with hospital procurement consortia.
Among diversified medical technology conglomerates, Stryker Corporation and Hill-Rom Holdings exemplify the premium-tier positioning through integrated patient care systems. Medline Industries represents the domestic fabrication archetype with cost-competitive adjustable pole lines, while Cardinal Health anchors hospital GPO relationships through bundled infusion support offerings. B. Braun Melsungen AG occupies a position bridging European engineering standards with global distribution reach.
| Leading Market Players |
|---|
| Stryker Corporation |
| Medline Industries |
| Cardinal Health |
| Hill-Rom Holdings |
| B. Braun Melsungen AG |
| Fresenius Kabi |
| Drive DeVilbiss Healthcare |
| Invacare Corporation |
| 3M |
| Others |
Value Chain & Pricing Dynamics
Hospital GPO procurement concentration in the United States anchors contract-based pricing for IV poles, with multi-year agreements locking in volume discounts that compress margins for non-integrated suppliers while rewarding backward-integrated fabricators with captive stainless steel sourcing.
Pricing Analysis
Stainless steel tubing cost pass-through dominates IV pole pricing, with mill-direct contract holders maintaining margin stability against spot-market buyers facing volatile input swings. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification status and integrated pump-mounting functionality. Cost compression in economy-grade aluminum residential units is intensifying because CMS reimbursement parity pressures rental distributors to source lower-specification alternatives. Home healthcare operators exhibit highest price sensitivity, while oncology centers purchasing multi-function systems tolerate premium positioning for protocol compliance.
Supply Chain Analysis
Orbital welding technician scarcity across the Midwest manufacturing corridor and Kansai industrial belt constrains stainless steel fabrication throughput, extending order-to-delivery intervals for FDA-compliant durable medical equipment. Supply concentrates in the United States, Germany, and China, with raw material feeds drawing from North American steel mills and Yangtze River Delta aluminum extruders. Chrome plating substitution under EPA emissions enforcement creates single-source vulnerability at certified electropolishing finish houses. Distribution runs through hospital GPO consortia and durable medical equipment rental networks serving residential infusion patients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IV Poles Market functions as a stable compounder, with aging demographics and outpatient infusion expansion providing durable demand tailwinds that transcend cyclical healthcare capital spending volatility.
For Market Incumbents: Anticipate carbon fiber composite displacement in premium home healthcare segments by securing exclusive supply agreements with hospice agency networks before specialty fabricators scale production. Deepen backward integration into powder-coating finish capacity to capture EPA compliance premiums that smaller competitors cannot absorb. Prioritize ISO 13485 certification maintenance as the priority lever for institutional procurement channel access. For New Entrants and Emerging Players: FDA durable medical equipment classification requirements in the United States open a window for regulatory arbitrage by targeting CMS reimbursement expansion in underpenetrated rural counties where incumbent distribution networks remain thin. Focus initial penetration on aluminum residential-grade rental models serving mobile infusion nursing services. Pursue white-glove logistics partnerships with regional durable medical equipment distributors as the primary go-to-market pathway. For Investors and Strategic Acquirers: Hospital system consolidation is the most active acquirer in this space, with integrated supply partners commanding valuation premiums over standalone pole fabricators. The five-to-ten-year viability window favors targets with captive welding capacity and GPO contract relationships. Acquisition target archetypes include domestic fabrication shops with orbital welding certifications and established hospice agency rental agreements. Monitor CMS home healthcare reimbursement code revisions for early signals of residential-grade specification parity shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder-Coating Capacity | EPA emissions compliance secures qualification for hospital GPO environmental scorecards. |
| ISO 13485 Certification Investment | Quality management compliance unlocks institutional procurement channels across multiple jurisdictions. |
| Carbon Fiber Composite Product Line Launch | Material substitution captures premium positioning in mobile hospice and infusion nursing segments. |
| Hospital System Partnership Expansion | Bundled infusion support contracts disintermediate traditional durable medical equipment distributors. |
| Rural Home Healthcare Distribution Buildout | Underpenetrated counties present white space for rental and lease-based IV pole deployment models. |
Study Parameters
Direct dialogue with hospital procurement managers, GPO contracts specialists, biomedical engineering directors, and durable medical equipment distributors grounded qualitative findings, cross-referenced against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital capital expenditure disclosures, and stainless steel trade flow data. Secondary validation drew from ISO certification registries, EPA emissions compliance records, and industry association shipment reports. Bottom-up and top-down triangulation reconciled facility-level installation estimates with macro healthcare infrastructure spending patterns.
Bottom-up modeling aggregated addressable patient populations across inpatient, ambulatory, and residential settings, while top-down analysis calibrated against national healthcare capital equipment budgets. Segmentation dimensions included product mobility configuration, material grade tier, end-user channel, and functionality integration level. CAGRs derived from historical replacement cycle analysis and projected infrastructure renewal timelines, with infusion protocol complexity and reimbursement policy shifts serving as key demand elasticity inputs.
Revisions become necessary when FDA device classification thresholds tighten, EPA finish technology mandates accelerate, or CMS residential reimbursement codes diverge from institutional parity assumptions. Practitioners should monitor home healthcare penetration rates in rural counties and carbon fiber composite tubing cost curves for early signals of segment displacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Atrial Appendage Occluder Market
Medical Devices
Mexico Contraceptive Devices Market
Medical Devices
Photomedicine Technology Market
Medical Devices
Global 3D Printed Surgical Models Market
Medical Devices
Global Uterine Manipulation Devices Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Minimally Invasive Spine Technologies Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
Lumbar Disc Replacement Device Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
Annuloplasty Rings Market
Medical Devices
Middle East and Africa Surgical Equipment Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
Remote Magnetic Catheter Systems Market