
 Wireless ECG Devices Market | 2026-2036
Wireless ECG Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless ECG Devices Market Intelligence
A fragmentation of the customer base, moving from large hospital systems to include individual consumers and telehealth providers, is restructuring market access and sales strategies. AliveCor specializes in direct-to-consumer devices, gaining significant traction through mobile app integration. In contrast, iRhythm Technologies focuses on long-term continuous monitoring solutions prescribed by clinicians. GE HealthCare leverages its established hospital network to supply clinical-grade wearable monitors for inpatient and outpatient settings.
Wireless ECG devices are medical-grade sensors that capture the heart's electrical signals without restrictive cables, transmitting data via protocols like Bluetooth or Wi-Fi. Their function is to enable continuous or intermittent cardiac monitoring outside of traditional clinical environments. Among product types, patch devices and wearable monitors are experiencing the most rapid adoption due to their convenience and user compliance. While hospitals remain a large end-user segment, the home care setting is expanding at a significant rate, driven by the push for remote patient management.
Regulatory bodies such as the US FDA, European authorities enforcing the MDR, and China's NMPA impose stringent requirements for clinical validation and data security. These regulations ensure that devices provide accurate diagnostic data, a critical factor for market access and physician adoption. Navigating the evolving landscape of reimbursement policies for remote monitoring services will be a decisive factor for commercial success.
Market Dynamics
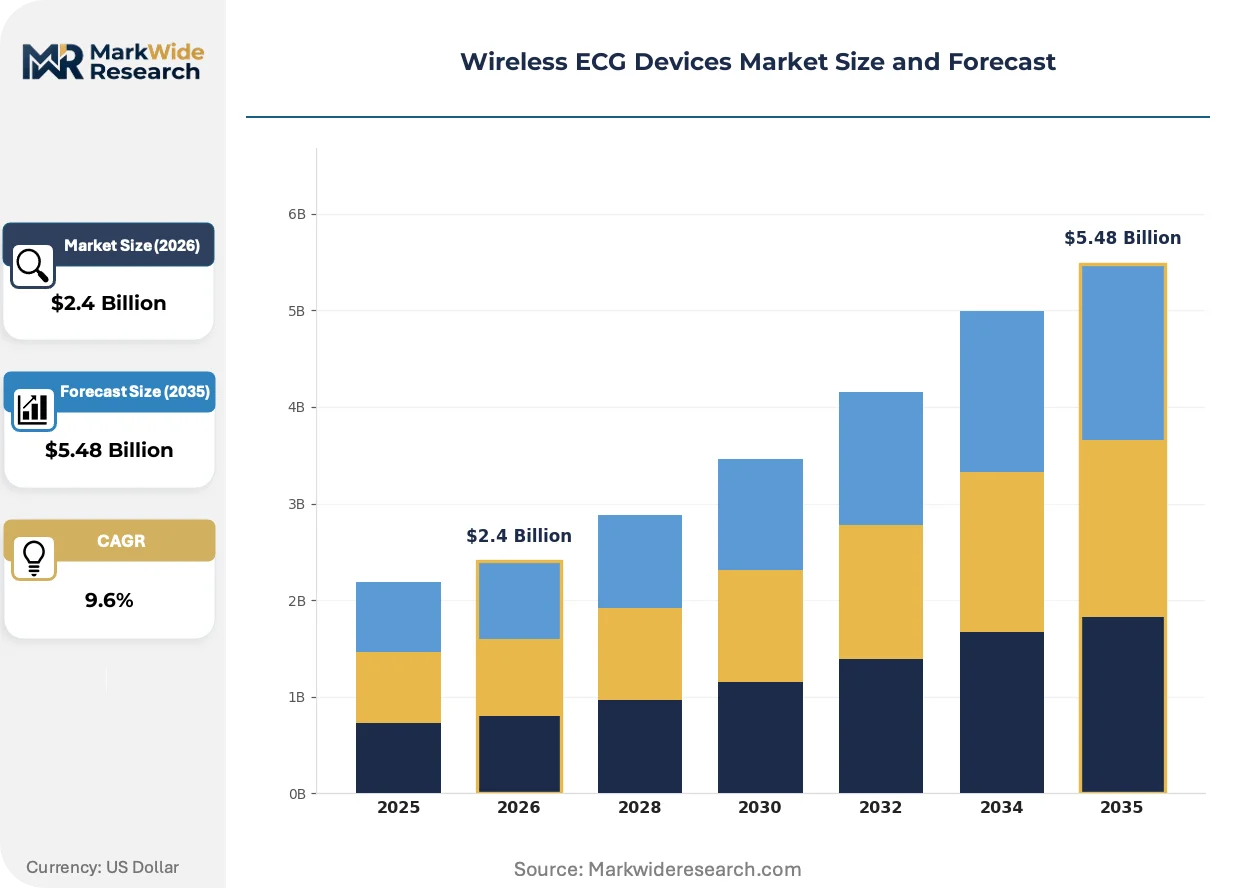
The central force shaping the market is the fragmentation of the customer base away from exclusively large hospitals. This expansion to include individual consumers and telehealth providers for home-based continuous monitoring is restructuring sales strategies and market access requirements.
Growth Catalysts
- Favorable Reimbursement:Expanding reimbursement frameworks for remote patient monitoring services in the United States and parts of Europe create direct financial incentives for clinicians to adopt wireless ECG solutions for outpatient care.
- Technology Miniaturization:Advances in sensor technology and power management enable smaller, more comfortable patch devices and wearable monitors, which significantly improves long-term patient compliance and data quality.
- Chronic Disease Management:A growing focus on proactive management of cardiovascular diseases in developed healthcare systems, such as in Germany, drives demand from home care settings for continuous monitoring tools.
Market Restraints
- Data Security and Privacy:Stringent data protection regulations, including HIPAA in the US and GDPR in Europe, impose significant compliance costs and create liabilities regarding the secure transmission and storage of sensitive patient health information.
- Diagnostic Accuracy Concerns:Signal artifacts and noise from patient movement in ambulatory settings can compromise the quality of ECG data, leading to diagnostic uncertainty and requiring advanced algorithms to filter interference.
- Interoperability Hurdles:The lack of standardized data formats and communication protocols creates significant challenges in integrating device data into the diverse array of Electronic Health Record systems used by hospitals and clinics.
Strategic Opportunities
- Algorithm and AI Integration:Developing proprietary machine learning algorithms for automated arrhythmia detection and predictive risk stratification offers a significant opportunity for vendors to differentiate their products and add clinical value.
- Expansion into Emerging Markets:Targeting telehealth expansion in Asia-Pacific countries provides a pathway for growth, as governments in the region invest in digital health infrastructure to improve healthcare access.
- Direct-to-Consumer Channels:Establishing mobile app-integrated, direct-to-consumer sales models allows manufacturers to bypass traditional, lengthy hospital procurement cycles and build brand recognition directly with end-users.
Industry Challenges
- Navigating Global Regulations:Securing and maintaining regulatory clearance across multiple jurisdictions, such as FDA approval, CE marking under MDR, and NMPA certification, is a complex and resource-intensive process.
- Physician Adoption and Training:Overcoming clinical inertia and ensuring physicians are adequately trained to interpret and act upon the large volumes of data generated by continuous monitoring devices remains a barrier to wider use.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless ECG Devices Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.48 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitors, Handheld Devices, Patch Devices, Smart Clothing End User: Hospitals, Home Care, Fitness Centers, Telehealth Providers Technology: Bluetooth, Wi-Fi, Cellular Network, Cloud-Based Solutions Application: Cardiology Monitoring, Patient Rehabilitation, Remote Patient Monitoring, Sports Analytics |
| Companies Covered | AliveCor, iRhythm Technologies, GE HealthCare, Nihon Kohden Corporation, Medtronic, Koninklijke Philips, Bittium, Aerotel Medical Systems, VivaLNK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless ECG Devices Market Strategic Shifts & Innovations
The consumerization of medical-grade monitoring is reshaping competitive positioning. This shift from institution-centric hardware to patient-centric data services places new emphasis on user experience, mobile integration, and the clarity of diagnostic information provided to both patients and clinicians.
AI-powered analytics embedded within the device or its companion mobile application represent the fastest-growing area of innovation. Telehealth providers and individual consumers are adopting these tools for near real-time arrhythmia detection without requiring immediate clinical oversight. This integration of on-device intelligence is decentralizing diagnostic capabilities away from specialized cardiac centers and into the hands of users.
Europe's Medical Device Regulation (MDR) has elevated the requirements for market access. The regulation mandates more extensive clinical evidence and robust post-market surveillance systems for all medical devices, including wireless ECGs. Manufacturers of patch and wearable monitors are most affected, now needing to invest more heavily in clinical trials and quality management to maintain CE marking.
A shift in patient behavior towards demanding direct access to personal health data is disrupting traditional care pathways. This trend challenges the model of clinician-gated cardiac monitoring, as consumers increasingly use direct-to-consumer devices to track their own heart health. This behavioral change is most prominent in the United States, where a strong consumer health technology market and direct-to-patient advertising exist.
Wireless ECG Devices Market Segmentation
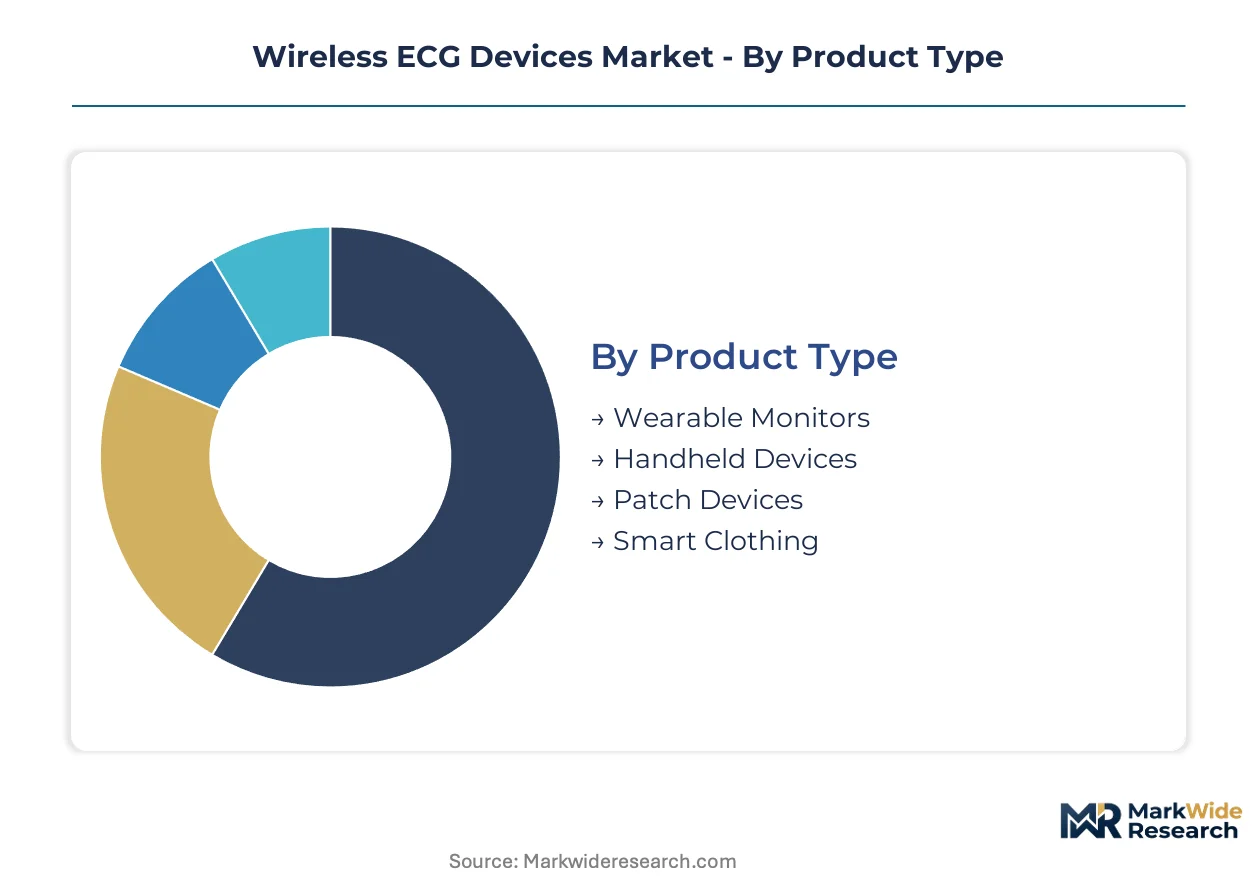
The Wireless ECG Devices Market exhibits distinct segmentation across various dimensions, reflecting the diverse technological capabilities, end-user requirements, and application-specific demands. Understanding these segments is crucial for manufacturers to tailor product development and market penetration strategies effectively.
Product Type:
The capital intensity associated with developing and manufacturing wireless ECG devices varies significantly across product types, influencing market entry barriers and required R&D investments.
- Patch Devices:These disposable or reusable adhesive sensors attach directly to the skin, offering continuous, long-term monitoring with minimal patient interference. Demand concentrates in home care settings for extended diagnostic periods, driven by improved patient compliance and convenience.
- Wearable Monitors:Integrated into wristbands or chest straps, these devices provide continuous cardiac data capture through non-invasive contact. Developed healthcare systems, particularly in the United States, utilize these for both outpatient monitoring and fitness tracking, enhancing user experience.
- Handheld Devices:These portable, on-demand ECG recorders are used for intermittent spot checks, often by individual consumers or telehealth providers for quick assessments.
- Smart Clothing:ECG sensors are integrated directly into garments, offering discreet, continuous monitoring, with emerging demand from remote patient management programs.
Most installed capacity flows through Wearable Monitors. Expansion is steepest in Patch Devices.
End User:
The procurement patterns for wireless ECG devices differ substantially across end-user segments, reflecting distinct operational needs and regulatory compliance requirements.
- Hospitals:Large-scale healthcare facilities integrate wireless ECG devices for inpatient monitoring, emergency diagnostics, and pre-discharge assessments. Germany's hospital networks increasingly adopt these for seamless data integration into electronic health records, improving workflow efficiency.
- Home Care:This segment involves patients monitoring cardiac activity in their residences, often under physician guidance for chronic disease management. The United States sees significant demand for remote patient monitoring services, driven by favorable reimbursement policies.
- Telehealth Providers:These entities leverage wireless ECG devices to conduct remote cardiac consultations and provide diagnostic insights, expanding access to specialists in underserved areas.
- Fitness Centers:Users in these facilities employ wireless ECG for performance tracking and heart rate monitoring during exercise, focusing on personal health and wellness data.
Hospitals represent the largest volume consumer of wireless ECG devices. Telehealth Providers are expanding their usage significantly.
Technology:
The underlying communication technology dictates the data throughput capabilities and real-time monitoring potential of wireless ECG devices, impacting their clinical utility.
- Bluetooth:This short-range wireless protocol enables secure data transmission between ECG devices and nearby mobile applications or gateways. Its low power consumption makes it ideal for battery-operated wearables, widely used in direct-to-consumer devices like AliveCor's offerings.
- Wi-Fi:Providing higher bandwidth over longer ranges, Wi-Fi facilitates rapid data transfer to local networks or cloud platforms, supporting continuous monitoring in home environments. Integration into hospital systems for real-time data streaming is common practice.
- Cellular Network:Devices utilizing cellular connectivity transmit data directly to cloud servers, ensuring monitoring continuity even without local Wi-Fi, crucial for remote patient management.
- Cloud-Based Solutions:These platforms store, process, and analyze ECG data transmitted from various devices, enabling remote access for clinicians and supporting AI-powered diagnostic algorithms.
Bluetooth remains a foundational technology for device-to-app communication. Cloud-Based Solutions are driving the most innovation.
Application:
The regulatory scrutiny and diagnostic criticality associated with wireless ECG applications significantly influence product design, clinical validation requirements, and market acceptance.
- Cardiology Monitoring:This primary application focuses on diagnosing and managing various cardiac arrhythmias and conditions, often requiring FDA or CE marking for diagnostic accuracy. Hospitals and specialized clinics in the United States rely on these for clinical-grade assessments.
- Remote Patient Monitoring:Devices in this segment enable continuous or intermittent cardiac surveillance for patients outside clinical settings, facilitating proactive disease management. Reimbursement policies in Europe are increasingly supporting these services for chronic cardiovascular conditions.
- Patient Rehabilitation:Wireless ECG supports monitoring cardiac activity during physical therapy for patients recovering from cardiovascular events, ensuring safety and progress tracking.
- Sports Analytics:Athletes and fitness enthusiasts use these devices to optimize training and monitor cardiac performance, with demand concentrating among high-performance users.
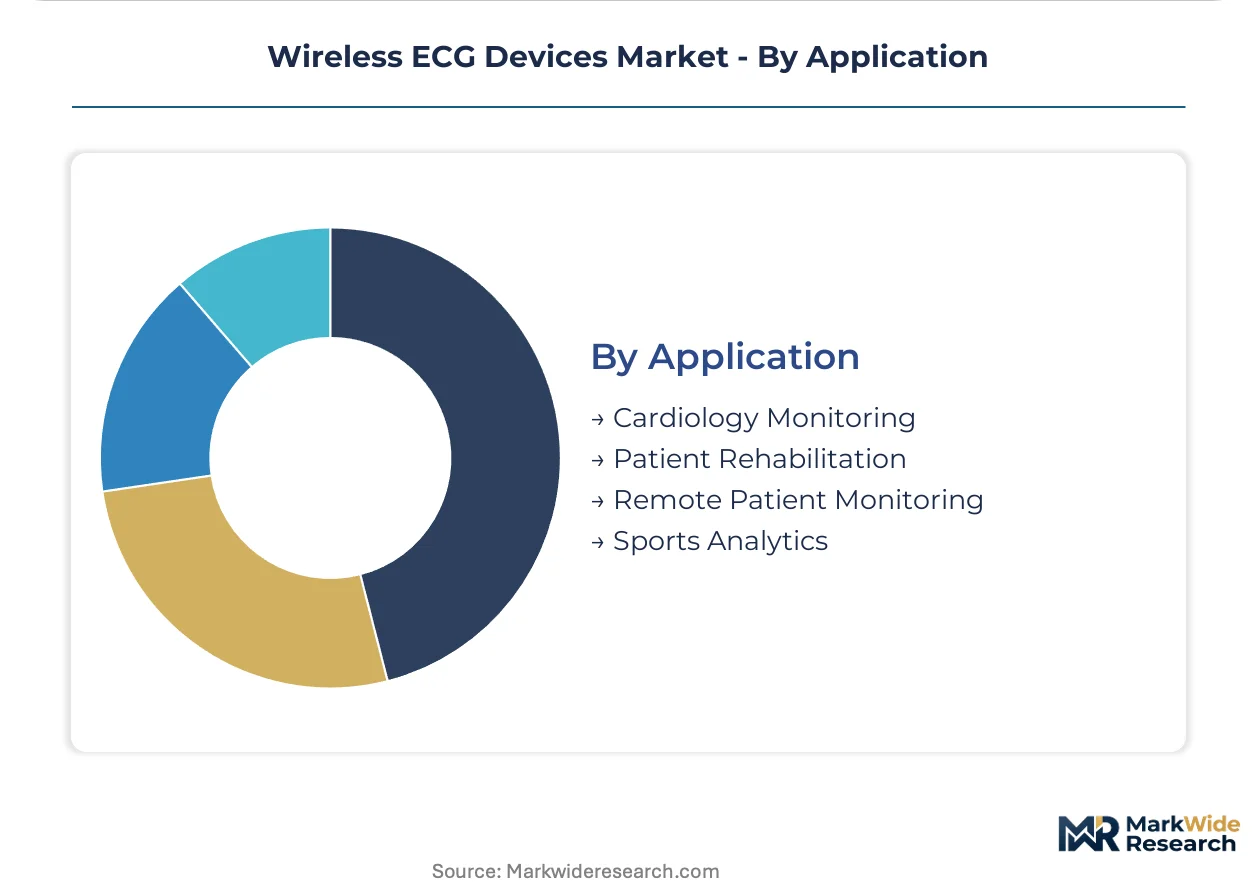
Cardiology Monitoring has the broadest clinical impact. Sports Analytics shows emerging potential for consumer health tracking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Talent concentrations in medical device engineering and digital health innovation anchor the market's geographic distribution. Developed healthcare systems with established infrastructure and favorable reimbursement policies drive significant demand. These regions also possess the regulatory expertise necessary for complex medical device approvals.
United States
Expanding remote patient monitoring services and home care settings drive demand for wireless ECG devices. The FDA clearance pathways facilitate market entry for new technologies. Major medical device manufacturing and R&D hubs in states like California and Massachusetts foster continuous innovation.
Germany
Proactive management of cardiovascular diseases and integration into hospital networks propel device adoption. European authorities enforcing the MDR ensure high standards for clinical validation and post-market surveillance. Medical technology clusters in Bavaria and North Rhine-Westphalia are central to product development.
China
Government investments in digital health infrastructure and telehealth expansion create new growth avenues. The NMPA regulates device approvals, focusing on data security and clinical efficacy. Technology manufacturing centers in the Yangtze River Delta region are pivotal for device production.
Japan
An aging population and a focus on preventative care stimulate the adoption of continuous cardiac monitoring. The PMDA oversees medical device regulations, emphasizing patient safety and data accuracy. The Kanto region, including Tokyo, serves as a hub for advanced medical electronics research.
India
Improving healthcare access in remote areas and a rising burden of chronic diseases underpin market expansion. The CDSCO regulates medical devices, supporting local manufacturing initiatives. Bengaluru and Hyderabad are emerging as key centers for health tech startups and digital health solutions.
Wireless ECG Devices Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a dynamic market structure. The landscape includes established medical device manufacturers, innovative telehealth solution providers, and consumer electronics companies. Strategic archetypes include clinical-grade device providers, direct-to-consumer platforms, and integrated monitoring service operators. Key competitive moves involve technology licensing agreements and expanding portfolio diversification to capture new end-user segments.
Specialists in direct-to-consumer devices, such as AliveCor, exemplify an archetype focused on user accessibility and mobile app integration. iRhythm Technologies occupies a position centered on long-term continuous monitoring solutions prescribed by clinicians. GE HealthCare anchors the segment providing clinical-grade wearable monitors through established hospital networks, leveraging its extensive healthcare infrastructure.
| Leading Market Players |
|---|
| AliveCor |
| iRhythm Technologies |
| GE HealthCare |
| Nihon Kohden Corporation |
| Medtronic |
| Koninklijke Philips |
| Bittium |
| Aerotel Medical Systems |
| VivaLNK |
| Others |
Cost & Logistics Intelligence
Telehealth providers, expanding their usage significantly, influence subscription-based pricing models for continuous monitoring services.
Pricing Analysis
The bundled-versus-unbundled service split significantly influences pricing strategies for wireless ECG devices. Subscription-based models are prevalent for continuous monitoring solutions, while per-unit transactional pricing often applies to handheld devices. Price differentiation stems from clinical validation status, FDA/CE marking, and integrated AI-powered data analytics services. Pricing pressure stems from the consumerization trend, driving demand for more affordable devices. Individual consumers and fitness centers exhibit the highest price sensitivity, whereas hospitals prioritize clinical accuracy and data integration.
Supply Chain Analysis
Logistics and freight costs represent a notable component of the overall supply chain for wireless ECG devices. Manufacturing concentrates in China and Southeast Asia for electronic components, while specialized medical-grade sensors and microcontrollers often source from the United States and Germany. The supply chain relies on advanced sensor technology and secure communication modules. Single-source vulnerability for critical medical-grade components presents a structural risk. Distribution runs through direct-to-consumer channels, hospital procurement networks, and value-added resellers serving telehealth providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
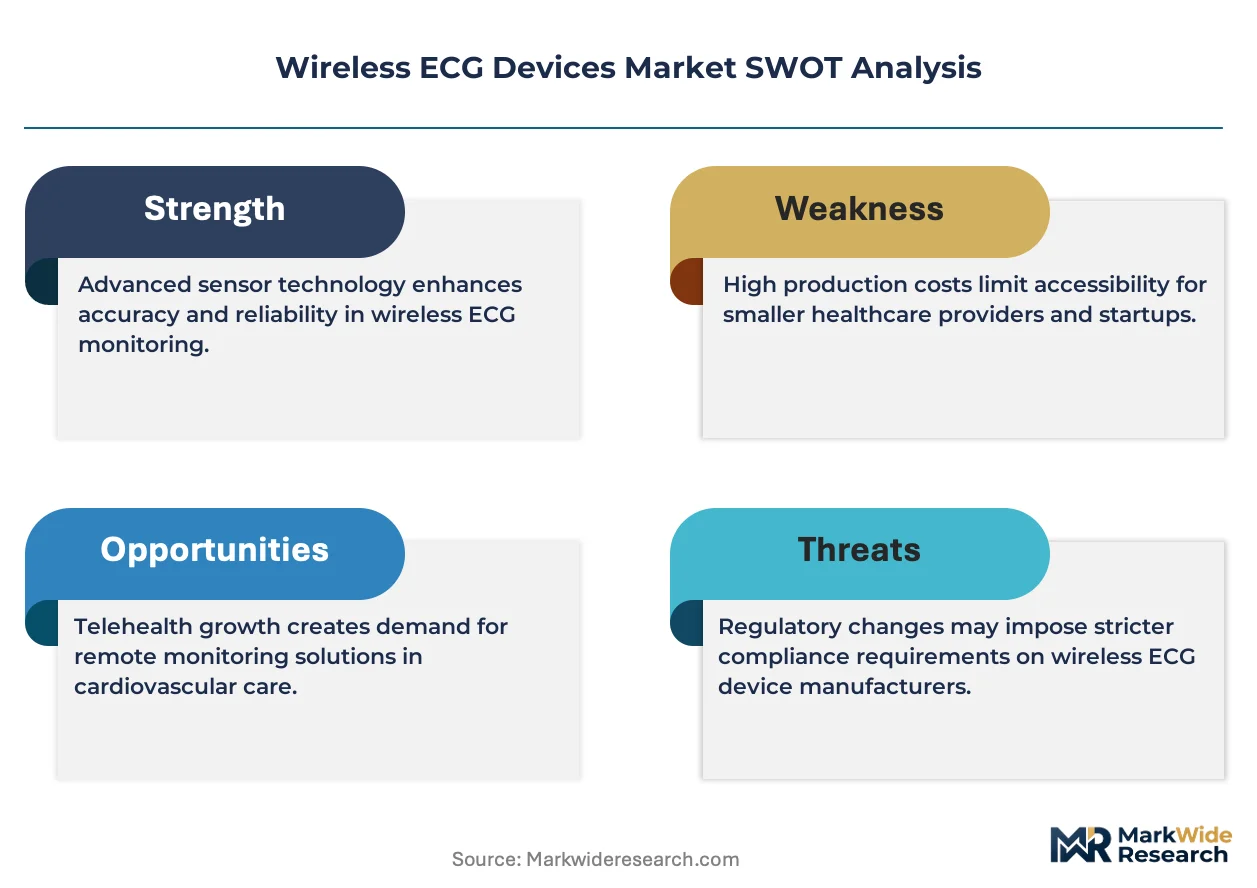
The Wireless ECG Devices Market operates as a stable compounder, driven by the sustained expansion of remote patient monitoring services globally.
For Market Incumbents: Deepen clinical validation efforts for AI-powered diagnostic algorithms to counter diagnostic accuracy concerns from consumer-grade devices. Strengthen partnerships with large hospital systems by investing in seamless EHR integration capabilities. Secure additional regulatory clearances across diverse geographies to mitigate market access threats from local competitors. Invest in robust data security infrastructure to address stringent privacy regulations like HIPAA and GDPR.
For New Entrants and Emerging Players: Telehealth platforms offer a strategic entry point for new entrants to access underserved patient populations in emerging markets. Target direct-to-consumer channels with mobile app-integrated devices, focusing on user experience and real-time feedback. Develop proprietary machine learning algorithms for automated arrhythmia detection to differentiate offerings. Focus on expanding into Asia-Pacific countries where digital health infrastructure is rapidly developing.
For Investors and Strategic Acquirers: Established medical technology conglomerates are the most active acquirers in this space, seeking to integrate advanced monitoring capabilities into their existing portfolios. The market offers long-term viability, underpinned by chronic disease management and remote care trends. Target companies specializing in AI-driven analytics, secure cloud-based solutions, or those with strong direct-to-consumer brand recognition. A critical signal to watch is the expansion of favorable reimbursement policies for remote cardiac monitoring services.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Acceleration | Expedites market entry for innovative devices in the United States, expanding patient access to new technologies. |
| CE Marking Pathway Optimization | Ensures compliance with Europe's MDR, critical for market access and physician trust in the European Union. |
| Hospital System Partnership | Secures large-volume contracts and integrates devices into established clinical workflows, enhancing physician adoption. |
| Software Companion Development | Adds value through AI-powered analytics and user-friendly interfaces, improving diagnostic insights for clinicians. |
| Reimbursement Strategy Development | Facilitates financial incentives for clinicians and telehealth providers, accelerating device adoption and utilization. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the market analysis. This included in-depth interviews with cardiology clinicians, hospital procurement managers, telehealth service providers, and medical device engineers. Secondary validation involved reviewing regulatory filings from the FDA and EMA, industry association reports, academic literature, and company annual reports. Both bottom-up and top-down triangulation methods were applied to ensure data accuracy and consistency.
Rate-of-change decomposition over the projection horizon informed the quantitative model, isolating the impact of key market dynamics. The analytical framework modeled segmentation dimensions including product type, end-user, technology, application, and device form factor. Compound annual growth rates were derived from historical data and projected market trends. Industry-specific forecast inputs included changes in reimbursement policies and chronic cardiovascular disease prevalence rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory changes and technological advancements. The analysis reflects assumptions regarding market forces and technological trajectories. A model refresh is warranted upon material change in remote patient monitoring reimbursement policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Polyglyconate Sutures Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
Global Gait Analysis System Market
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
Mechanical Chest Compression System Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
Global Artificial Kidney Market
Medical Devices
Indwelling Pleural Catheters Market
Medical Devices
Colon Hydrotherapy Units Market
Medical Devices
Oxygen Concentrators Market
Medical Devices
Indian Laparoscopy Devices Market
Medical Devices
Global Aneurysm Clips Market
Medical Devices
Global Large Volume Wearable Injectors Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
Pocket Otoscope Market