
 Thyroid Cancer Market | 2026-2036
Thyroid Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Thyroid Cancer Market Analysis
CE marking under the EU Medical Device Regulation is collapsing the window for non-compliant diagnostic equipment manufacturers seeking European market access. Roche leverages its integrated diagnostics portfolio to anchor molecular testing workflows across major oncology networks. Bayer competes through its radioactive iodine therapy supply chain, sustaining vertical control from isotope production through hospital delivery. Eisai specializes in kinase inhibitor development, differentiating its pipeline against differentiated thyroid carcinoma subtypes.
Thyroid cancer encompasses malignant neoplasms arising from follicular epithelial or parafollicular C cells of the thyroid gland, characterized by histological variants including papillary, follicular, medullary, and anaplastic forms with distinct genomic driver profiles and iodine avidity determining treatment pathways. Its primary commercial purpose centers on enabling staged therapeutic intervention ranging from surgical resection through systemic targeted therapy based on biomarker stratification. Targeted therapy commands the fastest expansion within product type segments, driven by RET and BRAF inhibitor approvals reshaping advanced disease management. Diagnostic laboratories represent a concentrated margin pool within end user segments, capturing high-value molecular profiling and serial monitoring workflows that lock in recurring revenue streams.
The FDA governs new drug approvals and companion diagnostic co-labeling requirements, while the EMA oversees centralized marketing authorizations across European member states through its Committee for Medicinal Products for Human Use. Both frameworks mandate escalating evidence standards for progression-free survival endpoints, directly shaping clinical trial investment and pipeline prioritization decisions among developers. Stakeholders must monitor evolving reimbursement policies for next-generation sequencing panels, as coverage determinations will dictate whether precision oncology approaches achieve scalable adoption in community oncology settings.
Market Dynamics
The thyroid cancer market pivots on precision medicine's penetration into community oncology settings, where biomarker-driven therapy selection is displacing empiric radioactive iodine protocols and compressing the addressable population for traditional interventions.
Growth Catalysts
- RET Inhibitor Approvals:The FDA's breakthrough therapy designation pathway accelerates selpercatinib and pralsetinib access for RET-altered medullary and differentiated thyroid carcinomas, expanding the precision oncology eligible population.
- Next-Generation Sequencing Reimbursement:Medicare coverage determinations for comprehensive genomic profiling in solid tumors enable molecular stratification at diagnosis, locking in recurring testing revenue for diagnostic laboratories.
- Specialized Thyroid Center Expansion:Academic medical centers in the United States consolidate surgical and medical oncology workflows, creating concentrated referral networks that standardize targeted therapy adoption.
Market Restraints
- Isotope Supply Concentration:Molybdenum-99 production concentrates in aging research reactors across Canada and Europe, creating vulnerability for radioactive iodine therapy supply chains serving North American patients.
- Companion Diagnostic Co-Development Costs:The FDA's requirement for simultaneous therapeutic and diagnostic validation extends development timelines and capital requirements for kinase inhibitor programs.
- Small Patient Populations:Anaplastic thyroid carcinoma incidence limits randomized trial feasibility, forcing reliance on single-arm studies that complicate payer evidence requirements for novel agents.
Strategic Opportunities
- Undiagnosed Differentiated Thyroid Cancer:Incidental nodule detection through cervical imaging for other indications creates a latent population in Japan and South Korea where ultrasound screening infrastructure exceeds biopsy capacity.
- AI-Enabled Nodule Risk Stratification:Machine learning algorithms integrated into ultrasound workstations reduce unnecessary fine-needle aspiration procedures, creating workflow efficiency value capture for radiology practices.
- Radioactive Iodine Refractory Definitions:EMA guidance evolution on iodine avidity thresholds expands the labeled indication for multikinase inhibitors, opening salvage therapy positioning for lenvatinib and sorafenib.
Industry Challenges
- Thyroid Pathologist Scarcity:Fellowship-trained cytopathologists capable of interpreting the Bethesda System for Reporting Thyroid Cytopathology concentrate in tertiary centers, creating diagnostic bottlenecks for community hospitals.
- Cross-Border Radiopharmaceutical Logistics:Radioactive iodine's short half-life demands just-in-time delivery coordination across fragmented hospital networks, with customs clearance variability disrupting treatment scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thyroid Cancer Market |
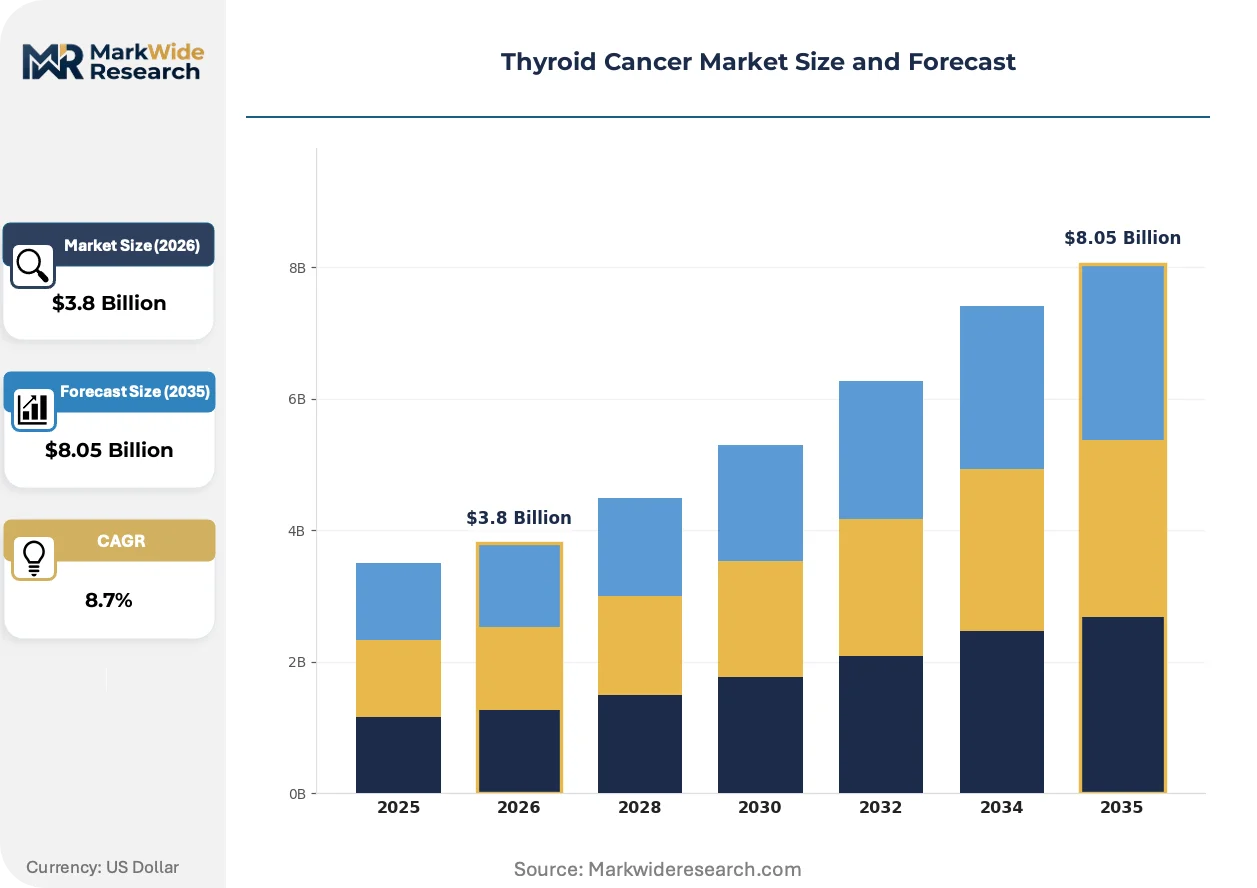
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Radioactive Iodine Therapy, Targeted Therapy, Chemotherapy End User: Hospitals, Oncology Clinics, Ambulatory Surgical Centers, Diagnostic Laboratories Technology: Ultrasound, CT Imaging, MRI, Biopsy Techniques Application: Diagnosis, Treatment, Monitoring, Research |
| Companies Covered | Roche, Bayer, Novartis, Eli Lilly and Company, Bristol-Myers Squibb, Eisai, Takeda Pharmaceutical Company, Pfizer, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thyroid Cancer Market Emerging Trajectories
Biomarker stratification is fragmenting the addressable patient population into molecularly defined subsegments, each requiring distinct therapeutic mechanisms and companion diagnostic pairings that reshape clinical trial design and commercial infrastructure.
Liquid biopsy circulating tumor DNA analysis is decomposing the traditional tissue-first diagnostic paradigm in differentiated thyroid carcinoma surveillance. Community oncology practices adopt plasma-based BRAF and RAS mutation monitoring to detect recurrence without repeat neck ultrasound. This technology is compressing the window for centralized reference laboratory molecular testing by enabling point-of-care genomic information.
EMA's In Vitro Diagnostic Medical Devices Regulation imposes new conformity assessment requirements on multigene panel assays used for thyroid nodule malignancy risk stratification. Manufacturers face notified body capacity constraints that delay CE marking renewals. Medium-sized diagnostic companies are responding by narrowing panel content to core oncogenic drivers to accelerate technical documentation completion.
Patient navigation programs now coordinate surgical, endocrinology, and medical oncology appointments through single-entry intake processes at high-volume thyroid centers. This integrated care model displaces fragmented referral patterns where patients self-coordinate between specialists. The United States exhibits the most advanced deployment, with bundled episode payments incentivizing care coordination investments.
Thyroid Cancer Market Segmentation
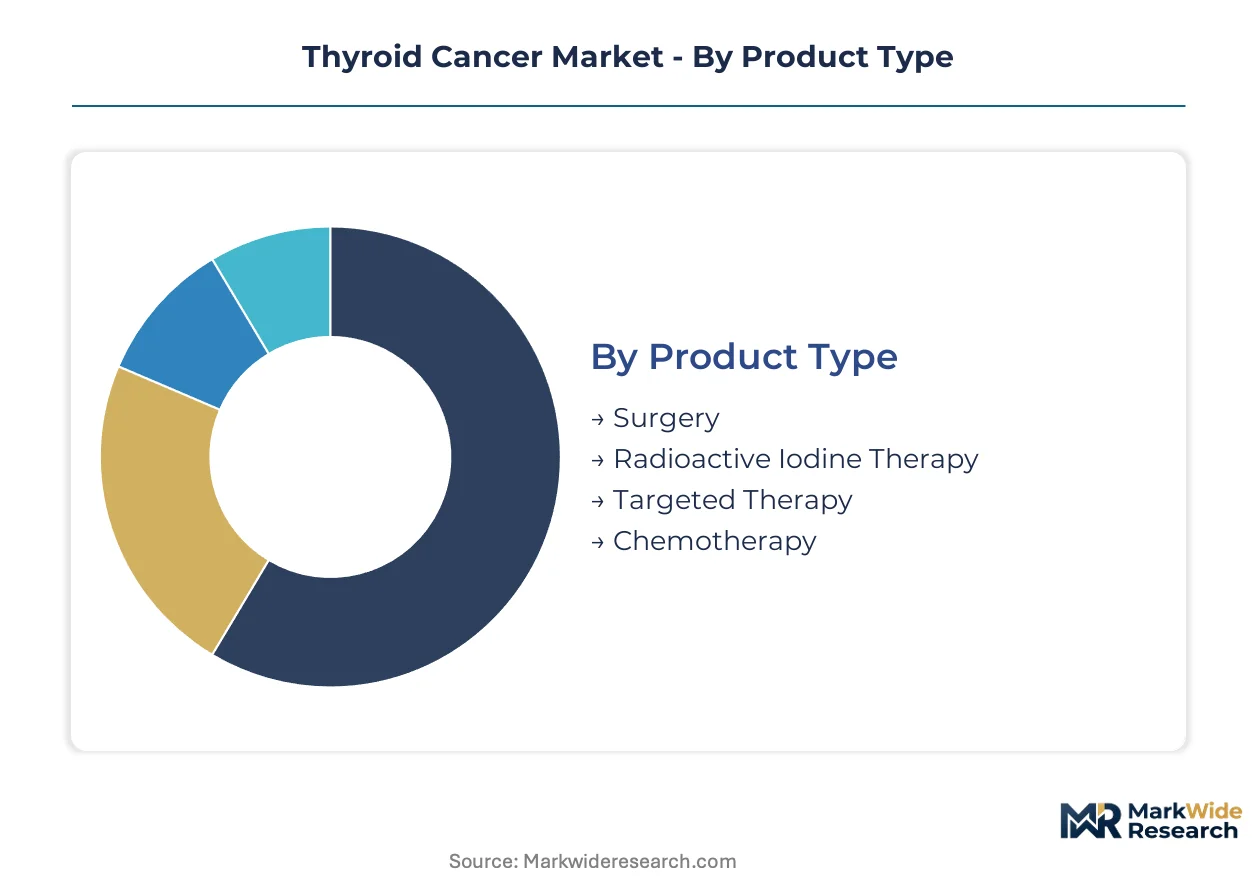
Thyroid cancer treatment pathways fragment across multiple intervention modalities, each commanding distinct reimbursement profiles and facility infrastructure requirements. Segmentation reveals where precision medicine is compressing traditional radioactive iodine volumes and redirecting capital toward molecular diagnostics.
Product Type:
Margin pools concentrate in systemic therapy segments where kinase inhibitors command premium pricing and extended duration of use.
- Surgery:Thyroidectomy and lymph node dissection procedures remain the foundational intervention for localized disease. Demand concentrates in high-volume academic medical centers in the United States where specialized endocrine surgeons reduce complication rates and justify bundled payment structures.
- Targeted Therapy:Selective RET and BRAF inhibitors deliver progression-free survival advantages in molecularly defined populations. Prescription volume is rotating toward community oncology practices as Medicare reimbursement for companion diagnostic testing standardizes biomarker-driven selection protocols.
- Radioactive Iodine Therapy:Iodine-131 ablation protocols face compression as active surveillance expands for low-risk differentiated carcinomas.
- Chemotherapy:Doxorubicin regimens retain niche positioning in anaplastic thyroid carcinoma where targeted options remain limited.
Surgery holds installed capacity across established referral networks. Targeted therapy is rotating up the share rankings as molecular eligibility criteria broaden.
End User:
Diagnostic laboratories capture recurring revenue through serial monitoring workflows that lock in long-term contractual relationships with oncology practices.
- Diagnostic Laboratories:Centralized reference labs process multigene panel testing for nodule risk stratification and recurrence surveillance. Volume concentrates in CAP-accredited facilities in the United States where PAMA reimbursement rates determine profitability of next-generation sequencing workflows.
- Oncology Clinics:Community-based practices integrate targeted therapy administration with molecular tumor board consultations. Patient flow is expanding fastest at regional cancer centers where clinical trial access attracts RET-altered and BRAF-mutant cases from surrounding geographies.
- Hospitals:Academic medical centers coordinate surgical resection, radioactive iodine therapy, and systemic treatment through multidisciplinary tumor boards.
- Ambulatory Surgical Centers:Limited to diagnostic thyroidectomy procedures in select markets where certificate-of-need restrictions permit outpatient thyroid surgery.
Hospitals hold installed capacity across comprehensive cancer center designations. Oncology clinics are rotating up the share rankings as site-of-care shifts favor infusion center economics.
Technology:
Imaging modalities fragment by diagnostic yield versus procedural cost tradeoffs that vary across healthcare system reimbursement environments.
- Ultrasound:High-frequency transducers enable TI-RADS scoring for nodule malignancy risk stratification. Deployment concentrates in Japan and South Korea where population screening programs generate volume that supports dedicated thyroid sonographer staffing models.
- Biopsy Techniques:Ultrasound-guided fine-needle aspiration with on-site cytology evaluation reduces nondiagnostic sampling rates. Adoption is expanding fastest at high-volume United States centers where rapid onsite evaluation justifies specialized cytopathologist presence.
- CT Imaging:Contrast-enhanced protocols assess extrathyroidal extension and distant metastasis in advanced disease staging.
- MRI:Reserved for recurrent laryngeal nerve mapping and substernal goiter evaluation where iodinated contrast is contraindicated.
Ultrasound holds installed capacity across primary care and radiology workflows. Biopsy techniques are rotating up the share rankings as molecular testing requirements increase specimen adequacy standards.
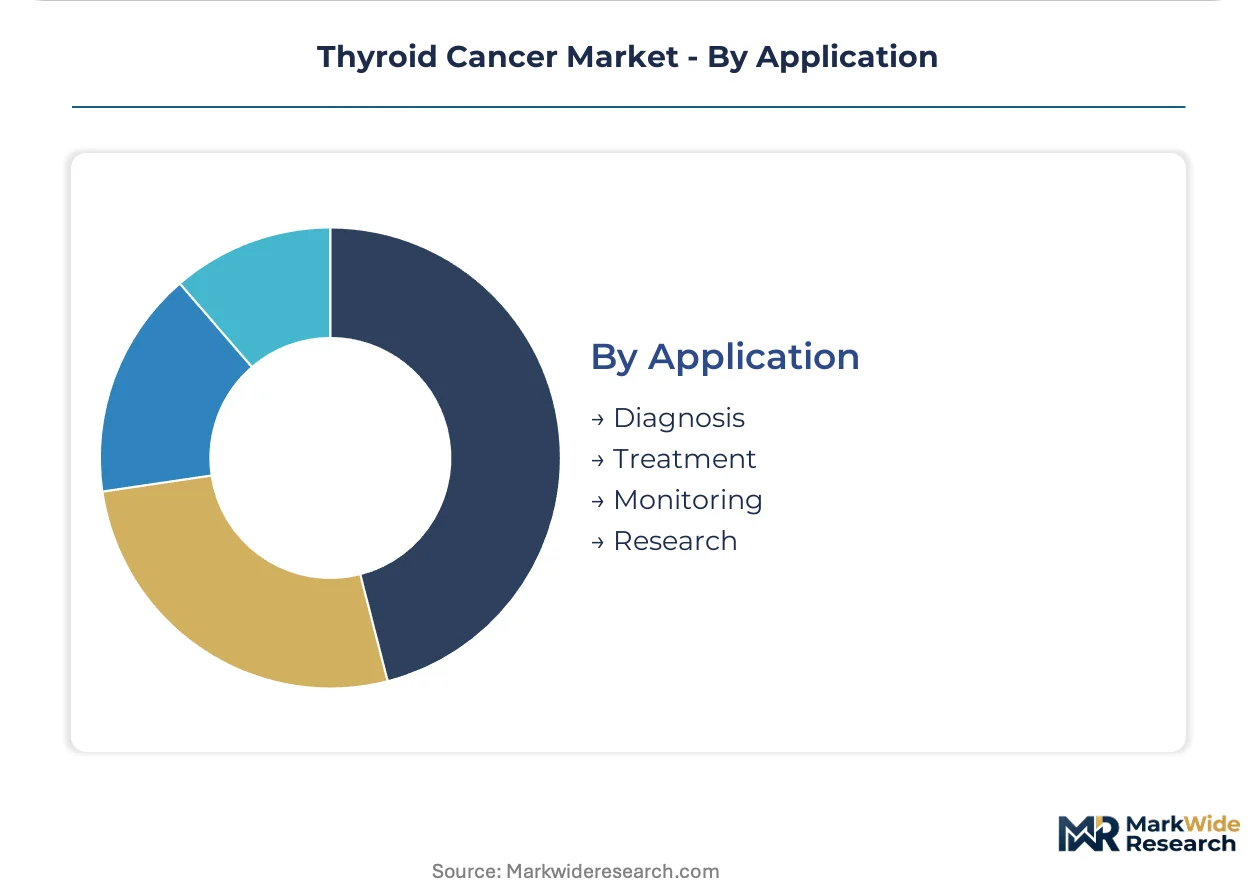
Application:
Recurring monitoring applications generate predictable revenue streams that offset cyclical diagnostic procedure volumes.
- Treatment:Surgical, radioactive, and pharmacologic interventions deliver curative intent or palliative disease control. Resource allocation concentrates in the United States where specialty pharmacy networks manage oral kinase inhibitor distribution and adherence monitoring.
- Monitoring:Serum thyroglobulin testing and neck ultrasound surveillance detect recurrence in differentiated carcinoma follow-up. Liquid biopsy adoption is expanding fastest at community oncology practices seeking to reduce imaging frequency through circulating tumor DNA analysis.
- Diagnosis:Cytology and molecular testing establish histology and driver mutation status for initial risk stratification.
- Research:Biobanking and clinical trial enrollment support pipeline development for novel targeted agents.
Treatment holds installed capacity across established reimbursement pathways. Monitoring is rotating up the share rankings as extended survival durations lengthen follow-up care requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's orphan drug designation framework accelerates novel therapeutic approvals in the United States, while EMA's centralized marketing authorization system shapes European access timelines. Japan's PMDA operates accelerated review pathways for rare cancers. These regulatory architectures concentrate investment in established approval jurisdictions.
United States
Specialized thyroid centers at academic medical centers drive treatment volume consolidation. Medicare coverage determinations for comprehensive genomic profiling enable molecular stratification at diagnosis. The MD Anderson Cancer Center in Houston anchors a referral network standardizing targeted therapy protocols across the Southwest.
Germany
Reference laboratory networks process multigene panel testing for nodule risk stratification under EMA oversight. The country's statutory health insurance system mandates evidence thresholds for progression-free survival endpoints. Heidelberg University Hospital coordinates surgical and medical oncology workflows through multidisciplinary tumor boards.
Japan
Population ultrasound screening programs generate incidental nodule detection volumes exceeding biopsy capacity. PMDA's sakigake designation accelerates access to RET inhibitors for medullary carcinoma subtypes. Tokyo Medical University Hospital maintains dedicated thyroid sonographer staffing models that reduce nondiagnostic sampling rates.
South Korea
National cancer screening infrastructure drives differentiated thyroid carcinoma diagnosis at earlier stages. MFDS regulates companion diagnostic co-labeling requirements for kinase inhibitor approvals. Seoul National University Hospital integrates AI-enabled nodule risk stratification into routine ultrasound workflows.
Switzerland
Swissmedic oversees marketing authorizations for radioactive iodine therapy supply chains serving alpine region patients. The country's centralized procurement system negotiates reimbursement for multikinase inhibitors. University Hospital Zurich maintains vertical control from isotope sourcing through hospital delivery logistics.
Thyroid Cancer Market Vendor Landscape
Player mix skews toward integrated pharmaceutical conglomerates with diagnostic and therapeutic capabilities. The competitive structure concentrates around three archetypes: diversified oncology portfolio holders, radiopharmaceutical supply chain controllers, and kinase inhibitor specialists. M&A activity targets molecular diagnostic capabilities, while portfolio diversification extends into companion diagnostic co-development partnerships.
Among diversified pharmaceutical conglomerates, Roche and Bayer occupy positions anchoring integrated diagnostics-to-therapy workflows. Eisai represents the kinase inhibitor specialist archetype, with its development pipeline differentiated against specific carcinoma subtypes. These three companies exemplify the strategic segmentation between diagnostic platform control, radiopharmaceutical supply chain mastery, and targeted therapeutic innovation.
| Leading Market Players |
|---|
| Roche |
| Bayer |
| Novartis |
| Eli Lilly and Company |
| Bristol-Myers Squibb |
| Eisai |
| Takeda Pharmaceutical Company |
| Pfizer |
| Sanofi |
| Others |
Supply Flow & Price Mechanics
Sixty-day lead times for Molybdenum-99 isotope sourcing concentrate pricing power with aging research reactor operators in Canada and Europe, while radioactive iodine therapy's short half-life compresses downstream margin capture for hospital networks managing just-in-time delivery coordination.
Pricing Analysis
Certification level (FDA-breakthrough versus standard NDA pathways) creates the primary spread between selpercatinib and pralsetinib positioning against multikinase inhibitors. Three-tier pricing structure across premium RET inhibitors, standard radioactive iodine protocols, and economy-tier chemotherapy regimens reflects biomarker stratification depth. Cost compression in radioactive iodine therapy is intensifying because active surveillance protocols reduce ablation volumes for low-risk differentiated carcinomas. Community oncology practices exhibit highest price sensitivity due to Medicare reimbursement rate compression for companion diagnostic testing, while academic medical centers absorb premium pricing through bundled episode payments.
Supply Chain Analysis
Port congestion at Rotterdam and Antwerp disrupts cold-chain logistics for radiopharmaceuticals moving from European isotope production facilities to North American treatment centers. Molybdenum-99 supply concentrates in Canada, the Netherlands, and South Africa, with pharmaceutical-grade iodine-131 production anchored in Belgium and Poland. The supply chain draws from enriched uranium targets, specialized reactor irradiation capacity, and on-site radiopharmacy compounding infrastructure. Single-source vulnerability concentrates in the NRU reactor replacement timeline, with distribution running through hospital-based nuclear medicine departments and specialized radiopharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision medicine penetration into community oncology settings represents an early-cycle expansion story, with Medicare coverage determinations for comprehensive genomic profiling accelerating biomarker-driven therapy selection displacement of empiric protocols.
For Market Incumbents: Fortify companion diagnostic co-development partnerships to lock in molecular testing workflows before laboratory-developed test regulations tighten. Deepen vertical integration into radioactive iodine supply chains through long-term offtake agreements with isotope producers, countering the threat of Molybdenum-99 reactor closures. Prioritize CAP-accredited laboratory capacity additions in the United States to capture PAMA reimbursement rate advantages before reference lab consolidation accelerates. For New Entrants and Emerging Players: Anchor in AI-enabled nodule risk stratification software for ultrasound workstations, where radiology practice workflow efficiency creates immediate value capture. Target the undiagnosed differentiated thyroid cancer population in Japan and South Korea, where screening infrastructure exceeds biopsy capacity and incidentally detected nodules await molecular characterization. Pursue hospital system partnerships for integrated patient navigation programs as the go-to-market angle, displacing fragmented specialist referral patterns. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting orphan oncology assets below portfolio-scale thresholds, particularly kinase inhibitor programs with single-indication positioning. Long-term viability hinges on molecular diagnostic platform control and radiopharmaceutical supply chain mastery across the precision medicine transition. Watch liquid biopsy reimbursement determinations as the inflection signal for whether circulating tumor DNA surveillance achieves scalable community adoption or remains concentrated in academic reference laboratories.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | Locks in FDA co-labeling requirements for selpercatinib and pralsetinib biomarker eligibility. |
| Radioactive Iodine Supply Chain Integration | Captures vertical control from Molybdenum-99 sourcing through hospital radiopharmacy delivery. |
| AI-Enabled Nodule Risk Stratification Launch | Reduces unnecessary fine-needle aspiration procedures for radiology practices adopting TI-RADS workflows. |
| Multidisciplinary Tumor Board Expansion | Consolidates surgical, endocrinology, and medical oncology referrals at high-volume thyroid centers. |
| Liquid Biopsy Reimbursement Strategy | Secures Medicare coverage for circulating tumor DNA monitoring to compress imaging surveillance frequency. |
Methodological Framework
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient flow modeling across treatment lines and top-down pharmaceutical revenue triangulation anchored volume estimates.
Variance decomposition across product type, end user, technology, and application segments isolated growth contribution by molecularly defined patient subpopulations. CAGRs were derived from log-linear trend fitting across the projection horizon, with progression-free survival endpoint data and companion diagnostic adoption curves as thyroid cancer-specific forecast inputs.
Underlying assumptions cover regulatory approval timelines for RET and BRAF inhibitors, with deviation risk concentrated in Medicare coverage determination delays for next-generation sequencing panels and Molybdenum-99 supply disruptions from reactor maintenance schedules. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Asia-Pacific Tumor Ablation Market
Oncology
Lung Cancer Treatment Market
Oncology
Bone Cancer Market
Oncology
Cancer Supportive Care Products Market
Oncology
Bone Cancer Treatment Market
Oncology
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Glottic Cancer Treatment Market
Oncology
Oncology Devices Market
Oncology
Global HER-2 Negative Breast Cancer Market
Oncology
Global Neuroendocrine Tumor Treatment Market
Oncology
Global Non-Small Cell Lung Cancer (NSCLC) Market
Oncology
Triple-Negative Breast Cancer Market
Oncology
Europe Proton Therapy Market
Oncology
Paraneoplastic Syndromes Market
Oncology
Colorectal Cancer Treatment Market
Oncology
Pharyngeal Neoplasm Market