
 Global Cardiology Electrodes Market | 2026-2036
Global Cardiology Electrodes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiology Electrodes Market Analysis
The cardiology electrodes market is restructuring around a widening gap between premium silver-silver chloride formulations and commodity conductive adhesive alternatives. 3M Company leverages its materials science heritage to dominate high-performance hospital contracts, while Ambu A/S specializes in single-use disposable electrodes that reduce cross-contamination risk. Cardinal Health sustains broad distribution control across North American acute care channels, competing on logistics scale rather than proprietary chemistry.
Cardiology electrodes are conductive interfaces that transmit bioelectrical signals from the skin surface to monitoring equipment, typically incorporating an Ag/AgCl sensing element, hydrogel adhesive layer, and snap or clip connector with impedance specifications below 5,000 ohms. Their primary purpose is to enable accurate cardiac signal acquisition for diagnostic and therapeutic decision-making in clinical and ambulatory settings. Surface electrodes occupy the mature volume base in electrocardiogram applications, while wearable electrodes represent the fastest-expanding segment as remote patient monitoring programs proliferate. Invasive electrodes command concentrated margin pools in electrophysiology procedures where signal fidelity directly ablation outcomes.
FDA 510(k) clearance requirements and the EU MDR's tightened clinical evidence standards are extending product development timelines and favoring manufacturers with dedicated regulatory affairs infrastructure. ISO 13485 quality management certification has become a non-negotiable market access threshold across both the United States and European hospital procurement systems. Stakeholders must monitor how reimbursement shifts toward remote cardiac monitoring reshape volume allocation between disposable and reusable electrode formats.
Market Dynamics
Hospital procurement consolidation and the FDA's evolving 510(k) validation standards are compressing vendor margins while elevating barriers for new entrants without dedicated regulatory infrastructure.
Growth Catalysts
- EU MDR clinical evidence mandates:Tightened post-market surveillance requirements favor incumbent manufacturers with established quality management systems, accelerating hospital preference for certified suppliers.
- Wearable cardiac monitoring:Remote patient monitoring programs in the United States and Germany are expanding electrode volumes beyond traditional acute care settings into ambulatory and home-based applications.
- Silver-silver chloride chemistry:Superior signal fidelity in electrophysiology procedures is concentrating procurement decisions around premium conductive formulations for ablation guidance.
Market Restraints
- Silver price volatility:Ag/AgCl electrode production faces input cost pressure from precious metal commodity swings, compressing margins on standardized hospital contracts.
- Single-source hydrogel supply:Proprietary adhesive formulations from concentrated specialty chemical suppliers in Germany and Japan create vulnerability in just-in-time manufacturing.
- Biocompatibility testing burden:ISO 10993 cytotoxicity and sensitization protocols extend validation timelines for novel skin-contact materials.
Strategic Opportunities
- Japan's electrophysiology lab expansion:METI-backed cardiovascular infrastructure investment is opening procurement channels for high-fidelity invasive electrodes in underpenetrated regional hospitals.
- Wireless electrode integration:Bluetooth-enabled disposable patches combined with cloud-based ECG analytics are creating new reimbursement categories in remote cardiac monitoring.
- CE marking mutual recognition:Streamlined EU MDR conformity assessment pathways are reducing time-to-market for manufacturers with existing FDA 510(k) clearances.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in bioelectrical signal processing and hydrogel polymer science is concentrating at established medical device hubs, constraining R&D scaling.
- Legacy ECG system compatibility:Hospital-installed base of proprietary connector standards forces electrode manufacturers to maintain fragmented SKU portfolios, complicating production economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiology Electrodes Market |
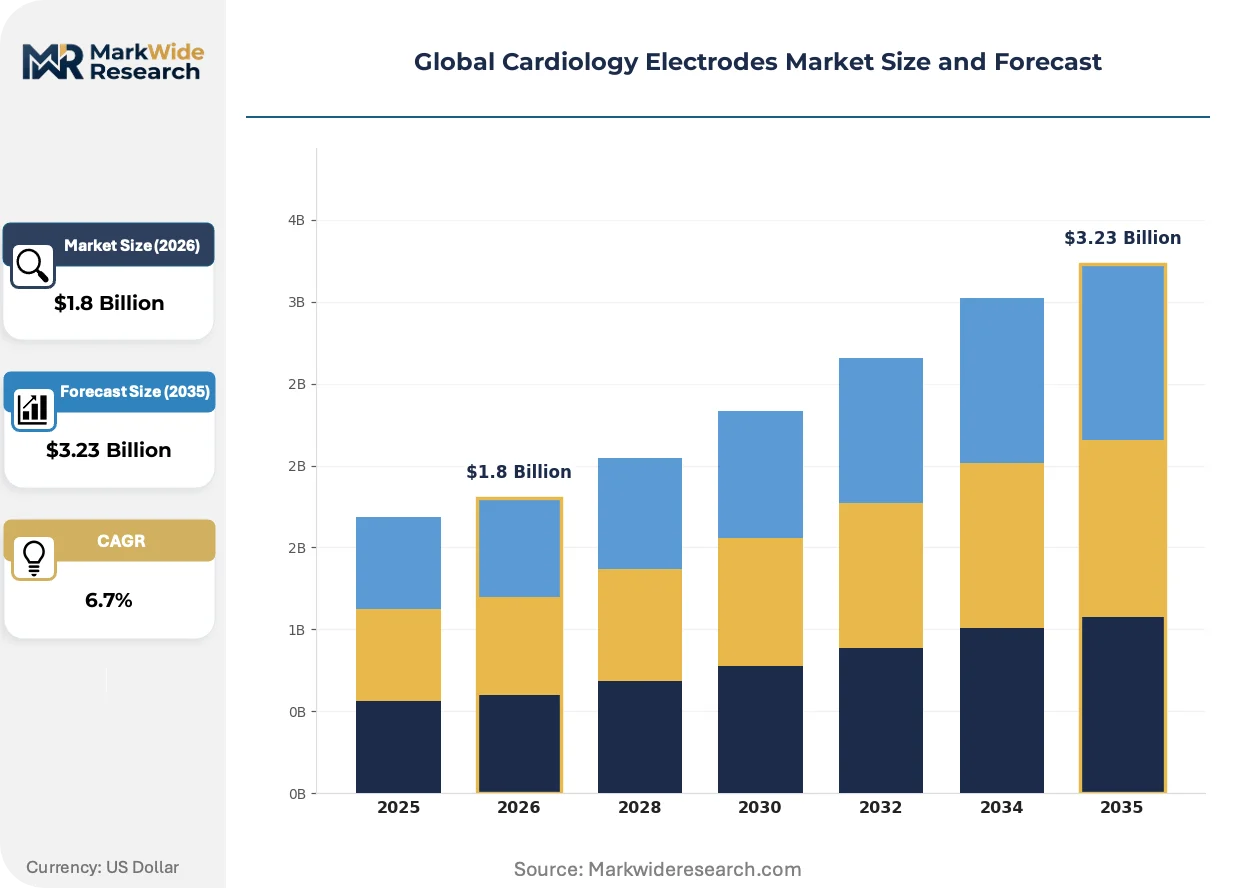
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Electrodes, Invasive Electrodes, Wearable Electrodes, Reusable Electrodes Technology: Conductive Polymer, Metal, Carbon, Nanomaterials End User: Hospitals, Research Institutes, Home Care, Diagnostic Centers Application: Electrocardiogram, Electrophysiology, Cardiac Monitoring, Stress Testing |
| Companies Covered | 3M Company, Cardinal Health, Koninklijke Philips, Ambu A/S, Nihon Kohden Corporation, CONMED Corporation, GE HealthCare, ZOLL Medical Corporation, Nissha Medical Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiology Electrodes Market Emerging Trajectories
Materials science convergence with digital health infrastructure is redefining electrode value propositions from passive conductive interfaces to active diagnostic components with embedded intelligence.
Conductive polymer nanocomposites incorporating carbon nanotube or graphene dispersions are expanding into stretchable wearable form factors that maintain impedance stability during patient motion. Cardiac rehabilitation centers and sports medicine clinics in Germany are piloting these materials for continuous Holter monitoring applications. The technology is expanding into traditional ECG market segments previously dominated by rigid Ag/AgCl discs.
EU MDR Article 10 clinical evaluation requirements are forcing manufacturers to generate prospective performance data rather than relying on predicate device equivalence. Small-to-mid tier suppliers without dedicated clinical affairs teams are exiting the European market, concentrating procurement options around vertically integrated multinationals. Electrophysiology catheter electrodes face the steepest compliance burden due to their invasive classification.
Hospital group purchasing organizations are unbundling electrode procurement from capital equipment bundles, creating standalone SKU negotiations that prioritize unit economics over system compatibility. Acute care networks in the United States are consolidating supplier panels to three-to-five approved vendors per category. This consolidation is most advanced in integrated delivery networks spanning multiple states with centralized supply chain authority.
Global Cardiology Electrodes Market Segmentation
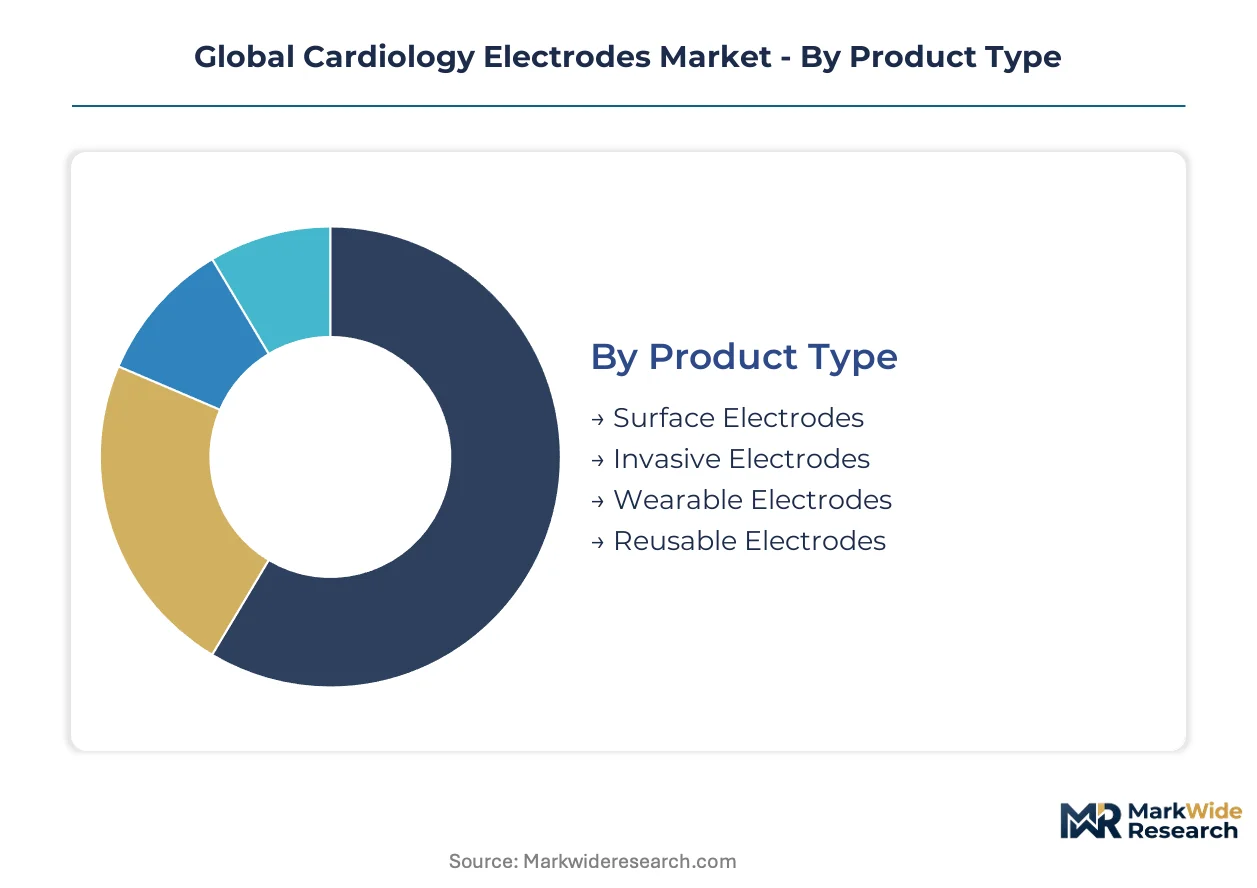
Cardiology electrode procurement splits across incompatible technical specifications, regulatory classifications, and care settings. Manufacturers must maintain parallel production lines to serve hospital electrophysiology labs, ambulatory monitoring programs, and emerging home-based cardiac surveillance simultaneously.
Product Type:
Supply concentration in Ag/AgCl chemistry and hydrogel adhesive formulation creates divergent margin profiles across disposable and durable formats.
- Surface Electrodes:Standardized Ag/AgCl discs with hydrogel adhesive layers dominate high-volume ECG procedures in United States emergency departments and German cardiac wards. Hospital group purchasing organizations in these countries negotiate multi-year contracts that lock in procurement volumes and compress per-unit pricing.
- Wearable Electrodes:Stretchable conductive polymer patches with integrated Bluetooth transmitters are gaining share in United States remote patient monitoring programs reimbursed under expanded CPT codes. German cardiac rehabilitation centers pilot these devices for continuous Holter monitoring during patient ambulation.
- Invasive Electrodes:Catheter-mounted sensing elements for electrophysiology ablation guidance command premium pricing in Japan's expanding EP lab network.
- Reusable Electrodes:Sterilizable metal-plated discs serve cost-conscious diagnostic centers in India with limited single-use budget allocation.
Surface electrodes absorb the bulk of installed capacity; wearable electrodes are expanding most quickly.
Technology:
Material selection dictates impedance stability, biocompatibility certification burden, and compatibility with legacy monitoring infrastructure.
- Conductive Polymer:Hydrogel-embedded polymer matrices with tunable adhesion properties balance signal fidelity against skin irritation risk in extended-wear applications. United States home care agencies specify these formulations for 7-day ambulatory monitoring protocols.
- Metal:Silver-silver chloride sintered pellets remain the reference standard for diagnostic-grade signal acquisition in electrophysiology procedures where ablation accuracy depends on microvolt-level resolution.
- Carbon:Graphite-loaded elastomers offer cost reduction for high-volume disposable electrodes in Indian diagnostic chains with price-sensitive procurement.
- Nanomaterials:Carbon nanotube dispersions enable stretchable form factors maintaining impedance stability under mechanical deformation.
Metal formulations retain the highest revenue per unit; nanomaterials are climbing the fastest as wearable form factors penetrate ambulatory care.
End User:
Procurement authority and reimbursement pathways fragment demand across institutional, research, and consumer-directed channels.
- Hospitals:Integrated delivery networks in the United States consolidate electrode purchasing through centralized supply chain offices, favoring vendors with ISO 13485 certification and FDA 510(k) clearance breadth. Electrophysiology lab expansion in Japan's regional hospitals is opening new account acquisition opportunities.
- Diagnostic Centers:High-throughput ECG screening facilities in India and Brazil prioritize unit economics over signal fidelity, sourcing commodity conductive adhesive alternatives.
- Research Institutes:Academic medical centers in Germany require custom electrode configurations for investigational cardiac mapping studies.
- Home Care:Direct-to-consumer channels in the United States are emerging as reimbursement shifts enable remote cardiac monitoring prescriptions.
Hospitals command the largest procurement volumes; home care channels are gaining share fastest as reimbursement extends beyond acute settings.
Application:
Clinical use case determines performance specifications, regulatory classification, and pricing tier.
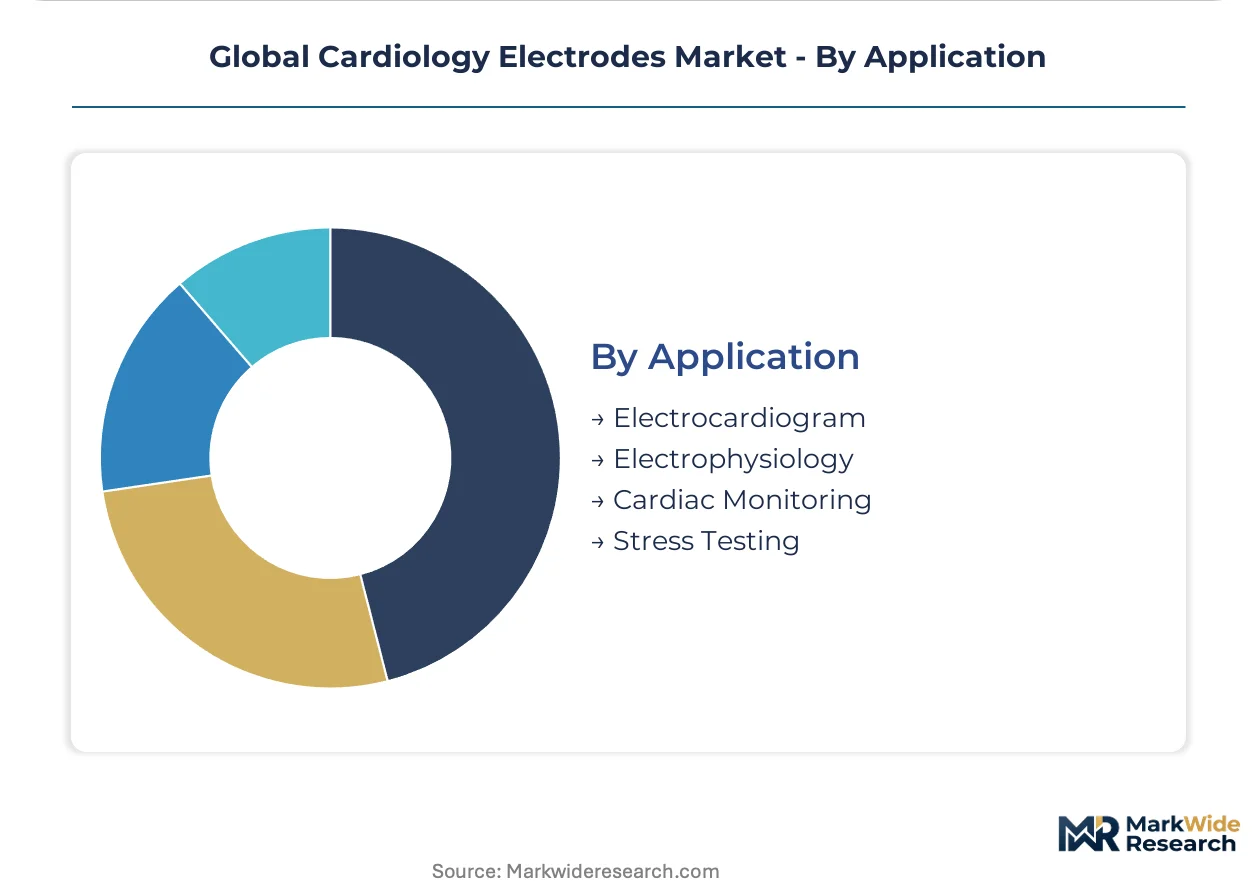
- Electrocardiogram:Standard 12-lead diagnostic procedures utilize disposable surface electrodes with established IEC 60601-2-25 compliance, representing the mature volume base across all major markets.
- Electrophysiology:Invasive catheter electrodes for arrhythmia ablation require sub-millimeter positioning accuracy and stable impedance across temperature fluctuations during radiofrequency energy delivery.
- Cardiac Monitoring:Continuous telemetry and event recorder applications in German hospitals and United States ambulatory settings demand extended-wear adhesion without skin irritation.
- Stress Testing:Treadmill ECG protocols require electrodes with motion-resistant signal stability and rapid application for high-patient-throughput cardiac labs.
Electrocardiogram applications anchor current production volumes; cardiac monitoring applications show the steepest expansion trajectory as remote patient surveillance programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American electrode manufacturing through 3M Company's materials science operations, while Tokyo and Osaka drive Asia-Pacific demand via electrophysiology lab networks. European procurement concentrates in German cardiac wards and research institutes.
United States
FDA 510(k) clearance requirements for diagnostic devices elevate validation standards for electrode manufacturers seeking hospital contracts. Remote patient monitoring programs reimbursed under expanded CPT codes drive wearable electrode volumes beyond acute care settings. The Minneapolis-St. Paul corridor hosts concentrated materials science operations serving integrated delivery networks.
Germany
EU MDR clinical evidence mandates favor incumbent manufacturers with established quality management systems in hospital procurement decisions. Cardiac rehabilitation centers in Bavaria pilot stretchable conductive polymer patches for continuous Holter monitoring. The Baden-Württemberg region clusters specialty chemical suppliers for proprietary hydrogel adhesive formulations.
Japan
METI-backed cardiovascular infrastructure investment opens procurement channels for high-fidelity invasive electrodes in regional hospitals. PMDA regulatory frameworks align with international standards while maintaining distinct documentation requirements. The Osaka-Kobe industrial zone concentrates electrophysiology catheter electrode production for domestic EP lab expansion.
India
Cost-conscious diagnostic centers in Maharashtra and Gujarat prioritize unit economics over signal fidelity for high-throughput ECG screening. CDSCO medical device regulations create compliance thresholds for imported electrode products. The Delhi-NCR corridor hosts distribution hubs serving price-sensitive procurement across northern diagnostic chains.
United Kingdom
NHS procurement consolidation favors vendors with ISO 13485 certification breadth for standardized hospital contracts. The MHRA operates post-Brexit regulatory pathways distinct from EU MDR conformity assessment. London's academic medical centers require custom electrode configurations for investigational cardiac mapping studies.
Global Cardiology Electrodes Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the electrode value chain, with materials science heritage separating premium formulation specialists from commodity assemblers. The vendor base concentrates around three strategic archetypes: vertically integrated multinationals controlling proprietary chemistry, regional distributors competing on logistics scale, and disposable-focused specialists reducing cross-contamination risk. Dominant competitive moves include hospital group purchasing organization panel consolidation and regulatory infrastructure investments to accelerate multi-market clearances.
Within the vertically integrated tier, 3M Company and Cardinal Health exemplify divergent paths—3M leverages captive materials science capabilities for high-performance hospital contracts, while Cardinal sustains broad distribution control across North American acute care channels. Ambu A/S occupies a position representing the disposable-specialist archetype, with its Danish corporate structure signaling European regulatory fluency. Koninklijke Philips and GE HealthCare anchor the diversified medical technology conglomerate segment, their scale enabling parallel compliance with FDA 510(k) and EU MDR frameworks.
| Leading Market Players |
|---|
| 3M Company |
| Cardinal Health |
| Koninklijke Philips |
| Ambu A/S |
| Nihon Kohden Corporation |
| CONMED Corporation |
| GE HealthCare |
| ZOLL Medical Corporation |
| Nissha Medical Technologies |
| Others |
Supply Flow & Price Mechanics
Integrated delivery networks in the United States and German hospital procurement consortia command concentrated purchasing power that enforces contract-based long-term offtake structures with locked volume commitments. This buyer concentration compresses per-unit pricing for standardized Ag/AgCl surface electrodes while preserving premium tiers for invasive electrophysiology applications where signal fidelity governs clinical outcomes.
Pricing Analysis
Value-based pricing anchored to ablation procedure accuracy and patient throughput metrics governs the invasive electrode segment. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified hospital-grade formulations from commodity conductive adhesive alternatives for diagnostic centers. Cost compression in the standard tier intensifies because silver price volatility feeds directly into Ag/AgCl pellet production economics. Diagnostic chains in India exhibit the highest price sensitivity, while Japanese electrophysiology labs show the least due to outcome-linked reimbursement for arrhythmia procedures.
Supply Chain Analysis
Silver-silver chloride pellet supply rests on specialty chemical producers in Germany and Japan, with hydrogel adhesive formulation concentrated among Baden-Württemberg polymer science clusters. Raw material dependencies span silver bullion markets, medical-grade hydrogel precursors, and proprietary snap connector metals. Single-source vulnerability in just-in-time hydrogel delivery creates exposure to regional logistics disruptions. Distribution runs through hospital group purchasing organizations in North America and centralized NHS supply frameworks in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cardiology electrode market sits in a materials-transition phase as stretchable conductive polymer nanocomposites displace rigid Ag/AgCl discs in wearable and ambulatory monitoring applications.
For Market Incumbents: Anchor defensive positioning through captive control of hydrogel polymer science capabilities and ISO 13485 certification breadth across multiple regulatory jurisdictions. Threat from Bluetooth-enabled disposable patch entrants demands accelerated software companion development for cloud-based ECG analytics integration. Backward integration into specialty chemical supply secures margin protection against silver commodity swings. For New Entrants and Emerging Players: Capture white-space opportunity in Japan's regional electrophysiology lab expansion where METI infrastructure investment outpaces established vendor penetration. The home care channel in the United States offers the most penetrable segment as reimbursement shifts enable remote cardiac monitoring prescriptions outside acute settings. Go-to-market execution should prioritize direct-to-clinician digital health partnerships over traditional hospital supply chain integration. For Investors and Strategic Acquirers: The window for entry favors materials science specialists with existing FDA 510(k) clearances and EU MDR technical documentation capabilities. Long-term viability hinges on differentiation through embedded intelligence and wireless connectivity rather than commodity electrode assembly. Watch for PMDA regulatory harmonization signals as the inflection indicator for Asia-Pacific market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance accelerates hospital procurement panel inclusion in Germany. |
| Hospital System Partnership | Integrated delivery network contracts lock multi-year volumes for acute care electrode supply. |
| Software Companion Development | Bluetooth-enabled patches require cloud analytics integration for remote monitoring reimbursement. |
| Backward Integration | Captive hydrogel production insulates margins from German specialty chemical supplier concentration. |
| Reimbursement Strategy | Expanded CPT code alignment drives wearable electrode volume in United States ambulatory settings. |
Methodological Framework
FDA 510(k) device clearances, EU MDR technical documentation databases, and hospital procurement contract records formed the secondary backbone of this analysis. Primary interviews with biomedical engineers, electrophysiology lab directors, GPO contracts managers, and hydrogel polymer scientists combined with secondary validation through ISO 13485 certification registries and silver commodity trade data. Bottom-up electrode shipment modeling and top-down cardiac monitoring equipment market sizing provided triangulation across the analysis window.
Historical trendline analysis of Ag/AgCl raw material costs, hydrogel formulation patents, and regulatory approval timelines informed the projection framework. Segmentation dimensions modeled include product type, conductive material chemistry, end-user channel, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections incorporating reimbursement pathway expansion and electrophysiology lab network growth. Forecast inputs included METI cardiovascular infrastructure budgets and CMS remote monitoring reimbursement schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silver price volatility, EU MDR post-market surveillance enforcement intensity, and PMDA regulatory harmonization timing. Forecasts reflect documented assumptions about reimbursement expansion trajectories and materials substitution rates. Regulatory pathway delays, hydrogel supply disruptions, or wireless connectivity standard fragmentation warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Heart Scan Market
Cardiology Equipment
Global Coronary Artery Bypass Grafting Market
Cardiology Equipment
Cardiac Rhythm Management Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Europe Cardiac Arrhythmia Monitoring Devices Market
Cardiology Equipment
Global Extra Corporeal Membrane Oxygenation (ECMO) System Market
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Cardiac Marker Analyzer Market
Cardiology Equipment
Intracardiac Echocardiography (ICE) Market
Cardiology Equipment
Left Atrial Appendage (LAA) Closure Market
Cardiology Equipment
Global Cardiac Mapping Market
Cardiology Equipment
Mobile Cardiac Telemetry Systems Market
Cardiology Equipment
North America Cardiac Rhythm Management Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Medical Smart Stethoscopes Market
Cardiology Equipment
Cardiopulmonary Auto-Transfusion System Market