
 Coil Assisted Flow Diverters Market | 2026-2036
Coil Assisted Flow Diverters Market Size, Share, and Industry Trends Forecast 2026-2036
Coil Assisted Flow Diverters Market Outlook
Aftermarket service revenue is narrowing as manufacturers bundle procedural support with device sales to capture lifetime patient value. Stryker Corporation leverages its neurovascular portfolio breadth to lock in hospital supply contracts. Medtronic anchors its position through integrated imaging-to-implant workflows that reduce procedure variability. MicroVention differentiates via specialized catheter delivery systems that expand physician access to tortuous vasculature.
Coil assisted flow diverters combine braided metallic mesh tubes with embolic coils to reconstruct diseased cerebral arteries while preserving parent vessel patency; nitinol superelasticity and platinum-tungsten coil composition enable catheter-based delivery through vessels under three millimeters diameter. Self-expanding stents and endovascular coils represent the dominant product pairing, with balloon-expandable stents gaining traction in distal vessel applications where precise wall apposition matters. Cerebrovascular disorders and aneurysm treatment command the largest therapy area volumes, though ischemic stroke indications are attracting accelerated R&D investment as thrombectomy protocols expand eligibility.
FDA premarket approval requirements and EU MDR conformity assessments impose substantial clinical evidence burdens that filter market entrants by capital depth. Japan's PMDA Shonin pathway and China's NMPA innovation review channel shape distinct approval timelines for Asia-Pacific commercialization. Stakeholders must monitor reimbursement coding evolution for flow diversion procedures across Medicare, national health systems, and private payers to anticipate volume inflection points.
Market Dynamics
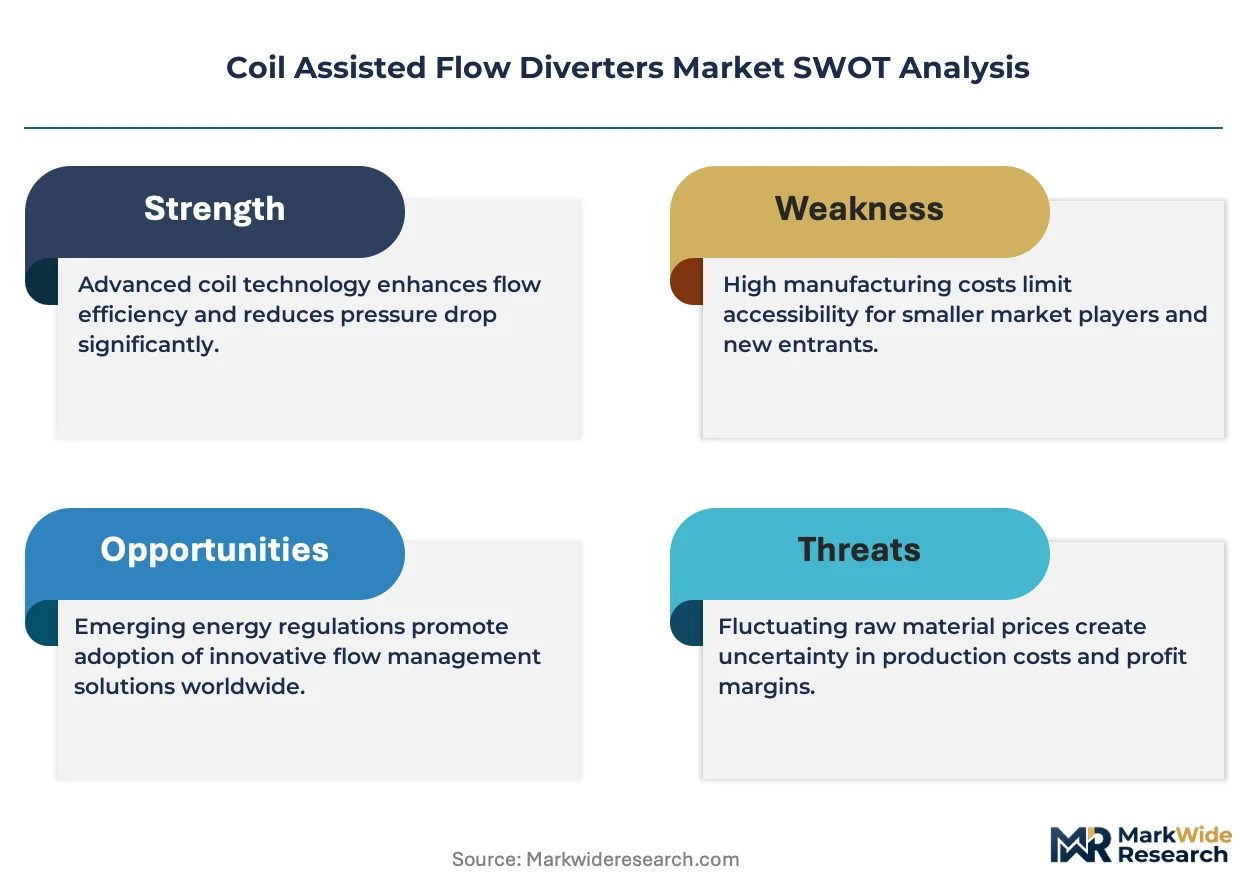
The convergence of braided nitinol mesh engineering with platinum-tungsten coil systems is compressing the traditional separation between flow diversion and embolization procedures, forcing manufacturers to reconfigure R&D roadmaps around integrated delivery platforms.
Growth Catalysts
- FDA Breakthrough Device Pathway:Expedited review timelines for novel stent-coil combinations accelerate commercial entry for complex aneurysm indications, reducing time-to-revenue for qualifying submissions.
- Neurovascular Center Expansion:Leading hospital systems in the United States, Germany, and Japan are building dedicated neurointerventional suites that standardize coil-assisted flow diversion protocols for wide-neck and bifurcation aneurysms.
- Nitinol Superelasticity Advances:Improved heat-treatment processes enable catheter-based delivery through vessels under three millimeters diameter, expanding addressable anatomy for distal and tortuous cerebrovascular applications.
Market Restraints
- EU MDR Clinical Evidence Burden:Conformity assessment requirements for Class III implantable devices impose multi-year follow-up studies that filter market entrants by capital depth and trial infrastructure.
- Platinum-Tungsten Input Volatility:Precious metal price swings in tungsten and platinum markets compress gross margins for coil manufacturers without long-term supply agreements.
- Thrombectomy Protocol Substitution:Mechanical thrombectomy advances for acute ischemic stroke divert R&D investment and physician training hours away from elective aneurysm procedures.
Strategic Opportunities
- China NMPA Innovation Channel:Accelerated review pathways for breakthrough neurovascular devices enable first-mover positioning in the world's fastest-growing aging population market.
- Ischemic Stroke Indication Expansion:Thrombectomy protocol evolution creates white space for flow diversion in tandem with clot retrieval, requiring device modifications for acute procedural compatibility.
- Integrated Imaging-to-Implant Workflows:Convergence of intraoperative 3D rotational angiography with AI-powered vessel reconstruction reduces procedure variability and opens bundled reimbursement negotiations.
Industry Challenges
- Neurointerventionalist Training Pipeline:The specialized skill set for microcatheter navigation through tortuous cerebrovascular anatomy limits procedure volume scaling regardless of device availability.
- Dual Certification Complexity:Separate FDA premarket approval for stent and coil components creates regulatory friction that delays integrated product launches and fragments clinical trial design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coil Assisted Flow Diverters Market |
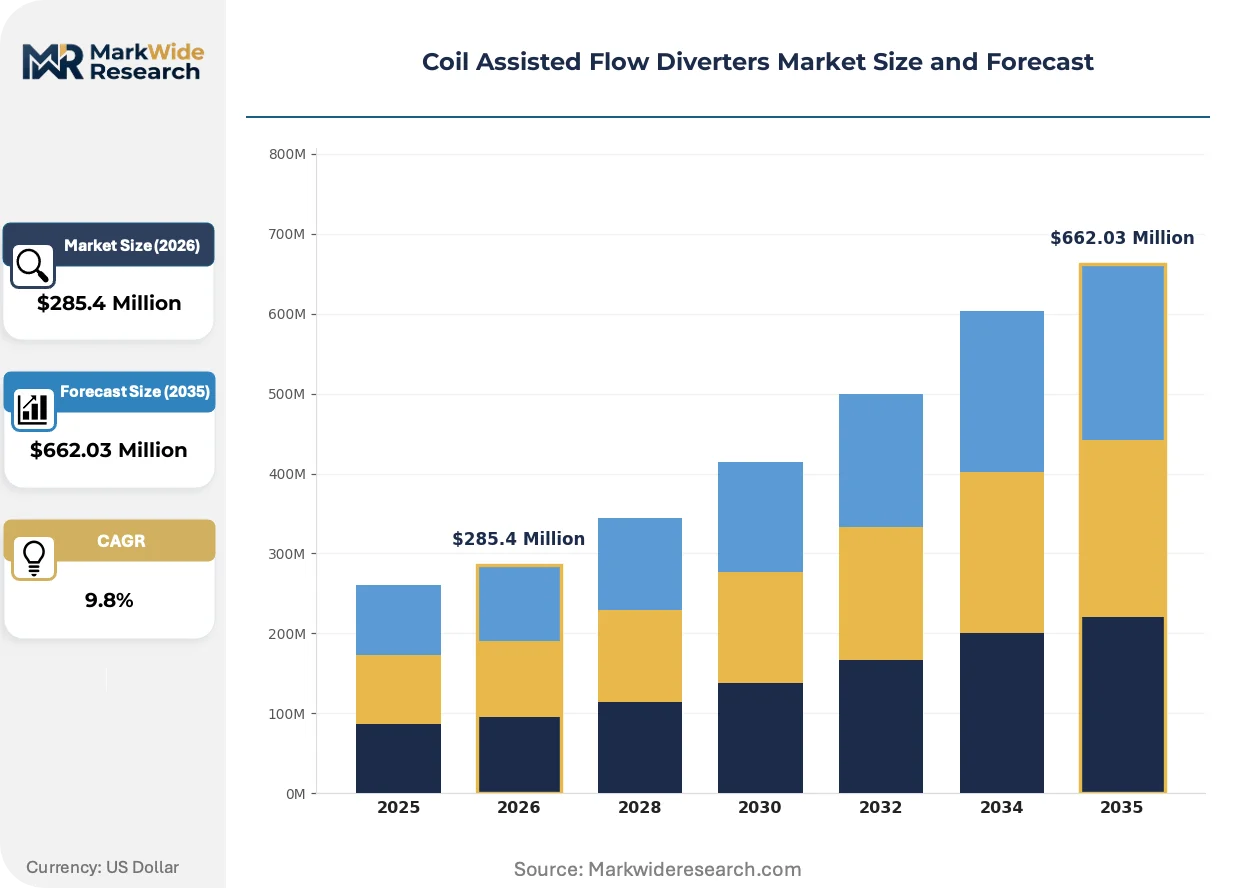
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $662.03 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-expanding Stents, Balloon-expandable Stents, Bypass Grafts, Endovascular Coils Therapy Area: Cerebrovascular Disorders, Aneurysm Treatment, Ischemic Stroke, Vascular Malformations End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes Technology: Laser Cutting, 3D Printing, Biocompatible Materials, Coating Technologies |
| Companies Covered | Stryker Corporation, Medtronic, MicroVention, Terumo Corporation, Balt, MicroPort Scientific Corporation, Johnson & Johnson, Phenox GmbH, Acandis GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coil Assisted Flow Diverters Market Strategic Shifts
Braided metallic mesh engineering is actively displacing laser-cut stent platforms in complex aneurysm reconstruction, while regulatory pathways and procurement models co-evolve around integrated procedural ecosystems rather than discrete device categories.
Bioabsorbable polymer coatings on nitinol flow diverters are collapsing the historical trade-off between acute thrombogenicity and long-term endothelialization. Academic medical centers in Germany and Japan are piloting these surfaces in high-risk bifurcation cases. The technology is collapsing the need for extended dual antiplatelet therapy, compressing total cost of care and expanding eligibility for patients with bleeding contraindications.
EU MDR's heightened clinical evidence requirements for implantable neurovascular devices are restructuring competitive entry barriers. Small manufacturers without captive trial infrastructure face capital requirements that favor established players with integrated regulatory affairs departments. The balloon-expandable stent segment is responding by consolidating supplier relationships and pooling clinical data across multiple notified bodies.
Hospital procurement committees are consolidating vendor contracts around full procedural ecosystems rather than individual device SKUs. Neurovascular centers in the United States are replacing transactional purchasing with multi-year partnerships that bundle devices, imaging support, and physician training. This shift is most visible in integrated delivery networks where supply chain standardization across multiple sites overrides individual physician preference.
Coil Assisted Flow Diverters Market Segmentation
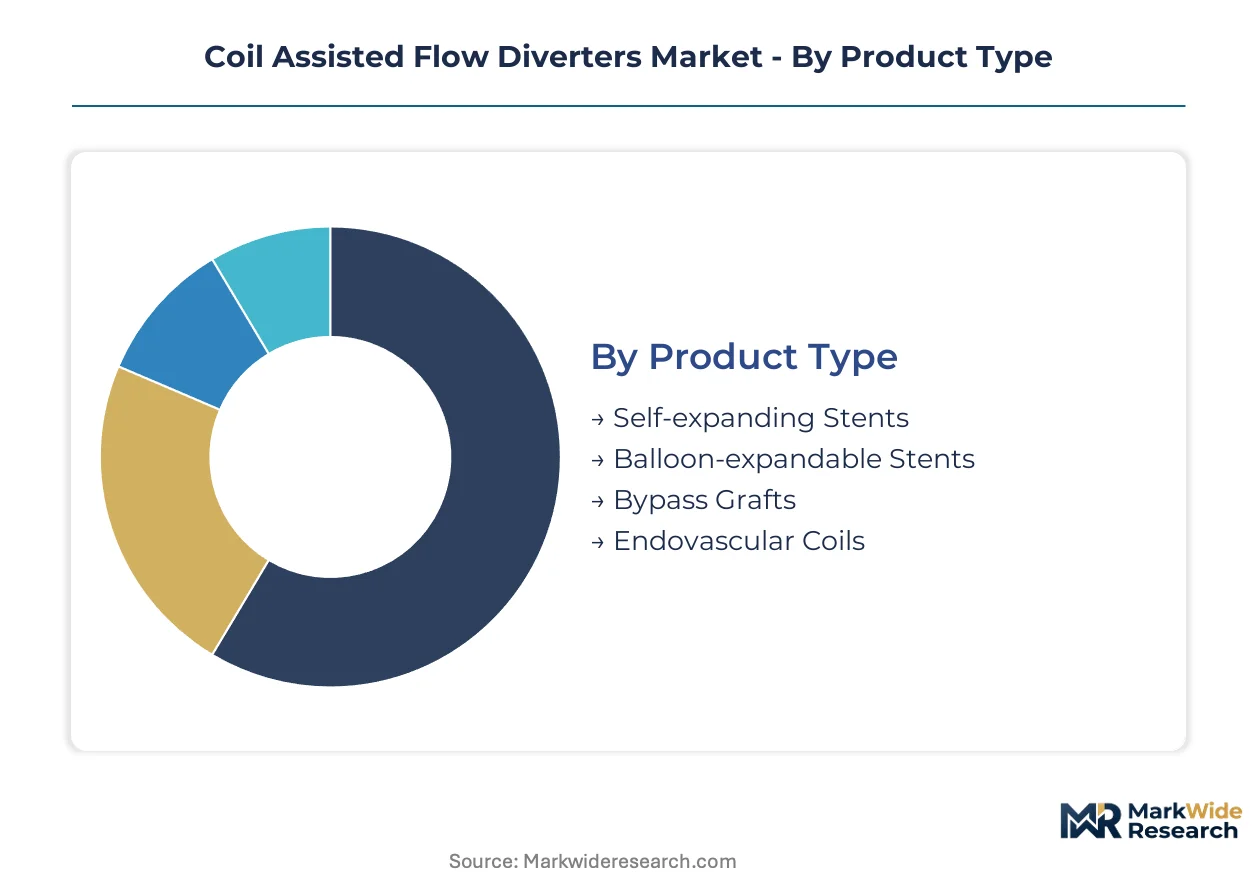
Coil assisted flow diverter segmentation reveals distinct procurement cycles across device categories, with stent platforms turning over faster than coil systems due to iterative braid pattern improvements. Therapy area stratification shows cerebrovascular applications commanding longer sales cycles than acute stroke interventions. Understanding these velocity differentials shapes inventory planning and R&D resource allocation for manufacturers.
Product Type:
Replacement cycles vary dramatically across implant platforms, with self-expanding stents refreshing every 18-24 months versus bypass grafts holding 5-7 year design stability.
- Self-expanding Stents:Braided nitinol mesh constructs exploit superelastic recovery to deploy through sub-3mm tortuous vessels without balloon assistance. Demand clusters at academic medical centers in Germany and Japan where wide-neck aneurysm protocols require rapid wall apposition. FDA breakthrough designations for next-generation braid densities are compressing competitive refresh timelines.
- Balloon-expandable Stents:Laser-cut cobalt-chromium platforms deliver precise radial force for distal vessel segments where diameter control outweighs conformability. German neurovascular centers favor these for bifurcation aneurysms requiring exact landing zone positioning. Platinum-iridium marker bands enable fluoroscopic visualization during inflation.
- Bypass Grafts:Expanded polytetrafluoroethylene conduits with heparin-bonded luminal surfaces address complex aneurysms unsuitable for endovascular reconstruction.
- Endovascular Coils:Platinum-tungsten filament bundles with polyglycolic acid fiber cores achieve progressive thrombosis through electrolytic detachment systems.
Self-expanding stents dominate installed base. Balloon-expandable stents are where expansion concentrates.
Therapy Area:
Procedure volume stratifies sharply across indications, with elective aneurysm repair generating higher per-case device revenue than emergent stroke interventions.
- Cerebrovascular Disorders:Broad category encompassing intracranial atherosclerosis and vasospasm management through flow-modulating implants. Japanese stroke centers lead protocol standardization for combined stent-coil approaches. Reimbursement coding complexity across national health systems fragments pricing realization.
- Aneurysm Treatment:Saccular and fusiform aneurysm reconstruction represents the commercial core, with wide-neck morphology driving coil-assisted rather than standalone flow diversion. United States neurovascular centers generate the highest procedural volumes for unruptured elective cases. Dual antiplatelet therapy requirements create patient selection constraints.
- Ischemic Stroke:Mechanical thrombectomy expansion is creating tandem intervention opportunities where flow diversion follows clot retrieval. Acute procedural compatibility demands device modifications for rapid deployment.
- Vascular Malformations:Arteriovenous malformation and dural arteriovenous fistula embolization uses adapted coil systems with liquid embolic adjuncts.
Aneurysm treatment anchors revenue concentration. Ischemic stroke is climbing the fastest as thrombectomy protocols mature.
End User:
Capital intensity and case mix create distinct purchasing behaviors across facility types, with hospitals amortizing device costs across bundled episodes versus specialty clinics optimizing per-procedure margins.
- Hospitals:Integrated delivery networks in the United States negotiate multi-year supply contracts bundling devices, imaging support, and physician training. Neurovascular suite construction in Germany and Japan concentrates high-complexity cases requiring full product portfolios.
- Ambulatory Surgical Centers:Limited to stable elective aneurysm cases with straightforward anatomy, these facilities prioritize disposable cost control over technology breadth. Procedure volume per site remains constrained by emergency backup requirements.
- Specialty Clinics:Focused neurointerventional practices in urban United States markets capture referred complex cases from community hospitals without on-site neurosurgical coverage.
- Research Institutes:Academic medical centers in Germany and Japan pilot bioabsorbable coatings and next-generation braid architectures through investigator-initiated trials.
Hospitals dominate installed base. Ambulatory surgical centers are gaining share fastest as elective case migration accelerates.
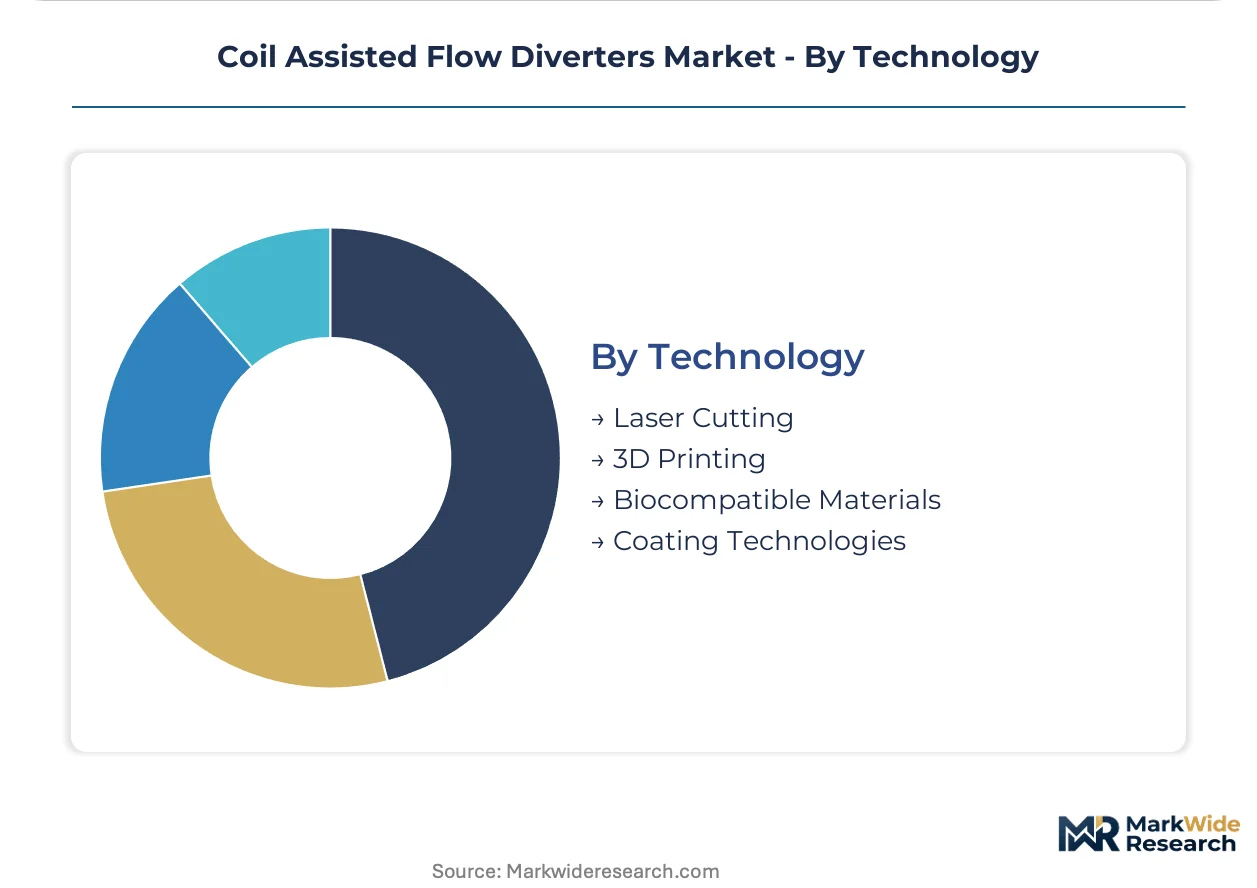
Technology:
Manufacturing process selection directly determines regulatory pathway complexity and gross margin structure, with additive methods attracting venture funding despite limited commercial scale.
- Laser Cutting:Femtosecond laser ablation of nitinol tubes produces strut geometries with sub-50-micron precision for balloon-expandable platforms. German precision engineering suppliers anchor equipment sourcing.
- 3D Printing:Selective laser melting of cobalt-chromium enables patient-specific flow diverter geometries, though FDA validation timelines have stalled commercial introduction beyond research protocols.
- Biocompatible Materials:Nitinol superelasticity and platinum-tungsten radiopacity form the material foundation, with surface modification research concentrating at Japanese academic centers.
- Coating Technologies:Bioabsorbable polymer surfaces for thrombogenicity reduction are collapsing dual antiplatelet therapy duration requirements in German pilot programs.
Laser cutting dominates installed base. Coating technologies are where R&D investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across neurovascular markets, with United States buyers absorbing premium device costs through bundled reimbursement while German and Japanese purchasers negotiate tighter per-procedure margins.
United States
Medicare reimbursement coding for flow diversion procedures anchors hospital purchasing power, with integrated delivery networks consolidating vendor contracts across multi-site neurovascular suites. FDA premarket approval timelines shape product launch sequencing, favoring manufacturers with established regulatory affairs infrastructure. The Cleveland Clinic and Mayo Clinic clusters in Ohio and Minnesota drive protocol standardization for complex aneurysm cases.
Germany
Statutory health insurance reimbursement rates compress device margins while demanding comprehensive clinical evidence packages for novel stent-coil combinations. EU MDR conformity assessments through German notified bodies impose multi-year follow-up requirements that filter market entrants. The Ruhr Valley and Baden-Württemberg industrial corridors concentrate precision nitinol processing capabilities for braided mesh manufacturing.
Japan
PMDA Shonin pathway timelines accelerate commercial entry for breakthrough neurovascular devices compared to standard pharmaceutical reviews. National health insurance pricing negotiations occur biennially, creating predictable revenue windows for approved products. Tokyo and Osaka academic medical centers pilot bioabsorbable coating technologies through investigator-initiated trials.
China
NMPA innovation review channels enable expedited approval for domestically manufactured flow diverters, reducing reliance on imported devices in tier-one hospitals. Provincial centralized procurement programs drive price compression for mature product categories. The Yangtze River Delta cluster around Shanghai anchors catheter manufacturing supply chains for regional device assembly.
United Kingdom
NICE technology appraisals determine NHS England commissioning for novel neurovascular interventions, creating evidence thresholds that delay adoption relative to European counterparts. Brexit regulatory divergence from EU MDR is restructuring notified body relationships for UK market access. London neurosciences centers concentrate specialist training capacity for complex aneurysm reconstruction procedures.
Coil Assisted Flow Diverters Market Competitive Environment
Capability concentration sits with specialized neurovascular engineering firms; scale advantage sits with diversified medical technology conglomerates. The market structures around three tiers: integrated multinationals with full procedural ecosystems, mid-size specialists with catheter delivery expertise, and regional manufacturers serving domestic procurement programs. Dominant competitive moves include multi-year hospital supply contract bundling and backward integration into nitinol wire processing to secure material cost positions.
Within the diversified multinational tier, Stryker Corporation and Medtronic exemplify scale-driven positioning through neurovascular portfolio breadth. MicroVention occupies a specialist position emphasizing catheter delivery system differentiation. These three anchors demonstrate how competitive advantage in coil-assisted flow diverters derives from either procedural ecosystem control or targeted access technology rather than discrete device manufacturing alone.
| Leading Market Players |
|---|
| Stryker Corporation |
| Medtronic |
| MicroVention |
| Terumo Corporation |
| Balt |
| MicroPort Scientific Corporation |
| Johnson & Johnson |
| Phenox GmbH |
| Acandis GmbH |
| Others |
Value Chain & Pricing Dynamics
Platinum-tungsten input volatility compresses gross margins for coil manufacturers without long-term supply agreements, forcing tiered pricing spreads between premium braid-density stents and standard coil platforms while simultaneously reshaping sourcing strategies toward captive nitinol wire processing in Germany and Japan.
Pricing Analysis
Procedural support bundling drives lifetime value capture as manufacturers shift from transactional device sales to multi-year hospital partnerships. Three-tier pricing structure across premium, standard, and economy levels stratifies by braid density sophistication and dual antiplatelet therapy reduction claims. Cost compression in standard coil tiers intensifies because provincial procurement programs in China consolidate volume and squeeze per-unit realization. Ambulatory surgical centers exhibit highest price sensitivity due to constrained reimbursement ceilings, while academic medical centers in the United States absorb premium costs through bundled episode payments.
Supply Chain Analysis
Precision nitinol processing capabilities concentrate at German and Japanese specialty metallurgy houses, with braid pattern engineering increasingly captive to Stryker, Medtronic, and MicroVention through backward integration into wire drawing and heat treatment. Platinum-tungsten filament, nitinol superelastic alloy, and bioabsorbable polymer coatings constitute critical input dependencies. Single-source vulnerability for medical-grade nitinol creates exposure to export restriction shocks from either jurisdiction. Distribution runs through GPO-negotiated contracts in the United States and direct hospital procurement in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from procedural training and imaging workflow integration expands faster than hardware sales, making after-sales ecosystem control the primary value capture mechanism in coil-assisted flow diverters.
For Market Incumbents: Entrench position through exclusive multi-year supply contracts with integrated delivery networks that bundle devices, physician training, and AI-powered imaging support. Backward integration into nitinol wire processing secures material cost positions against platinum-tungsten volatility. Defend against mechanical thrombectomy protocol substitution by accelerating ischemic stroke indication R&D. For New Entrants and Emerging Players: Build out specialized catheter delivery capabilities for tortuous distal vasculature that incumbent platforms struggle to navigate. China NMPA innovation review channel offers the most penetrable regulatory pathway for breakthrough device positioning. Target investigator-initiated trial partnerships at Tokyo and Osaka academic centers to generate clinical evidence without captive trial infrastructure. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-size specialists with catheter delivery expertise over diversified conglomerates lacking neurovascular focus. Five-to-ten year viability hinges on procedural ecosystem control rather than discrete device manufacturing. Acquisition target archetype: German or Japanese precision engineering firms with captive nitinol processing and established notified body relationships. Monitor quarterly FDA breakthrough device designation announcements as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Bundled contracts with Cleveland Clinic and Mayo Clinic clusters lock in multi-site standardization. |
| CE Marking Pathway | EU MDR conformity through German notified bodies accelerates complex aneurysm indication expansion. |
| Backward Integration | In-house nitinol wire processing insulates margin from platinum-tungsten price swings. |
| Reimbursement Strategy | Medicare coding evolution for flow diversion procedures shapes hospital purchasing power. |
| Software Companion Development | AI-powered vessel reconstruction integration reduces procedure variability and supports bundled pricing. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across neurointerventionalists at academic medical centers, hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and regulatory affairs leads at device manufacturers. Secondary validation drew from FDA premarket approval filings, PMDA Shonin submissions, EU MDR notified body assessments, hospital procurement databases, and CMS Medicare reimbursement coding records. Bottom-up procedure volume estimates and top-down market sizing were triangulated to constrain forecast variance.
Calibration against historical product launch trajectories and regulatory approval timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include stent platform type, therapy area indication, end-user facility category, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to procedural volume elasticities against reimbursement and demographic drivers. Forecast inputs incorporated neurovascular center construction pipelines and PMDA Shonin approval velocity.
Stress conditions across platinum-tungsten commodity volatility, EU MDR clinical evidence requirement tightening, and mechanical thrombectomy protocol substitution were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reimbursement stability and physician training pipeline expansion. Quarterly review of FDA breakthrough device designation grants and NMPA innovation channel approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Baby Thermometer Market
Medical Devices
Medical Mobility Aid Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
Eye Examination Equipment Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
Nephrostomy Devices Market
Medical Devices
Global Medical Device Security Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Global Robotic Wheelchairs Market
Medical Devices
Hemodynamic Flow Alteration Devices Market
Medical Devices
Prescription Goggles Market
Medical Devices
Indonesia Devices Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
Americas Medical Suction Device Market
Medical Devices
General Surgery Devices Market
Medical Devices
Global Mobile ECG Devices Market