
 Global Wearable Injectors Market | 2026-2036
Global Wearable Injectors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wearable Injectors Market Foresight
Asset-light leasing models for wearable injector platforms are reshaping competitive dynamics in drug delivery. Becton Dickinson leverages its manufacturing scale to dominate hospital procurement channels across North America. Insulet Corporation anchors its position through vertical integration into disposable pod production. Ypsomed Group specializes in pen injector and auto-injector formats for European biopharma partners.
Wearable injectors are electromechanical or spring-loaded drug delivery devices worn on the body, typically administering subcutaneous doses of biologics over minutes to hours through micro-needle arrays. These systems eliminate the need for clinical supervision during administration of therapies such as monoclonal antibodies and insulin analogues. Patch injector and bolus injector formats lead current revenue pools, while infusion pump configurations capture premium pricing in oncology and immunology indications. Electromechanical technology segments are displacing spring-loaded alternatives in high-viscosity biologic applications, and diabetes management remains the most mature indication category with established reimbursement pathways.
The FDA breakthrough device program and EU MDR certification requirements create divergent compliance burdens for manufacturers seeking transatlantic market access. ISO 13485 quality management standards and IEC 60601 electrical safety protocols govern device design verification across all target jurisdictions. Stakeholders must monitor evolving FDA guidance on human factors testing and the EU AI Act's potential application to closed-loop dosing algorithms before committing to platform architectures.
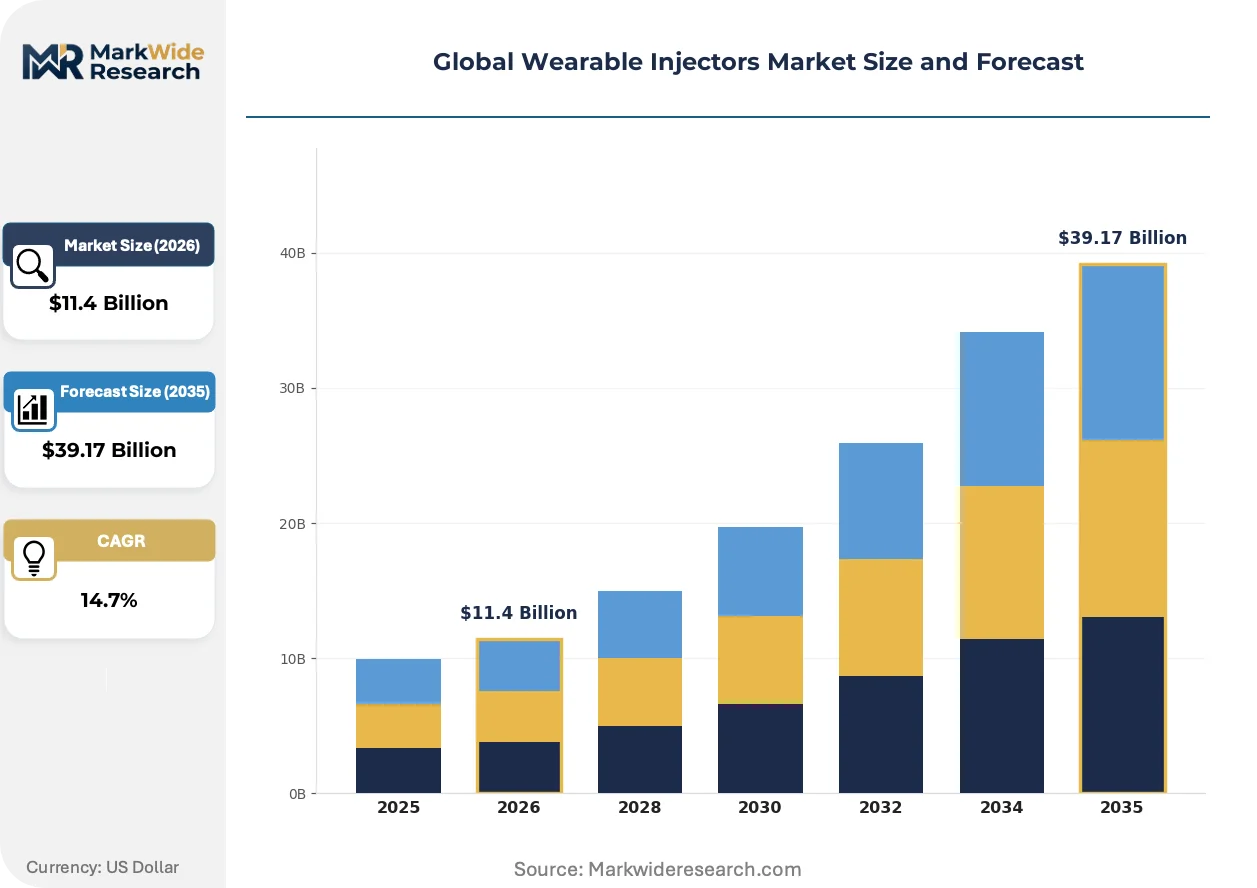
Market Dynamics
Electromechanical wearable injector platforms are compressing development timelines as FDA breakthrough device designations and EU MDR compliance requirements force simultaneous dual-track regulatory submissions. Biopharma contract manufacturers now face capability gaps in human factors validation and closed-loop algorithm testing.
Growth Catalysts
- Hospital-at-home expansion:CMS reimbursement codes for ambulatory drug delivery in the United States accelerate procurement of patch injector systems for post-acute care transitions.
- EU MDR harmonization:Streamlined conformity assessment pathways reduce time-to-market for spring-loaded bolus injectors targeting European biopharma partners.
- High-viscosity biologics pipeline:Monoclonal antibody formulations above 20 cP viscosity drive electromechanical platform adoption in oncology and immunology indications.
Market Restraints
- Polymer supply concentration:Cyclic olefin polymer reservoirs for disposable pods depend on Japanese and German specialty chemical suppliers, creating input cost volatility.
- ISO 13485 certification bottlenecks:Notified body capacity constraints in Europe extend quality management system audit queues to 14-18 months.
- Manual injection persistence:Prefilled syringes and conventional auto-injectors retain cost advantage in low-viscosity, high-volume diabetes segments.
Strategic Opportunities
- Japan's aging population:METI incentives for home healthcare medical devices create demand for Japanese-language localized wearable injector platforms with simplified user interfaces.
- Closed-loop insulin delivery:Convergence of continuous glucose monitors with electromechanical patch pumps enables algorithm-driven dosing in Type 1 diabetes management.
- Direct-to-patient distribution:Specialty pharmacy channels bypass hospital procurement committees, capturing margin previously allocated to group purchasing organizations.
Industry Challenges
- Human factors engineering talent scarcity:FDA guidance on combination product usability testing requires specialized industrial design capabilities concentrated in Boston and Basel metropolitan clusters.
- IEC 60601-1 third edition compliance:Electrical safety testing for wearable devices with wireless connectivity adds 8-12 months to verification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wearable Injectors Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $39.17 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Patch Injector, Bolus Injector, Infusion Pump, Pen Injector, Jet Injector, Auto-Injector Technology: Micro-Needle, Electromechanical, Hydraulic, Spring-Loaded, Disposable, Reusable Indication: Diabetes Management, Rheumatoid Therapy, Allergy Treatment, Cancer Therapy, Hormone Replacement, Pain Management End User: Pharmaceutical Companies, Biotechnology Firms, Specialty Clinics, Home Healthcare Providers, Clinical Research Organizations, Rehabilitation Centers |
| Companies Covered | Medtronic, Becton Dickinson, Amgen, Insulet Corporation, West Pharmaceutical Services, Ypsomed Group, Enable Injections, Johnson & Johnson Services, Gerresheimer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wearable Injectors Market Shifts & Advancements
Micro-needle array technologies and smart connectivity features are redefining competitive differentiation in wearable drug delivery. Platform architectures now prioritize data interoperability and patient adherence monitoring over pure mechanical reliability.
Silicon micro-needle arrays with hollow-bore designs enable painless subcutaneous administration of biologics previously requiring intravenous infusion. Oncology centers in Germany and Japan are piloting these systems for at-home monoclonal antibody delivery. Electromechanical control is migrating from spring-loaded mechanisms to piezoelectric actuation, compressing dose delivery windows from hours to minutes.
The EU AI Act's risk classification framework for medical devices with machine-learning components is forcing algorithm disclosure requirements. Closed-loop dosing systems must now document training data provenance and decision boundary specifications. Wearable injector developers targeting European markets are segregating hardware platforms from software modules to isolate certification pathways.
Biopharma procurement teams are unbundling device supply from drug substance contracts, creating standalone platform leasing arrangements. This model shifts capital burden from pharmaceutical sponsors to device manufacturers while locking in multi-year disposable pod commitments. The United States exhibits the fastest uptake of this arrangement, with hospital-at-home programs demanding per-patient-per-month pricing rather than capital purchase structures.
Global Wearable Injectors Market Segmentation
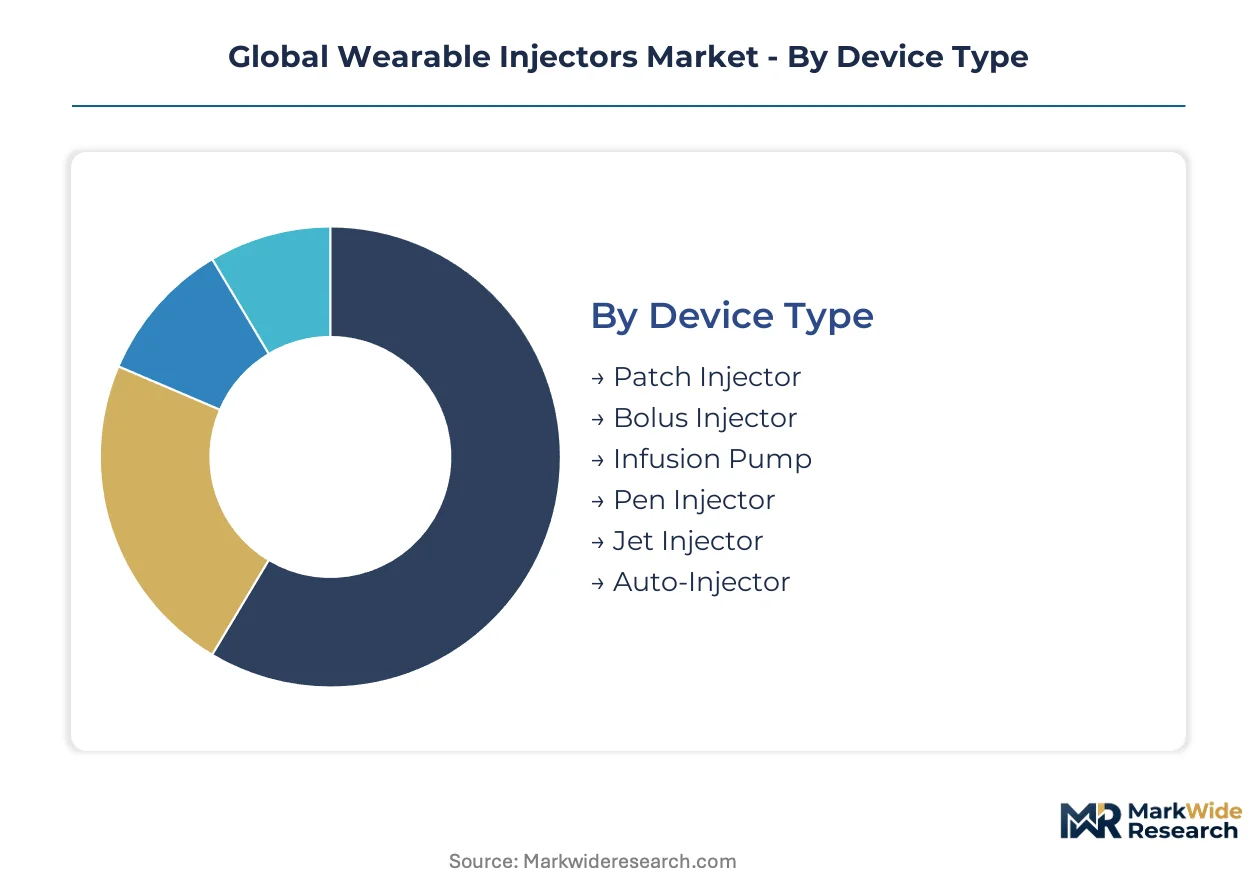
Segmentation in wearable injectors reveals divergent replacement cycles across device architectures. Patch and bolus formats turn over every 24-36 months in high-volume diabetes settings, while infusion pumps operate on 5-7 year depreciation schedules in oncology. Technology choices and end-user procurement patterns further stratify commercial dynamics.
Device Type:
Patch injectors and bolus systems rotate through patient populations fastest, driven by disposable pod consumption and protocol-driven replacement. Infusion pumps and pen formats anchor longer capital cycles, with jet and auto-injector categories occupying intermediate refresh positions.
- Patch Injector:Electromechanical platforms with adhesive-backed disposable pods administer subcutaneous biologics over 2-24 hour windows. Demand clusters in United States hospital-at-home programs where CMS reimbursement codes favor ambulatory drug delivery transitions.
- Bolus Injector:Spring-loaded or electromechanical devices deliver single high-volume doses through micro-needle arrays. German and Japanese biopharma partners specify these for monoclonal antibody therapies where viscosity exceeds 20 cP.
- Infusion Pump:Programmable electromechanical systems with reservoir cartridges for extended multi-hour administration. Oncology centers in Switzerland and Australia deploy these for at-home immunotherapy regimens.
- Pen Injector:Handheld reusable devices with disposable needle cartridges for patient-controlled dosing. Diabetes management in Japan and South Korea drives volume through established insulin analogue protocols.
- Jet Injector:Needle-free systems using high-pressure fluid streams to penetrate dermal layers. Pediatric allergy clinics in Canada and France pilot these for needle-averse patient populations.
- Auto-Injector:Pre-filled spring-loaded devices with automated needle insertion and retraction. Emergency epinephrine and rescue medication applications dominate procurement in United States school and workplace settings.
Patch injectors dominate installed base in diabetes and post-acute care. Bolus injectors are where expansion concentrates for high-viscosity biologics in immunology and oncology.
Technology:
Cost tier stratification separates premium electromechanical platforms from economy spring-loaded alternatives, with micro-needle and hydraulic systems occupying mid-market positions. Disposable configurations generate recurring revenue streams that reusable architectures cannot match.
- Micro-Needle:Silicon or polymer arrays with hollow-bore designs enable painless subcutaneous delivery previously requiring intravenous infusion. German oncology centers pilot these for at-home monoclonal antibody administration.
- Electromechanical:Motor-driven piston or piezoelectric actuation systems with programmable dose profiles and wireless connectivity. FDA breakthrough device designations accelerate development timelines for closed-loop insulin delivery applications.
- Hydraulic:Pressure-driven fluid delivery using compressed gas or liquid propellants. Limited adoption in specialty pain management clinics where dose precision requirements are less stringent.
- Spring-Loaded:Mechanical energy storage in coiled springs for rapid needle insertion and drug expulsion. Retains cost advantage in high-volume diabetes segments where manual injection alternatives compete aggressively.
- Disposable:Single-use devices with integrated drug reservoirs and power sources. Pharmaceutical companies in the United States favor per-patient-per-month leasing models that shift capital burden to device manufacturers.
- Reusable:Durable handheld platforms with replaceable drug cartridges and battery modules. Environmental regulations in France and extended producer responsibility frameworks in Germany constrain growth trajectories.
Spring-loaded systems dominate installed base in cost-sensitive diabetes segments. Electromechanical platforms are gaining share fastest in high-viscosity biologics and closed-loop applications.
Indication:
Application maturity varies dramatically, with diabetes management exhibiting established reimbursement pathways while cancer therapy and hormone replacement build clinical evidence for ambulatory administration.
- Diabetes Management:Insulin delivery for Type 1 and intensive Type 2 protocols through patch pumps and pen injectors. United States Medicare Advantage plans and Japanese national health insurance provide comprehensive coverage for continuous subcutaneous infusion.
- Rheumatoid Therapy:Subcutaneous TNF-alpha inhibitors and IL-6 antagonists for autoimmune joint disease. Specialty clinics in Germany and Switzerland drive adoption where patient self-administration reduces infusion center burden.
- Allergy Treatment:Immunotherapy regimens and emergency epinephrine delivery. Pediatric populations in Canada and France show strongest uptake of needle-free jet injector alternatives.
- Cancer Therapy:Monoclonal antibodies and immune checkpoint inhibitors for at-home administration. Oncology centers in Japan and Australia pilot micro-needle arrays to eliminate infusion chair time.
- Hormone Replacement:Growth hormone and testosterone delivery through discreet wearable platforms. Home healthcare providers in the United States manage direct-to-patient distribution for privacy-sensitive indications.
- Pain Management:Opioid and non-opioid analgesic delivery for chronic conditions. Regulatory scrutiny from FDA and DEA constrains expansion in United States markets.
Diabetes management dominates installed base with mature reimbursement infrastructure. Cancer therapy is where expansion concentrates as biopharma sponsors unbundle device supply from drug contracts.
End User:
Customer type determines procurement channel and pricing power, with pharmaceutical companies commanding volume discounts while home healthcare providers accept premium per-patient pricing for operational flexibility.
- Pharmaceutical Companies:Large-cap sponsors integrating wearable injectors into combination product submissions for biologic therapies. FDA and EMA parallel track requirements compress development timelines and demand dual regulatory expertise.
- Biotechnology Firms:Mid-stage developers outsourcing device selection to specialized contract manufacturers. Human factors validation capabilities concentrate in Boston and Basel metropolitan clusters.
- Specialty Clinics:Infusion centers and rheumatology practices transitioning patients to self-administration. German and Swiss reimbursement frameworks favor ambulatory drug delivery cost savings.
- Home Healthcare Providers:Agencies managing post-acute care transitions and chronic disease monitoring. United States hospital-at-home programs demand per-patient-per-month pricing rather than capital purchase structures.
- Clinical Research Organizations:Trial operators requiring device standardization across multi-site protocols. ISO 14155 clinical investigation standards govern investigator training and adverse event reporting.
- Rehabilitation Centers:Facilities managing pain management and hormone replacement for recovering patients. Limited procurement scale constrains pricing leverage relative to pharmaceutical sponsors.
Pharmaceutical companies dominate installed base through integrated combination product strategies. Home healthcare providers are where expansion concentrates as specialty pharmacy channels bypass hospital procurement committees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital-at-home programs and self-administration protocols concentrate procurement power with United States payers, German biopharma sponsors, and Japanese national insurers. Device manufacturers align platform development to reimbursement frameworks in these three markets while navigating divergent regulatory timelines.
United States
CMS reimbursement codes for ambulatory drug delivery accelerate patch injector procurement in post-acute care transitions. FDA breakthrough device designations compress development timelines for closed-loop insulin delivery systems. The Boston metropolitan cluster concentrates human factors engineering talent serving combination product submissions.
Germany
Spring-loaded bolus injectors for high-viscosity monoclonal antibodies dominate procurement from domestic biopharma partners. EU MDR streamlined conformity assessment pathways reduce certification burdens for device manufacturers. The Basel metropolitan cluster anchors contract manufacturing capabilities for European combination product development.
Japan
METI incentives for home healthcare medical devices drive demand for localized wearable injector platforms with simplified user interfaces. PMDA consultation procedures align with FDA breakthrough pathways for parallel track submissions. The Kansai region concentrates disposable pod production for diabetes management devices.
Switzerland
Oncology centers pilot micro-needle arrays for at-home immunotherapy regimens under Swissmedic accelerated access pathways. Reimbursement frameworks favor ambulatory drug delivery cost savings in specialty clinic settings. The Zurich-Basel corridor anchors precision manufacturing for electromechanical platform components.
Australia
TGA priority review pathways attract sponsors seeking early market validation for closed-loop dosing algorithms. Hospital-at-home programs in Victoria and New South Wales demand per-patient-per-month leasing structures. The Melbourne metropolitan cluster concentrates clinical investigation capabilities for wearable device trials.
Global Wearable Injectors Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. The market structure consolidates around three strategic archetypes: diversified medical technology conglomerates with hospital purchasing leverage, vertically integrated diabetes device specialists with captive disposable supply, and European precision manufacturers serving biopharma contract relationships. Dominant competitive moves include strategic partnerships for combination product development and geographic licensing arrangements for regulatory pathway access.
Among diversified medical technology conglomerates, Medtronic and Johnson & Johnson Services occupy positions spanning electromechanical platform development and hospital procurement channel control. Insulet Corporation exemplifies the vertically integrated specialist archetype through captive production of disposable pod systems. Becton Dickinson anchors the scale-driven tier with manufacturing infrastructure serving North American hospital procurement committees. Ypsomed Group represents the European precision manufacturer archetype specializing in pen injector and auto-injector formats for biopharma partners.
| Leading Market Players |
|---|
| Medtronic |
| Becton Dickinson |
| Amgen |
| Insulet Corporation |
| West Pharmaceutical Services |
| Ypsomed Group |
| Enable Injections |
| Johnson & Johnson Services |
| Gerresheimer |
| Others |
Supply & Pricing Matrix
The Kansai region's disposable pod production capacity directly shapes pricing leverage for electromechanical platform manufacturers serving Japanese and United States hospital-at-home programs. When polymer reservoir output tightens, device makers pass input volatility through to per-patient-per-month leasing contracts.
Pricing Analysis
Cost-plus contracts with Japanese cyclic olefin polymer indexation dominate procurement between German specialty chemical suppliers and North American device manufacturers. Three-tier pricing structure across premium electromechanical, standard spring-loaded, and economy manual injection levels separates FDA breakthrough-designated platforms from commodity auto-injectors. Pricing pressure stems from CMS reimbursement compression in United States diabetes segments. Pharmaceutical companies exhibit lowest price sensitivity due to combination product margin capture, while home healthcare providers face acute cost scrutiny under per-patient capitation.
Supply Chain Analysis
Export-control restrictions on silicon micro-needle etching equipment limit technology transfer from German precision engineering clusters to emerging manufacturing hubs. Supply concentrates in Japan for cyclic olefin polymers, Germany for specialty springs and actuators, and Switzerland for electromechanical control modules. Raw material dependencies span medical-grade polymers, lithium-ion cells for disposable power, and biocompatible adhesives. Single-source vulnerability concentrates in Japanese polymer feedstock. Distribution runs through pharmaceutical company procurement committees and specialty pharmacy direct-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Human factors engineering talent scarcity in Boston and Basel metropolitan clusters constrains platform development velocity, creating asymmetric advantage for incumbents with captive industrial design capabilities.
For Market Incumbents: Harden regulatory submission capabilities through dual-track FDA and EU MDR expertise to compress time-to-market for closed-loop insulin platforms. Deepen backward integration into disposable pod production to defend margin position against contract manufacturing price erosion. Prioritize ISO 13485 certification queue positioning to offset notified body capacity bottlenecks extending audit timelines. For New Entrants and Emerging Players: Build out micro-needle array specialization for oncology monoclonal antibody delivery, where German and Japanese pilot programs demonstrate unmet demand. Target Australian TGA priority review pathways for algorithm-driven dosing validation with lower regulatory capital requirements than FDA breakthrough tracks. Pursue specialty clinic partnerships in Switzerland to bypass pharmaceutical company procurement committee gatekeeping. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core drug delivery divisions amid portfolio rationalization pressures. Five-to-ten year viability hinges on electromechanical platform adoption in high-viscosity biologics exceeding spring-loaded mechanical limits. Monitor EU AI Act algorithm disclosure requirements as inflection signal for software-modular platform architectures.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerates development timelines for closed-loop insulin delivery systems in Type 1 diabetes. |
| EU MDR Conformity Assessment | Streamlines market access for spring-loaded bolus injectors targeting German biopharma partners. |
| Hospital System Partnership | Locks in per-patient-per-month pricing for United States hospital-at-home program procurement. |
| Software Companion Development | Enables algorithm-driven dosing while isolating certification pathways under EU AI Act risk classification. |
| Reimbursement Strategy | Secures CMS coverage codes for ambulatory drug delivery transitions in post-acute care settings. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs leads, hospital procurement managers, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EMA design dossiers, CMS Medicare reimbursement databases, and ISO 13485 audit records. Bottom-up installed base estimates triangulated with top-down pharmaceutical company R&D pipeline analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling device type, technology tier, indication category, and end-user procurement channel dimensions. CAGRs derived from segment-level volume trajectories and pricing elasticity assumptions, incorporating biopharma pipeline progression for high-viscosity monoclonal antibodies and METI incentive program uptake curves for Japanese home healthcare devices.
Sensitivities concentrate around EU MDR notified body capacity constraints, FDA guidance evolution on human factors testing, and polymer feedstock price volatility. Forecasts reflect documented assumptions on reimbursement pathway expansion and algorithm regulatory classification. Material shifts in CMS ambulatory drug delivery coverage determination or EU AI Act medical device risk tiering would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Chest Drainage Devices Market
Medical Devices
Veterinary Procedure Lights Market
Medical Devices
Medical Device Coating Market
Medical Devices
Patellar Implant Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
Global Sperm Separation Devices Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
Global Stabilometric Platform Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Global Canes and Crutches Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
IV Therapy and Vein Access Devices Market
Medical Devices
Bilirubin Meters Market
Medical Devices
Ultrasonic Skin Care Devices Market
Medical Devices
Abdominal Closure Systems Market