
 Medical Device Validation and Verification Market | 2026-2036
Medical Device Validation and Verification Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Device Validation and Verification Market Intelligence
The EU Medical Device Regulation is hardening compliance timelines for legacy device recertification. SGS SA leverages its pan-European notified body network to capture overflow demand from capacity-constrained competitors. Eurofins Scientific SE anchors its position through specialized biocompatibility testing laboratories in France and Germany. TÜV SÜD AG dominates the German market with deep relationships with Mittelstand medical device manufacturers.
Medical device validation and verification encompasses the systematic evaluation of design outputs, process controls, and software lifecycle documentation to confirm conformance with predetermined specifications and regulatory requirements. The discipline employs test method validation, installation qualification, operational qualification, and performance qualification protocols to demonstrate that devices function safely and effectively under anticipated use conditions. Software validation commands premium pricing due to IEC 62304 compliance complexity and the proliferation of software-as-medical-device products. In vitro diagnostics represents a high-velocity segment driven by companion diagnostic development and personalized medicine pipelines. Process validation for surgical instruments maintains stable demand from established orthopedic and cardiovascular device portfolios.
The FDA, EMA, and ISO shape market dynamics through evolving submission requirements and harmonized quality management standards. FDA premarket approval pathways demand extensive design history files and clinical evidence packages that third-party laboratories assemble and review. The EU AI Act introduces additional scrutiny for machine-learning-enabled diagnostic devices, expanding the scope of required verification activities. Stakeholders must monitor notified body designation delays and FDA user fee reauthorizations as these directly determine project backlogs and pricing power across the service provider landscape.
Market Dynamics
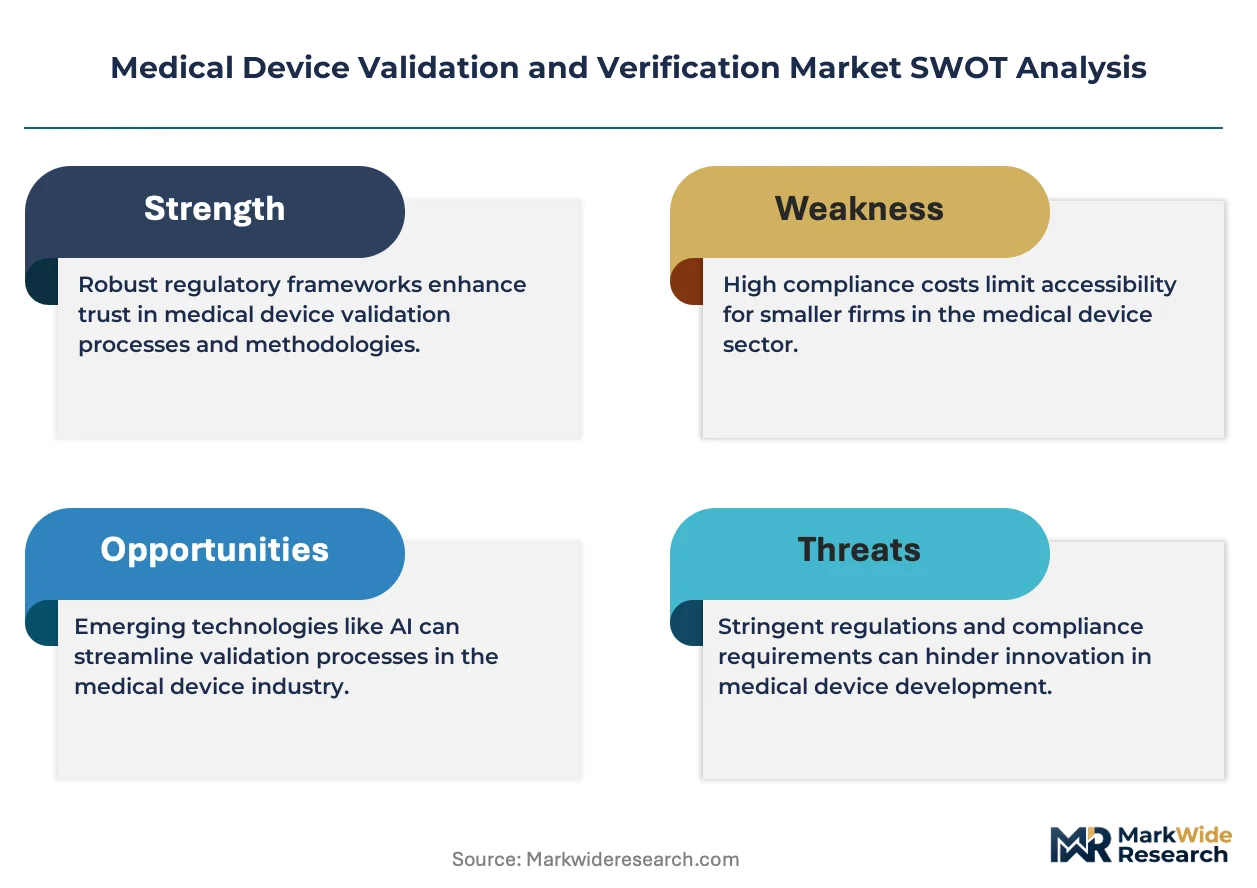
Notified body capacity constraints across Europe are compressing CE marking timelines and forcing orthopedic implant manufacturers to front-load validation expenditures ahead of MDR recertification deadlines. This supply-side bottleneck is redistributing project volumes toward laboratories with pan-European accreditation networks.
Growth Catalysts
- FDA premarket submission requirements:The FDA demands extensive design history files and clinical evidence packages that third-party laboratories assemble and review, expanding outsourced validation service contracts.
- Companion diagnostic pipelines:Personalized medicine development is accelerating in vitro diagnostic verification cycles, particularly for oncology biomarker assays requiring ISO 15189-compliant testing protocols.
- Germany:Mittelstand medical device manufacturers concentrate validation demand in Bavaria and Baden-Württemberg, sustaining specialized service provider ecosystems around Stuttgart and Munich.
Market Restraints
- Notified body designation delays:EU MDR implementation has shrunk the pool of designated conformity assessment bodies, extending project queues to 12-18 months for high-risk device categories.
- ISO 17025 laboratory accreditation costs:Specialized biocompatibility testing facilities face six-figure capital outlays for analytical equipment upgrades to maintain ISO 10993 compliance.
- Software-as-medical-device substitution:Pure-play SaMD products bypass traditional hardware validation pathways, cannibalizing segments of the physical device verification market.
Strategic Opportunities
- EU AI Act compliance services:Machine-learning-enabled diagnostic devices face additional algorithmic validation requirements, opening new verification service lines for conformity assessment bodies.
- France:The Paris-Saclay medical technology cluster hosts emerging startups lacking in-house quality assurance capabilities, creating captive demand for outsourced validation partnerships.
- Continuous manufacturing validation:Process analytical technology integration with real-time release testing protocols is electrifying demand for hybrid hardware-software qualification services.
Industry Challenges
- IEC 62304 software lifecycle expertise:Validation engineers with embedded medical device software competency command premium compensation, constraining laboratory hiring pipelines.
- Legacy device technical documentation gaps:Pre-MDR orthopedic and cardiovascular portfolios lack contemporary design history files, forcing costly retrospective documentation efforts for recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Device Validation and Verification Market |
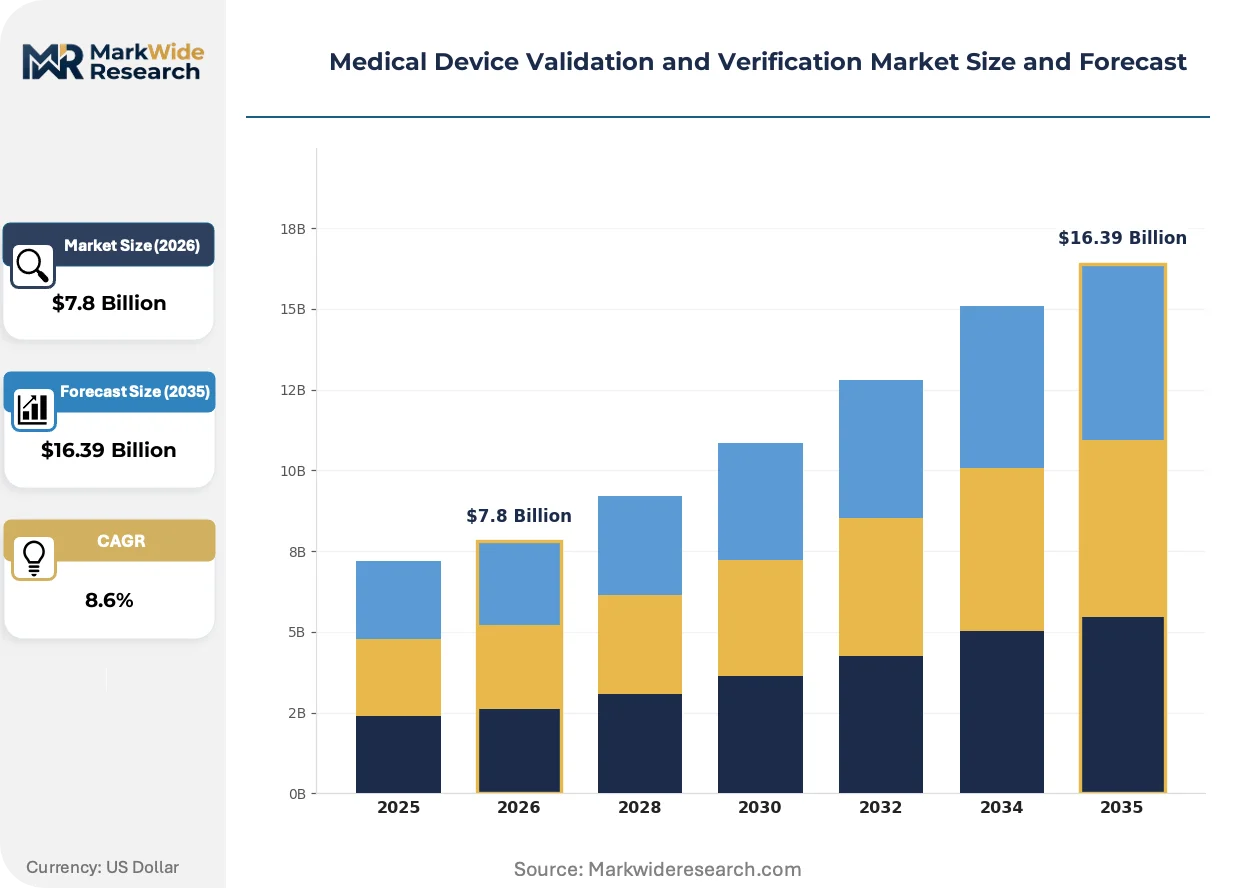
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.39 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In Vitro Diagnostics, Surgical Instruments, Imaging Systems, Patient Monitoring Devices End User: Hospitals, Clinics, Laboratories, Research Institutions Regulatory Standard: ISO 13485, FDA Guidelines, CE Marking, IEC 62304 Technology: Software Validation, Hardware Verification, Process Validation, Risk Management |
| Companies Covered | SGS SA, QuEST Global Services Pte. Ltd., Intertek, Element Materials Technology, TÜV SÜD AG, North American Science Associates, Inc. (NAMSA), Eurofins Scientific SE, Charles River, Pacific Biolabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Device Validation and Verification Market Strategic Shifts & Innovations
Artificial intelligence integration into diagnostic workflows is compressing traditional verification timelines while expanding the scope of required algorithmic validation protocols. Laboratories are retooling capabilities to address software-as-medical-device conformity assessment.
Digital twin technology is electrifying the medical device validation landscape. Manufacturers deploy virtual replicas of orthopedic implants and surgical instruments to simulate stress-testing scenarios before physical prototyping. Stryker and Zimmer Biomet adoption of Siemens Healthineers simulation platforms is compressing design iteration cycles by enabling predictive performance modeling. This virtualization is displacing traditional bench-testing volumes while expanding demand for computational validation specialists.
The EU AI Act introduces mandatory conformity assessments for machine-learning-enabled diagnostic devices, expanding verification scope beyond traditional hardware safety testing. Manufacturers must now document algorithmic performance across demographic subgroups and edge-case clinical scenarios. In vitro diagnostics with AI components face the steepest compliance burden, with notified bodies developing novel assessment frameworks for black-box algorithm validation.
Hospital procurement departments are consolidating vendor qualification processes through centralized third-party audit programs. Group purchasing organizations now mandate pre-registered validation certificates from accredited laboratories, bypassing individual hospital quality reviews. This concentration is most visible in Germany, where university hospital networks in North Rhine-Westphalia have standardized on TÜV SÜD and DEKRA certification marks for implantable device categories.
Medical Device Validation and Verification Market Segmentation
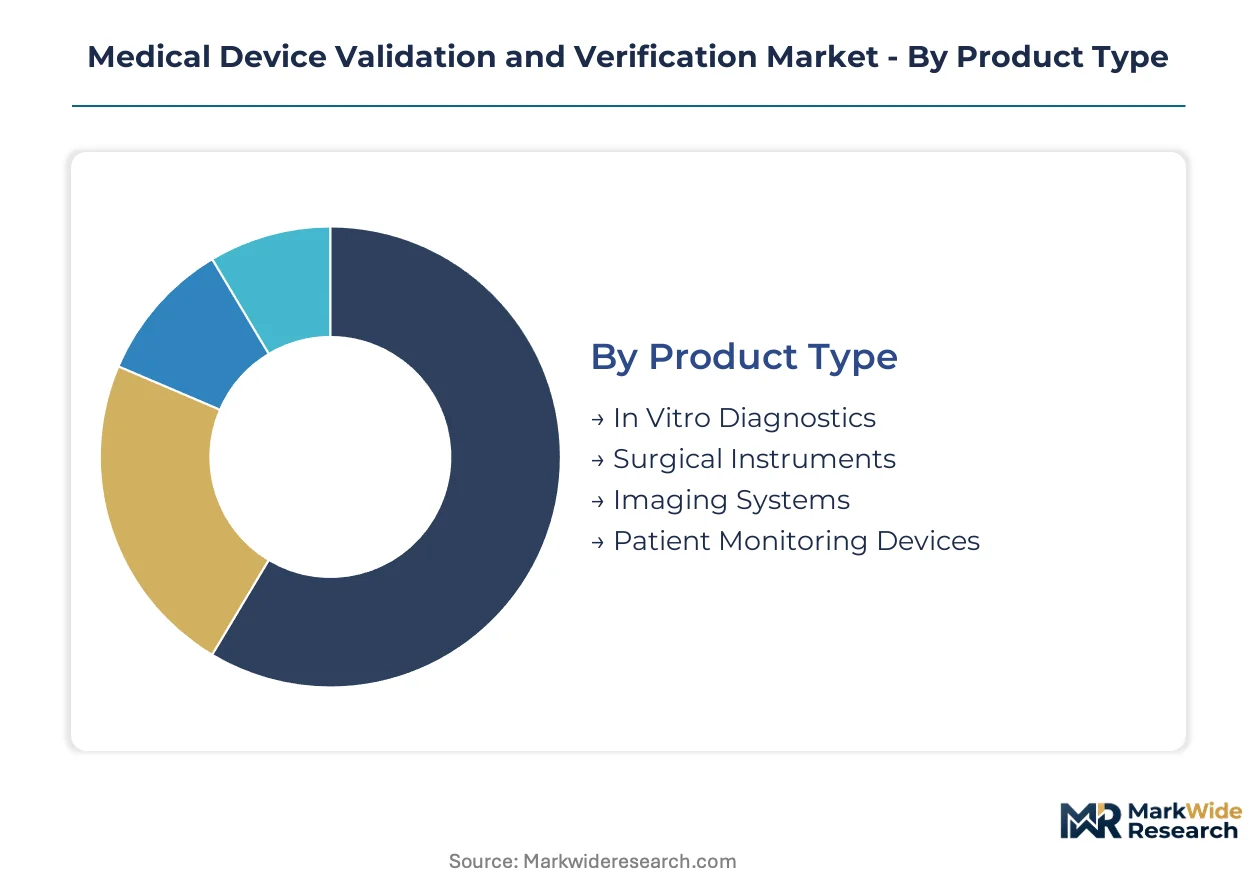
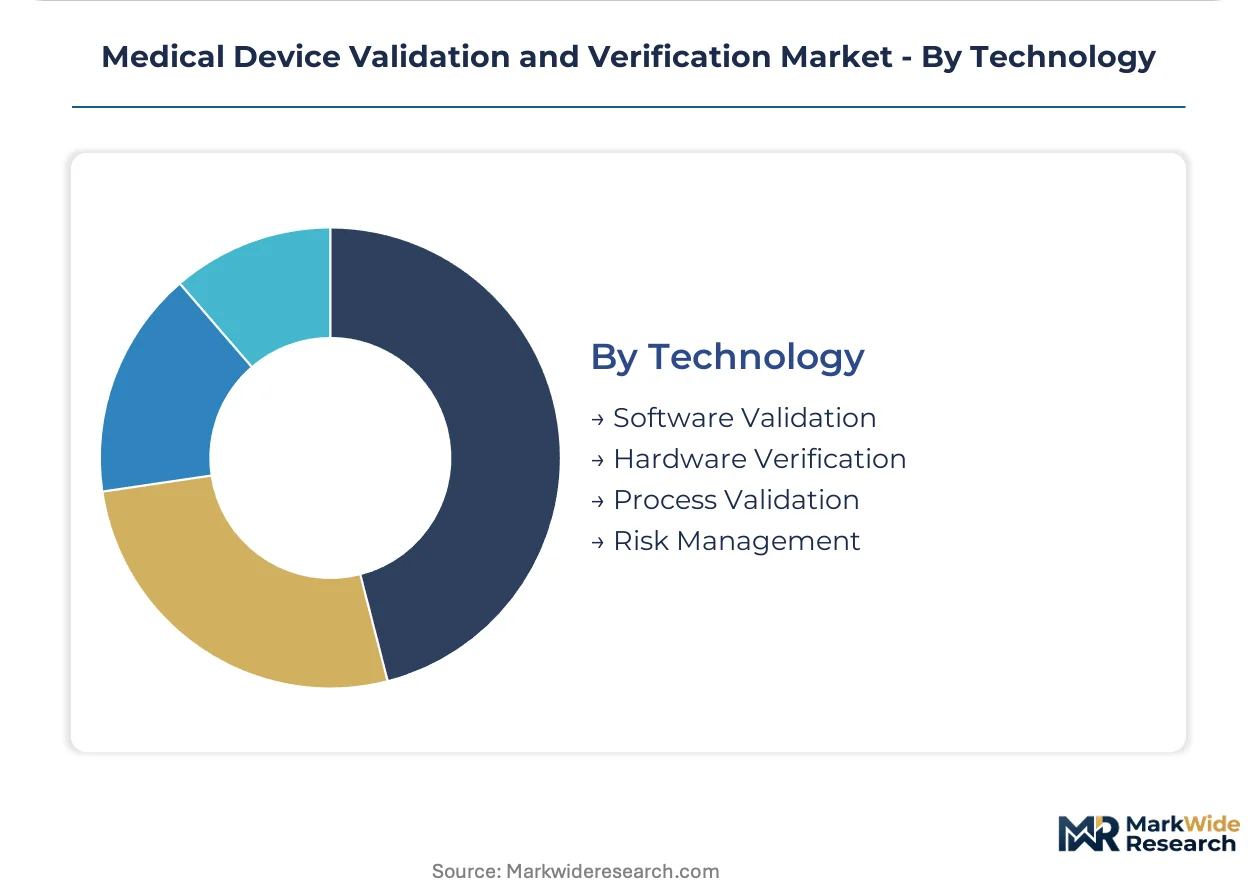
Medical device validation and verification services fragment across technical specifications, regulatory pathways, and end-user sophistication levels. Each segmentation axis carries distinct pricing structures and capability requirements that reshape competitive positioning among service providers.
Product Type:
Technical complexity and biocompatibility exposure determine validation protocol intensity across device categories.
- In Vitro Diagnostics:Companion diagnostic development and personalized medicine pipelines accelerate verification cycles for oncology biomarker assays requiring ISO 15189-compliant testing protocols. Demand concentrates in Germany and France where centralized laboratory networks process high-throughput diagnostic workflows.
- Surgical Instruments:Orthopedic and cardiovascular device portfolios sustain stable process validation demand through established manufacturing footprints. Mittelstand manufacturers in Bavaria and Baden-Württemberg front-load validation expenditures ahead of MDR recertification deadlines.
- Imaging Systems:Hardware-software hybrid architectures command integrated qualification protocols spanning electrical safety and DICOM conformance.
- Patient Monitoring Devices:Wearable form factors and wireless connectivity introduce electromagnetic compatibility testing layers.
Surgical instruments lead on scale; in vitro diagnostics lead on momentum.
End User:
Procurement centralization and in-house quality capability create divergent outsourcing patterns across customer types.
- Hospitals:University hospital networks in North Rhine-Westphalia standardize on pre-registered validation certificates from accredited laboratories, bypassing individual quality reviews. Group purchasing organizations mandate third-party audit programs that consolidate vendor qualification processes.
- Laboratories:Commercial reference laboratories face ISO 17025 accreditation pressures that expand subcontracted analytical validation services.
- Clinics:Smaller facilities rely on distributor-provided documentation packages rather than direct laboratory relationships.
- Research Institutions:Preclinical device development generates early-stage verification demand with flexible timeline requirements.
Hospitals dominate contract value; laboratories show the steepest expansion trajectory.
Regulatory Standard:
Geographic market access requirements fragment service provider specialization and accreditation investments.
- ISO 13485:Quality management system certification forms the baseline predicate for all major market submissions, with notified body capacity constraints compressing audit scheduling availability.
- FDA Guidelines:Premarket approval pathways demand extensive design history files and clinical evidence packages that third-party laboratories assemble for US market entry.
- CE Marking:MDR implementation has shrunk the pool of designated conformity assessment bodies, extending project queues to 12-18 months for high-risk device categories.
- IEC 62304:Medical device software lifecycle processes command premium pricing due to compliance complexity and engineer scarcity.
ISO 13485 anchors volume; IEC 62304 captures margin.
Technology:
Validation methodology specialization determines laboratory capital intensity and talent acquisition strategies.
- Software Validation:Algorithmic performance documentation across demographic subgroups and edge-case scenarios expands with EU AI Act implementation. Black-box validation frameworks for machine-learning-enabled diagnostics are gaining share fastest among emerging service lines.
- Process Validation:Continuous manufacturing integration with real-time release testing protocols electrifies demand for hybrid hardware-software qualification services.
- Hardware Verification:Bench-testing volumes face displacement from digital twin simulation adoption while computational validation specialist demand rises.
- Risk Management:ISO 14971 compliance documentation supports predicate device equivalence arguments in regulatory submissions.
Process validation maintains installed base; software validation captures growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The medical device validation and verification industry traces its commercial roots to post-war European industrial laboratories that standardized quality assurance protocols for precision manufacturing. German engineering culture institutionalized third-party testing as a prerequisite for market access. Swiss pharmaceutical precision and American regulatory science subsequently elevated validation to a specialized discipline.
United States
FDA premarket submission requirements drive orthopedic implant manufacturers to expand validation budgets for design history files and clinical evidence packages. The agency's 510(k) and PMA pathways mandate extensive third-party laboratory assembly and review services. Boston and Minneapolis medical technology clusters concentrate demand for outsourced verification partnerships.
Germany
Mittelstand manufacturers in Bavaria and Baden-Württemberg front-load validation expenditures ahead of MDR recertification deadlines. Notified body capacity constraints compress CE marking timelines to 12-18 months for high-risk device categories. Stuttgart and Munich sustain specialized service provider ecosystems around automotive-derived precision engineering capabilities.
Switzerland
Swissmedic's harmonized recognition agreements with EU notified bodies streamline dual-market access for orthopedic and cardiovascular portfolios. Basel and Zurich host precision manufacturing clusters where legacy device recertification demands retrospective documentation efforts. The country's pharmaceutical heritage elevates biocompatibility testing standards across device categories.
France
The Paris-Saclay medical technology cluster generates captive demand from emerging startups lacking in-house quality assurance capabilities. ANSM's national health product safety agency coordinates with EU notified bodies on MDR implementation. Lyon and Grenoble surgical instrument manufacturers sustain stable process validation demand through established manufacturing footprints.
United Kingdom
Post-Brexit UKCA marking requirements parallel EU MDR standards while creating duplicate certification burdens for multinational portfolios. The Medicines and Healthcare products Regulatory Agency maintains accelerated access pathways for innovative devices. Cambridge and Oxford medical research clusters drive early-stage verification demand with flexible timeline requirements.
Medical Device Validation and Verification Market Key Industry Players
Premium-margin players sit above commodity-margin players across accreditation breadth and specialized biocompatibility capabilities. The vendor base stratifies into pan-European notified body networks, regional testing laboratories, and niche software validation specialists. Three archetypes dominate: multi-accreditation conglomerates capturing overflow demand, specialized biocompatibility facilities anchoring pharmaceutical-adjacent testing, and software-focused boutiques addressing IEC 62304 complexity. Competitive moves concentrate on M&A for geographic accreditation expansion and strategic partnerships for AI Act compliance service development.
Within the multi-accreditation tier, SGS SA leverages its pan-European notified body network to capture overflow demand from capacity-constrained competitors. Eurofins Scientific SE and TÜV SÜD AG exemplify divergent specialization strategies—Eurofins anchors position through biocompatibility testing laboratories in France and Germany, while TÜV SÜD dominates German market relationships with Mittelstand medical device manufacturers. These three entities represent distinct archetypes for how validation service providers navigate regulatory fragmentation across European markets.
| Leading Market Players |
|---|
| SGS SA |
| QuEST Global Services Pte. Ltd. |
| Intertek |
| Element Materials Technology |
| TÜV SÜD AG |
| North American Science Associates, Inc. (NAMSA) |
| Eurofins Scientific SE |
| Charles River |
| Pacific Biolabs |
| Others |
Cost & Logistics Intelligence
IEC 62304 software validation engineers in Stuttgart and Munich command compensation premiums that compress margins at mid-tier laboratories while widening spreads between premium and economy service tiers. Labor-cost differentials between German metropolitan hubs and Eastern European satellite offices directly determine pricing-band positioning across the European notified body landscape.
Pricing Analysis
Project-based fee structures with volume-scaled discounts dominate medical device validation contracting. Price differentiation hinges on ISO 17025 accreditation tier and FDA 510(k) submission experience. Cost compression in standard biocompatibility testing intensifies as automated analytical platforms displace manual protocols. Mittelstand manufacturers in Bavaria exhibit highest price sensitivity; multinational orthopedic portfolios anchored in Switzerland show lowest.
Supply Chain Analysis
Workforce availability constraints in German precision engineering clusters are forcing laboratory expansion into Poland and Czech Republic manufacturing corridors. Analytical equipment sourcing draws from Germany, Switzerland, and USA. Single-source vulnerability concentrates in specialized biocompatibility reagent supply. Distribution runs through pan-European notified body networks with regional satellite laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical device validation services function as a geographic-arbitrage play where regulatory cost differentials between EU MDR and FDA pathways create margin expansion opportunities for dual-accredited laboratories.
For Market Incumbents: Anchor market position through backward integration into specialized biocompatibility testing capabilities that competitors subcontract. Expand notified body capacity in Eastern European geographies to capture overflow demand from capacity-constrained German competitors. Software-as-medical-device substitution threatens traditional hardware validation volumes; IEC 62304 competency investment defends margin position.
For New Entrants and Emerging Players: Group purchasing organizations represent the most penetrable channel partner type for bypassing entrenched hospital procurement relationships. Target Paris-Saclay medical technology cluster startups lacking in-house quality assurance infrastructure. White-space opportunity concentrates in EU AI Act algorithmic validation services where assessment frameworks remain underdeveloped.
For Investors and Strategic Acquirers: Pan-European testing conglomerates are the most active acquirer in this space, consolidating regional laboratories to capture MDR recertification demand. Long-term viability favors targets with dual FDA-EU accreditation and software validation capabilities. Notified body designation delays serve as inflection indicator; resolution would compress pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Expansion | EU MDR implementation extends project queues to 12-18 months for high-risk categories. |
| Hospital System Partnership | Group purchasing organizations in North Rhine-Westphalia consolidate vendor qualification processes. |
| Software Companion Development | IEC 62304 compliance complexity commands premium pricing from SaMD manufacturers. |
| FDA Submission Capability Buildout | Premarket approval pathways demand extensive design history files from orthopedic implant portfolios. |
| Reimbursement Strategy Alignment | Companion diagnostic verification cycles accelerate with personalized medicine pipeline expansion. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement spanned regulatory affairs directors at notified bodies, biomedical engineers at Mittelstand manufacturers, GPO contracts managers at German hospital networks, and software validation leads at SaMD startups. Secondary validation drew from FDA 510(k) and PMA filings, EUDAMED database extracts, ISO accreditation registries, and notified body designation records. Bottom-up service-provider revenue aggregation and top-down end-user expenditure surveys triangulated market sizing.
Segment-weighting applied product type, regulatory standard, and technology methodology dimensions across the projection horizon. In vitro diagnostics, surgical instruments, and imaging systems anchored volume distribution. ISO 13485, FDA Guidelines, CE Marking, and IEC 62304 regulatory pathways shaped geographic revenue allocation. CAGRs derived from historical validation expenditure patterns and forward pipeline analysis of MDR recertification deadlines and AI Act implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to notified body designation velocity and FDA user fee reauthorization cycles. Forecasts reflect documented assumptions regarding regulatory implementation timelines and laboratory capacity expansion plans. Material deviation in MDR audit queue resolution or EU AI Act enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Bioabsorbable Stents Market
Medical Devices
Atrial Fibrillation Devices Market
Medical Devices
Interventional Spine Devices Market
Medical Devices
Polyglyconate Sutures Market
Medical Devices
Subcutaneous Implantable Defibrillator System Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Global Retinoscopes Market
Medical Devices
Radiotherapy Devices Market
Medical Devices
Penile Implants Market
Medical Devices
Massage Equipment Market
Medical Devices
Netherlands Aesthetic Devices Market
Medical Devices
Global Artificial Organs and Bionics Market
Medical Devices
South Korea Minimally Invasive Surgery Devices Market
Medical Devices
Global Surgical Visualization Systems Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
Global Sphygmomanometer Market