
 South Korea Ultrasound Devices Market | 2026-2036
South Korea Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Ultrasound Devices Market Analytics
South Korea is rewriting its domestic medical imaging supply equation through expanded cleanroom assembly capacity in Gyeonggi-do. Samsung Medison leverages in-house semiconductor fabrication to control transducer chip supply. Siemens Healthineers anchors premium cart-based system sales through long-term service contracts with Seoul National University Hospital. GE Healthcare competes on point-of-care deployment across rural clinic networks.
Ultrasound devices generate real-time anatomical images through piezoelectric crystal arrays operating at 2-18 MHz, with beamforming algorithms processing reflected acoustic echoes for diagnostic visualization. Portable ultrasound systems capture expanding share in emergency and bedside settings where maneuverability outweighs raw resolution. Diagnostic ultrasound dominates revenue pools in cardiology and obstetrics applications, while 4D imaging technology commands premium positioning in fetal monitoring suites. Hospitals absorb the majority of capital expenditure, though ambulatory surgical centers represent the fastest procurement expansion as outpatient procedural volume rises.
MFDS enforces Good Manufacturing Practice standards for active medical devices, while the Ministry of Health and Welfare reimbursement schedules directly determine hospital purchase cycles. KFDA-equivalent post-market surveillance protocols mandate adverse event reporting that shapes manufacturer liability exposure. Stakeholders must track how AI diagnostic software classification under revised medical device rules alters regulatory burden and time-to-market for next-generation platforms.
Market Dynamics
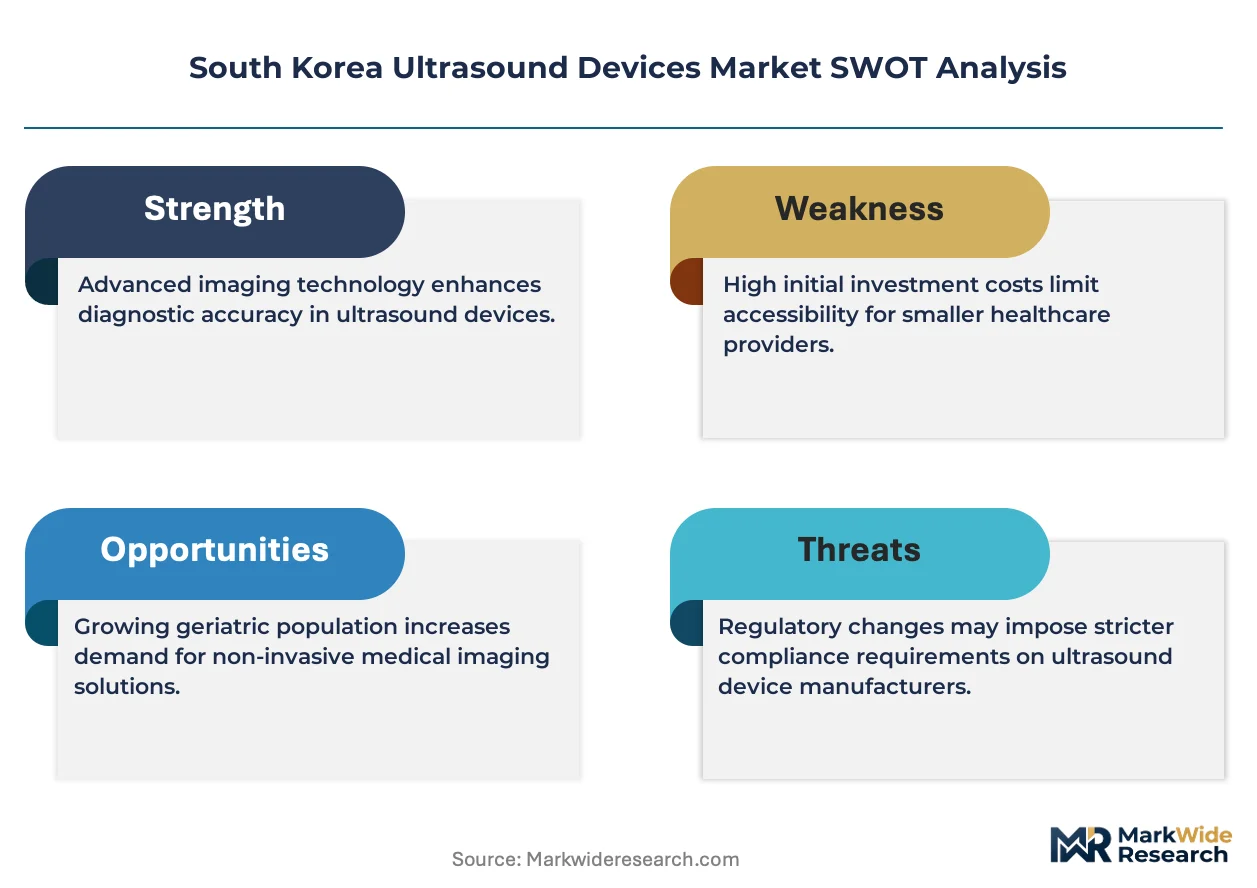
AI-integrated diagnostic software is restructuring procurement criteria across South Korea's hospital network, forcing manufacturers to recertify platforms under MFDS revised medical device classification rules while tertiary institutions prioritize algorithmic decision-support capabilities over hardware specifications alone.
Growth Catalysts
- MFDS AI Software Classification:Revised medical device rules create clear regulatory pathways for algorithmic diagnostic tools, accelerating hospital adoption of intelligent imaging platforms.
- Tertiary Hospital Capital Expansion:Seoul's metropolitan hospital network drives volume concentration as affiliated diagnostic chains standardize on premium cart-based systems.
- Piezoelectric Transducer Advances:Semiconductor fabrication integration enables tighter frequency control across 2-18 MHz operating ranges, improving beamforming precision.
Market Restraints
- Transducer Chip Supply Concentration:Domestic cleanroom assembly capacity in Gyeonggi-do remains limited relative to demand, creating input bottlenecks for array manufacturing.
- MFDS Post-Market Surveillance Burden:KFDA-equivalent adverse event reporting protocols extend manufacturer liability exposure and compliance costs.
- Portable System Resolution Trade-offs:Maneuverability advantages in emergency settings compromise raw image quality, restricting clinical application scope.
Strategic Opportunities
- Rural Clinic Network Penetration:Point-of-care deployment gaps outside Seoul's metropolitan corridor offer expansion terrain for handheld and portable system vendors.
- 4D Fetal Monitoring Suites:Obstetrics applications command premium positioning as birthing centers upgrade visualization capabilities for expectant parents.
- Ambulatory Surgical Center Channel:Outpatient procedural volume growth is redirecting procurement toward compact systems suited to same-day discharge protocols.
Industry Challenges
- AI Algorithm Validation Timelines:MFDS software-as-medical-device pathways require extensive clinical evidence packages, stretching certification cycles.
- Legacy System Integration Friction:Hospital IT infrastructure heterogeneity complicates seamless connectivity for cloud-connected imaging platforms.
- Specialized Sonographer Shortage:Advanced 4D and elastography modalities demand extended training protocols that outpace workforce pipeline capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Ultrasound Devices Market |
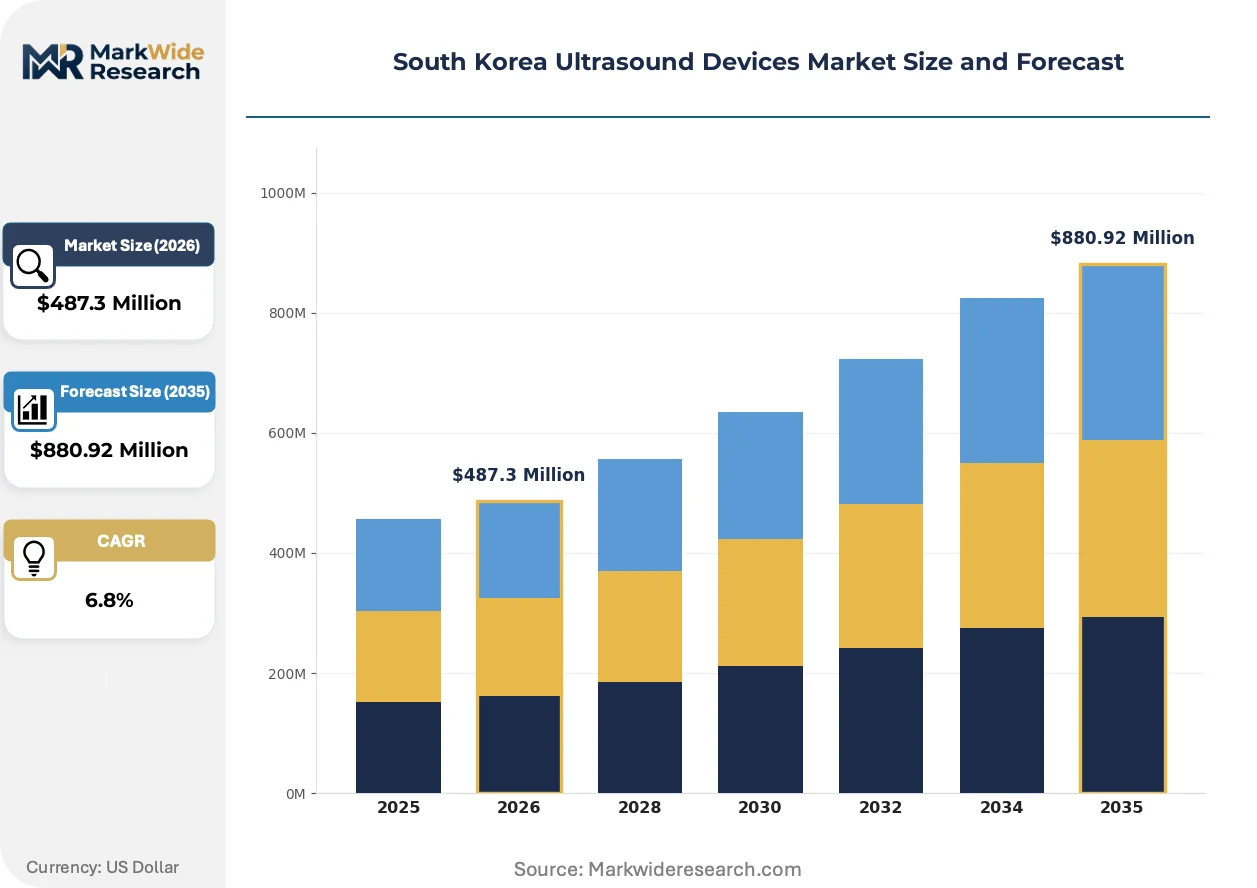
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ultrasound, Diagnostic Ultrasound, 3D Ultrasound, Therapeutic Ultrasound End User: Hospitals, Clinics, Ambulatory Surgical Centers, Diagnostic Laboratories Technology: Color Doppler, Power Doppler, 2D Imaging, 4D Imaging Application: Cardiology, Obstetrics, Urology, Musculoskeletal |
| Companies Covered | Samsung Medison, Siemens Healthineers, GE Healthcare, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Koninklijke Philips, Mindray Medical International, Alpinion Medical Systems, SG HealthCare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Ultrasound Devices Market Evolving Landscape
Beamforming architecture is converging with semiconductor advances to redefine performance benchmarks, while regulatory frameworks recalibrate around software-centric diagnostic tools and procurement patterns fragment across care settings.
Capacitive micromachined ultrasonic transducer technology is hybridizing conventional piezoelectric arrays with semiconductor fabrication methods, enabling tighter integration of transmit-receive electronics. Tertiary hospitals in Seoul are piloting these platforms for cardiac and abdominal applications where penetration depth competes with resolution demands. This hybridization is compressing the traditional separation between premium cart-based systems and mid-tier portable units.
MFDS enforcement of Good Manufacturing Practice standards for active medical devices is tightening traceability requirements across the supply chain. Manufacturers must now document cleanroom assembly protocols and component sourcing with granular specificity. Domestic producers with captive semiconductor fabrication capabilities are adapting fastest, while import-dependent vendors face extended qualification timelines.
Service contract unbundling is separating hardware acquisition from maintenance and software subscription components. Seoul National University Hospital and affiliated diagnostic chains are negotiating multi-year performance agreements that prioritize uptime guarantees over capital expenditure minimization. This restructuring is most pronounced in cardiology departments where system availability directly impacts procedural throughput.
South Korea Ultrasound Devices Market Segmentation
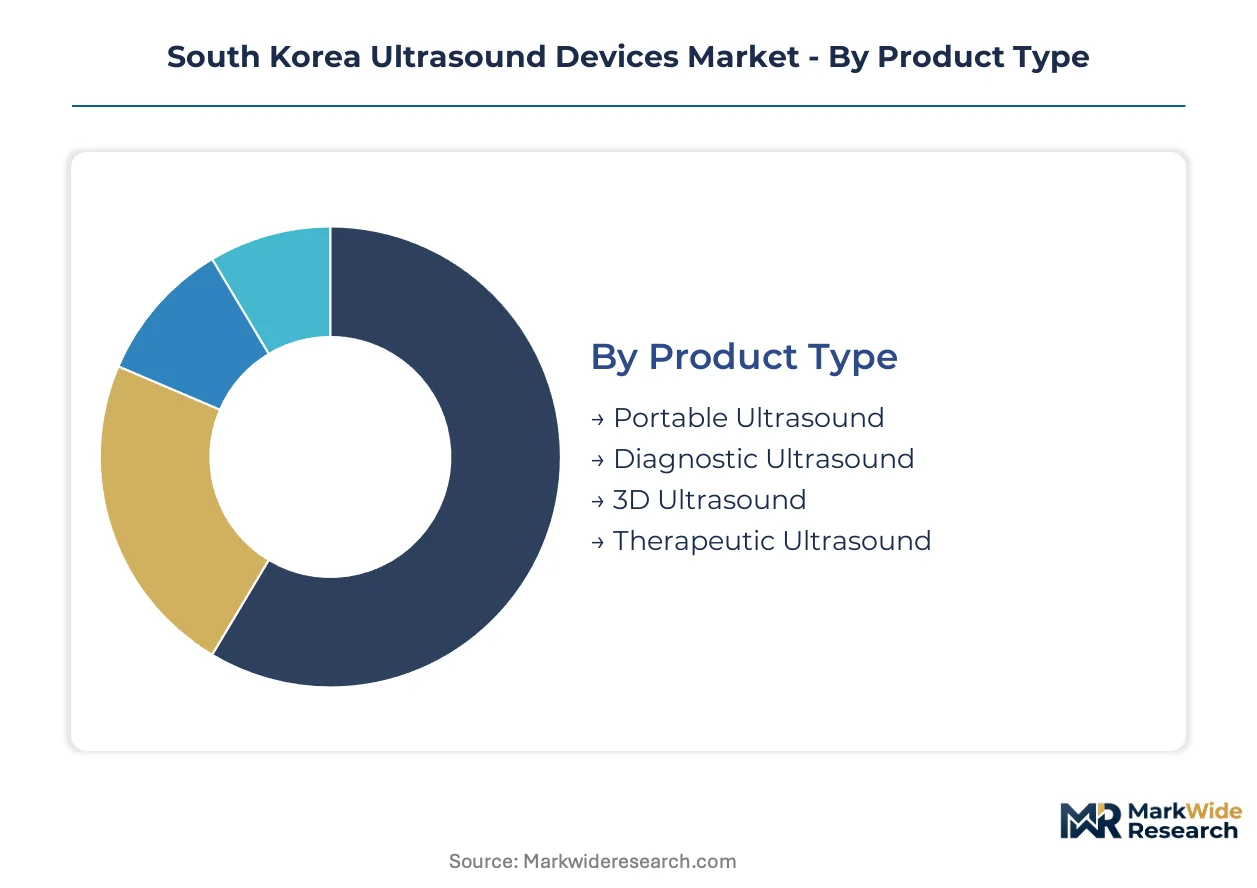
Ultrasound device segmentation in South Korea reflects divergent procurement priorities across care settings, with MFDS regulatory pathways and reimbursement schedules creating distinct commercial thresholds for each category. Understanding these segment boundaries enables targeted positioning against Seoul's tertiary hospital concentration versus rural clinic expansion corridors.
Product Type:
Use-case spectrum spans emergency bedside maneuverability through premium cart-based diagnostic suites, with semiconductor fabrication integration determining competitive positioning across frequency ranges.
- Portable Ultrasound:Compact systems operating at reduced power draw prioritize maneuverability in emergency departments and rural clinic networks where infrastructure constraints limit cart-based deployment. Seoul National University Hospital affiliates are piloting these for pre-hospital triage, though resolution trade-offs restrict cardiology application scope.
- Diagnostic Ultrasound:Cart-based platforms with 2-18 MHz transducer arrays dominate revenue pools in tertiary institutions, with beamforming precision determining procurement decisions. Samsung Medison leverages in-house semiconductor fabrication to control transducer chip supply for these systems.
- 3D Ultrasound:Volumetric reconstruction capabilities command mid-tier positioning between conventional 2D and premium 4D systems in obstetrics suites.
- Therapeutic Ultrasound:Focused acoustic delivery systems target physiotherapy and lithotripsy applications with distinct regulatory pathways under MFDS active device standards.
Established volume favors Diagnostic Ultrasound; emerging adoption favors Portable Ultrasound.
End User:
Capital expenditure cycles diverge sharply across institutional tiers, with reimbursement schedules and procedural throughput determining hardware refresh rates.
- Hospitals:Tertiary institutions absorb majority capital expenditure through multi-year service contracts prioritizing uptime guarantees. Siemens Healthineers anchors premium sales here via long-term agreements with Seoul National University Hospital.
- Ambulatory Surgical Centers:Same-day discharge protocols redirect procurement toward compact systems with rapid sterilization compatibility. These facilities are climbing the fastest as outpatient procedural volume rises.
- Clinics:Point-of-care deployment gaps outside Seoul's metropolitan corridor offer expansion terrain for handheld system vendors.
- Diagnostic Laboratories:High-throughput imaging chains standardize on platforms with automated workflow integration and cloud connectivity.
Procurement gravity sits with Hospitals; steepest expansion trajectory belongs to Ambulatory Surgical Centers.
Technology:
Beamforming architecture convergence with semiconductor advances redefines performance benchmarks across frequency modulation capabilities.
- 4D Imaging:Real-time volumetric rendering with temporal resolution commands premium positioning in fetal monitoring suites where expectant parent visualization drives capital allocation. Tertiary obstetrics departments in Seoul prioritize these for competitive differentiation.
- Color Doppler:Velocity-encoded flow mapping dominates cardiology applications, with algorithmic enhancement now central to MFDS software classification pathways.
- Power Doppler:Amplitude-based perfusion imaging gains traction in musculoskeletal and vascular applications where low-velocity detection matters.
- 2D Imaging:Conventional grayscale platforms retain cost-sensitive segment share despite algorithmic displacement pressure.
Revenue concentration aligns with 4D Imaging; algorithmic investment flows toward Color Doppler.
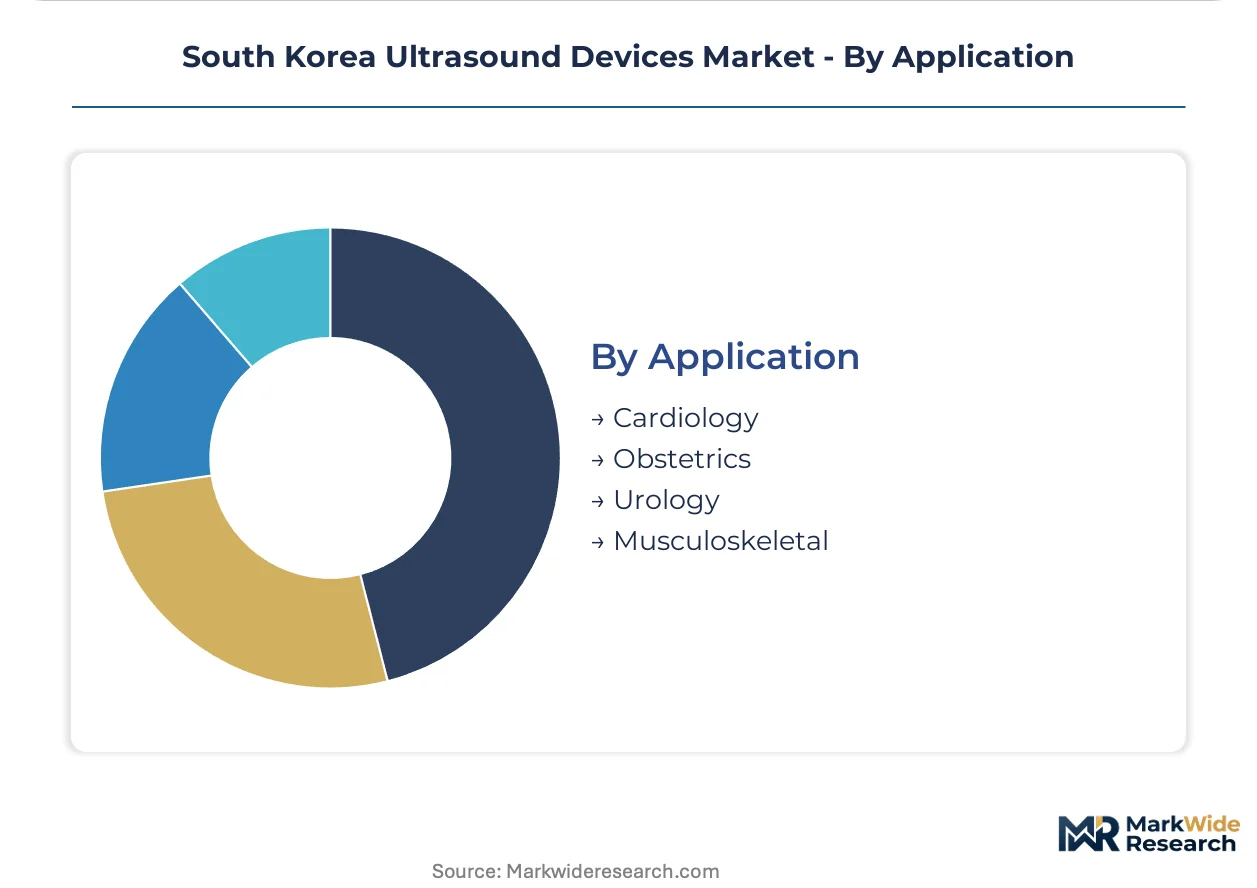
Application:
Clinical specialization determines transducer configuration requirements and software subscription attach rates.
- Obstetrics:4D fetal monitoring suites command premium hardware and software positioning, with birthing center upgrades driving visualization capability investments.
- Cardiology:Doppler-dependent functional assessment requires highest beamforming precision, creating vendor stickiness through specialized probe portfolios.
- Urology:Transrectal and abdominal imaging protocols favor mid-tier portable systems with targeted preset configurations.
- Musculoskeletal:Superficial structure imaging at higher frequencies expands point-of-care adoption in sports medicine and orthopedics.
Capital intensity peaks in Obstetrics; point-of-care penetration advances fastest in Musculoskeletal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cleanroom assembly capacity in Gyeonggi-do province concentrates transducer chip fabrication, while Seoul's metropolitan hospital network absorbs the majority of diagnostic system procurement. Provincial industrial clusters and regulatory enforcement patterns create divergent commercial thresholds across South Korea's territory.
Seoul Capital Area
Seoul National University Hospital and affiliated diagnostic chains anchor premium cart-based system demand through multi-year service contracts prioritizing uptime guarantees. MFDS Good Manufacturing Practice standards enforce traceability requirements that favor domestic producers with captive semiconductor fabrication. Samsung Medison leverages in-house chip production in Gyeonggi-do to supply Seoul's tertiary institutions with beamforming-optimized arrays.
Busan-Ulsan
Port logistics infrastructure and heavy industrial presence generate demand for point-of-care deployment in occupational health screening and maritime medical services. The Ministry of Health and Welfare reimbursement schedules determine purchase cycles for regional hospital networks. Ulsan's industrial medical complexes are expanding cleanroom partnerships to reduce import dependency for transducer components.
Daegu-Gyeongbuk
Textile and manufacturing heritage clusters are repurposing precision fabrication facilities toward medical device component supply. Regional health authorities are piloting portable ultrasound networks for rural outreach programs. Daegu's medical technology parks are attracting CMUT hybrid array developers seeking proximity to Seoul's validation infrastructure.
Daejeon-Sejong
Government research complexes and regulatory science centers concentrate AI algorithm validation capabilities under MFDS revised medical device classification rules. Public procurement for military and civil service hospitals creates standardized demand pools. Sejong's administrative city status accelerates pilot programs for cloud-connected imaging platforms.
Gwangju-Honam
Agricultural and aging demographics drive demand for compact systems in rural clinic networks where infrastructure constraints limit cart-based deployment. Regional universities are expanding sonographer training pipelines to address workforce shortages for advanced 4D modalities. Gwangju's biomedical cluster is targeting ambulatory surgical center channels with sterilization-compatible portable units.
South Korea Ultrasound Devices Market Competitive Landscape
Vertically integrated conglomerates and specialized imaging technology firms split the market into distinct competitive strata. Domestic producers with captive semiconductor fabrication anchor the supply side, while multinational service contract specialists dominate premium hospital procurement. Three strategic archetypes define positioning: in-house chip fabricators, algorithm-integrated platform vendors, and point-of-care mobility specialists. Capacity expansion in Gyeonggi-do cleanrooms and AI software recertification under MFDS pathways represent the dominant competitive moves reshaping procurement criteria.
Among domestic conglomerate fabricators, Samsung Medison exemplifies the vertically integrated archetype through captive transducer chip production. Siemens Healthineers and GE Healthcare occupy positions as multinational service contract anchors, with the former securing long-term agreements with Seoul National University Hospital affiliates. These three companies represent the spectrum from domestic supply chain control to global service infrastructure deployment.
| Leading Market Players |
|---|
| Samsung Medison |
| Siemens Healthineers |
| GE Healthcare |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| Koninklijke Philips |
| Mindray Medical International |
| Alpinion Medical Systems |
| SG HealthCare |
| Others |
Value Network & Pricing Analysis
Gyeonggi-do's cleanroom assembly capacity for piezoelectric transducer chips concentrates upstream supply control, granting domestic fabricators leverage over downstream system pricing while import-dependent vendors absorb qualification delays and margin compression.
Pricing Analysis
MFDS Good Manufacturing Practice standards dictate the pricing tier structure across South Korea's ultrasound device market, with certification-grade differentiation separating Seoul National University Hospital's premium cart-based procurement from rural clinic economy-tier portable acquisitions. Price differentiation hinges on semiconductor fabrication integration and after-sales service bundling, with in-house chip producers commanding hardware premiums. Cost compression in mid-tier diagnostic systems is intensifying because tertiary hospital service contracts now prioritize algorithmic uptime guarantees over capital expenditure minimization. Ambulatory surgical centers exhibit highest price sensitivity due to same-day discharge protocol constraints, while cardiology departments show lowest sensitivity given procedural throughput dependencies.
Supply Chain Analysis
Export control regimes on advanced semiconductor lithography equipment constrain transducer chip fabrication flows into South Korea, compressing domestic cleanroom expansion timelines. Supply concentrates in South Korea's Gyeonggi-do province for array assembly, Japan for precision ceramics, and the United States for beamforming algorithm IP. Raw material dependencies span piezoelectric crystals, CMOS readout circuits, and acoustic lens polymers. Single-source vulnerability around CMUT hybrid array technology creates qualification bottlenecks for next-generation platforms. Distribution runs through Seoul's metropolitan hospital procurement consortia and affiliated diagnostic chains for premium systems, with direct manufacturer relationships dominating rural clinic portable deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's ultrasound device market functions as a regulatory entrenchment story, where MFDS software recertification pathways and captive semiconductor fabrication create switching-cost moats that protect incumbent positioning against algorithmic disruption.
For Market Incumbents: Build switching-cost moats by embedding AI diagnostic software into multi-year hospital service contracts that exceed MFDS recertification cycle lengths. Deepen backward integration into Gyeonggi-do cleanroom capacity to control transducer chip supply against emerging CMUT hybrid array entrants. Anchor premium positioning through Seoul National University Hospital affiliation networks that resist price-based displacement. For New Entrants and Emerging Players: Pursue handheld portable penetration in Gwangju-Honam rural clinic networks where infrastructure constraints exclude cart-based competition. Target ambulatory surgical center channels with sterilization-compatible compact systems suited to same-day discharge growth. Deploy direct sales teams bypassing Seoul procurement consortia to capture price-sensitive volume outside metropolitan hospital networks. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because algorithmic validation timelines and MFDS software classification burdens favor scaled R&D platforms over fragmented hardware specialists. Target acquisition profiles center on domestic cleanroom operators with captive semiconductor fabrication and established MFDS quality system documentation. Monitor MFDS adverse event reporting frequency as the signal indicating incumbent liability exposure versus emerging platform reliability.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS AI Software Recertification | Accelerates hospital procurement of algorithm-integrated platforms by clarifying regulatory pathways under revised medical device rules. |
| Gyeonggi-do Cleanroom Capacity Expansion | Reduces import dependency for transducer chip supply while tightening domestic control over beamforming array manufacturing. |
| Hospital System Partnership Consolidation | Locks in multi-year service contracts with Seoul National University Hospital affiliates that prioritize uptime over capital minimization. |
| Portable System Rural Deployment | Captures point-of-care gaps outside metropolitan corridors where infrastructure constraints limit cart-based system penetration. |
| 4D Fetal Monitoring Suite Upgrade | Commands premium positioning in obstetrics applications where expectant parent visualization drives birthing center capital allocation. |
Research Methodology
Cross-validation between primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and MFDS regulatory affairs specialists anchors the qualitative findings against secondary validation from MFDS device clearance databases, hospital procurement records, and Ministry of Health and Welfare reimbursement schedules. Bottom-up triangulation across transducer chip fabrication capacity in Gyeonggi-do and top-down reconciliation against tertiary hospital capital expenditure cycles ensures dimensional consistency.
Calibration against historical MFDS clearance timelines and semiconductor fabrication yield curves shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, end user tier, technology modality, and clinical application, with CAGRs derived from elasticity modeling against reimbursement schedule revisions and outpatient procedural volume trajectories. CMUT hybrid array adoption curves and AI software validation timelines constitute critical industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Korean won exchange rates against Japanese yen and US dollar import costs would shift the trajectory of transducer component sourcing economics. Forecasts reflect documented assumptions regarding MFDS enforcement intensity and cleanroom capacity expansion timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Clinical Rollators Market
Medical Devices
Mandibular Advancement Devices Market
Medical Devices
Pediatric Home-Use Medical Devices Market
Medical Devices
MIS Sacroiliac Joint Fusion Market
Medical Devices
Global Medical Device Contract Manufacturing Market
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
Walking Aids Market
Medical Devices
Global Implantable Cardiac Monitor Market
Medical Devices
Global Photobiostimulation Market
Medical Devices
Neurotech Devices Market
Medical Devices
Global Medical Footwear Market
Medical Devices
Global Surgical/Operating Microscopes Market
Medical Devices
Global Deep Brain Stimulation Devices Market
Medical Devices
Robotic Biopsy Devices Market
Medical Devices
Cheek Implants Market
Medical Devices
Breast Biopsy Marker Market