
 MRI Motion Tracking Systems Market | 2026-2036
MRI Motion Tracking Systems Market Size, Share, and Industry Trends Forecast 2026-2036
MRI Motion Tracking Systems Market Intelligence
Project finance and equipment leasing is rewriting competitive dynamics in MRI motion tracking, allowing mid-sized imaging centers to deploy advanced patient monitoring without capital-intensive purchases. KinetiCor leverages its specialized sensor architecture to compete in high-field MRI environments. Siemens Healthineers anchors its position through deep integration with existing scanner platforms. GE HealthCare extends its reach via service contracts that bundle motion tracking with broader imaging system maintenance.
MRI motion tracking systems use optical, electromagnetic, or infrared sensors to detect and compensate for patient movement during magnetic resonance imaging, typically achieving sub-millimeter positional accuracy through real-time feedback loops that preserve image fidelity. These systems serve primarily to reduce motion artifacts that degrade diagnostic quality and necessitate costly scan repetitions. Optical tracking dominates current installations due to its non-interference with magnetic fields, while hybrid systems represent the fastest-expanding category as vendors combine multiple sensing modalities to address complex neurological and cardiac applications. Software layers command disproportionate margin pools because recurring licensing and algorithm updates generate sustained revenue beyond initial hardware deployment.
The FDA's 510(k) clearance framework and the EU MDR's clinical evidence requirements shape product development timelines and market access strategies for device manufacturers. Japan's PMDA imposes additional localization testing that filters out vendors lacking dedicated regulatory infrastructure. Stakeholders must monitor how evolving AI-enabled tracking algorithms trigger new software-as-medical-device classifications across major jurisdictions.
Market Dynamics
Equipment leasing and project finance are compressing capital barriers for mid-sized imaging centers, allowing real-time motion tracking deployment without full ownership burdens. This financing shift is redistributing purchasing power across the provider landscape.
Growth Catalysts
- EU MDR compliance deadlines:The Medical Device Regulation's clinical evidence requirements are accelerating validation investments by vendors targeting European hospital procurement cycles.
- Neurological imaging protocols:High-resolution functional MRI studies for pre-surgical mapping demand sub-millimeter tracking precision that optical systems now deliver.
- Japan's aging diagnostic infrastructure:Hospital replacement cycles for MRI suites in Tokyo and Osaka are bundling motion tracking with scanner upgrades.
Market Restraints
- Electromagnetic sensor interference:Radiofrequency shielding requirements for 7 Tesla scanners limit electromagnetic tracking deployment in ultra-high-field environments.
- CE marking documentation burden:The EU MDR's post-market surveillance obligations extend product launch timelines by 12-18 months for smaller manufacturers.
- Optical marker occlusion:Patient body positioning during cardiac MRI frequently blocks line-of-sight for camera-based systems, forcing scan interruptions.
Strategic Opportunities
- Pediatric sedation reduction:Real-time tracking enables faster scan completion for uncooperative young patients, opening pediatric radiology departments previously reliant on anesthesia.
- Hybrid sensing convergence:Vendors combining optical and electromagnetic modalities are capturing complex neurological and cardiac applications that single-technology systems cannot address.
- Software-as-medical-device pathways:AI-enabled algorithm updates are creating recurring revenue streams through subscription licensing beyond initial hardware sales.
Industry Challenges
- Algorithm validation timelines:Machine learning-based tracking systems face extended FDA 510(k) review cycles as regulators establish performance benchmarking protocols.
- Legacy scanner integration:Retrofitting motion tracking onto installed MRI platforms from GE, Siemens, and Philips requires proprietary interface development for each manufacturer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRI Motion Tracking Systems Market |
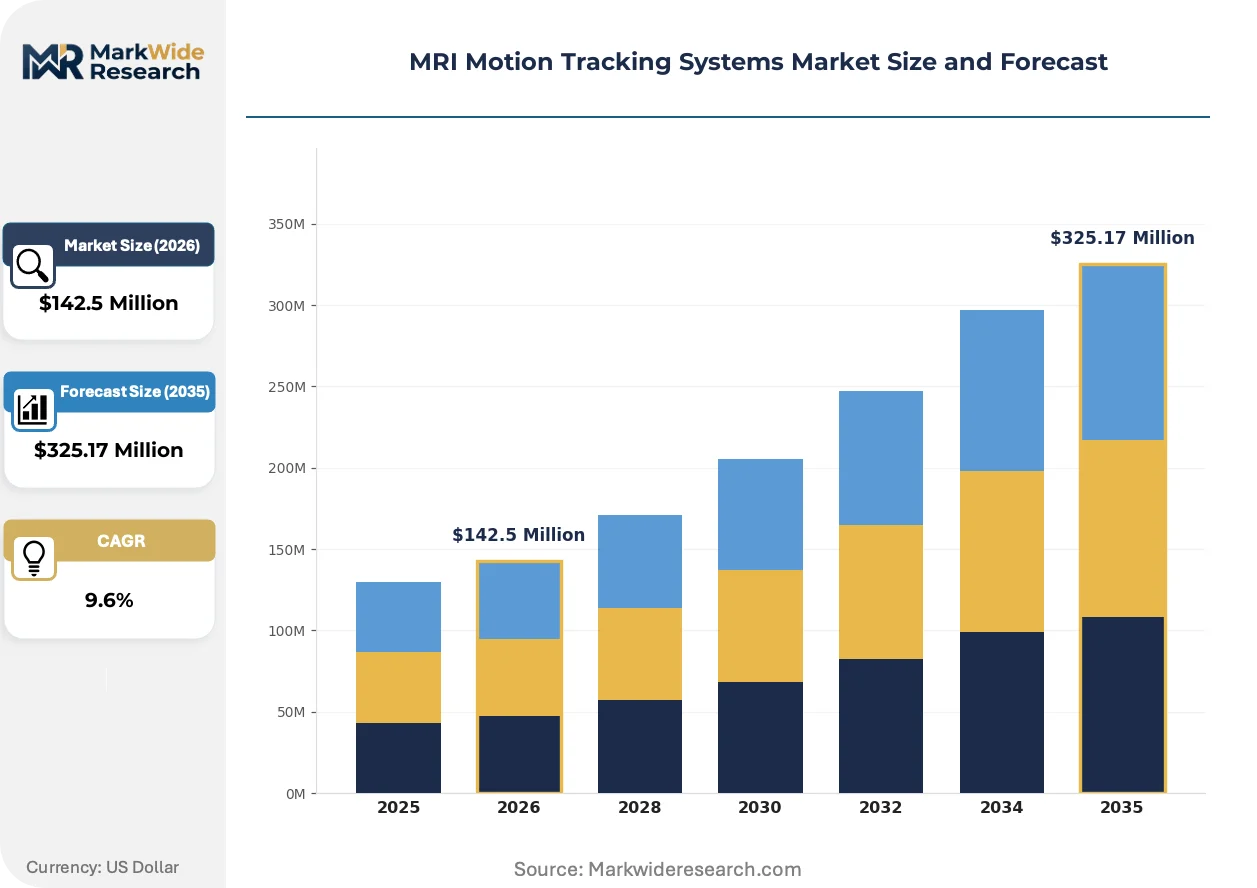
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $325.17 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Systems, Software, Sensors, Services End User: Hospitals, Research Centers, Clinics, Diagnostic Labs Technology: Optical Tracking, Electromagnetic Tracking, Infrared Systems, Hybrid Systems Application: Oncology, Neurology, Orthopedics, Cardiology |
| Companies Covered | Canon Medical Systems, KinetiCor, Inc., Siemens Healthineers, Nous Imaging, Inc., TracInnovations A/S, GE HealthCare, FUJIFILM Healthcare, Qualisys, Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRI Motion Tracking Systems Market Strategic Shifts & Innovations
Sensor fusion architectures are displacing single-modality designs across high-field installations. Vendors are racing to integrate optical, electromagnetic, and infrared layers into unified tracking platforms.
Hybrid motion tracking is migrating from experimental neurological research to standard clinical deployment in academic medical centers. Major hospital systems in Germany and the United States are mandating multi-sensor configurations for new MRI suite constructions. The technology is migrating from premium-tier installations toward mid-field systems as component costs compress and software standardization accelerates.
The FDA's evolving software-as-medical-device guidance is forcing algorithm developers to document training data provenance and performance drift metrics. This documentation burden favors established vendors with dedicated regulatory affairs teams. Neurological imaging applications face the steepest compliance ramps as tracking algorithms directly influence diagnostic interpretation.
Service unbundling is fragmenting traditional equipment procurement in the United States. Imaging centers are separating motion tracking hardware acquisition from installation, calibration, and algorithm update services. Independent service organizations in Texas and California are capturing maintenance contracts previously held by original equipment manufacturers.
MRI Motion Tracking Systems Market Segmentation
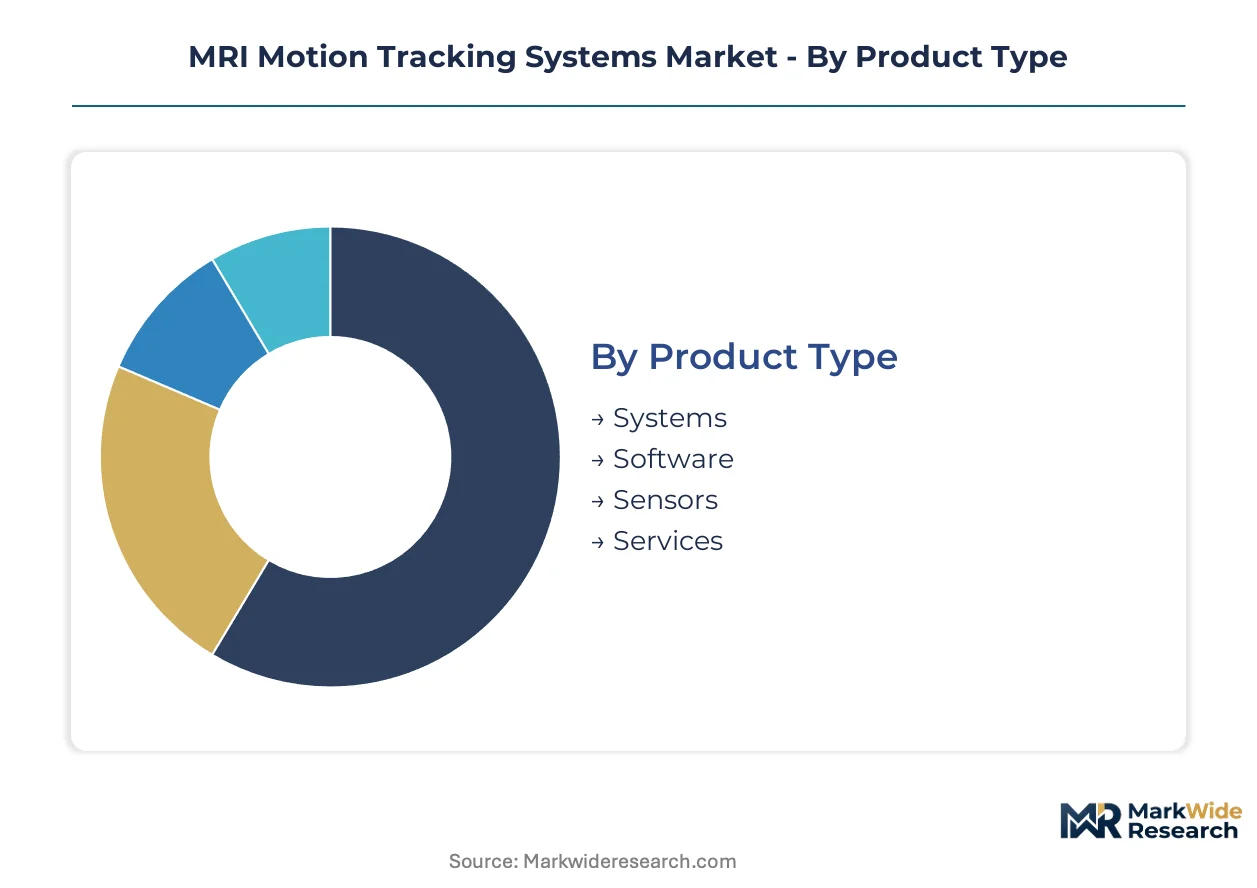
Segmentation in MRI motion tracking reveals divergent technology maturities and purchasing behaviors across clinical settings. Product architecture, sensing modality, and end-user infrastructure each create distinct margin profiles and deployment timelines that vendors must navigate simultaneously.
Product Type:
Use-case spectrum spans capital-intensive hardware installations through recurring software licensing and aftermarket service contracts.
- Systems:Integrated hardware platforms combining sensors, processing units, and calibration interfaces for direct MRI suite installation. Academic medical centers in Germany and the United States prioritize these configurations for high-throughput neurological protocols requiring sub-millimeter precision.
- Software:Algorithm layers processing raw sensor data into motion compensation vectors, delivered via perpetual licenses or subscription models. Recurring revenue concentration here attracts vendors seeking margin stability beyond one-time hardware sales.
- Sensors:Discrete optical, electromagnetic, or infrared detection components sold for retrofit or replacement cycles.
- Services:Installation, calibration, preventive maintenance, and algorithm update contracts unbundling from traditional equipment procurement.
Established volume favors Systems; emerging adoption favors Software.
End User:
Customer infrastructure determines deployment complexity and purchasing authority concentration.
- Hospitals:Large-scale radiology departments with dedicated MRI suites and capital equipment committees. Tokyo and Osaka replacement cycles for aging diagnostic infrastructure are bundling motion tracking with scanner upgrades, creating concentrated demand windows.
- Research Centers:Academic institutions conducting functional MRI studies for pre-surgical mapping and neuroscientific investigation. Sub-millimeter tracking precision requirements here drive specification premiums for hybrid sensing configurations.
- Clinics:Outpatient imaging facilities with lower scan volumes and compressed capital budgets.
- Diagnostic Labs:Independent imaging providers competing on throughput and turnaround time metrics.
Procurement authority concentrates in Hospitals; specification leadership originates in Research Centers.
Technology:
Sensing modality selection trades magnetic field compatibility against line-of-sight reliability and multi-parameter tracking capability.
- Optical Tracking:Camera-based positional detection using passive or active markers, dominant in current installations due to non-interference with magnetic fields. Cardiac MRI applications in the United States face persistent occlusion challenges when patient positioning blocks camera sightlines.
- Hybrid Systems:Sensor fusion architectures combining optical, electromagnetic, and infrared layers into unified platforms. These configurations are climbing the fastest in academic medical centers across Germany and the United States for complex neurological and cardiac applications.
- Electromagnetic Tracking:Radiofrequency-based position sensing limited by shielding requirements at 7 Tesla field strengths.
- Infrared Systems:Thermal or structured-light detection for specific motion signature identification.
Deployment scale favors Optical Tracking; capability expansion favors Hybrid Systems.
Application:
Clinical specialty determines resolution requirements, scan duration, and patient cooperation constraints.
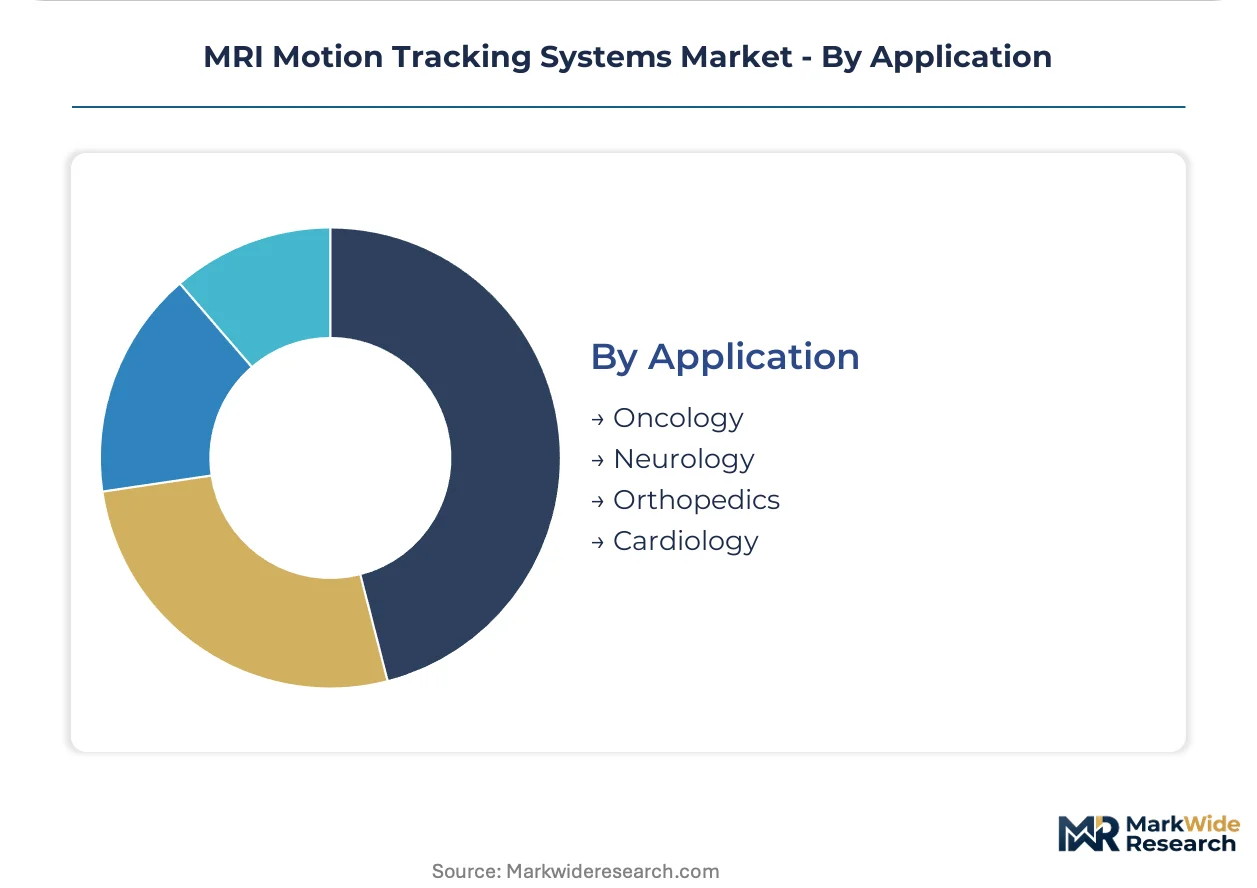
- Neurology:Functional MRI for pre-surgical mapping and neurodegenerative assessment demands the most stringent tracking precision. High-resolution protocols here are mandating hybrid sensor configurations in major hospital systems.
- Oncology:Tumor imaging and treatment monitoring applications where motion artifacts compromise lesion boundary definition. Radiation therapy planning integration in German university hospitals is driving specification requirements.
- Cardiology:Cardiac MRI with continuous cardiac and respiratory motion compensation needs.
- Orthopedics:Musculoskeletal imaging with patient positioning stability challenges.
Precision requirements peak in Neurology; volume throughput concentrates in Oncology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA device clearance pathways and EU MDR clinical evidence requirements are accelerating product validation timelines across major jurisdictions. Demand concentrates in the United States, Germany, and Japan as these countries invest in advanced diagnostic infrastructure.
United States
Academic medical centers in Boston and Houston are mandating hybrid sensor configurations for new MRI suite constructions. The FDA's 510(k) clearance framework shapes algorithm validation timelines for machine learning-based tracking systems. Texas and California imaging centers are unbundling motion tracking hardware from maintenance contracts, capturing service revenue previously held by original equipment manufacturers.
Germany
German university hospitals are driving radiation therapy planning integration that bundles motion tracking with scanner upgrades. The EU MDR's post-market surveillance obligations extend product launch timelines by 12-18 months for smaller manufacturers. Bavaria and North Rhine-Westphalia replacement cycles for aging diagnostic infrastructure are creating concentrated demand windows for multi-sensor platforms.
Japan
Tokyo and Osaka hospital replacement cycles for MRI suites are bundling motion tracking with scanner upgrades. The PMDA imposes additional localization testing that filters out vendors lacking dedicated regulatory infrastructure. Kanto region academic centers are specifying sub-millimeter tracking precision for functional MRI studies in pre-surgical mapping protocols.
United Kingdom
NHS radiology departments in London and Manchester are deploying real-time tracking to reduce pediatric sedation requirements. The MHRA operates under retained EU MDR requirements with additional UKCA marking obligations for market access. Southeast England research centers are migrating hybrid motion tracking from experimental neurological studies toward standard clinical deployment.
Switzerland
Swiss university hospitals in Zurich and Geneva are specifying multi-sensor configurations for complex cardiac and neurological applications. Swissmedic maintains alignment with EU MDR standards while requiring German-language documentation for device submissions. Basel-region pharmaceutical research facilities are integrating motion tracking into clinical trial imaging protocols.
MRI Motion Tracking Systems Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three archetypes: diversified imaging conglomerates with scanner-integrated platforms, sensor-technology specialists with modular hardware, and algorithm-focused developers with software-as-medical-device offerings. Dominant competitive moves include strategic partnerships for legacy scanner integration and geographic expansion through regulatory infrastructure investment.
Within the sensor-specialist tier, KinetiCor and TracInnovations exemplify focused hardware developers competing on magnetic field compatibility. Siemens Healthineers anchors the diversified conglomerate archetype through deep platform integration. Among algorithm-focused developers, Nous Imaging occupies a position representing AI-enabled tracking software that triggers evolving software-as-medical-device classifications.
| Leading Market Players |
|---|
| Canon Medical Systems |
| KinetiCor, Inc. |
| Siemens Healthineers |
| Nous Imaging, Inc. |
| TracInnovations A/S |
| GE HealthCare |
| FUJIFILM Healthcare |
| Qualisys |
| Philips |
| Others |
Cost & Logistics Intelligence
Bavaria's precision sensor manufacturing cluster anchors component supply for MRI motion tracking systems, concentrating upstream capacity that translates into asymmetric pricing power for hybrid sensing platforms over single-modality alternatives. This geographic concentration shapes how vendors negotiate volume contracts with academic medical centers and imaging center chains.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA 510(k)-cleared and CE-marked MDR-compliant systems commanding substantial premiums over uncertified research-grade configurations. Three-tier pricing structure across premium, standard, and economy levels reflects this regulatory stratification, with software-as-medical-device subscriptions adding recurring revenue layers. Cost compression in the economy tier is intensifying because independent service organizations in Texas and California are unbundling maintenance from hardware acquisition. Research centers exhibit the lowest price sensitivity due to grant-funded procurement, while mid-sized imaging centers face acute budget constraints.
Supply Chain Analysis
High-resolution optical sensors and electromagnetic coils draw from specialized semiconductor foundries concentrated in Taiwan, Germany, and Japan, with rare-earth magnet components sourced through limited channels. Raw material dependencies include precision optical glass, radiofrequency shielding alloys, and application-specific integrated circuits for real-time signal processing. Single-source vulnerability persists for 7 Tesla-compatible electromagnetic sensors due to concentrated manufacturing expertise. Distribution runs through original equipment manufacturer service networks and emerging independent calibration specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the vendor base creates entry niches as service unbundling and software-as-medical-device pathways redistribute purchasing authority away from consolidated imaging conglomerates.
For Market Incumbents: Harden regulatory moats by accelerating EU MDR post-market surveillance infrastructure investments before smaller competitors can absorb documentation burdens. Deepen backward integration into proprietary sensor architectures to defend margin position against modular hardware specialists. Lock in hospital system partnerships through bundled scanner upgrade cycles that embed motion tracking as non-negotiable infrastructure. For New Entrants and Emerging Players: Establish a beachhead in pediatric radiology departments where sedation reduction protocols create urgent, unmet demand for faster scan completion. Target mid-sized imaging centers in Texas and California where equipment leasing appetite runs highest and incumbent service contracts are expiring. Lead with algorithm-first positioning that decouples software licensing from hardware procurement. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA and EU MDR documentation burdens are structurally filtering out undercapitalized competitors. Acquisition targets should display dedicated regulatory affairs teams with proven 510(k) and CE marking track records. Watch for inflection when AI-enabled tracking algorithms trigger reclassification as software-as-medical-device across multiple jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance accelerates European hospital procurement access for validated vendors. |
| Hospital System Partnership | Bundled scanner upgrades in Germany and Japan embed motion tracking as standard infrastructure. |
| Software Companion Development | AI-enabled algorithm subscriptions create recurring revenue beyond one-time hardware deployment. |
| Reimbursement Strategy | Pediatric sedation reduction protocols open new billing codes for faster scan completion. |
| FDA Submission | 510(k) clearance for machine learning-based tracking extends addressable market to risk-averse systems. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with radiology department heads, biomedical engineers, hospital procurement committee members, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up and top-down triangulation cross-checked vendor shipment estimates against installed base calculations.
Calibration against historical validation timelines and regulatory approval cycles anchored the analytical framework across the analysis window. Segmentation dimensions modeled include sensing modality, product architecture, end-user infrastructure tier, clinical application specialty, and regional regulatory cluster. CAGRs were derived from weighted average growth assumptions applied to each segment, with algorithm licensing velocity and replacement cycle timing for aging MRI suites serving as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure budgets or medical device reimbursement rates would shift the trajectory. Forecasts reflect documented assumptions about regulatory pathway durations and technology adoption curves. Cross-checking against hospital construction pipeline data and scanner manufacturer order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Anesthesia Vaporizers Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Nitinol-Based Guide Wire Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
Nephrostomy Devices Market
Medical Devices
APAC Ablation Devices Market
Medical Devices
Transabdominal Retrieval Kits Market
Medical Devices
Global Coronary Artery Bypass Graft Devices Market
Medical Devices
Global Medical Device Labeling Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Pelvic Floor Stimulators Market
Medical Devices
Pressotherapy Systems Market
Medical Devices
Submucosal Injections Market
Medical Devices
Pharmaceutical Robots Market
Medical Devices
External Pacemakers Market
Medical Devices
Small Bone and Joint Devices Market