
 Reprocessed Medical Devices Market | 2026-2036
Reprocessed Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Reprocessed Medical Devices Market Analysis
Aftermarket service revenue from device reprocessing is rewriting profit allocation between original manufacturers and third-party reprocessors. Stryker leverages its in-house reprocessing division to capture recurring revenue streams from hospital customers. Johnson & Johnson MedTech competes through specialized sterilization technologies that extend device lifecycle counts. Vanguard AG dominates the European reprocessing landscape with centralized cleaning and validation facilities.
Reprocessed medical devices are cleaned, sterilized, inspected, and functionally restored products originally designated for single use, meeting biocompatibility and sterility assurance levels equivalent to new devices through validated washing, disinfection, and packaging protocols. Their primary purpose is reducing per-procedure supply costs while maintaining clinical safety standards in high-volume hospital settings. Catheters command the largest revenue pool among product types due to high procedural volume and established reprocessing protocols, while endoscopic devices represent the fastest-expanding category as flexible scope refurbishment techniques advance. Cardiology applications anchor current demand through electrophysiology catheter reuse programs, though orthopedics is gaining traction as power tool reprocessing achieves broader regulatory acceptance.
The FDA's 510(k) premarket notification framework governs reprocessed single-use device commercialization in the United States, requiring substantial equivalence demonstrations that shape product development timelines and validation investment levels. The EU Medical Device Regulation imposes stricter clinical evidence and quality system requirements through notified body oversight, influencing which reprocessors achieve CE marking for European market access. Stakeholders must monitor evolving FDA guidance on cleaning validation endpoints and emerging EU harmonized standards for reprocessed device labeling claims.
Market Dynamics
Hospital procurement departments face mounting pressure to reduce per-procedure supply costs while maintaining clinical safety standards, creating structural pull toward validated reprocessing programs that extend device lifecycles without compromising sterility assurance.
Growth Catalysts
- FDA 510(k) Pathway Streamlining:The FDA's substantial equivalence framework for reprocessed single-use devices accelerates commercialization timelines and reduces validation investment barriers for third-party reprocessors entering the US market.
- German Hospital Cost-Containment Mandates:National reimbursement pressures force German healthcare facilities to adopt catheter and endoscopic device reprocessing at scale, driving volume concentration in centralized cleaning facilities.
- Electrophysiology Catheter Reuse Protocols:Cardiology departments deploy validated washing and functional restoration techniques for high-value electrophysiology devices, establishing clinical precedent for complex single-use device reprocessing.
Market Restraints
- EU Medical Device Regulation Stringency:The MDR imposes elevated clinical evidence and quality system requirements through notified body oversight, extending CE marking timelines and excluding smaller reprocessors from European market access.
- Original Manufacturer IP Protections:Device patents and proprietary sterilization specifications limit third-party reprocessor access to certain catheter designs and endoscopic component architectures.
- Stainless Steel and Polymer Input Volatility:Reprocessing facility capital equipment and consumable packaging materials face commodity price fluctuations that compress margin structures in high-volume operations.
Strategic Opportunities
- Orthopedic Power Tool Reprocessing:Broader FDA regulatory acceptance for surgical power tool refurbishment creates expansion potential beyond established cardiology and endoscopy categories.
- CE Marking Harmonization for Flexible Scopes:Advancements in scope refurbishment techniques align with emerging EU harmonized standards for reprocessed device labeling claims, opening premium endoscopic segments.
- Centralized Validation Facility Networks:Regional hub-and-spoke cleaning and sterilization infrastructure reduces per-facility compliance burden while capturing economies of scale in multi-hospital systems.
Industry Challenges
- Cleaning Validation Endpoint Disputes:Evolving FDA guidance on residual protein and bioburden detection thresholds creates compliance uncertainty for reprocessors validating new device categories.
- Sterilization Technician Certification Gaps:Shortages of personnel trained in ISO 17665 steam sterilization and ISO 11137 radiation dosimetry protocols constrain facility throughput expansion.
- Legacy Hospital Inventory System Integration:Reprocessed device tracking and lot traceability requirements clash with established ERP configurations in older healthcare IT environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reprocessed Medical Devices Market |
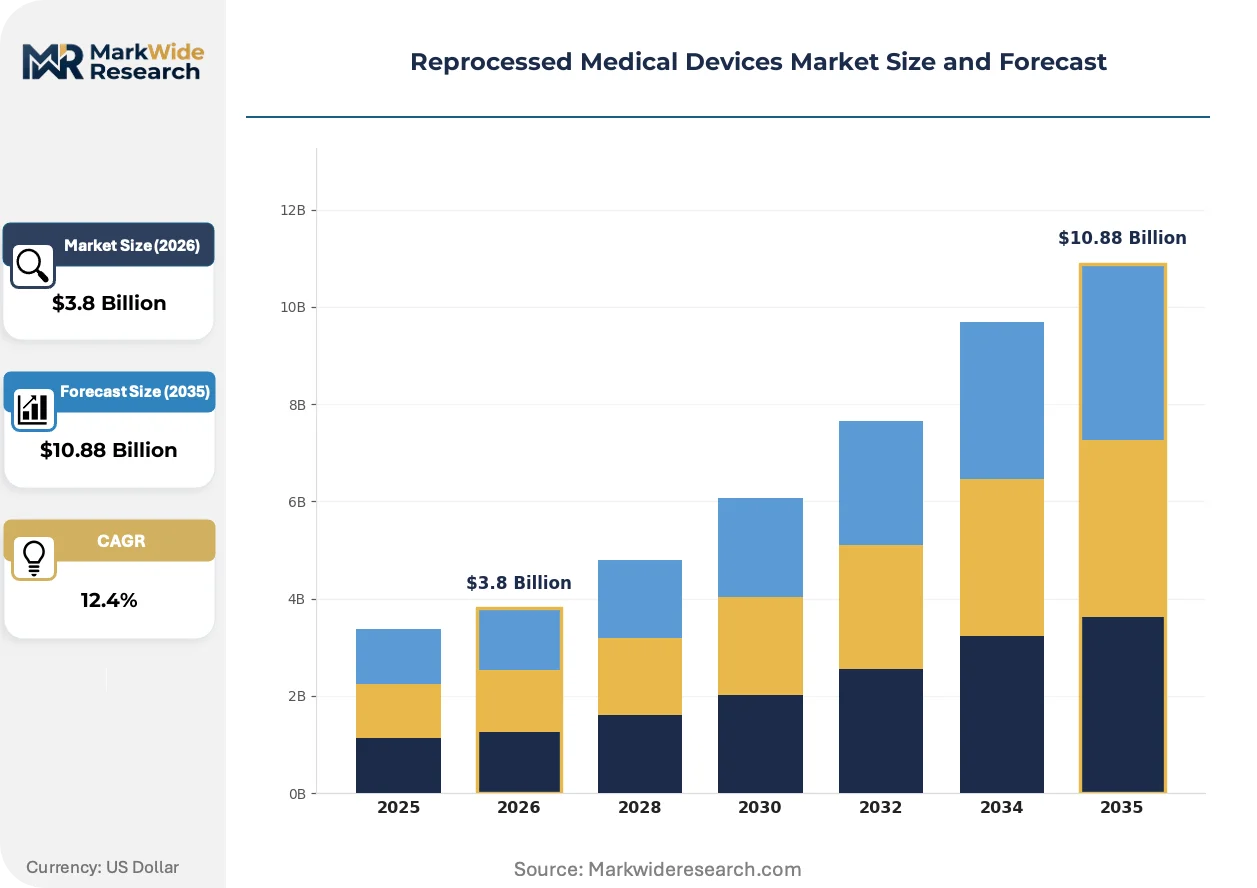
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Surgical Instruments, Electrosurgical Devices, Endoscopic Devices Application: Cardiology, Orthopedics, Gastroenterology, Urology Delivery Mode: Hospitals, Clinics, Home Healthcare, Specialized Centers Certification: ISO Certified, FDA Approved, CE Marked, Reusable |
| Companies Covered | Stryker, Johnson & Johnson MedTech, Medline Industries, Arjo, Cardinal Health, Innovative Health, NEScientific, SureTek Medical, Vanguard AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reprocessed Medical Devices Market Emerging Trajectories
Digital validation technologies and automated inspection systems are compressing quality assurance cycles while regulatory harmonization efforts reshape competitive access rules across major healthcare markets.
Ultrasonic cleaning combined with automated visual inspection systems is virtualizing traditional manual cleaning validation workflows. German and US hospital reprocessing centers deploy these integrated platforms to reduce human error rates in bioburden detection. The technology is virtualizing labor-intensive quality control steps, enabling higher-throughput operations without proportional staffing increases.
The EU Medical Device Regulation's stricter clinical evidence requirements for reprocessed devices are restructuring European market entry economics. Notified body oversight now demands extensive technical documentation that smaller third-party reprocessors struggle to assemble. Cardiology catheter reprocessors with established quality management systems are consolidating market position while new entrants face extended certification timelines.
Hospital supply chain managers increasingly bundle reprocessed device procurement with sterilization service contracts rather than purchasing disposable alternatives separately. This consolidated sourcing model displaces traditional distributor relationships in large integrated delivery networks. The shift is most visible in US multi-hospital systems where procurement officers negotiate enterprise-wide reprocessing agreements with centralized validation providers.
Reprocessed Medical Devices Market Segmentation
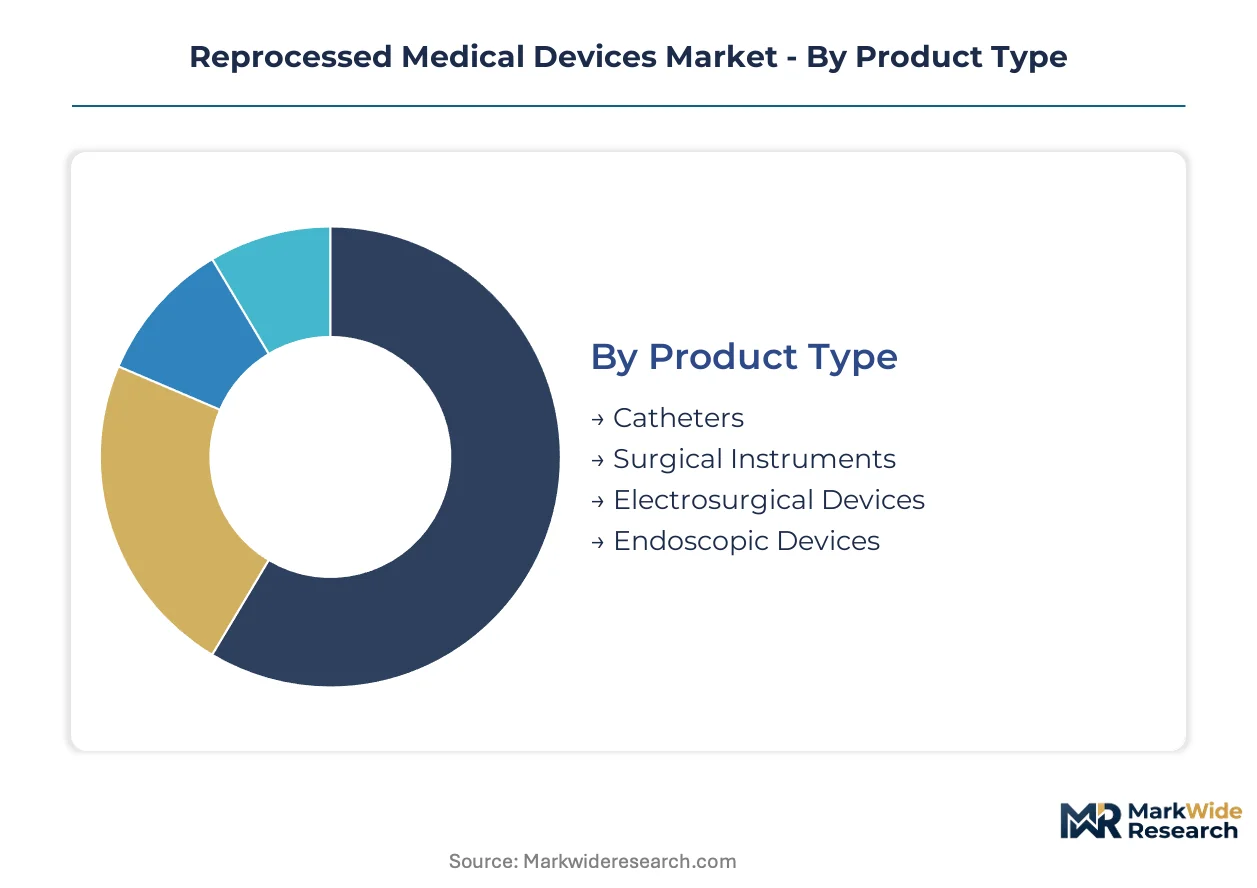
Segmentation in reprocessed medical devices reflects divergent maturity levels across product categories, with established catheter protocols contrasting emerging orthopedic applications. Understanding these structural differences enables procurement officers to align validation investments with regulatory readiness and volume economics.
Product Type:
Mature reprocessing protocols dominate high-volume categories, while emerging techniques unlock expansion in complex instrument refurbishment.
- Catheters:Polymer-based tubular devices undergo validated washing, disinfection, and functional testing to restore biocompatibility. Demand concentrates in German electrophysiology departments facing national cost-containment mandates. Cardiology catheter reuse programs anchor current procurement volumes through established FDA 510(k) clearance pathways.
- Endoscopic Devices:Flexible fiberoptic and video scopes require specialized refurbishment of insertion tubes, bending sections, and electrical connectors. German hospital systems deploy centralized cleaning facilities for these high-value instruments. Advancements in automated visual inspection systems are compressing quality assurance cycles for scope reprocessors.
- Surgical Instruments:Stainless steel graspers, scissors, and clamps follow standardized steam sterilization protocols with documented lifecycle limits.
- Electrosurgical Devices:Cautery pencils and electrodes present thermal degradation challenges that constrain reprocessing economics in high-throughput settings.
Catheters retain volume leadership; endoscopic devices hold the steepest expansion curve.
Application:
Cost tier segmentation separates high-value device reuse from commoditized single-use alternatives, with reimbursement pressure dictating adoption intensity.
- Cardiology:Electrophysiology catheter programs generate substantial per-procedure savings through validated functional restoration. US hospital procurement departments expand reprocessed device catalogs as FDA streamlines market entry. The category commands the largest revenue pool among applications due to high procedural volume and established protocols.
- Gastroenterology:Colonoscope and gastroscope refurbishment advances through ultrasonic cleaning combined with automated inspection. German healthcare facilities adopt these programs at scale under centralized facility networks. The segment is climbing the fastest as flexible scope techniques achieve broader regulatory acceptance.
- Orthopedics:Surgical power tool reprocessing achieves expanding FDA regulatory acceptance, creating new volume beyond established categories.
- Urology:Cystoscope and ureteroscope reuse follows established endoscopic protocols with specialized attention to optical component integrity.
Cardiology anchors current procurement; gastroenterology is gaining share fastest.
Delivery Mode:
Customer type segmentation distinguishes centralized validation infrastructure from distributed point-of-use processing, with compliance burden driving consolidation.
- Hospitals:Multi-hospital systems negotiate enterprise-wide reprocessing agreements with centralized validation providers. US integrated delivery networks increasingly bundle reprocessed device procurement with sterilization service contracts. These facilities capture economies of scale through regional hub-and-spoke cleaning infrastructure.
- Specialized Centers:Ambulatory surgery centers and cardiac catheterization labs concentrate demand for specific device categories with rapid turnaround requirements. German outpatient facilities feed into centralized cleaning networks under national cost-containment frameworks. The segment expands most quickly as procedural volume shifts from inpatient settings.
- Clinics:Smaller physician practices face capital equipment barriers that limit in-house reprocessing adoption.
- Home Healthcare:Regulatory constraints and sterility assurance requirements substantially limit reprocessing applicability in non-clinical environments.
Hospitals dominate procurement volume; specialized centers show the steepest growth trajectory.
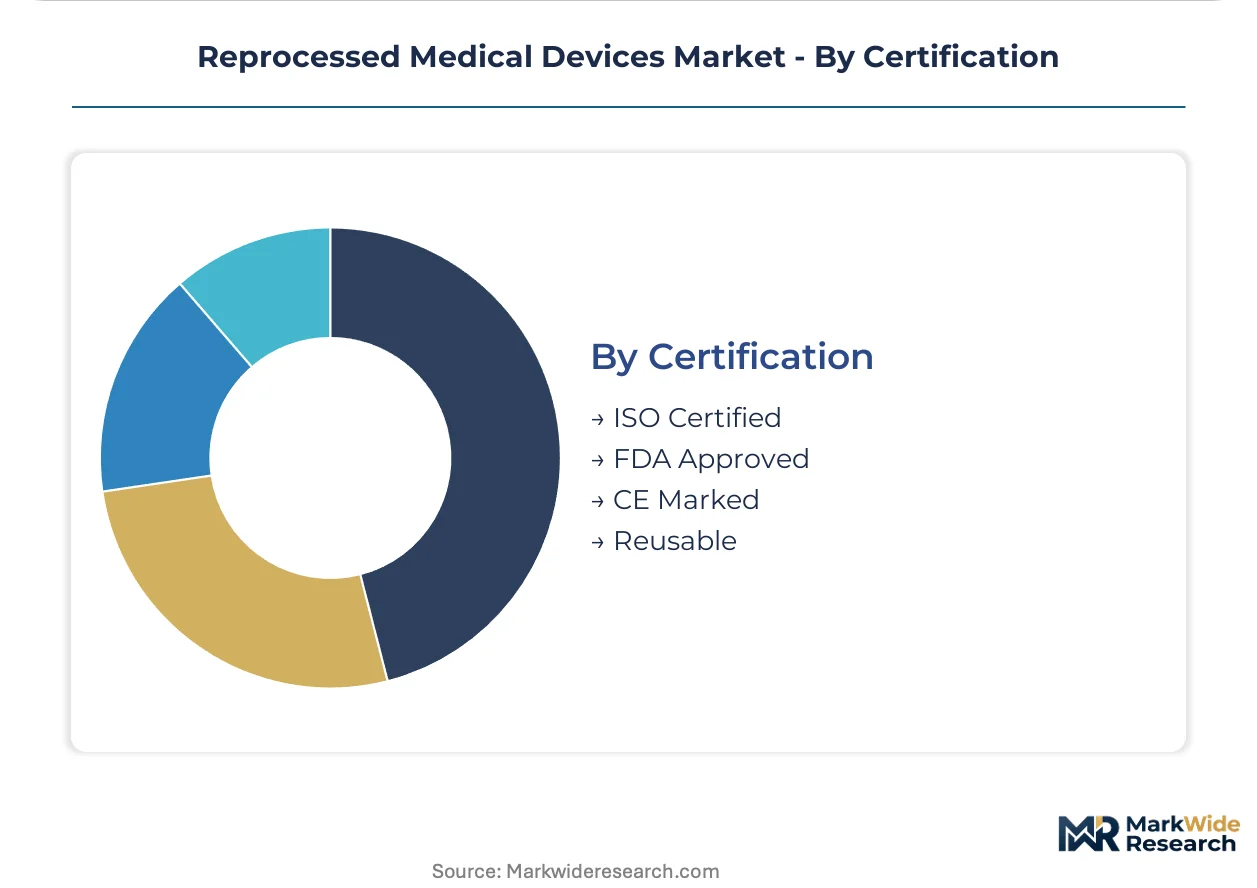
Certification:
Geography-linked regulatory frameworks create distinct market access tiers, with harmonization efforts reshaping competitive boundaries.
- FDA Approved:Substantial equivalence demonstrations through 510(k) premarket notification govern US commercialization. The framework accelerates timelines for third-party reprocessors entering the market. FDA guidance on cleaning validation endpoints shapes compliance investment levels.
- CE Marked:EU Medical Device Regulation imposes stricter clinical evidence and quality system requirements through notified body oversight. German reprocessors leverage CE marking for European market access under elevated documentation standards. The certification faces extended timelines that consolidate market position among established quality management systems.
- ISO Certified:ISO 17665 steam sterilization and ISO 11137 radiation dosimetry protocols provide foundational quality benchmarks across jurisdictions.
- Reusable:Original manufacturer-designated multi-use devices follow distinct regulatory pathways from single-use device reprocessing.
FDA Approved retains volume leadership; CE Marked holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in Germany demonstrate the highest price elasticity for reprocessed catheters and endoscopes, while US integrated delivery networks balance cost savings against FDA compliance investment thresholds. Cost-containment mandates in European national health systems accelerate adoption faster than discretionary purchasing in private-dominated markets.
United States
Multi-hospital systems in Texas and Florida expand reprocessed device catalogs through enterprise-wide sterilization service contracts. The FDA's 510(k) substantial equivalence framework accelerates commercialization timelines for third-party reprocessors entering the market. Greater Boston anchors electrophysiology catheter reuse programs at academic medical centers with established quality management infrastructure.
Germany
National hospital cost-containment mandates force healthcare facilities to adopt catheter and endoscopic device reprocessing at scale. The CE marking framework under EU Medical Device Regulation imposes stricter clinical evidence requirements through notified body oversight. North Rhine-Westphalia concentrates centralized cleaning and validation facilities serving multi-hospital networks.
United Kingdom
NHS procurement frameworks prioritize per-procedure supply cost reduction through validated reprocessing programs. The Medicines and Healthcare products Regulatory Agency enforces post-Brexit device regulations that align with retained EU MDR standards. London and the Southeast concentrate specialized endoscope refurbishment operations for national distribution.
France
Hospital cost pressure from national health insurance funds drives adoption of reprocessed cardiology and gastroenterology devices. ANSM oversight of single-use device reprocessing requires substantial equivalence demonstrations for market authorization. The Île-de-France region hosts centralized sterilization facilities serving Parisian academic hospital networks.
Japan
PMDA regulatory acceptance of reprocessed electrophysiology catheters lags Western markets, constraining near-term volume expansion. METI industrial policy supports domestic sterilization technology development for future market entry. The Kanto region around Tokyo concentrates pilot reprocessing programs at designated advanced medical centers.
Reprocessed Medical Devices Market Vendor Landscape
Capability concentration sits with original equipment manufacturers possessing in-house sterilization divisions; scale advantage sits with third-party reprocessors operating centralized validation networks. The market structures around two dominant tiers: integrated medtech conglomerates capturing recurring revenue streams, and specialized reprocessors achieving regulatory compliance at lower capital intensity. Strategic archetypes include backward-integrated device manufacturers, standalone sterilization service providers, and hospital-affiliated captive reprocessors. Competitive moves center on M&A to acquire FDA-cleared device portfolios and capacity expansion of regional hub-and-spoke cleaning infrastructure.
Among US-based medtech conglomerates, Stryker and Johnson & Johnson MedTech exemplify the backward-integrated archetype, leveraging in-house reprocessing divisions to capture recurring revenue from hospital customers. Vanguard AG represents the European standalone specialist, occupying a position within Germany's centralized facility network under national cost-containment frameworks. Medline Industries anchors the distributor-service hybrid tier, sitting within procurement consolidation plays that bundle reprocessed device sourcing with sterilization contracts.
| Leading Market Players |
|---|
| Stryker |
| Johnson & Johnson MedTech |
| Medline Industries |
| Arjo |
| Cardinal Health |
| Innovative Health |
| NEScientific |
| SureTek Medical |
| Vanguard AG |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on German centralized validation facilities determines both pricing tier spreads and supply chain shape. Hospital procurement departments face compressed margins when regional hub capacity saturates, forcing price differentiation between FDA-cleared and CE-marked device tiers while reshaping distributor relationships.
Pricing Analysis
Aftermarket sterilization service contracts drive lifetime value capture for reprocessors serving US multi-hospital systems. Three-tier pricing structure across premium, standard, and economy levels separates original manufacturer reprocessing from third-party validation and hospital-affiliated captive operations. Cost compression in standard-tier catheter reprocessing is intensifying because polymer input volatility squeezes margin structures. Ambulatory surgery centers exhibit highest price sensitivity due to capital equipment barriers, while academic medical centers prioritize certification grade over unit cost.
Supply Chain Analysis
Extended payment terms from hospital GPOs strain working capital for standalone reprocessors operating centralized facilities. Stainless steel instrument sourcing draws from Germany, polymer catheter components from the United States, and sterilization equipment from Japan. Single-source vulnerability concentrates in CE-marked device validation where notified body capacity constrains throughput. Distribution runs through regional hub-and-spoke networks serving integrated delivery networks rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive positioning. FDA 510(k) clearance pathways and CE marking requirements impose switching costs that protect incumbent reprocessors from rapid displacement.
For Market Incumbents: Build regulatory certification moats by accelerating CE marking investments ahead of EU MDR enforcement timelines. Acquire specialized endoscope refurbishment capabilities to consolidate position in the fastest-expanding product category. Capacity addition in North Rhine-Westphalia captures German hospital volume concentration under national cost-containment mandates.
For New Entrants and Emerging Players: Pursue orthopedic power tool reprocessing as the most penetrable segment with expanding FDA regulatory acceptance. Target US ambulatory surgery centers with rapid-turnaround service models that bypass incumbent hospital system lock-in. Partner with regional sterilization facilities to minimize capital intensity while achieving validation compliance.
For Investors and Strategic Acquirers: FDA guidance harmonization on cleaning validation endpoints reshapes the acquisition landscape toward quality-system-ready targets. Five-to-ten-year viability favors reprocessors with established notified body relationships over technology-only entrants. Acquire firms with ISO 17665 and ISO 11137 certification infrastructure. Watch electrophysiology catheter reuse program expansion rates as the inflection signal for cardiology segment maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | Notified body pre-submission meetings compress EU MDR approval timelines for catheter reprocessors. |
| Hospital System Partnership | Enterprise-wide sterilization contracts displace traditional distributor relationships in Texas and Florida IDNs. |
| Automated Inspection Deployment | Ultrasonic cleaning combined with machine vision reduces bioburden detection error rates in German facilities. |
| Orthopedic Power Tool FDA Submission | 510(k) clearance expansion beyond cardiology unlocks procedural volume in high-margin surgical segments. |
| Centralized Validation Facility Network | Hub-and-spoke infrastructure captures economies of scale while reducing per-facility compliance burden. |
Methodological Framework
A spread of perspectives from hospital procurement officers, biomedical engineers, GPO contracts managers, and sterilization technicians converged on the working assumptions. Primary interviews with reprocessing facility directors and regulatory affairs specialists combined with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up device volume estimates and top-down market sizing triangulated on segment-level figures.
Demand-supply balance across the analysis window anchored the quantitative framework. Segmentation dimensions modeled include product type, application specialty, delivery mode, and certification jurisdiction. CAGRs derived from logistic growth curve fitting to historical adoption patterns. Key inputs incorporated hospital cost-containment mandate intensity by country and FDA guidance evolution on cleaning validation endpoints.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by original equipment manufacturers or regulatory enforcement shifts by FDA would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
3D Printed Prosthetics Market
Medical Devices
Sleep Apnea Devices Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
Solar Surgical Light Market
Medical Devices
Cervical Fusion Market
Medical Devices
Tinnitus Maskers Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
Toe Fixation System Market
Medical Devices
Global Micro Injection Molding Medical Devices Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
China Respiratory Devices Market
Medical Devices
Esophagoscopes and Gastroscopes Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Devices Market
Medical Devices
Wearable Medical Device Connectivity and Cybersecurity Test Systems Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market