
 Heart Blocks Treatment Market | 2026-2036
Heart Blocks Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Blocks Treatment Market Analysis
Hospital end-user demand is pivoting toward ambulatory surgical centers as payers push same-day pacemaker implantation protocols. Medtronic leverages its integrated cath-lab ecosystem to sustain dominance in dual-chamber device placements. Abbott competes through leadless pacemaker miniaturization that reduces infection risk profiles. Biotronik anchors European procurement networks with MRI-conditional portfolio breadth.
Heart blocks treatment encompasses pharmacologic intervention, temporary and permanent cardiac pacing, and catheter-based ablation for conduction system restoration. Pacemakers deliver electrical impulses at programmable rates between 40 and 120 beats per minute to compensate for atrioventricular nodal failure. The pacemaker segment leads value generation due to battery longevity improvements and remote monitoring integration, while telemedicine delivery mode captures the fastest growth trajectory as remote device interrogation replaces in-person clinic visits. Radiofrequency ablation technology occupies mature margin pools in atrioventricular nodal reentrant tachycardia, though cryoablation differentiates through reduced collateral thermal damage in pediatric and septal applications.
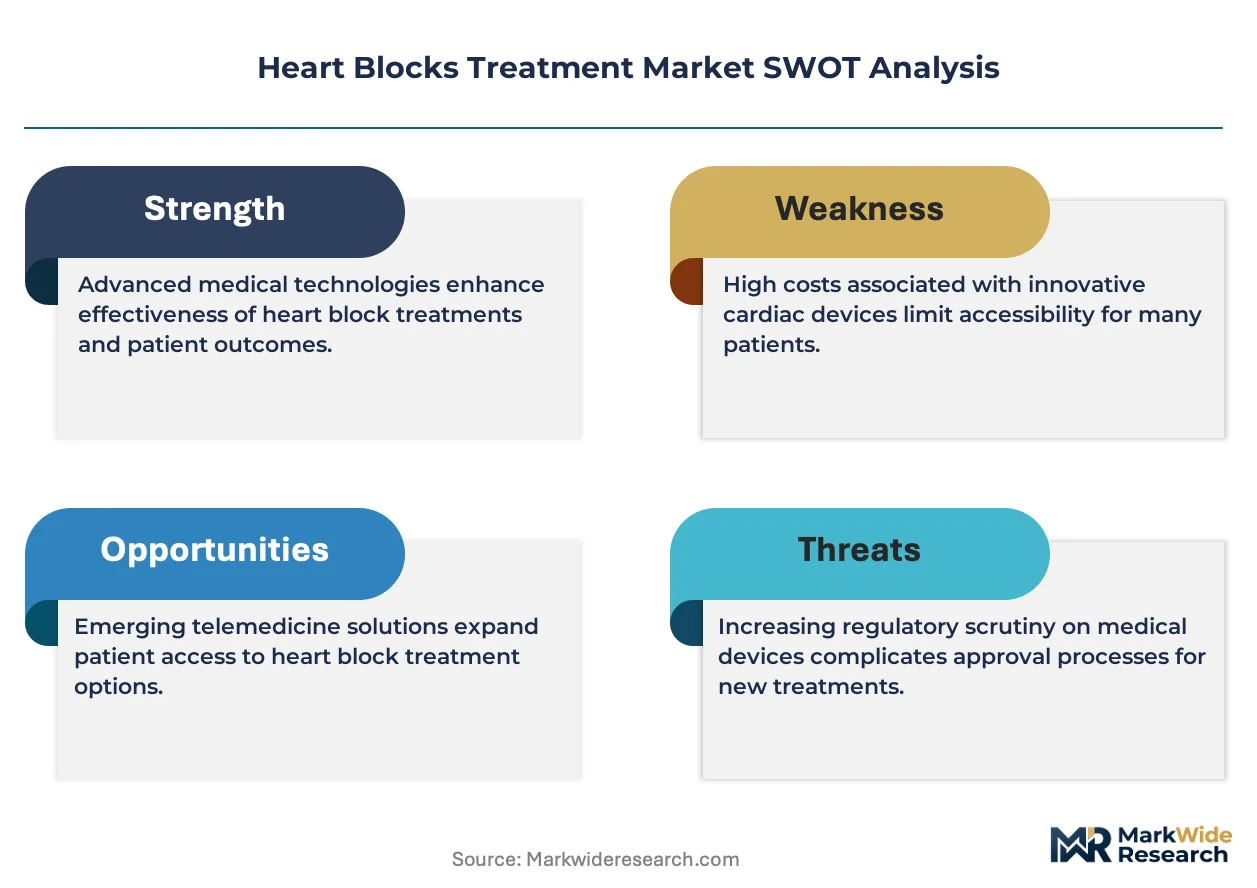
FDA premarket approval and EU MDR conformity assessment shape device commercialization timelines and clinical evidence burdens for manufacturers. Japan's PMDA enforces stringent QMS inspections that filter non-compliant entrants from the third-largest cardiac rhythm device market. Stakeholders must monitor reimbursement parity between leadless and transvenous systems as coding decisions will determine capital allocation toward next-generation conduction therapy platforms.
Market Dynamics
Hospital systems are consolidating electrophysiology service lines to capture same-day pacemaker reimbursement codes, compressing device procurement cycles and forcing manufacturers to bundle remote monitoring subscriptions with hardware placements.
Growth Catalysts
- Aging demographics:Japan, Germany, and the United States face expanding atrioventricular block caseloads as populations over 75 require permanent pacing interventions at accelerating rates.
- EU MDR framework:Stricter clinical evidence requirements for cardiac rhythm management devices filter out marginal competitors and solidify positions of firms with robust quality management systems.
- Leadless miniaturization:Transcatheter delivery systems eliminate transvenous lead complications, reducing infection risk profiles and expanding candidacy to anticoagulated patients previously excluded from conventional implants.
Market Restraints
- Platinum-iridium electrode costs:Precious metal price volatility in cathode materials squeezes gross margins on dual-chamber generator assemblies.
- Taiwan semiconductor concentration:Discrete component sourcing for pulse generators faces single-point vulnerability from foundry capacity constraints.
- FDA premarket approval timelines:Extended review cycles for novel conduction system pacing algorithms delay commercialization by 18-24 months versus legacy device clearances.
Strategic Opportunities
- India tertiary expansion:Corporate hospital chains in Mumbai, Delhi, and Bangalore are installing electrophysiology labs to capture outbound medical tourism from Bangladesh and Nepal.
- Telemedicine integration:Remote device interrogation platforms allow ambulatory surgical centers to manage post-implant follow-up without specialist clinic infrastructure.
- Japanese PMDA QMS harmonization:Firms achieving concurrent FDA-PMDA inspection readiness gain accelerated access to the third-largest cardiac rhythm device market.
Industry Challenges
- Electrophysiologist training pipelines:Fellowship positions lag procedural volume growth, creating procedural backlogs in community hospital settings.
- Legacy EMR integration:Device data streams require middleware development to populate electronic health records, extending implementation timelines for integrated monitoring contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Blocks Treatment Market |
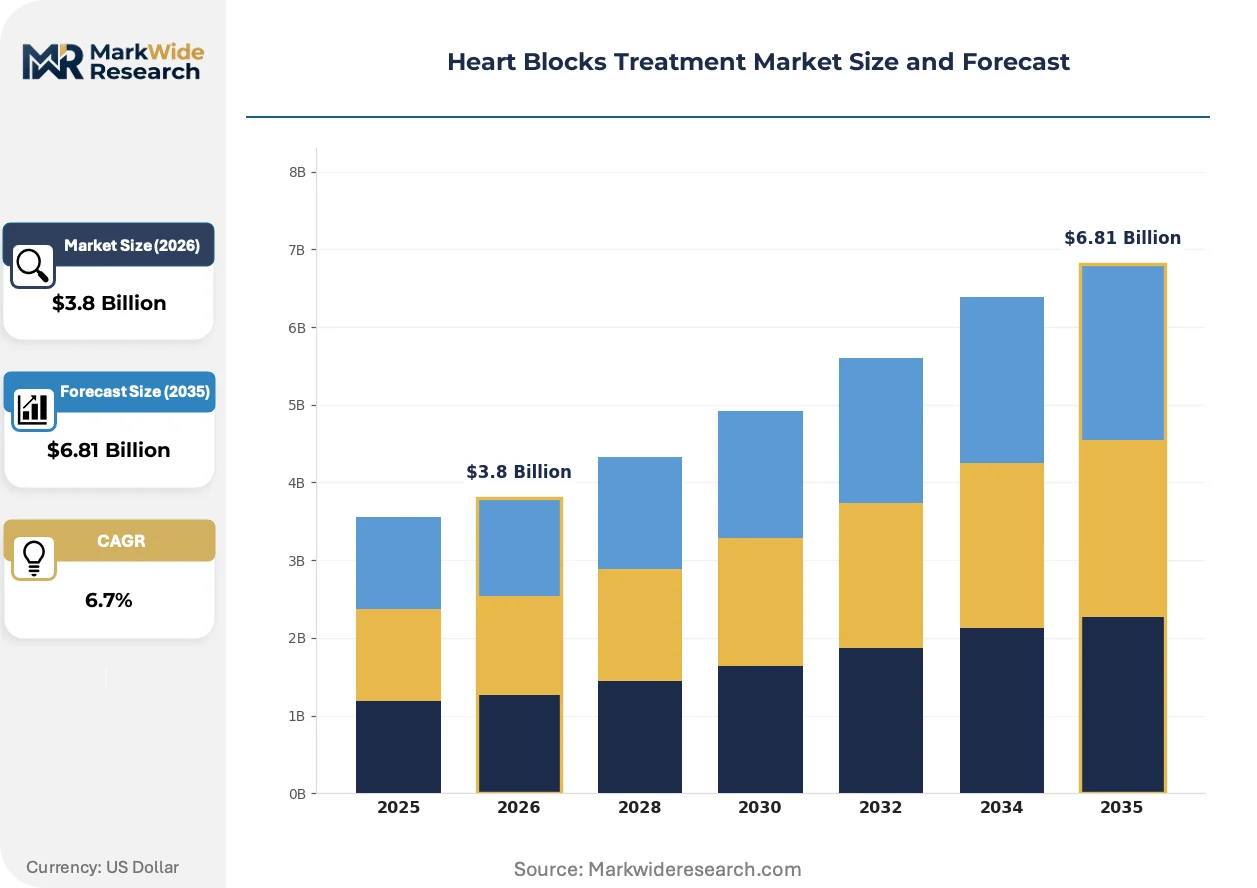
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pacemakers, Catheters, Stents, Implantable Cardioverter Defibrillators Delivery Mode: Inpatient, Outpatient, Home Care, Telemedicine End User: Cardiology Clinics, Hospitals, Ambulatory Surgical Centers, Research Institutions Technology: Radiofrequency Ablation, Cryoablation, Deep Brain Stimulation, High-Intensity Focused Ultrasound |
| Companies Covered | Medtronic, Abbott, Boston Scientific Corporation, Biotronik, MicroPort Scientific Corporation, Koninklijke Philips N.V., LivaNova PLC, Lepu Medical Technology, St. Jude Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Blocks Treatment Market Emerging Trajectories
Conduction system pacing is displacing traditional right ventricular apical leads as electrophysiologists prioritize physiological activation patterns over implant simplicity.
His-bundle and left bundle branch area pacing is unifying electrical resynchronization with bradycardia support in single-device platforms. Academic medical centers in Boston and Rotterdam are adopting these techniques for heart failure patients with atrioventricular block, collapsing the historical separation between pacemaker and cardiac resynchronization therapy markets. This convergence is unifying procurement decisions around multi-function generators rather than discrete device categories.
EU MDR conformity assessment timelines have extended by 12-18 months for Class III active implantable devices, forcing manufacturers to front-load clinical evidence generation. Notified body capacity constraints in Germany and the Netherlands are creating queue bottlenecks that favor firms with dedicated regulatory affairs teams. Smaller device developers are responding by partnering with established quality management system holders to access CE marking pathways.
Ambulatory surgical centers are capturing pacemaker implant volume from traditional hospital outpatient departments as Medicare and commercial payers expand same-day procedure coverage. Cardiology groups in Florida, Texas, and Arizona are consolidating into multi-site platforms that centralize device inventory and remote monitoring infrastructure. This channel migration is most visible in Medicare Advantage populations where capitated contracts reward site-of-care optimization.
Heart Blocks Treatment Market Segmentation
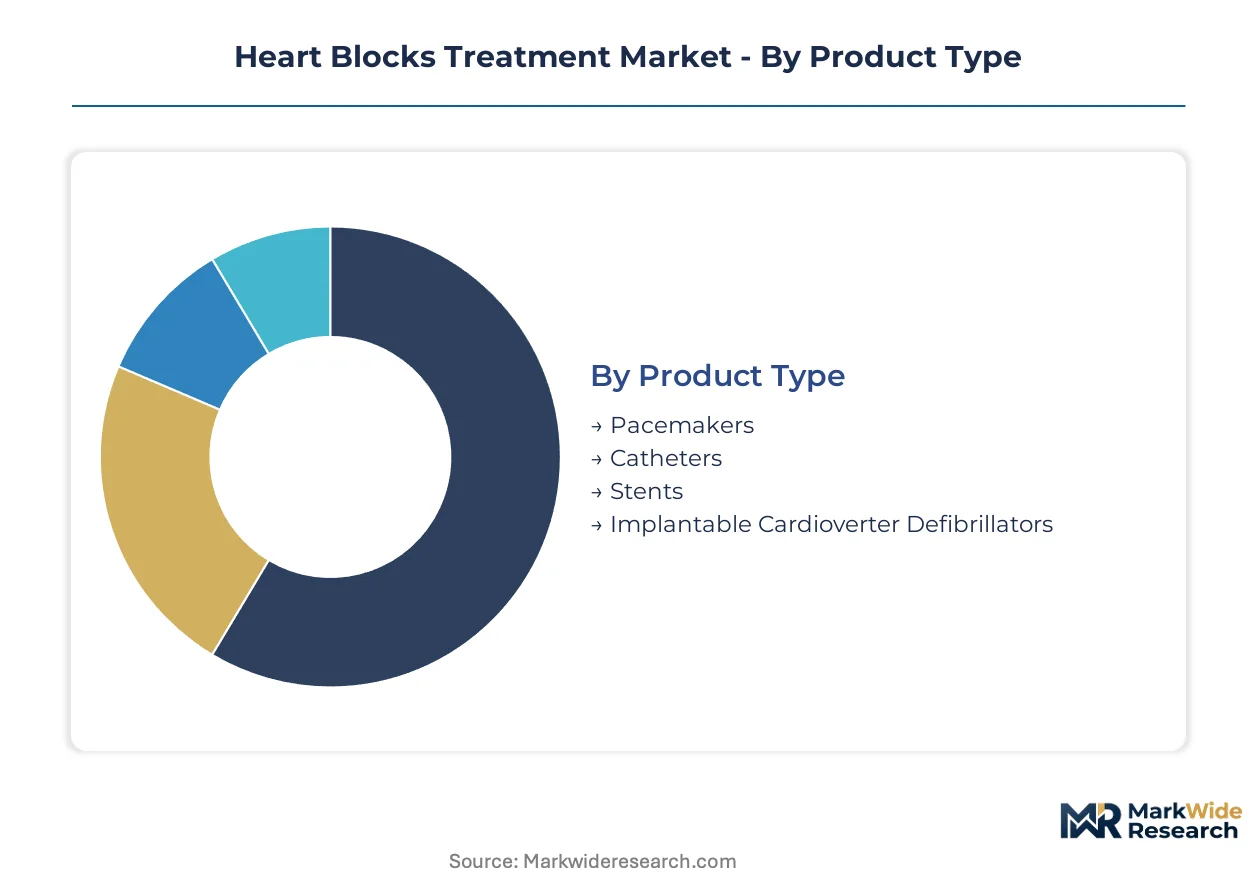
Segmentation in heart blocks treatment reveals how clinical workflows, reimbursement structures, and technological capabilities partition demand across distinct procurement channels. Each category maps to specific stakeholder priorities — from electrophysiologists selecting ablation platforms to administrators optimizing site-of-care economics.
Product Type:
Customization intensity spans from programmable generator firmware to standardized catheter geometries across this category.
- Pacemakers:Dual-chamber and leadless generators deliver electrical impulses between 40-120 beats per minute through transvenous or transcatheter delivery. Demand concentrates in Medicare Advantage populations where ambulatory surgical centers capture same-day implant volume through bundled reimbursement codes.
- Catheters:Electrophysiology mapping and ablation catheters enable conduction system diagnosis and targeted energy delivery. Hospital systems in Florida, Texas, and Arizona consolidate multi-site inventory to reduce per-procedure procurement cycles.
- Stents:Coronary stents address concomitant ischemic disease in AV block patients undergoing catheterization.
- Implantable Cardioverter Defibrillators:Combined bradycardia-tachycardia devices serve heart failure patients with conduction disease.
Most installed capacity flows through Pacemakers. Expansion is steepest in Catheters as conduction system pacing techniques proliferate.
Delivery Mode:
Cost tier stratification separates capital-intensive inpatient infrastructure from lean outpatient workflows in this category.
- Inpatient:Traditional hospital admissions for complex multi-lead implants and concomitant cardiac surgery. Academic medical centers in Boston and Rotterdam anchor volume for His-bundle pacing requiring specialized electrophysiology support.
- Outpatient:Hospital outpatient departments and freestanding surgical centers performing same-day generator changes and leadless implants. Medicare site-of-care differentials drive channel migration toward lower-cost settings.
- Home Care:Post-discharge wound management and device education delivered through visiting nurse services.
- Telemedicine:Remote device interrogation and arrhythmia monitoring via cellular-connected pacemakers. Remote monitoring platforms allow ambulatory surgical centers to manage follow-up without specialist clinic infrastructure, capturing the steepest expansion trajectory as in-person visits decline.
Most installed capacity flows through Inpatient settings. Telemedicine climbs fastest as remote interrogation replaces clinic visits.
End User:
Customer type determines procurement sophistication — from integrated delivery networks to independent physician practices.
- Cardiology Clinics:Office-based electrophysiology practices performing diagnostic workup and device follow-up. Independent groups in Germany consolidate into platform networks to negotiate MRI-conditional device contracts with Biotronik.
- Hospitals:Tertiary centers with full electrophysiology service lines including hybrid operating rooms. Japan's PMDA QMS inspections filter non-compliant entrants, solidifying positions of manufacturers with robust quality systems.
- Ambulatory Surgical Centers:Same-day procedure facilities capturing pacemaker volume from hospital outpatient departments. Cardiology groups in Florida and Arizona centralize inventory and remote monitoring infrastructure across multi-site platforms.
- Research Institutions:Academic medical centers conducting conduction system pacing trials and device development.
Most installed capacity flows through Hospitals. Ambulatory Surgical Centers gain share fastest as payers expand same-day coverage.
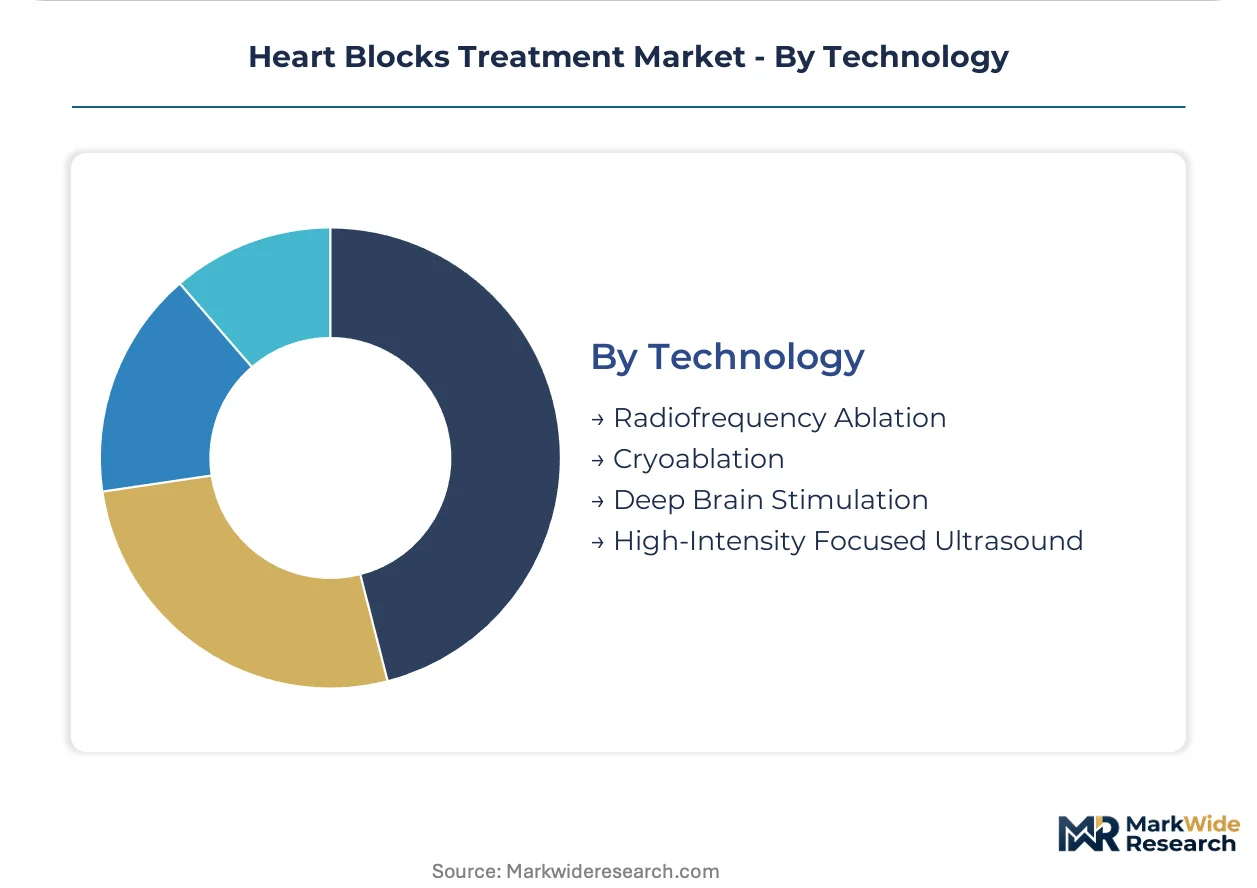
Technology:
Maturity curves separate established thermal ablation from emerging neuromodulation approaches in this category.
- Radiofrequency Ablation:Resistive heating through catheter electrodes for AV nodal reentrant tachycardia. Mature margin pools in atrioventricular nodal applications face pressure from physiological pacing alternatives.
- Cryoablation:Nitrous oxide-mediated freezing for septal and pediatric applications where thermal collateral damage risks are elevated. Academic centers prioritize cryoenergy for AV nodal slow pathway modification in younger patients.
- Deep Brain Stimulation:Neuromodulation technology with limited current application in cardiac conduction disorders.
- High-Intensity Focused Ultrasound:Non-invasive thermal ablation under investigation for cardiac tissue modulation.
Most installed capacity flows through Radiofrequency Ablation. Cryoablation expands most quickly in pediatric and septal niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Minneapolis medical device corridor anchors global cardiac rhythm management manufacturing, with FDA premarket approval pathways shaping commercialization timelines for pacemaker and leadless systems across major demand centers.
United States
Medicare Advantage expansion and ambulatory surgical center site-of-care differentials accelerate same-day pacemaker volume migration. FDA 510(k) and PMA pathways enforce 18-24 month review cycles for novel conduction system pacing algorithms. Cardiology groups in Florida, Texas, and Arizona consolidate multi-site platforms to centralize device inventory and remote monitoring infrastructure.
Germany
Aging demographics over 75 drive accelerating atrioventricular block caseloads requiring permanent pacing interventions. EU MDR conformity assessment extends timelines 12-18 months for Class III active implantable devices, filtering marginal competitors. Notified body capacity constraints in Berlin and Munich create queue bottlenecks favoring firms with dedicated regulatory affairs teams.
Japan
PMDA QMS inspections enforce stringent quality management standards that filter non-compliant entrants from the third-largest cardiac rhythm device market. METI industrial policy supports domestic electrophysiology lab expansion in tertiary centers. Tokyo and Osaka academic medical centers anchor His-bundle pacing adoption for heart failure patients with conduction disease.
India
Corporate hospital chains in Mumbai, Delhi, and Bangalore install electrophysiology labs to capture outbound medical tourism from Bangladesh and Nepal. CDSCO medical device regulations harmonize with international standards for cardiac implantable electronic devices. Karnataka and Maharashtra tertiary expansion concentrates procurement decisions among integrated delivery networks.
United Kingdom
NHS England procurement frameworks prioritize MRI-conditional device portfolios for electrophysiology service line consolidation. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR evidence requirements for active implantables. London and Manchester academic centers drive conduction system pacing technique adoption, collapsing historical separations between pacemaker and resynchronization therapy markets.
Heart Blocks Treatment Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers bundle remote monitoring subscriptions with hardware placements to capture ambulatory surgical center volume. The vendor base concentrates around integrated cath-lab ecosystem holders, quality management system specialists, and miniaturization-focused entrants. Three archetypes define positioning: full-service rhythm management platforms, leadless technology specialists, and regional procurement network anchors. M&A activity and strategic technology licensing represent the primary competitive vectors as firms seek conduction system pacing capabilities and telemedicine integration assets.
Among integrated rhythm management platforms, Medtronic, Abbott, and Boston Scientific Corporation exemplify distinct strategic postures. Medtronic occupies a position representing full-service ecosystem integration across dual-chamber and leadless modalities. Abbott exemplifies the miniaturization specialist archetype through transcatheter delivery system development. Boston Scientific Corporation anchors the interventional cardiology convergence position, bridging electrophysiology and structural heart capabilities. These three entities collectively represent the competitive tension between physiological pacing advancement, infection risk reduction, and procedural workflow optimization that defines current capital allocation decisions.
| Leading Market Players |
|---|
| Medtronic |
| Abbott |
| Boston Scientific Corporation |
| Biotronik |
| MicroPort Scientific Corporation |
| Koninklijke Philips N.V. |
| LivaNova PLC |
| Lepu Medical Technology |
| St. Jude Medical |
| Others |
Supply Flow & Price Mechanics
Platinum-iridium electrode spot indices cascade through cardiac rhythm management supply chains, compressing margins on dual-chamber generator assemblies while pushing manufacturers toward leadless architectures that reduce precious metal content. This input-cost volatility stratifies pricing tiers between conventional transvenous systems and next-generation miniaturized platforms, with procurement committees in Medicare Advantage networks capturing site-of-care arbitrage.
Pricing Analysis
Input-cost pass-through from precious metal electrodes and semiconductor components stratifies pricing across premium MRI-conditional, standard dual-chamber, and economy single-chamber generator tiers. Price differentiation hinges on FDA PMA certification grade and remote monitoring subscription bundling. Pricing pressure stems from ambulatory surgical center procurement consolidation demanding hardware-plus-service bundles. Medicare Advantage payers exhibit highest price sensitivity; academic medical centers purchasing His-bundle pacing systems show lowest sensitivity due to clinical outcome prioritization.
Supply Chain Analysis
Platinum-iridium electrode supply rests on South African mining output and German refining capacity, with pulse generator semiconductor sourcing concentrated in Taiwan and South Korea. Discrete component dependencies include lithium-iodine battery cells, titanium device housings, and application-specific integrated circuits. Single-source vulnerability from Taiwan foundry concentration creates procurement risk for pulse generator manufacturers. Distribution runs through integrated delivery network central warehouses to hospital cath labs and ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heart blocks treatment functions as a geographic-arbitrage play where EU MDR compliance costs in Germany and the Netherlands create 12-18 month regulatory delays that Japanese PMDA-ready manufacturers can exploit for accelerated Asian market entry.
For Market Incumbents: Hedge platinum-iridium price exposure through long-term offtake agreements with South African refiners and accelerate leadless platform R&D to reduce precious metal dependence. Defend against Abbott's miniaturization threat by bundling remote monitoring subscriptions with generator placements. Prioritize vertical integration into titanium housing production to insulate margins from aerospace demand competition. For New Entrants and Emerging Players: Telemedicine-enabled remote monitoring platforms offer the lowest barrier entry point for device interrogation software licensing to ambulatory surgical centers. White-space targets include Bangladesh and Nepal medical tourism corridors served by Indian corporate hospital chains, plus pediatric cryoablation niches where thermal collateral damage concerns limit incumbent penetration. Pursue hospital system partnership models with inventory consignment rather than capital equipment sales. For Investors and Strategic Acquirers: Asymmetric upside sits with telemedicine integration specialists possessing FDA-cleared remote monitoring algorithms and cellular connectivity modules. Long-term viability favors platforms spanning diagnostic catheters through implantable generators rather than single-modality device developers. Watch FDA reimbursement coding decisions for leadless versus transvenous system parity as the inflection signal determining capital allocation toward next-generation conduction therapy.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | PMA submissions for His-bundle pacing algorithms face 18-24 month review cycles that filter marginal competitors. |
| CE Marking Conformity Assessment | EU MDR Class III device timelines extend 12-18 months, favoring firms with dedicated Berlin and Munich regulatory teams. |
| Hospital System Partnership | Integrated delivery networks in Florida and Arizona consolidate multi-site inventory and remote monitoring infrastructure. |
| Software Companion Development | Remote device interrogation platforms allow ambulatory surgical centers to manage post-implant follow-up without specialist clinics. |
| Reimbursement Strategy | Medicare site-of-care differentials drive channel migration toward lower-cost ambulatory surgical center settings. |
Methodological Framework
Direct dialogue with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded qualitative findings, validated against FDA 510(k) and PMA filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Secondary sources included SEC 10-K disclosures from public manufacturers and cardiac rhythm management society procedure registries. Bottom-up procedure volume estimates and top-down device shipment data underwent cross-triangulation.
Segment-level value outputs across product type, delivery mode, end user, and technology dimensions were generated through the analytical framework over the projection horizon. CAGRs were derived from installed base growth, replacement cycle compression, and procedure volume elasticity models. Industry-specific inputs incorporated electrophysiologist training pipeline constraints, EU notified body capacity bottlenecks, and Japan PMDA QMS inspection timelines.
The model assumes a particular technology adoption path; alternative pathways for leadless pacemaker miniaturization or conduction system pacing algorithm refinement would alter the outlook. Forecasts reflect documented assumptions regarding reimbursement parity, regulatory clearance timelines, and precious metal price stability. A small set of triggers—FDA coding decisions, Taiwan semiconductor capacity disruptions, and EU MDR notified body queue extensions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Global Statin Market
Cardiovascular
Restrictive Cardiomyopathy Treatment Market
Cardiovascular
Cardiovascular Disease Drugs Market
Cardiovascular
Global Deep Vein Thrombosis Market
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Coronary Artery Disease Therapeutics Market
Cardiovascular
Atrial Fibrillation Stroke Treatment Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market
Cardiovascular
Cardiopulmonary Disease Diagnostics and Treatment Market
Cardiovascular
Treatment-Resistant Hypertension Management Market
Cardiovascular
Global Cardiac Tamponade Market
Cardiovascular
Myocarditis Disease Market
Cardiovascular
Pericarditis Treatment Market
Cardiovascular
US Statin Market
Cardiovascular
Heart Health Products Market
Cardiovascular
Acute Coronary Syndrome (ACS) Market