
 Thin Film Photovoltaic and Batteries Market | 2026-2036
Thin Film Photovoltaic and Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Film Photovoltaic and Batteries Market Intelligence
Expertise in advanced materials science and deposition process engineering is reorganizing the value chain for energy generation and storage. First Solar leverages its manufacturing scale in Cadmium Telluride technology to command a significant market share. Meanwhile, Oxford PV differentiates through its research into high-efficiency perovskite tandem solar cells, and Cymbet Corporation specializes in solid-state micro-batteries for compact electronics.
Thin film photovoltaics and batteries involve depositing energy harvesting and storage layers in micro-scale thicknesses onto a substrate. This technology, utilizing methods like roll-to-roll processing, creates flexible and lightweight power solutions. Cadmium Telluride leads the PV segment, while Lithium-Ion dominates battery chemistries. Applications in Electric Vehicles and Grid-Scale Storage are driving innovation toward next-generation Solid-State technologies.
Material composition and end-of-life management are governed by the EU's RoHS and REACH directives, impacting global supply chains. In parallel, safety and performance are regulated by GB standards in China and are subject to review by the EPA in the United States. Stakeholders must navigate these divergent regulatory frameworks while balancing material sourcing against performance targets.
Market Dynamics
The convergence of advanced materials science and deposition process engineering is the central force reorganizing value chains. This shift enables integrated energy harvesting and storage solutions, moving beyond discrete component manufacturing.
Growth Catalysts
- EV Sector Demand:The rapid expansion of the electric vehicle market, particularly in Germany and China, creates sustained demand for lightweight, high-energy-density batteries and integrated solar solutions.
- Roll-to-Roll Processing:Innovations in roll-to-roll manufacturing enable high-volume production of flexible photovoltaic films and batteries, lowering costs for applications in consumer electronics and smart textiles.
- Supportive Policies:Government incentives, such as the EU Green Deal, promote renewable energy adoption and create a favorable investment climate for grid-scale battery storage projects.
Market Restraints
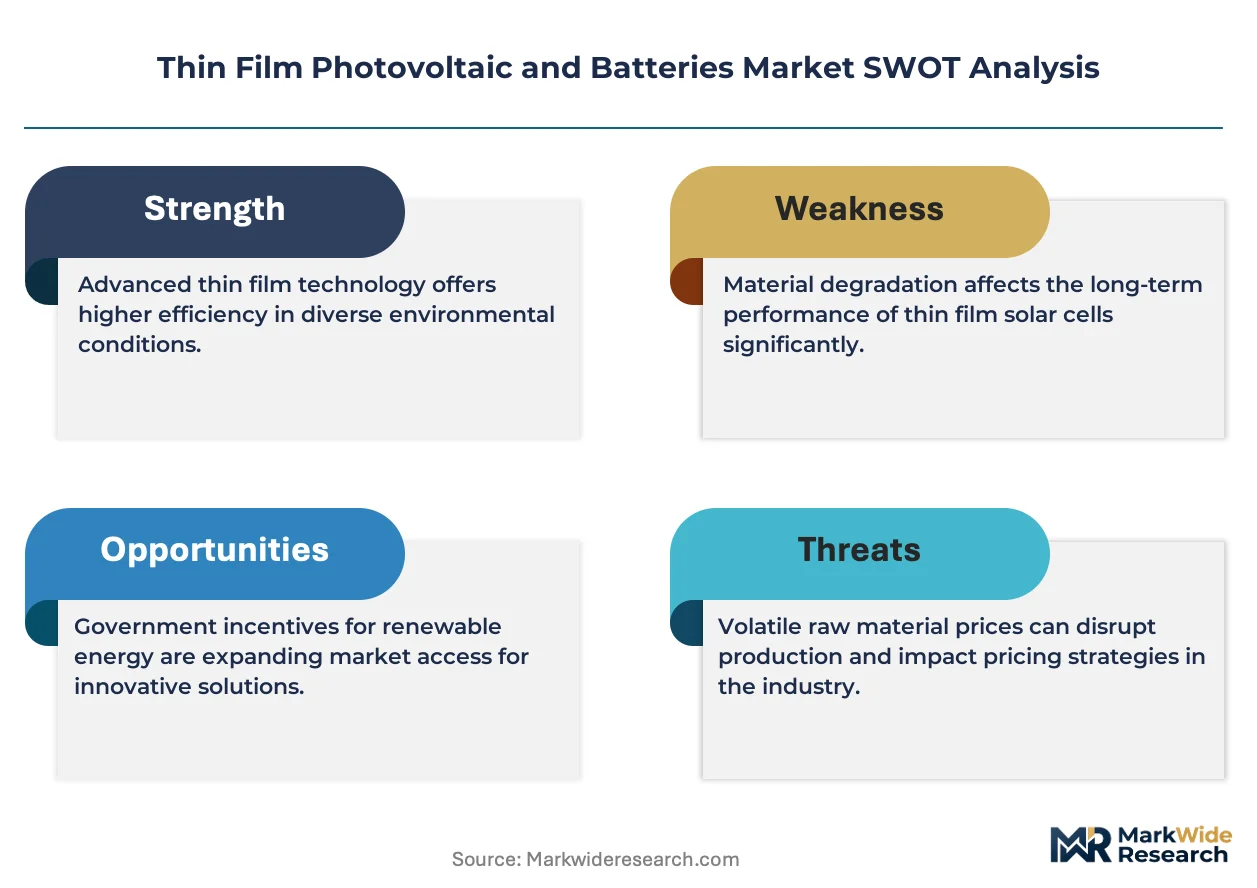
- Material Scarcity:The supply of critical raw materials, including tellurium for CdTe cells and high-purity lithium for batteries, is concentrated in a few geographies, creating price volatility and supply chain risks.
- Regulatory Compliance:Navigating divergent regulations, such as the EU's REACH directive and China's GB standards, increases compliance costs and can delay market entry for new material compositions.
- Performance Degradation:Certain thin-film chemistries exhibit faster degradation rates compared to conventional silicon PV or established battery technologies, posing a barrier for applications requiring long-term reliability.
Strategic Opportunities
- Building-Integrated PV:The development of transparent and flexible solar films opens opportunities in the architectural sector, turning building facades and windows into power-generating surfaces.
- Solid-State Technology:Maturation of solid-state battery technology presents an opportunity to displace lithium-ion in high-value applications like medical devices and electric vehicles, offering improved safety and energy density.
- Circular Economy Models:Creating closed-loop recycling processes for thin-film materials can unlock new revenue streams and address end-of-life management concerns, aligning with circular economy mandates.
Industry Challenges
- End-of-Life Recycling:The complex, layered composition of thin-film devices, particularly those containing hazardous materials like cadmium, makes efficient and cost-effective recycling a significant operational hurdle.
- Standardization Gaps:A lack of universally accepted standards for testing the performance and longevity of next-generation technologies like perovskite cells and solid-state batteries complicates direct comparisons for buyers.
- Capital-Intensive Scaling:Transitioning novel deposition processes from laboratory to mass production requires substantial capital investment in specialized manufacturing equipment, posing a barrier for smaller innovators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Film Photovoltaic and Batteries Market |
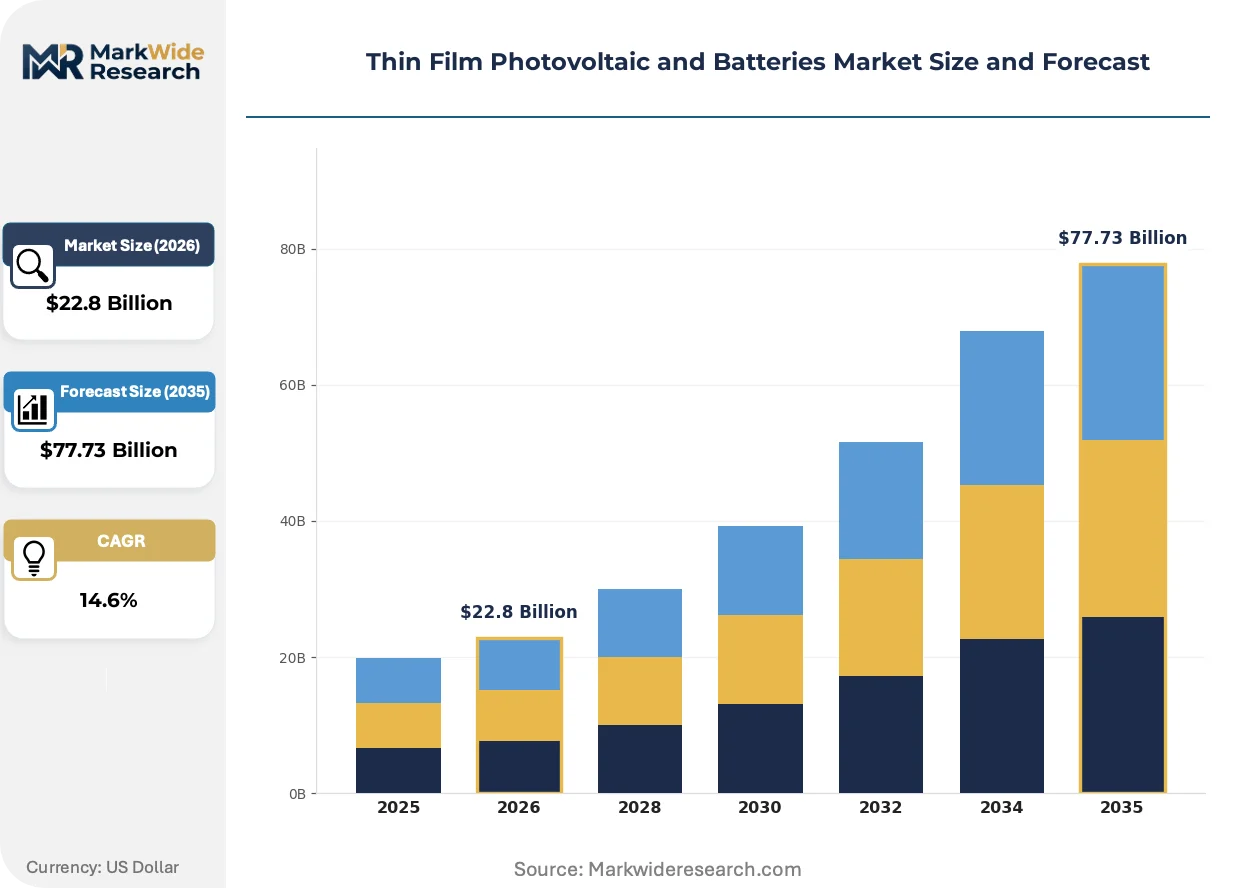
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $77.73 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cadmium Telluride, Copper Indium Gallium Selenide, Amorphous Silicon, Lithium-Ion, Solid-State, Nickel Metal Hydride Application: Residential Solar Systems, Grid-Scale Storage, Portable Electronics, Electric Vehicles, Telecommunications Power, Off-Grid Lighting Technology: Thin Film Deposition, Laser Scribing, Roll-to-Roll Processing, Solid Electrolyte, Thermal Management, Battery Management Systems End User: Utility Providers, Consumer Electronics Manufacturers, Transportation OEMs, Telecommunication Companies, Construction Firms, Energy Storage Integrators |
| Companies Covered | Cymbet Corporation, Blue Spark Technologies, First Solar, Heliatek, Oxford PV, Ascent Solar Technologies, Excellatron Solid State, Enfucell, Kaneka Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Film Photovoltaic and Batteries Market Strategic Shifts & Innovations
Material science breakthroughs are fundamentally altering device architecture and performance capabilities. These innovations are enabling new form factors and application-specific chemistries, pushing the market beyond monolithic technology platforms.
Perovskite materials provide a pathway to ultra-high efficiency solar cells through their tunable electronic properties. Research institutions and specialized firms are rapidly developing perovskite-on-silicon tandem configurations. This focus on high-performance niches is fragmenting the technology landscape away from a singular reliance on established CdTe or CIGS thin-film approaches.
The European Union's RoHS directive restricts the use of hazardous substances, directly impacting materials like cadmium in CdTe photovoltaics. This regulation compels manufacturers across the supply chain to invest in material containment, substitution research, and comprehensive compliance documentation. The cadmium-based PV segment is most affected, accelerating exploration into alternative thin-film chemistries.
A clear shift toward lifecycle value assessment is underway in the utility-scale energy storage sector. Buyers are moving beyond initial capital cost, prioritizing long-term performance contracts that include degradation warranties and guaranteed uptime. This behavior is most pronounced in German and US grid projects where long-term asset reliability is paramount.
Thin Film Photovoltaic and Batteries Market Segmentation
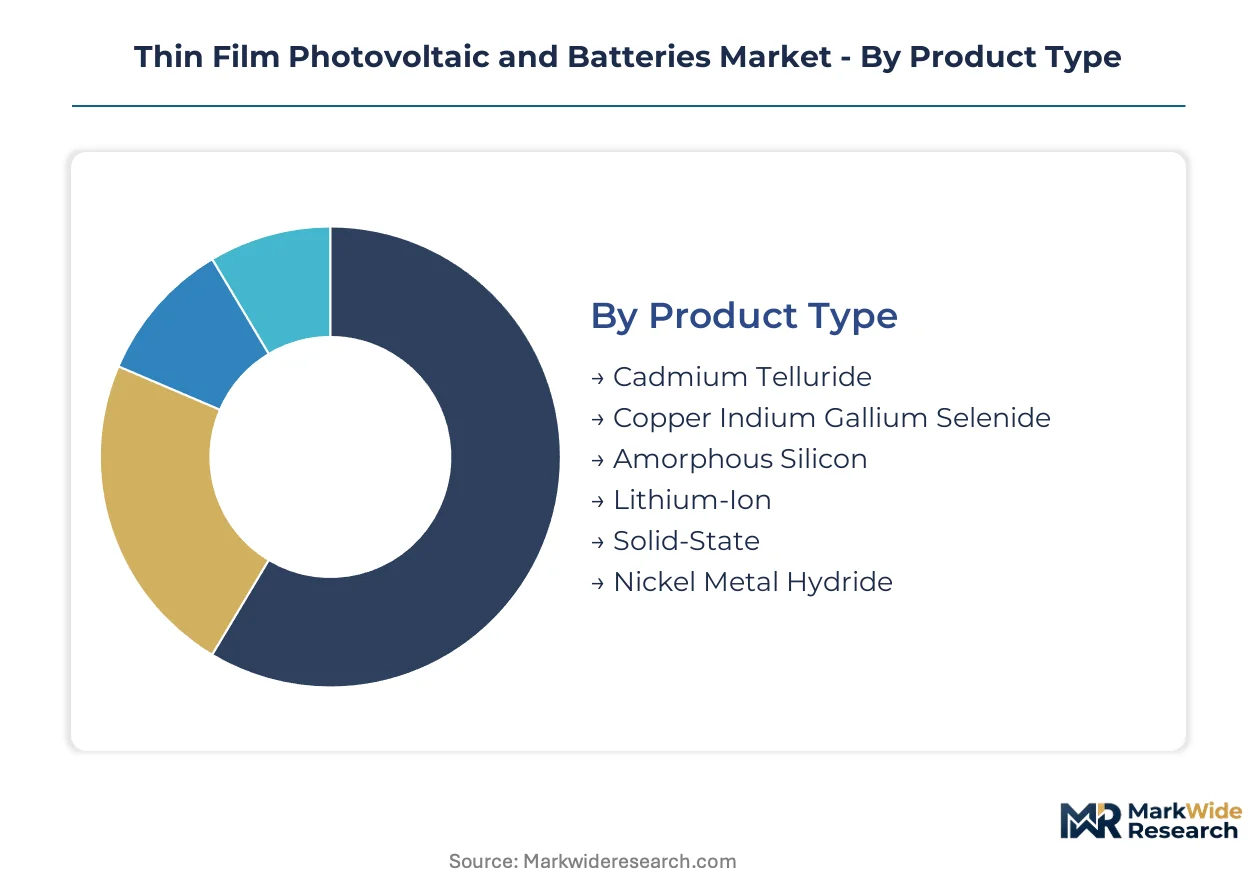
The Thin Film Photovoltaic and Batteries market is characterized by diverse technologies and applications, each requiring specialized material compositions and manufacturing processes. Understanding these distinct segments is crucial for stakeholders to align product development with specific end-user demands and regulatory landscapes.
Product Type:
Product type differentiation significantly influences the distribution channels, from direct sales to specialized integrators and original equipment manufacturers.
- Cadmium Telluride:This thin film technology utilizes a direct bandgap semiconductor for efficient solar energy conversion, offering a lower manufacturing cost profile. Demand concentrates in utility-scale projects and large commercial installations, particularly in the United States and China, driven by its established performance and cost-effectiveness.
- Solid-State:Solid-state batteries replace liquid electrolytes with solid materials, enhancing safety and energy density for compact power solutions. This technology sees demand concentrating in high-value applications such as medical devices and electric vehicles in Germany, where improved performance and safety are paramount.
- Copper Indium Gallium Selenide:CIGS technology offers high efficiency in flexible form factors, finding niches in specialized architectural and portable power applications.
- Amorphous Silicon:Amorphous silicon is suitable for low-power applications and flexible substrates, often integrated into consumer electronics and building materials.
- Lithium-Ion:Lithium-ion batteries provide high energy density and cycle life, dominating the portable electronics and electric vehicle battery segments.
- Nickel Metal Hydride:NiMH batteries offer a mature, reliable, and safer alternative for specific hybrid vehicle models and industrial backup power systems.
Cadmium Telluride dominates the installed PV base. Solid-State technology is where expansion concentrates.
Application:
Application segments dictate specific design requirements and performance envelopes for thin film solutions, influencing material selection and system integration.
- Electric Vehicles:Thin film batteries provide lightweight, high-energy-density power solutions essential for extending range and improving vehicle performance. Demand for these integrated solutions is high from transportation OEMs in China and Germany, driven by electric vehicle production targets.
- Grid-Scale Storage:Large-scale battery systems provide stability and reliability for renewable energy integration and peak shaving in national grids. Utility providers in the United States and Germany prioritize long-duration, high-cycle-life thin film battery solutions for grid modernization initiatives.
- Residential Solar Systems:These systems provide on-site power generation for homes, often utilizing flexible thin-film modules for aesthetic integration.
- Portable Electronics:Compact and lightweight thin-film batteries power devices like smartphones, wearables, and medical sensors, requiring high energy density.
- Telecommunications Power:Thin film solutions offer reliable backup power for remote cell towers and communication infrastructure, ensuring continuous operation.
- Off-Grid Lighting:Standalone lighting solutions in remote areas leverage small-scale thin film PV and batteries for sustainable, decentralized power.
Electric Vehicles represent the fastest-growing segment for thin film batteries. Portable Electronics demand consistent innovation for miniaturization.
Technology:
Technology maturity levels determine investment cycles and scaling challenges across the value chain, from research and development to mass production.
- Roll-to-Roll Processing:This manufacturing method enables continuous, high-volume production of flexible thin films, significantly lowering unit costs for PV and battery components. Innovations in this process are critical for scaling flexible electronics and smart textile applications.
- Solid Electrolyte:Solid electrolytes are fundamental to solid-state battery development, replacing liquid components to enhance safety, thermal stability, and energy density. Research into new solid electrolyte compositions is crucial for next-generation battery performance.
- Thin Film Deposition:Various techniques, including PVD and CVD, are used to precisely apply ultra-thin material layers onto substrates for both PV and battery construction.
- Laser Scribing:Laser scribing is a precision technique used to pattern thin film layers, enabling efficient cell interconnections and module design for solar panels.
- Thermal Management:Effective thermal management systems are vital for maintaining optimal operating temperatures and extending the lifespan of high-performance batteries.
- Battery Management Systems:BMS actively monitors and controls battery parameters, ensuring safety, maximizing performance, and prolonging the operational life of battery packs.
Roll-to-Roll Processing enables high-volume manufacturing. Solid Electrolyte development advances next-generation battery performance.
End User:
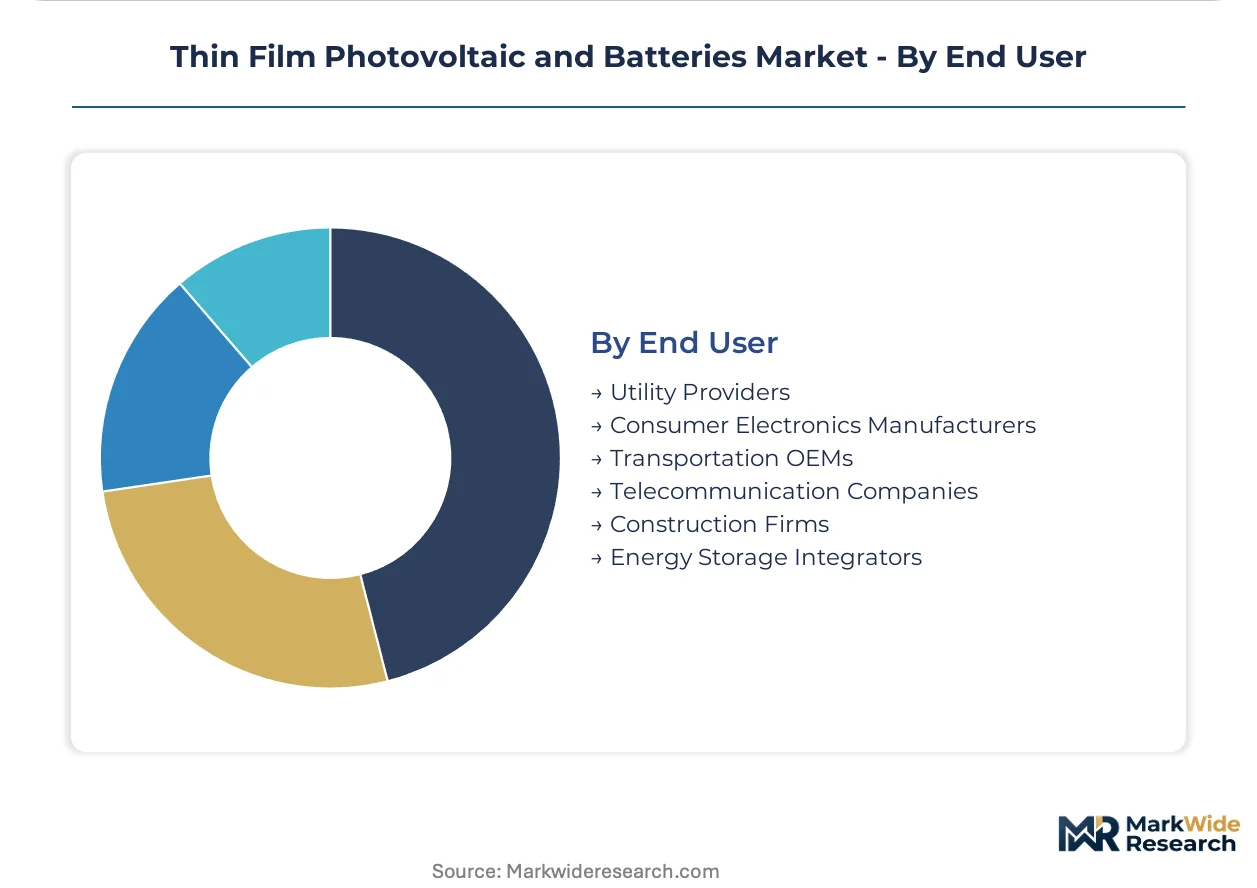
End user types shape procurement strategies and long-term service contract requirements for energy solutions, influencing product specifications and support models.
- Transportation OEMs:Automotive manufacturers integrate thin film batteries into electric vehicles, demanding high-density, lightweight, and safe power solutions. These OEMs prioritize long-term supply agreements and performance guarantees for vehicle integration projects in Germany and China.
- Utility Providers:These entities deploy large-scale thin film PV and battery systems for grid stabilization, renewable energy integration, and peak load management. Utility providers in the United States and Germany require solutions with long lifespans, high reliability, and robust regulatory compliance.
- Consumer Electronics Manufacturers:These companies integrate compact thin-film batteries into portable devices, requiring miniaturization and high energy density.
- Telecommunication Companies:Telecommunication firms use thin film power solutions for remote base stations and network infrastructure, emphasizing reliability and low maintenance.
- Construction Firms:Construction companies incorporate building-integrated photovoltaics (BIPV) into architectural designs, requiring aesthetic and durable solar film solutions.
- Energy Storage Integrators:These firms design and deploy customized energy storage systems for various applications, leveraging diverse thin film battery technologies.
Transportation OEMs demand high-energy-density solutions for vehicle integration. Utility Providers prioritize long-duration storage and grid stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal significantly influences the Thin Film Photovoltaic and Batteries market. This directive promotes renewable energy adoption and fosters investment in grid-scale battery storage projects. Global demand for these advanced energy solutions is concentrated across key industrial nations.
Germany
KBA standards drive electric vehicle battery development in Germany. The country's robust automotive sector creates sustained demand for lightweight, high-energy-density batteries. Stuttgart hosts a significant cluster of automotive OEMs and battery research institutes.
United States
The EPA reviews safety and performance for battery technologies in the United States. Utility providers prioritize long-duration, high-cycle-life thin film battery solutions for grid modernization initiatives. California leads in residential solar installations and energy storage mandates.
China
GB standards regulate safety and performance for thin film technologies in China. The rapid expansion of the electric vehicle market creates sustained demand for integrated solar solutions. Shenzhen acts as a hub for portable electronics manufacturing and battery innovation.
Japan
METI policies encourage advanced material science research for energy storage in Japan. The country focuses on high-efficiency perovskite tandem solar cells for specialized applications. Tokyo's research institutions are developing next-generation solid-state battery technologies.
India
India's PLI scheme promotes domestic manufacturing of advanced chemistry cells. The country's growing demand for decentralized power solutions drives adoption of thin-film PV in remote areas. Bengaluru is an emerging center for renewable energy technology development.
Thin Film Photovoltaic and Batteries Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the Thin Film Photovoltaic and Batteries market. This market exhibits structural fragmentation, with specialized innovators coexisting alongside large-scale manufacturers. Strategic archetypes include high-efficiency material developers, volume-driven PV producers, and niche solid-state battery providers. Companies engage in capacity expansion and strategic partnerships to secure raw materials and enhance market reach.
Specialists in advanced materials and manufacturing scale exemplify distinct competitive approaches. First Solar, a US-based corporation, represents a volume-driven PV producer leveraging established Cadmium Telluride technology. Oxford PV, a UK-based firm, anchors the high-efficiency material development segment with its perovskite research. Cymbet Corporation, a US-based company, sits within the niche solid-state micro-battery archetype for compact electronics.
| Leading Market Players |
|---|
| Cymbet Corporation |
| Blue Spark Technologies |
| First Solar |
| Heliatek |
| Oxford PV |
| Ascent Solar Technologies |
| Excellatron Solid State |
| Enfucell |
| Kaneka Corporation |
| Others |
Cost & Logistics Intelligence
Continuous manufacturing scale in thin film photovoltaic and battery production shapes both supply concentration and market price floors for established technologies. This efficiency allows large players to dominate volume segments while specialized innovators target high-value niches.
Pricing Analysis
Geographic price spreads for thin film products reflect regional manufacturing costs and regulatory compliance burdens. Pricing for utility-scale PV and grid-scale storage often follows contract-based long-term offtake agreements. Price differentiation stems from volume scale for established technologies like Cadmium Telluride and degradation warranties for long-duration battery solutions. Cost compression in the CdTe PV segment intensifies due to increased manufacturing capacity. Consumer Electronics Manufacturers exhibit the highest price sensitivity for compact battery solutions, while Utility Providers prioritize long-term reliability over initial capital cost.
Supply Chain Analysis
Just-in-time inventory strategies are common for high-volume components, while strategic stockpiles secure critical raw materials for specialized battery chemistries. Geographic supply concentration for thin film components centers on China for battery manufacturing and the United States for Cadmium Telluride production. The market relies heavily on specific raw materials, including tellurium for PV cells and high-purity lithium for next-generation batteries. Commodity price volatility for these critical materials presents a significant supply chain risk. Distribution runs through direct sales channels to Transportation OEMs and specialized integrators for grid-scale projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Thin Film Photovoltaic and Batteries market is undergoing a platform-economics inflection, driven by the convergence of energy harvesting and storage into integrated solutions. This shift creates new interoperability challenges and opportunities across diverse application ecosystems.
For Market Incumbents:Fortify existing market share by investing in advanced roll-to-roll processing capabilities to lower unit costs for established Cadmium Telluride PV. Secure long-term supply agreements for critical raw materials like tellurium to mitigate commodity price volatility. Address performance degradation concerns in certain thin-film chemistries through continuous R&D. Invest in alternative thin-film chemistries to mitigate the impact of the EU's RoHS directive on cadmium-based products.
For New Entrants and Emerging Players:Differentiate on high-efficiency performance by focusing on perovskite tandem solar cells for specialized applications in Building-Integrated PV. Target the medical devices segment with solid-state micro-batteries, capitalizing on demand for improved safety and energy density. The architectural sector in Europe presents a penetrable segment for transparent and flexible solar films. Partner with specialized integrators to accelerate market entry and co-develop application-specific solutions.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized innovators with strong intellectual property in solid-state battery technology or advanced perovskite materials. The market offers sustained growth over the next decade, particularly in integrated energy solutions for electric vehicles and grid modernization. Focus on companies developing scalable manufacturing processes for next-generation technologies. Commercialization milestones for solid electrolytes or high-volume roll-to-roll perovskite production are key signals to watch as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Roll-to-Roll Processing | Lowers manufacturing costs for flexible PV films, enhancing competitiveness in consumer electronics. |
| Technology Licensing for Solid Electrolytes | Accelerates development of safer, higher-energy-density solid-state batteries for medical devices. |
| Strategic Partnership with Transportation OEMs | Secures long-term demand for lightweight, high-energy-density batteries in the electric vehicle sector. |
| Green Manufacturing Transition for Circularity | Addresses end-of-life recycling challenges and aligns with EU circular economy mandates for materials. |
| Product Launch in Building-Integrated PV | Captures opportunities in the architectural sector, turning facades into power-generating surfaces. |
Research Approach
Two parallel data streams informed the analysis: primary interviews and secondary validation. Primary insights were gathered from R&D directors at material science firms, procurement leads at automotive OEMs, utility planners, and specialized integrators. Secondary data sources included regulatory filings from the EPA and EU Green Deal documents, national GB standards from China, and industry association reports, all triangulated with financial disclosures.
The forecasting framework covers the entire analysis window, modeling market dynamics without specific year references. Segmentation dimensions include product type, application, technology, and regional regulatory environments. Compound annual growth rates were derived from historical trends and projected shifts in technology adoption and policy support. Key forecast inputs include electric vehicle production targets and renewable energy deployment mandates across major economies.
The analysis sits within stated boundaries; outcomes outside significant shifts in raw material availability or unforeseen regulatory restrictions would require recalibration. Forecasts reflect assumptions regarding technological maturation and sustained investment in energy transition initiatives. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Battery Swapping Market
Batteries
Military Battery Packs Market
Batteries
Portable Battery Station Market
Batteries
Global Zinc Air Batteries Market
Batteries
Netherlands Rechargeable Battery Market
Batteries
Europe Rechargeable Battery Market
Batteries
India Alkaline Battery Market
Batteries
Nuclear Battery Sales Market
Batteries
Two Wheeler Lead Acid Batteries Market
Batteries
Taiwan Battery Market
Batteries
Europe Automotive Lead-Acid Battery Market
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market
Batteries
South America Battery Cell Market
Batteries
Mobile Battery Market
Batteries
Second-Life Automotive Battery Module Systems Market
Batteries
South Africa Battery Market