
 Battery Swapping Market | 2026-2036
Battery Swapping Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Swapping Market Analysis
A shift from single-source battery supply toward multi-source procurement networks is hardening across the battery swapping ecosystem. NIO sustains one of the most integrated captive networks, designing vehicles, batteries, and stations as a unified architecture. Gogoro dominates Taiwan's urban two-wheeler corridors through exclusive channel control of its GoStation footprint. Ample positions its modular robotics platform as a hardware-agnostic alternative, competing for fleet partnerships with OEM-agnostic operators.
Battery swapping is the automated or semi-automated exchange of depleted traction battery packs for fully charged units, typically completing in under five minutes through mechanical docking systems with standardized form factors and CAN-bus communication protocols. The primary commercial purpose is eliminating dwell time for electric vehicles operating on high-utilization schedules. Smart batteries command attention as the leading product type because their embedded battery management systems enable real-time state-of-health tracking that underpins subscription pricing models. Fleet operators represent the deepest end-user margin pool, since delivery services and ride-sharing companies absorb swap fees as operational expenses rather than capital outlays. Automated installation methods are displacing manual swapping in high-throughput corridors where labor costs and throughput constraints create bottlenecks.
FCC guidelines govern wireless communication protocols between swap stations and central management systems in the United States, while China's MIIT enforces GB/T dimensional and electrical standards that determine which vehicles qualify for national subsidies. India's CEA technical standards for battery swapping infrastructure, issued under the broader PLI scheme for advanced chemistry cells, shape market access by mandating interoperability testing before public deployment. Stakeholders must monitor whether regulatory divergence around connector geometry and data protocols fragments equipment markets or converges toward de facto international standards.
Market Dynamics
China's MIIT standardization mandates for battery form factors and electrical interfaces are compressing deployment timelines and forcing interoperability across previously siloed swapping networks. This regulatory pressure is accelerating consolidation among station operators while opening procurement channels for multi-source battery suppliers.
Growth Catalysts
- Commercial Fleet Electrification:Delivery aggregators and ride-hailing platforms in Jakarta, Bangkok, and Ho Chi Minh City are absorbing swap fees as operational expenses, bypassing the capital barrier that slows individual EV adoption.
- India's PLI Scheme for Advanced Chemistry Cells:The CEA technical standards issued under this incentive framework mandate interoperability testing, creating a certified equipment market that reduces deployment risk for station investors.
- Automated Docking Systems:Mechanical robotics platforms with CAN-bus communication protocols are cutting swap times below three minutes, enabling throughput volumes that justify urban real estate costs.
Market Restraints
- Lithium Price Volatility:Battery pack asset values fluctuate with cathode material costs, complicating depreciation schedules for swap station operators who carry inventory on balance sheets.
- Connector Geometry Fragmentation:Divergent physical interface standards between China's GB/T ecosystem and India's emerging CEA specifications force equipment makers to maintain separate tooling lines.
- Grid Interconnection Queues:High-voltage charging infrastructure at swap stations faces utility approval timelines that extend station commissioning by six to eighteen months in dense urban districts.
Strategic Opportunities
- Indonesia's National EV Roadmap:Presidential regulations prioritizing battery swapping for two-wheeler commercial mobility are unlocking state-owned land leases for station deployment across Greater Jakarta.
- Smart Battery-as-a-Service Models:Embedded battery management systems enabling real-time state-of-health tracking allow subscription pricing that decouples vehicle ownership from energy asset risk.
- Cross-Platform Robotics:Hardware-agnostic automated swapping platforms can capture fleet contracts from OEMs without captive networks, aggregating demand across multiple vehicle brands.
Industry Challenges
- Certification Bottlenecks:Multi-jurisdictional safety testing for thermal runaway containment systems extends product launch timelines and strains engineering resources at equipment manufacturers.
- Interoperability Integration:Legacy fleet management software requires API reconfiguration to interface with swap station central management systems, creating deployment friction for early adopters.
- Skilled Technician Scarcity:The mechatronics expertise required for robotic station maintenance outpaces vocational training program output in Southeast Asian deployment corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Swapping Market |
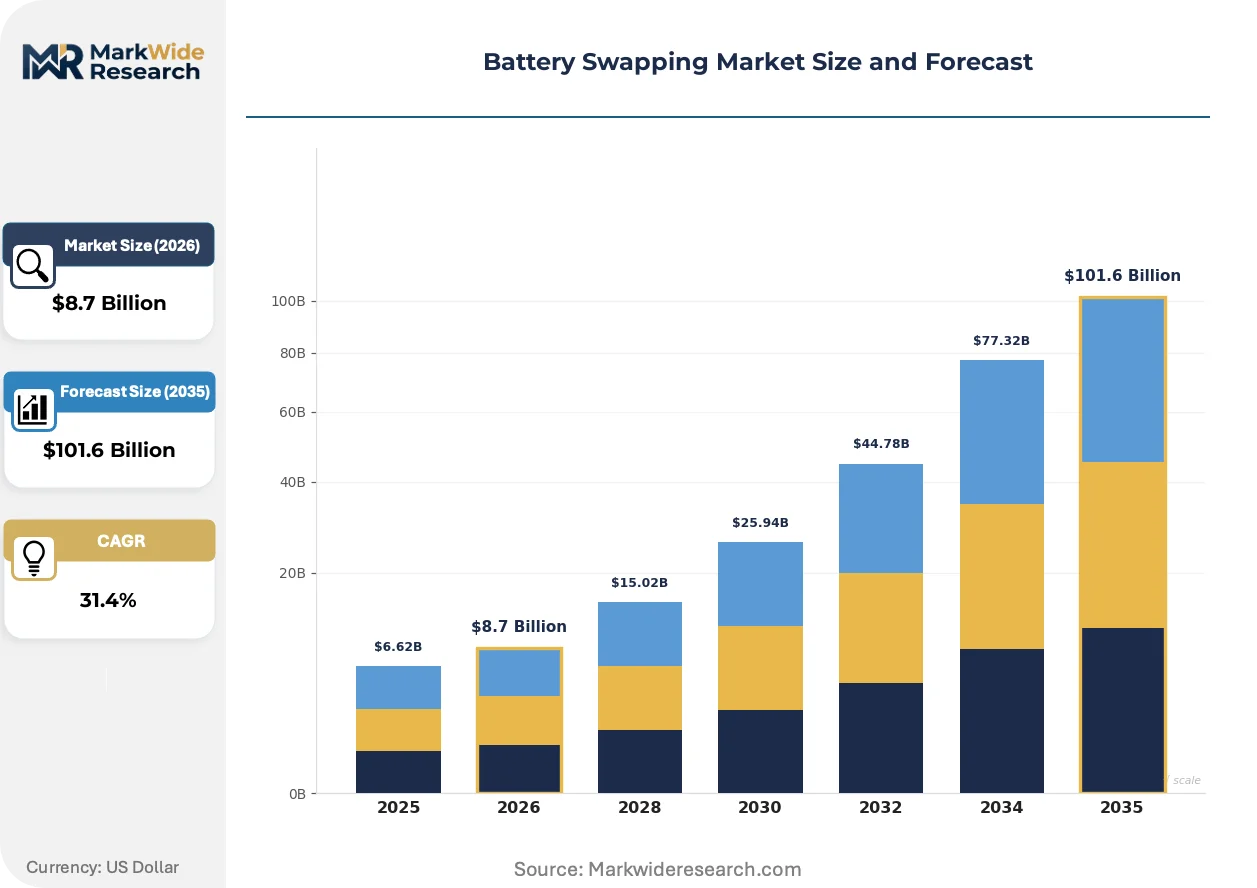
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $101.6 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Batteries, Modular Batteries, High-capacity Batteries, Standard Batteries Installation Method: Stationary, Mobile, Automated, Manual End User: Electric Vehicle Owners, Fleet Operators, Delivery Services, Ride-sharing Companies Deployment Model: Public Stations, Private Stations, Urban Installations, Rural Installations |
| Companies Covered | NIO, Gogoro, Ample, Sun Mobility, Contemporary Amperex Technology Co., Limited, Battery Smart, BYD Co. Ltd., Yadea Technology Group Co., Ltd., Kwang Yang Motor Co. Ltd. (KYMCO), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Swapping Market Emerging Trajectories
Robotics platforms and embedded intelligence are converging to transform swapping from a mechanical service into a data-rich energy arbitrage node. Station operators are repositioning as grid-interactive distributed storage assets rather than simple fueling points.
Modular battery pack architectures with standardized cell-to-pack interfaces are absorbing design complexity from vehicle manufacturers. Fleet operators in Taiwan and Vietnam are specifying these platforms in procurement tenders, compressing integration timelines for new vehicle models from eighteen months to under six months. The structural consequence is that battery suppliers are capturing value previously held by chassis integrators.
China's MIIT enforcement of GB/T dimensional standards is eliminating form factor fragmentation that previously locked vehicles to proprietary swapping networks. The industrial consequence is a hardware-agnostic equipment market where station operators can serve multiple OEM brands from identical infrastructure. Two-wheeled commercial fleets are responding fastest, as standardized packs enable multi-source battery procurement that hedges supply concentration risk.
Fleet procurement departments are consolidating vendor relationships around full-service energy contracts that bundle vehicle lease, battery subscription, and swap access into per-kilometer pricing. This displaces capital-intensive asset ownership models that previously required separate financing for vehicles and charging infrastructure. The shift is most visible among last-mile delivery platforms in India, where operational expenditure treatment of mobility costs aligns with investor preference for asset-light balance sheets.
Battery Swapping Market Segmentation
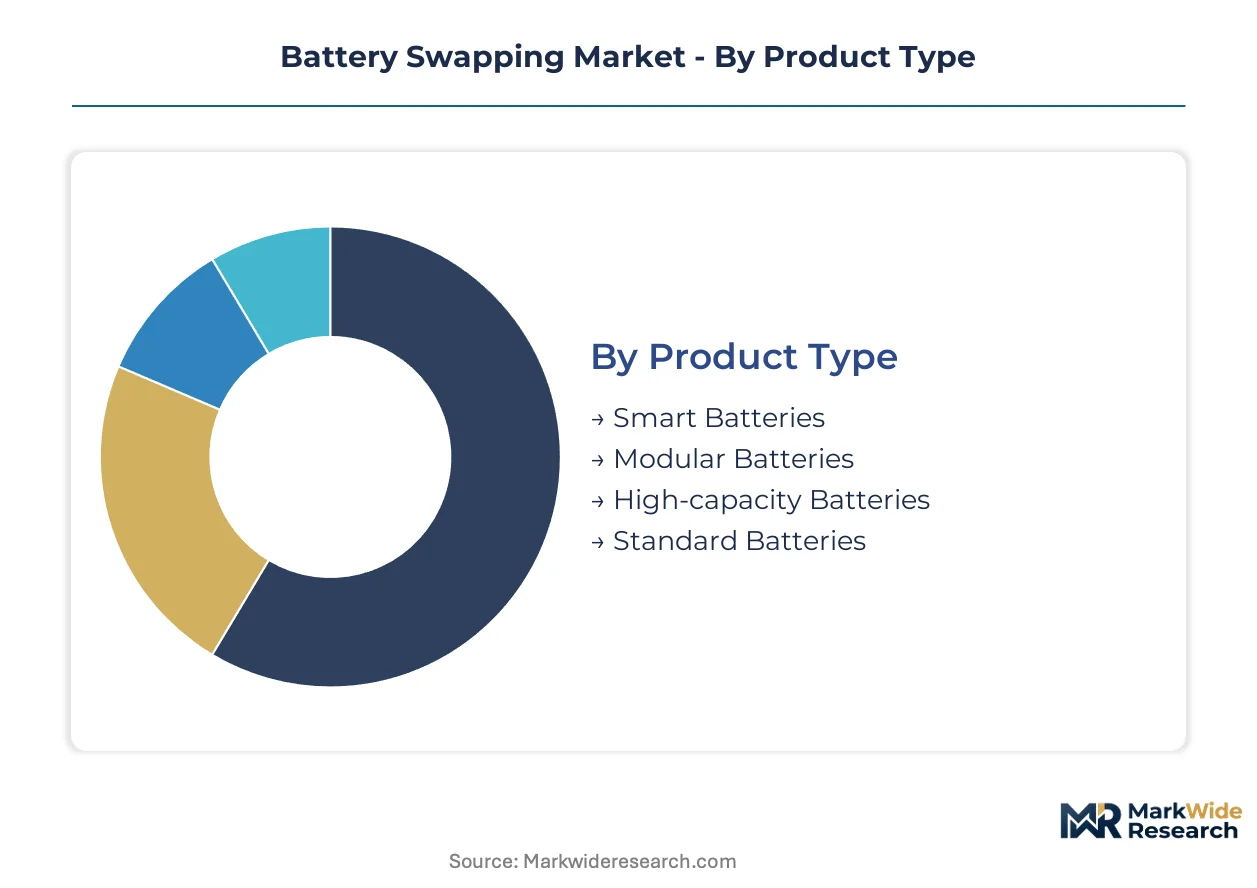
Battery swapping market segmentation reveals distinct procurement patterns across product architectures and operational models. Fleet operators prioritize standardized interfaces and throughput capacity, while individual owners emphasize accessibility and subscription flexibility. Understanding these divergent buyer profiles shapes equipment design and station network planning.
Product Type:
Fleet procurement departments weight total cost of ownership against asset utilization rates when selecting battery architectures.
- Smart Batteries:Embedded battery management systems enable real-time state-of-health monitoring and predictive maintenance scheduling. Delivery aggregators in Jakarta and Ho Chi Minh City specify these units to minimize downtime from unexpected failures. Subscription pricing models depend on this telemetry layer.
- Modular Batteries:Standardized cell-to-pack interfaces allow rapid capacity reconfiguration without vehicle redesign. Taiwan's two-wheeler fleet operators specify these platforms to compress integration timelines for new vehicle models from eighteen months to under six months.
- High-capacity Batteries:Extended range packs serve intercity commercial routes where station density remains sparse.
- Standard Batteries:Basic units without embedded intelligence dominate price-sensitive individual owner segments.
Smart batteries lead on scale; modular batteries lead on momentum.
Installation Method:
Urban real estate costs and labor availability determine capital deployment priorities across mechanization levels.
- Automated:Robotic docking platforms with CAN-bus protocols cut swap times below three minutes. High-throughput corridors in Bangkok and Greater Jakarta deploy these systems where labor costs and throughput constraints create bottlenecks.
- Stationary:Fixed-location infrastructure dominates established networks with secured real estate tenure.
- Mobile:Truck-mounted swap units serve construction sites and event logistics with unpredictable demand patterns.
- Manual:Operator-assisted systems persist in low-volume rural corridors where capital recovery timelines extend beyond investor horizons.
Automated systems command the steepest expansion trajectory; stationary installations retain installed base dominance.
End User:
Balance sheet treatment of mobility costs separates commercial fleet demand from individual consumer adoption patterns.
- Fleet Operators:Delivery services and ride-hailing platforms absorb swap fees as operational expenses rather than capital outlays. India's last-mile delivery platforms align this opex treatment with investor preference for asset-light structures.
- Delivery Services:High-utilization schedules maximize the value proposition of sub-five-minute battery exchanges.
- Ride-sharing Companies:Driver incentive programs increasingly bundle swap access to reduce vehicle downtime during revenue hours.
- Electric Vehicle Owners:Individual adopters face capital barriers that slow uptake relative to commercial segments.
Fleet operators anchor revenue concentration; delivery services are gaining share fastest.
Deployment Model:
Land access rights and grid interconnection timelines shape station economics across public and captive network configurations.
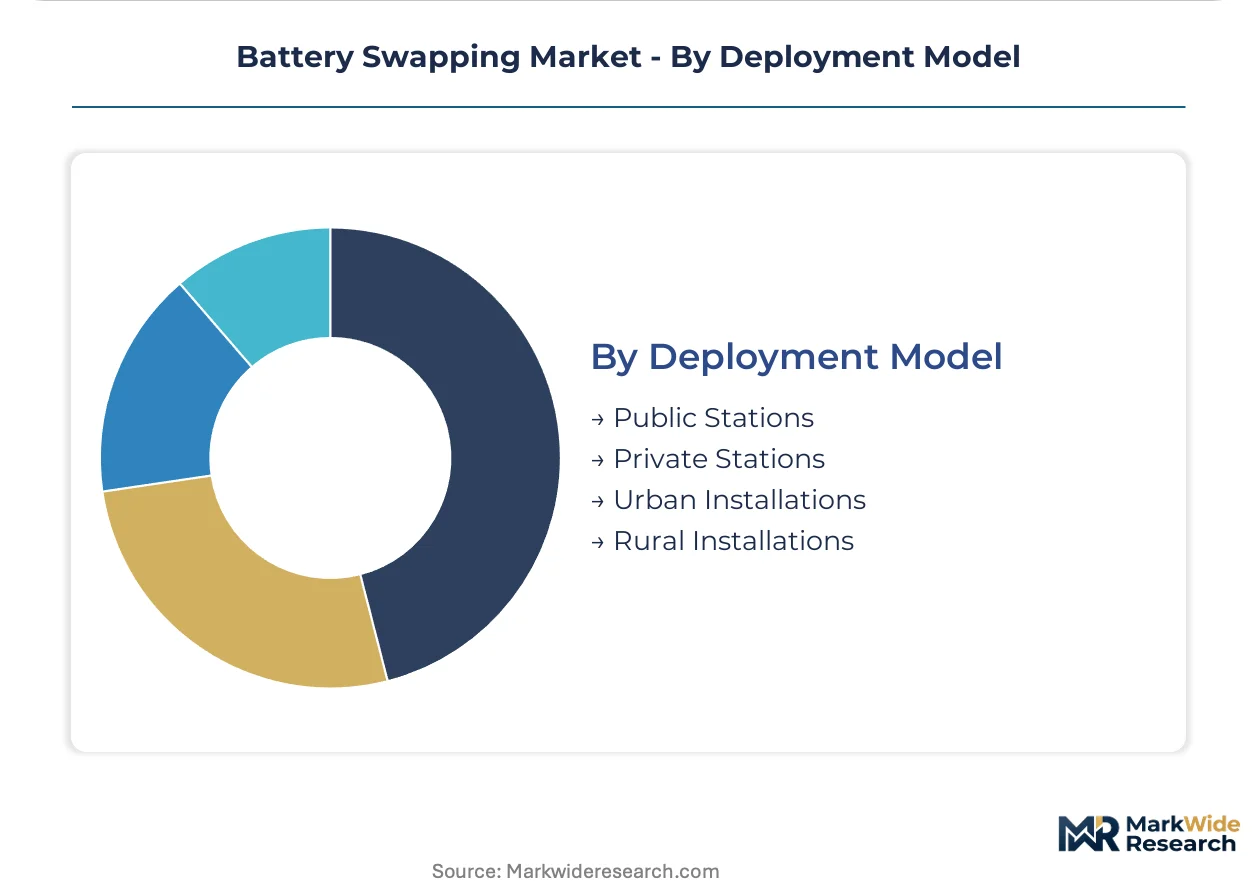
- Public Stations:Open-access infrastructure serves multiple OEM brands and vehicle categories. Indonesia's state-owned land leases for Greater Jakarta deployment prioritize this model under national EV roadmap regulations.
- Urban Installations:Dense metropolitan corridors justify high-voltage grid connections and automated throughput systems.
- Private Stations:Captive networks like NIO's integrated architecture maintain exclusive channel control.
- Rural Installations:Sparse demand patterns extend payback periods and deter private capital deployment.
Public stations lead on scale; urban installations lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Jakarta anchors battery swapping deployment density through Indonesia's state-backed land access programs. Fleet electrification across Southeast Asian megacities is compressing payback timelines for station operators while regulatory standardization in China and India reshapes equipment procurement patterns.
China
MIIT enforcement of GB/T dimensional standards is eliminating proprietary form factor lock-in that previously tethered vehicles to single networks. The Yangtze River Delta corridor hosts the densest station concentration, with Shanghai and Suzhou clusters processing high-throughput commercial fleet exchanges. Automated docking platforms with CAN-bus protocols dominate new installations.
India
CEA technical standards issued under the PLI scheme for advanced chemistry cells mandate interoperability testing before public deployment. Maharashtra and Karnataka lead station buildouts, with Mumbai and Bangalore corridors prioritizing last-mile delivery fleet conversions. Asset-light balance sheet preferences among delivery platforms accelerate opex-based subscription uptake.
Indonesia
Presidential regulations prioritizing battery swapping for two-wheeler commercial mobility unlock state-owned land leases across Greater Jakarta. The national EV roadmap channels private capital toward public station models serving multiple OEM brands. Surabaya and Bandung replication is following Jakarta's deployment template.
Taiwan
Gogoro's GoStation network dominates urban two-wheeler corridors through exclusive channel control of high-frequency swap points. Taipei and Kaohsiung metropolitan clusters exhibit mature subscription penetration among delivery riders. The regulatory environment permits captive network operation without interoperability mandates.
Vietnam
Ho Chi Minh City delivery aggregators absorb swap fees as operational expenses, bypassing capital barriers that slow individual EV adoption. Modular battery pack specifications in fleet procurement tenders compress vehicle integration timelines. The Mekong Delta corridor shows emerging demand from intercity commercial routes.
Battery Swapping Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue hardware-agnostic platform positioning. The market exhibits moderate consolidation around integrated captive networks and modular robotics specialists. Three archetypes dominate: vehicle-battery-station integrators, station-only operators with exclusive geographic control, and OEM-agnostic equipment vendors. Capacity expansion and strategic partnerships constitute the primary competitive vectors, with multi-source battery procurement networks hardening across ecosystems.
Among integrated network operators, NIO and Gogoro exemplify divergent strategic positions. NIO sustains unified architecture control across vehicle, battery, and station layers. Gogoro anchors Taiwan's urban two-wheeler infrastructure through exclusive real estate partnerships. Ample occupies the equipment-vendor tier with modular robotics positioning for fleet-agnostic deployment. Each represents a distinct archetype in how value capture distributes across the swapping value chain.
| Leading Market Players |
|---|
| NIO |
| Gogoro |
| Ample |
| Sun Mobility |
| Contemporary Amperex Technology Co., Limited |
| Battery Smart |
| BYD Co. Ltd. |
| Yadea Technology Group Co., Ltd. |
| Kwang Yang Motor Co. Ltd. (KYMCO) |
| Others |
Supply Flow & Price Mechanics
Captive battery production networks in China and South Korea anchor both supply security and pricing power for integrated swapping station operators. NIO's unified architecture control and CATL's cell-to-pack dominance demonstrate how upstream integration insulates subscription pricing from lithium carbonate volatility while locking in margin capture across the energy-services value chain.
Pricing Analysis
Lithium carbonate and nickel sulfate pass-through mechanisms dominate battery pack asset pricing, with cathode material cost swings of twenty to thirty percent compressing depreciation schedules for station operators carrying inventory. Subscription models stratify across fleet-scale, individual consumer, and enterprise tiers, with volume commitments unlocking preferential per-swap rates. Cost compression in standard battery tiers intensifies as China's MIIT standardization opens multi-source procurement channels. Fleet operators exhibit lowest price sensitivity due to opex treatment, while individual owners in emerging markets resist subscription uptake without steep entry discounts.
Supply Chain Analysis
Reverse-logistics flows for degraded battery packs concentrate refurbishment capacity in China's Yangtze River Delta and South Korea's Incheon corridor, where cell-to-pack reassembly extends asset lifecycles. Cell manufacturing draws from cathode precursor supply anchored in Indonesia's nickel processing zones and Chile's lithium brine operations. Single-source vulnerability persists in high-nickel cathode chemistries where Indonesian processing dominance concentrates geopolitical exposure. Distribution runs through regional battery assembly hubs serving station operator procurement networks, with modular pack architectures enabling last-mile configuration flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in battery swapping rests on automated throughput scaling that collapses per-transaction labor content while subscription tiering captures premium fleet demand. Standardization mandates across China, India, and Indonesia compress equipment costs and open multi-source procurement channels.
For Market Incumbents: Deepen robotic station deployment in Greater Jakarta and Ho Chi Minh City corridors where land access competition intensifies. Consolidate around GB/T and CEA-certified battery interfaces before interoperability mandates fragment procurement. Defend against hardware-agnostic entrants by locking exclusive real estate partnerships with state-owned land lessors.
For New Entrants and Emerging Players: Fleet management software vendors represent the most penetrable channel anchor, as legacy TMS platforms require API reconfiguration to interface with swap station central management systems. Target India's last-mile delivery platforms where asset-light balance sheet preferences accelerate opex-based energy contract uptake. Lead with modular robotics positioning that aggregates demand across multiple OEM brands without captive network investment.
For Investors and Strategic Acquirers: Roll-up economics work for regional station operators because Indonesia's state-backed land lease programs and India's PLI-certified equipment standards create deployable asset bases with reduced regulatory risk. Five-to-ten year viability hinges on grid-interactive storage revenue streams beyond pure swapping throughput. Monitor CEA and MIIT standardization convergence as inflection signal for cross-border equipment market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Docking Platform Deployment | CAN-bus robotics in Bangkok and Jakarta corridors cut swap times below three minutes, justifying premium urban real estate. |
| Multi-Source Battery Procurement Network | CEA and GB/T standardization enables station operators to hedge CATL concentration with BYD and LG Energy Solution supply. |
| Grid-Interactive Storage Certification | FERC and state utility commission approvals unlock ancillary services revenue beyond core swapping operations. |
| Fleet Energy Contract Consolidation | Per-kilometer bundling of vehicle lease, battery subscription, and swap access aligns with Indian delivery platform investor preferences. |
| Reverse-Logistics Refurbishment Capacity | Cell-to-pack reassembly in Yangtze Delta hubs extends battery asset lifecycles and improves subscription margin structure. |
Methodological Framework
Bottom-up fleet operator modeling reconciled against top-down station deployment tracking forms the analytical core of this study. Primary interviews with swap station network planners, battery procurement executives at delivery platforms, CEA certification engineers, and grid interconnection officers combined with secondary validation from MIIT standardization filings, PLI scheme disclosures, and utility distribution expansion records. Top-down supply-side assessment tracked equipment manufacturer capacity announcements and battery cell production allocations across certified supplier networks.
Historical trendline analysis of commercial fleet electrification patterns and station utilization rates informed projection frameworks across the analysis window. Segmentation dimensions modeled include battery architecture type, installation mechanization level, end-user balance sheet treatment, and deployment model configuration. CAGRs derived from S-curve adoption modeling weighted by regulatory mandate implementation timelines and grid interconnection queue clearance rates. Forecast inputs incorporated lithium price scenario bands and standardization protocol convergence probabilities.
Revisions become necessary when MIIT or CEA regulatory amendments alter interoperability requirements, when lithium carbonate price volatility exceeds modeled bands, or when utility interconnection timelines extend beyond eighteen-month commissioning assumptions. Forecasts reflect documented assumptions regarding fleet operator opex preference persistence and state-backed land access program continuity. Practitioners should monitor GB/T and CEA connector geometry alignment negotiations, PLI scheme beneficiary announcements, and Jakarta land lease tender volumes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Printable Battery Market
Batteries
US Solar Battery Market
Batteries
Asia Pacific Electric Vehicle VRLA Batteries Market
Batteries
Breathing Battery Market
Batteries
Italy SLI Battery Market
Batteries
West Africa Battery Market
Batteries
Iron Flow Battery Market
Batteries
Lithium Marine Battery Market
Batteries
Floor Scrubber Battery Market
Batteries
Battery Binders Market
Batteries
Alkaline Battery Market
Batteries
South America Primary Battery Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
Battery Anode Materials Market
Batteries
UAV Battery Pack Market
Batteries
Lithium Battery Testing System Market