
 Europe Automotive Lead-Acid Battery Market | 2026-2036
Europe Automotive Lead-Acid Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Lead-Acid Battery Market Intelligence
Preventive maintenance subscriptions for commercial fleets is realigning how battery value gets captured in Europe. Clarios leverages its pan-European service network to lock in fleet renewal contracts. Banner Batterien anchors its position through specialized OEM supply agreements with German and Austrian vehicle manufacturers. TAB Batteries competes on cost-optimized production from its Slovenian manufacturing base.
Europe automotive lead-acid batteries are electrochemical storage devices using lead dioxide positive plates, sponge lead negative plates, and sulfuric acid electrolyte, typically rated at 12 volts with cold cranking amperage between 300 and 1000 A for passenger vehicle applications. These batteries provide engine starting power, stabilize vehicle electrical systems, and supply reserve capacity for stop-start functionality in conventional internal combustion vehicles. Flooded technology still dominates unit volumes across the aftermarket channel due to lower upfront cost, though AGM batteries command premium positioning as original equipment on vehicles with advanced stop-start systems and higher electrical loads. Aftermarket Providers represent the most fragmented end-user segment, while OEMs concentrate procurement among a narrow supplier base with multi-year platform agreements.
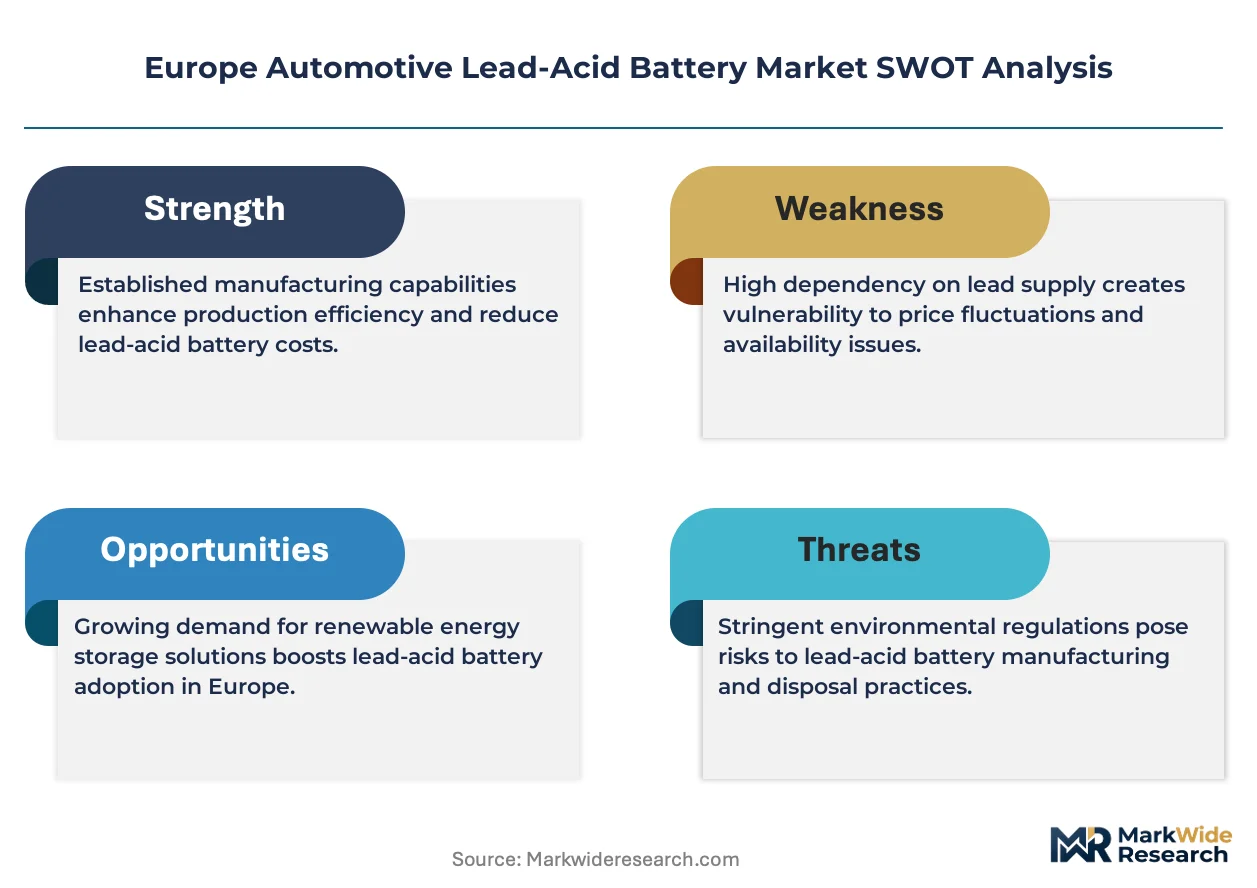
EU Battery Regulation mandates minimum recycled content thresholds and full supply chain due diligence, forcing producers to restructure collection logistics and material provenance systems. ECHA's REACH restrictions on lead exposure in manufacturing environments are elevating capital requirements for plant modernization across member states. CE marking and the F-Gas Regulation's indirect pressure on vehicle electrification timelines create mixed demand signals for lead-acid technology. Stakeholders must monitor how the EU Green Deal's transport decarbonization targets reshape the residual value of conventional battery infrastructure before committing to long-term capacity decisions.
Market Dynamics
Fleet operators across Germany and France are compressing replacement cycles for commercial vehicle starter batteries while EU Battery Regulation mandates force producers to restructure collection logistics and prove material provenance across member states.
Growth Catalysts
- EU Battery Regulation compliance deadlines:Minimum recycled content thresholds and due diligence requirements are pulling forward investment in closed-loop collection infrastructure across Poland and Romania.
- Stop-start system proliferation:AGM technology penetration in passenger vehicles with advanced electrical architectures is sustaining premium battery demand despite electrification headwinds.
- Poland's battery assembly clusters:Cost-optimized production bases near German OEM supply corridors are capturing contract manufacturing volumes from Western European producers.
Market Restraints
- Lead price volatility:Raw material input swings compress margin predictability for flooded battery producers serving price-sensitive aftermarket channels.
- Li-ion substitution in commercial segments:Urban delivery fleets piloting electric powertrains are bypassing lead-acid starter batteries entirely for auxiliary power units.
- ECHA REACH manufacturing compliance:Lead exposure limits in plant environments are elevating capital requirements for Czech and Slovak production facilities.
Strategic Opportunities
- Preventive maintenance subscriptions:Fleet operators in Benelux are unbundling battery replacement from vehicle service contracts, creating recurring revenue streams for specialized providers.
- Second-life stationary storage:Retired automotive batteries are finding residual value in grid stabilization applications across Spanish and Italian renewable energy zones.
- Circular economy mandates:EU Green Deal transport decarbonization targets are accelerating state-funded collection point density in Eastern European member states.
Industry Challenges
- Skilled technician scarcity:Battery diagnostics and safe handling certification programs are struggling to match retirement rates in France's automotive service sector.
- Multi-jurisdiction compliance complexity:Producers must maintain parallel documentation systems for CE marking, REACH substance tracking, and member-state-specific waste transfer protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Lead-Acid Battery Market |
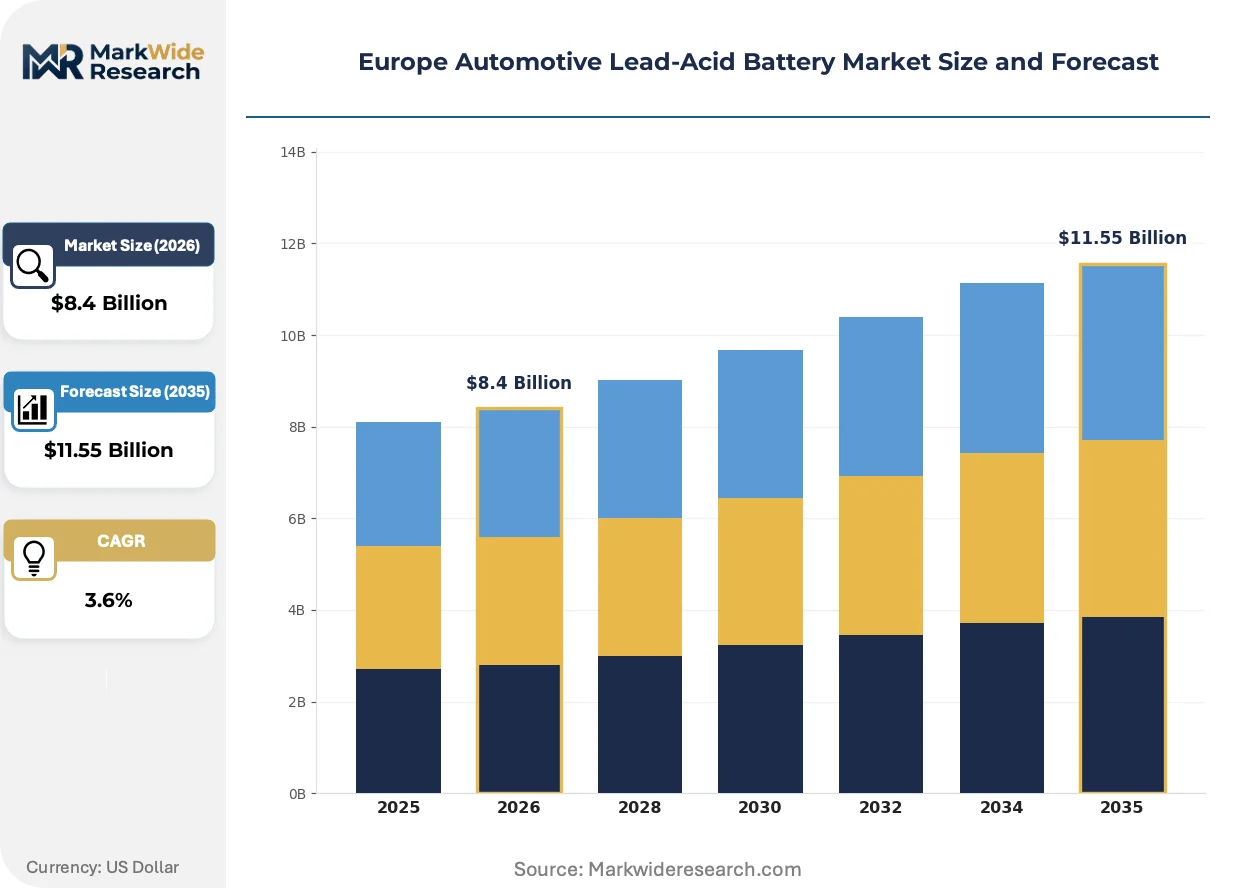
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $11.55 Billion |
| CAGR (2026 – 2036) | 3.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starter Batteries, Traction Batteries, Stationary Batteries, AGM Batteries Technology: Flooded, VRLA, Gel, Lithium End User: OEMs, Aftermarket Providers, Exporters, Retail Distributors Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy Equipment |
| Companies Covered | EnerSys, FIAMM Energy Technology, Exide Technologies, NorthStar Battery Company, TAB Batteries, Clarios, Banner Batterien, C&D Technologies, GS Yuasa Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Lead-Acid Battery Market Strategic Shifts & Innovations
Technology evolution, regulatory stringency, and procurement model compression are simultaneously reshaping how battery value gets captured and who controls distribution relationships across European automotive channels.
Absorbent Glass Mat (AGM) technology is expanding into mid-segment passenger vehicles as OEM electrical architectures demand higher cyclic durability for stop-start functionality. German and Austrian vehicle manufacturers are specifying AGM as standard equipment on B-segment and above platforms. This specification shift is expanding into aftermarket replacement demand as vehicle parc ages and independent service providers stock dual inventory.
REACH restrictions on lead compound exposure are forcing manufacturing plant modernization across Czechia, Slovakia, and Hungary. ECHA's updated occupational exposure limits require automated plate handling and enclosed formation processes. Smaller producers in these geographies are consolidating or exiting rather than absorbing seven-figure capital requirements.
Subscription-based fleet maintenance contracts are displacing transactional battery replacement across German and French commercial vehicle operators. Clarios and Banner Batterien are restructuring sales organizations to capture multi-year renewal commitments rather than spot aftermarket volume. This contracting shift is most visible in long-haul trucking segments where total cost of ownership visibility outweighs upfront component pricing.
Europe Automotive Lead-Acid Battery Market Segmentation
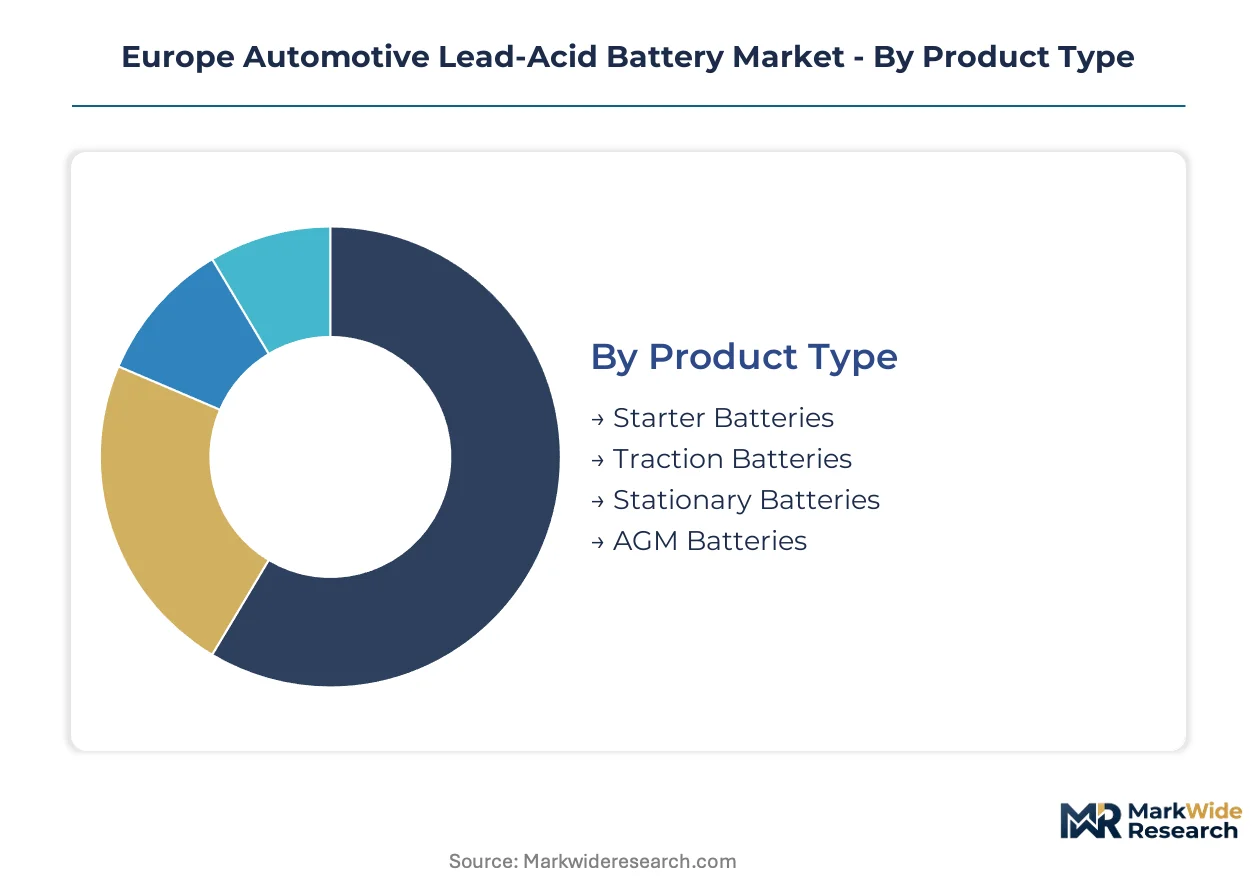
European automotive lead-acid battery segmentation reveals distinct procurement patterns between integrated OEM supply chains and fragmented aftermarket channels. Technology specifications and end-user contracting models determine margin capture across flooded, AGM, and emerging lithium alternatives.
Product Type:
Starter batteries function as standalone replaceable components, while traction and stationary systems embed into larger vehicle or infrastructure architectures with longer replacement cycles.
- Starter Batteries:These 12-volt units deliver cold cranking amperage for internal combustion engine ignition across passenger and commercial vehicle fleets. Demand clusters in Germany's automotive manufacturing corridor where OEM platform agreements concentrate procurement among Clarios, Banner Batterien, and Varta. ECHA REACH compliance costs are compressing margins for flooded starter battery producers serving price-sensitive aftermarket channels.
- AGM Batteries:Absorbent Glass Mat construction eliminates free electrolyte, enabling higher cyclic durability for advanced stop-start systems and elevated electrical loads. German and Austrian OEMs specify AGM as standard equipment on B-segment platforms and above, pulling aftermarket replacement demand as vehicle parc ages. EU Battery Regulation recycled content mandates favor AGM producers with established closed-loop collection infrastructure.
- Traction Batteries:Deep-cycle designs power electric forklifts and material handling equipment in logistics hubs across Poland and Czechia.
- Stationary Batteries:Reserve power applications for telecommunications and backup systems in Spanish and Italian renewable energy zones.
Volume placements concentrate in Starter Batteries; the faster expansion belongs to AGM Batteries.
Technology:
Cost tier differentiation separates mature flooded production from premium VRLA and gel alternatives, with lithium emerging as a technology displacement threat in select commercial segments.
- Flooded:Liquid electrolyte designs dominate aftermarket unit volumes due to lower upfront cost, though margin compression from lead price volatility limits producer profitability. Polish and Romanian assembly clusters leverage cost-optimized production to supply Western European price-sensitive channels.
- VRLA:Valve-Regulated Lead-Acid technology eliminates maintenance requirements through oxygen recombination chemistry, commanding premium positioning in fleet maintenance contracts. German commercial vehicle operators specify VRLA for long-haul trucking segments where total cost of ownership visibility outweighs upfront component pricing.
- Gel:Silica-thickened electrolyte provides vibration resistance for motorcycle and heavy equipment applications across Alpine regions.
- Lithium:Urban delivery fleets in France and the Netherlands pilot lithium auxiliary power units, bypassing lead-acid entirely for weight-sensitive applications.
Cost-sensitive procurement favors Flooded technology; premium fleet contracts are accelerating VRLA placement.
End User:
Customer type determines contracting structure, with OEMs locking in multi-year platform agreements while aftermarket channels fragment across competing service networks.
- OEMs:Original equipment manufacturers concentrate procurement among narrow supplier bases with multi-year platform agreements spanning vehicle generations. German automotive producers specify battery performance standards that cascade through tiered supply chains into Slovenian and Czech production facilities.
- Aftermarket Providers:Independent service networks and retail channels represent the most fragmented end-user segment, with inventory complexity rising as AGM penetration expands alongside legacy flooded demand. Benelux fleet operators are unbundling battery replacement from vehicle service contracts, creating recurring revenue streams for specialized providers.
- Exporters:Eastern European producers ship cost-optimized production to Middle Eastern and African markets outside EU regulatory jurisdiction.
- Retail Distributors:Auto parts chains and e-commerce platforms stock dual inventory for DIY replacement and professional installer channels.
Contract value concentrates with OEMs; the steepest expansion trajectory sits with Aftermarket Providers restructuring around subscription models.
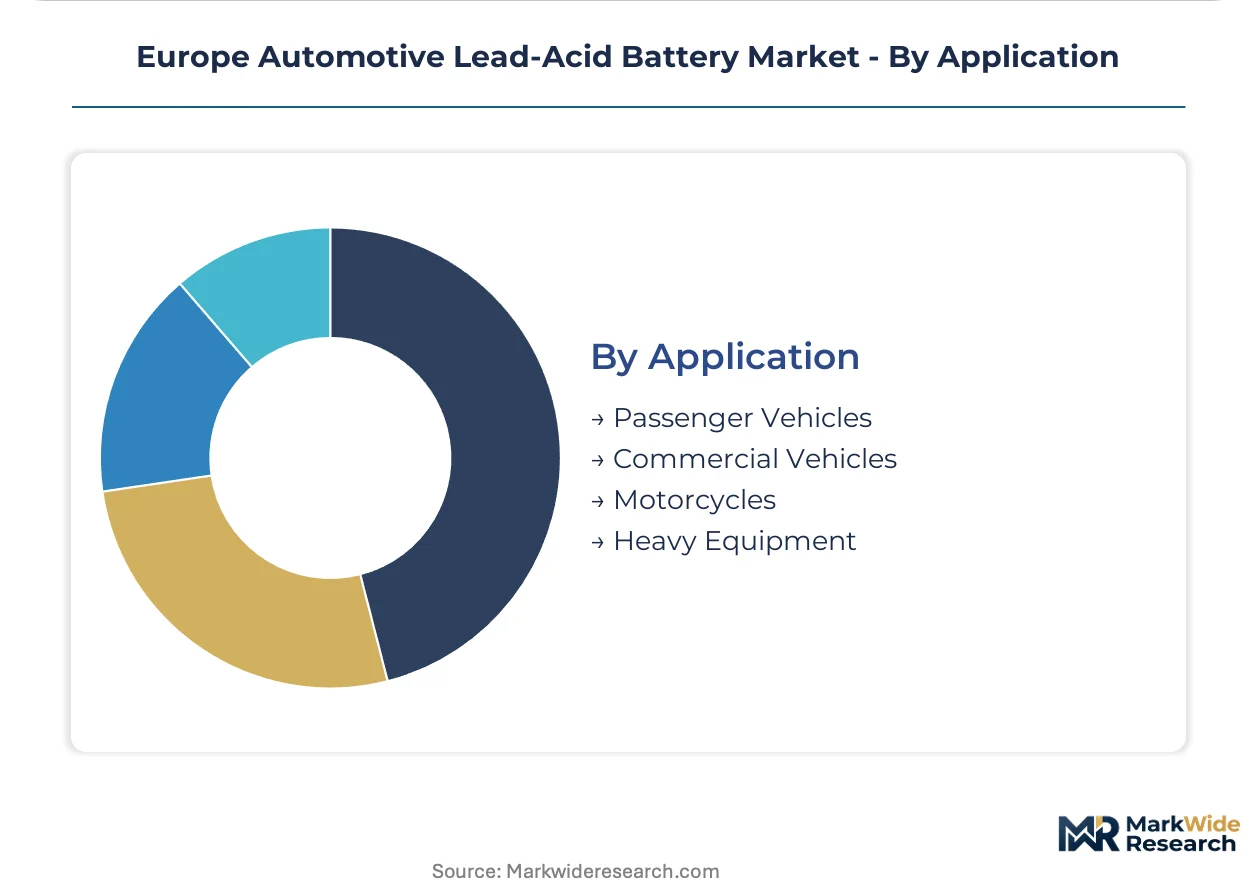
Application:
Vehicle electrification timelines vary by application, with passenger vehicle stop-start proliferation sustaining lead-acid demand while commercial segments face earlier lithium substitution.
- Passenger Vehicles:Conventional internal combustion and mild-hybrid architectures sustain starter battery demand across Europe's aging vehicle parc. Stop-start system proliferation in German and Austrian B-segment platforms and above is expanding AGM specification as standard equipment.
- Commercial Vehicles:Long-haul trucking and urban delivery fleets operate under diverging technology pressures, with highway segments extending lead-acid replacement cycles while last-mile electrification pilots bypass starter batteries entirely. French fleet operators compress replacement cycles for starter batteries while piloting lithium auxiliary power units in urban delivery configurations.
- Motorcycles:Powersports applications in Alpine regions favor gel technology for vibration resistance and cold-weather performance.
- Heavy Equipment:Construction and agricultural machinery in Poland's emerging manufacturing clusters demand deep-cycle durability for intermittent use patterns.
Unit volume leadership remains with Passenger Vehicles; Commercial Vehicles are gaining share fastest through fleet subscription restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Central European manufacturing corridors while consumption clusters in Western European fleet operator bases, creating a cross-border supply configuration shaped by regulatory arbitrage and logistics optimization.
Germany
Automotive OEM platform agreements concentrate procurement among narrow supplier bases with multi-year contracts spanning vehicle generations. ECHA REACH occupational exposure limits are forcing automated plate handling investments in Bavarian and Baden-Württemberg production facilities. The Stuttgart automotive manufacturing corridor anchors AGM specification as standard equipment on B-segment platforms and above.
Poland
Cost-optimized assembly clusters near German OEM supply corridors are capturing contract manufacturing volumes from Western European producers facing compliance cost pressures. EU Battery Regulation recycled content mandates are pulling forward investment in closed-loop collection infrastructure across Lower Silesian industrial zones. Warsaw and Krakow logistics hubs serve as distribution nodes for Eastern European aftermarket channels.
France
Commercial fleet operators are compressing replacement cycles for starter batteries while piloting lithium auxiliary power units in urban delivery configurations. The country's national environmental regulator enforces extended producer responsibility schemes that elevate collection point density requirements. Lyon and Paris basin logistics corridors sustain demand for deep-cycle traction batteries in material handling applications.
Italy
Retired automotive batteries are finding residual value in grid stabilization applications across renewable energy zones in the south. CE marking and F-Gas Regulation compliance create documentation burdens for producers serving the fragmented aftermarket channel. Milan-Turin industrial clusters concentrate battery distribution for Alpine powersports and motorcycle applications favoring gel technology.
Czechia
ECHA REACH manufacturing compliance is elevating capital requirements for production facilities in the Ostrava industrial region. Smaller producers are consolidating or exiting rather than absorbing seven-figure modernization investments. The country's position between German demand centers and Polish supply bases creates logistics arbitrage opportunities for regional distributors.
Europe Automotive Lead-Acid Battery Market Key Industry Players
Top-tier vendors anchor OEM platform agreements, while mid-tier specialists compete on cost-optimized production and aftermarket service density. The vendor base stratifies across integrated pan-European networks, regional manufacturing specialists, and commodity assemblers serving price-sensitive channels. Two dominant competitive moves are restructuring sales organizations around subscription-based fleet contracts and consolidating production capacity to absorb REACH compliance costs.
Among diversified energy storage conglomerates, EnerSys and Exide Technologies exemplify scale-driven positioning across industrial and automotive applications. Within the European specialist tier, Clarios represents integrated service network architecture, while Banner Batterien anchors OEM supply relationships with German and Austrian vehicle manufacturers. TAB Batteries occupies a position as a cost-optimized producer from Slovenian manufacturing bases serving contract manufacturing demand.
| Leading Market Players |
|---|
| EnerSys |
| FIAMM Energy Technology |
| Exide Technologies |
| NorthStar Battery Company |
| TAB Batteries |
| Clarios |
| Banner Batterien |
| C&D Technologies |
| GS Yuasa Corporation |
| Others |
Cost & Logistics Intelligence
London Metal Exchange lead price volatility cascades through European battery supply chains, compressing margins for flooded battery producers in Poland and Romania while amplifying pricing power for AGM specialists with backward-integrated recycling networks. ECHA REACH compliance costs add a fixed-cost layer that stratifies producers into compliance-capable and exit-bound tiers.
Pricing Analysis
Margin tightening in flooded aftermarket channels reflects lead price volatility and Polish assembly competition. Three-tier pricing structure across AGM premium, VRLA standard, and flooded economy levels segments buyers by electrical architecture requirements. Cost-down pressure on economy tiers accelerates because fleet operators in Benelux unbundle battery replacement from service contracts. Aftermarket DIY channels exhibit highest price sensitivity; OEM platform agreements show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale procurement from German and Austrian vehicle manufacturers, while aftermarket distribution runs through fragmented service networks across France and Italy. Supply concentrates in Poland, Czechia, and Slovenia for cost-optimized assembly, with lead smelting and paste production anchored in Germany and Spain. Raw material sourcing draws from secondary lead recyclers and primary smelters in Iberia. Single-source vulnerability in lead concentrate imports from North Africa creates exposure. Distribution feeds from regional hubs into installer and retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Battery Regulation compliance deadlines erect a barrier-to-entry moat favoring incumbents with closed-loop collection infrastructure and proven material provenance systems.
For Market Incumbents: Deepen backward integration into secondary lead smelting to secure recycled content thresholds and absorb ECHA REACH capital requirements. Consolidate Czech and Slovak production capacity as smaller competitors exit. Lithium auxiliary power units in French urban delivery fleets threaten long-haul trucking dominance. For New Entrants and Emerging Players: Fleet maintenance subscription providers in Benelux represent the most penetrable channel archetype. Target second-life stationary storage applications in Spanish and Italian renewable zones as asset-light entry points. Partner with regional logistics operators for collection point density without capital-heavy manufacturing. For Investors and Strategic Acquirers: Distressed-cycle entries favor Slovenian and Romanian assembly specialists with OEM contract manufacturing relationships and sub-scale REACH compliance burdens. Five-to-ten-year viability hinges on electrification pace in commercial segments. Watch lithium penetration rates in French last-mile delivery fleets as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Investment | EU Battery Regulation recycled content mandates favor producers with captive smelting in Germany and Spain. |
| Fleet Subscription Restructuring | Multi-year renewal contracts with Benelux operators displace transactional aftermarket volume for specialized providers. |
| AGM Capacity Expansion | German OEM stop-start proliferation pulls aftermarket replacement demand as B-segment vehicle parc ages. |
| Second-Life Storage Partnerships | Retired automotive batteries grid-stabilize renewable zones in southern Italy and Spain. |
| REACH Compliance Modernization | Automated plate handling investments separate viable Czech and Slovak producers from exit-bound competitors. |
Research Approach
Multi-period observation of lead price indices, vehicle registration data, and OEM platform specifications anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement managers, aftermarket distributor operations heads, fleet maintenance contract directors, and ECHA regulatory compliance officers. Secondary validation drew from EU Battery Regulation implementation documents, ECHA REACH guidance updates, vehicle production databases, and customs trade records. Bottom-up volume modeling triangulated against top-down market sizing across technology and end-user segments.
Input-output matrices mapped lead raw material flows through paste production, plate manufacturing, assembly, and collection stages across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user contracting structure, and regional production cluster. CAGRs derived from regression analysis of historical replacement cycle compression and stop-start system penetration curves, stress-tested against electrification scenario modeling.
Several conditions sit outside the modeled scope, including abrupt lithium cost declines accelerating commercial vehicle substitution, geopolitical disruption of North African lead concentrate supply, and unilateral member-state REACH enforcement variations. Forecasts reflect base-case assumptions on regulatory timeline adherence and fleet electrification pacing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Middle East and Africa Rechargeable Battery Market
Batteries
AAA Battery Market
Batteries
18650 And 21700 Battery Market
Batteries
Power Tool Batteries Market
Batteries
Atomic Battery Market
Batteries
Primary Lithium Battery Market
Batteries
Battery Diagnostics and Repair Market
Batteries
Asia-Pacific Battery Market
Batteries
Leisure Battery Market
Batteries
Southeast Asia Battery Market
Batteries
Asia-Pacific NMC Battery Pack Market
Batteries
Battery Binders Market
Batteries
Europe Battery Market
Batteries
Solid-State Car Battery Market
Batteries
Home Inverter Battery Market
Batteries
Portable Battery Pack Market