
 Second-Life Automotive Battery Module Systems Market | 2026-2036
Second-Life Automotive Battery Module Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Second-Life Automotive Battery Module Systems Market Insights
UL 1974 certification for repurposed battery systems is collapsing the field of qualified suppliers, forcing aspirants into expensive validation cycles that stretch engineering budgets. CATL leverages its original cell chemistry knowledge to sustain module-to-system integration advantages. LG Energy Solution anchors its second-life strategy through direct OEM partnerships that secure predictable feedstock volumes. Connected Energy competes on stationary system design, converting degraded automotive packs into containerized storage without full cell disassembly.
Second-life automotive battery module systems consist of retired electric vehicle battery packs that retain sufficient capacity for non-automotive duty cycles, typically operating at state-of-health thresholds of 70-80% with reconfigured battery management systems. These systems serve commercial and industrial energy storage, grid services, and backup power applications where weight and volumetric energy density matter less than cost per kilowatt-hour. Lithium-ion battery modules currently dominate installed capacity due to the surge of early-retirement EV packs from 2015-2020 model years. Energy storage systems applications capture the fastest growth trajectory as utility procurement standards increasingly accept certified second-life hardware alongside new cells. Stationary installations represent the mature deployment channel with established financing and insurance frameworks.
The EU Battery Regulation and REACH compliance frameworks impose traceability and hazardous substance constraints on module reprocessors selling into European markets. EPA hazardous waste determinations under RCRA in the United States create interstate transport complications for battery aggregators. Stakeholders must monitor how evolving fire safety codes for energy storage installations treat second-life systems differently from new battery hardware, as this classification will determine installation permitting timelines and insurance premiums.
Market Dynamics
The EU Battery Regulation's due diligence and recycled content mandates are forcing module reprocessors to restructure supplier relationships and validation workflows, compressing margins for unprepared operators while advantaging vertically integrated cell manufacturers with traceable feedstock.
Growth Catalysts
- Utility-scale storage procurement:Grid-balancing auctions in Germany and industrial park retrofits are creating concentrated demand pools for certified refurbished modules. Stationary energy storage deployments are accelerating as battery retirement volumes climb from early EV fleets.
- REACH compliance frameworks:European hazardous substance constraints are creating competitive moats for reprocessors with established traceability systems. Compliant operators capture premium placement in EU member state tenders.
- State-of-health screening advances:Automated diagnostic protocols for 70-80% capacity thresholds are reducing module grading costs. This process improvement expands economically viable feedstock pools for system integrators.
Market Restraints
- UL 1974 certification costs:Expensive validation cycles are collapsing the field of qualified suppliers and stretching engineering budgets for aspirant reprocessors. Fewer certified players concentrate supply-side power.
- Interstate transport complications:EPA hazardous waste determinations under RCRA create friction for battery aggregators moving feedstock across US state lines. Regulatory fragmentation raises logistics costs.
- New cell price compression:Declining lithium-ion manufacturing costs threaten second-life cost advantages in price-sensitive backup power segments. Original equipment buyers face switching incentives.
Strategic Opportunities
- Containerized storage without full disassembly:Module-to-system integration approaches that bypass cell-level rework are opening margins in utility procurement. Design-focused competitors are capturing this white space.
- Direct OEM partnership models:Feedstock security agreements with vehicle manufacturers are creating predictable volume pipelines. Early movers in partnership structures are locking out later entrants.
- Fire safety code differentiation:Evolving installation standards for second-life systems present positioning opportunities for certified operators. Favorable classification would compress permitting timelines and insurance premiums.
Industry Challenges
- Battery management system reconfiguration:Adapting degraded automotive pack electronics to stationary duty cycles requires specialized firmware engineering. Talent scarcity in this function is constraining throughput.
- Financing and insurance framework gaps:Underdeveloped risk assessment tools for second-life assets are limiting project finance availability. Lenders demand performance guarantees that erode project returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Second-Life Automotive Battery Module Systems Market |
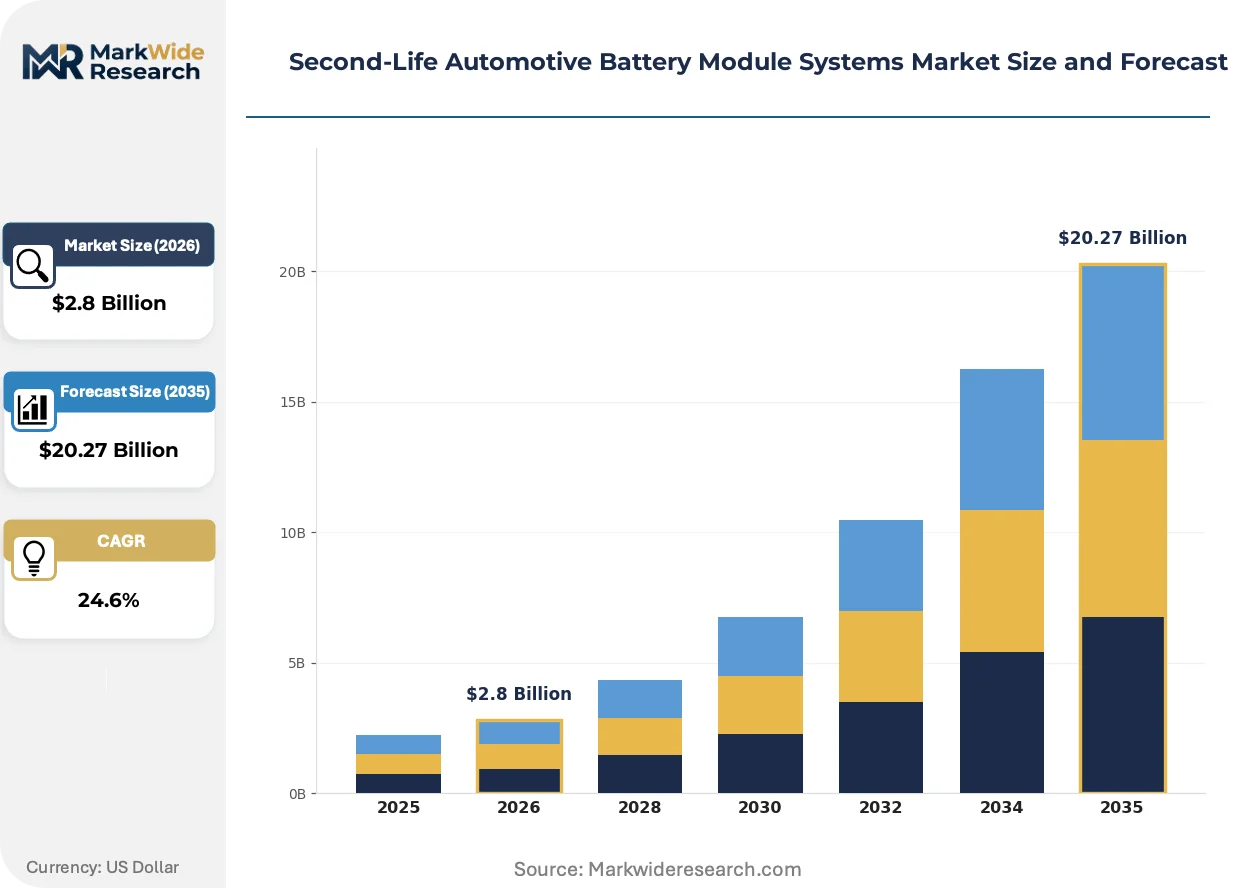
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.27 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion Battery Modules, Nickel-Metal Hydride Modules, Lead-Acid Battery Packs, Solid-State Battery Cells Application: Energy Storage Systems, Backup Power Supply, Renewable Integration, Grid Balancing, Off-Grid Power End User Industry: Electric Vehicle Manufacturers, Renewable Power Providers, Telecommunications, Data Centers, Industrial Automation Deployment Type: Stationary Installations, Mobile Units, Residential Systems, Commercial Facilities, Utility Scale |
| Companies Covered | CATL, BYD, LG Energy Solution, Tesla, Renault Group, Nissan Motor, Volkswagen AG, Umicore, Connected Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Second-Life Automotive Battery Module Systems Market Trends and Innovations
Automated state-of-health diagnostics and modular system architectures are compressing reprocessing timelines while regulatory pressure on supply chain traceability is forcing technology investments across the value chain.
Direct-module reuse architectures are decomposing the traditional cell-extraction model for second-life battery preparation. Utility-scale developers in Germany and the Netherlands are adopting containerized designs that preserve original module structures. This approach is decomposing capital requirements for entry-level reprocessors and shifting competitive advantage toward system design capabilities rather than cell chemistry expertise.
REACH substance restrictions and the EU Battery Regulation's recycled content mandates are tightening compliance burdens on module reprocessors selling into European markets. Industrial consequence includes mandatory supply chain documentation and due diligence obligations that favor large operators with established traceability systems. German and French industrial park retrofits are most affected, with procurement specifications now requiring certified origin documentation.
Buyer preference is rotating toward certified second-life hardware in utility procurement standards. Traditional new-cell suppliers face displacement in grid services tenders where cost-per-kilowatt-hour dominates weight and density considerations. This pattern is most visible in Germany's grid-balancing auction structures, where refurbished module bids are achieving price parity with new lithium-ion alternatives.
Second-Life Automotive Battery Module Systems Market Segmentation
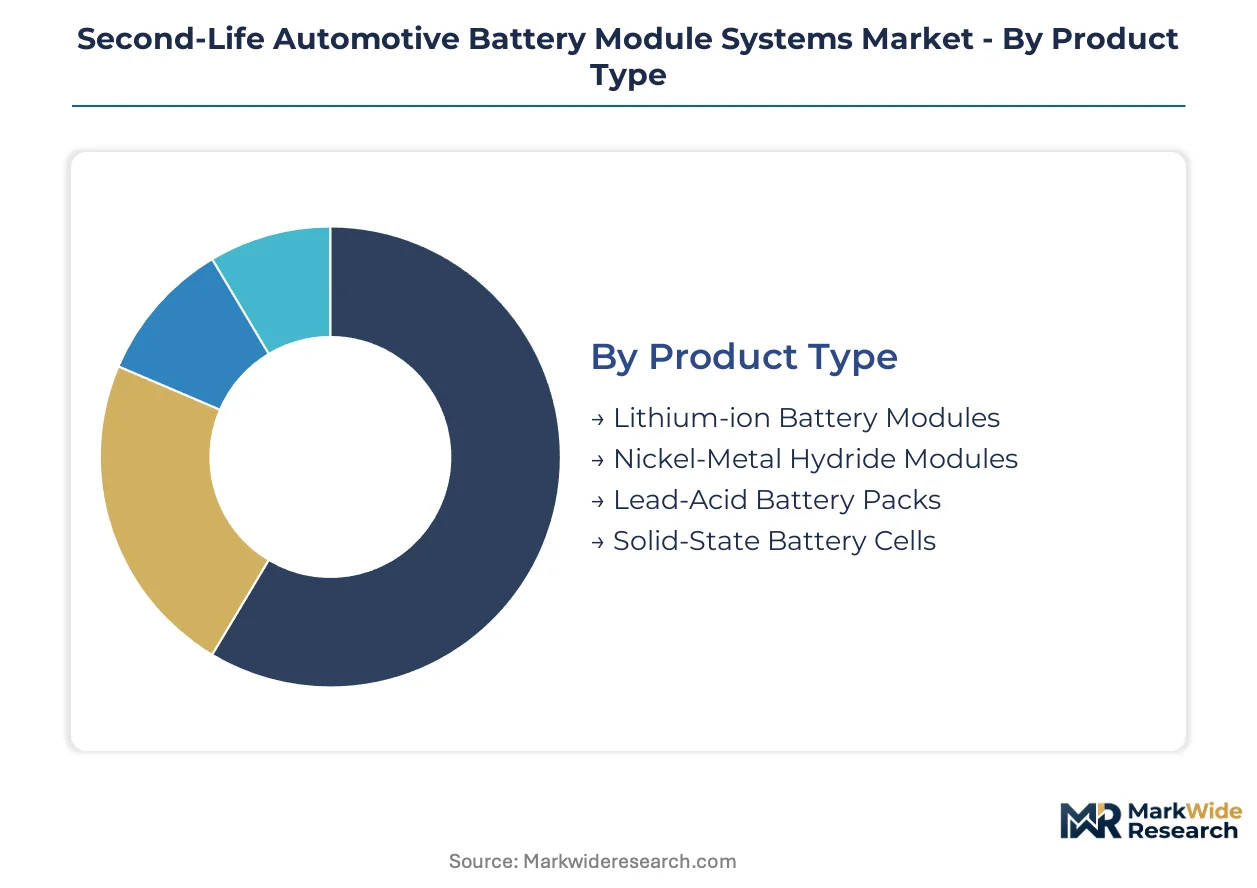
Segmentation reveals where substitute threats and regulatory pressures concentrate competitive risk. Each dimension exposes different vulnerability profiles for module reprocessors and system integrators.
Product Type:
Substitute pressure from new cell price compression falls unevenly across chemistry categories, with some legacy formats facing existential displacement while others retain defensible niches.
- Lithium-ion Battery Modules:Retired EV packs with 70-80% state-of-health dominate feedstock availability. Demand concentrates in Germany's grid-balancing auctions where certified refurbished modules achieve price parity with new alternatives.
- Nickel-Metal Hydride Modules:Legacy hybrid vehicle batteries retain marginal utility for low-cycling backup applications. Procurement pools are shrinking as automotive OEMs phase out NiMH production platforms.
- Lead-Acid Battery Packs:Mature recycling infrastructure and low raw material costs sustain cost-sensitive telecom backup deployments.
- Solid-State Battery Cells:Minimal commercial feedstock exists as next-generation chemistries remain in early production ramp.
Lithium-ion Battery Modules retain volume leadership; Solid-State Battery Cells hold the steepest expansion curve contingent on manufacturing scale breakthroughs.
Application:
Margin structures diverge sharply between regulated grid services and unregulated behind-the-meter installations, reshaping where reprocessors allocate engineering resources.
- Energy Storage Systems:Containerized stationary installations capture procurement volume from utility-scale developers. Germany and Netherlands project pipelines favor certified second-life hardware with UL 1974 validation.
- Backup Power Supply:Industrial facilities and critical infrastructure operators specify refurbished modules for cost reduction. REACH compliance documentation is becoming mandatory for European tender participation.
- Renewable Integration:Solar and wind pairing applications require cycling durability that degraded automotive cells struggle to guarantee.
- Grid Balancing:Frequency regulation services demand rapid response capabilities with stringent fire safety certification.
- Off-Grid Power:Remote installations prioritize acquisition cost over cycle life, exposing second-life systems to new cell price competition.
Energy Storage Systems command the dominant revenue share; Grid Balancing applications are climbing fastest as auction structures mature.
End User Industry:
Customer sophistication varies dramatically, with some sectors demanding full traceability while others prioritize unit economics above certification depth.
- Electric Vehicle Manufacturers:OEMs are emerging as feedstock suppliers rather than buyers, securing partnership agreements with reprocessors for predictable volume offtake. Direct OEM relationships are locking out later market entrants.
- Renewable Power Providers:Utility-scale solar and wind developers integrate second-life storage for smoothing output variability. Procurement specifications increasingly require EU Battery Regulation compliance documentation.
- Telecommunications:Tower operators specify refurbished modules for backup power where weight and density constraints are minimal.
- Data Centers:Mission-critical facilities demand performance guarantees that underdeveloped risk assessment tools struggle to underwrite.
- Industrial Automation:Manufacturing facilities adopt containerized storage for peak shaving and demand charge management.
Renewable Power Providers anchor current procurement volumes; Data Centers are gaining share fastest as insurance frameworks mature.
Deployment Type:
Installation complexity and permitting burden scale non-linearly with system size, compressing margins for small-scale operators while concentrating supply-side power among certified large-scale integrators.
- Stationary Installations:Fixed containerized systems represent the mature deployment channel with established financing frameworks. Fire safety code classification for second-life hardware determines insurance premium structures.
- Utility Scale:Grid-connected megawatt-hour installations require specialized firmware engineering for battery management system reconfiguration. Talent scarcity in this function is constraining throughput.
- Mobile Units:Transportable systems serve construction sites and temporary power applications with lower certification barriers.
- Commercial Facilities:Industrial park retrofits in Germany and France create concentrated demand pools for refurbished modules.
- Residential Systems:Behind-the-meter installations face switching incentives from declining new lithium-ion manufacturing costs.
Stationary Installations maintain volume dominance; Utility Scale deployments are expanding most quickly as auction structures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's high-voltage grid interconnects with Scandinavian and Alpine pumped-storage reservoirs anchor Europe's second-life battery arbitrage opportunities. The Port of Rotterdam's containerized battery logistics infrastructure underwrites Benelux reprocessing scale. China's ultra-high-voltage transmission corridors from Xinjiang to coastal load centers create interprovincial storage procurement at gigawatt-hour scale.
Germany
Grid-balancing auctions through the Federal Network Agency and industrial park retrofits in North Rhine-Westphalia concentrate procurement volumes. The EU Battery Regulation's due diligence mandates are reshaping supplier validation workflows for reprocessors serving German tenders. The Ruhr industrial corridor hosts containerized storage deployments converting retired automotive packs without full cell disassembly.
United States
ERCOT frequency regulation markets in Texas and CAISO resource adequacy mechanisms in California drive utility-scale procurement. EPA hazardous waste determinations under RCRA create interstate transport friction for battery aggregators moving feedstock across state lines. The Midwest manufacturing belt spanning Michigan and Ohio generates concentrated automotive retirement volumes for regional reprocessors.
China
Dual carbon goals and provincial renewable integration mandates accelerate stationary storage deployments in Jiangsu and Guangdong. MIIT battery traceability standards impose documentation burdens on module reprocessors serving state-owned utility procurement. The Yangtze River Delta cluster around Shanghai hosts integrated cell-to-system operators leveraging original chemistry knowledge for second-life integration.
Netherlands
Port of Rotterdam battery logistics infrastructure and North Sea offshore wind pairing requirements create demand for certified refurbished modules. REACH compliance frameworks and ECHA substance restrictions favor reprocessors with established European traceability systems. The Eindhoven high-tech cluster anchors system design capabilities for containerized storage without full disassembly.
Japan
METI stationary storage subsidies and grid stabilization requirements for renewable integration drive procurement from early-retirement EV fleets. JIS standards for repurposed battery systems create certification barriers that concentrate supply-side power among qualified integrators. The Kanto region around Tokyo hosts automotive OEM partnership models securing predictable feedstock pipelines.
Second-Life Automotive Battery Module Systems Market Competitive Landscape
Listed leaders compete with private specialists across capital access and feedstock security dimensions, producing a tiered structure where scale advantages concentrate among integrated cell manufacturers. The vendor base stratifies between original equipment producers with captive retirement volumes and independent reprocessors competing on system design capabilities. Three archetypes dominate: vertically integrated cell-to-system operators, OEM-captive partnership models, and design-focused containerized storage specialists. M&A activity targets feedstock security agreements, while capacity expansion concentrates in regions with favorable fire safety code classification for second-life hardware.
Within the integrated cell-to-system tier, CATL and BYD occupy positions anchored by original chemistry knowledge that sustains module-to-system integration advantages. LG Energy Solution exemplifies the OEM-captive archetype through partnership structures that secure predictable automotive retirement volumes. Connected Energy represents the design-focused specialist model, competing on containerized system architectures that bypass cell-level rework entirely.
| Leading Market Players |
|---|
| CATL |
| BYD |
| LG Energy Solution |
| Tesla |
| Renault Group |
| Nissan Motor |
| Volkswagen AG |
| Umicore |
| Connected Energy |
| Others |
Pricing and Supply Chain Analysis
UL 1974 certification gates both supply qualification and price differentiation simultaneously, compressing the field of qualified reprocessors while enabling certified operators to command premiums in German grid-balancing auctions and Dutch industrial tenders. The regulatory burden concentrates pricing power among vertically integrated cell manufacturers with traceable feedstock, while aspirants face stretched engineering budgets that erode margin flexibility.
Pricing Analysis
Volume-discount tiering structures separate UL 1974-validated premium modules from standard-grade refurbished units and uncertified economy feedstock. Price differentiation hinges on certification grade and geographic delivery cost to utility-scale developers. Cost compression in the economy tier intensifies because new lithium-ion manufacturing costs threaten second-life alternatives. Backup power buyers exhibit highest price sensitivity, while grid-balancing procurement demonstrates lowest sensitivity due to total-cost-of-ownership calculations.
Supply Chain Analysis
Port congestion at Rotterdam and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for module aggregators sourcing retired automotive packs. Feedstock concentrates in Germany, China, and the United States where early EV retirement volumes cluster. The supply chain rests on lithium carbonate, nickel sulfate, and cobalt hydroxide inputs tied to cell chemistry knowledge. Single-source vulnerability from OEM-captive feedstock agreements dominates structural risk. Distribution runs through specialized battery logistics providers with hazardous material certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Second-life automotive battery module systems represent an early-cycle expansion story as utility procurement standards increasingly accept certified refurbished hardware alongside new cells. Battery retirement volumes from 2015-2020 model year EV fleets provide the adoption tailwind accelerating procurement pipeline formation.
For Market Incumbents: Compound feedstock security through direct OEM partnership structures that lock in predictable automotive retirement volumes before competitors establish relationships. Invest in UL 1974 certification expansion to defend against substitute threats from declining new cell prices. Prioritize firmware engineering talent acquisition to overcome battery management system reconfiguration bottlenecks constraining throughput. For New Entrants and Emerging Players: Differentiate on containerized storage system design capabilities that bypass cell-level rework entirely, capturing white space in utility-scale procurement where module-to-system integration advantages matter most. Target German industrial park retrofits and Netherlands offshore wind pairing requirements as the most penetrable geographies. Pursue design-focused partnerships with established traceability systems to overcome REACH compliance barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across utility-scale system integration as containerized storage deployments require specialized firmware engineering and fire safety certification investments. Long-term viability favors acquisition targets with established OEM feedstock agreements and UL 1974 validation credentials. Watch German Federal Network Agency auction participation rates as the inflection indicator signaling certified second-life hardware acceptance.| Strategic Initiative | Industry Significance |
|---|---|
| UL 1974 Certification Expansion | Validates repurposed battery systems for German grid-balancing auctions and Dutch utility tenders. |
| Direct OEM Partnership Agreements | Secures predictable feedstock pipelines from automotive manufacturers retiring early EV fleets. |
| Containerized Storage System Design | Enables module-to-system integration without cell-level rework, compressing capital requirements. |
| Battery Management System Reconfiguration | Adapts degraded automotive pack electronics to stationary duty cycles with specialized firmware. |
| REACH Compliance Documentation Systems | Mandatory for European tender participation and creates competitive moats against unprepared operators. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility procurement officers, automotive OEM sustainability directors, module reprocessing plant managers, and battery management system firmware engineers. Secondary validation drew from EU Battery Regulation documentation, EPA RCRA hazardous waste determinations, MIIT battery traceability standards, and FERC interconnection queue data. Bottom-up feedstock volume estimates and top-down utility procurement forecasts were triangulated to anchor projections.
Across the analysis window, the forecasting framework modeled product type segmentation by chemistry format, application segmentation by duty cycle intensity, end user industry segmentation by procurement sophistication, and deployment type segmentation by installation scale. CAGRs were derived from regression analysis against EV fleet retirement curves and utility storage procurement pipelines. State-of-health screening cost trajectories and fire safety code evolution served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued EU Battery Regulation enforcement and stable lithium-ion raw material pricing; material deviation would warrant model refresh. Specific risk factors include accelerated new cell price compression, restrictive fire safety reclassification of second-life systems, and OEM vertical integration into reprocessing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
East Africa Battery Market
Batteries
Rear Rack Battery Market
Batteries
Rechargeable Coin Cell Market
Batteries
Elastic Battery Binders Market
Batteries
FORTELION Battery Module Market
Batteries
Southeast Asia Battery Market
Batteries
Smart Battery Market
Batteries
Industrial Battery Charger Market
Batteries
Primary Lithium Battery Market
Batteries
Battery Pack Balancer Market
Batteries
South America Rechargeable Battery Market
Batteries
Myanmar Battery Market
Batteries
Vietnam Battery Market
Batteries
Marine Powerboat Battery Market
Batteries
Stationary Lead-Acid Battery Market