
 Zinc Carbon Battery Market | 2026-2036
Zinc Carbon Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Carbon Battery Market Analysis
Market Context
Multi-pack blister configurations is realigning retail shelf strategy and buyer choice in zinc carbon batteries. Eveready Industries India Ltd. dominates the South Asian mass-market channel through extensive rural distribution networks. Panasonic Corporation leverages its component supply chain to sustain cost leadership in standard-duty cell production. Varta AG specializes in European private-label contracts and controls shelf positioning through retail partnerships.
Technical Definition and Segments
Zinc carbon batteries employ a zinc anode, manganese dioxide cathode, and ammonium chloride or zinc chloride electrolyte in a zinc canister housing, delivering nominal voltages of 1.5V with moderate energy density suited for intermittent low-drain devices. Standard zinc carbon cells occupy the mature volume tier where margin compression is most severe, while zinc chloride formulations capture premium positioning in tropical climates due to superior leak resistance. The consumer electronics end-user segment anchors replacement-cycle demand, whereas educational institutions and industrial equipment represent smaller but more stable procurement pools with longer contract horizons.
Regulatory Frame
India's BIS mandates and the EU's REACH chemicals framework constrain electrolyte formulations and canister material specifications, while the RoHS directive limits heavy metal content in cells sold across European markets. These standards elevate compliance costs for exporters but simultaneously filter out subscale producers unable to fund certification pathways. Stakeholders must monitor evolving state-level e-waste collection mandates that could impose end-of-life fees and reshape packaging economics.
Market Dynamics
India's BIS certification tightening is compressing import volumes and forcing domestic capacity expansion across South Asian manufacturing clusters. This regulatory pressure is accelerating supply chain reconfiguration as regional producers absorb demand previously served by uncertified overseas suppliers.
Growth Catalysts
- Flashlight OEM Sourcing:Southeast Asian manufacturing clusters for portable lighting equipment sustain bulk procurement volumes. Vietnamese and Indonesian assembly plants anchor replacement-cycle demand for standard-duty cells.
- REACH Compliance Filter:The EU's chemicals framework elevates production standards for electrolyte formulations. Subscale exporters exit European distribution channels, clearing shelf space for certified suppliers.
- Rural Electrification Gaps:Unreliable grid infrastructure across South Asian and African markets perpetuates dependence on battery-powered devices. Low-drain consumer electronics procurement remains inelastic in these geographies.
Market Restraints
- Zinc Price Volatility:Raw material cost swings in London Metal Exchange zinc contracts compress margin predictability for canister production. Smaller cell assemblers lack hedging capacity.
- Alkaline Substitution:Longer shelf life and higher energy density in alkaline manganese dioxide chemistry displace zinc carbon in mid-tier retail positioning. Price-sensitive segments remain the final refuge.
- Single-Source Electrolyte Supply:Ammonium chloride procurement concentrates among Chinese specialty chemical producers. Geographic concentration risk elevates input security concerns for non-integrated battery manufacturers.
Strategic Opportunities
- Sub-Saharan Distribution Gaps:Underdeveloped retail infrastructure in Nigeria and Kenya creates whitespace for mobile vendor networks. Direct-to-consumer battery packs bypass formal channel constraints.
- EU E-Waste Collection Mandates:Extended producer responsibility frameworks incentivize modular cell designs with recyclable canister housing. Compliance-ready packaging commands retail preferencing.
- Zinc Chloride Tropical Positioning:Superior leak resistance in high-humidity climates enables premium tiering against standard formulations. Southeast Asian and Latin American markets show receptivity to performance-differentiated SKUs.
Industry Challenges
- BIS Certification Timeline Compression:India's accelerated testing protocols for dry cell imports strain documentation capacity. Exporters face working capital pressure from extended customs clearance cycles.
- Legacy Equipment Integration:Automated winding and sealing equipment from prior decades lacks compatibility with modified electrolyte viscosity requirements. Retooling capex demands collide with compressed unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Carbon Battery Market |
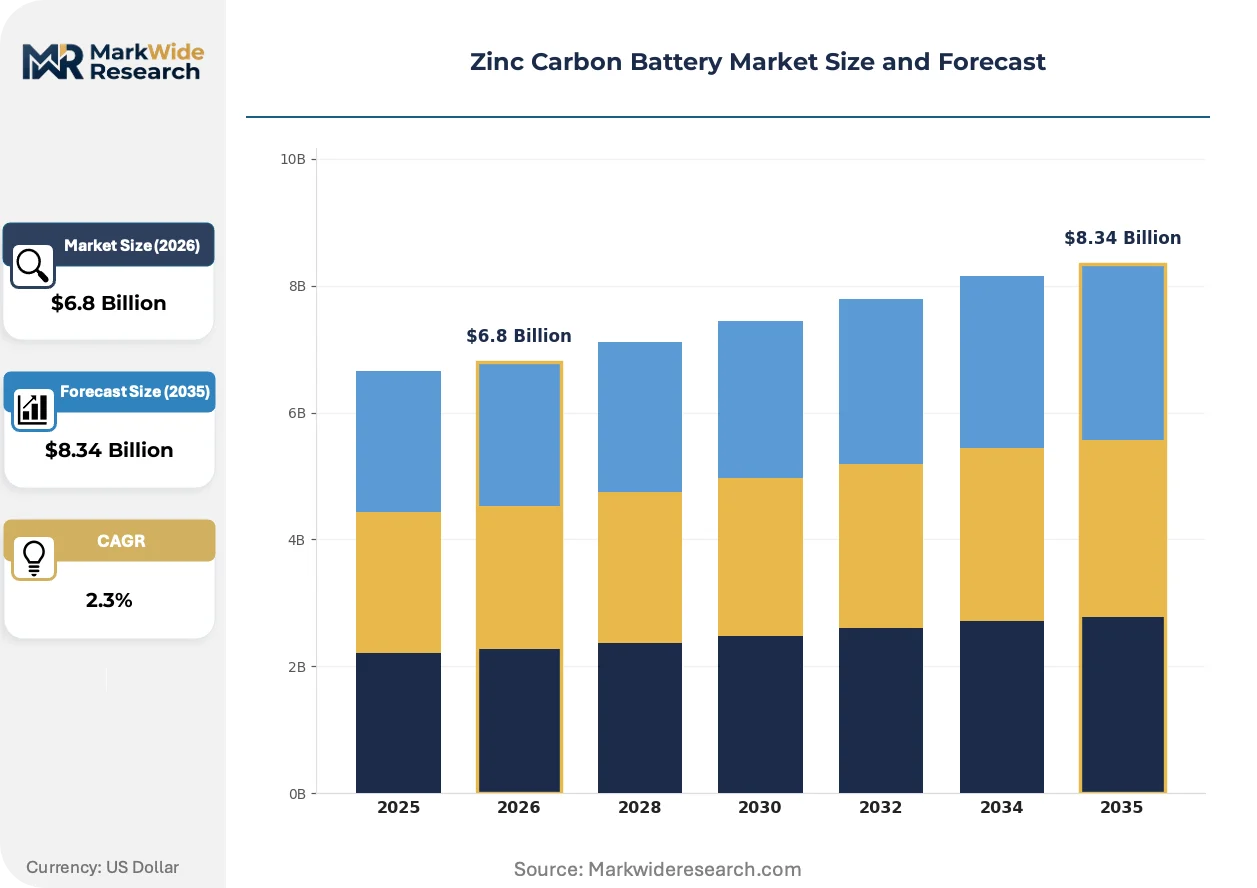
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $8.34 Billion |
| CAGR (2026 – 2036) | 2.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Zinc Carbon, Zinc Chloride, Heavy Duty, Super Heavy Duty, Alkaline Zinc Carbon Application: Flashlights, Portable Radios, Remote Controls, Clocks, Toys, Home Appliances End User: Consumer Electronics, Educational Institutions, Industrial Equipment, Automotive Accessories, Military Devices Packaging Type: Blister Pack, Bulk Packaging, Shrink Wrap, Cardboard Box, Plastic Container |
| Companies Covered | Eveready Industries India Ltd., Toshiba Corporation, Duracell Inc., Rayovac, Varta AG, Energizer Holdings, Inc., GP Batteries International Limited, Nippo Batteries Co. Ltd., Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Carbon Battery Market Emerging Trajectories
Electrolyte formulation advances and packaging automation are compressing production cost curves while regulatory chemistry constraints reshape competitive positioning. These forces are simultaneously enabling premium tier creation and threatening volume-tier viability.
Automated electrode winding and cell assembly systems are automating labor-intensive production stages previously dominant in emerging market facilities. Malaysian and Thai battery plants are deploying robotic stacking equipment at accelerating rates. This capital intensity is automating margin recovery for mid-scale producers while marginalizing manual-assembly operations.
India's BIS certification requirements for dry cell batteries are mandating electrolyte purity standards and canister material specifications that exceed prior import thresholds. The Central Electricity Authority's testing protocols now reject shipments from uncertified overseas facilities. Small-scale importers are exiting the market while domestic manufacturers absorb displaced volume.
Multi-pack blister configurations are displacing loose-cell counter sales across modern trade retail formats. Convenience store chains and supermarket battery sections now favor hanging display units over bulk bin presentations. This packaging evolution concentrates procurement authority with branded suppliers capable of shelf-ready merchandising support.
Zinc Carbon Battery Market Segmentation
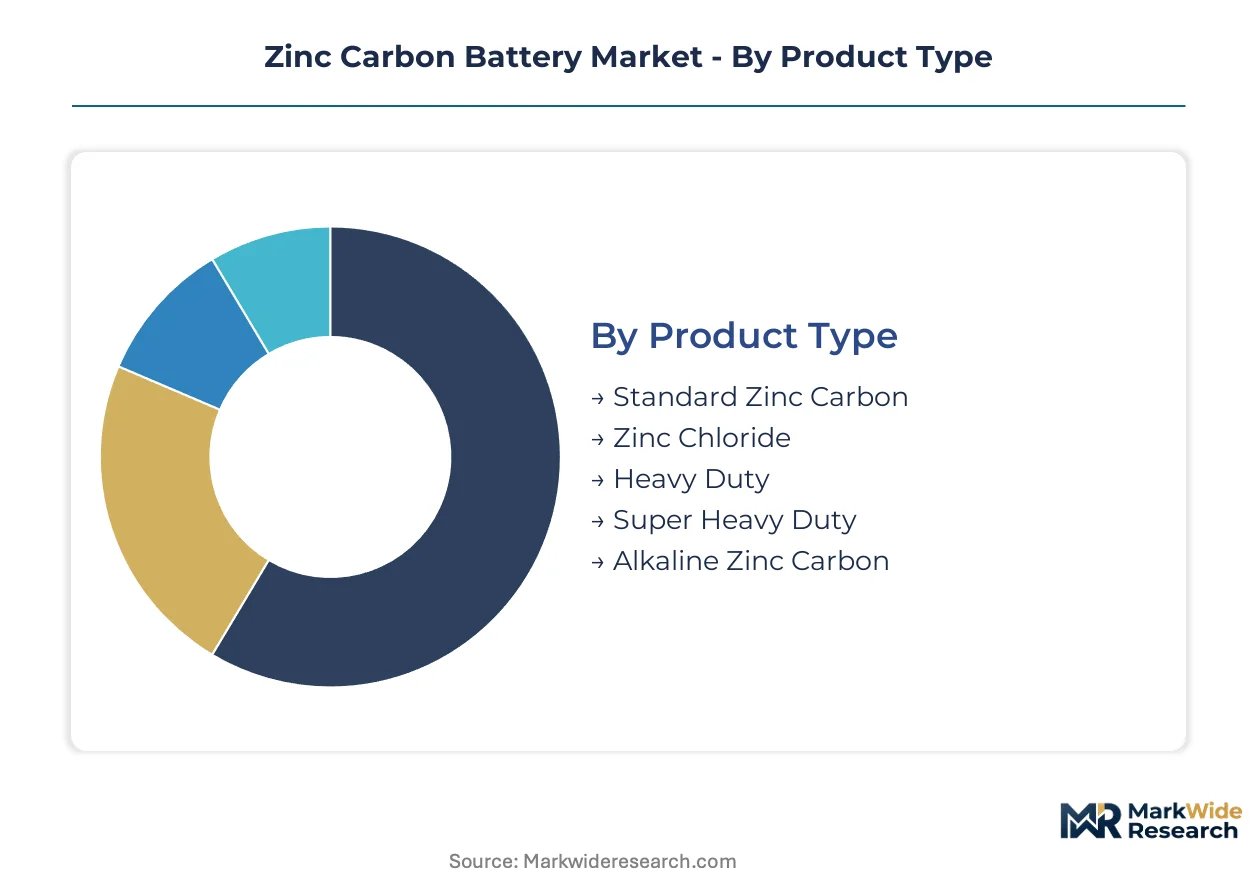
Zinc carbon battery procurement patterns diverge sharply across product chemistry, device compatibility, and channel format. Understanding these segment boundaries clarifies where margin compression concentrates versus where formulation premiums sustain profitability.
Product Type:
Supply concentration among Southeast Asian electrolyte specialists favors manufacturers with backward integration into ammonium chloride sourcing.
- Standard Zinc Carbon:Ammonium chloride electrolyte delivers 1.5V nominal output with moderate shelf stability. Indian mass-market retail and African informal trade absorb the highest procurement volumes where absolute unit cost dominates purchase decisions.
- Zinc Chloride:Zinc chloride electrolyte replaces ammonium chloride for superior leak resistance in tropical humidity. Southeast Asian flashlight OEMs and Latin American distributors pay formulation premiums for reduced corrosion failure rates in high-moisture environments.
- Heavy Duty:Enhanced manganese dioxide loading extends service life in moderate-drain devices. South Asian clock and radio manufacturers specify these cells for warranty-sensitive applications.
- Super Heavy Duty:Maximum cathode density targets intermittent high-drain pulses. Emergency lighting equipment in India's commercial buildings drives concentrated demand.
- Alkaline Zinc Carbon:Hybrid chemistry bridges alkaline performance with carbon zinc cost structures. Limited production runs serve niche military specification contracts.
Standard Zinc Carbon absorbs the bulk of installed capacity; Zinc Chloride is expanding most quickly.
Application:
Device power requirements and replacement frequency determine which chemistry tier captures each application segment.
- Flashlights:Portable lighting demands reliable low-drain output across temperature extremes. Vietnamese and Indonesian assembly plants source standard-duty cells in bulk for export markets.
- Portable Radios:Extended listening sessions favor higher capacity formulations. Rural African markets without grid access sustain steady replacement cycles.
- Remote Controls:Ultra-low drain profiles match standard zinc carbon economics perfectly. Indian urban households generate volume through multi-device ownership.
- Clocks:Continuous trickle discharge demands leak-proof sealing. Wall clock manufacturers in China's Pearl River Delta specify zinc chloride for tropical export destinations.
- Toys:Seasonal demand spikes align with holiday procurement calendars. Southeast Asian toy factories concentrate orders in Q3 for Western market distribution.
- Home Appliances:Smoke detectors and emergency devices require decade-long shelf stability. This application faces alkaline substitution pressure in developed markets.
Remote Controls and Flashlights together anchor volume procurement; Clocks and Toys show the steepest expansion trajectory in emerging market channels.
End User:
Procurement authority and contract structure vary dramatically across institutional versus consumer purchasing.
- Consumer Electronics:Replacement-cycle demand from individual households dominates absolute volume. Modern trade retail in India and Southeast Asia concentrates purchasing through branded multi-pack formats.
- Educational Institutions:Science laboratory equipment and demonstration kits require consistent voltage output. Indian state education boards issue annual tenders with 12-month delivery windows.
- Industrial Equipment:Backup power for instrumentation demands certified reliability. EU REACH compliance filters supplier eligibility for European manufacturing customers.
- Automotive Accessories:Tire pressure monitors and emergency tools tolerate moderate performance specifications. Aftermarket channels in Latin America favor cost-optimized standard cells.
- Military Devices:Specification-grade requirements demand traceable supply chains. Limited volume but premium pricing sustains specialized production lines.
Consumer Electronics commands the dominant share of manufacturing output; Educational Institutions provide the most predictable contract horizons.
Packaging Type:
Channel format and retail density determine packaging configuration economics.
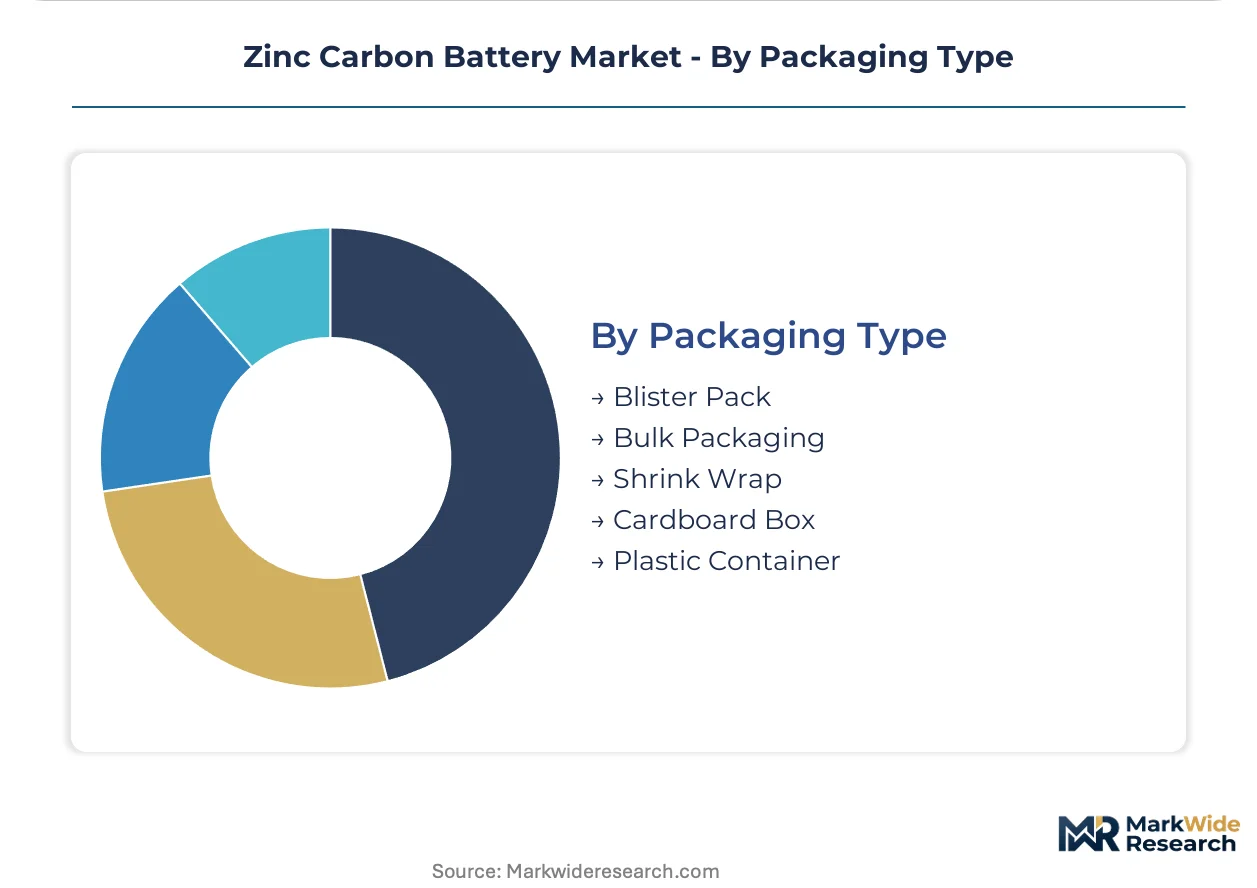
- Blister Pack:Hanging display compatibility drives modern trade penetration. Indian supermarket chains now mandate shelf-ready blister formats for battery category resets.
- Bulk Packaging:Loose-cell cartons serve traditional counter sales. African informal retail and Indian kirana stores continue bulk procurement for price-sensitive customers.
- Shrink Wrap:Multi-cell bundles balance display impact with material cost. Southeast Asian convenience chains favor four-cell and eight-cell configurations.
- Cardboard Box:Institutional tenders specify recyclable outer packaging. Indian government procurement mandates biodegradable secondary packaging.
- Plastic Container:Reusable storage appeals to household stockpiling behavior. Premium positioning in Middle Eastern retail commands higher shelf prices.
Blister Pack configurations are gaining share fastest in organized retail; Bulk Packaging retains dominance in informal trade corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Vietnam and Indonesia concentrate flashlight OEM assembly, driving bulk zinc carbon procurement across Southeast Asian manufacturing corridors. India's BIS-certified domestic capacity absorbs import displacement from tightened certification timelines. African informal trade channels sustain loose-cell distribution outside formal retail infrastructure.
India
Rural electrification gaps perpetuate flashlight and clock battery demand across Bihar and Uttar Pradesh. BIS certification mandates under the Central Electricity Authority now reject uncertified import shipments. Domestic manufacturers in Tamil Nadu and Gujarat expand canister production to capture displaced overseas supply.
Vietnam
Ho Chi Minh City assembly plants source standard-duty cells for export-bound portable lighting equipment. The Ministry of Industry and Trade enforces product safety labeling for battery imports entering modern retail channels. Binh Duong Province industrial parks concentrate robotic electrode winding investments from regional battery producers.
Indonesia
Jakarta and Surabaya manufacturing clusters anchor replacement-cycle demand for tropical-grade zinc chloride formulations. National standards agency SNI certification requirements elevate electrolyte purity thresholds for imported cells. Batam free trade zone facilities re-export packaged cells to Middle Eastern markets with reduced tariff exposure.
Nigeria
Lagos and Kano distribution hubs sustain mobile vendor networks bypassing underdeveloped formal retail. The Standards Organisation of Nigeria enforces pre-shipment inspection for battery imports through Apapa port. Onitsha market traders consolidate bulk loose-cell procurement for redistribution across West African hinterlands.
Germany
Private-label contract manufacturing serves EU REACH-compliant retail chains across North Rhine-Westphalia. ECHA chemical registration requirements constrain electrolyte formulation flexibility for non-integrated importers. Bavarian industrial distributors coordinate just-in-time replenishment for automotive aftermarket battery programs.
Zinc Carbon Battery Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Panasonic Corporation and Toshiba Corporation leverage electronics component supply chains to sustain cost leadership in high-volume cell production. Varta AG and Energizer Holdings occupy branded retail positioning through shelf-space negotiations. Competitive moves concentrate on automated assembly deployment and multi-pack packaging format standardization.
Within the diversified conglomerate tier, Panasonic Corporation and Toshiba Corporation represent scale-driven archetypes with captive component sourcing. Eveready Industries India Ltd. exemplifies the geography-focused specialist model through extensive rural distribution reach. Varta AG occupies the European private-label contract position, anchoring retail partnership structures for supermarket and hardware channel placement.
| Leading Market Players |
|---|
| Eveready Industries India Ltd. |
| Toshiba Corporation |
| Duracell Inc. |
| Rayovac |
| Varta AG |
| Energizer Holdings, Inc. |
| GP Batteries International Limited |
| Nippo Batteries Co. Ltd. |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
EU REACH chemical registration mandates gate qualified supply access and premium-tier pricing eligibility for zinc carbon battery exporters serving European retail channels. BIS certification timelines in India simultaneously constrain import arbitrage and sustain domestic price premiums for certified local production.
Pricing Analysis
Margin tightening in standard-grade cells reflects zinc price volatility on London Metal Exchange contracts and alkaline substitution pressure in mid-tier retail positioning. Three-tier pricing structure across zinc chloride premium, heavy-duty standard, and economy standard formulations segments buyer archetypes by climate exposure and device criticality. Cost-down pressure accelerates as Vietnamese flashlight OEMs consolidate procurement volumes and demand volume rebates. Price-sensitive informal trade channels in Nigeria and Kenya absorb economy-grade loose cells, while EU REACH-compliant distributors pay premiums for certified zinc chloride formulations.
Supply Chain Analysis
Single-source vulnerability sits with Chinese specialty chemical producers dominating ammonium chloride electrolyte supply. Canister production draws from zinc smelter output concentrated in China, India, and South Korea. Raw material dependencies span manganese dioxide cathode powders, zinc canister sheet, and electrolyte-grade ammonium chloride. Geographic concentration risk elevates input security concerns for non-integrated battery manufacturers. Distribution runs through Southeast Asian manufacturing clusters for OEM bulk sourcing, Indian modern trade retail for branded multi-packs, and African informal vendor networks for loose-cell redistribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIS-certified domestic capacity expansion in India represents the binding supply constraint sustaining price premiums for compliant manufacturers.
For Market Incumbents: Anticipate alkaline chemistry substitution by securing zinc chloride formulation patents and tropical climate positioning. Deepen backward integration into electrolyte sourcing to offset single-supplier vulnerability from Chinese ammonium chloride concentration. Expand robotic winding deployment in Tamil Nadu and Gujarat facilities to defend unit economics against margin compression. For New Entrants and Emerging Players: Launch via mobile vendor networks in Nigerian and Kenyan distribution corridors where formal retail penetration remains underdeveloped. Target zinc chloride premium tiering in Indonesian and Vietnamese tropical markets with humidity-resistant positioning. Pursue private-label contracts with Middle Eastern retailers seeking recyclable canister packaging for EU e-waste compliance. For Investors and Strategic Acquirers: BIS certification queue clearance acceleration is the leading indicator that Indian domestic capacity absorption is reaching equilibrium. Five-to-ten year viability hinges on electrolyte formulation adaptability under tightening chemical registration frameworks. Acquisition targets should demonstrate REACH-compliant supply chains and automated electrode winding capability. Monitor SNI certification adoption rates in Indonesia as signal for Southeast Asian regulatory convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Backward Integration | Captive ammonium chloride sourcing insulates margin from Chinese supplier concentration risk. |
| Automated Electrode Winding Deployment | Robotic assembly in Malaysian and Thai plants compresses labor cost curves for mid-scale producers. |
| Zinc Chloride Tropical Positioning | Leak-resistant formulations command premium tiering in Indonesian and Latin American humidity exposure. |
| BIS Certification Pre-Investment | Early compliance with Central Electricity Authority protocols secures customs clearance speed advantage. |
| Modular Recyclable Canister Design | EU extended producer responsibility frameworks reward compliance-ready packaging with retail preferencing. |
Methodological Framework
Independent corroboration across battery plant managers, OEM procurement leads at flashlight manufacturers, retail category buyers, and electrolyte chemical specialists underwrites the qualitative findings. Primary fieldwork combined with secondary validation from BIS certification registries, REACH chemical substance databases, customs trade flow records, and SEC filings from diversified battery producers. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Comparable-period anchoring to historical BIS import rejection rates and zinc price volatility bands structured the forecast window. Segmentation dimensions span electrolyte chemistry tier, device application category, end-user procurement structure, and packaging format. CAGRs derive from installed capacity trajectories, replacement-cycle frequency by application, and regulatory-driven import displacement patterns. Zinc price futures curves and OEM inventory cycle data inform margin compression assumptions.
Raw material cost spikes, regulatory timeline acceleration, and alkaline substitution velocity are the dominant revision risks. Forecasts reflect documented assumptions about certification queue clearance rates and rural electrification gap persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
South Europe Battery Market
Batteries
Battery Wash System Market
Batteries
SLI Battery Market
Batteries
Cobalt-Free Battery Market
Batteries
Heavy-Duty Truck Megapack Battery Systems Market
Batteries
N-Type Battery Market
Batteries
Battery Separators Market
Batteries
Battery Simulator Market
Batteries
Europe Consumer Battery Market
Batteries
Zinc Ion Batteries Market
Batteries
Lithium Battery Testing System Market
Batteries
Proton Battery Market
Batteries
Electrolyte Solutions for Li-Ion Batteries Market
Batteries
Romania Rechargeable Battery Market
Batteries
India Alkaline Battery Market
Batteries
Molten Salt Battery Market