
 Netherlands Rechargeable Battery Market | 2026-2036
Netherlands Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Rechargeable Battery Market Insights
Modular battery pack architectures is recalibrating buyer choice across Dutch industrial and mobility segments. Victron Energy B.V. leverages its marine and off-grid specialization to anchor premium pricing in niche applications. BYD Europe B.V. competes through integrated cell-to-pack manufacturing that compresses delivery timelines for regional bus and truck OEMs. MG Energy Systems B.V. differentiates via custom lithium-ion configurations purpose-built for yacht and commercial vessel electrification.
Netherlands rechargeable batteries are electrochemical storage devices designed for repeated charge-discharge cycling, typically employing lithium-ion chemistries with nickel-cobalt-manganese or lithium-iron-phosphate cathode formulations, and serve to power electric mobility, stabilize grid intermittency, and replace fossil-dependent backup systems. Lithium-ion chemistry dominates installed value given its superior gravimetric energy density and declining cell costs, while solid-state technology represents the fastest-advancing frontier for next-generation safety and range extension. Energy Storage as an end-user segment captures expanding margin pools as Dutch grid operators procure stationary battery systems to manage wind and solar variability.
The EU Green Deal and Netherlands' national climate agreement shape product standards and procurement mandates, while CE marking under the EU Battery Regulation governs carbon footprint disclosure and recycled content thresholds for market access. The Dutch central bank and Enterprise Agency coordinate green financing instruments that reduce capital costs for large-scale battery deployments. Stakeholders must monitor how solid-state pilot production timelines and EU critical raw materials partnerships reshape cell supply security and localization economics.
Market Dynamics
Modular battery pack architectures are forcing Dutch industrial buyers to reconfigure procurement specifications as cell-to-pack integration compresses assembly costs and delivery timelines for regional OEMs.
Growth Catalysts
- EU Battery Regulation:CE marking mandates for carbon footprint disclosure and recycled content thresholds are accelerating compliance-driven procurement upgrades across Dutch mobility and stationary storage sectors.
- North Brabant automotive corridor:Concentrated battery assembly infrastructure serving European OEM customers creates localized demand pull for lithium-ion pack integration.
- Grid-scale storage deployment:Dutch grid operators are procuring stationary battery systems to manage wind and solar intermittency, expanding the addressable market beyond mobility applications.
Market Restraints
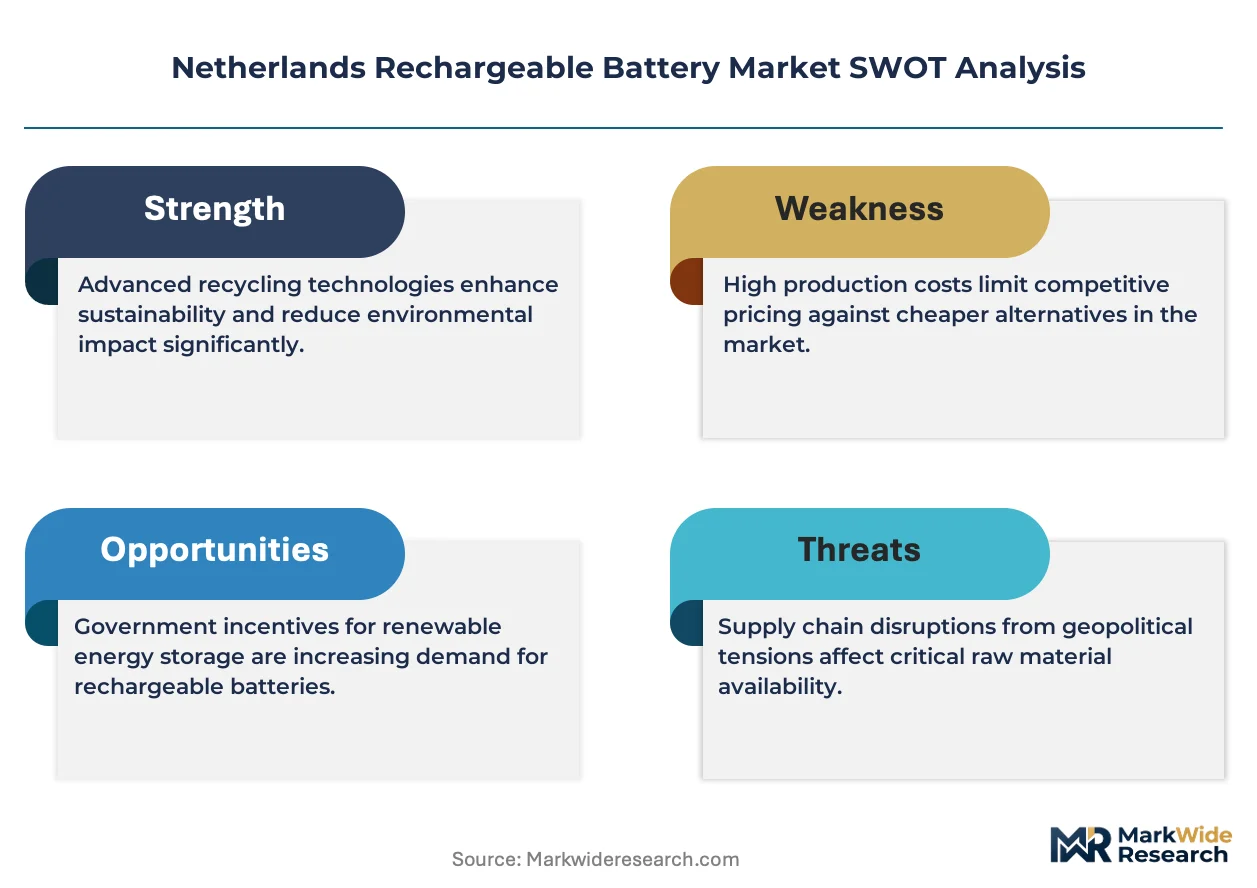
- Cobalt and nickel price volatility:Cathode material cost swings compress margin predictability for NCM chemistry packs deployed in premium mobility segments.
- Cell supply concentration:Asian-dominant electrode and separator production creates import dependency risks for Dutch pack assemblers lacking backward integration.
- Solid-state manufacturing readiness:Pilot production gaps between laboratory performance and scalable dry-electrode processing delay next-generation chemistry commercialization timelines.
Strategic Opportunities
- Marine electrification niche:Dutch yacht and commercial vessel builders are specifying custom lithium-ion configurations for propulsion and hotel load systems.
- Green financing instruments:The Dutch Enterprise Agency coordinates reduced-capital-cost structures for large-scale battery deployments.
- Second-life stationary repurposing:Retired electric vehicle packs are finding grid stabilization applications as circular economy regulations tighten disposal pathways.
Industry Challenges
- Battery management system firmware integration:Pack assemblers face compatibility complexity when interfacing heterogeneous cell chemistries with OEM vehicle control architectures.
- Thermal runaway testing certification:Extended UN 38.3 and IEC 62619 validation timelines delay product launches for custom pack configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Rechargeable Battery Market |
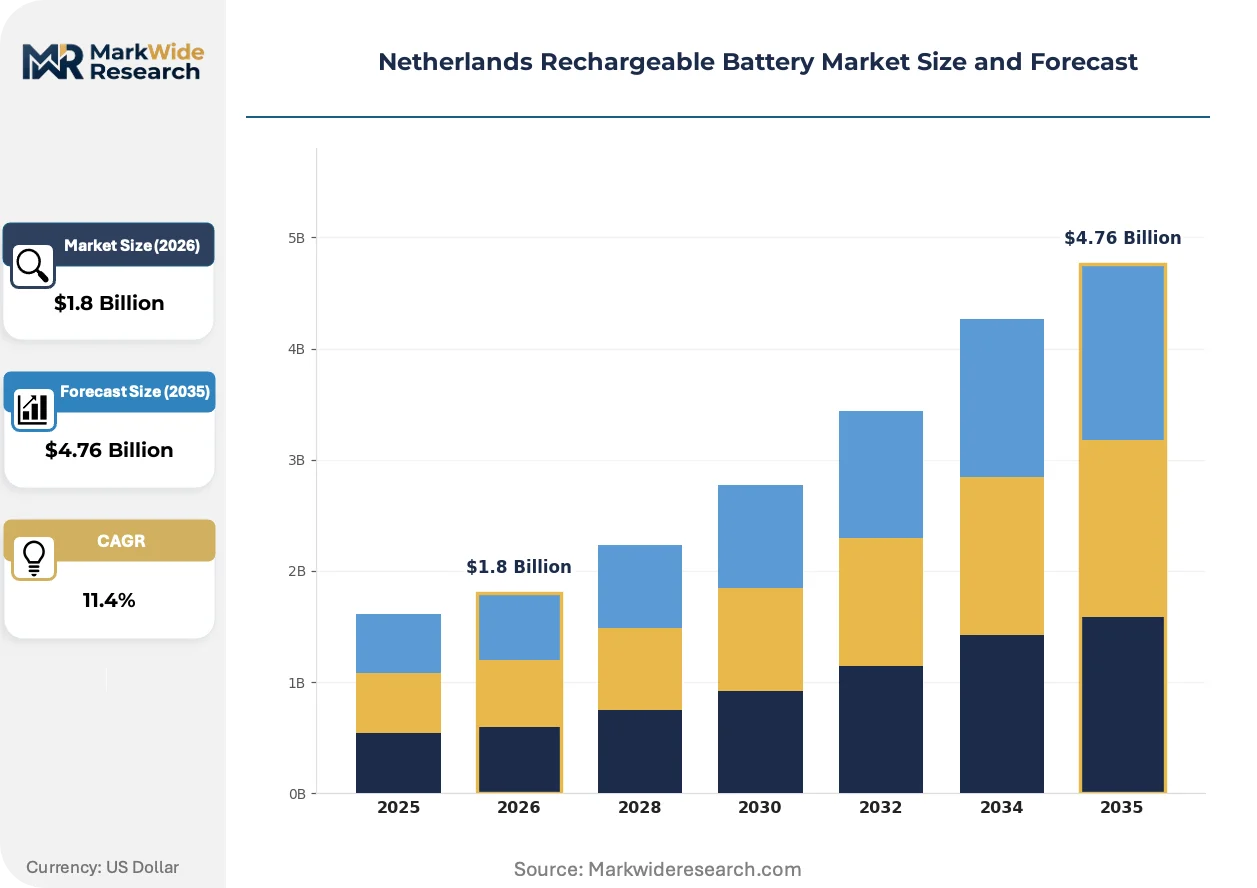
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-Metal Hydride, Lead-Acid, Lithium Polymer End User: Consumer Electronics, Automotive, Industrial, Energy Storage Application: Power Tools, Electric Vehicles, UPS Systems, Renewable Energy Technology: Fast Charging, Wireless Charging, Solid-State, Advanced Lithium |
| Companies Covered | Tesla, Inc., VARTA AG, Panasonic Holdings Corporation, EnerSys, Intercel, Victron Energy B.V., BYD Europe B.V., MG Energy Systems B.V., Saft Groupe SAS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Rechargeable Battery Market Trends and Innovations
Electrochemical storage technology is bifurcating between mature lithium-ion cost optimization and solid-state safety-performance breakthroughs, with Dutch market participants positioning across both trajectories.
Lithium-iron-phosphate chemistry is consolidating share in Dutch commercial vehicle and stationary applications as nickel-cobalt-manganese formulations face cost and supply security headwinds. Municipal bus operators and grid-scale developers are specifying LFP packs for their thermal stability and extended cycle life. This chemistry shift is compressing the premium pricing historically commanded by high-nickel cathode systems in volume segments.
The EU Battery Regulation's carbon footprint disclosure requirements are forcing Dutch importers to requalify cell suppliers against documented Scope 3 emissions thresholds. Pack assemblers serving European OEM customers must now integrate blockchain-tracked material provenance systems to maintain CE marking eligibility. North Brabant-based manufacturers are responding by auditing Southeast Asian cell partners for renewable electricity sourcing.
Fleet operators are unbundling battery procurement from vehicle acquisition, signing separate power purchase agreements with third-party asset owners. This financialization of storage assets is displacing traditional bundled leasing in Dutch electric bus and truck deployments. The separation is most visible in Rotterdam and Amsterdam municipal tenders, where transport authorities now specify service-level agreements for guaranteed energy availability rather than capital equipment purchase.
Netherlands Rechargeable Battery Market Segmentation
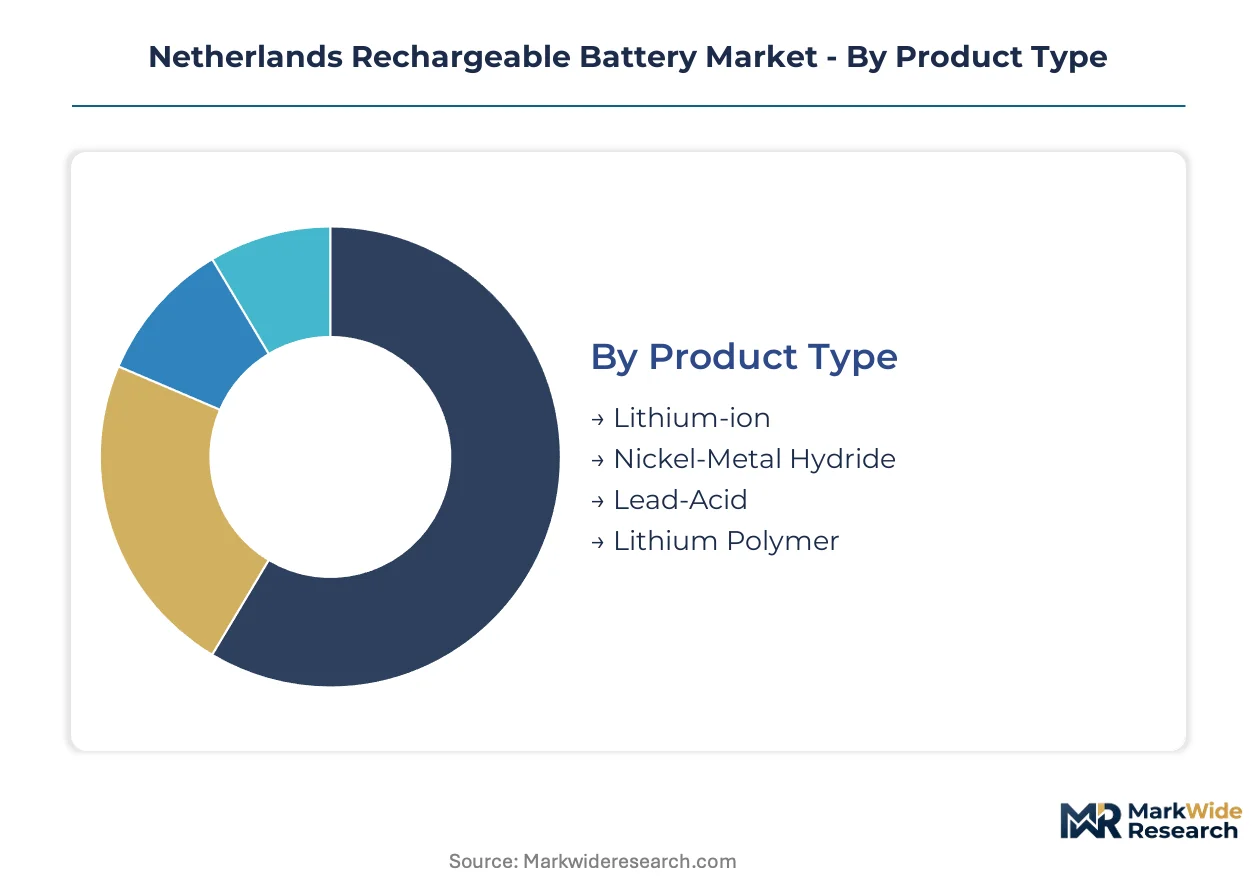
Segmentation in the Netherlands rechargeable battery market reveals distinct procurement patterns across standalone energy systems and embedded power architectures. Dutch buyers prioritize chemistry selection and integration depth based on application-critical performance thresholds and regulatory compliance mandates.
Product Type:
Standalone battery systems dominate procurement volumes, while embedded configurations in mobility platforms command premium integration margins.
- Lithium-ion:Nickel-cobalt-manganese and lithium-iron-phosphate cathode formulations deliver superior gravimetric energy density for electric mobility and grid-scale storage. North Brabant assembly plants concentrate demand for NCM packs serving European OEM bus and truck programs, while LFP chemistry gains share in stationary applications for thermal stability advantages.
- Nickel-Metal Hydride:Mature nickel-hydride chemistry retains position in hybrid vehicle auxiliary systems and industrial backup power where cost sensitivity outweighs energy density requirements. Toyota hybrid platforms and Dutch forklift fleets sustain residual procurement volumes.
- Lead-Acid:Flooded and valve-regulated lead-acid configurations persist in uninterruptible power supply and starter applications where capital expenditure constraints dominate. Data centers and telecommunications infrastructure in Amsterdam-Rotterdam corridor maintain replacement demand.
- Lithium Polymer:Pouch-cell lithium polymer architectures enable form-factor flexibility for marine electrification and portable equipment. Dutch yacht builders specify custom Li-Po packs for weight-critical propulsion integration.
Volume placements concentrate in Lithium-ion; the faster expansion belongs to Lithium Polymer.
End User:
Cost tier stratification separates mass-market consumer procurement from capital-intensive industrial deployments with extended performance guarantees.
- Consumer Electronics:Smartphone, laptop, and portable device manufacturers drive high-volume cylindrical and prismatic cell demand. Retail channel distribution through Dutch electronics retailers sustains replacement battery aftermarket.
- Automotive:Electric vehicle OEMs and conversion specialists command the largest revenue concentration with pack-level integration requirements. Dutch bus operators in Rotterdam and Amsterdam municipal fleets unbundle battery procurement from vehicle acquisition through power purchase agreements.
- Industrial:Material handling equipment, robotics, and manufacturing automation specify ruggedized battery systems with extended cycle life warranties. Port of Rotterdam electrification projects drive forklift and yard truck battery replacement cycles.
- Energy Storage:Grid operators and renewable developers procure containerized battery systems for frequency regulation and solar-wind intermittency management. TenneT and regional distribution system operators expand stationary storage procurement under EU Green Deal targets.
Revenue concentration sits with Automotive; Energy Storage climbs the fastest.
Application:
Application diversity spans portable equipment, mobility platforms, and infrastructure-grade backup systems with divergent thermal management and safety certification requirements.
- Power Tools:Cordless construction and garden equipment demand high-discharge-rate cylindrical cells with robust mechanical packaging. Professional contractor segments in Dutch building trades prioritize runtime and durability over unit cost.
- Electric Vehicles:Passenger cars, commercial vans, buses, and trucks require pack-level thermal management and battery management system integration. Cell-to-pack architectures compress assembly costs for regional OEM customers in North Brabant corridor.
- UPS Systems:Data center and critical facility backup power specifications prioritize instantaneous response and cycle life over energy density. Dutch cloud infrastructure expansion sustains demand for lithium-ion replacements of legacy lead-acid installations.
- Renewable Energy:Solar-plus-storage and standalone wind buffering systems require megawatt-hour scale containerized deployments with 15-20 year operational horizons. Agricultural and industrial self-consumption projects in rural Netherlands drive distributed storage adoption.
Deployment scale peaks in Electric Vehicles; Renewable Energy scales most steeply.
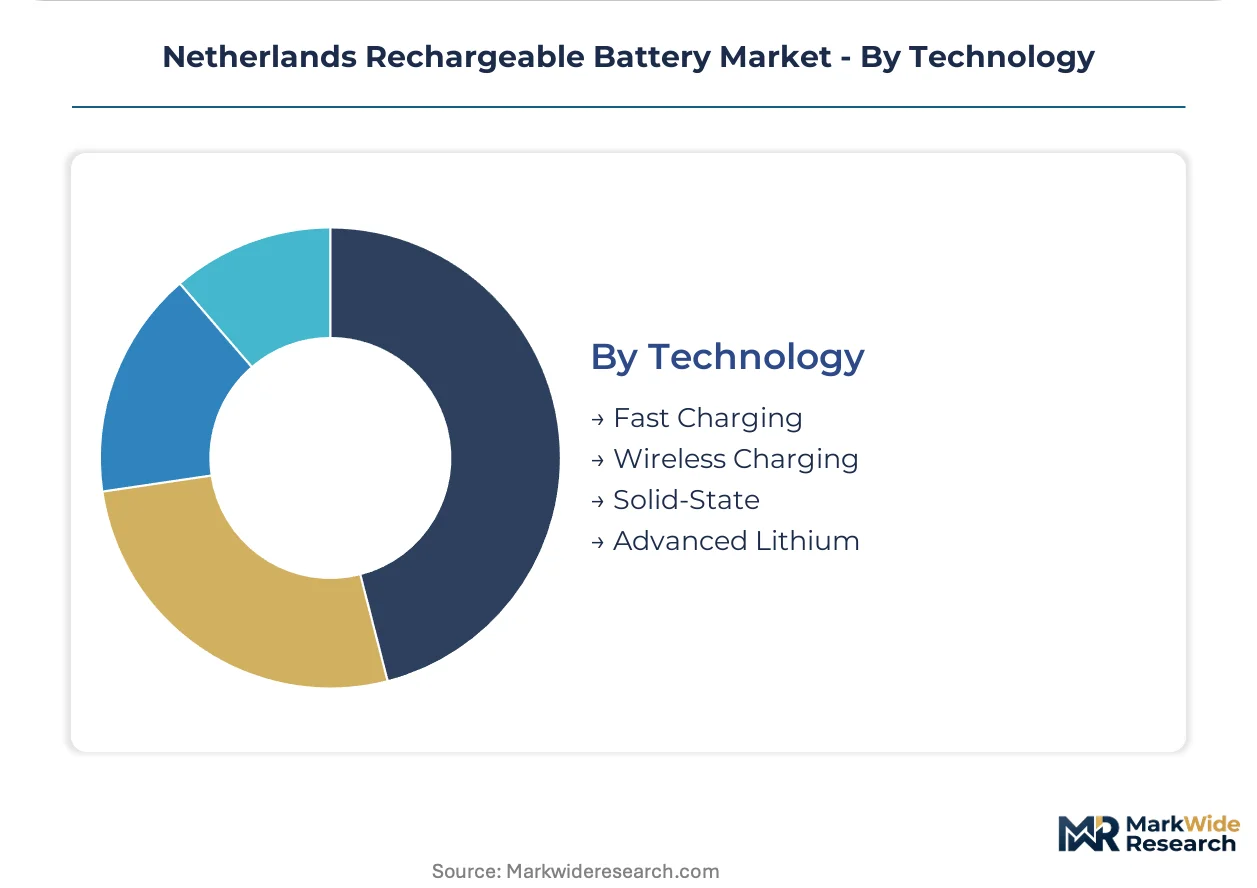
Technology:
Technology maturity curves separate commercially proven charging architectures from next-generation chemistry platforms still navigating pilot production gaps.
- Fast Charging:High-C-rate capable cells and thermal management systems enable 15-30 minute recharge cycles for commercial vehicle depot charging. Dutch bus fleet operators specify fast-charge compatibility for opportunity charging at route terminals.
- Wireless Charging:Inductive power transfer systems eliminate connector wear in automated guided vehicles and premium consumer applications. Rotterdam port automation projects pilot wireless charging for autonomous yard equipment.
- Solid-State:Ceramic electrolyte and dry-electrode processing promise enhanced safety and energy density breakthroughs. Laboratory performance advantages await scalable manufacturing solutions before Dutch market entry.
- Advanced Lithium:Silicon-anode and high-voltage electrolyte formulations extend conventional lithium-ion performance envelopes. Cell suppliers serving Dutch pack assemblers sample next-generation materials for premium mobility segments.
Commercial penetration concentrates in Fast Charging; Solid-State holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch battery production concentrates in North Brabant's automotive corridor, while consumption spreads across Randstad mobility hubs and northern grid-scale storage projects. This geographic split shapes procurement patterns and logistics networks.
North Brabant
North Brabant hosts the densest concentration of battery assembly plants serving European OEM customers. The Eindhoven Region anchors this corridor, where pack integrators cluster near automotive supplier networks. CE marking compliance under the EU Battery Regulation drives carbon footprint auditing across this manufacturing belt.
Randstad
Randstad metropolitan demand centers on electric bus depots and port electrification in Rotterdam and Amsterdam. Municipal fleet operators here unbundle battery procurement from vehicle acquisition through power purchase agreements. The Dutch Enterprise Agency coordinates green financing instruments for large-scale deployments across this urban corridor.
Northern Netherlands
Northern provinces host expanding grid-scale storage installations managing wind intermittency from North Sea offshore farms. TenneT procures containerized battery systems for frequency regulation across Groningen and Friesland. Agricultural self-consumption projects drive distributed storage adoption in rural catchments.
Netherlands Rechargeable Battery Market Competitive Landscape
The competitive structure tilts toward integrated cell-to-pack manufacturers and specialized system integrators. Market concentration remains moderate, with Asian-origin cell suppliers feeding Dutch pack assemblers lacking backward integration into electrode production. Two strategic archetypes dominate: integrated manufacturers compressing delivery timelines through captive cell supply, and niche specialists commanding premium pricing in marine and off-grid segments. Capacity expansion and strategic partnerships represent the dominant competitive moves, as pack assemblers secure long-term cathode material offtake agreements.
Among Dutch-based specialists, Victron Energy B.V. and MG Energy Systems B.V. exemplify the premium-tier niche strategy, while BYD Europe B.V. represents integrated manufacturing scale. These three anchors illustrate the market's bifurcation between custom-configured marine electrification systems and volume-driven commercial vehicle programs.
| Leading Market Players |
|---|
| Tesla, Inc. |
| VARTA AG |
| Panasonic Holdings Corporation |
| EnerSys |
| Intercel |
| Victron Energy B.V. |
| BYD Europe B.V. |
| MG Energy Systems B.V. |
| Saft Groupe SAS |
| Others |
Pricing and Supply Chain Analysis
Electrochemical engineering talent concentration in Eindhoven and Helmond widens labor-cost spreads between premium custom-configured packs and commodity-standard assemblies. CE marking compliance investments and cathode material procurement volatility feed into three-tier pricing differentiation across Dutch battery procurement.
Pricing Analysis
Cost-down pressure on standard lithium-ion packs accelerates because Asian cell suppliers compress NCM and LFP cell pricing for volume offtake agreements. Contract-based long-term offtake structures dominate automotive procurement, while project-based pricing governs grid-scale stationary deployments. Price differentiation traces to certification grade—UN 38.3 and IEC 62619 validation tiers—and volume scale commitments. Municipal fleet operators exhibit highest price sensitivity; marine yacht builders remain least sensitive due to weight-critical performance requirements.
Supply Chain Analysis
Skilled battery assembly workforce availability in North Brabant and Randstad logistics hubs anchors pack integration economics against Asian cell manufacturing concentration. Cell supply draws from China, South Korea, and Japan for electrode and separator production. Raw material dependencies center on cobalt from the DRC, lithium from Australia and Chile, and nickel from Indonesia. Single-source vulnerability in cathode precursor processing creates structural risk. Distribution runs through Rotterdam port terminals and Eindhoven Region supplier parks to European OEM customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Netherlands rechargeable battery market sits in a chemistry-transition phase as lithium-iron-phosphate formulations displace nickel-cobalt-manganese in commercial vehicle and stationary applications.
For Market Incumbents: Acquire cathode material offtake agreements to secure cell supply against Asian-dominant electrode production concentration. Build backward integration into battery management system firmware development to reduce OEM compatibility complexity. Solid-state pilot production timelines and cobalt price volatility represent primary threats; captive supply of LFP cells and thermal runaway testing certification investment offer defensive leverage. For New Entrants and Emerging Players: Enter via marine electrification custom configurations where MG Energy Systems and Victron Energy anchor premium pricing with limited volume competition. Target North Brabant automotive supplier corridor for cell-to-pack integration services to regional bus and truck OEMs. White-space sits in second-life stationary repurposing of retired electric vehicle packs for agricultural self-consumption projects. For Investors and Strategic Acquirers: Re-rating potential sits with specialized system integrators possessing CE marking compliance infrastructure and marine certification depth given EU Battery Regulation enforcement tightening. Long-term viability favors pack assemblers with demonstrated OEM qualification timelines and cathode chemistry flexibility across NCM and LFP platforms. Watch solid-state manufacturing readiness announcements as inflection signal for next-generation chemistry commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Integration Investment | Compresses assembly costs and delivery timelines for North Brabant OEM customers. |
| Cathode Material Offtake Agreement | Reduces import dependency risk from Asian-dominant electrode production concentration. |
| CE Marking Compliance Infrastructure | Maintains market access under EU Battery Regulation carbon footprint disclosure mandates. |
| Marine Certification Expansion | Captures premium pricing in Dutch yacht and commercial vessel electrification niche. |
| Second-Life Repurposing Partnership | Aligns with circular economy regulations tightening disposal pathways for retired packs. |
Research Methodology
Independent corroboration across battery pack assembler executives, OEM procurement leads, and grid operator planning officers underwrites the qualitative findings. Secondary validation draws from EU Battery Regulation documentation, TenneT procurement disclosures, and North Brabant economic development databases. Bottom-up cell demand modeling and top-down stationary storage deployment targets triangulate market sizing.
Comparable-period anchoring to historical lithium-ion cost curves and electric vehicle fleet penetration rates shapes the projection horizon. Segmentation dimensions span chemistry formulation, integration depth, end-use application, and regional procurement cluster. CAGRs derive from cell price trajectory assumptions and OEM program ramp schedules. Forecast inputs incorporate solid-state pilot production timelines and EU critical raw materials partnership developments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cobalt and nickel price volatility or accelerated solid-state commercialization. Material deviation in cathode material supply security or CE marking compliance cost inflation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
HIT Battery Market
Batteries
Lithium Marine Battery Market
Batteries
South America Micro Battery Market
Batteries
Europe Consumer Battery Market
Batteries
Zinc Carbon Battery Market
Batteries
Sodium-Air Battery Market
Batteries
Proton Battery Market
Batteries
Zinc-Ion Battery Cells Market
Batteries
Rechargeable Battery Market
Batteries
Japan Mobile Battery Market
Batteries
Battery Plate Market
Batteries
Japan Rechargeable Battery Market
Batteries
Zinc-Manganese Oxide Printed Battery Market
Batteries
Inverter Battery Market
Batteries
SLI Battery Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market