
 Military Battery Packs Market | 2026-2036
Military Battery Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Military Battery Packs Market Insights
Domestic cell manufacturing in the United States is recalibrating supply security for defense-grade electrochemical storage. EnerSys leverages vertical integration across battery assembly and subsystem integration to secure Department of Defense contracts. Saft anchors European supply chains through specialized lithium-thionyl chloride production for missile and aerospace applications. EaglePicher Technologies dominates niche requirements for satellite and strategic weapons platforms with heritage radiation-hardened designs.
Military battery packs are sealed electrochemical energy storage systems engineered to operate across temperature extremes from minus forty to plus seventy-one degrees Celsius while meeting stringent shock, vibration, and electromagnetic interference specifications. These systems power mission-critical electronics where grid independence and operational continuity determine tactical outcomes. Lithium-ion chemistry leads current procurement volumes due to energy density advantages in dismounted soldier applications, while solid-state technology represents the fastest-growing segment as developers resolve manufacturing scalability for field deployment. Weapons systems applications concentrate margin pools through qualification-intensive custom engineering that locks in long-term supplier relationships.
The U.S. Department of Defense mandates MIL-STD-810 environmental testing and MIL-PRF-32052 performance standards for all deployed battery systems, creating compliance barriers that favor established suppliers with qualification heritage. NATO standardization agreements additionally shape interoperability requirements across allied procurement programs. Stakeholders must monitor solid-state manufacturing yield improvements and domestic content thresholds in U.S. defense appropriations to anticipate qualification timelines and contract eligibility shifts.
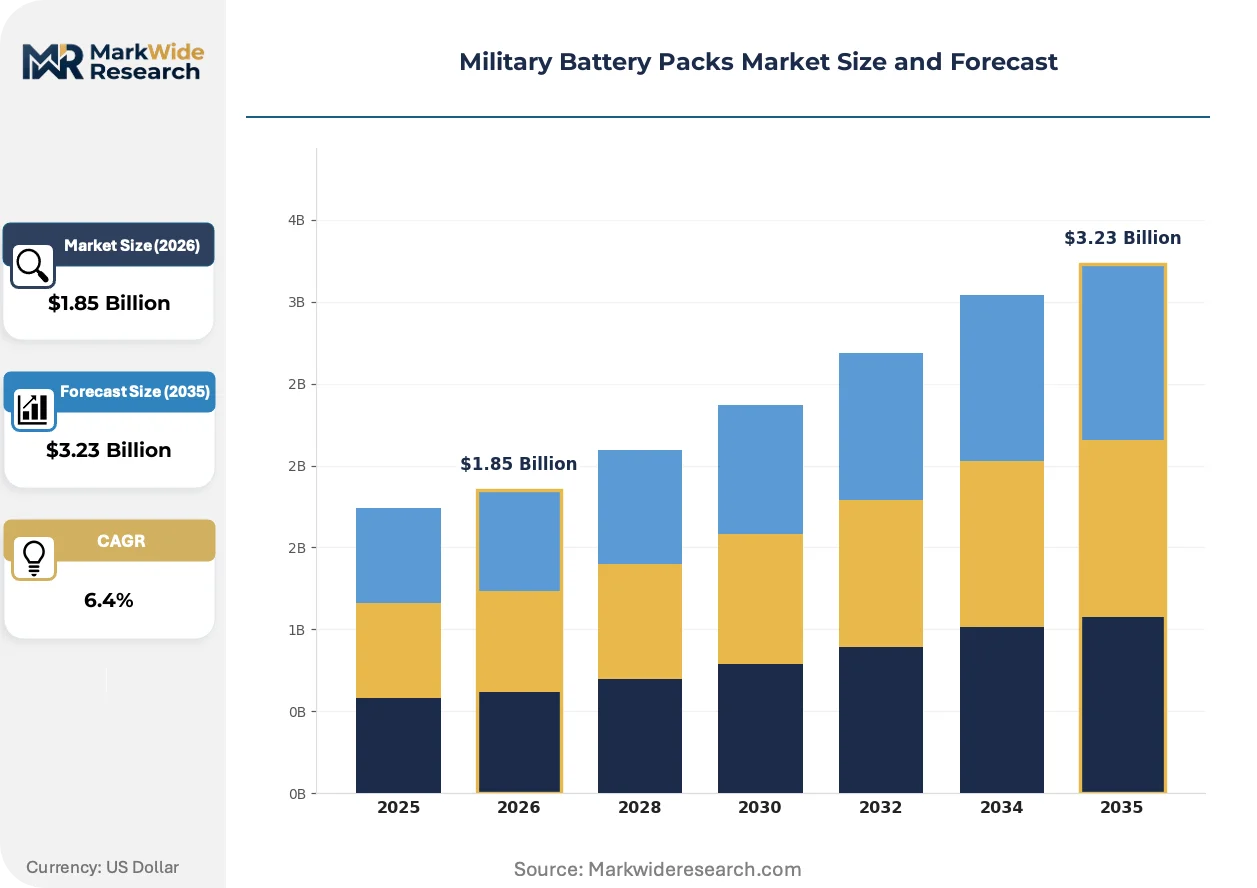
Market Dynamics
Solid-state battery chemistry is displacing legacy lithium-ion architectures in tactical power systems, forcing incumbent suppliers to requalify manufacturing lines and secure new raw material partnerships for defense procurement eligibility.
Growth Catalysts
- MIL-PRF-32052 Performance Standards:The U.S. Department of Defense mandates rigorous electrochemical testing that locks in multi-year supplier relationships once qualification is achieved.
- Dismounted Soldier Programs:NATO member states are expanding portable power procurement for individual warfighter electronics, concentrating demand in wearable battery form factors.
- Domestic Content Thresholds:U.S. defense appropriations increasingly require in-country cell manufacturing, redirecting supply chain investment toward American production facilities.
Market Restraints
- Lithium Metal Anode Scarcity:Solid-state manufacturing depends on ultra-thin lithium foil supply concentrated among Asian chemical processors.
- Radiation-Hardening Costs:Satellite and strategic weapons applications require specialized shielding materials that multiply unit costs versus commercial equivalents.
- REACH Chemical Compliance:European environmental regulations restrict thionyl chloride and other electrolyte solvents used in aerospace battery systems.
Strategic Opportunities
- India Defense Modernization:The country's PLI scheme for advanced chemistry cell manufacturing creates entry points for foreign battery system integrators.
- Hybrid Solid-Liquid Electrolytes:Semi-solid architectures offer near-term performance gains while full solid-state yields mature, bridging qualification timelines.
- Direct Military Contracting:Bypassing traditional prime contractor tiers through Other Transaction Authority pathways accelerates technology insertion cycles.
Industry Challenges
- Electrochemist Talent Pipeline:Defense battery development requires specialized expertise in solid-state interfaces that universities produce in limited volumes.
- MIL-STD-810 Requalification Burden:Each chemistry iteration demands exhaustive environmental testing across temperature, shock, and vibration profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Battery Packs Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-Metal Hydride, Lead Acid, Alkaline Technology: Rechargeable, Primary Cells, Solid-State, Zinc-Air Application: Communication Equipment, Portable Devices, Surveillance Systems, Weapons Systems End User: Defense Forces, Intelligence Agencies, Security Contractors, Peacekeeping Operatives |
| Companies Covered | EnerSys, Saft, EaglePicher Technologies, Arotech Corporation, Ultralife Corporation, Bren-Tronics, GS Yuasa Corporation, BAE Systems PLC, Inventus Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Battery Packs Market Trends and Innovations
Solid-state manufacturing advances are compressing development timelines for next-generation tactical power systems. Three converging developments are restructuring competitive positioning and procurement patterns.
Sulfide-based solid electrolytes are integrating into pilot production lines for dismounted soldier batteries, replacing flammable liquid electrolytes with ceramic-ion conductors. U.S. Army Natick Soldier Systems Center is evaluating these cells for conformal wearable applications. This integration is enabling thinner form factors that redistribute weight across body armor rather than concentrating it at the waist.
The EU AI Act and associated defense procurement directives are mandating algorithmic transparency in battery management systems that predict state-of-charge and health. European defense agencies now require explainable diagnostics for autonomous power distribution decisions. French and German land forces are prioritizing suppliers with certified transparent BMS architectures in recent tender evaluations.
Multi-year performance-based logistics contracts are replacing transactional battery purchases in major NATO programs. Prime contractors now guarantee operational availability rather than delivering hardware alone, transferring lifecycle risk to suppliers. This restructuring is most advanced in U.S. Marine Corps expeditionary power programs and British Army future soldier initiatives.
Military Battery Packs Market Segmentation
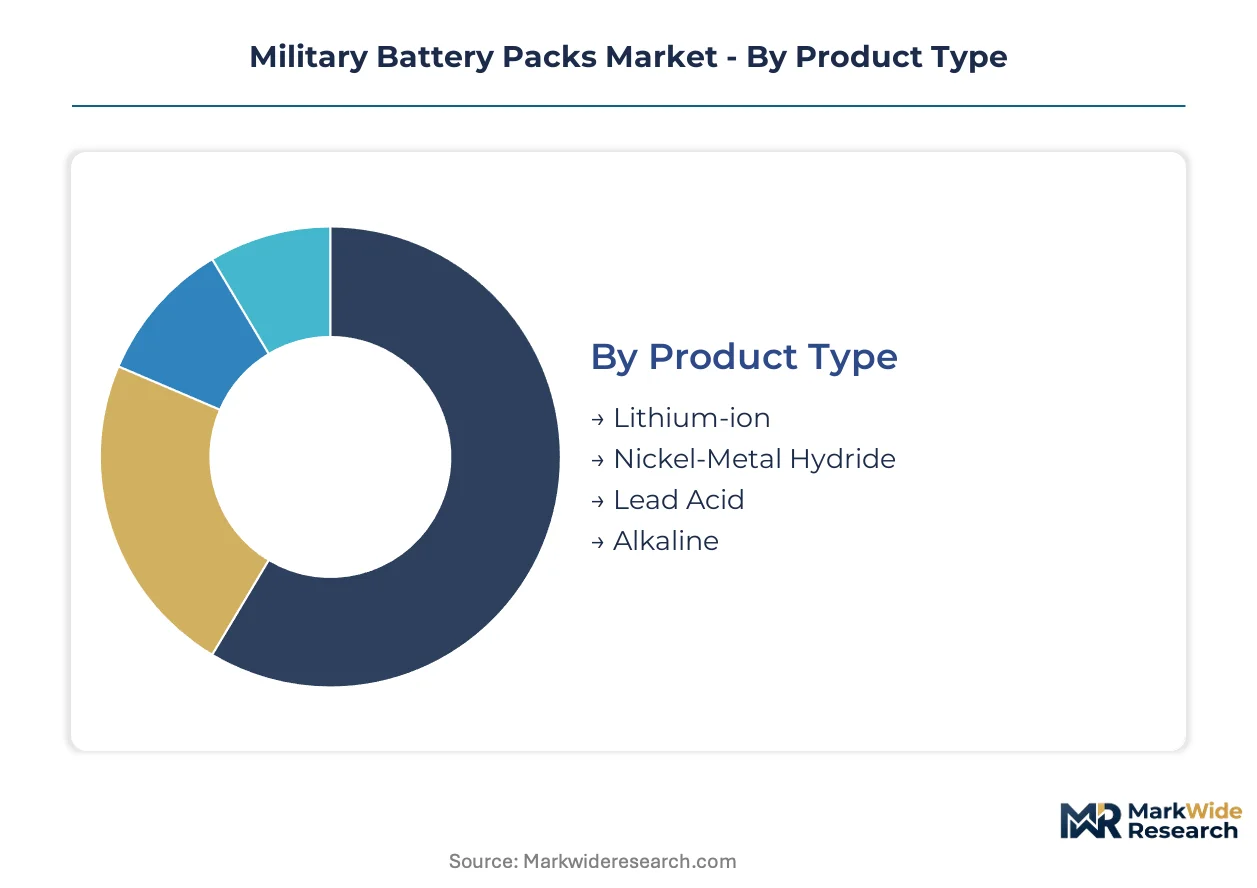
Military battery segmentation separates procurement streams by electrochemical performance, operational lifecycle, and mission-criticality tiers. Defense buyers optimize form factor, energy density, and qualification heritage against specific deployment profiles rather than selecting on unit cost alone.
Product Type:
Volume procurement concentrates in mature chemistries with established MIL-STD-810 qualification trails, while premium applications migrate toward next-generation architectures with superior thermal stability.
- Lithium-ion:Cobalt-oxide and iron-phosphate cathode formulations deliver 150-250 Wh/kg energy density in conformal wearable packs. The U.S. Army's Nett Warrior program drives procurement volume through standardized BB-2590 form factor requirements.
- Nickel-Metal Hydride:Rare-earth alloy anodes tolerate minus thirty degree Celsius discharge without capacity collapse. NATO cold-weather exercises in Norway and Estonia sustain demand for this chemistry where lithium-ion thermal management proves impractical.
- Lead Acid:Absorbed glass mat construction remains specified for vehicle starting-lighting-ignition backup systems. The chemistry's tolerance to complete discharge cycles suits reserve power roles in armored vehicle electrical architectures.
- Alkaline:Zinc-manganese dioxide primary cells power disposable mission equipment where recharging infrastructure is absent. Special operations forces procure these for extended reconnaissance patrols beyond resupply reach.
Today's leader: Lithium-ion. Tomorrow's challenger: Solid-state lithium-metal architectures displacing liquid electrolyte formats in next-generation tactical programs.
Technology:
Lifecycle economics separate procurement categories, with rechargeable systems dominating sustained operations and primary cells reserved for contingency stockpiles.
- Rechargeable:Lithium-ion and nickel-cadmium chemistries support 500-1000 cycle lifespans in forward operating base power networks. The U.S. Marine Corps Expeditionary Power Systems program mandates rechargeable formats for all company-level electronics to reduce logistics tail.
- Primary Cells:Non-rechargeable lithium-thionyl chloride and magnesium-silver chloride deliver shelf lives exceeding ten years. Strategic weapons platforms and undersea sensors specify these for deployment readiness without maintenance access.
- Solid-State:Sulfide and oxide ceramic electrolytes eliminate thermal runaway risk while enabling lithium-metal anodes. DARPA's Structural Battery Program is qualifying these for air-dropped sensor networks where impact survival determines mission success.
- Zinc-Air:Atmospheric oxygen cathodes yield theoretical energy densities approaching 400 Wh/kg. Hearing protection and micro-unmanned aerial vehicle applications in the British Army's Future Soldier program are evaluating zinc-air for weight-critical roles.
Primary cells anchor strategic deterrent readiness. Solid-state chemistries are climbing the fastest through DARPA and NATO investment pipelines.
Application:
Mission duration and electromagnetic signature requirements fragment procurement specifications across operational domains.
- Communication Equipment:Software-defined radios demand pulse-power discharge profiles with minimal voltage sag. The U.S. Army's Integrated Tactical Network standardizes battery interfaces across Harris and Thales radio families.
- Portable Devices:Night vision, GPS, and laser designators require 72-hour operational endurance at three-kilogram total carried weight. French Army FELIN soldier modernization concentrates demand in this segment through centralized battery logistics.
- Surveillance Systems:Unattended ground sensors and aerostat payloads prioritize calendar life over cycle life. Israeli border surveillance programs drive procurement for lithium-thionyl chloride formats in desert thermal cycling conditions.
- Weapons Systems:Missile guidance, torpedo propulsion, and electromagnetic railgun capacitors demand customized electrochemical architectures. Qualification-intensive engineering locks supplier relationships across decade-long production runs.
Portable devices generate highest unit volume. Weapons systems capture steepest margin pools through custom engineering barriers.
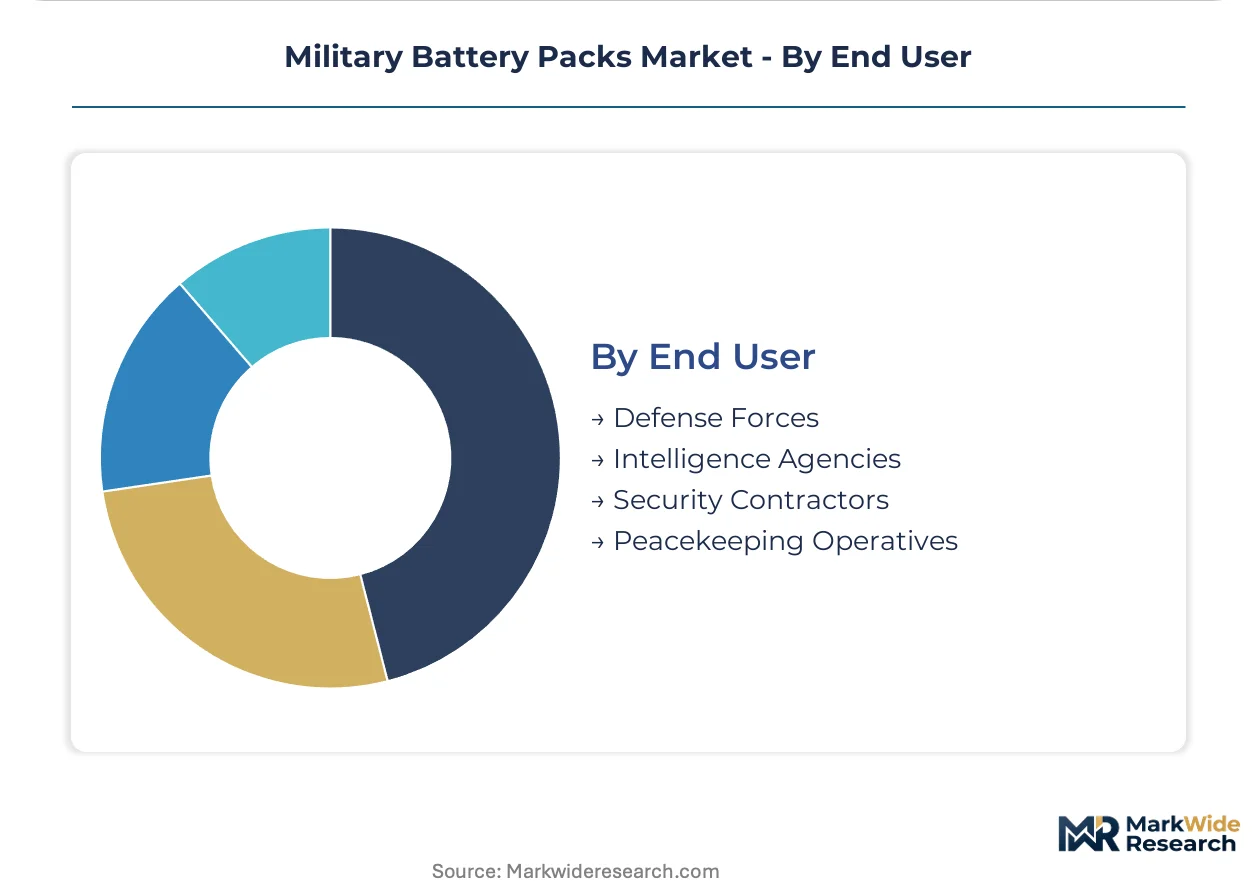
End User:
Procurement authority and operational security classification shape supplier access and contract structures.
- Defense Forces:National military services execute multi-year programmatic acquisitions through defense acquisition regulations. The U.S. Department of Defense's Battery Innovation Consortium channels R&D funding toward domestic manufacturing scale-up.
- Intelligence Agencies:Clandestine technical collection requires minimized electromagnetic signatures and non-attributable supply chains. National Technical Means programs procure through classified contract vehicles with enhanced counterintelligence vetting.
- Security Contractors:Private military companies operate under commercial terms with accelerated procurement cycles. Embassy security and maritime anti-piracy contracts in the Gulf of Aden sustain aftermarket demand for NATO-standard battery formats.
- Peacekeeping Operatives:United Nations and African Union missions rely on donor-funded equipment packages with interoperability mandates. MONUSCO and MINUSMA operations in the Sahel specify battery commonality across contributing nation equipment pools.
Defense forces control qualification infrastructure and volume contracts. Intelligence agencies pioneer performance specifications that diffuse into broader military procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic content mandates in U.S. defense appropriations are redirecting cell manufacturing investment away from Asian supply chains, while European REACH compliance costs and Indian production incentives create divergent cost-of-compliance arbitrage opportunities for electrochemical storage suppliers.
United States
The Department of Defense drives procurement volume through multi-year battery modernization contracts and the Battery Innovation Consortium channels R&D toward domestic manufacturing scale-up. MIL-STD-810 and MIL-PRF-32052 standards lock in supplier relationships once qualification is achieved. Michigan and Arizona host emerging solid-state pilot production facilities serving Army Natick Soldier Systems Center evaluation programs.
Germany
Bundeswehr future soldier initiatives concentrate demand for NATO-interoperable portable power systems with explainable battery management architectures. The EU AI Act mandates algorithmic transparency in state-of-charge diagnostics for defense procurement eligibility. Bavaria anchors industrial activity through specialized suppliers serving Franco-German land force modernization tenders.
France
The FELIN soldier system centralizes battery logistics for portable devices across night vision, GPS, and laser designator applications. ANSM and defense procurement directives enforce chemical safety standards for thionyl chloride electrolytes in aerospace battery systems. The Provence-Alpes-Côte d'Azur region hosts qualification facilities for Mediterranean naval surveillance programs.
India
Defense modernization budgets are expanding procurement of dismounted soldier electronics under Atmanirbhar Bharat self-reliance frameworks. The PLI scheme for advanced chemistry cell manufacturing creates entry points for foreign battery system integrators. Tamil Nadu and Gujarat are attracting defense-grade lithium-ion assembly investments through state-level electronics manufacturing clusters.
Israel
Border surveillance programs sustain demand for lithium-thionyl chloride formats in unattended ground sensors operating under desert thermal cycling conditions. The national defense establishment prioritizes minimized electromagnetic signatures for clandestine technical collection applications. Tel Aviv and Haifa anchor development activity for strategic weapons platform power systems.
Military Battery Packs Market Competitive Landscape
American producers anchor one tier through Department of Defense contract capture and vertical integration across assembly and subsystem integration; European specialists hold qualification heritage in aerospace and strategic weapons applications with radiation-hardened designs. The supplier base concentrates around three strategic archetypes: domestic-integrated defense contractors, European niche qualification holders, and Asian cell manufacturers seeking Western defense market entry. Competitive dynamics center on manufacturing yield improvements for solid-state chemistries and strategic partnerships securing lithium metal anode supply.
Among established defense contractors, EnerSys exemplifies the vertically integrated archetype with captive battery assembly and subsystem integration capabilities. Saft occupies a position representing European heritage in specialized lithium-thionyl chloride production for missile and aerospace qualification-intensive segments. EaglePicher Technologies anchors the radiation-hardened design tier with heritage positioning in satellite and strategic weapons platform applications.
| Leading Market Players |
|---|
| EnerSys |
| Saft |
| EaglePicher Technologies |
| Arotech Corporation |
| Ultralife Corporation |
| Bren-Tronics |
| GS Yuasa Corporation |
| BAE Systems PLC |
| Inventus Power |
| Others |
Pricing and Supply Chain Analysis
Electrochemist talent concentration in the Great Lakes industrial corridor and southwestern Germany generates labor-cost differentials that widen pricing-tier spreads between qualification-intensive custom engineering and commoditized form-factor production. MIL-STD-810 requalification burdens and solid-state manufacturing yield challenges concentrate premium pricing in heritage suppliers with established Department of Defense relationships, while volume procurement of standardized BB-2590 formats compresses margins in interchangeable cell segments.
Pricing Analysis
Distributor margins on NATO-standard battery formats typically run 15-25 percent above direct-to-OEM contracting for prime integrators. Three-tier pricing structure across radiation-hardened strategic weapons platforms, conformal wearable soldier systems, and disposable alkaline mission equipment reflects certification-grade differentiation and volume scale. Cost compression in lithium-ion conformal packs intensifies as domestic content thresholds redirect supply chain investment toward American assembly facilities with higher labor inputs. Security contractors and peacekeeping procurement pools exhibit greatest price sensitivity due to donor-funded budget constraints, while intelligence agency programs prioritize electromagnetic signature performance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for rechargeable field batteries are emerging through performance-based logistics contracts that transfer lifecycle risk to suppliers. Raw material supply concentrates in China for processed cathode materials, South Korea for separator membranes, and Japan for electrolyte additives. Solid-state manufacturing draws from ultra-thin lithium foil supply concentrated among Asian chemical processors, creating single-source vulnerability for defense-grade sulfide electrolyte production. Distribution runs through prime contractor tiers for weapons systems integration and direct military contracting via Other Transaction Authority pathways for experimental solid-state insertion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Military Battery Packs Market functions as a stable compounder underpinned by multi-year Department of Defense modernization contracts that lock in supplier relationships across decade-long production cycles.
For Market Incumbents: Extend qualification heritage into solid-state architectures through pilot production partnerships with Army Natick Soldier Systems Center evaluation programs. Secure lithium metal anode supply agreements with Asian chemical processors before domestic content thresholds tighten. Backward integration into cell manufacturing in Michigan and Arizona production clusters defends margin position against emerging domestic competitors. For New Entrants and Emerging Players: Capture entry points through India's PLI scheme for advanced chemistry cell manufacturing, where foreign system integrators face lower qualification barriers than in NATO procurement streams. Target hybrid solid-liquid electrolyte architectures as a near-term bridge technology while full solid-state yields mature. Pursue direct military contracting through Other Transaction Authority pathways to bypass entrenched prime contractor tiers. For Investors and Strategic Acquirers: Defense prime contractors with captive power electronics divisions are the most active acquirer in this space, seeking to internalize battery subsystem integration capabilities. Acquisition focus should center on mid-cap specialists with MIL-PRF-32052 qualification heritage and radiation-hardened design archives. Solid-state manufacturing yield improvements at pilot scale represent the critical inflection signal for timing entry into next-generation tactical power systems.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Pilot Production Scale-Up | Army Natick Soldier Systems Center qualification unlocks conformal wearable procurement volume. |
| Lithium Metal Anode Supply Agreement | Asian chemical processor partnerships secure defense procurement eligibility before domestic content mandates tighten. |
| Performance-Based Logistics Contracting | U.S. Marine Corps expeditionary power programs transfer lifecycle risk from buyer to supplier. |
| Domestic Cell Manufacturing Investment | Michigan and Arizona facilities satisfy Department of Defense Battery Innovation Consortium domestic content thresholds. |
| Hybrid Solid-Liquid Electrolyte Development | Semi-solid architectures bridge qualification timelines while full solid-state manufacturing yields mature. |
Research Methodology
Bottom-up dismounted soldier electronics modeling reconciled against top-down defense procurement tracking forms the analytical core of this study. Primary interviews with electrochemist R&D directors, Department of Defense program managers, prime contractor procurement leads, and battery subsystem integration engineers combined with secondary validation from MIL-STD-810 qualification databases, Department of Defense contract award announcements, and NATO standardization agreement documentation. Triangulation across bottom-up segment builds and top-down budget authority flows ensures consistency in volume and value estimates.
Input-output matrices map electrochemical chemistry iterations to specific application requirements across communication equipment, portable devices, surveillance systems, and weapons platforms. Segmentation dimensions include product type, technology lifecycle, mission-criticality tier, and end-user procurement authority. CAGRs derive from projected qualification timeline compression for solid-state architectures and domestic manufacturing scale-up assumptions. Forecast inputs incorporate Battery Innovation Consortium funding disbursements and PLI scheme incentive trajectories for advanced chemistry cell production.
Domestic content threshold revisions, solid-state manufacturing yield volatility, and lithium metal anode supply disruptions are the dominant revision risks to projection assumptions. Forecasts reflect documented qualification heritage timelines and defense appropriations patterns without assuming breakthrough manufacturing scale-up. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
Global Battery Market
Batteries
Middle East and Africa Solar and Motorcycle Battery Market
Batteries
Li-Ion Pouch Battery Market
Batteries
DMC for Battery Market
Batteries
PVT Battery Panel Market
Batteries
Middle East and Africa Rechargeable Battery Market
Batteries
Low Temperature Battery Market
Batteries
Flow Battery Market
Batteries
Tubular Batteries Market
Batteries
Stretchable Battery Market
Batteries
United States Household Battery Market
Batteries
Battery Binders Market
Batteries
Asia Pacific Electric Vehicle VRLA Batteries Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Europe Consumer Battery Market