
 India Alkaline Battery Market | 2026-2036
India Alkaline Battery Market Size, Share, and Industry Trends Forecast 2026-2036
India Alkaline Battery Market Foresight
BIS certification under IS 8144 is collapsing the supplier base as smaller assemblers fail to meet revised leakage-resistance and shelf-life benchmarks. Eveready Industries India Ltd. leverages its Kolkata-based manufacturing footprint to sustain distribution dominance across tier-three towns and rural hinterlands. Panasonic Energy India Co Ltd. anchors premium positioning through OEM relationships with Japanese consumer electronics brands operating in India. Indo National Limited competes on price in the institutional procurement channel for educational devices and security systems.
Alkaline batteries electrochemically store energy through a zinc-manganese dioxide reaction with potassium hydroxide electrolyte, delivering nominal voltage of 1.5V with superior shelf stability compared to zinc-carbon predecessors. Their primary commercial purpose spans portable power for consumer electronics, industrial sensors, and emergency equipment where reliable off-grid operation matters. The AA and AAA product types occupy the volume core as remote controls and wireless mice penetrate semi-urban households, while the 9V segment generates disproportionate margin contribution from smoke detector and security system installations. Zinc Manganese Dioxide technology leads absolute output though Nickel Zinc formulations are gaining traction in high-drain camera and flashlight applications.
The Bureau of Indian Standards enforces mandatory ISI marking under IS 8144 for cell dimensional tolerance and discharge performance, while the Central Pollution Control Board governs hazardous waste rules for spent battery collection and mercury content limits. Compliance costs favor organized manufacturers with in-house testing laboratories, squeezing unorganized regional assemblers out of branded retail channels. Stakeholders must monitor BIS amendments on heavy metal thresholds and Extended Producer Responsibility frameworks, as these will determine which technology platforms and product formats remain viable for long-cycle investment.
Market Dynamics
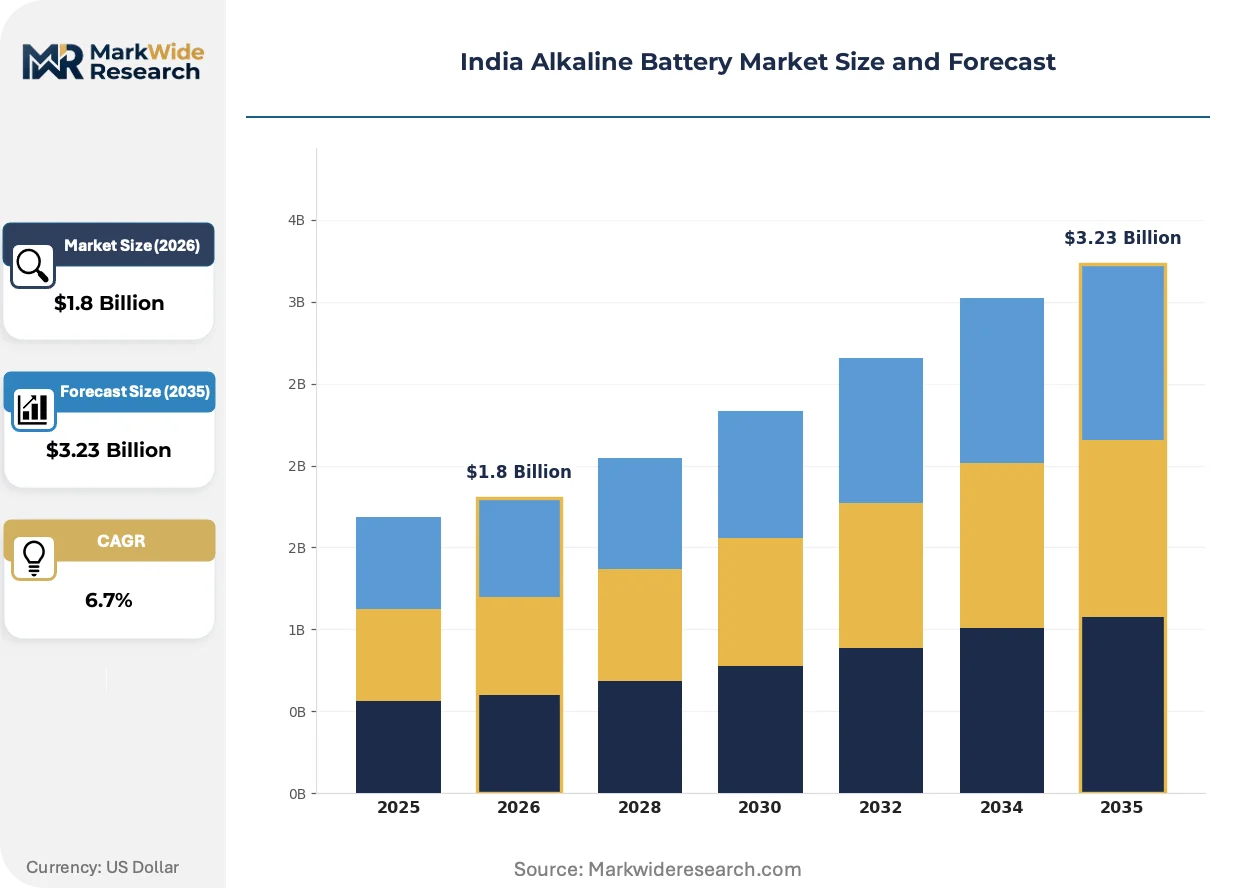
BIS certification under IS 8144 is compressing the supplier base as smaller assemblers fail to meet revised leakage-resistance and shelf-life benchmarks, forcing consolidation toward organized manufacturers with in-house testing infrastructure.
Growth Catalysts
- Rural electrification gaps:Unreliable grid access in Uttar Pradesh and Bihar villages is expanding demand for flashlights and emergency lighting powered by alkaline cells.
- IS 8144 compliance:Tightened dimensional tolerance and discharge performance standards are elevating quality expectations and rewarding manufacturers with captive laboratory capacity.
- OEM procurement intensity:Maharashtra's consumer electronics clusters around Mumbai and Pune are scaling remote control and wireless peripheral manufacturing, pulling volume through branded cell supply chains.
Market Restraints
- Potassium hydroxide electrolyte cost volatility:Input price swings for separator-grade materials are compressing margin structures for mid-tier producers without backward integration into chemical sourcing.
- Organized distribution concentration:Kolkata and Chennai-based logistics hubs control interstate movement, creating bottleneck risk for regional assemblers seeking national retail placement.
- Lithium primary cell substitution:High-drain camera and medical device applications are migrating toward lithium iron disulfide chemistry where energy density premiums justify cost differentials.
Strategic Opportunities
- Educational device institutional procurement:Government tablet and calculator distribution programs in Rajasthan and Madhya Pradesh are creating bulk tender opportunities for standardized AA and AAA supply.
- Extended Producer Responsibility frameworks:Anticipated CPCB mandates for spent battery collection infrastructure will favor early movers with reverse logistics networks in tier-two cities.
- Nickel-zinc convergence:High-drain flashlight and photography applications are opening to rechargeable alkaline alternatives as cycle stability improves through electrolyte additive advances.
Industry Challenges
- Electrochemical engineering talent scarcity:Formulation chemistry and separator material expertise concentrates in legacy zinc-carbon regions, constraining alkaline R&D expansion.
- BIS certification timeline compression:IS 8144 amendment cycles are accelerating, requiring continuous retesting investment that exhausts smaller laboratory budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Alkaline Battery Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AA, AAA, C, D, 9V, Button Cells Technology: Zinc Manganese Dioxide, Zinc Carbon, Lithium Alkaline, Nickel Zinc Application: Remote Controls, Flashlights, Portable Audio Devices, Toys, Wireless Mice, Cameras End User: Consumer Electronics, Industrial Equipment, Security Systems, Educational Devices, Emergency Tools |
| Companies Covered | Panasonic Energy India Co Ltd., Geep Industries Pvt. Ltd., Duracell Inc., Toshiba Corporation, Gold Peak Industries, Eveready Industries India Ltd., Energizer Holdings Inc., Sony Group Corporation, Indo National Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Alkaline Battery Market Shifts & Advancements
Electrochemical storage architectures are fragmenting across performance tiers as end-use applications diverge in power density and cycle requirements, forcing manufacturers to specialize rather than standardize.
Nickel-zinc formulations are bifurcating the high-drain segment from conventional alkaline dominance. Camera operators and tactical flashlight users are adopting these cells for superior voltage stability under load. This chemistry is bifurcating procurement patterns between premium professional channels and mass retail, compressing zinc-manganese dioxide to mid-drain applications.
The Bureau of Indian Standards is accelerating IS 8144 amendment cycles for heavy metal thresholds and leakage resistance. Manufacturers with captive testing laboratories are absorbing compliance costs while regional assemblers exit branded retail. Maharashtra and Tamil Nadu production clusters are responding with dedicated quality assurance divisions to maintain ISI marking continuity.
Institutional procurement through state education departments is displacing open-market purchasing for bulk alkaline requirements. Tender specifications now mandate BIS certification and minimum shelf-life guarantees, filtering unorganized suppliers from government contracts. This pattern is most visible in Karnataka and Gujarat where digital literacy programs are scaling device distribution.
India Alkaline Battery Market Segmentation
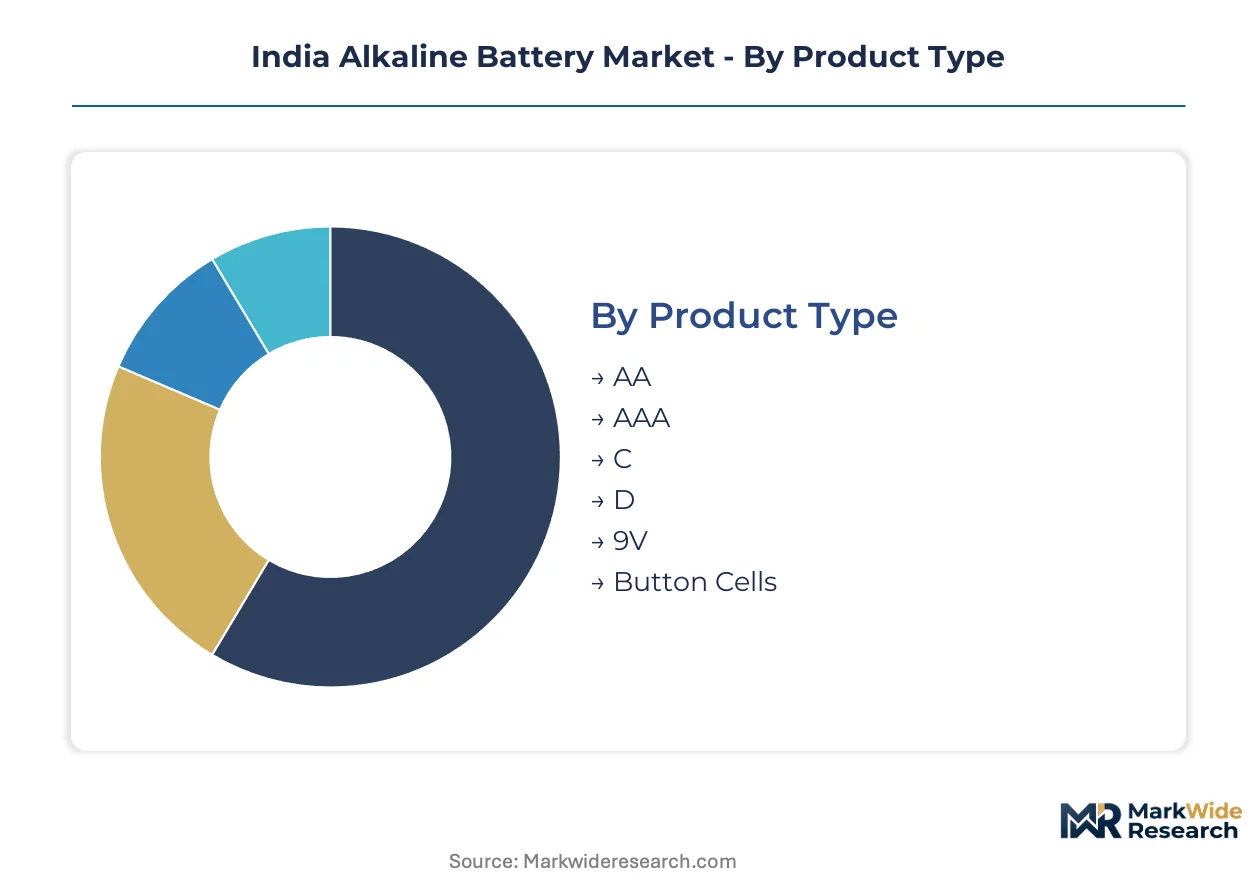
Segmentation in the India alkaline battery market reveals how procurement power concentrates around specific form factors and institutional channels. Understanding these divisions exposes where BIS compliance costs reshape competitive access and margin capture.
Product Type:
Margin pools concentrate in high-volume cylindrical formats where OEM procurement scale outweighs per-unit manufacturing cost.
- AA:The cylindrical zinc-manganese dioxide cell delivers 1.5V nominal voltage with 2000-3000 mAh capacity under standard discharge. Maharashtra's consumer electronics clusters around Mumbai and Pune pull volume through remote control and wireless peripheral manufacturing, with BIS-certified suppliers capturing institutional tenders.
- AAA:This compact cylindrical format sacrifices capacity for device miniaturization, offering 1000-1200 mAh in space-constrained applications. Demand concentrates in wireless mice and compact remote controls penetrating semi-urban households, where shelf-life guarantees determine retail placement.
- C:Mid-size cylindrical cells power higher-drain portable audio equipment with extended runtime requirements.
- D:Large cylindrical format serves heavy-duty flashlights and emergency lighting in rural electrification gaps across Uttar Pradesh and Bihar.
- 9V:Rectangular prismatic construction with stacked cell architecture generates disproportionate margin contribution from smoke detector and security system installations requiring reliable long-term standby power.
- Button Cells:Flat disc format serves compact electronics and medical devices where space constraints override energy density priorities.
The dominant share belongs to AA, while AAA is closing the gap fastest.
Technology:
Cost tier stratification separates premium electrochemical formulations from commodity zinc-carbon legacy production.
- Zinc Manganese Dioxide:Potassium hydroxide electrolyte enables superior shelf stability and higher energy density than acidic predecessors. Organized manufacturers with in-house testing laboratories absorb BIS certification costs under IS 8144, squeezing regional assemblers from branded retail channels.
- Zinc Carbon:Ammonium chloride electrolyte chemistry dominates ultra-low-price rural markets where device replacement cycles are shorter.
- Lithium Alkaline:Lithium iron disulfide construction delivers extreme temperature tolerance and decade-long shelf life for critical standby applications.
- Nickel Zinc:Rechargeable alkaline alternative gains traction in high-drain camera and flashlight applications as cycle stability improves through electrolyte additive advances.
Zinc Manganese Dioxide commands institutional procurement, though Nickel Zinc is expanding most quickly in professional channels.
Application:
Volume concentration follows household electronics penetration patterns across tier-two and tier-three urban centers.
- Remote Controls:AA and AAA formats dominate television and air conditioner peripherals where alkaline shelf life outlasts device replacement cycles.
- Flashlights:D and C cells serve emergency lighting demand in villages across Uttar Pradesh and Bihar where grid reliability remains intermittent.
- Portable Audio Devices:Mid-size cylindrical formats power radios and speakers in rural markets with limited electrification.
- Toys:High-volume disposable consumption favors zinc-carbon price points in mass retail.
- Wireless Mice:AAA miniaturization requirements concentrate demand in Maharashtra's electronics manufacturing corridors.
- Cameras:High-drain professional applications are migrating toward lithium primary cells where energy density premiums justify cost differentials.
Remote Controls retains the largest installed base, while Flashlights is gaining share fastest on rural electrification gaps.
End User:
Customer type determines certification requirements and procurement channel structure across institutional versus retail pathways.
- Consumer Electronics:OEM procurement through Maharashtra clusters demands BIS-certified supply chains with documented shelf-life guarantees.
- Industrial Equipment:Sensor and monitoring applications require temperature-tolerant formulations for outdoor deployment.
- Security Systems:9V smoke detector installations generate recurring replacement demand with stringent reliability specifications.
- Educational Devices:Government tablet and calculator distribution programs in Rajasthan and Madhya Pradesh create bulk tender opportunities mandating ISI marking.
- Emergency Tools:Tactical flashlight and medical device procurement favors premium electrochemical performance over unit cost.
Consumer Electronics holds the dominant position, while Educational Devices is climbing the fastest on state digital literacy program scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional buyers in state education departments and security system installers dominate procurement volume, while rural household demand for emergency lighting concentrates in grid-deficient eastern and northern sub-regions.
Maharashtra
Consumer electronics OEMs in Mumbai and Pune drive AA and AAA cell consumption for remote controls and wireless peripherals. BIS certification under IS 8144 filters supplier access to branded retail channels. Manufacturing clusters in Pimpri-Chinchwad absorb compliance costs through captive testing infrastructure.
Uttar Pradesh
Rural electrification gaps expand demand for D-cell flashlights and emergency lighting across village markets. State-level digital literacy programs generate institutional tender opportunities for educational device power supplies. Kanpur and Lucknow distribution hubs control interstate movement into Bihar.
Tamil Nadu
Electronics manufacturing services in Chennai and Coimbatore pull volume through component supply chains. The Central Pollution Control Board's hazardous waste rules govern spent battery collection infrastructure development. Sriperumbudur industrial corridor hosts quality assurance divisions serving ISI marking continuity.
West Bengal
Kolkata-based logistics networks sustain distribution dominance across tier-three towns and rural hinterlands. State procurement for security systems and smoke detectors generates 9V replacement demand. Howrah manufacturing belt concentrates electrochemical formulation expertise from legacy zinc-carbon operations.
Karnataka
Bengaluru's consumer electronics R&D ecosystem drives specification-setting for high-drain applications. Government tablet distribution programs mandate BIS-certified AA supply with minimum shelf-life guarantees. Mysuru and Hubli-Dharwad corridors serve as secondary distribution nodes for southern markets.
India Alkaline Battery Market Competitive Landscape
Player mix skews toward organized manufacturers with in-house testing laboratories and legacy distribution networks. Three structural tiers emerge: multinational battery majors with OEM relationships, domestic incumbents with rural penetration, and regional assemblers retreating to unbranded wholesale. Consolidation accelerates as BIS certification costs compress the supplier base. Dominant competitive moves include backward integration into separator-grade material sourcing and strategic partnerships with state education departments for institutional tenders.
Among multinational battery majors, Panasonic Energy India Co Ltd. and Duracell Inc. occupy positions anchoring premium-tier supply chains. Eveready Industries India Ltd. exemplifies the domestic incumbent archetype with established rural distribution density. Indo National Limited represents price-focused competition in institutional procurement channels. These three players illustrate the competitive spectrum from premium OEM positioning to volume-driven state tender participation.
| Leading Market Players |
|---|
| Panasonic Energy India Co Ltd. |
| Geep Industries Pvt. Ltd. |
| Duracell Inc. |
| Toshiba Corporation |
| Gold Peak Industries |
| Eveready Industries India Ltd. |
| Energizer Holdings Inc. |
| Sony Group Corporation |
| Indo National Limited |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day inventory cycles for separator-grade potassium hydroxide materials concentrate pricing power among Kolkata and Chennai-based distributors with backward integration into chemical sourcing. This lead-time band compresses margin structures for mid-tier producers lacking captive laboratory capacity while amplifying premiums for BIS-certified organized manufacturers.
Pricing Analysis
Cost-plus contracts indexed to potassium hydroxide electrolyte spot markets dominate procurement between organized manufacturers and Maharashtra OEM clusters. Three-tier pricing structure across premium, standard, and economy levels separates Panasonic-anchored premium supply from Eveready's mass-market positioning and regional assembler discount tiers. Pricing pressure stems from lithium primary cell substitution in high-drain camera applications, compressing zinc-manganese dioxide margins. Institutional procurement through state education departments exhibits lowest price sensitivity due to mandated BIS certification requirements, while rural retail channels remain most price-sensitive.
Supply Chain Analysis
Strategic stockpiling of separator-grade materials prevails among organized manufacturers with captive testing infrastructure, while just-in-time procurement characterizes regional assemblers vulnerable to BIS certification timeline compression. Supply concentration rests on China for potassium hydroxide electrolyte, Japan for advanced separator membranes, and domestic Tamil Nadu production for zinc oxide processing. Raw material dependencies include manganese dioxide ore, potassium hydroxide, and polypropylene separator films. Single-source vulnerability concentrates in Japanese separator membrane supply for premium-grade cells. Distribution runs through Kolkata and Chennai logistics hubs controlling interstate movement into tier-three towns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise scarcity constrains alkaline R&D expansion as legacy zinc-carbon regions fail to transfer electrochemical engineering talent to potassium hydroxide platforms. This capability gap rewards early movers with dedicated quality assurance divisions.
For Market Incumbents: Fortify BIS certification continuity through captive laboratory investment as IS 8144 amendment cycles accelerate, squeezing regional competitors from branded retail. Deepen upstream control over separator-grade material sourcing to buffer potassium hydroxide cost volatility threatening mid-tier margin structures. For New Entrants and Emerging Players: Reverse logistics service gaps in tier-two cities present white-space entry points as Extended Producer Responsibility frameworks anticipate CPCB mandates for spent battery collection infrastructure. Target institutional procurement channels for educational devices in Rajasthan and Madhya Pradesh where tender specifications filter unorganized suppliers. Pursue asset-light partnership models with state education departments rather than manufacturing scale. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational consumer electronics parents seeking to divest non-core battery operations amid chemistry specialization pressures. Long-term viability hinges on electrochemical platform breadth spanning zinc-manganese dioxide through nickel-zinc convergence. Monitor BIS heavy metal threshold amendments as inflection signal determining which technology platforms warrant capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Separator Materials | Captive potassium hydroxide sourcing buffers margin compression from electrolyte spot market volatility. |
| BIS Certification Infrastructure Investment | In-house testing laboratories sustain ISI marking continuity through accelerating IS 8144 amendment cycles. |
| State Education Department Partnership | Institutional procurement tenders in Karnataka and Gujarat create volume anchors with shelf-life guarantee requirements. |
| Nickel-Zinc Formulation Development | Electrolyte additive advances open high-drain flashlight and photography applications to rechargeable alternatives. |
| Reverse Logistics Network Buildout | Early spent battery collection infrastructure positions for anticipated CPCB Extended Producer Responsibility mandates. |
Research Methodology
A standing panel of electrochemical formulation chemists, BIS certification auditors, state education procurement officers, and Kolkata-based distribution channel heads provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders against secondary validation from BIS notification records, Central Pollution Control Board hazardous waste filings, customs data on potassium hydroxide imports, and SEC disclosures from listed battery manufacturers. Bottom-up volume estimates from product-type segmentation triangulated against top-down state-level electrification gap projections.
Consistency checks validated volume and value outputs against external benchmarks including state digital literacy program device distribution targets and Maharashtra OEM cluster production indices. The analytical framework modeled segmentation across product format, electrochemical technology, application use-case, and end-user type throughout the projection horizon. CAGRs derived from installed base replacement cycles, rural electrification gap closure trajectories, and OEM procurement intensity trends in consumer electronics manufacturing corridors.
Forecasts assume regulatory continuity in BIS certification regimes and CPCB hazardous waste enforcement; material policy shifts on heavy metal thresholds or Extended Producer Responsibility acceleration would require re-modeling. Revision becomes warranted when lithium primary cell substitution rates in high-drain applications cross critical adoption thresholds or when BIS amendment cycles compress beyond laboratory retesting capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
UAV Battery Pack Market
Batteries
Advanced Batteries Market
Batteries
Europe Consumer Battery Market
Batteries
South America Micro Battery Market
Batteries
Iron-Chromium Flow Battery Market
Batteries
Australia Battery Market
Batteries
South America Battery Cell Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
India Battery Market
Batteries
Utility Battery Market
Batteries
Zinc Ion Batteries Market
Batteries
Portable Battery Powered Products Market
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market
Batteries
Asia-Pacific NMC Battery Pack Market
Batteries
Power Battery Sealant Market
Batteries
Europe Industrial Battery Market